
 Tetradecyl Chloride Market | 2026-2036
Tetradecyl Chloride Market Size, Share, and Industry Trends Forecast 2026-2036
Tetradecyl Chloride Market Analytics
Aftermarket technical service revenue is narrowing as specialty chemical producers internalize formulation support and captive chlorination capabilities. BASF SE leverages integrated C14 alcohol-to-chloride conversion assets across Ludwigshafen and Antwerp to sustain margin capture from feedstock through finished intermediate. Evonik Industries AG anchors its position via high-purity distillation expertise that commands premium positioning in pharmaceutical-grade tetradecyl chloride. Arkema S.A. competes through controlled chlorination process technology that reduces byproduct formation in long-chain alkyl halide production.
Tetradecyl chloride denotes a C14 straight-chain alkyl chloride synthesized via thionyl chloride or phosphorus trichloride substitution of myristyl alcohol, typically yielding a colorless liquid with boiling points near 160°C at reduced pressure and primary utility as an intermediate for quaternary ammonium compounds, amphoteric surfactants, and phase-transfer catalysts. Purity 99% material dominates margin pools as pharmaceutical and medical device manufacturers enforce tight specification windows for API synthesis and sterile formulation components. The Personal Care application segment accelerates fastest as Asian formulators substitute tetradecyl chloride-derived conditioning agents for silicones in rinse-off products. Technical Grade supply remains mature with stable offtake from industrial coating crosslinking and textile softener base production.
EPA oversight under TSCA Section 5 governs new chemical introductions and significant new use notifications for chlorinated paraffin alternatives including tetradecyl chloride in U.S. commerce, while REACH registration requirements in Europe mandate full toxicological dossiers for C14 alkyl chloride substances above one-tonne annual thresholds. India's CDSCO and BIS jointly enforce impurity limits on imported chlorinated intermediates destined for pharmaceutical and cosmetic applications. Stakeholders must monitor evolving per- and polyfluoroalkyl substance restrictions that could redirect surfactant demand toward tetradecyl chloride-based alternatives in textile and coating formulations.
Market Dynamics
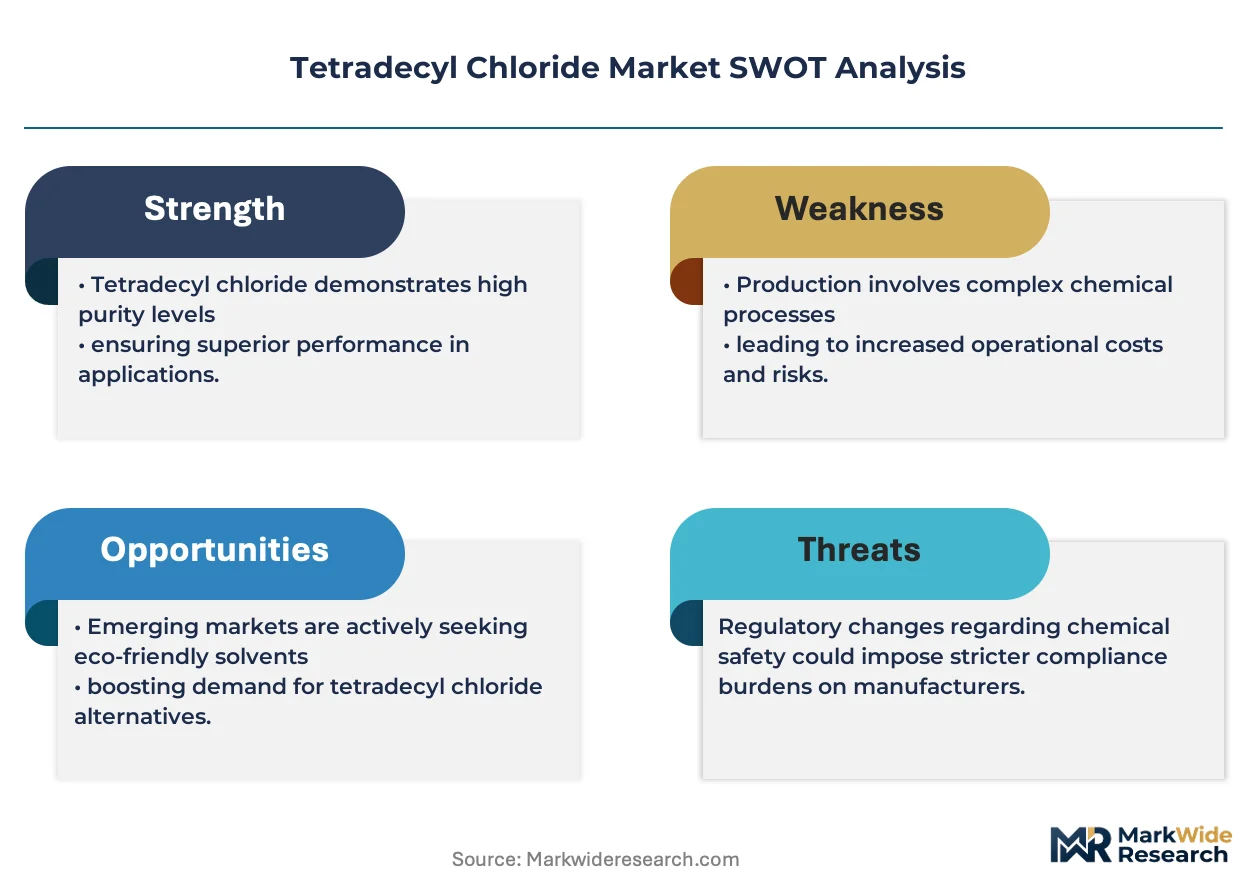
REACH compliance in Europe is restructuring feedstock sourcing for chlorinated intermediates, forcing API manufacturers to validate alternative supply chains and tighten impurity specifications for C14 alkyl chloride inputs.
Growth Catalysts
- Pharmaceutical intermediate demand:CDSCO-regulated API producers in India are scaling tetradecyl chloride purchases for antiseptic and surfactant synthesis, creating concentrated offtake growth.
- Silicone substitution in personal care:Asian formulators are replacing silicone-based conditioning agents with tetradecyl chloride-derived alternatives in rinse-off products.
- PFAS restriction tailwinds:Evolving per- and polyfluoroalkyl substance limits are redirecting surfactant demand toward tetradecyl chloride-based formulations in textile and coating applications.
Market Restraints
- Feedstock cost volatility:Myristyl alcohol price swings directly compress margins for thionyl chloride substitution routes.
- Supply concentration risk:High-purity distillation capabilities for pharmaceutical-grade material concentrate among a limited set of European specialty chemical producers.
- Regulatory friction:REACH registration requirements mandate full toxicological dossiers for C14 alkyl chloride substances above one-tonne annual thresholds, raising compliance burdens.
Strategic Opportunities
- Captive chlorination expansion:Contract manufacturers in India are building in-house long-chain alkyl chloride programs to secure intermediate supply.
- Medical device sterilization:Tighter FDA specifications for sterile formulation components are opening premium positioning for ultra-high-purity grades.
- Green chemistry incentives:EU Green Deal funding streams support process innovation in controlled chlorination technologies that reduce byproduct formation.
Industry Challenges
- Specialized distillation expertise scarcity:Pharmaceutical-grade production requires operators trained in high-vacuum fractional distillation of thermally sensitive organics.
- Cross-border certification timelines:CDSCO and BIS joint enforcement of impurity limits creates extended validation periods for imported chlorinated intermediates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tetradecyl Chloride Market |
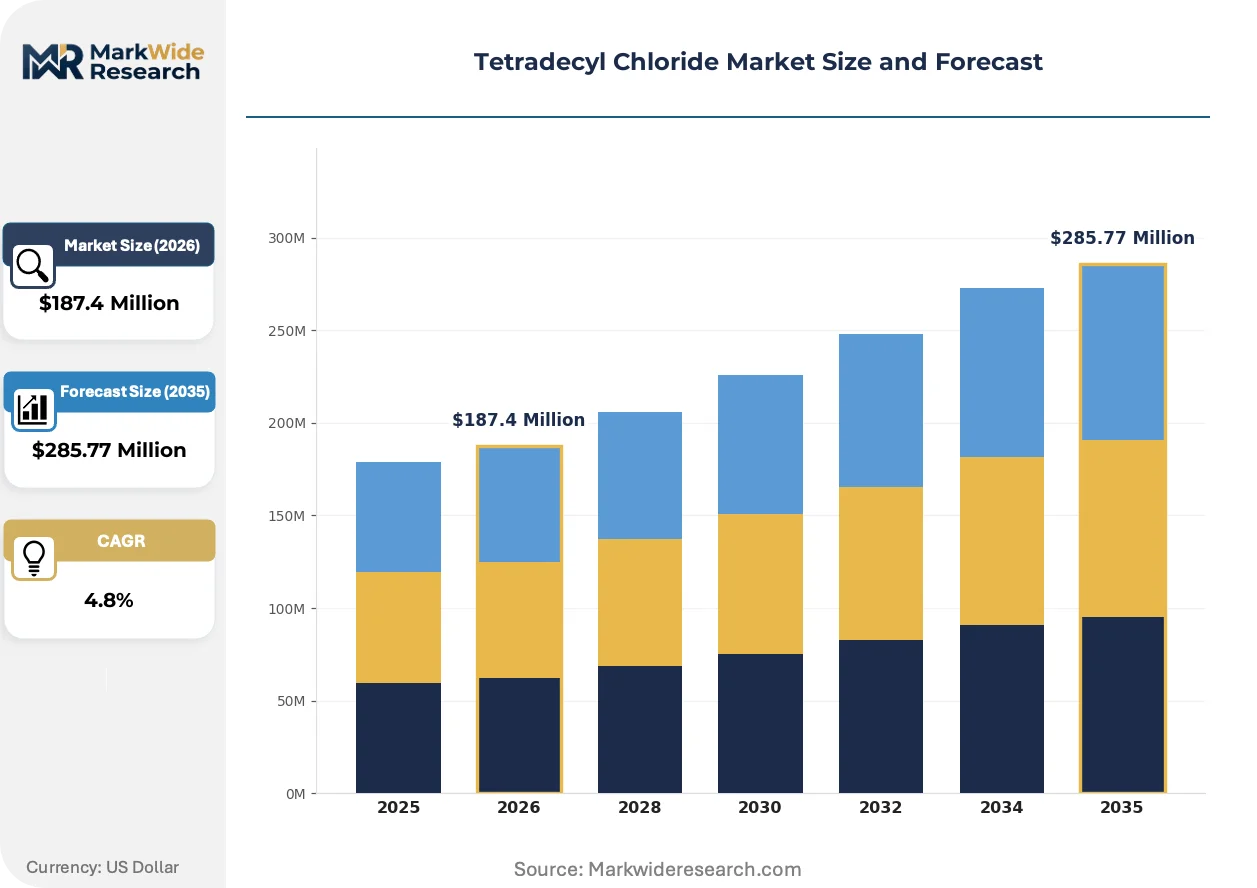
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Purity 99%, Purity 98%, Purity 95%, Technical Grade Application: Pharmaceuticals, Personal Care, Coatings, Textile End User: Chemical Manufacturers, Research Institutions, Cosmetic Companies, Medical Device Manufacturers Packaging Type: Drums, Canisters, Bags, Cylinders |
| Companies Covered | DuPont de Nemours, Inc., BASF SE, Evonik Industries AG, Arkema S.A., Clariant AG, Solvay, Lonza, Transpek Industry Limited, KLK Oleo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tetradecyl Chloride Market Evolving Landscape
Process control technologies and regulatory data systems are reshaping how tetradecyl chloride manufacturers validate purity and traceability across multi-step synthesis routes.
Advanced process analytical technology is digitizing real-time monitoring of thionyl chloride substitution reactions. Pharmaceutical-grade producers are adopting in-line spectroscopic sensors to detect trace byproduct formation before distillation. This capability is digitizing quality assurance workflows and compressing batch release cycles for CDSCO-regulated API customers.
REACH Article 33 disclosure obligations are tightening supply chain transparency for chlorinated paraffin alternatives. Downstream formulators must now document safe-use guidance for C14 alkyl chloride derivatives in cosmetic and medical applications. European personal care manufacturers are responding by demanding certified chain-of-custody documentation from intermediate suppliers.
Formulation houses are consolidating supplier relationships around integrated technical service providers. Specialty chemical producers that once relied on external formulation support are internalizing application development capabilities. This pattern is most visible in India, where domestic surfactant manufacturers now specify tetradecyl chloride grades based on in-house quaternization performance testing rather than supplier certificates.
Tetradecyl Chloride Market Segmentation
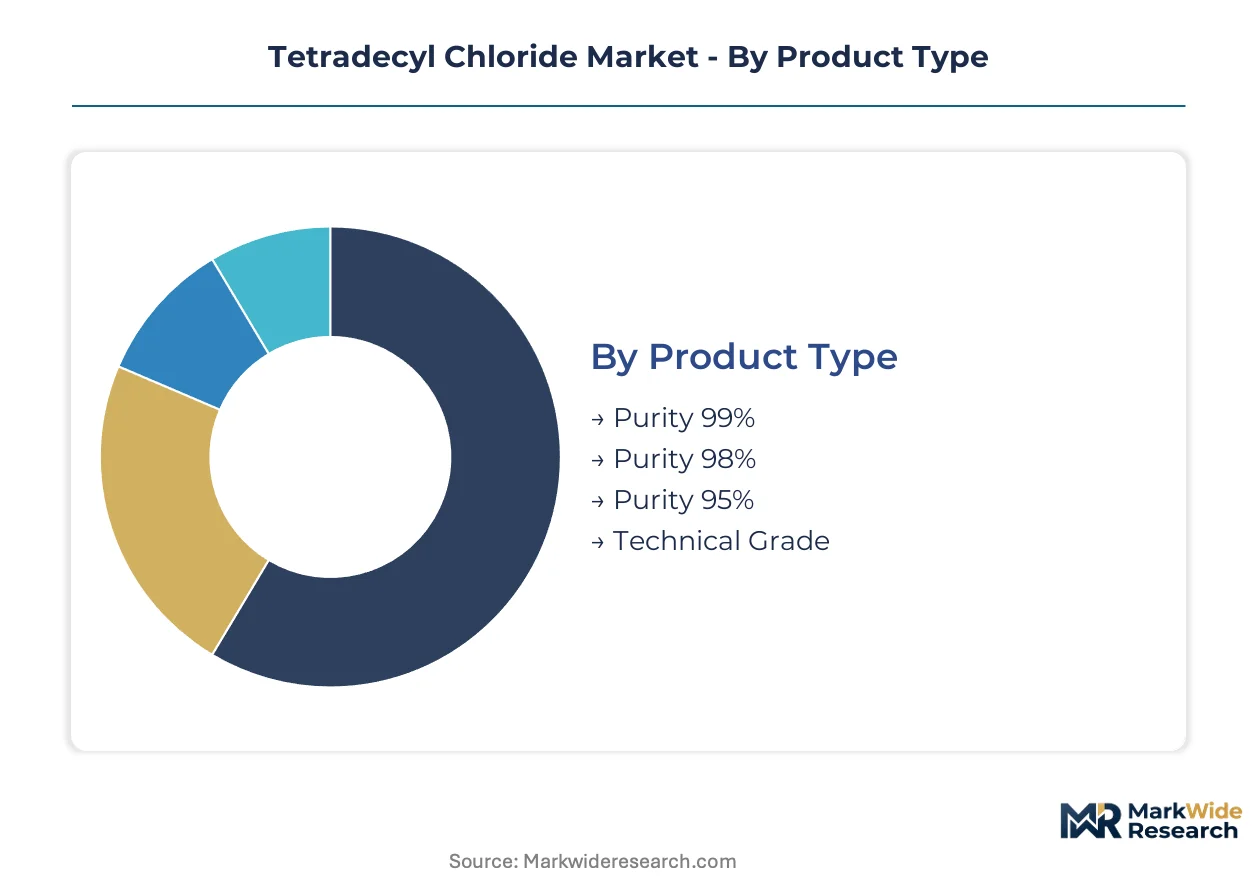
Tetradecyl chloride procurement patterns diverge sharply across purity grades and end-use specifications. Pharmaceutical and medical device manufacturers enforce the strictest quality protocols, while industrial coating formulators prioritize cost-efficient technical grades with broader specification windows.
Product Type:
After-sales technical support intensity escalates with purity tier, as pharmaceutical-grade buyers demand batch-specific certificates of analysis and regulatory documentation packages.
- Purity 99%:Ultra-high-purity material undergoes high-vacuum fractional distillation to eliminate trace organochlorine byproducts. CDSCO-regulated API producers in India specify this grade for antiseptic synthesis and sterile formulation components where impurity thresholds are measured in parts per million.
- Purity 98%:Distilled product meets most pharmaceutical intermediate requirements without the premium commanded by 99% material. European contract manufacturers under REACH Article 33 disclosure obligations favor this tier for quaternary ammonium compound production where documentation traceability matters more than absolute purity.
- Purity 95%:Intermediate grade serves surfactant manufacturers with in-house purification capabilities. Asian formulators substitute this material for silicone-derived conditioning agents in rinse-off personal care products.
- Technical Grade:Industrial specification material drives stable offtake from coating crosslinking and textile softener base production. Price-sensitive buyers internalize formulation adjustments to accommodate broader specification ranges.
By volume, Technical Grade leads. By growth pace, Purity 99% is ahead.
Application:
Margin capture potential varies dramatically across application segments, with pharmaceutical intermediates commanding premium positioning and personal care driving volume expansion.
- Pharmaceuticals:Antiseptic and surfactant synthesis applications require full toxicological dossiers under REACH registration requirements. FDA specifications for sterile formulation components are tightening impurity limits on imported chlorinated intermediates.
- Personal Care:Asian formulators are replacing silicone-based conditioning agents with tetradecyl chloride-derived alternatives. Rinse-off product manufacturers specify C14 alkyl chloride inputs based on in-house quaternization performance testing rather than supplier certificates.
- Coatings:Industrial crosslinking applications consume technical grade material with stable, mature demand curves. Evolving PFAS restrictions are redirecting surfactant demand toward tetradecyl chloride-based formulations in textile and coating applications.
- Textile:Softener base production relies on cost-optimized procurement with limited technical service requirements. BIS joint enforcement of impurity limits creates extended validation periods for imported chlorinated intermediates destined for this segment.
Pharmaceuticals generates the highest margin per tonne. Personal Care is climbing the fastest.
End User:
Procurement sophistication separates institutional buyers from commercial formulators, with research institutions demanding smallest volumes but most intensive documentation support.
- Chemical Manufacturers:Integrated producers with captive chlorination capabilities backward integrate into long-chain alkyl chloride programs. BASF SE leverages C14 alcohol-to-chloride conversion assets across Ludwigshafen and Antwerp to sustain margin capture from feedstock through finished intermediate.
- Research Institutions:Academic and government laboratories require gram-to-kilogram scale quantities with comprehensive safety data sheets. CDSCO-regulated API producers scale tetradecyl chloride purchases for antiseptic synthesis validation studies.
- Cosmetic Companies:Personal care formulators consolidate supplier relationships around integrated technical service providers. Domestic surfactant manufacturers in India now specify grades based on in-house performance testing protocols.
- Medical Device Manufacturers:Sterile formulation component producers enforce the tightest specification windows for API synthesis. Tighter FDA specifications are opening premium positioning for ultra-high-purity grades in implantable and invasive device applications.
Chemical Manufacturers dominate volume. Medical Device Manufacturers show the steepest expansion trajectory.
Packaging Type:
Supply chain configuration for liquid organochlorides reflects hazard classification requirements and customer scale fragmentation across the value chain.
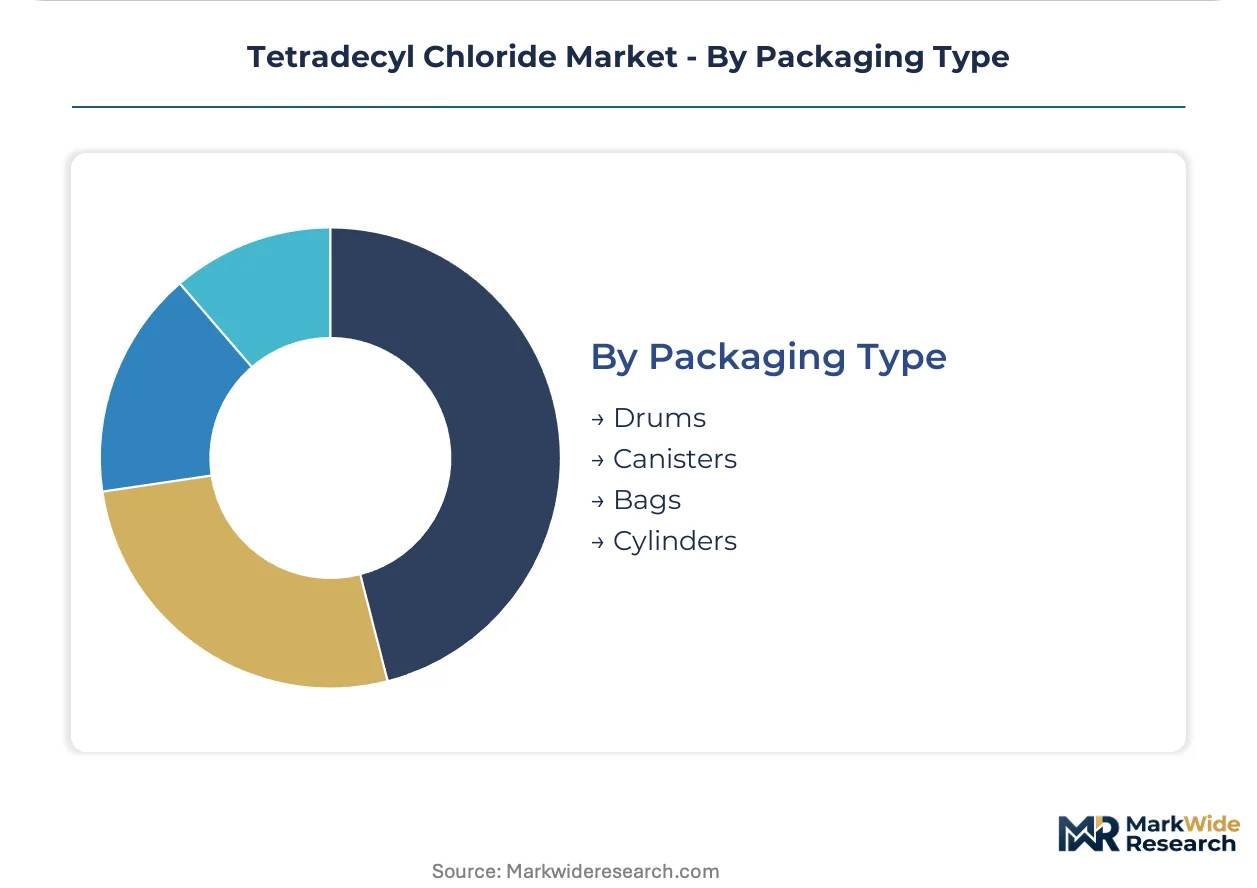
- Drums:Standard 200-liter steel drums serve mid-scale chemical manufacturers and cosmetic compounders with moderate throughput requirements. REACH-compliant labeling and chain-of-custody documentation accompany bulk drum shipments to European personal care manufacturers.
- Canisters:Smaller format containers address research institutions and specialty formulators with limited storage infrastructure. BIS impurity limit enforcement extends validation timelines for canister-sized imports into Indian pharmaceutical applications.
- Bags:Flexible intermediate bulk containers suit high-volume textile softener producers with dedicated handling equipment. Cost-sensitive coating crosslinking operations favor bag packaging for technical grade material.
- Cylinders:Pressurized or inert-atmosphere cylinders preserve purity for pharmaceutical-grade and medical device applications. High-purity distillation specialists like Evonik Industries AG specify cylinder packaging for premium positioning in pharmaceutical-grade tetradecyl chloride.
Drums anchor volume throughput. Cylinders are gaining share fastest on medical device demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across geographies. Indian buyers absorb premium grades for CDSCO-regulated API production while European formulators drive hard bargains on technical material. Contract manufacturers in Asia-Pacific internalize chlorination capabilities to escape feedstock volatility.
United States
Medical device sterilization applications command ultra-high-purity grades under tightening FDA specifications. EPA oversight through TSCA Section 5 governs new chemical introductions for chlorinated paraffin alternatives. Gulf Coast chemical clusters sustain captive chlorination programs for long-chain alkyl chloride intermediates.
Germany
Integrated C14 alcohol-to-chloride conversion assets anchor margin capture from feedstock through finished intermediate. REACH registration requirements mandate full toxicological dossiers for C14 alkyl chloride substances above one-tonne annual thresholds. Ludwigshafen and Antwerp production complexes supply pharmaceutical-grade material across European contract manufacturing networks.
India
CDSCO-regulated API producers scale tetradecyl chloride purchases for antiseptic and surfactant synthesis. BIS and CDSCO jointly enforce impurity limits on imported chlorinated intermediates destined for pharmaceutical and cosmetic applications. Gujarat and Maharashtra chemical corridors host expanding long-chain alkyl chloride programs as contract manufacturers build in-house capabilities.
China
Personal care formulators substitute tetradecyl chloride-derived conditioning agents for silicones in rinse-off products. The country's national chemical regulator enforces emission controls on thionyl chloride substitution processes. Yangtze River Delta surfactant clusters drive volume procurement of technical grade material for textile softener base production.
Japan
High-purity distillation expertise concentrates among specialty chemical producers serving pharmaceutical and medical device sectors. METI oversees chemical substance management under industrial safety frameworks. Kansai and Chubu industrial zones maintain precision manufacturing capabilities for thermally sensitive organics processing.
Tetradecyl Chloride Market Competitive Landscape
Capability concentration sits with one tier; scale advantage sits with another. High-vacuum fractional distillation expertise for pharmaceutical-grade material clusters among European specialty chemical producers while Asian manufacturers capture volume through technical grade output. Three archetypes dominate: integrated petrochemical conglomerates with captive alcohol feedstocks, high-purity distillation specialists commanding premium positioning, and regional surfactant intermediates suppliers serving formulation houses. Competitive moves center on backward integration into feedstock alcohol production and strategic partnerships with CDSCO-regulated API manufacturers in India.
Within the integrated conglomerate tier, BASF SE and Evonik Industries AG exemplify divergent positioning strategies. BASF SE anchors its presence through Ludwigshafen and Antwerp production complexes spanning feedstock conversion through finished intermediate. Evonik Industries AG occupies a position centered on high-purity distillation capabilities. Arkema S.A. represents the controlled process technology archetype with expertise in byproduct reduction. Among Asia-Pacific suppliers, Transpek Industry Limited sits within the regional intermediate specialist tier.
| Leading Market Players |
|---|
| DuPont de Nemours, Inc. |
| BASF SE |
| Evonik Industries AG |
| Arkema S.A. |
| Clariant AG |
| Solvay |
| Lonza |
| Transpek Industry Limited |
| KLK Oleo |
| Others |
Value Network & Pricing Analysis
European high-purity distillation specialists concentrate pharmaceutical-grade margin pools while Asian technical-grade producers compete on feedstock conversion economics. Thionyl chloride substitution routes anchor cost structures across both tiers, with myristyl alcohol price volatility transmitting directly into downstream pricing power.
Pricing Analysis
After-sales technical service revenue drives lifetime value for pharmaceutical-grade suppliers serving CDSCO-regulated API producers. Three-tier pricing structure across pharmaceutical-grade, intermediate-grade, and technical-grade levels stratifies by certification intensity and impurity documentation. Pricing pressure stems from Indian contract manufacturers internalizing captive chlorination capabilities to escape feedstock volatility. Chemical manufacturers with backward-integrated C14 alcohol assets exhibit lowest price sensitivity, while textile softener producers prioritize cost-optimized technical material.
Supply Chain Analysis
REACH Article 33 disclosure obligations restrict technology flows for chlorinated paraffin alternatives entering European cosmetic and medical applications. Supply concentrates in Germany, India, and China, with Ludwigshafen-Antwerp complexes, Gujarat-Maharashtra corridors, and Yangtze River Delta clusters anchoring regional output. Feedstock dependencies center on myristyl alcohol from palm-derived and petrochemical routes, plus thionyl chloride and phosphorus trichloride reagents. Single-source vulnerability concentrates in high-vacuum fractional distillation equipment for pharmaceutical-grade production. Distribution runs through drum and cylinder formats for mid-scale chemical manufacturers and sterile formulation component producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory fragmentation across REACH, CDSCO, and FDA jurisdictions creates niche positioning opportunities for purity-tier specialists. Silicone substitution tailwinds in Asian personal care fragment demand across conditioning-agent suppliers.
For Market Incumbents: Entrench positioning through captive C14 alcohol-to-chloride conversion assets that insulate margin capture from feedstock volatility. Invest in high-vacuum fractional distillation capacity expansion to defend against emerging Indian contract manufacturers building in-house chlorination programs. Prioritize REACH-compliant chain-of-custody documentation systems that satisfy European personal care manufacturers tightening supplier consolidation criteria.
For New Entrants and Emerging Players: Indian pharmaceutical intermediate demand represents the most penetrable white-space target, with CDSCO-regulated API producers scaling tetradecyl chloride purchases for antiseptic synthesis. Medical device sterilization applications offer premium positioning entry points under tightening FDA specifications for sterile formulation components. Pursue technical service partnerships with domestic surfactant manufacturers in Gujarat and Maharashtra chemical corridors as the primary go-to-market angle.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed European specialty chemical producers holding high-purity distillation capabilities but limited feedstock integration. Long-term viability hinges on backward integration into palm-based or petrochemical C14 alcohol supply over the mid-cycle window. Acquisition targets should display integrated technical service capabilities and validated CDSCO supplier status. Monitor PFAS restriction implementation timelines as the critical inflection signal for surfactant demand redirection toward tetradecyl chloride-based alternatives.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into C14 Alcohol Feedstock | BASF SE leverages Ludwigshafen and Antwerp assets to capture margin from feedstock through finished intermediate. |
| High-Purity Distillation Capacity Expansion | Evonik Industries AG commands premium positioning in pharmaceutical-grade material through thermally sensitive organics expertise. |
| Controlled Chlorination Process Technology | Arkema S.A. reduces byproduct formation in long-chain alkyl halide production through proprietary reaction control. |
| Captive Chlorination Program Buildout | Indian contract manufacturers in Gujarat and Maharashtra escape feedstock volatility through in-house long-chain alkyl chloride capabilities. |
| REACH-Compliant Chain-of-Custody Documentation | European personal care manufacturers demand certified traceability for C14 alkyl chloride derivatives under Article 33 obligations. |
Research Methodology
Operator-level perspectives from plant managers at chlorination facilities, procurement leads at CDSCO-regulated API producers, technical R&D directors in surfactant formulation houses, and distribution channel partners in specialty chemical networks anchored the qualitative base. Primary interview insights combined with secondary validation from customs and trade data, ECHA registration dossiers, SEC 10-K filings from listed chemical producers, and BIS import certification records. Bottom-up volume modeling across purity tiers and top-down market sizing triangulated demand estimates.
Scenario-bracketing framed analytical projections across the analysis window, with segmentation dimensions spanning purity grade, end-use application, packaging format, and regional production hub. CAGRs derived from historical trajectory analysis and forward-looking demand elasticity assessments for pharmaceutical intermediate and personal care substitution segments. Forecast inputs incorporated REACH compliance cost burdens, CDSCO validation timeline extensions, and PFAS restriction implementation pace.
Practitioners should monitor myristyl alcohol price volatility, CDSCO-BIS joint enforcement intensity, and PFAS regulatory expansion for early signals of forecast deviation. Forecasts reflect assumptions regarding sustained silicone substitution momentum in Asian personal care and stable REACH registration compliance costs. Material shifts in feedstock availability or accelerated captive chlorination adoption among Indian contract manufacturers would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surfactants
Global Fluorosurfactants Market
Surfactants
Polymer Surfactants Market
Surfactants
Alkylamines Market
Surfactants
Global Detergent Polymers Market
Surfactants
Coconut Derived Surfactants Market
Surfactants
Natural Wax Emulsion Market
Surfactants
Polysorbate 40 Market
Surfactants
Sodium Lauroyl Glycinate Market
Surfactants
Global Thioglycolic Acid Market
Surfactants
Surfactant Cleansers and Adjuvants Market
Surfactants
Global Hydrophobically Modified Alkali Swellable Emulsion (HASE) Market
Surfactants
Alkyl Polyglucosides Market
Surfactants
Micellar Water Market
Surfactants
Bio-Based Surfactants Market
Surfactants
Calcium Stearoyl-2 Lactylate Market
Surfactants
Linear Alkylbenzene Sulfonate (LAS) Market