
 1, 4 Butanediol Market | 2026-2036
1, 4 Butanediol Market Size, Share, and Industry Trends Forecast 2026-2036
1, 4 Butanediol Market Intelligence
The divergence between high-purity, bio-based grades and conventional petrochemical-derived commodity grades is pivoting on end-user sustainability targets and stricter purity specifications. BASF SE leverages its vast production scale and integrated Verbund system to serve high-volume applications efficiently. In contrast, Ashland Global Holdings Inc. specializes in derivatives for more specialized end-markets. Dow competes across the value chain by integrating BDO production with its broader polymer and intermediate chemical portfolio.
1, 4-Butanediol is a colorless, viscous diol with the chemical formula HO(CH2)4OH, primarily produced via petrochemical routes like the Reppe process. It serves as a crucial chemical intermediate for manufacturing other polymers and solvents. Its use as an intermediate for producing tetrahydrofuran (THF), polybutylene terephthalate (PBT), and gamma-butyrolactone (GBL) constitutes the largest share of consumption. Within applications, the automotive and textiles sectors remain significant consumers due to the use of BDO derivatives in engineering plastics and elastic fibers like spandex.
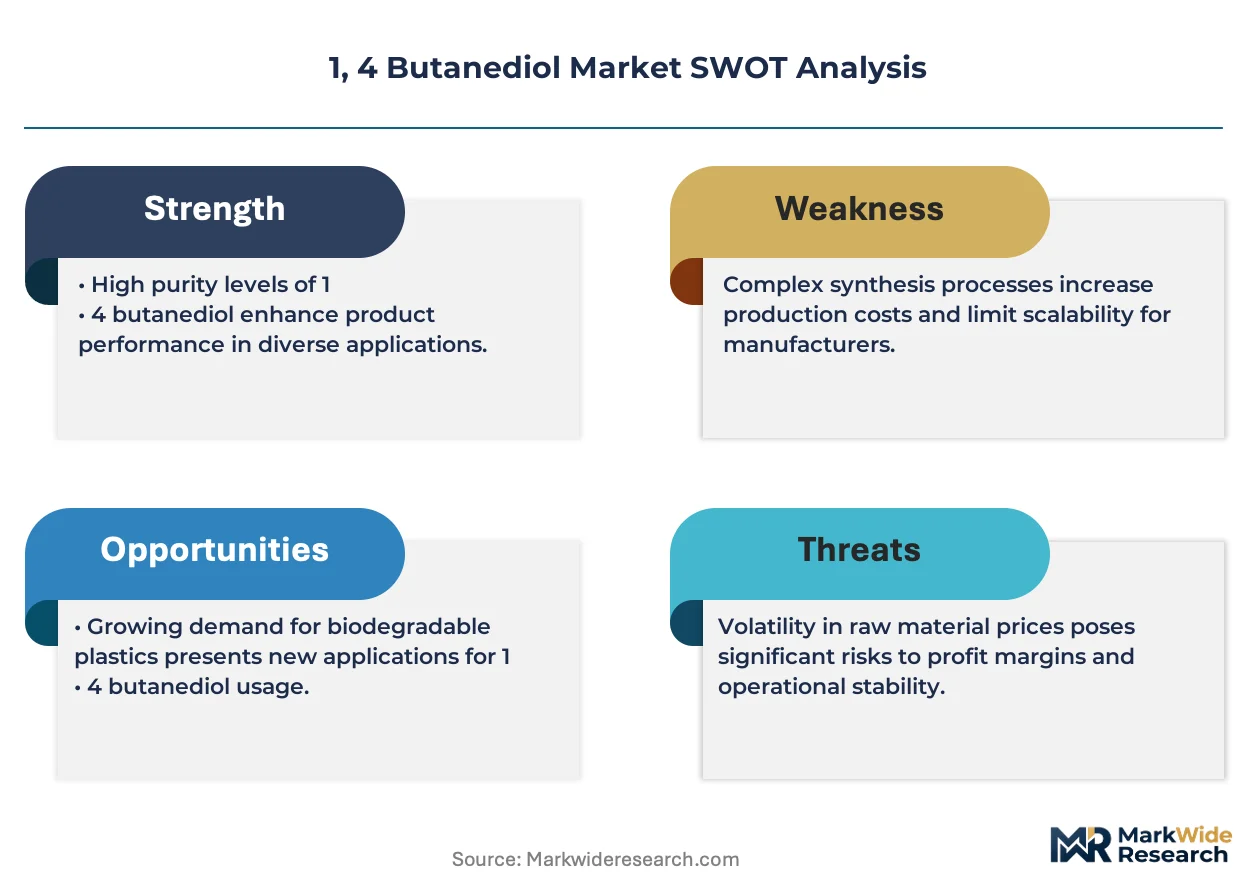
The regulatory environment is defined by chemical control laws such as the European Union’s REACH regulation, managed by ECHA, and the US EPA's oversight under the Toxic Substances Control Act. These frameworks mandate rigorous testing and registration for chemicals, influencing production costs and market access. Consequently, producers face a strategic decision between expanding existing petrochemical capacity and committing capital to nascent bio-based production technologies to secure future market position.
Market Dynamics
The central dynamic in the 1, 4-Butanediol market is the strategic divergence between scaled petrochemical production and emerging bio-based pathways. This split is driven by end-user sustainability mandates clashing with the cost-efficiency of established, high-volume manufacturing hubs.
Growth Catalysts
- Automotive Lightweighting:Demand from the automotive sector for polybutylene terephthalate (PBT) in connectors, housings, and EV battery components provides a consistent volume driver for BDO consumption.
- Bio-Based Production:Advances in direct fermentation and catalytic conversion of renewable feedstocks like sugars into BDO are enabling commercial-scale production, aligning with corporate sustainability goals.
- Circular Economy Policies:Frameworks such as the EU Green Deal encourage the use of materials with lower carbon footprints and greater recyclability, creating a favorable environment for bio-BDO and its derivatives.
Market Restraints
- Feedstock Volatility:The market remains vulnerable to price fluctuations in petrochemical feedstocks like natural gas and acetylene, which directly impact the production cost of conventional BDO.
- Geographic Concentration:Heavy reliance on production capacity located in China creates significant supply chain risks for consumers in North America and Europe, exposing them to logistical disruptions and trade policy shifts.
- Substitution Threats:In certain applications, BDO-derived products face competition from alternative materials, such as different types of engineering plastics or fibers that do not rely on BDO as a precursor.
Strategic Opportunities
- Biodegradable Polymers:The expanding market for biodegradable plastics, particularly polybutylene succinate (PBS) for packaging and agricultural films, presents a significant growth avenue for BDO.
- Closed-Loop Recycling:Developing chemical recycling processes to depolymerize PBT and polyurethane waste back into BDO and other monomers offers a path to a circular supply chain.
- Emerging Market Industrialization:Growth in manufacturing sectors within Southeast Asia and Latin America provides an opportunity to establish regional BDO supply chains to serve local demand for plastics, textiles, and electronics.
Industry Challenges
- Capital Investment Hurdles:The substantial capital expenditure required to construct greenfield bio-based BDO facilities or to upgrade existing petrochemical plants with greener technology presents a major financial barrier.
- Regulatory Compliance Timelines:Navigating the extensive testing and registration requirements under chemical control laws like the EU's REACH and the US's TSCA for new bio-based grades can delay market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 1, 4 Butanediol Market |
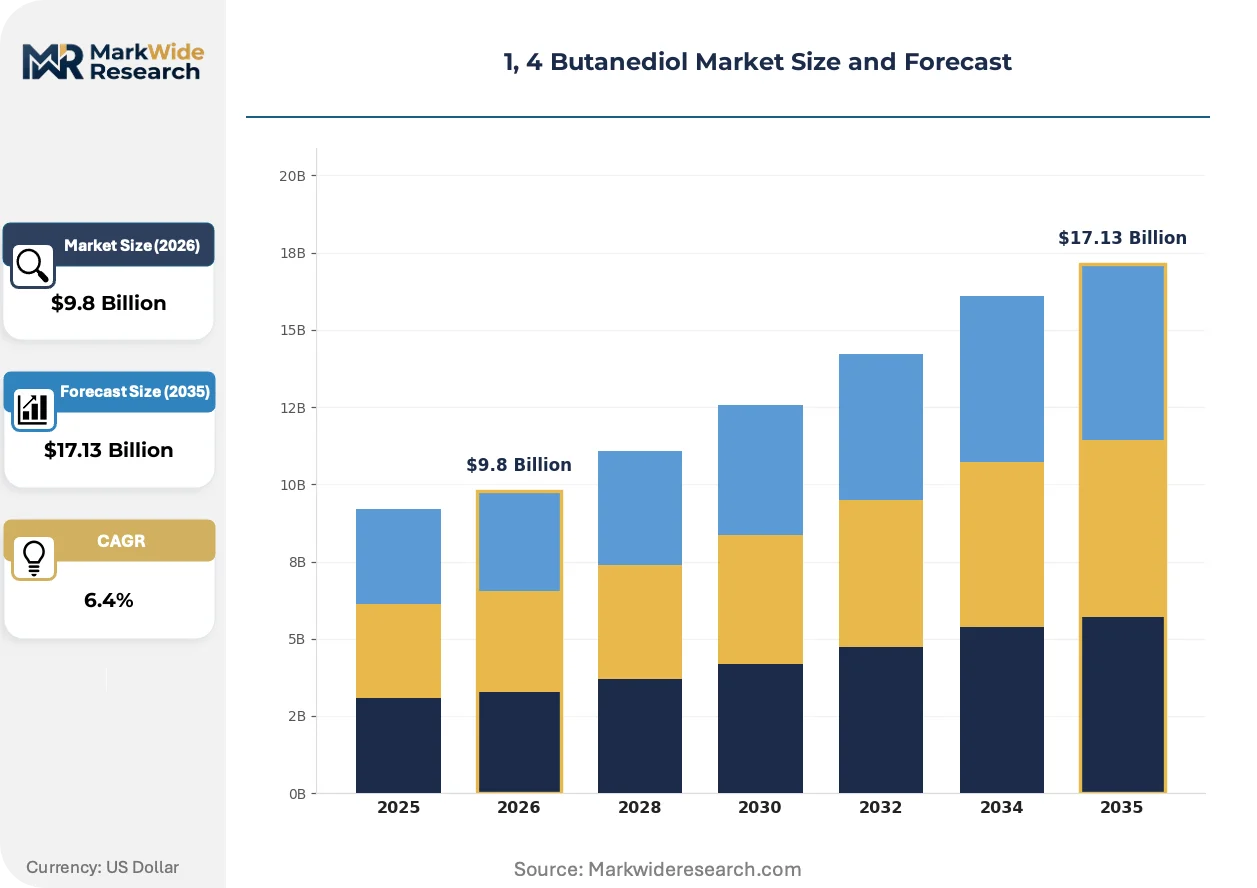
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $17.13 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solvent, Plasticizer, Intermediate, Polymer Application: Coatings, Automotive, Textiles, Adhesives End User: Manufacturers, Distributors, Retailers, Enterprises Distribution Channel: Direct Sales, Online Retail, Wholesalers, Traders |
| Companies Covered | BASF SE, LyondellBasell Industries Holdings B.V., Dow, Mitsubishi Chemical Corporation, DCC, Huntsman Corporation, Ashland Global Holdings Inc., Dairen Chemical Corporation, Nanya Plastics Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
1, 4 Butanediol Market Strategic Shifts & Innovations
The market's evolution is defined by a clear bifurcation between high-volume, price-sensitive commodity grades and performance-differentiated, sustainable specialty grades. This division influences technology investment, supply chain structure, and customer engagement models across the value chain.
Bio-fermentation processes that convert renewable sugars directly into 1, 4-Butanediol represent a pivotal technological shift. Specialty polymer and consumer goods manufacturers are adopting this route to meet stringent sustainability targets and reduce carbon footprints. This technology is integrating renewable feedstocks into a traditionally fossil-fuel-based chemical supply chain, creating a parallel, premium-priced material stream.
China's national dual carbon goals are compelling its vast chemical industry to improve energy efficiency and reduce emissions. This policy framework incentivizes producers to invest in less energy-intensive BDO synthesis routes and explore waste-to-chemical technologies. The domestic Chinese market, being the largest global producer and consumer, is most directly affected as manufacturers face mounting pressure to modernize their production assets.
A notable behavioral shift involves procurement teams in consumer-facing industries specifying BDO sourced from certified sustainable or bio-based origins. This disrupts traditional purchasing models based purely on technical specifications and price, forcing suppliers to provide clear traceability and certification. This trend is most prominent within the European textiles and packaging sectors, where brand reputation is closely tied to supply chain sustainability.
1, 4 Butanediol Market Segmentation
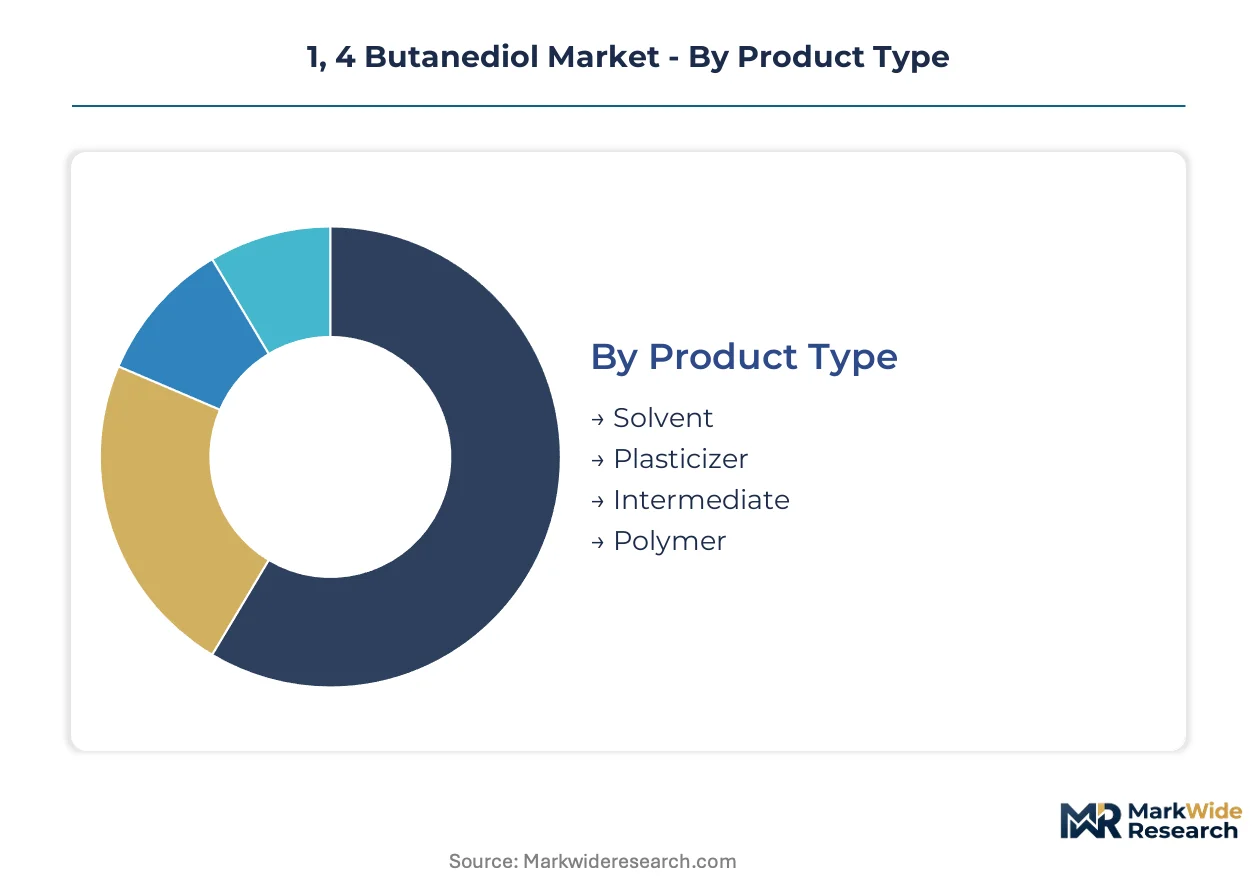
The 1, 4 Butanediol market exhibits diverse segmentation, reflecting varied product specifications, end-use requirements, and distribution models. Understanding these distinct segments is crucial for identifying targeted growth opportunities and navigating specific regulatory landscapes. This granular analysis reveals where value concentrates and how different market forces impact product development and market access.
Product Type:
Certification burdens heavily influence the market for specific 1, 4 Butanediol product types, with high-purity grades often requiring more extensive regulatory approvals.
- Intermediate:This product type refers to BDO used as a chemical building block for synthesizing other polymers and solvents, including tetrahydrofuran (THF) and polybutylene terephthalate (PBT). Demand concentrates in industrial manufacturing zones like China and Germany, driven by the need for precursor chemicals in plastics production.
- Polymer:BDO directly forms part of the polymer chain in materials such as PBT, polyurethanes, and biodegradable plastics like polybutylene succinate (PBS). The automotive sector in Japan and the packaging industry in the EU drive consumption, seeking durable and sustainable material solutions.
- Solvent:BDO functions as a solvent in various industrial processes, valued for its high boiling point and solubility characteristics.
- Plasticizer:As a plasticizer, BDO enhances the flexibility and durability of polymers, particularly in PVC and other resin formulations.
Leading the category by volume: Intermediate. Growing fastest: Polymer.
Application:
Cost efficiencies and performance specifications dictate the choice of 1, 4 Butanediol across various applications, influencing procurement strategies for large-scale industrial users.
- Automotive:BDO derivatives, particularly PBT, are integral to manufacturing lightweight components like connectors, housings, and EV battery parts. The push for vehicle electrification in the US and Germany drives demand, emphasizing material performance and weight reduction.
- Textiles:In the textiles sector, BDO is a precursor for elastic fibers like spandex and PBT fibers used in technical textiles. European fashion brands and Chinese sportswear manufacturers prioritize these materials for their durability and stretch properties.
- Coatings:BDO contributes to the formulation of various coatings, providing flexibility and chemical resistance in industrial and protective finishes.
- Adhesives:BDO-derived polyurethanes and polyesters find use in adhesive formulations, offering strong bonding and flexibility for construction and assembly.
Automotive applications drive the largest share, while Textiles expand most quickly.
End User:
The diverse needs of 1, 4 Butanediol end users shape demand patterns, from bulk industrial purchasing to specialized requirements for advanced materials development.
- Manufacturers:Industrial manufacturers consume BDO as a critical raw material for producing a wide array of chemicals, polymers, and derivatives in large volumes. Companies in China and India represent significant manufacturing hubs, driving consistent BDO demand.
- Distributors:Distributors act as intermediaries, supplying BDO to smaller manufacturers and diverse end-users who do not purchase directly from large producers. This channel is vital for market penetration in fragmented regions like Southeast Asia.
- Retailers:Retailers indirectly interact with BDO through finished consumer products containing BDO derivatives, such as apparel or electronic devices.
- Enterprises:Large enterprises, particularly integrated chemical companies, utilize BDO for captive consumption or for producing specialized derivatives within their own value chains.
Manufacturers account for the largest consumption, with Enterprises showing the steepest expansion trajectory.
Distribution Channel:
Supply concentration heavily influences the viability and reach of various 1, 4 Butanediol distribution channels, particularly for high-volume commodity grades.
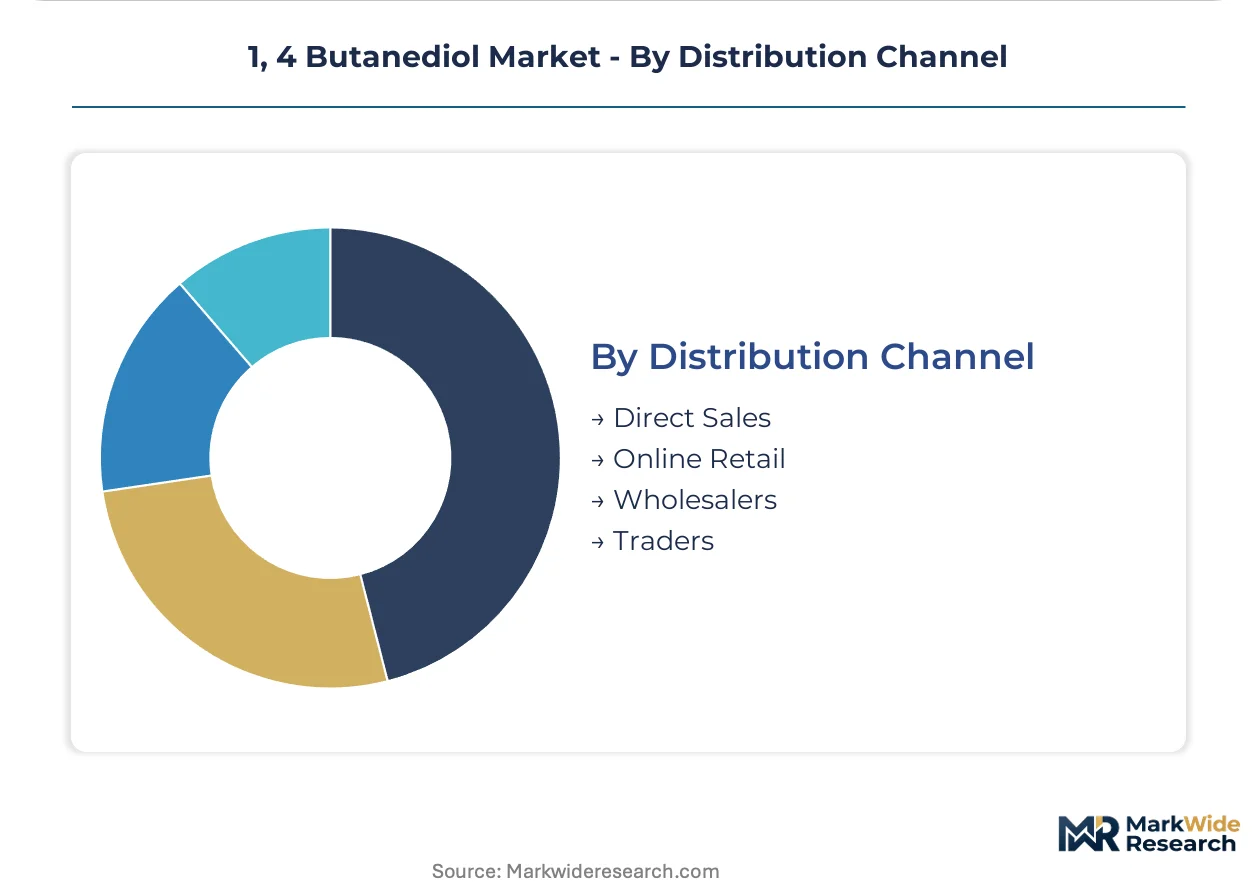
- Direct Sales:Major BDO producers engage in direct sales to large industrial customers, ensuring consistent supply and technical support for high-volume contracts. This model dominates in established markets like the US and Western Europe for strategic partnerships.
- Wholesalers:Wholesalers aggregate BDO from producers and distribute it to a broader base of small to medium-sized enterprises, particularly in regions with diverse industrial bases. This channel supports market access in Brazil and Mexico.
- Online Retail:Online platforms facilitate BDO transactions for niche applications or smaller quantities, offering convenience and broader accessibility for specialized buyers.
- Traders:Traders manage the international movement of BDO, capitalizing on price differentials and managing logistics for cross-border supply to various regions.
Direct Sales remain the dominant channel, and Online Retail is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai's chemical industry cluster drives substantial demand for 1, 4 Butanediol, serving both domestic and international markets. This region benefits from integrated supply chains supporting plastics and automotive manufacturing. Its strategic location facilitates distribution across Asia.
China
Demand for BDO in China stems from its vast manufacturing base, particularly for PBT in electronics and automotive components. China's national dual carbon goals incentivize producers to adopt greener BDO synthesis routes. The Yangtze River Delta region, including cities like Nanjing, hosts major chemical production facilities.
Germany
The German automotive sector drives significant BDO consumption for engineering plastics and polyurethanes. The European Union’s REACH regulation mandates rigorous testing for BDO, influencing production costs. Bavaria's industrial clusters specialize in high-performance materials development.
United States
Automotive lightweighting and the expanding market for EV battery components fuel BDO demand in the United States. The US EPA oversees chemical substances under the Toxic Substances Control Act (TSCA). The Gulf Coast region concentrates petrochemical production and BDO derivatives manufacturing.
Japan
Japan's advanced automotive industry requires BDO derivatives for high-performance engineering plastics. The Ministry of Economy, Trade and Industry (METI) promotes sustainable chemical production methods. Aichi Prefecture, a major automotive hub, consumes BDO in various vehicle parts.
India
India's growing manufacturing sector, especially for textiles and consumer goods, generates consistent BDO demand. The Bureau of Indian Standards (BIS) sets quality benchmarks for industrial chemicals. Gujarat's chemical industrial estates are expanding BDO derivative production.
1, 4 Butanediol Market Key Industry Players
Capital-heavy producers compete with asset-light specialists in the 1, 4 Butanediol market. The industry structure shows consolidation among large chemical manufacturers for commodity grades, alongside fragmentation for bio-based and high-purity variants. Archetypes include integrated petrochemical giants, specialized derivatives manufacturers, and emerging bio-based technology providers. Companies pursue capacity expansion and strategic partnerships to secure feedstock and market access.
At the scale-driven end, BASF SE, a German chemical company, exemplifies integrated operations across the BDO value chain, leveraging its Verbund system for efficiency. Dow, a US-based multinational, occupies a position as a diversified chemical producer with extensive polymer and intermediate portfolios. Ashland Global Holdings Inc., another US-based entity, represents specialization in derivatives for niche end-markets, focusing on specific performance applications. These players collectively shape the market's competitive dynamics through their distinct business models.
| Leading Market Players |
|---|
| BASF SE |
| LyondellBasell Industries Holdings B.V. |
| Dow |
| Mitsubishi Chemical Corporation |
| DCC |
| Huntsman Corporation |
| Ashland Global Holdings Inc. |
| Dairen Chemical Corporation |
| Nanya Plastics Corporation |
| Others |
Cost & Logistics Intelligence
Petrochemical feedstock volatility directly influences 1,4 Butanediol production costs, impacting the final price for downstream polymer and solvent manufacturers. Bio-based BDO, while premium, offers stability linked to agricultural commodity pricing.
Pricing Analysis
Outcome-based pricing for specialized 1,4 Butanediol grades reflects the performance and sustainability benefits delivered in end-use applications. Contract-based long-term offtake agreements dominate for commodity volumes, while high-purity and bio-based variants command premiums based on certification levels and stringent technical specifications. Pricing softness for conventional BDO stems from intensified competition among large-scale producers in industrial manufacturing zones. Manufacturers of high-volume commodity plastics exhibit high price sensitivity, contrasting with the lower sensitivity of specialty chemical enterprises.
Supply Chain Analysis
Closed-loop recycling processes for polybutylene terephthalate and polyurethane waste back into 1,4 Butanediol are nascent but critical reverse logistics flows. Global supply concentration centers on China, the United States, and Germany, drawing from petrochemical feedstocks like natural gas and acetylene, or renewable sugars for bio-BDO. Reliance on Chinese production capacity creates significant supply chain risks due to potential trade policy shifts. Direct sales from major producers to large industrial customers represent the dominant distribution model, ensuring consistent supply for high-volume contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The 1,4 Butanediol market is in a technology-transition phase, with bio-fermentation processes gradually displacing traditional petrochemical routes. This fundamental shift reshapes competitive positioning and supply chain dynamics across the value chain.
For Market Incumbents: Anticipate sustained pressure from sustainability mandates and emerging bio-based entrants. Invest significantly in greenfield bio-based BDO facilities or upgrade existing petrochemical plants with less energy-intensive synthesis routes. Establish strategic partnerships with renewable feedstock suppliers to secure future raw material access. This proactive approach mitigates the threat of regulatory restrictions and ensures long-term market relevance.
For New Entrants and Emerging Players: Distributors targeting fragmented regional markets, particularly in Southeast Asia, offer immediate market penetration opportunities. Focus on developing high-purity bio-based BDO for specialized applications like biodegradable polymers and high-performance textiles. Leverage robust sustainability certifications and transparent traceability to differentiate against conventional commodity grades. This strategy addresses the unmet demand for green materials in consumer-facing industries.
For Investors and Strategic Acquirers: Increased capital deployment into greenfield bio-based BDO facilities is the leading indicator that the market is transitioning to sustainable production at scale. The sector exhibits strong long-term viability over the next 5-10 years, driven by global decarbonization trends. Target mid-cap specialists possessing patented bio-production technologies or established regional distribution networks for strategic acquisitions. Monitor regulatory tightening on carbon emissions and significant price convergence between bio- and petrochemical BDO.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion for Bio-BDO | Scaling bio-based production reduces costs and meets growing demand from sustainability-focused consumer goods manufacturers. |
| Green Manufacturing Transition | Adopting less energy-intensive BDO synthesis routes aligns with China's dual carbon goals and EU Green Deal objectives. |
| Long-term Supply Agreements | Securing feedstock for bio-BDO production hedges against petrochemical price volatility for polymer manufacturers. |
| Joint Venture for Technology Licensing | Partnerships accelerate the commercialization of novel bio-fermentation processes, enhancing market access for new entrants. |
| Distribution Channel Expansion in Emerging Markets | Establishing regional BDO supply chains serves local demand for plastics and textiles in Southeast Asia and Latin America. |
Research Approach
Customs/trade data, company 10-K filings, and chemical industry association reports formed the secondary backbone for this analysis. Primary interviews with plant managers, procurement leads at downstream OEMs, and technical R&D directors provided granular insights. This approach combined bottom-up data aggregation with top-down market validation, ensuring robust data triangulation.
Historical trendline analysis underpinned the quantitative projections across the analysis window. The analytical framework modeled key segmentation dimensions including product type, application, end user, and distribution channel. Compound Annual Growth Rates were derived through regression analysis, integrating industry-specific forecast inputs such as feedstock price forecasts and bio-based BDO production capacity additions.
Several conditions sit outside the modeled scope, including geopolitical conflicts and unforeseen technological breakthroughs. Forecasts reflect assumptions about stable regulatory environments and prevailing economic conditions. Practitioners should monitor new bio-BDO plant announcements and significant shifts in petrochemical feedstock prices for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Global Zinc Pyrithione Market
Chemicals
2-(4-(Bromomethyl)phenyl)propionic Acid (BMPPA) Market
Chemicals
Scouring Agents Market
Chemicals
Quaternium-15 Market
Chemicals
Malaysia Construction Chemicals Market
Chemicals
Dimethylaminopropylamine (DMAPA) Market
Chemicals
Coagulant Market
Chemicals
Acetophenone Market
Chemicals
Bakers Ammonia Market
Chemicals
Bronopol Market
Chemicals
Mining Flotation Chemicals Market
Chemicals
Cumene Hydroperoxide Market
Chemicals
Anticoagulant Rodenticides Market
Chemicals
Potassium Fluoride Market
Chemicals
Africa Mining Chemicals Market
Chemicals
Industrial Hydrofluoric Acid Market