
 Chemical Dust Suppressants Market | 2026-2036
Chemical Dust Suppressants Market Size, Share, and Industry Trends Forecast 2026-2036
Chemical Dust Suppressants Market Analysis
Direct sales channels for bulk chemical formulations is rewriting procurement relationships between suppressant manufacturers and mining conglomerates. BASF SE leverages its polymer research infrastructure to sustain long-term supply contracts with Australian iron ore producers. Ecolab Inc. anchors its position through integrated water-and-dust management programs across North American coal operations. Midwest Industrial Supply Inc. competes on geographic proximity to Powder River Basin mines, reducing logistics exposure for rail-shipped concentrate.
Chemical dust suppressants are formulated liquid or solid compounds—typically lignin sulfonates, calcium chlorides, synthetic acrylic copolymers, or vegetable oil derivatives—applied to unpaved surfaces or material stockpiles to agglomerate fine particles and reduce airborne particulate generation below regulatory thresholds. Liquid suppressants dominate current procurement volumes due to ease of spray application and compatibility with existing water truck fleets. Synthetic polymers capture premium pricing in high-traffic mining corridors where rainfall variability demands extended performance duration. Natural binders from agricultural byproducts are gaining traction among agricultural producers seeking biodegradable alternatives to chloride-based formulations.
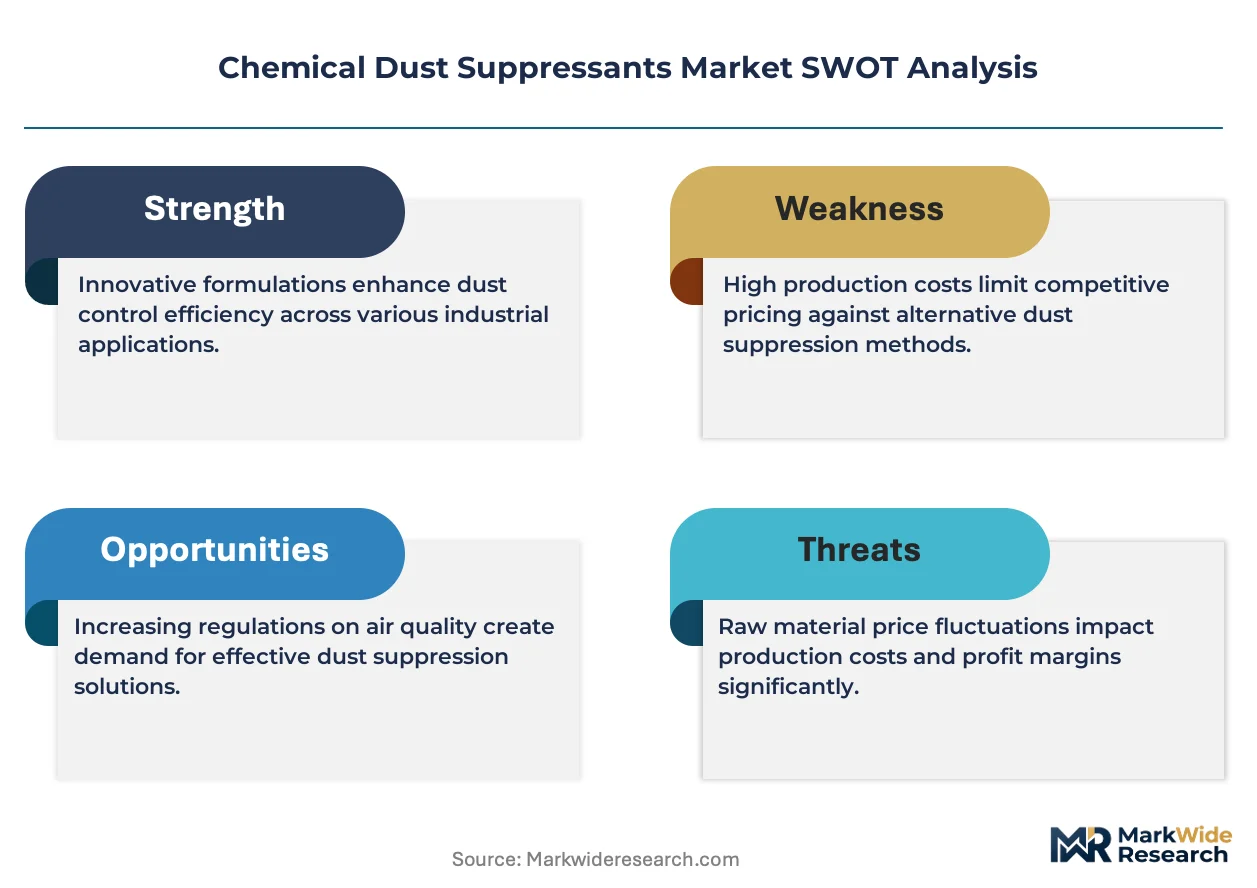
EPA enforces National Ambient Air Quality Standards for PM10 and PM2.5 that directly mandate fugitive dust controls at mining and construction sites, while MEE implements GB 16297 emission standards requiring chemical stabilization of coal storage yards in China. REACH registration requirements in Europe restrict certain chloride-based formulations, redirecting formulation investment toward polymer and bio-based alternatives. Stakeholders must monitor regulatory divergence between jurisdictions to align product portfolios with shifting compliance baselines and emerging restrictions on persistent chemistries.
Market Dynamics
Regulatory tightening on particulate emissions is compressing operational margins for open-pit miners while simultaneously expanding the addressable market for high-performance chemical stabilizers. Procurement departments now weight suppressant longevity against water consumption metrics, shifting specification criteria toward polymer-based formulations.
Growth Catalysts
- EPA PM10 enforcement:Mining operations in the Powder River Basin face escalating penalties for fugitive dust violations, accelerating chemical suppressant adoption over water-only spraying protocols.
- Haul road traffic intensity:Pilbara iron ore corridors now process triple the tonnage per kilometer versus 2015 baselines, exhausting traditional chloride treatments and mandating synthetic polymer upgrades.
- Vegetable oil derivatives:Agricultural waste streams from Brazilian soybean processing are supplying lignin sulfonate alternatives that biodegrade within 90 days, satisfying watershed protection mandates.
Market Restraints
- Acrylic monomer cost volatility:Synthetic polymer feedstock prices track propylene oxide markets, exposing formulators to petrochemical margin compression without pass-through pricing power.
- Chloride corrosion liability:Calcium and magnesium chloride formulations face structural substitution risk as infrastructure owners document accelerated rebar degradation in treated haul roads.
- REACH authorization delays:ECHA scrutiny of persistent organic compounds extends registration timelines for novel bio-based chemistries, freezing European product launches.
Strategic Opportunities
- Inner Mongolia coal yards:MEE enforcement of GB 16297 standards at uncontrolled storage sites creates immediate demand for dust suppression retrofitting across 400-plus facilities.
- Spray drone distribution:Agricultural aviation contractors are repurposing crop-dusting fleets for suppressant application, opening rural construction and quarry markets previously inaccessible to water truck logistics.
- Dual carbon policy alignment:China's national carbon neutrality targets reward water-conserving dust control methods with provincial green financing preferences.
Industry Challenges
- Application engineering shortage:Mining contractors lack personnel trained in polymer dosing calibration, resulting in uneven coverage and premature surface failure.
- Legacy water truck fleet incompatibility:Existing spray equipment requires pump and nozzle retrofits to handle viscous synthetic formulations without clogging.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chemical Dust Suppressants Market |
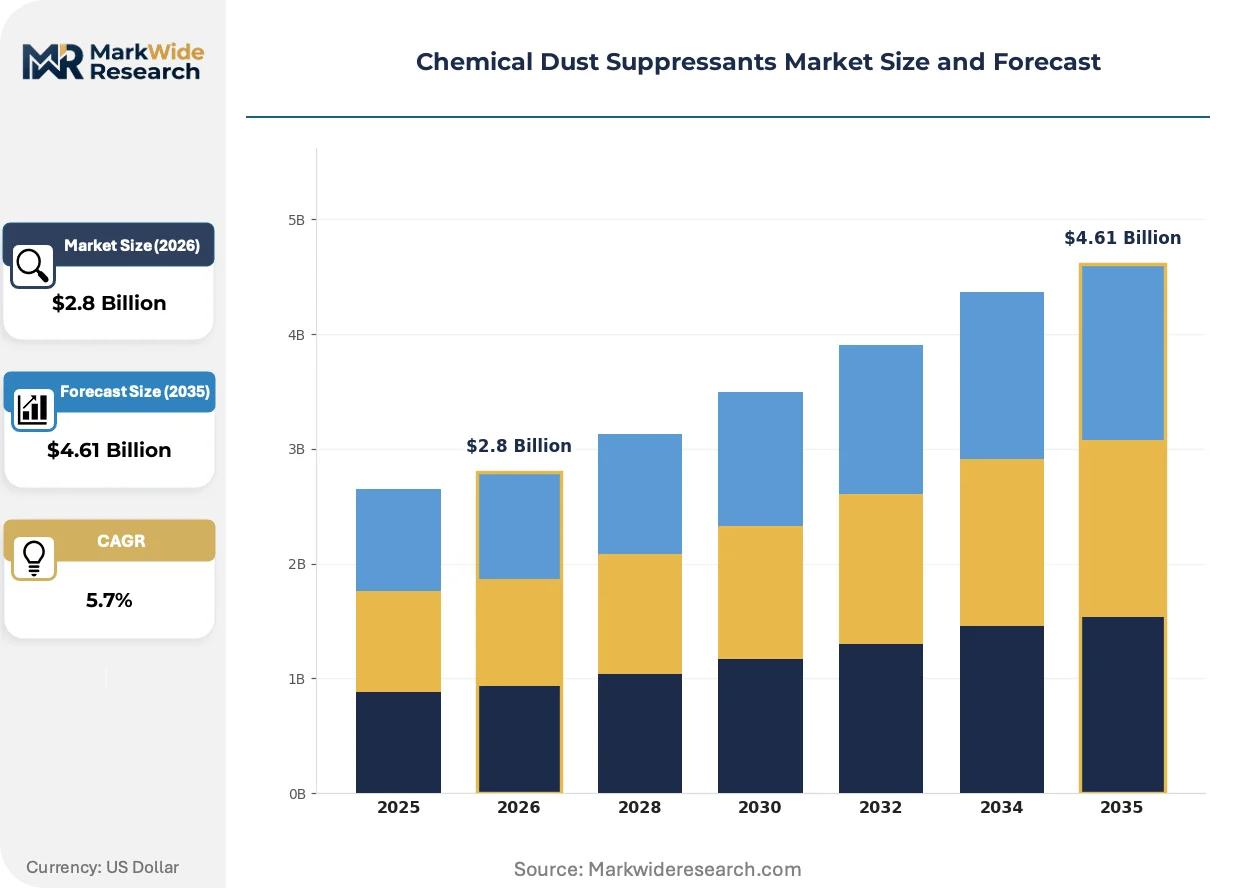
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Suppressants, Granular Suppressants, Synthetic Polymers, Natural Binders Application: Mining Operations, Construction Sites, Unpaved Roads, Agriculture End User: Mining Companies, Construction Firms, Agricultural Producers, Municipalities Distribution Channel: Direct Sales, Online Retail, Distributors, Resellers |
| Companies Covered | Veolia Environnement S.A., Soilworks, LLC, Ecolab Inc., Solenis LLC, BASF SE, Borregaard AS, Cargill, Incorporated, Midwest Industrial Supply Inc., Quaker Houghton, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chemical Dust Suppressants Market Emerging Trajectories
Formulation chemistry and application hardware are converging to extend suppressant efficacy windows while reducing water intensity. Equipment manufacturers and chemical suppliers are co-developing integrated systems rather than selling discrete components.
Enzyme-modified lignin sulfonates are collapsing the performance gap between agricultural byproducts and synthetic polymers. Australian coal operators in the Bowen Basin have adopted these formulations for secondary haul roads where traffic frequency does not justify premium acrylic copolymers. The technology is collapsing price stratification in mid-tier mining segments that previously accepted chloride-only treatment.
MEE's 2023 revision of emission calculation methodologies for coal storage yards now mandates continuous particulate monitoring rather than periodic inspection. This regulatory shift forces facility operators toward automated suppressant injection systems tied to real-time dust detection. Northern Chinese port terminals are retrofitting stacker-reclaimers with integrated spray bars to maintain compliance during vessel loading operations.
Volume-based procurement contracts are losing ground to performance guarantees indexed against measurable PM10 reduction. Mining conglomerates in Western Australia now negotiate payment terms contingent on third-party air quality verification rather than liters delivered. This behavioral shift concentrates supplier selection among formulators willing to assume operational risk and maintain on-site technical staff.
Chemical Dust Suppressants Market Segmentation
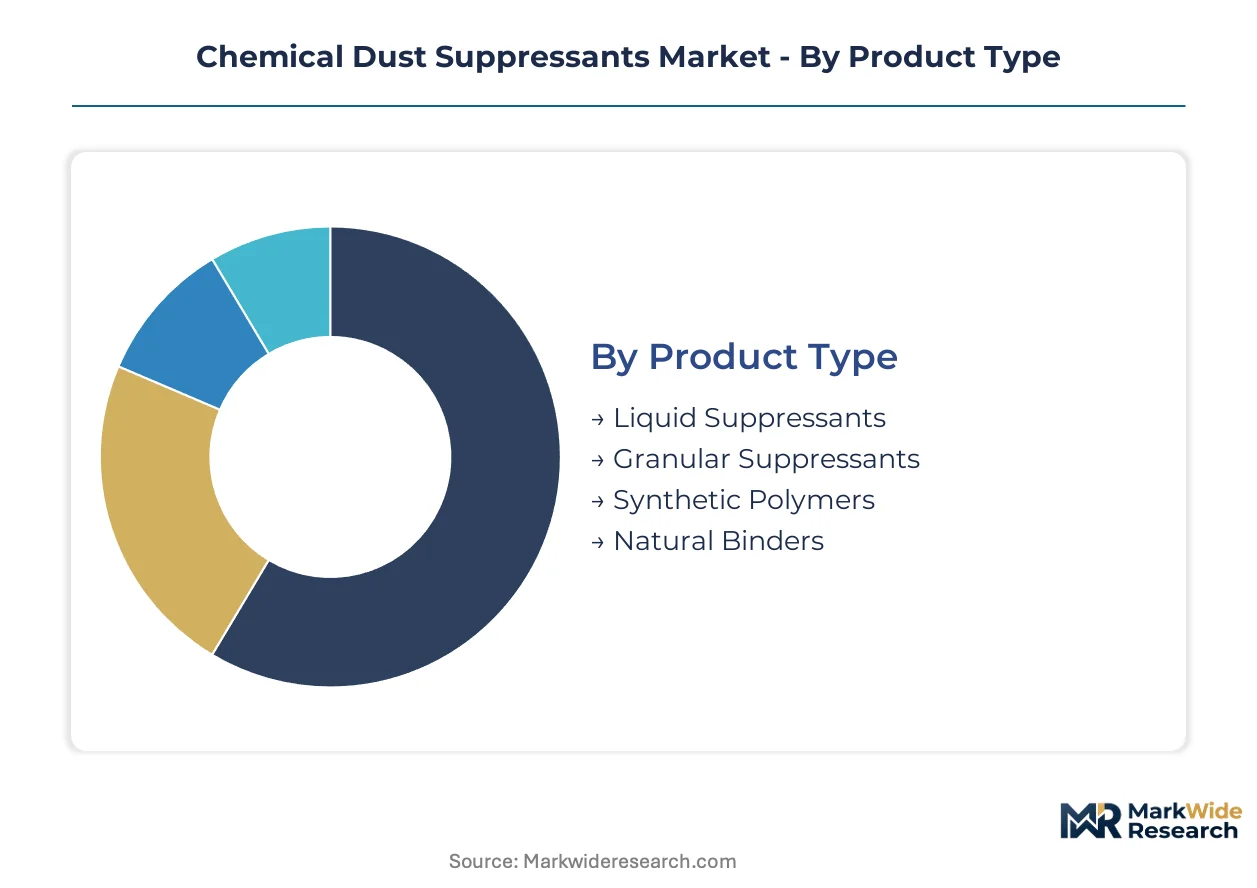
Chemical dust suppressant procurement varies sharply by application environment and performance requirements. Mining corridors demand polymer longevity while agricultural users prioritize biodegradability. Formulation chemistry, application method, and regulatory exposure all shift across these divides.
Product Type:
After-sales-service intensity runs highest for synthetic polymer installations requiring on-site calibration support and performance guarantees.
- Liquid Suppressants:Water-based emulsions and solutions compatible with standard spray equipment dominate procurement volumes. Australian iron ore haul roads and Powder River Basin coal corridors specify these formulations for rapid coverage of high-traffic surfaces. By volume, Liquid Suppressants lead. By growth pace, Synthetic Polymers are gaining share fastest.
- Synthetic Polymers:Acrylic copolymers and polyvinyl acetate derivatives form durable surface crusts resistant to rainfall erosion. Pilbara mining operators specify these for primary haul roads where traffic intensity exhausts chloride treatments within weeks. Premium pricing reflects extended reapplication intervals and reduced water consumption.
- Granular Suppressants:Solid calcium chloride and magnesium chloride pellets dissolve with humidity to agglomerate surface particles.
- Natural Binders:Lignin sulfonates and vegetable oil derivatives from agricultural waste streams biodegrade within regulatory windows.
Cost tier separation is pronounced: synthetic polymers command 3-4x pricing over chloride granules.
Application:
Volume concentration tracks extractive industry activity, with mining procurement dwarfing other segments.
- Mining Operations:Open-pit iron ore, copper, and coal extraction generates the largest addressable demand. Western Australia's Pilbara region and China's Inner Mongolia autonomous region concentrate procurement volumes where EPA and MEE enforcement intensifies compliance spending. By volume, Mining Operations lead. By growth pace, Agriculture is climbing the fastest.
- Unpaved Roads:Rural infrastructure and industrial access routes require periodic treatment to control fugitive dust.
- Construction Sites:Earthmoving and demolition activities generate temporary dust plumes requiring suppression during active phases.
- Agriculture:Harvest residue management and unpaved farm roads drive demand for biodegradable formulations satisfying watershed protection mandates.
Mining contracts anchor supplier revenue; construction and agricultural segments offer volume expansion.
End User:
Customer sophistication determines specification complexity and technical support requirements.
- Mining Companies:Integrated operators in Australia and Chile negotiate performance-based contracts with air quality verification clauses. Procurement departments weight suppressant longevity against water consumption metrics, shifting specifications toward polymer formulations.
- Construction Firms:Project-based purchasing favors lower-cost chloride treatments for temporary dust control.
- Agricultural Producers:Brazilian soybean processors and Midwest grain operations specify biodegradable binders for environmental compliance.
- Municipalities:County road departments balance budget constraints with resident complaints about unpaved road dust.
Mining companies concentrate premium demand; municipalities represent price-sensitive volume.
Distribution Channel:
Supply chain configuration varies by order scale and formulation handling requirements.
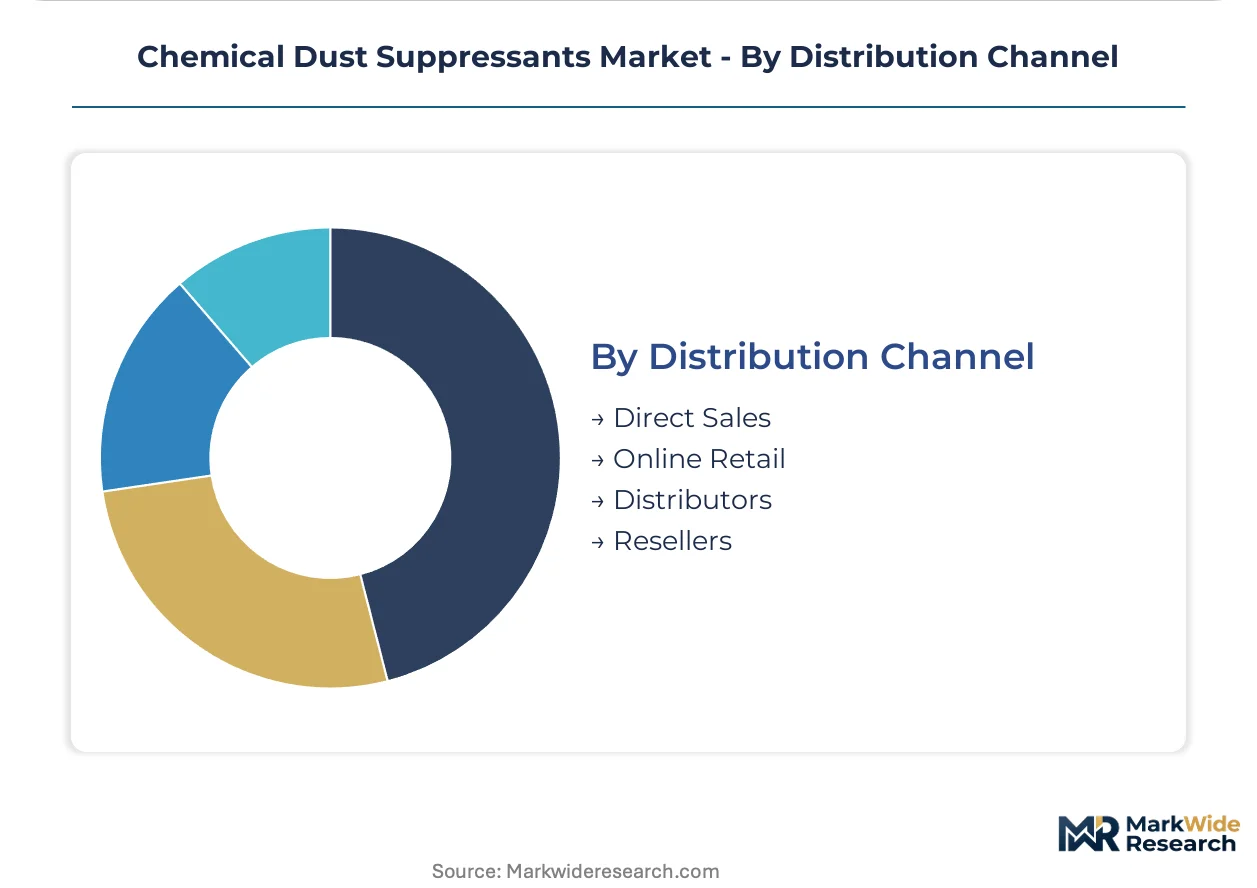
- Direct Sales:Bulk chemical formulations move through manufacturer-to-mine relationships. BASF SE and Ecolab Inc. sustain long-term supply contracts with Australian and North American operators respectively, embedding technical staff for dosing calibration and performance monitoring.
- Distributors:Regional chemical distributors serve mid-tier mining contractors and construction firms without direct manufacturer relationships.
- Resellers:Independent agents aggregate small agricultural and municipal orders.
- Online Retail:Packaged granular products for residential and light commercial use.
Direct sales capture mining value; distributors and resellers fragment agricultural and construction access.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Pilbara heavy-haul rail network underwrites Australia's dominance in iron ore dust suppression procurement. China's Daqin coal corridor similarly anchors Asian demand volumes. These infrastructure assets concentrate chemical suppressant deployment at loading points and along transport routes.
Australia
Pilbara iron ore producers face EPA-equivalent state enforcement on fugitive dust from haul roads and port stockpiles. Western Australia's Department of Water and Environmental Regulation mandates continuous PM10 monitoring at major extraction sites. BHP and Rio Tinto operations around Port Hedland and Dampier anchor polymer suppressant procurement volumes exceeding regional peers.
China
Inner Mongolia coal yards and Shanxi coking facilities drive demand under tightening MEE emission standards. GB 16297 compliance deadlines force retrofits across 400-plus uncontrolled storage sites. Tianjin and Qinhuangdao port terminals deploy automated spray systems during vessel loading to meet revised calculation methodologies.
United States
Powder River Basin coal operations confront escalating EPA penalties for PM10 violations on unpaved haul corridors. Wyoming and Montana state regulators coordinate with federal enforcement to mandate chemical stabilization over water-only protocols. Rail-shipped concentrate from Gillette and Wright loadouts requires suppressant treatment to prevent particulate loss during transport.
Chile
Atacama Desert copper extraction generates extreme dust conditions requiring extended-performance formulations. Antofagasta Minerals and Codelco operations around Calama and Chuquicamata specify synthetic polymers resistant to rainfall variability. Chile's environmental regulator SMA enforces stricter particulate thresholds near populated areas, concentrating compliance spending at coastal processing facilities.
Brazil
Soybean processing waste streams supply lignin sulfonate alternatives for agricultural dust control. Brazilian soybean processors in Mato Grosso and Paraná states specify biodegradable binders satisfying watershed protection mandates. ANVISA and state environmental agencies coordinate on chemistries acceptable for food-adjacent agricultural operations.
Chemical Dust Suppressants Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream supplying formulation chemistry and application hardware. The market structures around three tiers: multinational chemical conglomerates with polymer research infrastructure, regional distributors with logistics proximity to mining clusters, and agricultural processors repurposing waste streams into natural binders. Competitive moves concentrate on performance-guarantee contracting and embedded technical staffing at customer sites.
Among European-headquartered chemical conglomerates, BASF SE and Veolia Environnement S.A. exemplify platform integrators leveraging polymer research infrastructure for long-term supply relationships. Borregaard AS represents the agricultural-waste-to-binder archetype, converting lignin byproducts into suppressant formulations. These three occupy positions spanning synthetic chemistry, integrated environmental services, and bio-based alternatives respectively.
| Leading Market Players |
|---|
| Veolia Environnement S.A. |
| Soilworks, LLC |
| Ecolab Inc. |
| Solenis LLC |
| BASF SE |
| Borregaard AS |
| Cargill, Incorporated |
| Midwest Industrial Supply Inc. |
| Quaker Houghton |
| Others |
Supply Flow & Price Mechanics
The Pilbara heavy-haul rail corridor's freight cost dynamics concentrate supply power among polymer formulators with Western Australian logistics infrastructure, while downstream price differentiation separates mining conglomerates with performance-guarantee contracts from municipal buyers purchasing chloride granules through distributors.
Pricing Analysis
Three-tier pricing structure across premium polymer, standard liquid emulsion, and economy chloride levels dominates procurement negotiations. Price differentiation hinges on formulation longevity and embedded technical service intensity, with synthetic acrylic copolymers commanding substantial premiums over lignin sulfonate alternatives. Pricing pressure stems from acrylic monomer feedstock volatility tracking propylene oxide markets, squeezing formulator margins without full pass-through elasticity. Mining companies demonstrate lowest price sensitivity due to operational risk transfer in performance-based contracts, while agricultural producers and municipalities exhibit acute cost consciousness favoring biodegradable or chloride formulations.
Supply Chain Analysis
Upstream feedstock sourcing for synthetic polymers centers on petrochemical complexes in the United States, Germany, and China, while lignin sulfonate precursors draw from Brazilian soybean processing and Scandinavian pulp milling operations. Raw material dependencies encompass propylene oxide derivatives, agricultural lignin waste streams, and calcium chloride brine extraction. Single-source vulnerability concentrates in specialty acrylic monomer supply, where limited global production capacity creates bottleneck exposure. Distribution runs through direct manufacturer-to-mine relationships for bulk polymer contracts, with regional chemical distributors fragmenting access for mid-tier mining contractors and construction segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where regulatory entrenchment creates substantial switching costs: mining operators cannot easily substitute established suppressant systems without retraining application personnel and renegotiating air quality compliance protocols.
For Market Incumbents: Insulate contract positions by embedding technical calibration staff at Pilbara and Powder River Basin operations, converting supply relationships into operational partnerships. Pursue backward integration into acrylic monomer supply through captive offtake agreements with propylene oxide producers, reducing exposure to petrochemical margin volatility. Prioritize certification investment for enzyme-modified lignin formulations to capture agricultural sector expansion while defending polymer dominance in mining corridors. For New Entrants and Emerging Players: Agricultural aviation contractors repurposing crop-dusting fleets for suppressant application represent the most penetrable entry point, opening rural construction and quarry markets previously inaccessible to water truck logistics. Spray drone distribution networks in Brazil's Mato Grosso soybean belt and Australia's wheat regions offer second-tier expansion vectors. A go-to-market angle emphasizing biodegradable performance guarantees indexed against watershed protection mandates differentiates against incumbent chloride suppliers. For Investors and Strategic Acquirers: Regional distributors with logistics proximity to Inner Mongolia coal clusters and Powder River Basin loadouts present acquisition targets with embedded customer relationships and regulatory compliance expertise. Long-term viability centers on water-conserving formulation chemistry aligned with tightening EPA and MEE emission standards. The signal to monitor is MEE enforcement velocity at uncontrolled Chinese storage sites, which would accelerate retrofit demand and validate premium polymer pricing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acrylic Monomer Supply | Captive propylene oxide sourcing insulates BASF and Veolia from petrochemical margin compression. |
| Enzyme-Modified Lignin Formulation Certification | Borregaard's bio-based alternatives collapse price stratification in mid-tier mining segments. |
| Spray Drone Distribution Partnership | Agricultural aviation contractors unlock rural quarry markets beyond water truck logistics reach. |
| Performance-Guarantee Contract Structuring | Ecolab's air-quality-verified payment terms transfer operational risk from Pilbara miners. |
| Automated Injection System Integration | Real-time dust detection tie-ins at Tianjin port terminals satisfy MEE continuous monitoring mandates. |
Methodological Framework
A spread of perspectives from mining procurement directors, chemical plant managers, environmental compliance officers, and agricultural aviation contractors converged on the working assumptions underpinning this analysis. Primary field engagement with Western Australian iron ore operators, Inner Mongolia coal yard managers, and Powder River Basin logistics coordinators was cross-referenced against EPA enforcement records, MEE emission standard filings, customs trade data for suppressant chemical flows, and SEC 10-K disclosures from listed chemical conglomerates. Bottom-up volume triangulation from individual facility procurement patterns was reconciled with top-down market sizing derived from extractive industry production forecasts.
Demand-supply-balance modeling across the analysis window incorporated formulation chemistry tier, application environment severity, end-user sophistication level, and regional regulatory enforcement intensity as core segmentation dimensions. CAGRs were derived from regression analysis of historical procurement volumes against mining production indices and enforcement penalty escalation trends. Industry-specific forecast inputs encompassed Pilbara haul road traffic intensity projections and MEE retrofit timelines for uncontrolled coal storage sites.
Practitioners should monitor acrylic monomer price volatility, REACH authorization delays for novel bio-based chemistries, and MEE calculation methodology revisions for early signals requiring forecast adjustment. Cross-checking against EPA civil penalty enforcement databases and Australian state environmental regulator inspection records is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cleaning Chemicals
Dry Electrostatic Wipes Market
Cleaning Chemicals
Brazil Industrial and Institutional Cleaning Chemicals Market
Cleaning Chemicals
Pipeline Chemical Cleaners Market
Cleaning Chemicals
Surface Cleaning Products Market
Cleaning Chemicals
Descaler Market
Cleaning Chemicals
Commercial Cleaning Products Market
Cleaning Chemicals
Deck Brightener Market
Cleaning Chemicals
Chlorinating Agents Market
Cleaning Chemicals
US Specialty Cleaners Market
Cleaning Chemicals
Mastic Remover Market
Cleaning Chemicals
Water Soluble Detergent Pods Market
Cleaning Chemicals
Cleaning Products Market
Cleaning Chemicals
North America Surface Treatment Chemicals Market
Cleaning Chemicals
Latin America Detergent Market
Cleaning Chemicals
Rust Remover Market
Cleaning Chemicals
Soap and Detergent Market