
 Aluminum Sulfate Market | 2026-2036
Aluminum Sulfate Market Size, Share, and Industry Trends Forecast 2026-2036
Aluminum Sulfate Market Analysis
Ferric chloride is consolidating share in North American municipal coagulant selection, yet aluminum sulfate retains cost advantages in low-turbidity source waters. Kemira Oyj leverages integrated bauxite-to-sulfate production across Nordic sites. Feralco AB anchors European municipal supply through dedicated flocculant distribution networks. Chemtrade Logistics competes on bulk liquid delivery density across Great Lakes watershed utilities.
Aluminum sulfate is an inorganic salt produced by reacting aluminum hydroxide with sulfuric acid, yielding a coagulant with typical commercial grades at 17-18% Al2O3 content. The compound destabilizes suspended colloids in raw water through charge neutralization, enabling particle aggregation for subsequent sedimentation or filtration. Liquid formulations dominate North American municipal procurement due to reduced handling labor and automated dosing compatibility, while granular and powder grades sustain margin pools in Asian textile dyeing operations where precise batch control matters. Water treatment applications lead volume globally, though paper and pulp retention-aid demand is accelerating fastest as packaging-grade recycled fiber content rises.
The US EPA Safe Drinking Water Act and China's MEE surface water standards both mandate enhanced coagulation for disinfection byproduct precursor removal, directly shaping aluminum sulfate purity specifications and certified supplier lists. REACH registration requirements in Europe restrict non-compliant imports, while India's BIS certification for drinking water chemicals creates parallel compliance pathways for domestic manufacturers. Stakeholders must monitor regulatory divergence between chloramine-disinfecting utilities favoring low-manganese sulfate grades and ozone-based systems tolerating broader impurity bands.
Market Dynamics
Municipal water utilities face replacement cycles for aging coagulation infrastructure while tightening purity standards from the US EPA and China's MEE reshape supplier qualification lists. This dual pressure is concentrating procurement among certified producers with integrated bauxite sourcing.
Growth Catalysts
- US EPA Safe Drinking Water Act mandates:Enhanced coagulation requirements for disinfection byproduct precursor removal are expanding certified aluminum sulfate procurement across Great Lakes and Mississippi River watershed utilities.
- Paper and pulp packaging fiber transition:Rising recycled content in corrugated packaging is accelerating retention-aid demand for aluminum sulfate in brown-stock washing operations.
- China's industrial corridor expansion:Chemical belt cities in Shandong and Jiangsu provinces are scaling wastewater treatment capacity, driving bulk liquid coagulant offtake.
Market Restraints
- Bauxite cost volatility:Guinea and Australian bauxite supply disruptions transmit directly to aluminum sulfate feedstock pricing, compressing margin stability for non-integrated producers.
- Ferric chloride substitution:North American utilities in high-turbidity source water regions are switching to ferric-based coagulants for superior phosphorus removal performance.
- REACH registration barriers:European Chemicals Agency compliance costs block non-EU importers from accessing municipal tender pools in Germany and France.
Strategic Opportunities
- India's BIS certification pathway:Domestic manufacturers in Gujarat and Maharashtra can capture municipal water treatment share as import substitution policies tighten.
- Ozone-tolerant grade segmentation:Utilities employing ozone disinfection tolerate broader impurity bands, enabling cost-optimized product lines distinct from chloramine-compatible low-manganese grades.
- Automated dosing system integration:Liquid formulation producers can embed sensors and control software into bulk delivery contracts, creating recurring service revenue streams.
Industry Challenges
- Dual certification timeline compression:Suppliers seeking simultaneous US EPA and China MEE approval face divergent testing protocols that extend qualification cycles.
- Legacy granular infrastructure retrofit:Asian textile dyeing operations with powder-handling equipment resist conversion to liquid systems despite labor savings.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aluminum Sulfate Market |
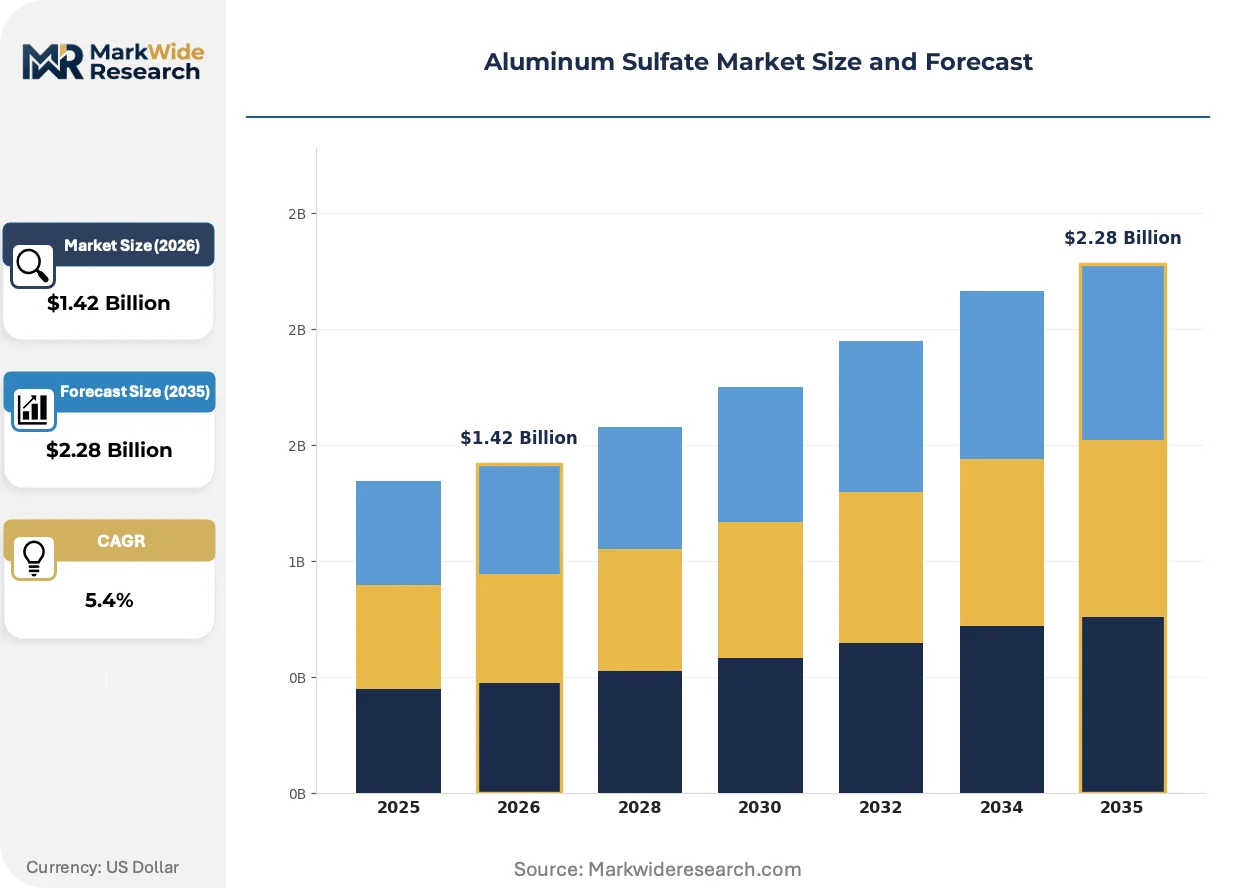
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.28 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granular, Liquid, Powder, Crystals End Use Industry: Water Treatment, Paper & Pulp, Textile, Food Processing Packaging Type: Bag, Drum, Bulk, Tote Application: Coagulation, Flocculation, pH Adjustment, Water Softening |
| Companies Covered | Feralco AB, Affinity Chemical, Chemtrade Logistics, Aditya Birla Chemicals, GAC Chemical Corporation, USALCO, Nippon Light Metal Company, Gujarat Alkalies and Chemicals, Kemira Oyj, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aluminum Sulfate Market Emerging Trajectories
Coagulant chemistry is converging with digital water management platforms, reshaping how utilities specify and procure treatment chemicals. Three interconnected developments are redefining competitive positioning.
High-purity low-manganese aluminum sulfate grades are absorbing premium positioning in chloramine-disinfecting utility contracts. North American municipal buyers with automated dosing infrastructure are specifying these grades for reduced manganese leaching risk. This specification tier is compressing commodity-grade margin pools while rewarding producers with bauxite-to-sulfate integration.
REACH registration requirements in Europe are fragmenting import access and fortifying domestic producer market positions. The European Chemicals Agency's substance evaluation protocols now demand extensive ecotoxicological dossiers for coagulant chemicals. German and French municipal tender boards are restricting qualified supplier lists to REACH-registered entities, excluding North African and Middle Eastern competitors.
Bulk liquid delivery contracts with embedded telemetry are displacing traditional spot procurement in watershed-scale utilities. Great Lakes and Ohio River basin water authorities are consolidating annual coagulant awards among three to four certified suppliers with dedicated tanker fleets. This buyer concentration is compressing distributor margins while rewarding producers with logistics density in specific drainage basins.
Aluminum Sulfate Market Segmentation
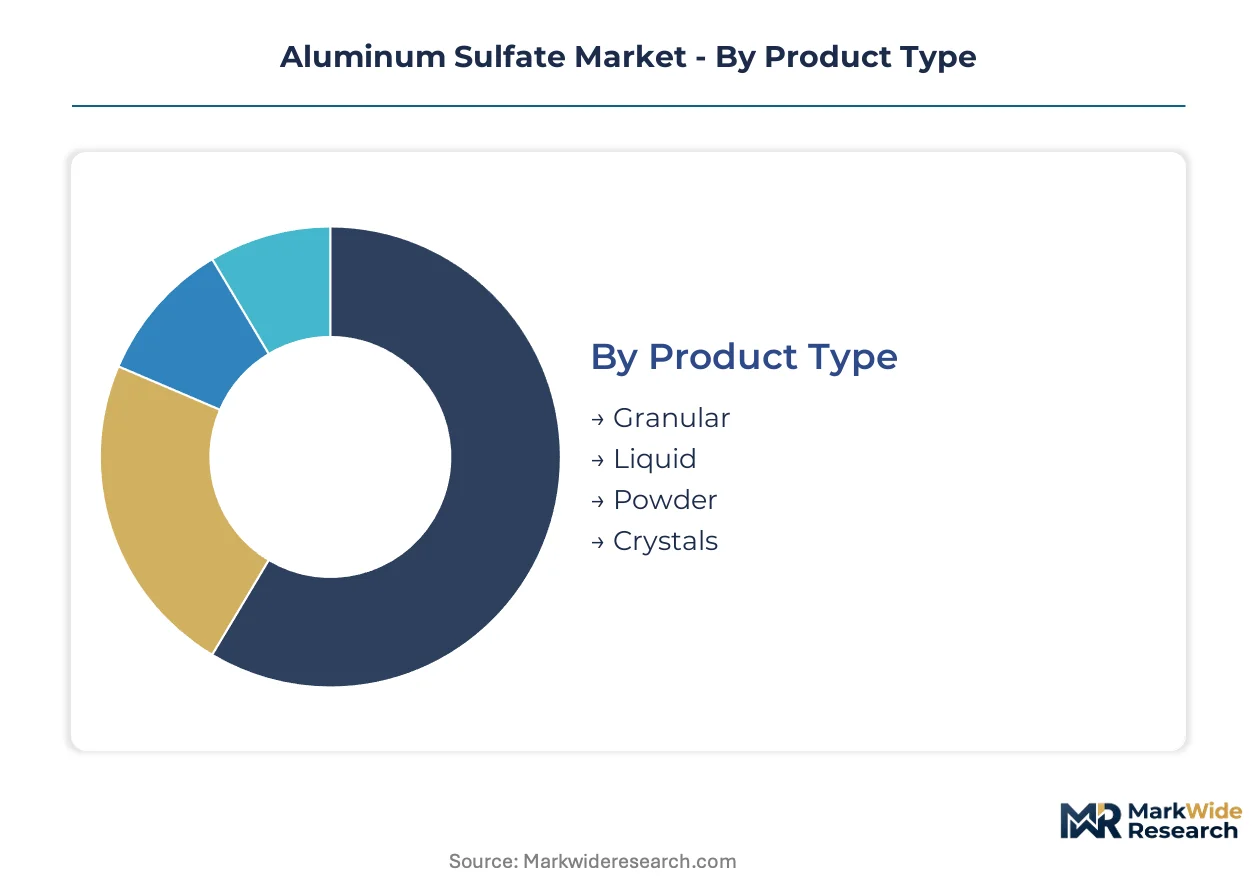
Aluminum sulfate procurement patterns diverge sharply between automated municipal utilities and batch-process industrial users. Specification tiers, packaging logistics, and application chemistry each create distinct margin pools that suppliers must navigate simultaneously.
Product Type:
Form selection hinges on handling infrastructure investment and dosing precision requirements.
- Liquid:Aqueous solutions at 48-50% concentration dominate North American municipal contracts. Great Lakes watershed utilities specify liquid grades for automated pump-and-control systems that cut labor costs and enable real-time turbidity response.
- Granular:Free-flowing particles at 17-18% Al2O3 content sustain Asian textile dyeing operations. Gujarat chemical belt manufacturers prefer granular feedstock for precise batch weighing in vat-dyeing processes where color consistency dictates reject rates.
- Powder:Finely ground material serves legacy paper mill retention-aid systems with pneumatic conveying infrastructure.
- Crystals:Large-format solid blocks target remote mining camp water treatment with minimal storage footprint.
Volume sits with Liquid; growth tilts toward Granular as India's chemical corridor expands.
End Use Industry:
Regulatory stringency and fiber economics reshape demand concentration across downstream sectors.
- Water Treatment:Municipal coagulation for surface water clarification absorbs the largest volume share. US EPA enhanced coagulation mandates and China's MEE surface water standards both tighten Al2O3 purity floors while certifying supplier lists.
- Paper & Pulp:Retention-aid demand climbs fastest as corrugated packaging shifts toward 90%+ recycled fiber content. Brown-stock washing operations in Wisconsin and Finland specify aluminum sulfate for fines retention without optical brightener interference.
- Textile:Dye-fixing applications concentrate in Shandong province's industrial corridor where wastewater discharge permits cap heavy metal content.
- Food Processing:Food-grade certification restricts supply to BIS-registered Indian manufacturers and FDA-inspected US facilities for edible oil clarification.
Procurement concentrates in Water Treatment; margin expansion tilts toward Paper & Pulp.
Packaging Type:
Logistics density and handling automation separate procurement tiers.
- Bulk:Tanker-trailer delivery locks in watershed-scale utilities with dedicated storage tanks. Ohio River basin authorities award three-year bulk contracts to producers with fleet presence.
- Drum:55-gallon steel containers serve mid-size paper mills with intermediate storage capacity and forklift handling.
- Tote:Intermediate bulk containers gain share in automated textile dye houses with pump-fed batch systems.
- Bag:50-pound multi-wall sacks sustain small municipal plants and food processors without liquid infrastructure.
Contract value aggregates in Bulk; flexibility premiums accrue to Drum.
Application:
Functional chemistry dictates specification granularity and certification burden.
- Coagulation:Charge neutralization of negatively charged colloids in raw water. Chloramine-disinfecting utilities specify low-manganese grades under US EPA Safe Drinking Water Act protocols.
- Flocculation:Bridging destabilized particles into settleable flocs. Paper machine wet-end chemistry favors high-basicity aluminum sulfate variants for fines retention.
- pH Adjustment:Acidic hydrolysis releases hydrogen ions for alkaline wastewater neutralization. Textile finishing houses in Jiangsu province deploy aluminum sulfate for effluent pH correction ahead of discharge.
- Water Softening:Precipitation of carbonate hardness as aluminum hydroxide floc. Niche deployment in small-scale groundwater treatment with high temporary hardness.
Specification intensity peaks in Coagulation; application breadth expands fastest in pH Adjustment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in China's industrial corridor cities and India's Gujarat chemical belt, with municipal water treatment utilities driving procurement across both manufacturing hubs and mature infrastructure markets.
United States
Great Lakes watershed utilities and Mississippi River basin authorities are expanding coagulant procurement under US EPA Safe Drinking Water Act enhanced coagulation mandates. The agency's revised guidelines tighten product purity requirements and certify supplier lists. Ohio River basin water authorities award multi-year bulk contracts to producers with dedicated tanker fleet presence.
China
Shandong and Jiangsu province chemical belt cities are scaling wastewater treatment capacity, driving bulk liquid coagulant offtake. The MEE surface water standards mandate enhanced coagulation for disinfection byproduct precursor removal. Qingdao and Nanjing industrial clusters concentrate procurement among certified producers with integrated bauxite sourcing.
India
Gujarat and Maharashtra domestic manufacturers capture municipal water treatment share as BIS certification for drinking water chemicals creates parallel compliance pathways. The country's import substitution policies tighten access for non-registered importers. Ahmedabad and Vadodara chemical belt operations sustain margin pools in textile dyeing applications.
Germany
REACH registration requirements restrict non-compliant imports from municipal tender pools. The European Chemicals Agency's substance evaluation protocols demand extensive ecotoxicological dossiers for coagulant chemicals. Rhine-Ruhr watershed utilities consolidate procurement among REACH-registered suppliers with dedicated distribution networks.
Japan
Paper and pulp retention-aid demand accelerates as corrugated packaging shifts toward higher recycled fiber content. METI industrial standards shape specification tiers for wet-end chemistry applications. Kansai region packaging-grade manufacturers specify aluminum sulfate for fines retention without optical brightener interference.
Aluminum Sulfate Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated bauxite-to-sulfate producers commanding premium positioning in certified municipal supply. The vendor base organizes around three archetypes: Nordic integrated producers with captive raw material access, European municipal specialists with dedicated flocculant distribution networks, and regional bulk liquid distributors competing on logistics density. Capacity expansion and automated dosing system integration represent the dominant competitive moves reshaping procurement relationships.
Among Nordic integrated producers, Kemira Oyj anchors the tier with bauxite-to-sulfate production across regional sites. Feralco AB exemplifies the European municipal specialist archetype through dedicated flocculant distribution networks. Chemtrade Logistics occupies a position among North American bulk liquid distributors competing on delivery density across Great Lakes watershed utilities.
| Leading Market Players |
|---|
| Feralco AB |
| Affinity Chemical |
| Chemtrade Logistics |
| Aditya Birla Chemicals |
| GAC Chemical Corporation |
| USALCO |
| Nippon Light Metal Company |
| Gujarat Alkalies and Chemicals |
| Kemira Oyj |
| Others |
Supply Flow & Price Mechanics
Great Lakes watershed utilities consolidating procurement among three to four certified suppliers with dedicated tanker fleets is compressing distributor margins while rewarding producers with logistics density in specific drainage basins. This buyer concentration forces non-integrated producers toward spot market exposure or costly certification investments, widening the spread between captive-bauxite and merchant-feedstock pricing tiers.
Pricing Analysis
Volume aggregates in liquid municipal contracts while margin pools concentrate in granular textile grades. Three-tier pricing structure across premium low-manganese, standard chloramine-compatible, and economy ozone-tolerant grades separates certified municipal supply from industrial commodity tiers. Cost compression in standard grades is intensifying because REACH registration barriers and bauxite volatility squeeze non-integrated producers. Municipal utilities with automated dosing infrastructure show least price sensitivity; Asian textile dye houses with legacy powder equipment show most.
Supply Chain Analysis
India's BIS certification pathway and China's MEE supplier qualification lists are reshaping sourcing toward domestic-content-compliant producers. Supply concentrates in China, India, and Finland, with bauxite feedstock drawing from Guinea and Australian mines. The supply chain rests on sulfuric acid and aluminum hydroxide inputs with single-source vulnerability in seaborne bauxite logistics. Distribution runs through dedicated flocculant networks in Europe and bulk liquid tanker fleets in North America.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where US EPA Safe Drinking Water Act certification creates a barrier-to-entry moat for qualified producers. The dual burden of purity mandates and integrated sourcing requirements divides winners from marginal players.
For Market Incumbents: Anchor municipal share through backward integration into bauxite sourcing and dedicated tanker fleet deployment in Ohio River and Great Lakes watersheds. Ferric chloride substitution in high-turbidity regions and REACH registration costs for European access represent priority defense levers. Certify simultaneously under US EPA and China MEE protocols to compress dual-qualification timelines. For New Entrants and Emerging Players: E-commerce-enabled bulk chemical platforms offer white-space entry into mid-size Indian textile dye houses and remote mining camp water treatment. India's Gujarat chemical belt presents the most penetrable geography given BIS certification requirements favoring domestic manufacture. Target automated dosing system integration as a service-layer wedge to bypass capital-intensive liquid infrastructure. For Investors and Strategic Acquirers: Re-rating potential sits with Nordic integrated producers given bauxite-to-sulfate captive supply and ozone-tolerant grade segmentation enabling premium tier capture. Long-term viability favors entities with watershed-scale logistics density and multi-regulatory certification portfolios. Watch for China MEE enforcement acceleration as the inflection signal tightening qualified supplier lists.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bauxite Sourcing | Guinean and Australian mine stakes insulate margin stability from seaborne supply disruptions. |
| REACH Registration Completion | ECHA substance evaluation protocols unlock German and French municipal tender pools. |
| Automated Dosing System Integration | Embedded telemetry and control software create recurring service revenue at Great Lakes utilities. |
| Ozone-Tolerant Grade Segmentation | Broader impurity tolerance enables cost-optimized product lines distinct from chloramine-compatible tiers. |
| Long-term Bulk Supply Agreement | Three-year Ohio River basin contracts lock in volume against spot market volatility. |
Methodological Framework
Multi-period observation of municipal procurement awards, bauxite import volumes, and certification timeline data anchored the trend analysis, supplemented by interviews with plant managers at Nordic integrated producers, procurement leads at Great Lakes watershed utilities, distribution channel partners in European flocculant networks, and technical R&D directors at textile chemical formulators. Secondary validation drew from US EPA certification databases, China MEE discharge permit filings, ECHA REACH registration records, and ACC trade flow statistics. Bottom-up segment sizing and top-down macro constraint triangulation cross-checked volume and value estimates.
Segment-weighting across product type, end-use industry, packaging format, and regional production hub shaped the analytical framework across the projection horizon. CAGRs derived from regression of historical procurement volumes against regulatory implementation timelines and infrastructure replacement cycles. Modeled inputs included brown-stock washing operation expansion in packaging-grade paper mills and Shandong-Jiangsu wastewater treatment capacity buildout.
The model holds under stable bauxite supply and continued regulatory enforcement; deviation in Guinea export disruptions or US EPA guideline revision would shift volume and value trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Sodium Tetraborate Market
Bulk Chemicals
Zinc Carbonate Market
Bulk Chemicals
North America Carbon Black Market
Bulk Chemicals
US Magnesium Stearate Market
Bulk Chemicals
Europe Barium Carbonate Market
Bulk Chemicals
Ethylene Dichloride Market
Bulk Chemicals
Vinyl Cyclohexane Market
Bulk Chemicals
Aniline Market
Bulk Chemicals
Nickel Carbonate Market
Bulk Chemicals
North America Caustic Potash Market
Bulk Chemicals
2,4-Dichlorophenoxyacetic Market
Bulk Chemicals
Global Vinyl Chloride Monomer Market
Bulk Chemicals
Needle Coke Market
Bulk Chemicals
Global Sodium Chloride Market
Bulk Chemicals
Sodium Hydrosulfide Market
Bulk Chemicals
Zinc L-Pidolate Market