
 Global Amines Market | 2026-2036
Global Amines Market Size, Share, and Industry Trends Forecast 2026-2036
Global Amines Market Analysis
Multi-source procurement for ethylene oxide and ammonia feedstocks is recalibrating how amine producers manage margin volatility. BASF SE leverages its integrated Ludwigshafen complex to sustain captive supply of critical intermediates. Evonik Industries anchors its competitive stance through specialized tertiary amine production for personal care and pharmaceutical applications. Huntsman Corporation competes by dominating aliphatic amine output for epoxy curing agents across North American industrial coatings channels.
Amines are nitrogen-containing organic compounds derived from ammonia by replacement of one or more hydrogen atoms with alkyl or aryl groups, typically manufactured through catalytic hydrogenation of nitriles or reductive amination of aldehydes and ketones, and function primarily as chemical intermediates, surfactants, corrosion inhibitors, and curing agents across industrial formulations. Primary amines occupy the largest volume share due to their foundational role in agrochemical and pharmaceutical active ingredient synthesis, while tertiary amines represent the fastest-expanding margin pool driven by quaternization demand in fabric softeners and biocidal formulations. The application split reveals pharmaceuticals and personal care as the highest-value outlets, whereas agricultural intermediates sustain the deepest volume throughput.
EPA toxicity evaluations under the Toxic Substances Control Act and REACH registration mandates administered by ECHA are elevating analytical certification burdens for amine exporters seeking US and European market access. China's SAMR enforces GB standards for residual solvent content in domestically produced amine grades, creating divergent compliance pathways for multinational suppliers. Stakeholders must monitor regulatory harmonization pressures between OECD chemical assessment frameworks and emerging economy standards to anticipate product reformulation requirements and territory-specific registration timelines.
Market Dynamics
REACH registration deadlines and EPA toxicity reassessments are compressing product development cycles while elevating purity certification costs for amine suppliers serving European and North American industrial channels.
Growth Catalysts
- Agrochemical intermediates:Formulators in Brazil and India are expanding tertiary amine purchases for crop protection synthesis, pulling volume through specialized chemical manufacturing corridors.
- Quaternization demand:Fabric softener and biocidal formulation producers are driving fastest-margin expansion in tertiary amine grades for household and institutional applications.
- Pharmaceutical synthesis:Primary amine consumption for active pharmaceutical ingredient production sustains deepest volume throughput across high-value therapeutic categories.
Market Restraints
- Feedstock volatility:Ethylene oxide and ammonia price swings compress producer margins when multi-source procurement strategies fail to synchronize with spot market movements.
- Regulatory friction:Divergent GB standards under China's SAMR versus REACH and EPA frameworks create parallel compliance pathways that fragment quality certification investments.
- Substitution pressure:Bio-based surfactant alternatives threaten tertiary amine demand in personal care applications where sustainability credentials determine supplier selection.
Strategic Opportunities
- Underpenetrated geographies:Specialty amine demand in Southeast Asian pharmaceutical manufacturing clusters offers expansion vectors beyond established Chinese and Indian supply bases.
- Regulatory tailwinds:EU Green Deal chemical sustainability mandates favor amine producers with verified low-carbon hydrogenation processes and renewable feedstock integration.
- Technology convergence:Catalytic membrane reactor advances combined with continuous flow processing enable modular plant designs that reduce capital intensity for mid-scale entrants.
Industry Challenges
- Analytical certification backlog:ECHA and EPA documentation requirements are extending product registration timelines by 12-18 months for novel amine derivatives.
- Legacy asset retrofit costs:Batch reactor facilities face capital-intensive upgrades to meet tightening residual solvent specifications under evolving OECD chemical assessment frameworks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Amines Market |
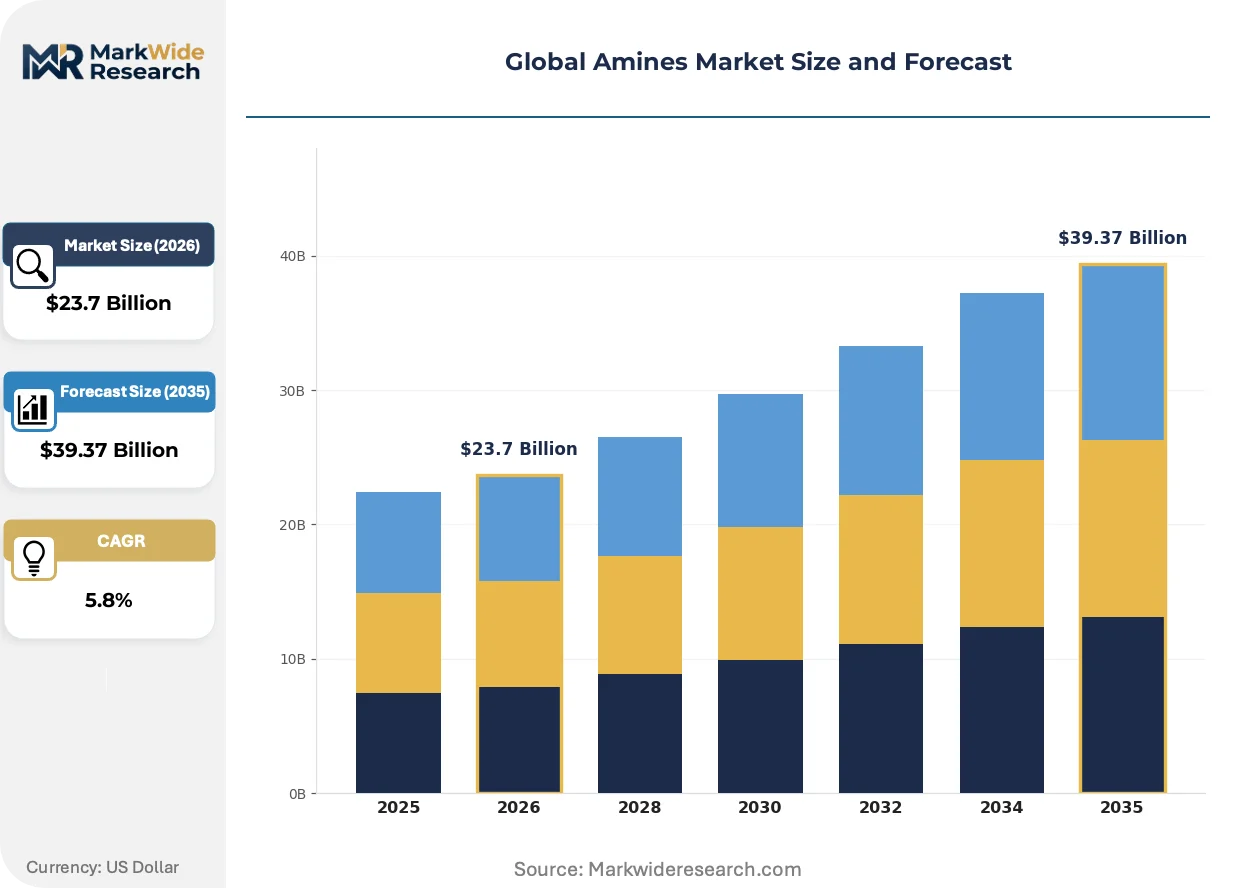
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $39.37 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Primary Amines, Secondary Amines, Tertiary Amines, Quaternary Amines Application: Personal Care, Pharmaceutical, Agriculture, Textile End Use Industry: Chemicals, Coatings, Plastics, Detergents Technology: Synthesis, Catalytic, Biological, Extraction |
| Companies Covered | Eastman Chemical Company, Evonik Industries, BASF SE, LyondellBasell Industries N.V., Arkema S.A., Dow Inc., Akzo Nobel N.V., Mitsubishi Chemical Corporation, Huntsman Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Amines Market Emerging Trajectories
Process intensification and regulatory harmonization pressures are compressing traditional manufacturing paradigms while opening differentiated positions for producers with advanced catalytic capabilities and multi-jurisdiction compliance infrastructure.
Continuous flow hydrogenation of nitriles is overtaking batch reactor operations in aliphatic amine production. Specialty chemical manufacturers serving North American epoxy curing agent channels are adopting these systems to reduce solvent handling and improve thermal efficiency. The technology is overtaking conventional fixed-bed configurations by enabling real-time purity adjustment that satisfies REACH and EPA certification demands without secondary refining steps.
ECHA's REACH registration mandates for existing amine substances are forcing reformulation investments across European personal care and agricultural chemical supply chains. The regulation compresses supplier lists to those with complete dossier submissions and validated analytical methods. German and Dutch formulators are consolidating purchases toward integrated producers with captive intermediate supply and in-house toxicology assessment capabilities.
Specification-driven procurement now dominates amine purchasing for pharmaceutical applications, displacing traditional spot-market volume contracting. Buyers in Swiss and Irish active ingredient manufacturing clusters are binding suppliers to multi-year purity guarantees with penalty clauses for deviation. This pattern concentrates supply relationships among producers with dedicated pharmaceutical-grade production lines and ISO-certified quality management systems.
Global Amines Market Segmentation
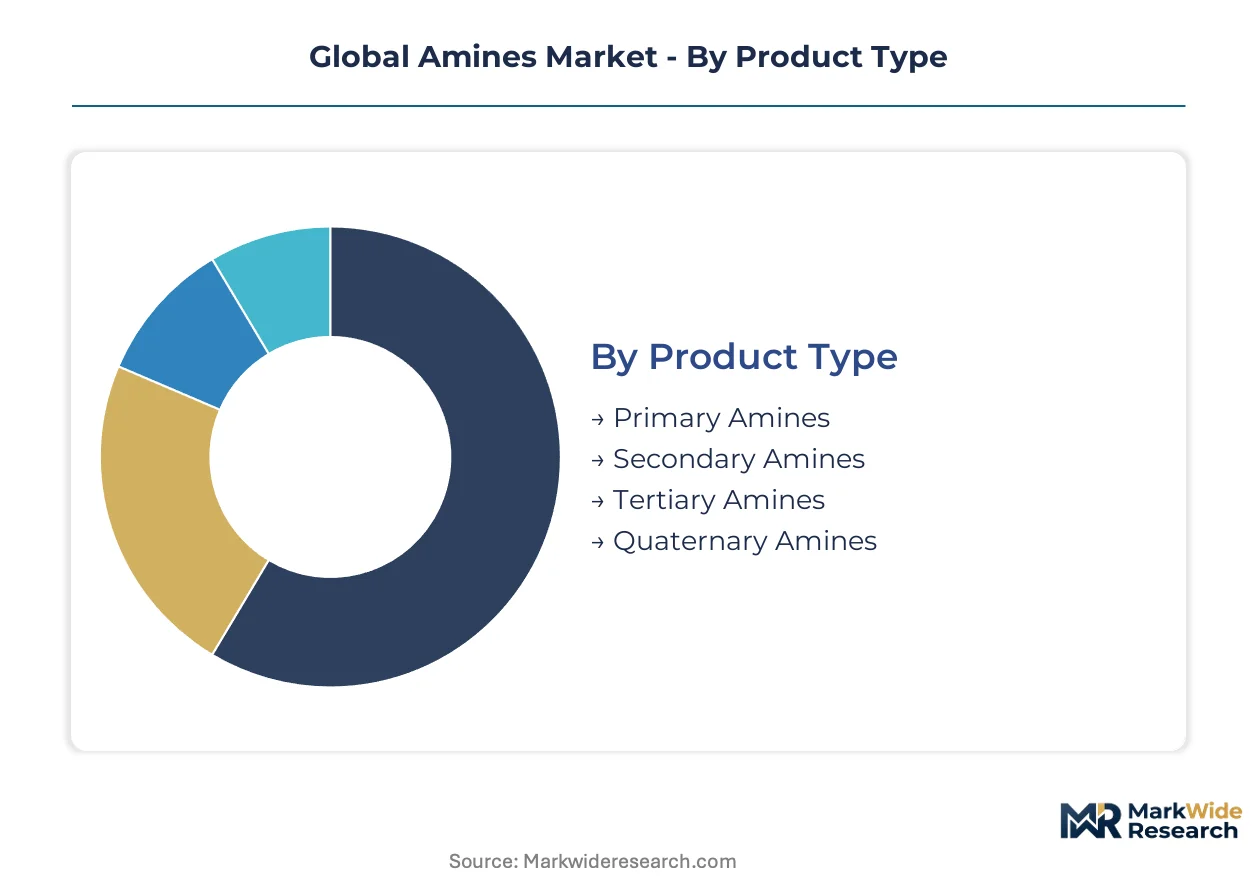
Amine producers configure product portfolios around distinct performance specifications that govern substitution economics across end-use channels. Segmentation reveals how purity grades, functional group positioning, and manufacturing routes create divergent margin structures that reward specialized capabilities over commodity scale.
Product Type:
Replacement cycles in downstream formulations are accelerating demand for higher-purity amine grades that reduce reformulation costs for registrants facing REACH and EPA deadlines.
- Primary Amines:Nitrogen compounds with one alkyl or aryl substituent, manufactured through catalytic hydrogenation of nitriles. Agrochemical formulators in Brazil and India consume the deepest volume for crop protection active ingredient synthesis, though residual solvent specifications under evolving OECD frameworks are compressing supplier lists.
- Tertiary Amines:Three substituent groups attached to nitrogen, enabling quaternization reactions essential to fabric softener and biocidal formulations. Personal care manufacturers in Germany and the United States are expanding specifications for low-carbon hydrogenation routes to satisfy EU Green Deal chemical sustainability mandates.
- Secondary Amines:Two substituents on nitrogen, serving as intermediates for corrosion inhibitors and rubber processing chemicals. Chemical manufacturers across China's specialty manufacturing corridors represent the dominant procurement channel.
- Quaternary Amines:Positively charged nitrogen with four substituents, functioning as cationic surfactants and phase transfer catalysts. Institutional cleaning product formulators drive specification requirements.
Primary Amines sits at the top of the volume ranking, with Tertiary Amines climbing the fastest.
Application:
Cost-tier stratification separates pharmaceutical-grade certifications from industrial-volume purchasing, with penalty clauses for purity deviation becoming standard in high-value segments.
- Pharmaceutical:Active pharmaceutical ingredient synthesis demands multi-year purity guarantees with ISO-certified quality management systems. Swiss and Irish manufacturing clusters bind suppliers to dedicated pharmaceutical-grade production lines, displacing spot-market contracting patterns.
- Agriculture:Crop protection intermediates sustain the deepest volume throughput across Brazilian and Indian formulator channels. Tertiary amine purchases are expanding for herbicide and fungicide synthesis, pulling volume through specialized chemical manufacturing corridors.
- Personal Care:Surfactant and emulsifier applications where bio-based alternatives threaten incumbent positions. Sustainability credentials determine supplier selection in North American and European channels.
- Textile:Fabric softener and dye-fixing agent applications, with quaternization demand driving fastest-margin expansion in household and institutional segments.
Pharmaceutical commands the steepest premium tier, while Agriculture anchors absolute volume throughput.
End Use Industry:
Customer-type concentration favors integrated producers with captive intermediate supply and in-house toxicology assessment capabilities for regulatory-intensive segments.
- Chemicals:Intermediate consumption for downstream specialty chemical synthesis, with REACH registration dossiers compressing supplier relationships toward German and Dutch integrated producers.
- Coatings:Epoxy curing agent applications dominate aliphatic amine consumption across North American industrial channels. Continuous flow hydrogenation systems are displacing batch reactor operations to satisfy real-time purity adjustment requirements.
- Plastics:Stabilizer and additive applications where specification-driven procurement is displacing traditional volume contracting. ISO certification requirements are standardizing supplier qualification.
- Detergents:Surfactant and cleaning agent formulations, with tertiary amine quaternization serving institutional and household biocidal applications.
Chemicals captures the broadest cross-segment demand, with Coatings showing the steepest specification escalation.
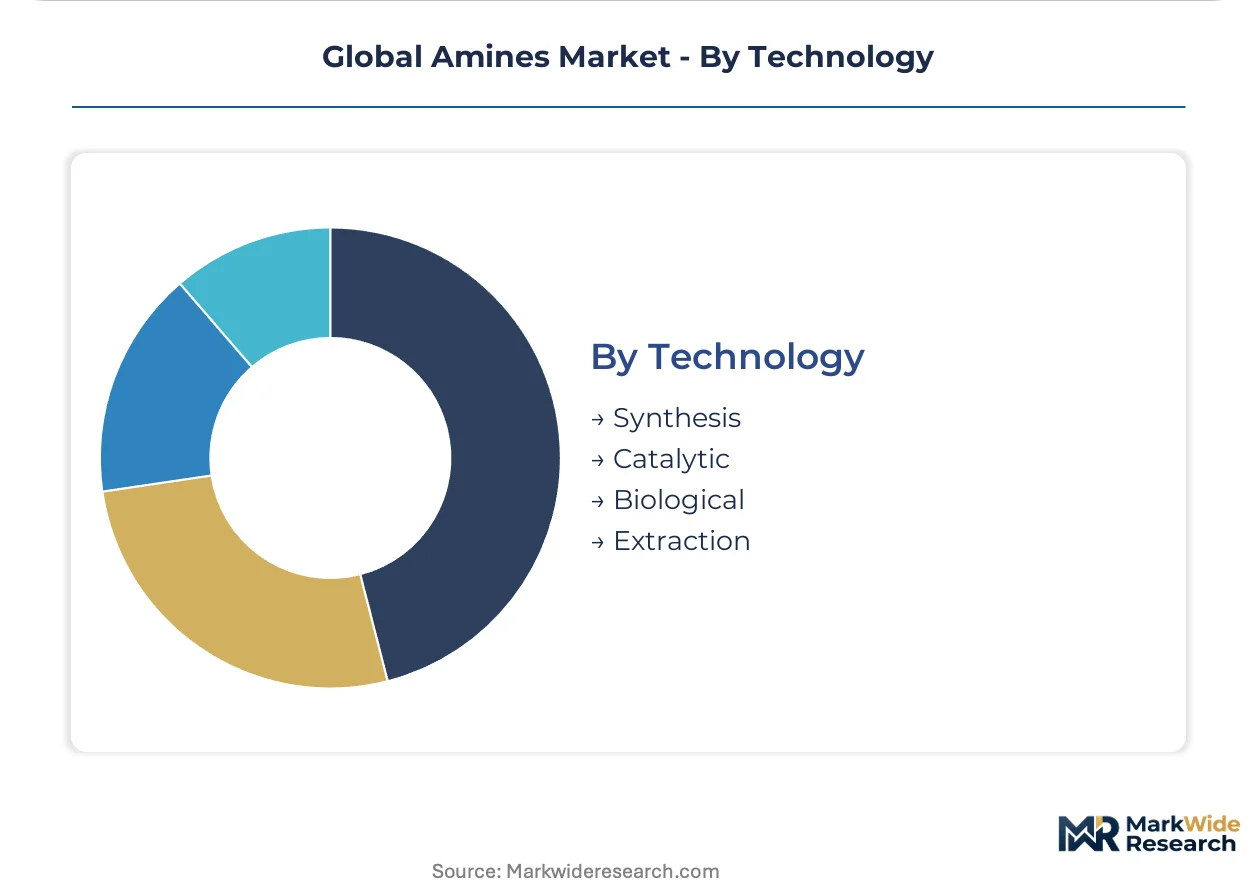
Technology:
Supply concentration among producers with advanced catalytic capabilities is fragmenting competitive positions as modular plant designs reduce capital intensity for compliant entrants.
- Catalytic:Hydrogenation of nitriles and reductive amination of aldehydes and ketones, with membrane reactor advances enabling continuous flow processing. Real-time purity adjustment satisfies ECHA and EPA certification without secondary refining.
- Synthesis:Conventional batch reactor operations facing capital-intensive upgrades to meet tightening residual solvent specifications under GB standards and OECD frameworks.
- Biological:Enzymatic and fermentation routes attracting investment for renewable feedstock integration and verified low-carbon process credentials under EU sustainability mandates.
- Extraction:Natural source isolation for niche pharmaceutical and personal care applications, limited by scale constraints and purity variability.
Catalytic dominates commercial scale deployment, with Biological gaining share fastest on sustainability tailwinds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Ludwigshafen chemical complex anchors European amine production through integrated hydrogenation corridors serving pharmaceutical and agrochemical formulators. Manufacturing gravity concentrates in three additional national markets where regulatory frameworks and feedstock access create divergent competitive conditions.
United States
Epoxy curing agent manufacturers along the Gulf Coast sustain aliphatic amine consumption for industrial coatings channels. EPA toxicity reassessments under the Toxic Substances Control Act compress product registration timelines for specialty chemical importers. Houston-area production clusters adopt continuous flow hydrogenation to satisfy real-time purity adjustment requirements without secondary refining steps.
Germany
Personal care formulators in the Rhine-Ruhr corridor expand tertiary amine specifications for fabric softener and biocidal applications. ECHA REACH registration mandates elevate analytical certification burdens for exporters seeking European market access. BASF SE leverages its Ludwigshafen complex to sustain captive intermediate supply for agrochemical and pharmaceutical synthesis.
China
Specialty chemical manufacturing corridors across the Yangtze River Delta dominate secondary amine procurement for corrosion inhibitor production. SAMR enforces GB standards for residual solvent content in domestically produced amine grades. Shanghai and Ningbo industrial zones concentrate capacity for quaternary amine surfactants serving institutional cleaning product channels.
Brazil
Agricultural chemical formulators in São Paulo state accelerate tertiary amine purchases for herbicide and fungicide active ingredient synthesis. ANVISA chemical registration requirements align with OECD assessment frameworks for crop protection intermediates. The Campinas industrial cluster anchors South American demand through specialized manufacturing corridors pulling volume from Asian supply bases.
India
Pharmaceutical manufacturers in Maharashtra and Gujarat sustain primary amine consumption for active ingredient synthesis across high-value therapeutic categories. CDSCO registration pathways for imported intermediates extend documentation requirements for novel derivatives. The Mumbai-Pune chemical belt concentrates formulation activity binding suppliers to multi-year purity guarantees with deviation penalties.
Global Amines Market Vendor Landscape
Global majors compete with regional champions across integrated versus specialized capability dimensions. The vendor base organizes around three tiers: diversified chemical conglomerates with captive feedstock positions, mid-scale specialists concentrating on high-purity pharmaceutical grades, and regional fabricators serving agricultural and coatings channels with volume-focused output. Consolidation pressure intensifies as REACH and EPA documentation requirements extend registration timelines and concentrate purchasing relationships toward producers with in-house toxicology assessment capabilities. Strategic moves cluster on backward integration into ethylene oxide and ammonia supply, plus modular plant deployment to capture mid-scale specialty opportunities.
Within the diversified conglomerate tier, BASF SE and Evonik Industries exemplify integrated producers combining captive intermediate supply with multi-jurisdiction compliance infrastructure. Huntsman Corporation occupies a position among North American specialists dominating aliphatic amine output. Dow Inc. and Eastman Chemical Company represent scale-driven participants with Gulf Coast manufacturing proximity to epoxy curing agent demand. Arkema S.A. and Mitsubishi Chemical Corporation anchor European and Asian regional positions respectively. Akzo Nobel N.V. and LyondellBasell Industries N.V. complete the landscape as diversified chemical operators with cross-segment amine exposure.
| Leading Market Players |
|---|
| Eastman Chemical Company |
| Evonik Industries |
| BASF SE |
| LyondellBasell Industries N.V. |
| Arkema S.A. |
| Dow Inc. |
| Akzo Nobel N.V. |
| Mitsubishi Chemical Corporation |
| Huntsman Corporation |
| Others |
Supply Flow & Price Mechanics
Ethylene oxide spot price volatility at the US Gulf Coast and Rotterdam hubs cascades through amine value chains into three distinct procurement tiers. Pharmaceutical-grade primary amines command premium contract structures indexed to feedstock movements, while agricultural intermediates trade on volume-scaled spot mechanisms that compress margins during ammonia price spikes.
Pricing Analysis
Input-cost pass-through mechanisms dominate amine pricing, with ethylene oxide and ammonia benchmarks resetting quarterly contract floors for most producers. Three-tier pricing structure across pharmaceutical-grade, technical-grade, and commodity-grade levels separates Swiss and Irish API manufacturers from Brazilian agrochemical formulators and Chinese industrial buyers. Pricing pressure stems from REACH registration cost recovery as producers amortize ECHA dossier investments across smaller volume bases. Agricultural intermediates exhibit highest price sensitivity due to Brazilian and Indian formulators' spot-market procurement patterns, while pharmaceutical channels absorb premiums for ISO-certified purity guarantees.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Houston, and Singapore anchor hub-and-spoke patterns for amine intermediates serving downstream formulators. Manufacturing concentrates in Germany, China, and the United States, with Ludwigshafen and the US Gulf Coast hosting integrated hydrogenation corridors. Feedstock dependencies on ethylene oxide, ammonia, and natural gas-derived hydrogen expose producers to energy cost volatility and naphtha-cracker output fluctuations. Single-source vulnerability characterizes specialty tertiary amine grades where Evonik and BASF captive production limits alternative sourcing. Distribution runs through chemical tanker networks and dedicated rail spurs serving epoxy curing agent manufacturers along North American industrial coatings channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Amines Market functions as a stable compounder anchored by irreplaceable intermediate demand across crop protection and pharmaceutical synthesis. Regulatory certification requirements create durable moats for incumbents with established ECHA and EPA dossiers.
For Market Incumbents: Deepen backward integration into ethylene oxide supply through pipeline commitments or cracker joint ventures to offset feedstock volatility. Expand pharmaceutical-grade capacity in Swiss and Irish supply corridors to capture specification-driven procurement migration away from spot-market contracting. Bio-based surfactant substitutes threaten tertiary amine positions in personal care; defend through low-carbon hydrogenation certification aligned with EU Green Deal mandates. For New Entrants and Emerging Players: E-commerce platforms serving Southeast Asian pharmaceutical manufacturing clusters offer white-space penetration routes outside established Chinese and Indian supply bases. Target modular continuous-flow hydrogenation systems to serve mid-scale epoxy curing agent producers seeking REACH-compliant purity without integrated producer minimums. Specialty quaternary amines for institutional biocidal applications present the most penetrable segment given fragmented European formulator demand and limited dedicated production capacity. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-scale specialists possessing pharmaceutical-grade certifications and captive hydrogen supply. Long-term viability hinges on regulatory compliance infrastructure rather than commodity scale, favoring targets with validated REACH dossiers and ISO-certified quality systems across the analysis window. Monitor ECHA substance evaluation timelines as inflection indicators for supplier list compression and pricing power consolidation among dossier-complete producers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ethylene Oxide | Captive feedstock supply insulates BASF and Dow from Rotterdam spot volatility. |
| Continuous Flow Hydrogenation Deployment | Modular reactor designs enable Huntsman to satisfy EPA real-time purity mandates. |
| Pharmaceutical-Grade Certification Investment | ISO 9001 and dedicated production lines secure multi-year Swiss and Irish contracts. |
| Low-Carbon Process Verification | Renewable hydrogenation routes position Evonik for EU Green Deal chemical procurement. |
| Southeast Asian Distribution Partnership | Singapore hub expansion captures underpenetrated pharmaceutical manufacturing demand. |
Methodological Framework
Direct dialogue with plant managers at German and US Gulf Coast hydrogenation facilities, procurement leads at Brazilian agrochemical formulators, and regulatory affairs directors navigating ECHA registration pathways grounded qualitative assessments. Secondary validation drew from customs trade data, ACC and Cefic industry reports, SEC 10-K filings, and EPA TSCA chemical substance inventories. Bottom-up capacity modeling and top-down end-use consumption estimates triangulated volume figures across the projection horizon.
Bottom-up segment analysis modeled amine demand by product type, application, and end-use industry, with cross-validation against regional production hub outputs. Catalytic hydrogenation capacity, pharmaceutical API synthesis trends, and agrochemical active ingredient registration patterns served as primary forecast inputs. CAGRs derived from regression analysis of historical ethylene oxide consumption correlations and segment-specific purity premium trajectories throughout the forecast period.
The model assumes a particular technology adoption path; alternative pathways for biological enzymatic routes would alter the outlook if renewable feedstock integration accelerates beyond current pilot scale. Forecasts reflect documented assumptions regarding REACH harmonization timelines and OECD framework convergence. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Decabromodiphenyl Ether Market
Chemicals
Calcium Disodium Ethylene Diamine Tetra-Acetate Market
Chemicals
Guaiacol Market
Chemicals
Africa Mining Chemicals Market
Chemicals
4-Dichlorodiphenyl Sulfone (DCDPS) Market
Chemicals
Lime Sulfur Market
Chemicals
Aluminium Chloride Market
Chemicals
Fireworks Market
Chemicals
Tromethamine Market
Chemicals
Automotive Appearance Chemicals Market
Chemicals
Pentanedione Market
Chemicals
Sodium Ethylate Market
Chemicals
Methanol to Gasoline Market
Chemicals
Sulfur Chemicals Market
Chemicals
Di Nitro Toluene Market
Chemicals
South America Surface Treatment Chemicals Market