
 Gorse Market | 2026-2036
Gorse Market Size, Share, and Industry Trends Forecast 2026-2036
Gorse Market Foresight
The EU Green Deal is realigning agricultural land-use incentives across member states, redirecting marginal pasture toward dedicated biofuel feedstock cultivation. SkyNRG leverages long-term offtake contracts with European refiners to secure supply chain priority for renewable aviation fuel inputs. Bach Flower Remedies Limited anchors its competitive position through proprietary extraction protocols that sustain premium positioning in homeopathic distribution channels. Circularity Fuels competes on waste-stream integration, converting invasive gorse thickets into standardized biomass pellets for industrial boilers.
Gorse (Ulex europaeus) constitutes a perennial leguminous shrub containing approximately 15-20% protein by dry weight, with seed oils rich in linoleic acid suitable for both cosmetic emulsions and pharmaceutical tinctures. The plant's dense lignocellulosic structure requires mechanical chipping followed by solvent extraction or cold-press processing to yield commercial-grade oil and powder fractions. Extract and oil segments dominate current revenue pools, reflecting sustained pharmaceutical and cosmetics demand for certified organic inputs. Seed and powder categories represent faster-growing structural positions, driven by expanding agriculture applications in nitrogen-fixing cover crops and specialty feed formulations.
EMA guidelines on herbal medicinal products impose stringent documentation requirements for gorse-derived extracts entering European pharmaceutical channels, while REACH compliance governs chemical safety profiling for cosmetic-grade oils. EFSA feed additive evaluations shape market access for agricultural applications, particularly where gorse meal enters ruminant nutrition programs. Stakeholders must monitor evolving sustainability certification schemes and biofuel mandate thresholds to anticipate demand inflections before supply commitments lock in.
Market Dynamics
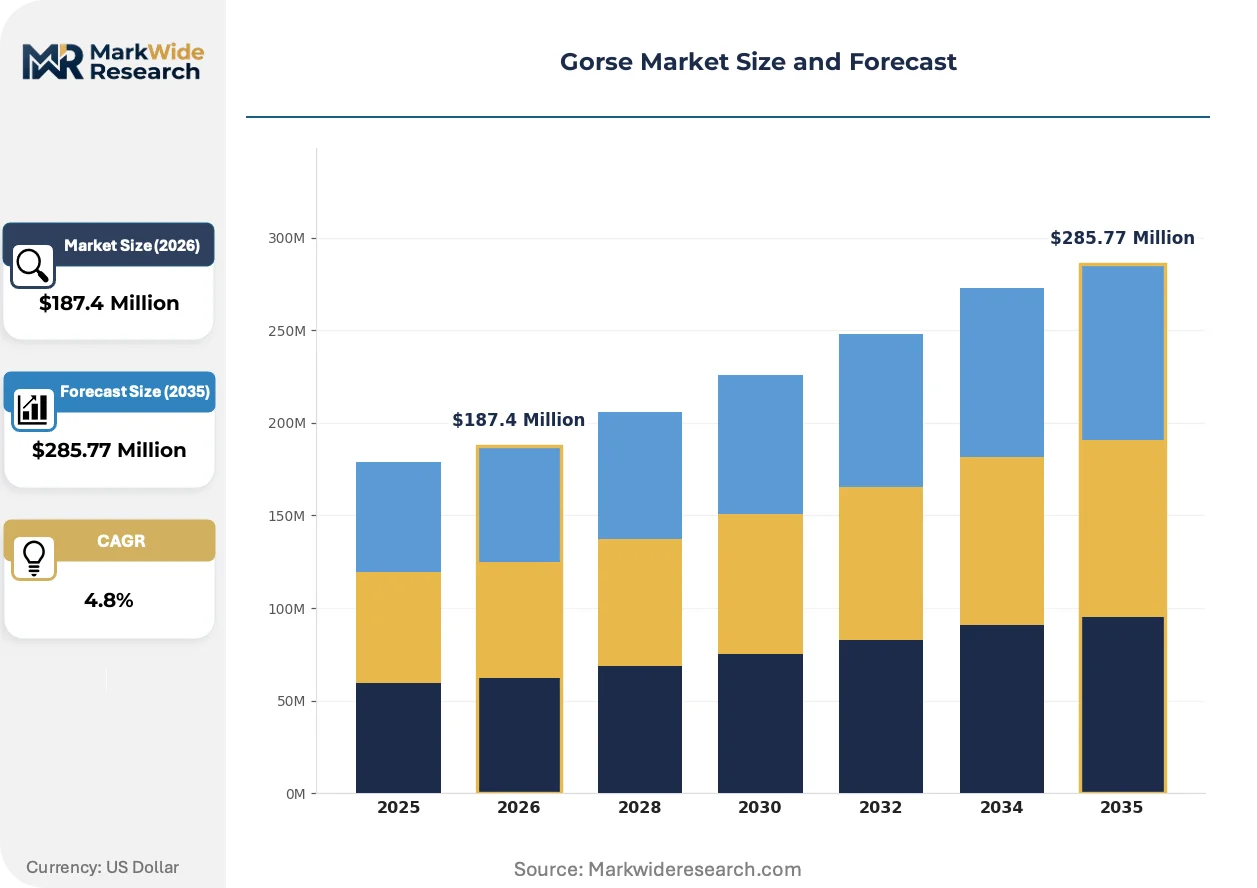
The EU Green Deal is redirecting marginal agricultural land toward dedicated biofuel feedstock cultivation, concentrating supply chain investments in France and the Netherlands while reshaping competitive positioning across pharmaceutical and renewable fuel channels.
Growth Catalysts
- Renewable Fuel Mandates:The EU Green Deal establishes binding biofuel blending thresholds that prioritize lignocellulosic feedstocks over food-crop alternatives. Refiners in Rotterdam and Marseille now contract directly with gorse pellet producers.
- France:ANSM guidance on homeopathic raw materials streamlines pharmaceutical-grade gorse extract approval timelines. Bach flower remedy manufacturers leverage this regulatory clarity to expand certified organic product lines.
- Supercritical CO2 Extraction:This solvent-free processing technology preserves thermolabile compounds in cosmetic-grade gorse oils. Premium skincare formulators in Germany and Switzerland specify CO2-extracted inputs for clean-label positioning.
Market Restraints
- Mechanical Harvesting Costs:Dense lignocellulosic structure demands specialized chipping equipment with high fuel consumption. Marginal pasture terrain in Galicia and Brittany limits mechanized efficiency.
- Portuguese Supply Concentration:Invasive gorse thickets in northern Portugal dominate waste-stream biomass volumes. Refiners face single-source risk when pellet contracts lock in before alternative Iberian supply matures.
- REACH Registration Burden:ECHA chemical safety dossiers for novel cosmetic ingredients impose six-figure compliance costs. Small-scale extractors lack resources to complete full substance characterization.
Strategic Opportunities
- Netherlands:SkyNRG's long-term offtake contracts with Amsterdam and Rotterdam refiners create template structures for aviation biofuel feedstock aggregation. Marginal Dutch polder land suits gorse nitrogen-fixing cultivation.
- EFSA Feed Additive Pathway:Pending evaluations for ruminant nutrition applications would unlock agricultural demand at scale. Dutch and Danish feed compounders await regulatory clarity to formulate gorse meal into dairy rations.
- Blockchain Provenance Tracking:Integration with organic certification schemes enables real-time supply chain transparency for pharmaceutical buyers. German homeopathic distributors pilot this for batch-level traceability.
Industry Challenges
- Extraction Chemistry Expertise:Solvent selection for pharmaceutical-grade alkaloid recovery requires specialized phytochemical knowledge. Labor pools in rural France and Spain lack trained technicians.
- EMA Documentation Timelines:Herbal medicinal product dossiers demand 18-24 months for full quality and safety review. Cash-constrained extractors struggle to bridge working capital gaps during approval periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gorse Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Seed, Extract, Oil, Powder End Use Industry: Pharmaceuticals, Cosmetics, Agriculture, Food & Beverage Distribution Channel: Online, Retail, Wholesale, Direct Sales Form: Liquid, Solid, Semi-Solid, Granular |
| Companies Covered | Nelsons, Healing Herbs, Crystal Herbs, Ainsworths, Bach Flower Remedies Limited, SkyNRG, Foresta, Circularity Fuels, Gracefruit, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gorse Market Shifts & Advancements
Processing technology convergence with digital traceability systems is compressing quality assurance timelines while regulatory harmonization across European pharmaceutical and cosmetic channels creates new compliance templates for market entry.
Supercritical CO2 extraction is overtaking traditional hexane-based solvent recovery in premium cosmetic oil production. Swiss and German skincare manufacturers specify CO2-processed gorse seed oil for residue-free positioning. This technology compression eliminates solvent disposal liabilities and enables cold-temperature compound preservation that hexane methods degrade.
REACH Annex XVII restrictions on persistent organic pollutants are tightening impurity thresholds for cosmetic-grade botanical oils. ECHA guidance documents now specify maximum allowable solvent residues and pesticide metabolite levels. French and Italian extractors invest in in-house analytical laboratories to preempt compliance failures that would trigger market withdrawal.
Certification-driven procurement now dominates pharmaceutical channel access. German homeopathic buyers require EU organic certification plus Bach Flower Remedies Association quality seals before contract consideration. This preference compression marginalizes uncertified suppliers and consolidates volume with established processors in Normandy and Bavaria who maintain dual certification infrastructure.
Gorse Market Segmentation
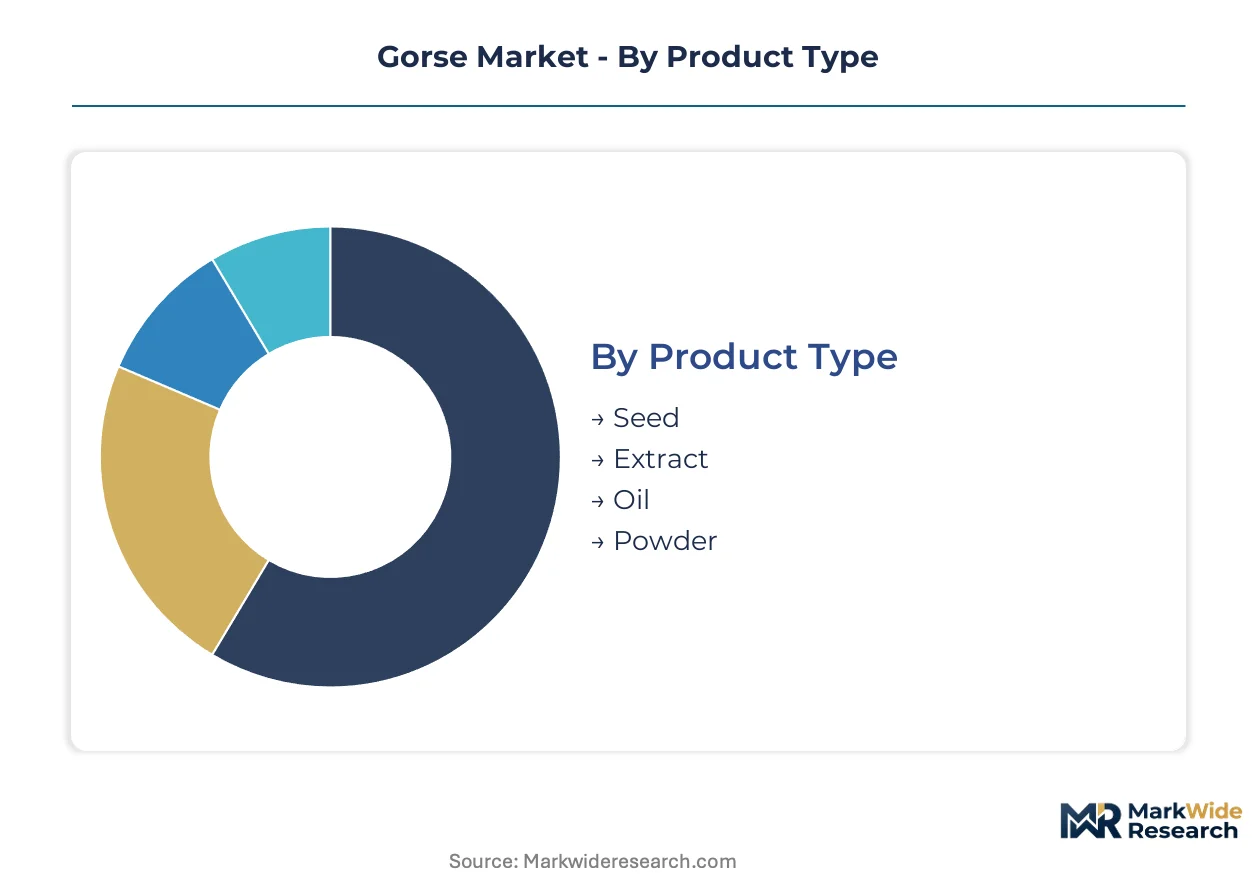
Certification requirements fragment the gorse market into distinct compliance tiers. EMA dossier complexity, REACH registration burdens, and EU organic standards create divergent margin structures across product categories.
Product Type:
EMA herbal medicinal product guidelines impose the heaviest documentation burden on extract and oil segments, while powder categories face lighter EFSA feed additive pathways.
- Extract:Standardized alkaloid and flavonoid concentrates require full EMA quality and safety dossiers for pharmaceutical channel access. German homeopathic manufacturers in Bavaria and Baden-Württemberg drive certified organic demand for Bach flower remedy formulations.
- Oil:Cold-pressed or supercritical CO2-derived seed oils carry linoleic acid specifications for cosmetic emulsions. Swiss skincare formulators specify residue-free CO2 extraction for clean-label positioning, tightening REACH Annex XVII compliance thresholds.
- Seed:Nitrogen-fixing cover crop applications expand in Dutch polder cultivation.
- Powder:Lignocellulosic biomass pellets supply Rotterdam and Marseille refiners under EU Green Deal mandates.
Extract sits at the top of the volume ranking, with Powder climbing the fastest.
End Use Industry:
Customer procurement patterns split between premium-certified pharmaceutical buyers and price-sensitive agricultural compounders.
- Pharmaceuticals:Homeopathic tincture manufacturers demand dual EU organic and Bach Flower Remedies Association certification. ANSM guidance in France streamlines raw material approval timelines for Normandy-based extractors.
- Cosmetics:Clean-label skincare brands in Germany and Switzerland specify supercritical CO2 extraction to eliminate solvent residues. ECHA impurity thresholds for persistent organic pollutants drive in-house analytical laboratory investments.
- Agriculture:Pending EFSA evaluations for ruminant nutrition applications would unlock Dutch and Danish dairy feed formulation demand.
- Food & Beverage:Specialty tea and functional beverage applications remain niche without established novel food authorizations.
Pharmaceuticals commands the highest margin tier, with Agriculture expanding most quickly pending regulatory clarity.
Distribution Channel:
Channel selection correlates with batch size and traceability requirements across end-use segments.
- Direct Sales:Long-term offtake contracts dominate aviation biofuel feedstock aggregation. SkyNRG structures multi-year agreements with Rotterdam refiners for standardized pellet volumes.
- Wholesale:Pharmaceutical-grade extracts move through specialized botanical distributors serving German homeopathic channels.
- Online:Certified organic seed and small-format oils reach artisan cosmetics formulators.
- Retail:Consumer-facing Bach flower remedy tinctures occupy pharmacy and natural health store shelves.
Direct Sales captures the largest transaction values, with Online gaining share fastest among small-batch buyers.
Form:
Physical state determines extraction chemistry requirements and packaging specifications.
- Liquid:Tincture and oil formats demand amber glass or nitrogen-flushed containers to prevent oxidation. EMA stability testing protocols extend approval timelines for novel liquid preparations.
- Solid:Compressed tablet and capsule forms for homeopathic applications require excipient compatibility documentation.
- Semi-Solid:Ointment bases for topical cosmetic applications specify emulsion stability parameters.
- Granular:Uniform pellet sizing optimizes combustion efficiency in industrial biomass boilers.
Liquid holds the widest application breadth, with Granular posting the steepest expansion trajectory in renewable fuel channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gorse cultivation and processing first scaled commercially in Normandy during the late nineteenth century, where small-scale distillers supplied tincture makers in Paris and Lyon. The industry later expanded into Brittany and the Loire Valley as mechanical harvesting techniques emerged in the 1960s.
France
Normandy and Brittany host the densest concentration of certified organic gorse extractors serving Bach flower remedy manufacturers. ANSM guidance on homeopathic raw materials accelerates pharmaceutical-grade approval timelines for processors in Caen and Rennes. The Loire Valley cluster specializes in supercritical CO2 extraction for cosmetic-grade oils exported to Swiss skincare formulators.
Germany
Bavarian homeopathic distributors drive certified organic demand for gorse tinctures and mother essences. The country's national pharmaceutical regulator imposes stringent documentation requirements under EMA herbal medicinal product guidelines. Processing facilities in Baden-Württemberg concentrate on cold-pressed seed oils for clean-label cosmetic applications.
Netherlands
Rotterdam and Amsterdam refiners contract directly with gorse pellet producers under EU Green Deal renewable aviation fuel mandates. Marginal Dutch polder land suits nitrogen-fixing gorse cultivation for biomass feedstock. SkyNRG structures multi-year offtake agreements that prioritize lignocellulosic inputs over food-crop alternatives.
Portugal
Invasive gorse thickets in northern Portugal around Braga and Porto dominate waste-stream biomass volumes for industrial pellet production. The country's central environmental authority monitors sustainable harvesting quotas to prevent ecosystem degradation. Refiners face single-source risk when contracts lock in before alternative Iberian supply from Galicia matures.
Switzerland
Swiss skincare manufacturers in Geneva and Basel specify supercritical CO2-extracted gorse seed oil for residue-free positioning in premium cosmetic channels. Swissmedic oversees quality standards for botanical ingredients entering pharmaceutical and cosmetic applications. The country's private-label formulators contract exclusively with certified organic European suppliers to maintain clean-label credibility.
Gorse Market Competitive Landscape
Capital-heavy biomass processors compete with asset-light botanical extractors across divergent margin structures in the gorse market. Pellet producers investing in specialized chipping equipment and drying infrastructure face high fixed costs and fuel price exposure. Three archetypes dominate: integrated biofuel feedstock aggregators, certified organic extractors serving pharmaceutical channels, and waste-stream specialists converting invasive thickets into standardized biomass. Competitive moves center on long-term offtake contract structures and dual-certification infrastructure for organic and homeopathic quality seals.
Among homeopathic remedy specialists, Bach Flower Remedies Limited and Nelsons occupy positions anchored by proprietary extraction protocols and established distribution relationships with European pharmacy channels. SkyNRG represents the biofuel aggregation archetype through structured supply agreements with Rotterdam refiners. Circularity Fuels exemplifies waste-stream integration, sourcing feedstock from invasive gorse management programs in northern Portugal and Galicia.
| Leading Market Players |
|---|
| Nelsons |
| Healing Herbs |
| Crystal Herbs |
| Ainsworths |
| Bach Flower Remedies Limited |
| SkyNRG |
| Foresta |
| Circularity Fuels |
| Gracefruit |
| Others |
Supply & Pricing Matrix
Certification-grade divergence between pharmaceutical-grade extracts and industrial biomass pellets manifests in starkly different pricing architectures and supply chain configurations. EMA-compliant tincture producers in Bavaria command substantial premiums through dual organic and Bach Flower certification, while Rotterdam refiners negotiate standardized pellet contracts indexed to lignocellulosic feedstock benchmarks under EU Green Deal mandates.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs transaction structures, with supercritical CO2-extracted cosmetic oils and certified organic pharmaceutical extracts occupying the premium tier against commodity-grade pellets. Price differentiation rests on certification depth and extraction technology sophistication, with REACH Annex XVII compliance adding measurable cost layers. Cost compression in the pellet segment intensifies because Portuguese waste-stream suppliers compete aggressively for refinery offtake slots. Agricultural compounders in Denmark exhibit the highest price sensitivity, while Swiss skincare formulators absorb premium positioning with minimal volume elasticity.
Supply Chain Analysis
Certification gating through EMA, REACH, and EU organic standards fragments supplier eligibility and concentrates pharmaceutical-grade flows through Normandy and Bavarian processing clusters. Geographic supply concentration centers on France, Portugal, and the Netherlands, with raw material dependencies spanning invasive thicket harvesting, mechanical chipping equipment, and solvent recovery infrastructure. Single-source vulnerability from Portuguese biomass dominance creates refinery exposure when Galician alternative supply remains underdeveloped. Distribution runs through long-term offtake contracts for aviation biofuel feedstock and specialized botanical distributors for pharmaceutical channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The gorse market compounds steadily as EU Green Deal biofuel mandates and pharmaceutical certification requirements create durable demand floors across multiple end-use channels.
For Market Incumbents: Lock in multi-year offtake agreements with Rotterdam and Marseille refiners before alternative Iberian pellet supply matures, while deepening backward integration into certified organic cultivation in Normandy to defend margin position against emerging waste-stream aggregators. Prioritize dual EMA and Bach Flower Remedies Association certification infrastructure as the priority defensive lever against regulatory complexity escalation. For New Entrants and Emerging Players: Launch via direct sales to Dutch polder cultivation cooperatives seeking nitrogen-fixing cover crop seed supply, bypassing established pharmaceutical certification barriers. Target EFSA feed additive pathway clarity as the most penetrable regulatory opening, with ruminant nutrition applications in Danish dairy operations offering white-space expansion before incumbent extractors pivot downstream. For Investors and Strategic Acquirers: Asymmetric upside sits with waste-stream specialists possessing invasive thicket management contracts and mechanical harvesting capabilities in northern Portugal and Galicia. Five-to-ten-year viability hinges on biofuel mandate durability and feed additive regulatory resolution, with EFSA evaluation timelines serving as the critical signal to watch for demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Supply Agreement | SkyNRG's Rotterdam refinery contracts establish template structures for aviation biofuel feedstock security. |
| Backward Integration | Normandy extractors cultivating captive organic gorse acreage reduce third-party certification dependency. |
| Green Certification Program | Dual EU organic and Bach Flower Remedies Association seals unlock German homeopathic distributor access. |
| Capacity Expansion | Supercritical CO2 extraction scale-up in the Loire Valley serves Swiss cosmetic formulator demand growth. |
| Joint Venture |
Research Methodology
Multiple input streams — primary interviews with extraction facility managers, pharmaceutical procurement leads, and refinery feedstock planners, alongside secondary validation through EMA herbal medicinal product filings, EFSA feed additive evaluation dockets, and EU customs trade data — were reconciled through bottom-up volume aggregation and top-down market sizing triangulation.
Historical shipment patterns were cross-referenced against expert panel assessments across the analysis window, with segmentation modeling across product type, end-use industry, distribution channel, and physical form dimensions. CAGRs were derived from slope-consistent growth trajectory fitting, incorporating EU Green Deal mandate implementation schedules and EMA documentation timeline assumptions as industry-specific forecast inputs.
Several conditions sit outside the modeled scope, including novel food authorization pathways for gorse-derived ingredients and potential REACH Annex XVII expansion to additional compound classes. Deviation in EFSA feed additive evaluation timelines or EU renewable fuel blending threshold adjustments would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Commodities
Feed Yeast Market
Agricultural Commodities
Citrus Pulp Pellets Market
Agricultural Commodities
Asia-Pacific Feed Amino Acids Market
Agricultural Commodities
Roundwood Market
Agricultural Commodities
Africa Feed Amino Acids Market
Agricultural Commodities
South America Feed Amino Acids Market
Agricultural Commodities
Feed Sucrose Market
Agricultural Commodities
Corn Hydrolysate Market
Agricultural Commodities
Asia-Pacific Ruminant Feed Market
Agricultural Commodities
Aloe Vera Market
Agricultural Commodities
UK Bird Feeder Market
Agricultural Commodities
Marine Powder Market
Agricultural Commodities
Castor Oil Market
Agricultural Commodities
Hermetic Food Grain Storage Market
Agricultural Commodities
Cottonseed Meal Market
Agricultural Commodities
Straw Market