
 Bird Feeding and Watering Suppliers Market | 2026-2036
Bird Feeding and Watering Suppliers Market Size, Share, and Industry Trends Forecast 2026-2036
Bird Feeding and Watering Suppliers Market Outlook
REACH compliance is expanding material certification costs for European-sourced metal components, altering how suppliers qualify overseas vendors. Woodlink leverages captive manufacturing in North America to sidestep import documentation delays. Central Garden & Pet Company anchors its position through shelf-space dominance at mass retail. Droll Yankees differentiates via lifetime warranty programs that reduce replacement-cycle revenue but build brand equity.
Bird feeding and watering suppliers manufacture and distribute vessels, dispensers, and consumables designed to attract, nourish, and hydrate wild avian species, typically employing UV-stabilized polycarbonate reservoirs, powder-coated steel hanging hardware, and drainage systems with minimum 0.25-inch mesh to prevent seed spoilage. Feeders constructed from powder-coated metal and recycled plastic command margin premiums due to weather durability, while seed mixes represent the highest-frequency purchase category driving recurring revenue. Online distribution channels are capturing share from garden centers as direct-to-consumer logistics improve, though brick-and-mortar retains importance for impulse accessories and novice buyer education.
The U.S. Consumer Product Safety Commission monitors small-part hazards in accessories, while the EU F-Gas Regulation indirectly affects insulated waterer manufacturing through refrigerant-phaseout supply chain adjustments. China's GB standards for plastic food-contact materials constrain low-cost exporter participation in developed markets. Stakeholders must monitor how state-level extended producer responsibility laws reshape packaging obligations and material traceability requirements.
Market Dynamics
Backyard birding participation is concentrating demand among suburban homeowners seeking durable, low-maintenance feeding solutions, while EPA guidance on treated lumber accelerates material substitution toward cedar and recycled plastic formulations.
Growth Catalysts
- Suburban Homeowner Expansion:Residential development patterns across the Great Lakes and Northeast corridor create dense addressable markets where seasonal migration drives repeat feeder and seed purchases.
- REACH Compliance Premium:European material certification requirements for metal components are segmenting supply tiers, rewarding suppliers with documented vendor qualification systems and captive North American manufacturing.
- UV-Stabilized Polycarbonate Adoption:Reservoir durability improvements extend replacement cycles while reducing warranty claims, shifting competitive emphasis toward design differentiation rather than material failure rates.
Market Restraints
- Cedar Input Cost Volatility:Untreated lumber demand from competing outdoor furniture and construction applications pressures raw material availability for premium feeder production.
- Chinese GB Standards Barrier:Plastic food-contact material requirements constrain low-cost exporter participation in developed markets, limiting price competition from overseas manufacturing.
- F-Gas Regulation Supply Chain Adjustment:EU refrigerant phaseout indirectly affects insulated waterer manufacturing through component sourcing disruptions and reformulation timelines.
Strategic Opportunities
- Direct-to-Consumer Logistics Maturation:Improved last-mile delivery economics enable seed subscription models and replacement part programs that bypass traditional garden center intermediaries.
- Extended Producer Responsibility Tailwinds:State-level packaging obligation laws in the United States create first-mover advantages for suppliers with recyclable material traceability systems already operational.
- Smart Feeder Convergence:Integration of weight sensors and mobile connectivity with traditional vessel designs opens premium pricing tiers among tech-adopter homeowner segments.
Industry Challenges
- Small-Part Hazard Certification:U.S. Consumer Product Safety Commission monitoring of accessory components extends product development timelines and testing expenditure for novel designs.
- Brick-and-Mortar Education Dependency:Novice buyer conversion relies on physical retail staff expertise, creating channel conflict as online share expands without equivalent guidance infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bird Feeding and Watering Suppliers Market |
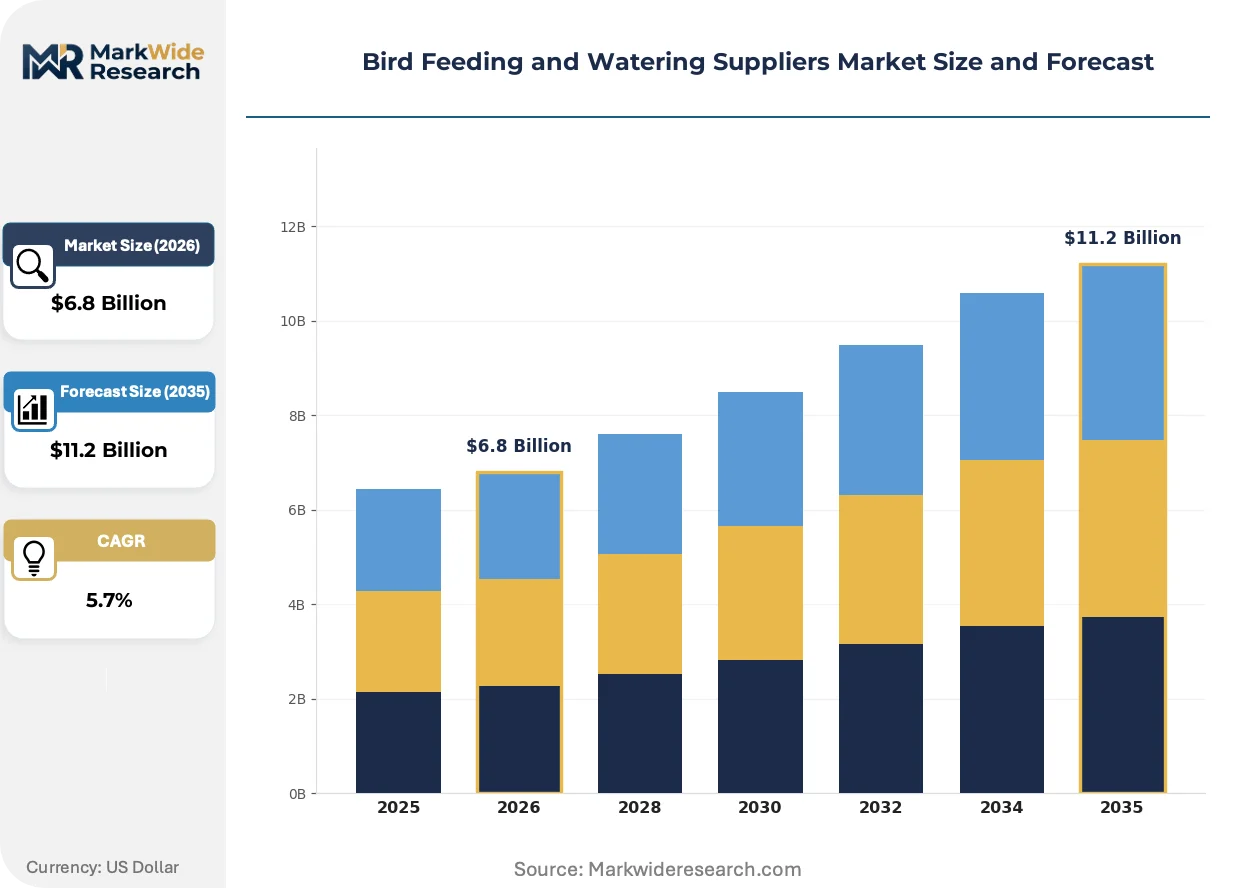
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Feeders, Waterers, Accessories, Seed Mixes Customer Type: Retailers, Homeowners, Garden Centers, Schools Distribution Channel: Online, Brick-and-Mortar, Direct Sales, Wholesalers Material: Plastic, Metal, Wood, Glass |
| Companies Covered | Woodlink, Aspects, Inc., Central Garden & Pet Company, Stokes Select, Kettle Moraine Bird Feeders, First Nature, Droll Yankees, Brome Bird Care, Perky-Pet, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bird Feeding and Watering Suppliers Market Strategic Shifts
Material science advances and regulatory pressure on chemical treatments are compressing traditional wood-metal feeder architectures while opening substitution pathways for synthetic and naturally durable alternatives.
Recycled high-density polyethylene formulations are electrifying feeder chassis construction by delivering UV resistance and impact durability without cedar's maintenance burden or treated lumber's regulatory exposure. Mass retail buyers and independent garden centers are adopting these platforms at accelerating rates. The technology is electrifying margin structures by reducing warranty replacement frequency and enabling modular component architectures.
EU F-Gas Regulation phaseout schedules are forcing insulated waterer manufacturers to redesign thermal retention systems around alternative barrier materials and passive insulation geometries. Component suppliers face compressed qualification windows as refrigerant-dependent legacy designs exit production. North American and European suppliers with in-house thermal engineering capabilities are capturing specification authority previously held by commodity HVAC component vendors.
Seed subscription procurement is consolidating purchase frequency among committed birding households, displacing opportunistic retail buying patterns. Direct-to-consumer platforms and specialty retailers with loyalty infrastructure are absorbing volume from mass merchants lacking replenishment automation. The United States Great Lakes corridor exhibits the most pronounced shift, where harsh winters create predictable consumption spikes that subscription models capture with superior inventory planning.
Bird Feeding and Watering Suppliers Market Segmentation
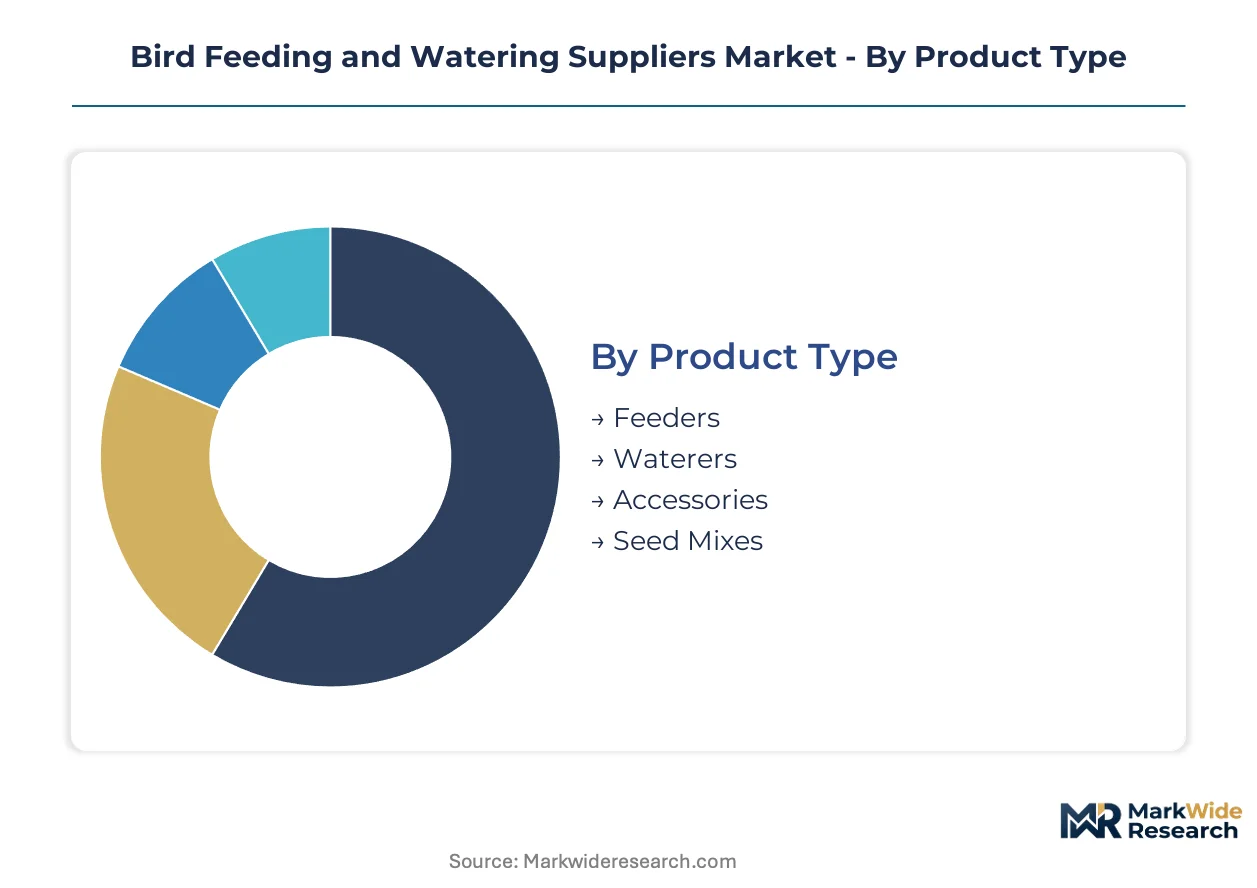
Segmentation in the bird feeding and watering suppliers market reveals distinct capital requirements, margin profiles, and channel dependencies that shape supplier strategy. Understanding these divisions clarifies where durable competitive advantages concentrate versus where commoditization pressures dominate.
Product Type:
Feeders demand the heaviest upfront tooling investment due to mold complexity and UV-stabilization requirements, while seed mixes require minimal fixed capital but working capital intensity for inventory turns.
- Feeders:UV-stabilized polycarbonate reservoirs and powder-coated steel hanging hardware define specifications. Demand concentrates among suburban homeowners across the Great Lakes corridor where seasonal migration drives replacement cycles. Cedar and recycled plastic formulations command margin premiums as EPA guidance on treated lumber accelerates material substitution.
- Waterers:Insulated thermal retention systems face redesign pressure from EU F-Gas Regulation phaseout schedules. Passive insulation geometries and alternative barrier materials absorb engineering resources as refrigerant-dependent legacy designs exit production.
- Accessories:Small-part hazard monitoring by the U.S. Consumer Product Safety Commission extends development timelines for novel designs.
- Seed Mixes:Highest-frequency purchase category with recurring revenue potential through subscription models.
Feeders absorb the bulk of installed manufacturing capacity; waterers are expanding most quickly as thermal engineering capabilities differentiate suppliers.
Customer Type:
Volume concentration varies sharply across customer types, with retailers and garden centers driving batch procurement while homeowners generate fragmented but high-margin direct sales.
- Retailers:Mass retail buyers demand modular component architectures and standardized packaging for shelf-space efficiency. Central Garden & Pet Company anchors position through shelf-space dominance at these channels.
- Homeowners:Suburban demographic seeking durable, low-maintenance feeding solutions. Backyard birding participation widens this addressable market.
- Garden Centers:Brick-and-mortar retains importance for impulse accessories and novice buyer education despite online share expansion.
- Schools:Institutional procurement with extended payment cycles but volume concentration in educational districts.
Retailers command the largest order volumes; homeowners deliver the steepest expansion trajectory as direct-to-consumer logistics mature.
Distribution Channel:
Channel economics diverge on working capital intensity and customer acquisition cost, with online platforms capturing share as last-mile delivery economics improve.
- Online:Direct-to-consumer platforms enable seed subscription models and replacement part programs. Improved logistics capture volume from mass merchants lacking replenishment automation.
- Brick-and-Mortar:Physical retail staff expertise drives novice buyer conversion. Channel conflict emerges as online share expands without equivalent guidance infrastructure.
- Direct Sales:Higher touch engagement with institutional and commercial accounts.
- Wholesalers:Intermediate inventory holding for independent garden centers and regional retailers.
Online channels gain share fastest; brick-and-mortar retains margin superiority for premium accessories.
Material:
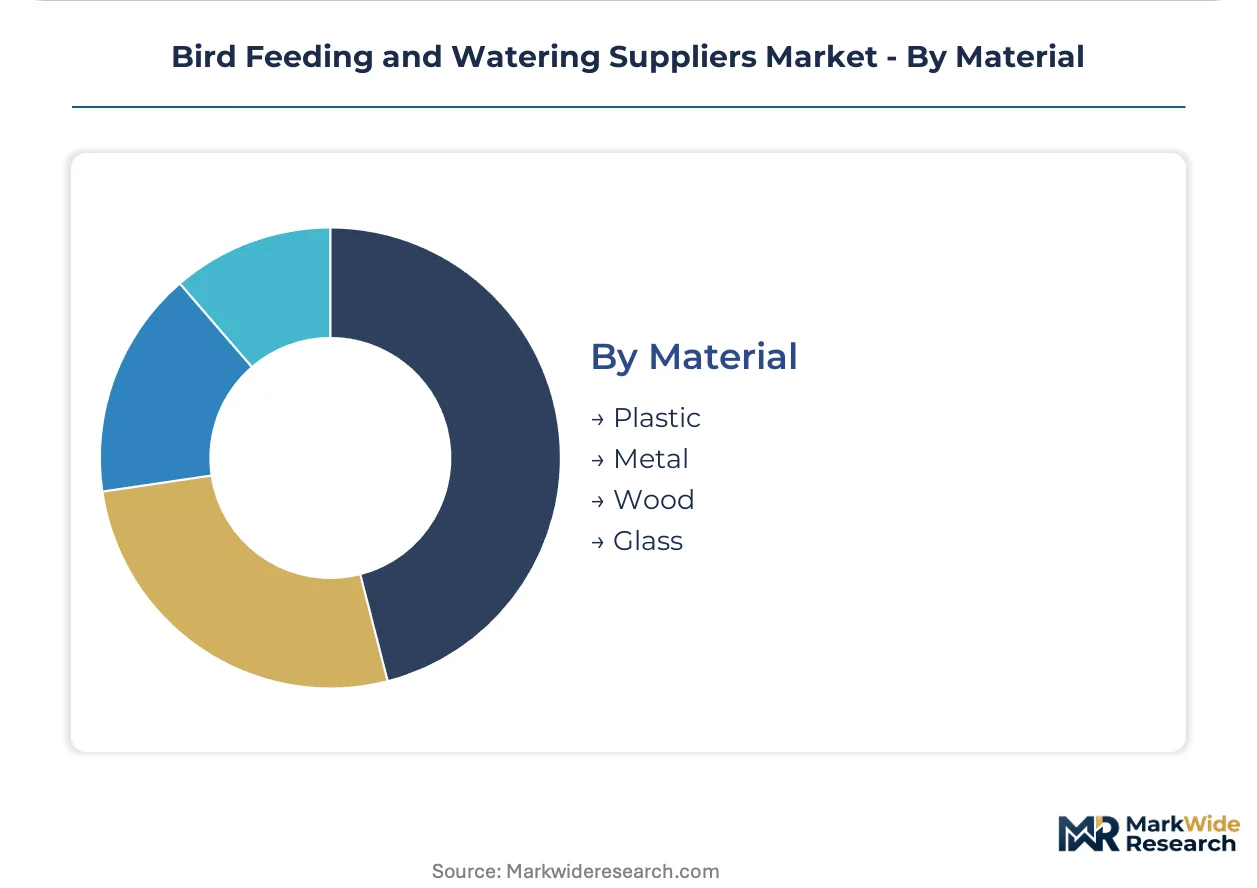
Material selection determines regulatory exposure, warranty liability, and supply chain qualification burden across supplier tiers.
- Plastic:Recycled high-density polyethylene formulations deliver UV resistance and impact durability without maintenance burden. China's GB standards for plastic food-contact materials constrain low-cost exporter participation in developed markets.
- Metal:Powder-coated steel commands weather durability premiums. REACH compliance expands material certification costs for European-sourced components.
- Wood:Untreated cedar faces input cost volatility from competing outdoor furniture and construction applications.
- Glass:Premium aesthetic positioning with breakage liability constraints.
Plastic and metal dominate production scale; recycled plastic formulations climb the fastest as mass retail buyers accelerate adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Opportunity Zones across the Great Lakes corridor concentrate backyard birding demand, with suburban development patterns creating dense addressable markets where seasonal migration drives repeat purchases of feeders and seed mixes.
United States
Suburban homeowner expansion across the Northeast and Great Lakes corridor generates the highest purchase frequency for UV-stabilized polycarbonate feeders and subscription seed services. The EPA's guidance on treated lumber in consumer products accelerates material substitution toward cedar and recycled plastic formulations. Chicago and Detroit metropolitan clusters anchor regional distribution networks serving migration-heavy corridors.
Canada
Harsh winter conditions in Ontario and Quebec provinces create predictable consumption spikes for insulated waterers and high-calorie seed blends. Health Canada and PMRA monitor small-part hazards in accessories, extending product development timelines for novel designs. Toronto and Vancouver metropolitan areas concentrate specialty retailer presence and direct-to-consumer fulfillment infrastructure.
Germany
REACH compliance expands material certification costs for metal components, segmenting supply tiers and rewarding suppliers with documented vendor qualification systems. ECHA enforcement of chemical safety standards alters how German distributors qualify overseas vendors. Bavaria and Baden-Württemberg host precision metalworking clusters supplying powder-coated steel hanging hardware to European markets.
United Kingdom
Garden center culture sustains brick-and-mortar importance for novice buyer education and impulse accessory purchases despite online channel expansion. The UK's departure from EU regulatory frameworks creates parallel certification requirements for cross-border trade. Southeast England and the Midlands concentrate specialty retail chains and distribution warehousing for continental supply.
China
GB standards for plastic food-contact materials constrain low-cost exporter participation in developed markets, limiting price competition from domestic manufacturing. MIIT oversight of industrial quality frameworks shapes export-oriented production. Guangdong and Zhejiang provinces host molding operations serving mid-tier international brands with UV-stabilized reservoir components.
Bird Feeding and Watering Suppliers Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The supplier base organizes around three strategic archetypes: mass retail shelf-space dominators, warranty-driven premium specialists, and captive manufacturing operators. Consolidation pressure concentrates among mid-tier regional brands lacking subscription infrastructure or material certification depth. Competitive moves center on direct-to-consumer logistics maturation and extended producer responsibility compliance positioning.
Within the captive manufacturing tier, Woodlink leverages North American production assets to sidestep import documentation delays. Central Garden & Pet Company anchors mass retail presence through shelf-space dominance and portfolio breadth. Droll Yankees occupies a premium positioning exemplifying warranty-driven brand equity construction. These three represent distinct strategic postures: vertical control, scale distribution, and service differentiation.
| Leading Market Players |
|---|
| Woodlink |
| Aspects, Inc. |
| Central Garden & Pet Company |
| Stokes Select |
| Kettle Moraine Bird Feeders |
| First Nature |
| Droll Yankees |
| Brome Bird Care |
| Perky-Pet |
| Others |
Value Chain & Pricing Dynamics
Captive North American manufacturing anchors supply positioning and pricing power for tier-one suppliers, insulating them from REACH documentation delays while enabling premium capture on documented vendor qualification systems. Cedar input cost volatility and recycled plastic formulation premiums feed directly into margin structures, with EPA guidance on treated lumber accelerating material substitution pathways that reshape cost baselines.
Pricing Analysis
Short lead-time premiums for UV-stabilized polycarbonate reservoirs and powder-coated steel hardware command margin capture over spot inventory liquidations, particularly across the Great Lakes corridor where seasonal migration timing compresses procurement windows. Three-tier pricing structure across premium, standard, and economy levels separates lifetime warranty programs from modular component architectures and basic seed-mix offerings. Cost compression in untreated lumber tiers is intensifying because competing outdoor furniture and construction applications strain raw material availability. Mass retail buyers exhibit highest price sensitivity due to shelf-space efficiency mandates, while committed birding households in subscription models demonstrate lowest sensitivity.
Supply Chain Analysis
Freight cost differentials between containerized Asian imports and domestic trucking networks favor North American captive production for time-sensitive feeder replenishment cycles. Supply concentration spans the United States, China, and Germany, with Guangdong and Zhejiang provinces hosting molding operations, Bavaria and Baden-Württemberg supplying precision metalworking clusters, and Chicago and Detroit anchoring regional distribution networks. Raw material dependencies rest on UV-stabilized polycarbonate resin, powder-coated steel coil, and untreated cedar lumber. Single-source vulnerability concentrates in European-sourced metal components facing REACH certification bottlenecks. Distribution runs through mass retail shelf-space dominance, garden center intermediaries, and maturing direct-to-consumer logistics platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cedar availability constraints prop pricing power for suppliers with secured lumber sourcing or recycled plastic substitution capabilities already operational. Capacity bottlenecks in REACH-compliant metal component certification segment supply tiers and reward documented vendor qualification systems.
For Market Incumbents: To counter direct-to-consumer subscription models displacing retail volume, incumbents should deepen garden center education infrastructure to preserve novice buyer conversion, while accelerating captive manufacturing investments in North America to sidestep import documentation delays and capture REACH compliance premiums on European-sourced alternatives. For New Entrants and Emerging Players: EU F-Gas Regulation phaseout schedules in Germany and neighboring markets open a window for insulated waterer redesigns around passive insulation geometries, targeting the premium thermal retention segment where refrigerant-dependent legacy designs exit production, with go-to-market positioning through specialty retailers lacking in-house thermal engineering capabilities. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by diversified garden and pet conglomerates seeking subscription infrastructure and material certification depth. Long-term viability over the coming decade hinges on extended producer responsibility compliance positioning as state-level packaging obligation laws reshape traceability requirements. Watch for smart feeder convergence adoption rates among tech-adopter homeowner segments as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Seed Subscription Infrastructure Buildout | Captures recurring revenue from committed birding households in the Great Lakes corridor. |
| Recycled Plastic Formulation Scale-Up | Reduces warranty replacement frequency while satisfying EPA guidance on treated lumber alternatives. |
| REACH-Compliant Vendor Qualification | Segments supply tiers and rewards documented certification systems for European metal components. |
| Direct-to-Consumer Logistics Maturation | Bypasses garden center intermediaries through improved last-mile delivery economics. |
| Smart Feeder Technology Integration | Opens premium pricing tiers via weight sensors and mobile connectivity for tech-adopter segments. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with product development executives at feeder manufacturers, category buyers at mass retail chains, procurement leads at garden center cooperatives, and supply chain directors at resin and steel distributors. Secondary validation drew from U.S. EPA guidance documents, ECHA REACH substance databases, U.S. Consumer Product Safety Commission hazard monitoring reports, and customs import records for UV-stabilized polycarbonate and powder-coated steel components. Bottom-up feeder and seed mix volume estimates triangulated against top-down market value reconstructions.
Data-stream reconciliation across shipment manifests, retail point-of-sale audits, and manufacturer production disclosures informed the analytical framework throughout the projection horizon. Segmentation dimensions modeled include product type, customer archetype, distribution channel, and material formulation, with regional regulatory clusters capturing EPA, REACH, and GB standard variations. CAGRs derived from fitted growth curves applied to normalized baseline values, with seed subscription adoption rates and smart feeder penetration serving as industry-specific demand-side inputs alongside housing formation patterns across suburban corridors.
The model assumes a particular technology adoption path for smart feeder convergence; alternative pathways for sensor-integrated vessel designs would alter the outlook if mobile connectivity adoption lags among target homeowner demographics. Forecasts reflect assumptions about REACH enforcement intensity, cedar input cost trajectories, and state-level extended producer responsibility implementation timelines. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Livestock Equipment
Livestock Farm Equipment Market
Livestock Equipment
Russia Horse Riding Equipment Market
Livestock Equipment
China Horse Riding Equipment Market
Livestock Equipment
Animal Cage Market
Livestock Equipment
Chicken Feeder and Drinkers Market
Livestock Equipment
Livestock Trailers Market
Livestock Equipment
Livestock Monitoring System Market
Livestock Equipment
Horse Stable Supplies Market
Livestock Equipment
Animal Feed Mixer Market
Livestock Equipment
Egg Incubator Market
Livestock Equipment
Cattle Farm Equipment Market
Livestock Equipment
Electric Fencing Market
Livestock Equipment
Milking Equipment Market
Livestock Equipment
Cattle Blower Market
Livestock Equipment
Horse Corral Panels Market
Livestock Equipment
Chicken Coop Market