
 Corn and Corn Starch Derivatives Market | 2026-2036
Corn and Corn Starch Derivatives Market Size, Share, and Industry Trends Forecast 2026-2036
Corn and Corn Starch Derivatives Market Intelligence
The substitution of expensive gums and hydrocolloids with cost-effective modified corn starches is rebalancing formulation economics in the food and beverage industry. Global agribusiness giant Cargill leverages its vast corn sourcing and processing network to supply these derivatives at scale. Ingredion specializes in developing high-performance modified starches for specific textural applications. Archer Daniels Midland Company competes across a wide product spectrum, from sweeteners to industrial ethanol, positioning itself broadly within the bio-based economy.
Corn and corn starch derivatives are ingredients obtained via the wet milling of corn kernels into starch, protein, fiber, and oil. The starch is then modified enzymatically or chemically to create products for thickening, sweetening, or binding. Sweeteners form a mature, high-volume product category, while modified starches command higher margins in specialized applications. The food & beverages industry is the dominant end-use market, with the paper industry providing stable demand for starches as adhesives.
Standards from the U.S. Food and Drug Administration (FDA) and the European Food Safety Authority (EFSA) govern the approval and labeling of food-grade starches. National bodies like India's FSSAI also influence market access through local food safety regulations. Processors must navigate regional differences in genetically modified organism (GMO) acceptance to secure their supply chains and meet consumer preferences.
Market Dynamics
The market's central dynamic is the tension between the food industry's demand for cost-effective, functional ingredients and consumer pressure for clean-label products. This forces processors to innovate beyond basic sweeteners and thickeners toward highly functional, minimally processed derivatives.
Growth Catalysts
- Clean-Label Formulations:The food and beverage sector's move away from artificial additives increases demand for physically or enzymatically modified starches that provide texture and stability without chemical-sounding names on ingredient lists.
- Chinese Industrial Demand:China's massive and expanding food processing industry provides a high-volume demand base for both native and modified corn starches, underpinning a significant portion of market growth.
- Food Safety Standardization:Regulations from bodies like the U.S. Food and Drug Administration (FDA) and the European Food Safety Authority (EFSA) mandate strict quality and safety controls, favoring large, compliant producers with certified supply chains.
Market Restraints
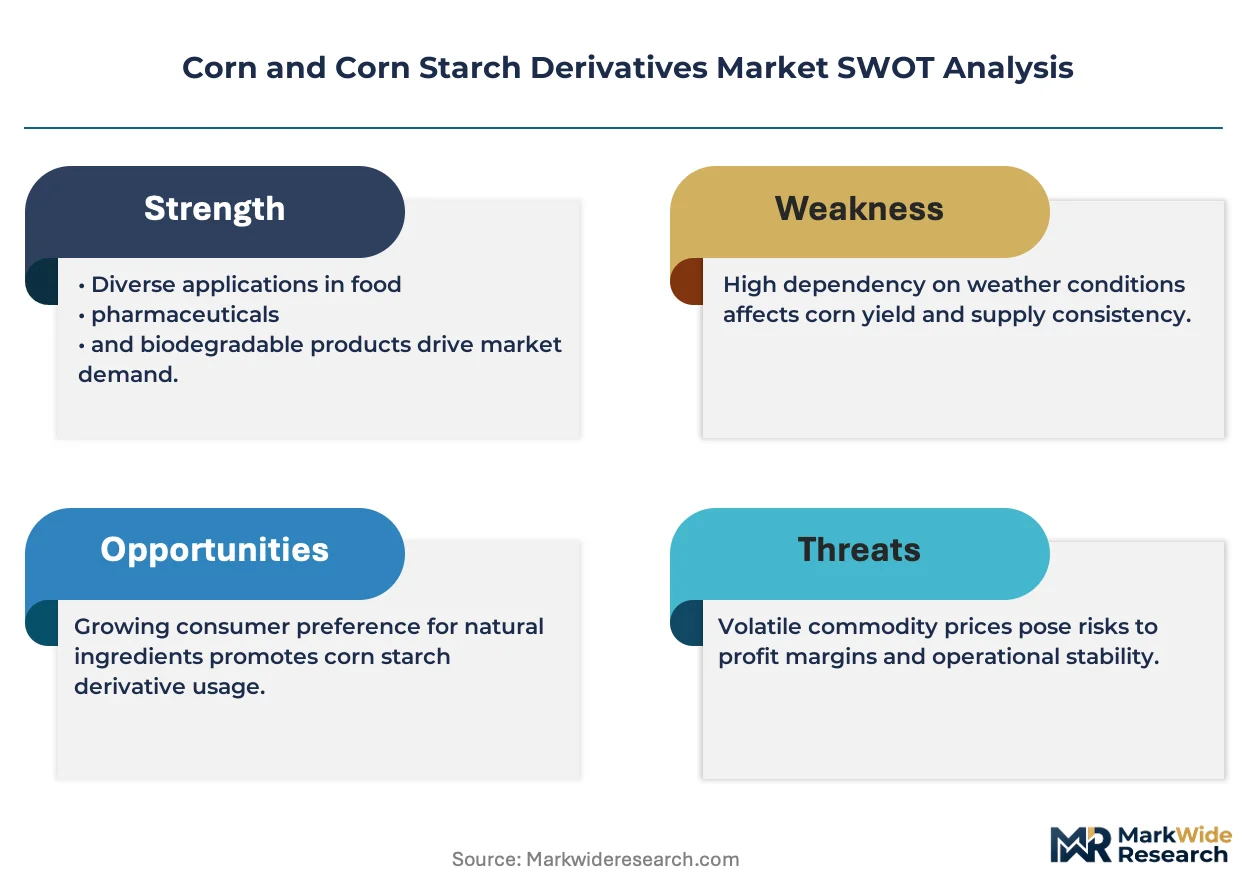
- Input Price Volatility:Dependence on corn as a primary feedstock exposes the market to price fluctuations driven by weather events, biofuel mandates like the U.S. Renewable Fuel Standard, and global agricultural commodity trading.
- GMO Regulatory Divergence:Conflicting regulations and consumer acceptance of genetically modified corn between regions, notably the stringent stance of the European Union versus widespread use in the Americas, complicates global sourcing and trade.
- Threat from Alternative Starches:In specific applications requiring unique gelling properties or a guaranteed non-GMO status, corn starch faces competition from substitutes like tapioca, potato, and pea starches.
Strategic Opportunities
- Bioplastics Feedstock:Growing environmental regulations against petroleum-based plastics create a significant opportunity for corn starch as a primary feedstock for biodegradable polymers like polylactic acid (PLA) used in packaging.
- Fermented Functional Ingredients:The convergence of starch modification with fermentation technology opens pathways to create novel ingredients, such as resistant starches, that offer clinically validated gut health and prebiotic benefits.
- Expansion in Southeast Asia:Rapid growth in the processed food and beverage industries across Southeast Asian nations presents an underpenetrated market for higher-value modified starches and specialized sweeteners.
Industry Challenges
- Traceability and Certification:Implementing and maintaining robust traceability systems to meet stringent non-GMO, organic, or other identity-preserved certifications across a global agricultural supply chain is a major operational complexity.
- Resource-Intensive Processing:The wet milling process is highly consumptive of water and energy, creating operational cost pressures and sustainability challenges in regions facing resource scarcity or carbon taxes.
- Navigating Additive Regulations:Securing regulatory approval for new modified starch products involves navigating a complex and fragmented global landscape of food additive rules, such as differing E-number classifications in Europe and GRAS notices in the United States.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Corn and Corn Starch Derivatives Market |
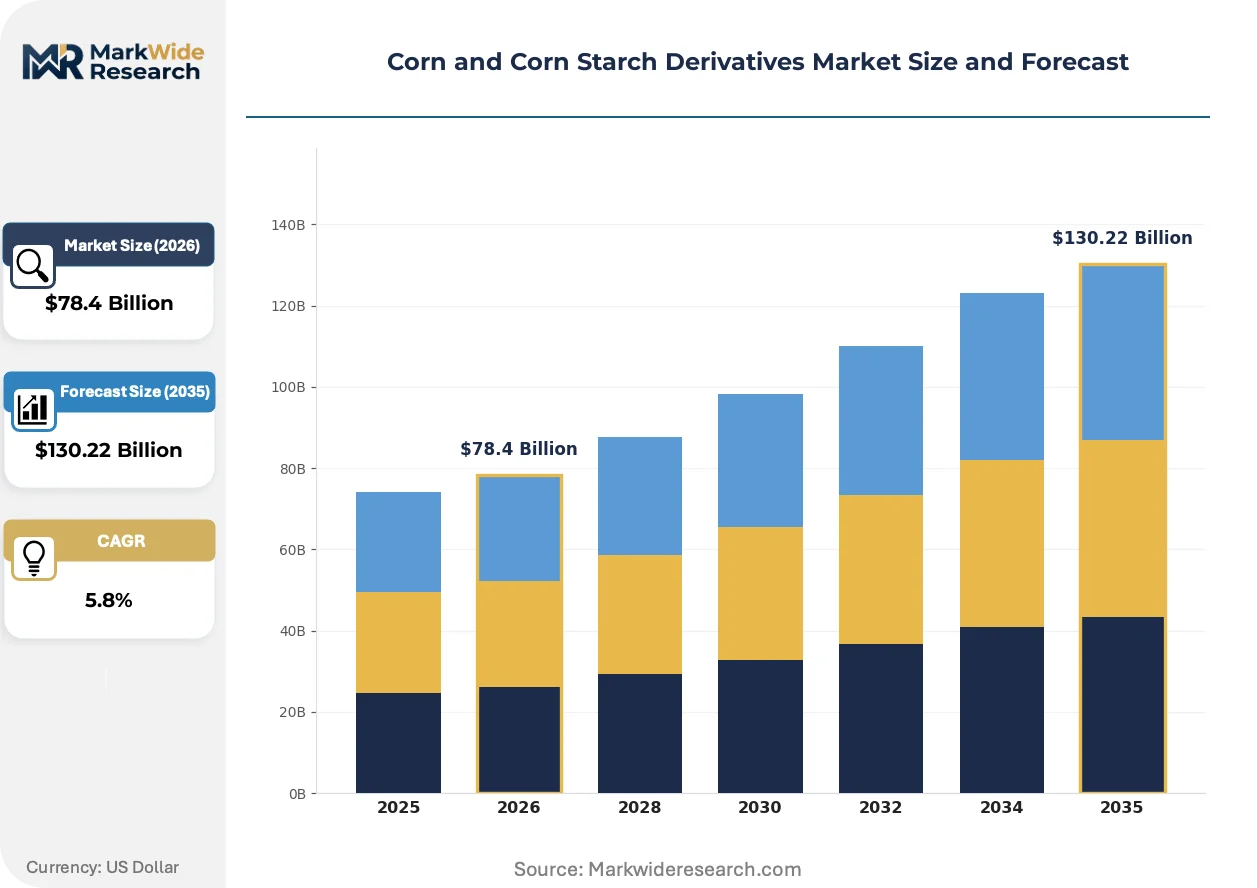
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $130.22 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Corn Starch, Modified Starch, Sweeteners, Ethanol End Use Industry: Food & Beverages, Pharmaceuticals, Textiles, Paper Application: Thickening Agent, Emulsifier, Adhesive, Binder Form: Powder, Liquid, Granules, Flakes |
| Companies Covered | Archer Daniels Midland Company, Cargill, Ingredion, Tate & Lyle, Roquette Frères, AGRANA Beteiligungs-AG, Wacker Chemie AG, Ashland, Tereos Starch & Sweeteners, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Corn and Corn Starch Derivatives Market Strategic Shifts & Innovations
Innovation in the corn derivatives market is driven by a dual focus on enhancing functionality for industrial users and meeting consumer demands for sustainability and naturalness. This pushes development beyond simple cost substitution toward creating value-added ingredients with specific performance attributes.
Advanced Modification Technologies
Enzymatic modification uses specific enzymes to alter starch structures for desired functionalities. Food manufacturers are adopting these derivatives to achieve superior viscosity, freeze-thaw stability, and mouthfeel in clean-label products. This technology is rewriting the formulation possibilities for natural foods, enabling textures and shelf life previously dependent on chemical additives.
Bio-Based Material Mandates
The European Union's Single-Use Plastics Directive is a key policy accelerating the shift toward sustainable materials. This regulatory pressure directly boosts demand for corn starch as a primary feedstock for compostable bioplastics like PLA. The packaging and food service sectors are most impacted, redesigning products to comply with new circular economy targets.
Demand for Plant-Based Excipients
A behavioral shift toward natural ingredients is influencing pharmaceutical and nutraceutical product design. This trend disrupts the market for traditional synthetic binders in tablet manufacturing, creating a preference for plant-derived excipients like corn starch. The shift is most pronounced in the North American and European supplement markets where clean-label positioning is a key consumer driver.
Corn and Corn Starch Derivatives Market Segmentation
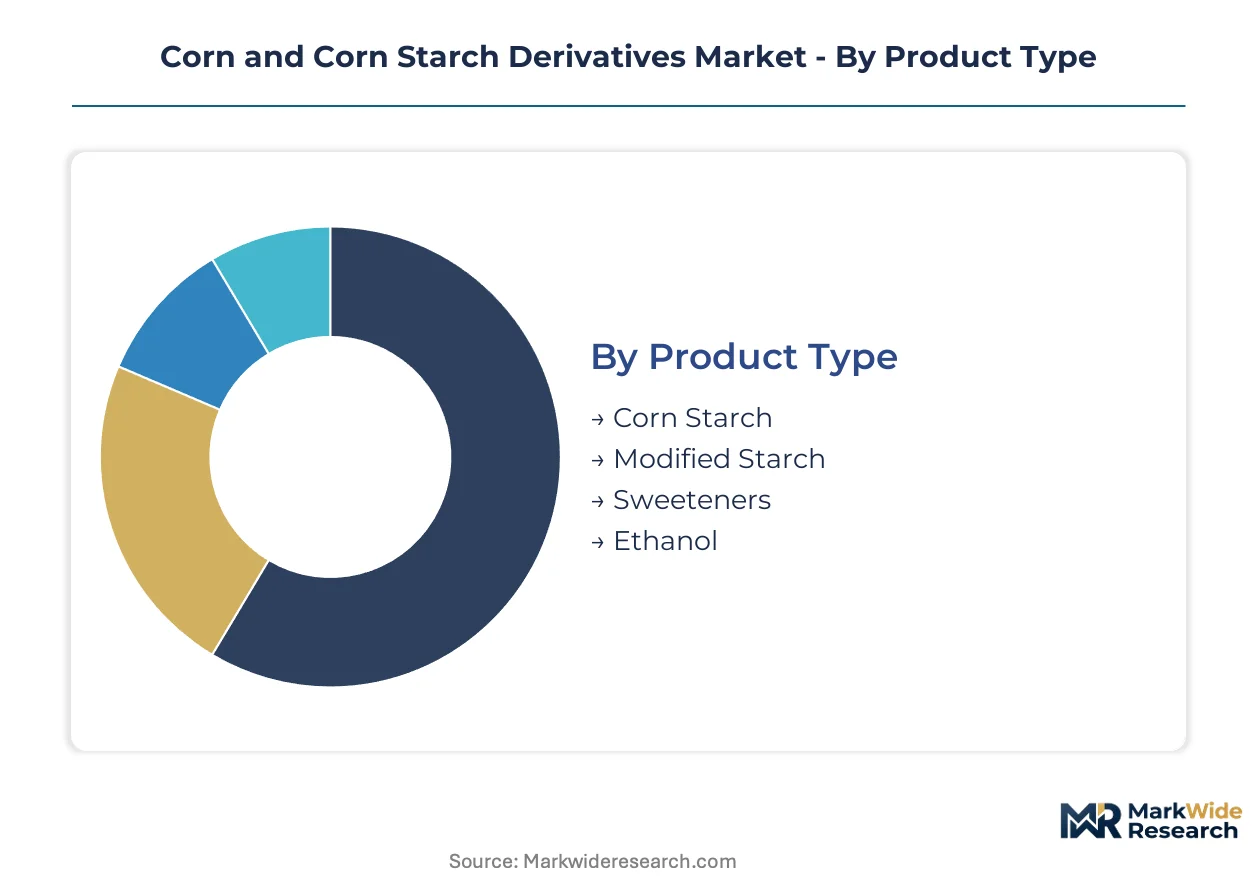
The corn and corn starch derivatives market is categorized by diverse product types, end-use industries, applications, and physical forms. Understanding these segments provides clarity on ingredient functionality and market penetration strategies. Processors tailor their offerings to meet specific industrial demands, from food texturizers to bioplastic feedstocks. This granular view highlights where innovation and investment are most impactful across the value chain.
Product Type:
The market for corn and corn starch derivatives is undergoing a significant upgrade cycle, as formulators replace traditional ingredients with advanced, functional alternatives.
- Modified Starch:These derivatives undergo enzymatic or chemical alterations to enhance properties like freeze-thaw stability, viscosity, and mouthfeel. Demand concentrates in the clean-label food and beverage sector, driven by consumer preference for natural-sounding ingredients.
- Sweeteners:This category encompasses high-volume products like high-fructose corn syrup and dextrose, providing caloric sweetness and functional properties. Demand remains substantial in the global beverage industry, influenced by cost-effectiveness and broad application in processed foods.
- Corn Starch:Native corn starch serves as a fundamental thickening agent and binder in various food and industrial applications.
- Ethanol:Produced from corn fermentation, ethanol primarily functions as a biofuel additive and an industrial solvent.
Volume placements concentrate in Sweeteners; the faster expansion belongs to Modified Starch.
End Use Industry:
The application landscape for corn and corn starch derivatives is diverse, with each industry leveraging specific functional attributes for product development.
- Food & Beverages:This sector is the primary consumer, utilizing derivatives for thickening, sweetening, and texturizing a vast array of products. Demand remains strong across Asia, particularly China, driven by its expanding food manufacturing base.
- Pharmaceuticals:Corn starch derivatives serve as excipients, binders, and disintegrants in tablet formulations and drug delivery systems. The North American and European supplement markets drive demand for plant-based, clean-label excipients.
- Paper:Starches function as binders and surface sizing agents, enhancing paper strength and printability.
- Textiles:Derivatives are used in textile sizing, printing, and finishing processes to improve fabric properties.
The largest application volume resides within the Food & Beverages sector, with Pharmaceuticals exhibiting the steepest expansion trajectory.
Application:
Formulators select corn and corn starch derivatives based on their specific functional requirements, optimizing product performance and consumer experience.
- Thickening Agent:Derivatives provide viscosity and body to liquid and semi-liquid food products, preventing separation and improving mouthfeel. This function is critical in sauces, soups, and dairy alternatives, with demand high in processed food manufacturing.
- Binder:Starches act as cohesive agents, holding particles together in applications such as tablets, pet food, and paper products. Demand is significant in the pharmaceutical industry, where binding consistency is crucial for drug integrity.
- Emulsifier:Certain modified starches stabilize oil-in-water emulsions, preventing phase separation in dressings and beverages.
- Adhesive:Corn starch derivatives are used as glues and pastes, particularly in the paper and packaging industries.
The most widespread functional utility comes from their role as a Thickening Agent, while their use as a Binder is gaining share fastest in specialized markets.
Form:
The physical presentation of corn and corn starch derivatives dictates their ease of handling, dispersion properties, and suitability for various manufacturing processes.
- Powder:The most common form, offering excellent shelf stability and ease of transport for bulk industrial use. Demand is pervasive across all end-use sectors, particularly in dry mixes and tablet manufacturing.
- Liquid:Syrups and solutions provide immediate dispersibility and are often preferred in beverage and confectionery production for ease of integration. This form is widely adopted in high-volume processing facilities in the Americas.
- Granules:Granular forms offer controlled dissolution rates and reduced dusting, beneficial in specific industrial and food applications.
- Flakes:Flakes are less common but find niche applications where rapid hydration or unique textural properties are desired.
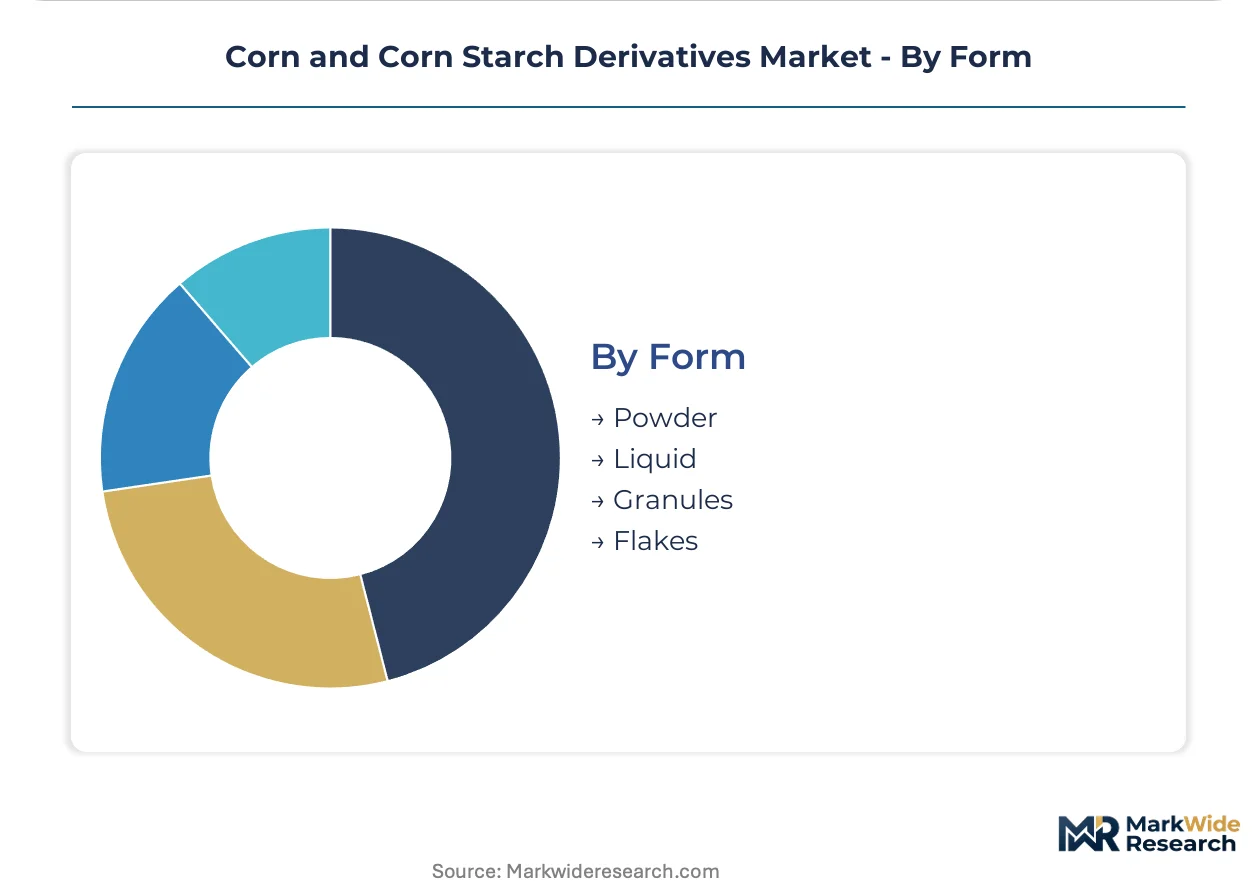
Powder forms represent the largest volume segment, with Liquid forms expanding most quickly in specific industrial applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Global demand for corn and corn starch derivatives concentrates significantly in regions with large-scale food manufacturing and processing capabilities. This demand is particularly strong in the Asia-Pacific region, driven by expanding consumer markets and industrial food production. Processors strategically position operations to serve these high-volume centers.
China
China's expansive food processing industry drives substantial demand for both native and modified corn starches. The country's GB standards govern food ingredient safety and quality, influencing market access for derivatives. Major food manufacturing hubs in the Yangtze River Delta region continually integrate corn starch products into processed foods.
United States
The United States exhibits robust demand for corn derivatives, especially for clean-label food formulations and pharmaceutical excipients. U.S. Food and Drug Administration (FDA) regulations dictate ingredient approval and labeling for food-grade starches. Major corn processing facilities across the Midwest, particularly in Illinois, supply the national food and pharmaceutical industries.
Germany
German food manufacturers seek high-performance modified starches for diverse applications, including bioplastics feedstock. European Food Safety Authority (EFSA) standards ensure strict quality and safety controls for food ingredients. Industrial clusters in North Rhine-Westphalia actively develop corn starch-based bioplastics for packaging solutions.
India
Growing processed food and beverage consumption in India fuels demand for cost-effective corn starch derivatives. The Food Safety and Standards Authority of India (FSSAI) influences market access through local food safety regulations. Food and pharmaceutical manufacturing centers in Maharashtra increasingly adopt corn starch as a functional ingredient.
Brazil
Brazil, a significant corn producer, utilizes derivatives extensively in its large domestic food industry and for ethanol production. ANVISA regulates food additives and ingredients, ensuring product safety and compliance. Corn-based ethanol production facilities in São Paulo state contribute significantly to the country's biofuel sector.
Corn and Corn Starch Derivatives Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments within the corn and corn starch derivatives market. The market features a blend of large, vertically integrated agribusiness giants and specialized ingredient providers. Global players often leverage extensive sourcing networks, while niche firms focus on high-margin, functional solutions. Companies pursue portfolio diversification into advanced modification technologies and bioplastics feedstock to secure future growth.
Within the market, global agribusiness giants like Cargill exemplify broad supply chain integration, leveraging vast corn sourcing and processing networks to deliver high-volume commodity and ingredient solutions. Ingredion represents a specialized ingredient provider, focusing on developing high-performance modified starches for specific textural applications and clean-label formulations. Archer Daniels Midland Company (ADM) anchors a diversified approach, competing across a wide product spectrum from high-fructose corn syrup to industrial ethanol. These entities collectively shape the competitive landscape, balancing commodity volume with specialized ingredient innovation and sustainability initiatives.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| Cargill |
| Ingredion |
| Tate & Lyle |
| Roquette Frères |
| AGRANA Beteiligungs-AG |
| Wacker Chemie AG |
| Ashland |
| Tereos Starch & Sweeteners |
| Others |
Cost & Logistics Intelligence
Food & beverage manufacturers, particularly large processors in China, frequently engage in long-term contract-based pricing for high-volume corn starches, balancing cost stability against commodity spot price volatility. This approach helps stabilize input costs for extensive food production.
Pricing Analysis
Sweeteners represent high-volume, lower-margin products, while modified starches command higher margins due to specialized functionality. Pricing operates on a hybrid model, combining contract-based long-term offtake for commodity products with value-based pricing for advanced modified starches. Price differentiation stems from clean-label certifications, specific functional performance like freeze-thaw stability, and geographic delivery costs. Pricing softness in native starches stems from commodity price volatility and oversupply. The beverage industry is highly price-sensitive for sweeteners, whereas pharmaceutical excipient buyers are less sensitive due to critical performance requirements.
Supply Chain Analysis
Single-source vulnerability sits with major corn-producing regions like the U.S. Midwest and Brazil for primary feedstock. Geographic supply concentrates in the United States, Brazil, and China, which serve as key processing hubs. The market depends on corn kernels as the primary input, with enzymes for starch modification also critical. Geopolitical tensions and climate-induced weather events pose significant commodity price volatility risks. Distribution runs through a mix of direct sales to large industrial users and specialized ingredient distributors for smaller formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The corn and corn starch derivatives market is navigating a technology-transition phase, as advanced enzymatic modification techniques displace older chemical modification methods. This shift enables new functionalities for clean-label product development.
For Market Incumbents:Anticipate sustained demand for clean-label solutions by investing heavily in R&D for enzymatic modification technologies. Competition from alternative starches like tapioca and pea starch represents a threat, especially in non-GMO segments. Secure long-term corn supply contracts in key agricultural regions to mitigate input price volatility. Expand certified non-GMO processing capabilities to meet European and specific consumer preferences.
For New Entrants and Emerging Players:Fermentation-enabled functional ingredients offer a technology-first wedge into the high-margin nutraceutical and health food sectors. Target underpenetrated Southeast Asian markets for specialized prebiotics and resistant starches. Partner with local food innovation hubs to co-develop region-specific clean-label products. Focus on clinically validated gut health benefits to differentiate from established players.
For Investors and Strategic Acquirers:The window for entry favors strategic acquirers seeking advanced bioprocessing capabilities over the next 5-10 years. Mid-sized firms specializing in novel starch modification technologies or bioplastics applications represent ideal acquisition targets. Market transformation toward sustainable packaging and functional foods provides robust long-term growth. Regulatory mandates for compostable packaging in major economies will serve as a key signal to watch, accelerating bioplastic feedstock demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Modification R&D | Develops high-performance clean-label ingredients for food and pharmaceutical applications. |
| Bioplastics Feedstock Capacity Expansion | Meets growing demand for sustainable packaging driven by environmental regulations. |
| Non-GMO Supply Chain Certification | Addresses consumer and regulatory preference for identity-preserved ingredients in key markets. |
| Southeast Asia Market Entry | Captures growth in processed food and beverage sectors across rapidly expanding economies. |
| Fermented Functional Ingredients Development | Creates value-added products with clinically validated health benefits for nutraceuticals. |
Research Approach
Multi-period observation of corn commodity prices and clean-label ingredient adoption rates anchored the trend analysis, supplemented by interviews. Primary research involved discussions with R&D directors at ingredient manufacturers, procurement leads in food & beverage, and regulatory affairs specialists. Secondary data sources included FDA and EFSA regulatory filings, USDA agricultural reports, and company annual reports. This approach facilitated bottom-up market sizing and top-down validation of market dynamics.
Segment-weighting approach calibrated volume and value across product types, end-use industries, applications, and physical forms. The analytical framework integrated macroeconomic indicators and consumer preference shifts throughout the forecast period. Compound annual growth rates were derived from historical data analysis and projected future demand scenarios. Key forecast inputs included global corn harvest yields and regional clean-label ingredient penetration rates.
Several conditions sit outside the modeled scope, including unforeseen geopolitical conflicts or rapid shifts in biofuel policy. Forecasts reflect assumptions about technology adoption and regulatory stability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Commodities
Gorse Market
Agricultural Commodities
Astrocaryum Murumuru Seed Butter Market
Agricultural Commodities
South America Feed Amino Acids Market
Agricultural Commodities
Blood Meal Market
Agricultural Commodities
Beet Pulp Pellets Market
Agricultural Commodities
Castor Oil Market
Agricultural Commodities
UK Bird Feeder Market
Agricultural Commodities
Asia-Pacific Feed Amino Acids Market
Agricultural Commodities
Cottonseed Meal Market
Agricultural Commodities
Global Wood Chips Market
Agricultural Commodities
Artificial Fishing Baits Market
Agricultural Commodities
Growing Peat Market
Agricultural Commodities
Black Pellet Market
Agricultural Commodities
Cottonseed Hulls Market
Agricultural Commodities
Vietnam Compound Feed Market
Agricultural Commodities
Straw Market