
 North America Aloe Vera Market | 2026-2036
North America Aloe Vera Market Size, Share, and Industry Trends Forecast 2026-2036
North America Aloe Vera Market Intelligence
Buyer concentration in the North American beverage sector is pivoting toward mid-sized functional drink brands seeking differentiated botanical formulations. Lily of the Desert leverages its integrated Texas growing and processing infrastructure to secure long-term supply contracts. ALO Drink anchors the ready-to-drink segment through premium retail placement and direct-store-delivery networks. Terry Laboratories Inc. specializes in cosmetic-grade aloe extracts, commanding technical specifications that mass-market suppliers rarely match.
Aloe vera comprises the succulent leaf tissue of Aloe barbadensis miller, yielding a mucilaginous gel containing polysaccharides, anthraquinones, and glycoproteins extracted through cold-press filtration or whole-leaf processing. The plant serves primarily as a functional ingredient in topical, ingestible, and cosmetic applications where consumers prioritize plant-derived formulation claims. Aloe gel and aloe juice dominate volume flows through food and beverage channels, while dried aloe and aloe powder capture higher margins in pharmaceutical and nutraceutical compounding where concentration standardization commands premium pricing. Cosmetics applications lead absolute value generation, though nutraceuticals represent the fastest-expanding application segment as supplement brands reformulate around digestive health positioning.
The FDA exercises oversight through GRAS self-affirmation pathways for aloe in beverages, while USDA organic certification governs premium tier product claims across North American retail. Health Canada and PMRA coordinate cross-border standards for topical aloe products entering Canadian distribution, creating compliance complexity for unified North American SKU strategies. Stakeholders must monitor evolving state-level Prop 65 litigation trends around anthraquinone content thresholds, as California enforcement patterns typically propagate to broader national formulation standards.
Market Dynamics
Clean-label procurement mandates from beverage formulators are compressing ingredient qualification timelines while concentrating supply relationships around vertically integrated growers with certified organic capacity and validated GRAS dossiers.
Growth Catalysts
- FDA GRAS Self-Affirmation Pathway:Streamlined ingredient approval for aloe-derived additives accelerates new product launches in functional beverage categories without lengthy pre-market notification delays.
- Digestive Health Positioning:Supplement brands reformulating around gut wellness claims drive polysaccharide-standardized aloe powder demand through nutraceutical compounding channels.
- California Central Valley Concentration:Year-round growing conditions and established organic certification infrastructure anchor North American raw material supply security.
Market Restraints
- Anthraquinone Content Thresholds:California Prop 65 litigation patterns around aloin levels force reformulation costs and batch testing protocols that erode margin structures for mass-market suppliers.
- Input Cost Volatility:Organic fertilizer and irrigation water pricing in Texas processing corridors fluctuates with drought cycles and energy tariffs, compressing processor economics.
- Technical Limitation in Cold-Press Yields:Gel extraction efficiency caps from whole-leaf versus inner-fillet processing methods constrain volume scalability for cosmetic-grade specifications.
Strategic Opportunities
- Canadian Distribution Expansion:Health Canada and PMRA coordination gaps create first-mover advantage for brands establishing compliant topical aloe SKUs ahead of unified North American standards.
- Direct-Store-Delivery Networks:Ready-to-drink aloe beverage penetration through independent convenience and natural channel routes bypasses traditional distributor markups.
- USDA Organic Certification Tailwind:Premium tier retail placement incentives reward processors with certified captive growing operations and transparent supply chain documentation.
Industry Challenges
- Cross-Border SKU Harmonization:Divergent Health Canada and FDA labeling requirements for aloe latex warnings complicate unified North American packaging strategies and inventory management.
- Capex Intensity for Cold-Chain Infrastructure:Fresh aloe gel stabilization requires flash-pasteurization and aseptic filling investments that strain mid-sized processor balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Aloe Vera Market |
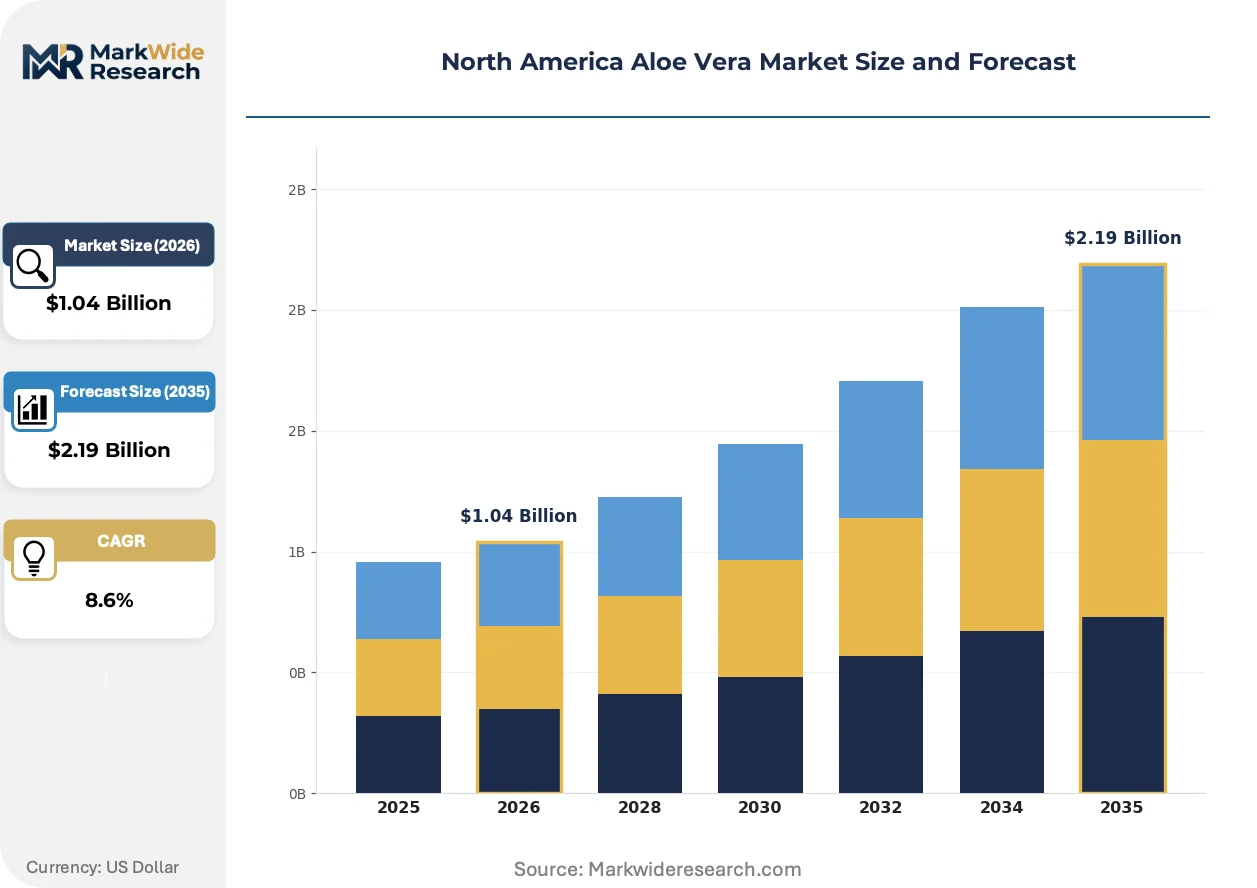
| Market Size in 2026 | $1.04 Billion |
| Market Size in 2035 | $2.19 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aloe Gel, Aloe Juice, Dried Aloe, Aloe Powder Application: Cosmetics, Food & Beverage, Pharmaceuticals, Nutraceuticals Distribution Channel: Online Retail, Supermarkets, Health Stores, Direct Sales Customer Type: Retail Consumers, Manufacturers, Wholesalers, Exporters |
| Companies Covered | ALO Drink (SPI West Port Group), Lily of the Desert, OKF Corporation, Terry Laboratories Inc., Aloecorp Inc., Herbalife Nutrition Ltd., Aloe Farms, Inc., Nature's Way Products LLC, Fruit of the Earth Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Aloe Vera Market Strategic Shifts & Innovations
Electrochemical stabilization and rapid low-temperature processing methods are compressing the gap between harvest and bioactive preservation, reshaping competitive advantage around technical extraction capabilities rather than raw acreage alone.
Whole-leaf processing with activated charcoal filtration is electrifying the premium cosmetic segment by delivering higher polysaccharide retention rates than traditional inner-fillet methods. Major skincare formulators in California and Texas are retrofitting extraction lines to capture this yield advantage. The technology is compressing price premiums previously commanded by specialized cosmetic-grade suppliers with legacy cold-press infrastructure.
USDA organic certification enforcement through the National Organic Program is tightening traceability documentation requirements for imported aloe concentrates. Processors must now maintain lot-level chain-of-custody records from Mexican and Central American growing operations through Texas border processing facilities. The nutraceutical segment faces the steepest compliance recertification burdens as supplement brands demand certified organic claims for digestive health positioning.
Functional beverage buyers are consolidating supplier relationships around processors offering validated GRAS dossiers and organic certification in single procurement contracts. Mid-sized drink brands bypass traditional ingredient distributors to secure direct supply agreements with Texas-integrated growers. This pattern concentrates most visibly in California's natural channel retail networks where clean-label claims determine shelf placement velocity.
North America Aloe Vera Market Segmentation
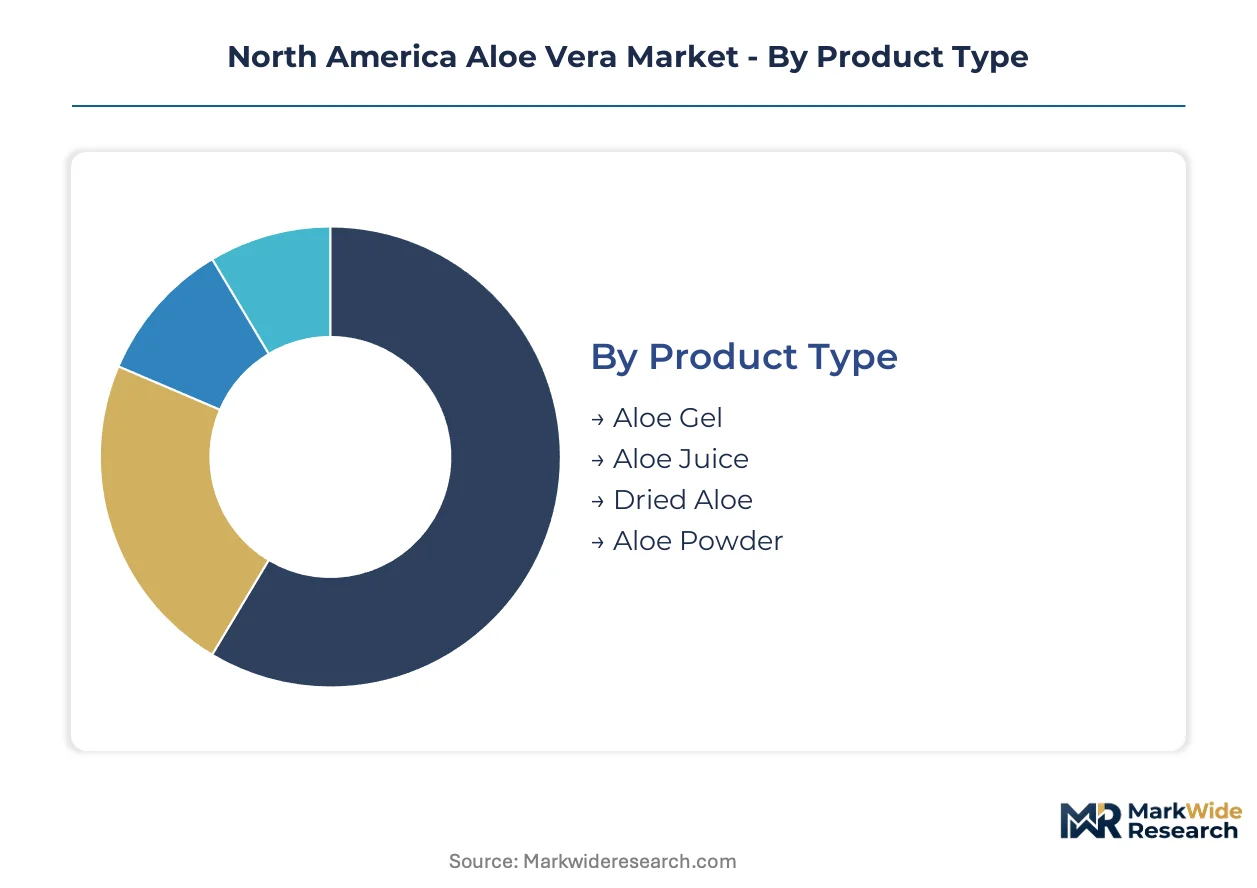
Segmentation in the North American aloe vera market reveals how capital requirements, regulatory pathways, and buyer concentration reshape competitive positioning across distinct product tiers. Processors with captive growing operations and certified extraction infrastructure command disproportionate margin capture versus commodity traders.
Product Type:
Capital intensity concentrates in cold-chain stabilization and aseptic filling infrastructure, with powder production demanding the heaviest upfront investment in spray-drying and concentration standardization equipment.
- Aloe Gel:Cold-pressed inner fillet or whole-leaf mucilaginous extract requiring flash-pasteurization and refrigerated logistics. California beverage formulators and Texas cosmetic compounders dominate procurement, with clean-label mandates compressing qualification timelines around GRAS-validated suppliers.
- Aloe Powder:Spray-dried or freeze-dried concentrate standardized to polysaccharide content for nutraceutical encapsulation. Supplement brands in the digestive health segment drive demand, with USDA organic certification commanding premium placement in natural channel retail.
- Aloe Juice:Decolorized and filtered beverage-grade liquid processed through activated charcoal filtration. Ready-to-drink brands in California's Central Valley anchor volume offtake.
- Dried Aloe:Sun-dried or low-temperature dehydrated leaf segments for traditional medicinal applications. Smaller batch production serves specialty herbal compounders with limited processing infrastructure.
Most installed capacity flows through Aloe Gel. Expansion is steepest in Aloe Powder.
Application:
Margin structures diverge sharply between premium cosmetic formulations and commodity beverage ingredients, with pharmaceutical-grade specifications imposing the steepest technical barriers to entry.
- Cosmetics:Topical formulations leveraging polysaccharide retention for moisturization and soothing claims. California skincare brands and Texas private-label manufacturers concentrate demand, with whole-leaf processing methods displacing traditional inner-fillet extraction for yield advantages.
- Nutraceuticals:Digestive health supplements and functional food fortification using standardized aloe polysaccharides. The segment climbs fastest as reformulation around gut wellness positioning accelerates powder demand through compounding channels.
- Food & Beverage:Ready-to-drink functional beverages and clean-label food processing. Direct-store-delivery networks in California natural channels bypass traditional distributor markups for mid-sized brands.
- Pharmaceuticals:Wound care and topical therapeutic applications requiring validated bioactive concentration. Health Canada and FDA labeling divergence complicates unified North American SKU strategies.
Revenue concentration sits with Cosmetics. Volume expansion runs through Nutraceuticals.
Distribution Channel:
Channel selection determines working capital intensity, with direct sales requiring the deepest field organization investment and online retail demanding digital infrastructure spend.
- Direct Sales:Long-term supply contracts between integrated Texas growers and California beverage or cosmetic formulators. Procurement consolidation around single-source agreements with validated organic certification and GRAS dossiers.
- Health Stores:Natural channel retail placement in California and Pacific Northwest markets where clean-label claims determine shelf velocity. Independent retailers favor processors with transparent supply chain documentation.
- Supermarkets:Mass-market retail distribution for ready-to-drink aloe beverages. Placement competition intensifies around premium positioning versus private-label alternatives.
- Online Retail:Direct-to-consumer and B2B platform sales for specialty aloe ingredients. Traceability documentation and organic certification visibility drive conversion in supplement segments.
Contract volume concentrates in Direct Sales. Digital infrastructure investment flows fastest into Online Retail.
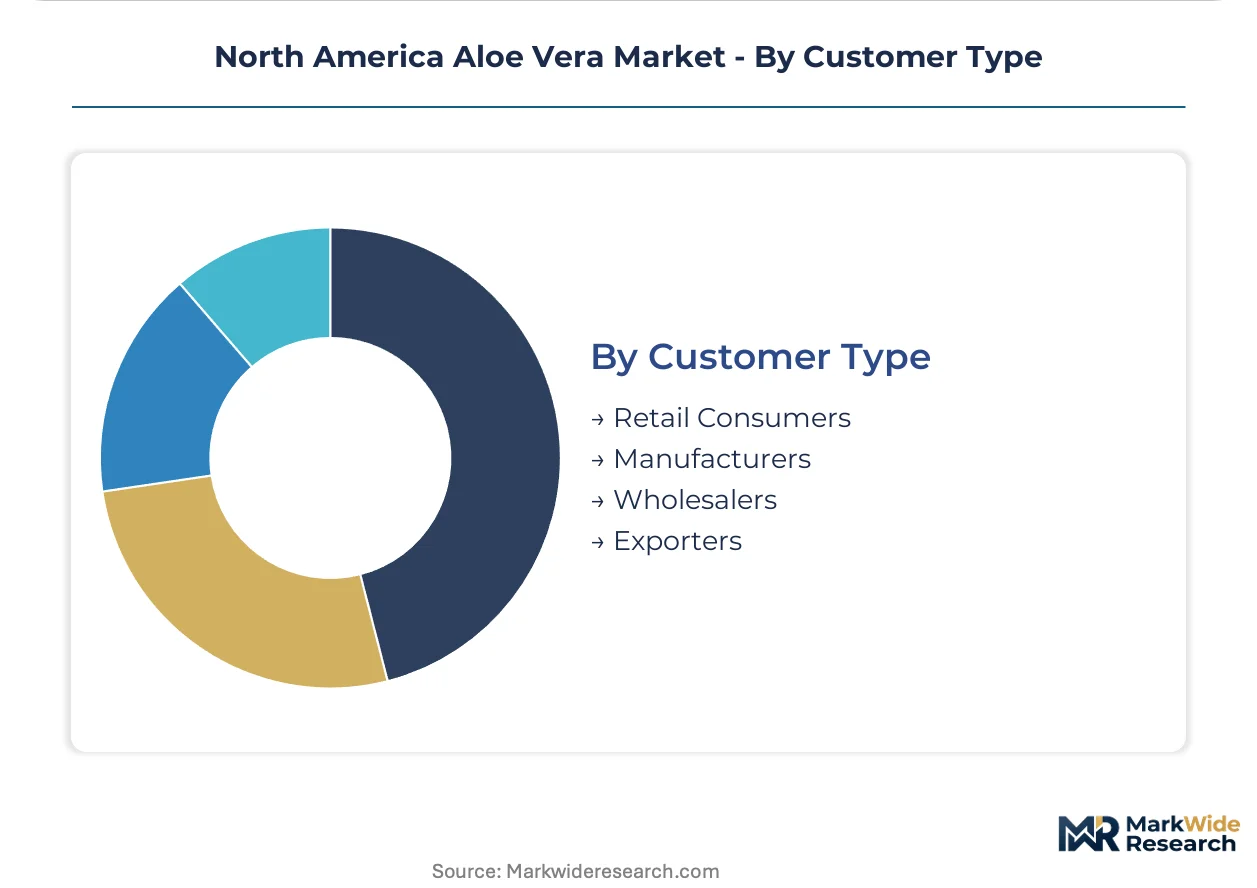
Customer Type:
Buyer scale and technical sophistication fragment procurement patterns, with manufacturers imposing the most stringent specification requirements and retail consumers driving brand premiumization.
- Manufacturers:Beverage, cosmetic, and pharmaceutical formulators requiring batch-level consistency and validated regulatory compliance. California and Texas processing corridors anchor geographic concentration of qualified suppliers.
- Retail Consumers:End-users purchasing finished aloe products through natural channel or mass retail. Premium positioning around organic claims and digestive health benefits supports price realization.
- Wholesalers:Regional distributors serving independent health stores and smaller cosmetic compounders. Inventory management complexity rises with cross-border SKU harmonization requirements.
- Exporters:Canadian and Mexican trade flows subject to Health Canada and PMRA coordination for topical products. Compliance documentation burdens concentrate on lot-level chain-of-custody records.
Specification intensity peaks with Manufacturers. Geographic expansion targets Exporters.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canada's aloe vera market advances through Health Canada and PMRA coordination for topical products, while the United States dominates raw material processing and beverage formulation volumes. Mexico supplies cross-border organic feedstock through established Central American growing networks.
United States
California's Central Valley anchors year-round growing operations with established USDA organic certification infrastructure. The FDA's GRAS self-affirmation pathway accelerates new product launches for functional beverage brands. Texas processing corridors concentrate cold-press extraction and spray-drying capacity serving cosmetic and nutraceutical compounders.
Canada
Health Canada and PMRA coordinate cross-border standards for topical aloe products entering Canadian distribution channels. The country's natural health product regulations impose distinct labeling requirements for aloe latex warnings. Ontario and British Columbia health store networks drive premium-tier demand for certified organic aloe supplements.
Mexico
Established aloe cultivation in northern states supplies raw leaf material to Texas border processing facilities. The country's national agricultural regulator enforces phytosanitary export documentation for organic concentrates. Jalisco and Nuevo León growing regions maintain lot-level chain-of-custody records required by USDA National Organic Program traceability mandates.
North America Aloe Vera Market Key Industry Players
Texas-integrated growers anchor one tier; California beverage specialists hold placement advantages in natural channel retail. The vendor base distributes across captive growing operations, contract processors, and finished goods marketers. Three archetypes dominate: vertically integrated growers with certified organic capacity, cosmetic-grade extract specialists commanding technical specifications, and ready-to-drink brands securing direct-store-delivery networks. Capacity expansion and procurement consolidation around single-source agreements represent the dominant competitive vectors.
Among Texas-based integrated producers, Lily of the Desert exemplifies the grower-processor archetype with captive organic operations. ALO Drink occupies a position within the ready-to-drink beverage tier through premium retail placement strategies. Terry Laboratories Inc. represents the cosmetic-grade specialist segment with technical extraction capabilities that mass-market suppliers rarely match.
| Leading Market Players |
|---|
| ALO Drink (SPI West Port Group) |
| Lily of the Desert |
| OKF Corporation |
| Terry Laboratories Inc. |
| Aloecorp Inc. |
| Herbalife Nutrition Ltd. |
| Aloe Farms, Inc. |
| Nature's Way Products LLC |
| Fruit of the Earth Inc. |
| Others |
Cost & Logistics Intelligence
Organic fertilizer and irrigation water pricing in Texas processing corridors fluctuates with drought cycles and energy tariffs, compressing processor economics and forcing tiered pricing stratification across certified organic, conventional, and commodity-grade aloe derivatives downstream.
Pricing Analysis
Capacity additions in Texas spray-drying facilities are reshaping price floors for aloe powder grades. Three-tier pricing structure across premium, standard, and economy levels separates USDA organic-certified extracts from conventional whole-leaf and commodity inner-fillet grades. Cost compression in mass-market beverage tiers is intensifying because California Prop 65 litigation forces batch testing protocols. Retail consumers in natural channel health stores demonstrate lowest price sensitivity, while mass-market beverage formulators exhibit highest elasticity.
Supply Chain Analysis
USDA National Organic Program traceability mandates are reshaping sourcing requirements for Mexican and Central American feedstock. Raw material supply draws from Mexico's Jalisco and Nuevo León growing regions, California's Central Valley, and Texas border processing facilities. The chain rests on organic leaf concentrate, activated charcoal filtration media, and aseptic packaging materials. Single-source vulnerability concentrates in Texas cold-press extraction capacity. Distribution runs through direct sales contracts between integrated growers and California beverage formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North American aloe vera market functions as a geographic-arbitrage play where Texas processing cost advantages versus California regulatory compliance burdens create margin capture opportunities for cross-border operators.
For Market Incumbents: Anticipate Health Canada and PMRA coordination tightening by pre-positioning compliant topical SKUs ahead of unified North American standards. Deepen backward integration into Mexican organic growing operations to secure lot-level chain-of-custody documentation required by USDA National Organic Program enforcement. Channel control through direct-store-delivery networks in California natural retail offers defensive moat against emerging ready-to-drink entrants.
For New Entrants and Emerging Players: Independent health stores in Ontario and British Columbia represent the most penetrable channel tier given Health Canada's distinct natural health product labeling requirements that complicate incumbent SKU adaptation. Target digestive health supplement compounding for nutraceutical brands seeking polysaccharide-standardized aloe powder with certified organic claims. A go-to-market angle anchored in transparent supply chain documentation and rapid GRAS self-affirmation support accelerates qualification timelines.
For Investors and Strategic Acquirers: Roll-up economics work for Texas-integrated processors with captive organic certification because FDA GRAS dossier validation and USDA traceability infrastructure create high switching costs for beverage brand customers. Five-to-ten year viability hinges on consolidation of mid-sized spray-drying capacity serving nutraceutical powder demand. The signal to watch is California Prop 65 enforcement patterns propagating to national anthraquinone thresholds, which would accelerate compliance-driven M&A.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Mexican Organic Growing | Captive supply of certified feedstock insulates against USDA National Organic Program traceability enforcement. |
| GRAS Dossier Validation Investment | FDA self-affirmation pathway acceleration compresses new product launch timelines for functional beverage clients. |
| Health Canada Pre-Positioning | Early compliance with PMRA topical standards captures first-mover advantage before unified North American regulations. |
| Direct-Store-Delivery Network Expansion | Bypassing traditional distributor markups improves margin capture in California natural channel retail placement. |
| Whole-Leaf Processing Retrofit | Activated charcoal filtration yields higher polysaccharide retention than inner-fillet methods for cosmetic-grade specifications. |
Research Approach
Bottom-up beverage and nutraceutical procurement modeling reconciled against top-down aloe leaf harvest and processing capacity tracking forms the analytical core. Primary interviews with Texas-integrated growers, California beverage formulators, cosmetic compounders, and Health Canada regulatory consultants combined with secondary validation against FDA GRAS notification databases, USDA National Organic Program certification records, and California Department of Public Health Prop 65 enforcement filings. Triangulation across supply-side capacity surveys and demand-side procurement pattern analysis ensures segment-level consistency.
Input-output matrices map aloe gel, powder, juice, and dried leaf flows across cosmetics, nutraceuticals, food and beverage, and pharmaceutical applications. Segmentation dimensions span product type, application, distribution channel, and customer archetype. CAGRs derive from regression-based trend extrapolation moderated by regulatory event probability weighting. Forecast inputs include California Central Valley growing season yield variability and Texas energy tariff exposure for spray-drying operations.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Health Canada and PMRA regulatory coordination timing and California Prop 65 litigation settlement patterns. Projections reflect documented assumptions around organic certification compliance rates and GRAS self-affirmation pathway efficiency. A small set of triggers—cross-border SKU harmonization mandates, drought-induced irrigation cost spikes, and anthraquinone threshold enforcement—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Swine Feed Premix Market
Agriculture and Agri Products
Animal Feed and Pet Food Market
Agriculture and Agri Products
Arnica Oil Market
Agriculture and Agri Products
Organic Hemp Market
Agriculture and Agri Products
United Kingdom Commercial Greenhouse Market
Agriculture and Agri Products
North America Alfalfa Hay Market
Agriculture and Agri Products
Malaysia Floriculture Market
Agriculture and Agri Products
North America Swine Feed Premix Market
Agriculture and Agri Products
Clover Leaf Oil Market
Agriculture and Agri Products
United Kingdom Animal Protein Market
Agriculture and Agri Products
Sugar Beet Market
Agriculture and Agri Products
France Compound Feed Market
Agriculture and Agri Products
South America Compound Feed Market
Agriculture and Agri Products
Italy Animal Protein Market
Agriculture and Agri Products
North America Poultry Feed Market
Agriculture and Agri Products
Asia Pacific Poultry Feed Market