
 South American Maize Market | 2026-2036
South American Maize Market Size, Share, and Industry Trends Forecast 2026-2036
South American Maize Market Analytics
Non-GMO IP certification is bifurcating the South American maize value chain into segregated supply streams. Bunge Limited leverages its crushing and export terminal network to sustain origination dominance across Brazil's Center-West. Cargill, Inc. anchors its position through integrated risk management and farmer financing programs. ADM competes via deep-water port assets and destination market relationships in Asia.
South American maize comprises Zea mays cultivars with moisture content typically standardized at 14.5% for commercial trade, processed through dry milling for grits and flour or wet milling for starch and ethanol extraction. Field maize dominates volume flows into animal feed and industrial channels, while sweet maize commands premium pricing in fresh and frozen food segments. The grade dimension reveals structural tension: organic and non-GMO categories capture margin premiums in European and North American export markets, whereas conventional hybrid volumes drive aggregate tonnage and price discovery at Brazilian terminals.
ANVISA in Brazil and SENASA in Argentina enforce mycotoxin limits and biotech event registration that shape cultivar approval timelines and cross-border trade eligibility. Brazil's MAPA grain inspection protocols and the Mercosur technical regulations on genetically modified organisms create compliance layers that filter market participation. Stakeholders must monitor evolving EU deforestation-free supply chain mandates and their traceability implications for Amazon and Cerrado sourcing regions.
Market Dynamics
Argentina's SENASA phytosanitary certification tightening is compressing export-grade supply pools and forcing quality investments across Brazilian and Argentine origination networks. This regulatory pressure cascades through silo infrastructure, port inspection protocols, and farmer financing terms.
Growth Catalysts
- Poultry and pork sector scaling:Brazil's integrated protein processors are expanding offtake volumes from Mato Grosso state suppliers, creating dedicated feed-grade demand corridors.
- EU deforestation-free mandates:Traceability requirements for Amazon and Cerrado sourcing are accelerating investment in geofenced origination and satellite-verified supply chains.
- Non-GMO IP certification premiums:European and North American export markets are rewarding segregated supply streams with margin capture for certified handlers.
Market Restraints
- Input cost volatility:Fertilizer and fuel price swings squeeze farmer margins in Brazil's Center-West, constraining planted area expansion.
- Port logistics concentration:Santos and Paranaguá terminals handle disproportionate export volumes, creating chokepoint vulnerability during peak harvest windows.
- Biotech event registration delays:Brazil's MAPA and Argentina's SENASA approval timelines extend cultivar commercialization cycles, limiting trait innovation speed-to-market.
Strategic Opportunities
- Underpenetrated Paraguayan origination:Land expansion potential and lower production costs attract crushing and trading infrastructure investment.
- Carbon credit monetization:No-till farming protocols and cover crop integration generate verified emissions reductions for compliance markets.
- Wet milling diversification:Starch and ethanol extraction capacity expansion captures value from industrial demand growth in Brazilian biofuel blending mandates.
Industry Challenges
- Geofencing and traceability system integration:EU deforestation regulations require farm-level polygon mapping and audit trail maintenance across fragmented supplier bases.
- Mycotoxin management expertise:ANVISA and SENASA enforcement of aflatoxin and fumonisin limits demands specialized storage handling and rapid testing capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South American Maize Market |
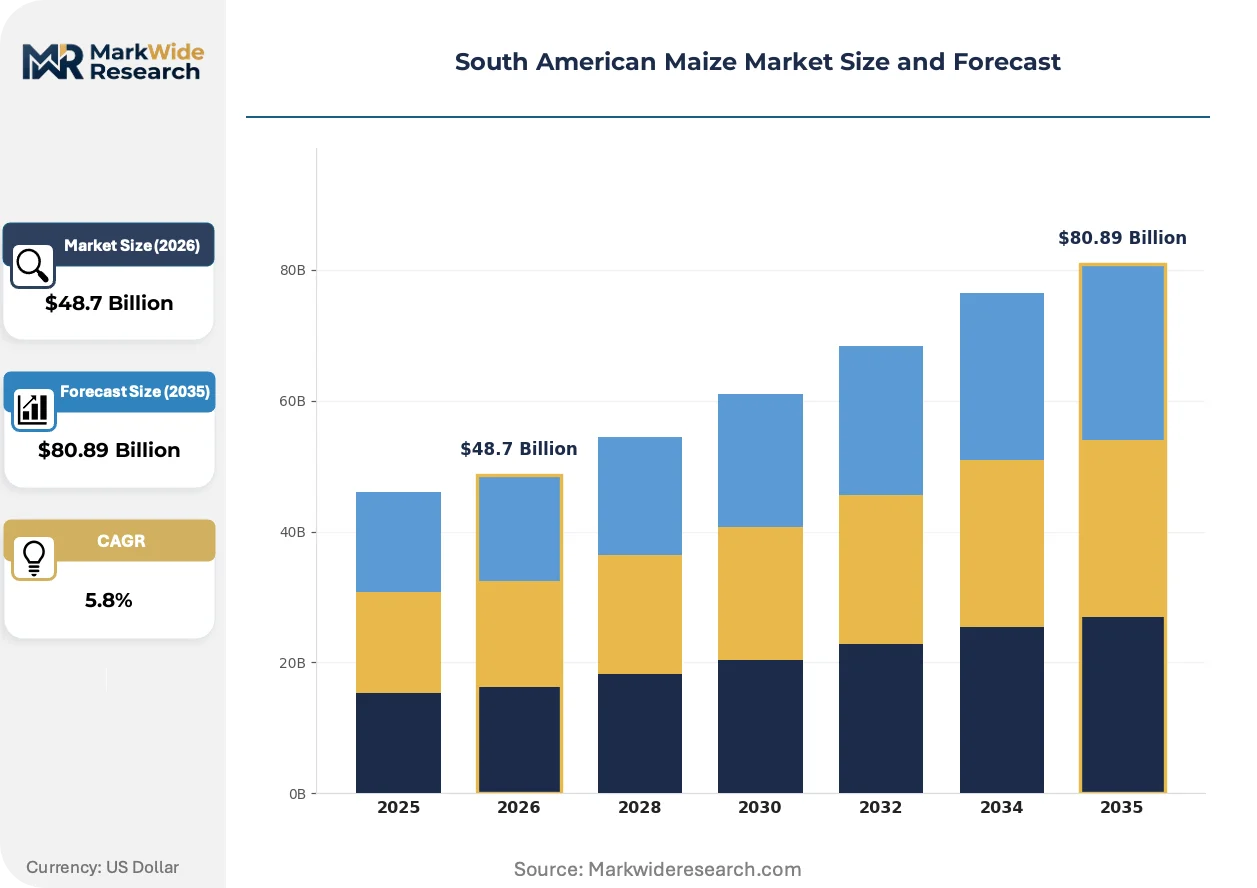
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $80.89 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sweet Maize, Field Maize, Flint Maize, Dent Maize End Use Industry: Food Processing, Animal Feed, Biofuel, Starch Production Distribution Channel: Wholesale, Retail, E-commerce, Direct Sales Grade: Organic, Non-GMO, Conventional, Hybrid |
| Companies Covered | Bunge Limited, Cargill, Inc., ADM, COFCO Corporation, Louis Dreyfus Company, Syngenta AG, Grupo La Caridad, AMAGGI, Olam International, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South American Maize Market Evolving Landscape
Digital traceability infrastructure and biotech trait pipelines are restructuring how South American maize moves from field to destination market. These forces are compressing traditional quality assurance timelines while opening premium capture for verified supply chains.
Gene editing platforms including CRISPR-Cas9 are accelerating drought-tolerance and pest-resistance trait development in Argentine breeding programs. Large-scale cooperatives and integrated processors are licensing these events for proprietary cultivar portfolios. The technology is bifurcating the seed market between biotech-enabled premium hybrids and conventional open-pollinated varieties serving cost-sensitive domestic feed channels.
Brazil's ANVISA and Argentina's SENASA are harmonizing mycotoxin sampling protocols under Mercosur technical regulations, reducing cross-border inspection redundancy. This alignment compresses export clearance timelines for dual-destination shipments. The regulatory convergence most benefits traders with integrated laboratory networks spanning both countries' major production belts.
Protein processors and feed compounders are consolidating procurement into annual volume contracts with origin-specific quality clauses, displacing spot-market purchasing. This contract concentration shifts price discovery power toward large-scale handlers with verified segregation capabilities. The behavioral shift is most pronounced in Brazil's southern states, where poultry integration density supports dedicated supply chain investments.
South American Maize Market Segmentation
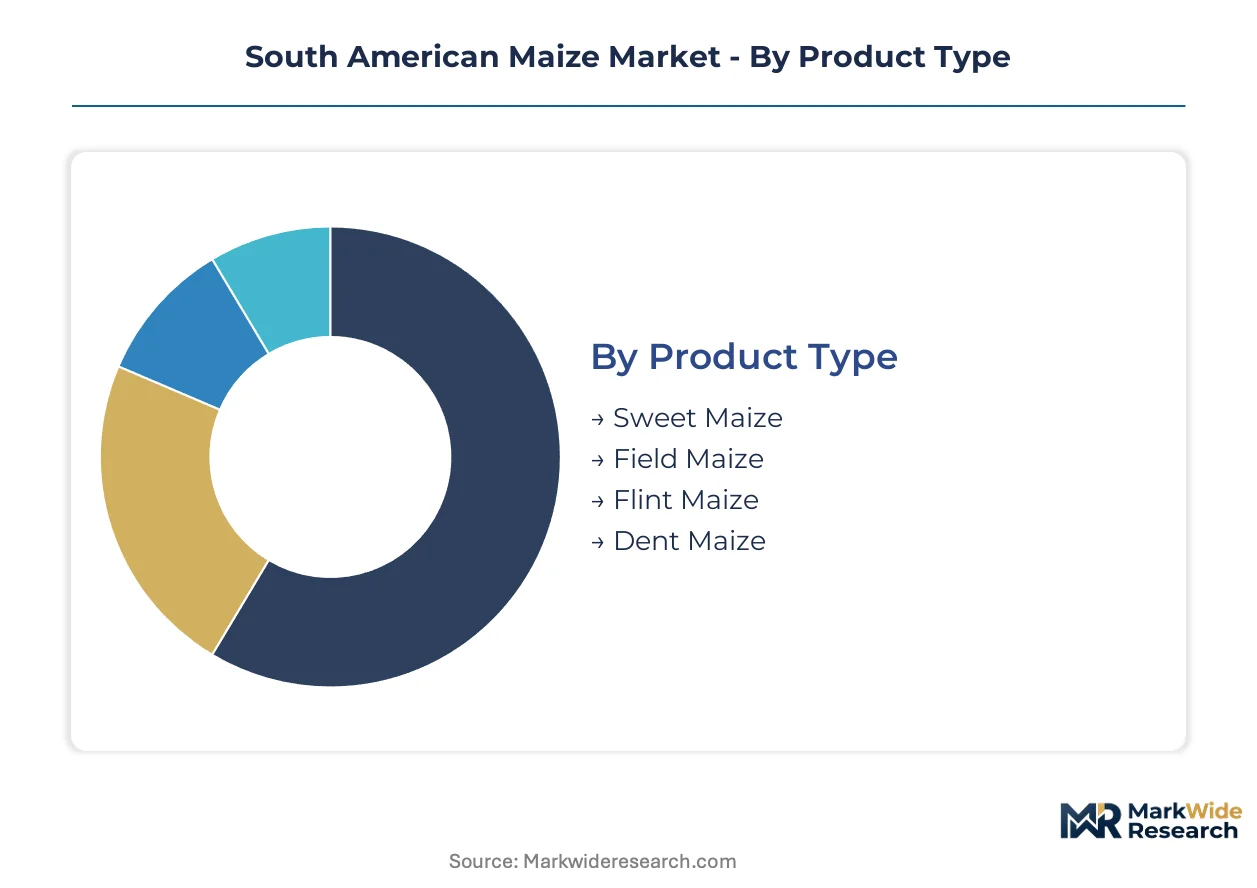
Maize segmentation in South America reflects divergent quality standards between export-facing and domestic consumption channels. Grade and product type distinctions determine compliance burdens, pricing tiers, and origination infrastructure requirements across Brazilian and Argentine supply networks.
Product Type:
Substitution pressure from alternative feed grains and sweeteners concentrates most intensely on field maize, where sorghum and soybean meal compete for formulation share in protein rations.
- Field Maize:High-starch Zea mays cultivars with hard endosperm structure dominate commercial volume flows. Poultry integrators in Brazil's southern states and pork processors in Santa Catarina anchor demand, though fertilizer cost volatility constrains planted area expansion in Mato Grosso's Center-West belt.
- Sweet Maize:Higher sugar content varieties harvested at immature kernel stage command fresh and frozen food premiums. Processing concentration in São Paulo state's canning facilities drives offtake, with export demand to European retail chains reinforcing quality certification investments.
- Flint Maize:Hard endosperm grain prized for alkaline cooking processes in traditional food applications.
- Dent Maize:Soft endosperm hybrid types optimized for mechanical harvesting and bulk commodity handling.
Field maize anchors the volume base while sweet maize gains share at the steepest rate.
End Use Industry:
Cost tier stratification separates capital-intensive industrial processing from fragmented agricultural consumption, with biofuel and starch channels demanding the most stringent quality specifications.
- Animal Feed:Compound feed manufacturers and integrated protein processors consume the majority of regional maize volume. Brazil's BR-163 corridor linking Mato Grosso farms to Santos port terminals supports dedicated feed-grade supply chains, though mycotoxin management requirements under ANVISA protocols elevate handling costs.
- Starch Production:Wet milling operations extract native and modified starches for food, paper, and textile applications. São Paulo state's industrial cluster concentrates capacity, with ethanol co-product streams capturing value from Brazilian biofuel blending mandates.
- Food Processing:Dry milling for grits, flour, and extruded products serves domestic consumption and export markets.
- Biofuel:Ethanol fermentation from maize starch competes with sugarcane feedstock in Brazilian renewable fuel programs.
Animal feed commands the dominant value share while starch production demonstrates the most rapid capacity expansion trajectory.
Distribution Channel:
Supply concentration in bulk commodity handling favors wholesale and direct sales channels, with retail and e-commerce penetration constrained by perishability and logistics economics.
- Wholesale:Grain elevators, cooperatives, and trading houses aggregate farm-level production into exportable parcels. Santos and Paranaguá port terminals handle the majority of wholesale volume, creating chokepoint vulnerability during peak harvest windows when silo capacity saturates.
- Direct Sales:Large-scale farming operations and cooperatives bypass intermediaries to supply crushing facilities and export terminals. Mato Grosso's integrated agricultural enterprises leverage this channel to capture origination premiums and reduce financing costs.
- Retail:Packaged maize products for human consumption reach consumers through supermarket chains.
- E-commerce:Digital platforms facilitate seed and input sales to farmers, with grain marketing platforms emerging for spot transactions.
Wholesale channels retain volume dominance while direct sales climb the fastest as farm consolidation accelerates.
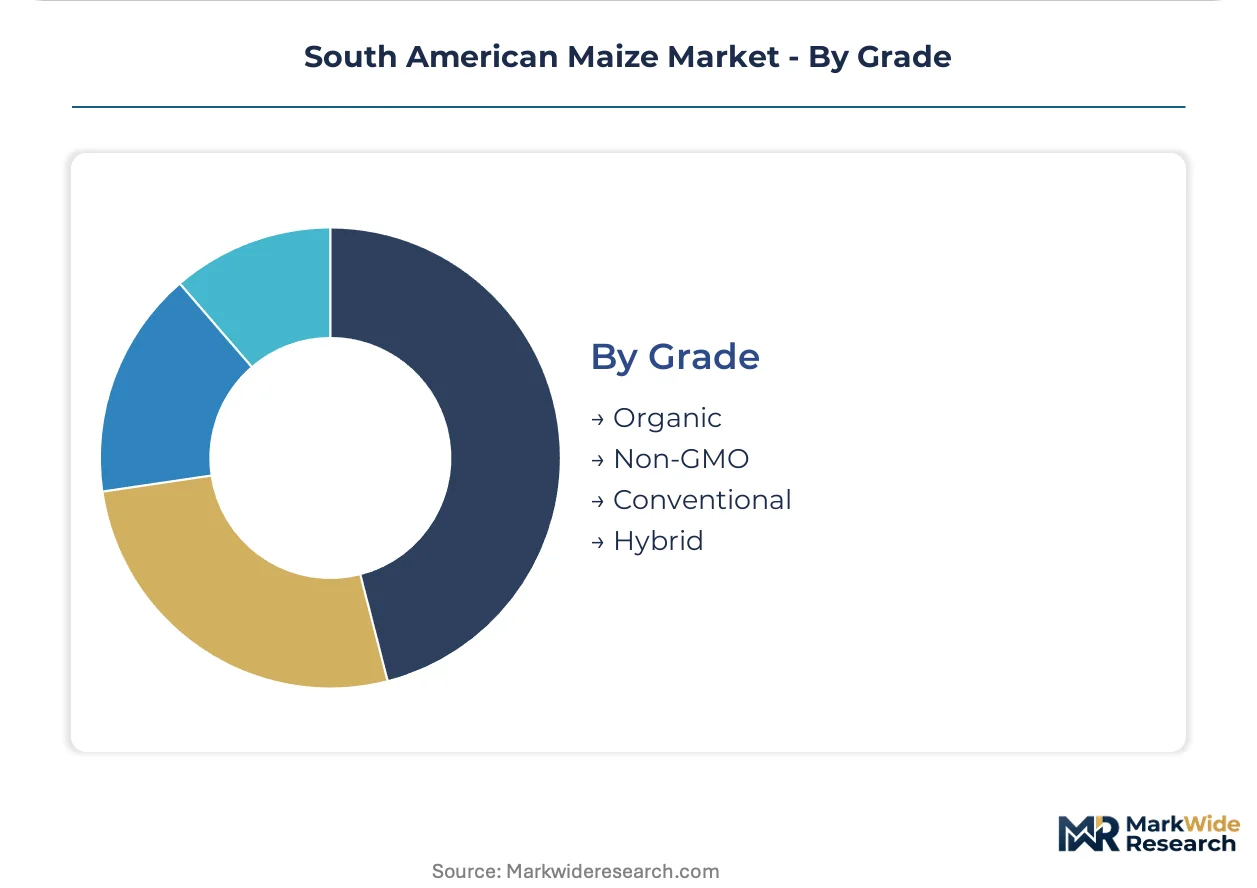
Grade:
Margin tier differentiation creates structural separation between certified premium streams and commodity bulk flows, with regulatory compliance costs filtering market participation.
- Non-GMO:Identity-preserved supply chains with genetic event testing and segregation protocols capture European and North American export premiums. SENASA certification requirements and EU deforestation-free traceability mandates elevate operational complexity for handlers across Argentine and Brazilian origination networks.
- Organic:Cultivation without synthetic inputs under third-party certification commands the steepest price premiums. Cerrado and Pampas regions with lower pest pressure support commercial organic production, though conversion timelines and buffer zone requirements constrain supply expansion.
- Conventional:Standard hybrid cultivars without specialty certification drive aggregate tonnage and terminal price discovery.
- Hybrid:Proprietary seed genetics optimized for yield, drought tolerance, and pest resistance dominate commercial plantings.
Conventional grades anchor the volume base while Non-GMO captures the steepest margin expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Santos-Paranaguá port complex on Brazil's southeastern coast anchors South American maize export capacity, handling the majority of regional grain shipments to Asian and European destinations. Rail corridors from Mato Grosso's Center-West production belt feed these terminals, creating a logistics backbone that shapes origination economics across the continent.
Brazil
Poultry integrators in Santa Catarina and pork processors in Rio Grande do Sul drive feed-grade demand through dedicated supply contracts. ANVISA enforces mycotoxin sampling protocols that elevate handling costs at Mato Grosso silo clusters. The BR-163 highway corridor linking Sorriso production zones to Santos terminals supports large-scale commercialization with expanding private elevator investments.
Argentina
Beef and dairy feedlot operations in Buenos Aires province sustain domestic consumption volumes alongside export-grade origination. SENASA phytosanitary certification tightening compresses eligible supply pools and forces quality infrastructure upgrades. Rosario's Paraná River port cluster concentrates crushing and export terminal capacity, with barge logistics integrating Pampas grain belts.
Paraguay
Land expansion potential in the Chaco and Eastern regions attracts crushing infrastructure investment from regional traders. The national agricultural regulator maintains biotech event registration timelines that lag Argentine and Brazilian approvals, creating asynchronous cultivar commercialization. Ciudad del Este processing zones leverage Itaipú electricity access for energy-intensive wet milling operations.
Uruguay
Integrated crop-livestock systems in Paysandú and Colonia departments generate rotational maize volumes for regional feed markets. Mercosur technical regulation alignment on GMO traceability reduces cross-border inspection friction with Argentine and Brazilian buyers. Montevideo's port terminal handles niche organic and non-GMO parcels for European specialty importers.
Bolivia
Santa Cruz lowland production supplies Andean highland poultry and swine operations through truck-based distribution networks. The national biosafety authority maintains cultivar approval processes that limit biotech hybrid penetration relative to neighboring markets. Cochabamba's feed manufacturing cluster processes imported Argentine grain alongside domestic origination.
South American Maize Market Competitive Landscape
Listed agribusiness majors compete with private trading houses and cooperative processors across origination, crushing, and export terminal assets. Market structure concentrates around integrated handlers with silo network density and port access, while specialist operators capture premiums in identity-preserved and organic segments. Three archetypes dominate: multinational traders with balance-sheet capacity, domestic cooperatives with farmer ownership ties, and seed-chemical integrators with proprietary genetics. Competitive dynamics center on backward integration into farm financing and forward positioning in destination market relationships.
Among the integrated trading archetype, Bunge Limited, Cargill, Inc., and ADM exemplify scale-driven origination and export infrastructure control. These entities anchor market liquidity through Center-West silo networks and deep-water terminal investments. Bunge represents the crushing-integrated model with oilseed-maize co-processing economics. Cargill exemplifies risk management and farmer financing program deployment. ADM occupies a position leveraging Asian destination relationships and biofuel corridor development. Specialist players including AMAGGI and Grupo La Caridad sit within the cooperative-processor tier, capturing origination premiums through farmer-aligned equity structures.
| Leading Market Players |
|---|
| Bunge Limited |
| Cargill, Inc. |
| ADM |
| COFCO Corporation |
| Louis Dreyfus Company |
| Syngenta AG |
| Grupo La Caridad |
| AMAGGI |
| Olam International |
| Others |
Value Network & Pricing Analysis
Long-term offtake contracts between Mato Grosso cooperatives and Brazilian poultry integrators lock in both supply access and price visibility across harvest cycles, insulating processors from spot-market volatility while committing origination networks to quality-tier investments. ANVISA mycotoxin enforcement and SENASA certification tightening add compliance cost layers that concentrate pricing power among handlers with integrated laboratory and geofencing capabilities.
Pricing Analysis
Volume-discount tiering structures separate large-scale annual contracts from spot-market transactions, with feed compounders capturing 5-10% price advantages on 50,000-tonne-plus commitments. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and segregation capability, with Non-GMO IP and organic handlers commanding margin capture in European export channels. Cost compression in conventional hybrid grades is intensifying because fertilizer price volatility squeezes farmer margins and constrains planted area expansion. Smallholder cooperatives in Paraguay and Bolivia exhibit highest price sensitivity, while integrated protein processors in Brazil's southern states prioritize supply security over unit cost.
Supply Chain Analysis
Strategic stockpile preferences dominate among Brazilian export handlers, who maintain 60-90 day silo buffers against port congestion during peak harvest windows. Supply concentration centers on Brazil, Argentina, and Paraguay, with the BR-163 corridor and Rosario Paraná River cluster anchoring origination gravity. Raw material dependencies rest on phosphate fertilizers, glyphosate formulations, and diesel fuel for mechanized harvesting operations. Single-source vulnerability runs through Santos and Paranaguá terminals, which handle disproportionate export volumes and create chokepoint exposure during weather-disrupted loading windows. Distribution runs through wholesale elevator networks and direct sales channels, with retail penetration constrained by bulk commodity economics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized expertise in geofenced origination and satellite-verified traceability is scarce relative to EU deforestation-free mandate requirements, creating a capability gap that filters market participation toward capital-integrated handlers.
For Market Incumbents: Shield origination dominance by deepening backward integration into Mato Grosso farm financing and silo infrastructure, while accelerating certification investments to capture Non-GMO IP premiums before SENASA tightening compresses eligible supply pools. Channel control through dedicated BR-163 corridor investments represents the critical defensive lever against trading house encroachment. For New Entrants and Emerging Players: Lead with underpenetrated Paraguayan origination, where land expansion potential and lower production costs attract crushing infrastructure investment absent entrenched incumbent density. The Chaco and Eastern regions offer the most penetrable geography, with wet milling capacity for Itaipú electricity access providing a differentiated go-to-market angle against commodity traders. For Investors and Strategic Acquirers: Capital is best deployed toward integrated handlers with silo network density and port terminal access, as these archetypes anchor market liquidity and capture origination premiums through the projection horizon. Acquisition targets should exhibit verified segregation capabilities and laboratory network span across Brazilian and Argentine production belts. The signal to watch is EU deforestation regulation enforcement intensity, which would accelerate consolidation pressure on fragmented supplier bases lacking polygon mapping infrastructure.| Strategic Initiative | Industry Significance |
|---|---|
| Geofenced Origination Investment | Satellite-verified supply chains satisfy EU deforestation-free mandates and unlock premium market access. |
| Wet Milling Capacity Expansion | Starch and ethanol extraction captures value from Brazilian biofuel blending mandate growth. |
| Long-term Supply Agreement | Annual volume contracts with quality clauses displace spot purchasing and shift price discovery power. |
| Laboratory Network Integration | ANVISA and SENASA mycotoxin protocol harmonization benefits handlers with cross-border testing infrastructure. |
| Carbon Credit Monetization Program | No-till farming protocols generate verified emissions reductions for compliance market participation. |
Research Methodology
Operator-level perspectives from grain elevator managers, port terminal operators, poultry procurement directors, and cooperative agronomists anchored the qualitative base for this study. Primary field engagement combined with secondary validation from MAPA grain inspection protocols, SENASA phytosanitary filings, Mercosur technical regulations, and customs/trade flow databases supported cross-reference integrity. Bottom-up origination volume modeling and top-down demand segmentation from feed compounders and wet mill operators were triangulated against trade statistics.
Sensitivity analysis tested forecast outputs against fertilizer price volatility scenarios, biotech event approval timeline variations, and EU regulatory enforcement intensity assumptions across the analysis window. Segmentation dimensions modeled include product type, end-use industry, distribution channel, and grade certification tier. CAGRs were derived from historical volume trajectories and demand elasticity parameters, with poultry sector scaling rates and ethanol blending mandate progression serving as key forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained Mercosur regulatory alignment or accelerated EU deforestation enforcement would require recalibration. Forecasts reflect documented assumptions regarding planted area expansion feasibility and port logistics capacity utilization. Revision becomes warranted when fertilizer cost volatility crosses thresholds that constrain Center-West farmer margins or when biotech registration delays extend cultivar commercialization cycles beyond modeled timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Grains
Soy Grits Market
Grains
Canada Pulses Market
Grains
Triticale Market
Grains
Ghana Grain Market
Grains
China Maize Market
Grains
Europe Wheat Protein Market
Grains
Global Grain Mill Products Market
Grains
Green Banana Flour Market
Grains
Corn Flour Market
Grains
Ancient and Specialty Grain Flour Market
Grains
India Rice Market
Grains
Non-Basmati Rice Market
Grains
Egypt Rice Market
Grains
Quinoa Flour Market
Grains
South Africa Grain Market
Grains
Guar Complex Market