
 Growing Peat Market | 2026-2036
Growing Peat Market Size, Share, and Industry Trends Forecast 2026-2036
Growing Peat Market Insights
Aftermarket soil amendment services is rewriting margin capture across the value chain. Neova Oy leverages its Nordic extraction base to sustain long-term supply contracts with greenhouse operators. Klasmann-Deilmann GmbH anchors its position through specialized propagation substrate formulations. Sun Gro Horticulture competes by controlling distribution depth across North American garden center networks.
Growing peat consists of partially decomposed sphagnum moss and organic matter harvested from acidic bog ecosystems, typically exhibiting pH ranges of 3.5 to 4.5 and water retention capacities exceeding ten times its dry weight. It serves primarily as a soilless growing medium and soil conditioner in commercial crop production. Milled peat dominates volume throughput due to mechanical harvest efficiency, while raised peat commands premium positioning in professional horticulture applications. Block peat retains structural integrity longer in greenhouse drip-irrigation systems, supporting its adoption among tomato and cucumber producers.
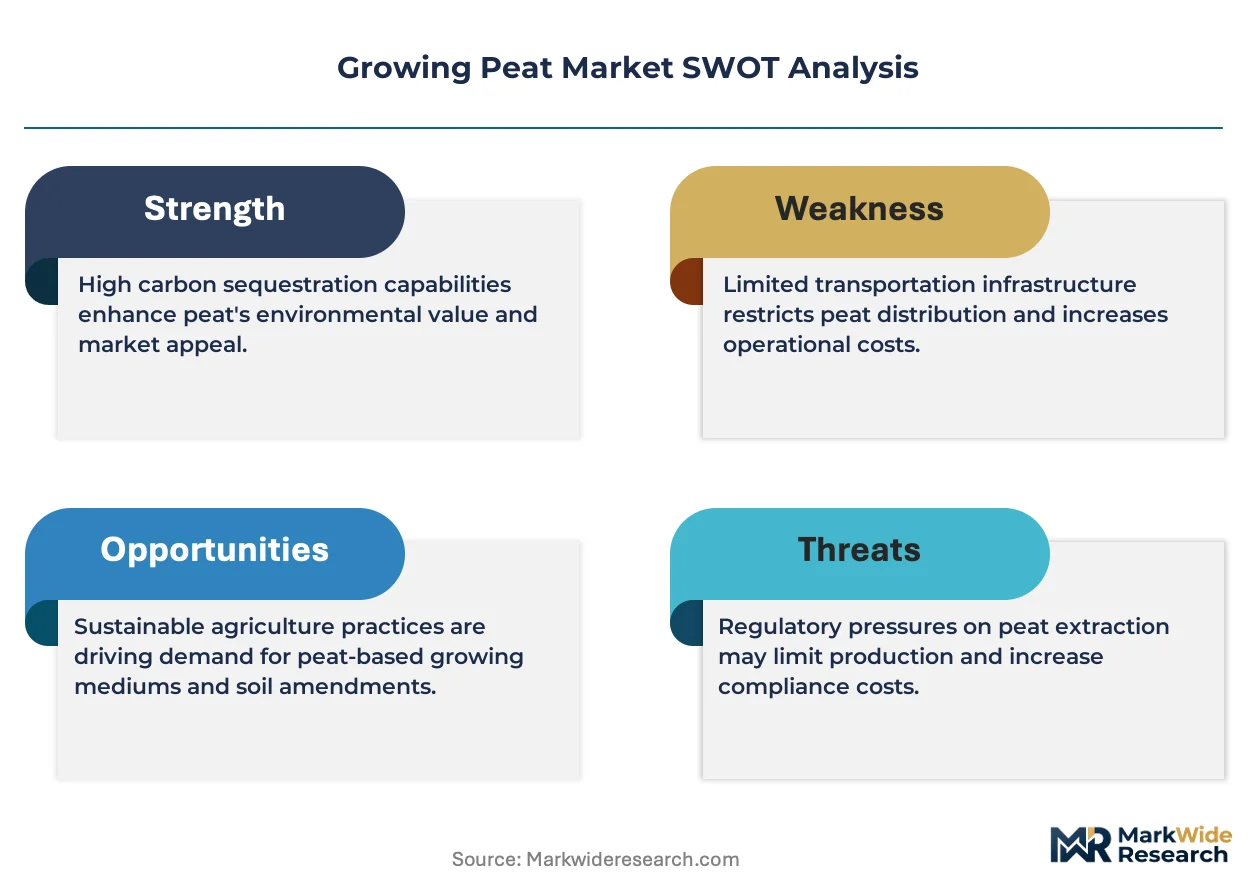
The EU's F-Gas Regulation and national peatland restoration mandates in Ireland and Finland constrain extraction licensing timelines, while BIS standards in India and EPA wetland protections in the United States shape import and domestic sourcing alternatives. Compliance with REACH substance restrictions and emerging carbon-border adjustment mechanisms will determine which suppliers retain market access. Stakeholders must monitor substitution technology maturation and regulatory enforcement intensity to calibrate capacity commitments.
Market Dynamics
EU peatland restoration mandates and carbon-border adjustment mechanisms are compressing extraction licensing timelines while accelerating substitution research investments across substrate formulators.
Growth Catalysts
- Controlled-environment agriculture expansion:Commercial greenhouse operators in the Netherlands and Spain are scaling peat-based propagation systems for year-round vegetable production.
- F-Gas Regulation compliance:The EU framework pressures substrate suppliers to document lifecycle emissions, favoring certified low-carbon peat sourcing from Baltic extraction zones.
- Block peat structural advantages:Tomato and cucumber producers prefer block peat for drip-irrigation longevity, driving premium grade demand.
Market Restraints
- Input cost volatility:Diesel and mechanical harvesting equipment prices fluctuate with energy markets, squeezing milled peat margin structures.
- Supply concentration risk:Estonia, Latvia, and Lithuania control accessible bog reserves, creating geographic single-point vulnerability for European substrate supply.
- Substitution threat:Coconut coir and wood fiber substrates are capturing share in amateur gardening segments where performance tolerance is wider.
Strategic Opportunities
- Underpenetrated professional horticulture:Poland and Romania greenhouse sectors remain below Western European peat intensity per hectare.
- Regulatory tailwind:Ireland's national peatland restoration mandate creates restoration-services revenue streams for extraction contractors pivoting to rehabilitation.
- Distribution innovation:Direct-to-grower substrate blending stations bypass traditional garden center markups in Nordic markets.
Industry Challenges
- Capex intensity for carbon capture retrofit:Extraction sites require drainage rewetting infrastructure to meet emerging carbon accounting standards.
- Certification timeline compression:REACH substance documentation and emerging eco-label requirements demand extended product testing cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Growing Peat Market |
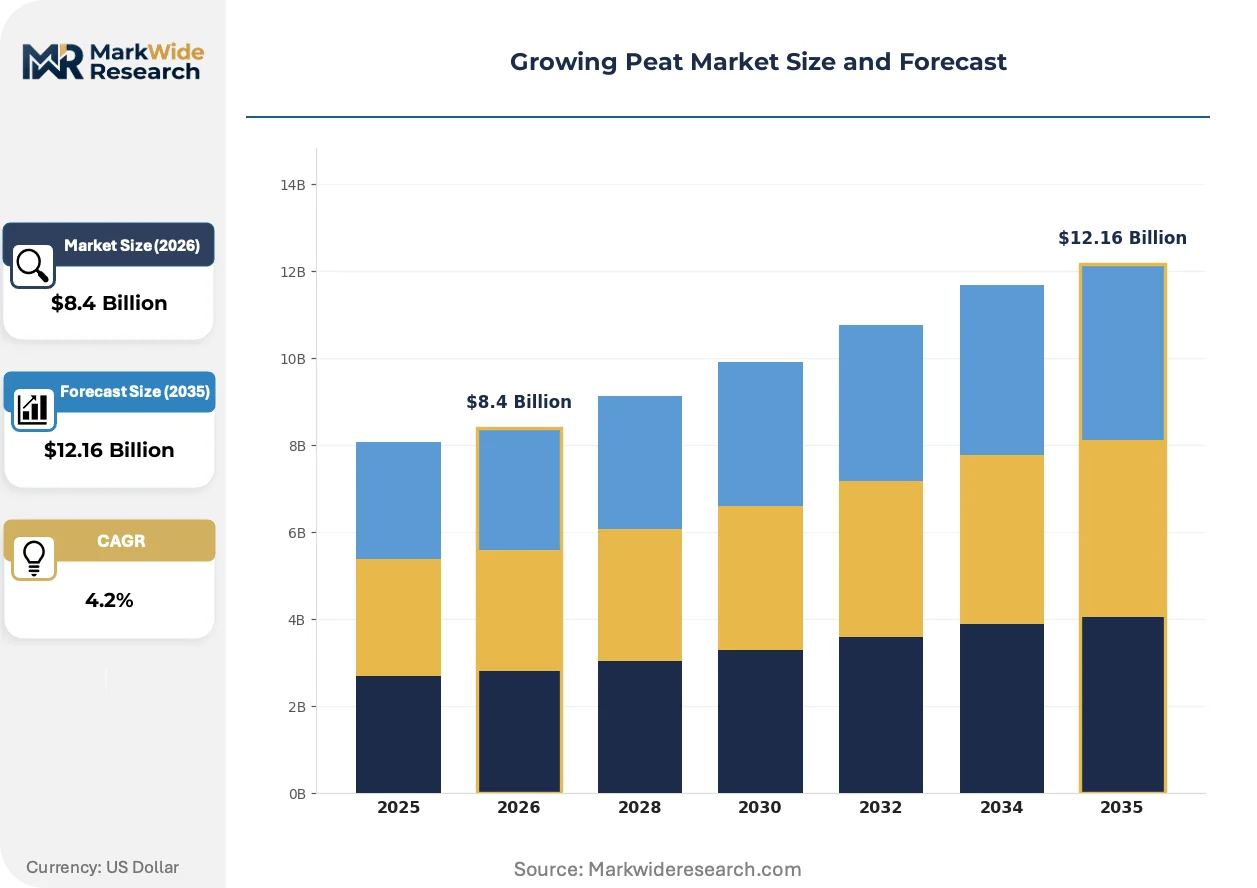
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $12.16 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Raised Peat, Block Peat, Milled Peat, Warm Peat Application: Horticulture, Agriculture, Greenhouses, Landscaping End User: Commercial Growers, Home Gardeners, Municipalities, Landscape Architects Distribution Channel: Online Retail, Garden Centers, Wholesale Distributors, Supermarkets |
| Companies Covered | Neova Oy, AB Rėkyva, Lambert Peat Moss, Berger Peat Moss Ltd., Premier Tech Ltd., Sun Gro Horticulture, Bord na Mona, Mikskaar, Klasmann-Deilmann GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Growing Peat Market Trends and Innovations
Substrate chemistry and regulatory compliance frameworks are converging to redefine product specifications and sourcing protocols across professional horticulture supply chains.
Precision-blended peat-coir formulations is migrating from experimental trials to standard propagation protocols. Large-scale tomato propagators in Almeria and Dutch glasshouse clusters are adopting these mixes at accelerating rates. This migration from single-source substrates is compressing traditional commodity peat margins while rewarding formulation IP.
The EU F-Gas Regulation and national carbon accounting frameworks are tightening extraction licensing and import documentation requirements. Industrial peat processors must now verify bogland carbon stocks and restoration commitments to maintain market access. Professional horticulture buyers in Germany and France are prioritizing suppliers with verified low-emission certification chains.
Amateur gardening purchasers are consolidating toward private-label substrate offerings through home improvement retail channels. Traditional branded peat products are losing shelf space to retailer-controlled labels with simplified grade specifications. This consolidation is most visible in UK and French garden center networks where price transparency has compressed brand loyalty.
Growing Peat Market Segmentation
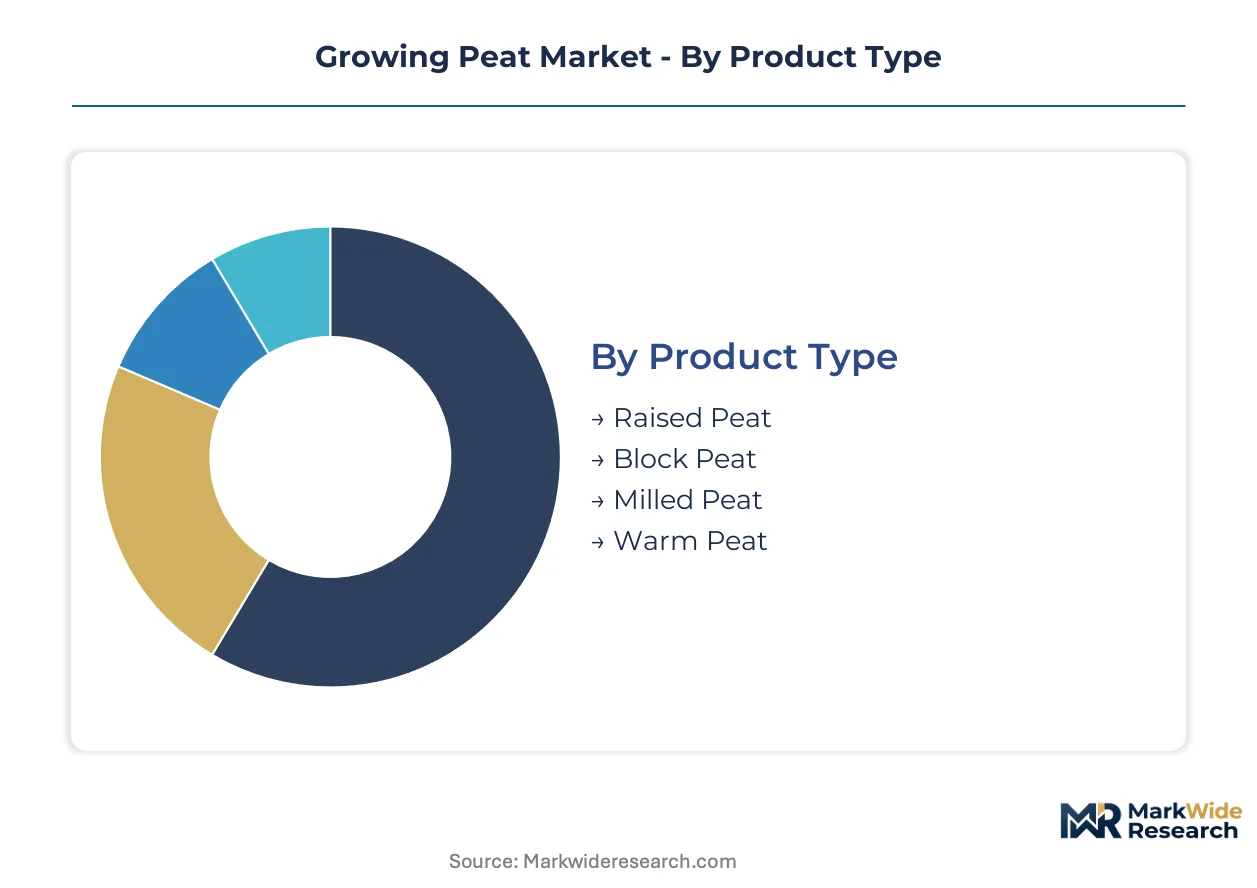
Peat substrate procurement cycles vary dramatically across product grades and buyer categories, with professional horticulture operators turning inventory weekly while municipal landscaping contracts stretch across seasons. Understanding these velocity differentials enables suppliers to calibrate production scheduling and margin capture strategies.
Product Type:
Milled peat turns over fastest through bulk commodity channels, while block peat sits longest in greenhouse irrigation systems before replacement.
- Milled Peat:Mechanically shredded and dried material harvested from surface layers enables rapid field processing and bulk transport. Dutch glasshouse clusters and Spanish Almeria propagators consume milled peat in continuous propagation cycles, though diesel price volatility squeezes per-ton margins.
- Block Peat:Compressed slabs retain structural integrity through multiple drip-irrigation seasons, supporting tomato and cucumber producer preference. Tomato propagators in the Netherlands specify block peat for longevity in hydroponic systems, commanding premium pricing over loose grades.
- Raised Peat:Hand-cut sod harvested from deeper bog layers serves specialized professional horticulture formulations requiring precise air-water ratios.
- Warm Peat:Partially decomposed material from lower bog profiles suits soil conditioning applications where structural stability matters less than organic content.
Milled peat anchors the volume base while block peat gains share at the steepest rate.
Application:
Cost tiering separates propagation-grade substrates from bulk landscaping material, with greenhouse operators paying triple per cubic meter what municipal buyers accept.
- Greenhouses:Controlled-environment agriculture demands precisely calibrated pH and porosity specifications. Netherlands and Spanish commercial operators specify peat-coir blends for year-round vegetable propagation, driving formulation complexity.
- Horticulture:Nursery stock and ornamental production requires consistent substrate chemistry across seasonal cycles. Baltic suppliers serve German and French nursery networks through long-term supply agreements.
- Agriculture:Field crop amendment applications prioritize cost efficiency over precision specifications, exposing this segment to coconut coir substitution.
- Landscaping:Large-scale turf establishment and soil remediation projects consume volume grades with wider tolerance bands.
Greenhouse applications command the highest per-unit margins while landscaping absorbs volume at the lowest price tier.
End User:
Customer sophistication spans from laboratory-grade propagation protocols to seasonal home gardener impulse purchases.
- Commercial Growers:Professional greenhouse operators negotiate annual contracts with certified carbon documentation. Dutch tomato propagators and Spanish pepper producers specify low-emission peat chains to satisfy retailer sustainability requirements.
- Landscape Architects:Specification-driven procurement for commercial and public projects demands consistent quality documentation and project-scale logistics.
- Home Gardeners:Price-sensitive seasonal purchasers increasingly consolidate toward private-label substrate offerings through home improvement retail channels.
- Municipalities:Public procurement cycles and restoration project budgets constrain pricing flexibility despite volume potential.
Commercial growers drive premium-grade innovation while home gardeners shift fastest toward substitute substrates.
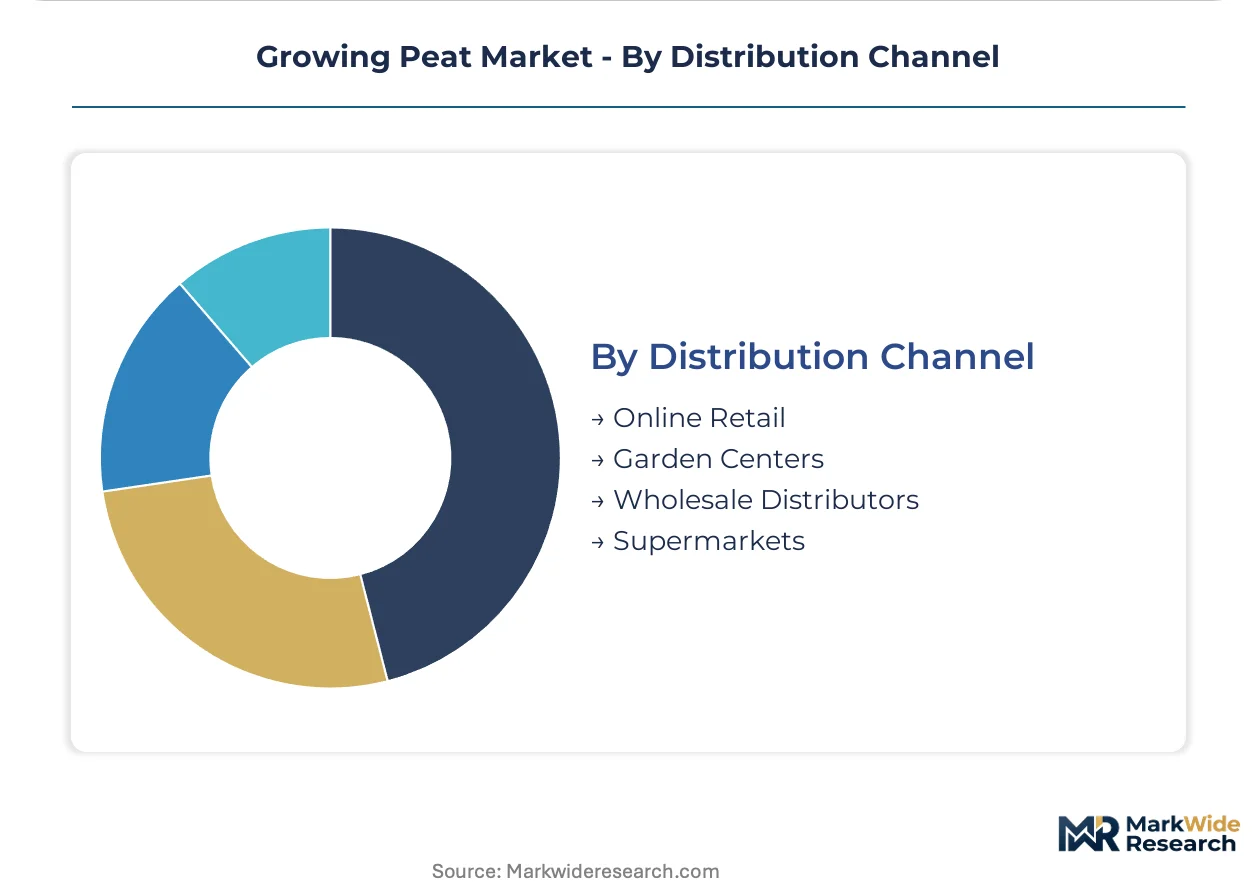
Distribution Channel:
Channel concentration in the Baltic extraction zone creates geographic vulnerability for European substrate supply.
- Wholesale Distributors:Bulk logistics networks from Estonian, Latvian, and Lithuanian bogs supply industrial-scale greenhouse operators. Concentrated bog reserve access in these three states creates single-point supply risk for continental European propagation capacity.
- Garden Centers:Traditional retail channels face shelf-space compression from private-label consolidation in UK and French networks.
- Online Retail:Direct-to-grower substrate blending stations in Nordic markets bypass traditional markup structures.
- Supermarkets:Mass-market seasonal displays capture amateur gardening volume with simplified grade specifications and aggressive price positioning.
Wholesale distributors control professional horticulture volume while online retail expands fastest among direct-to-grower innovators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across the Growing Peat Market. Amateur gardeners in France and the UK resist premium grades, while Dutch greenhouse operators absorb triple the per-cubic-meter cost for certified low-carbon propagation substrates.
Netherlands
Commercial tomato and cucumber propagators in Westland and Aalsmeer drive premium block peat consumption. The EU F-Gas Regulation pressures Dutch buyers to document lifecycle emissions, favoring certified Baltic supply chains. Rotterdam logistics hubs consolidate bulk substrate imports for redistribution across continental greenhouse clusters.
Germany
German nursery networks and glasshouse operators in Lower Saxony and Bavaria specify precisely calibrated pH substrates for ornamental propagation. REACH substance documentation requirements compress certification timelines for imported peat products. The Rhine-Ruhr corridor hosts formulation blending facilities serving professional horticulture buyers.
Spain
Almeria's concentrated greenhouse belt consumes peat-coir blends for year-round vegetable production. Spanish operators prioritize drip-irrigation longevity, driving block peat specification. Barcelona and Valencia distribution centers channel Baltic-sourced material into Mediterranean propagation operations.
Estonia
Industrial peat extraction concentrates in Ida-Viru and Tartu counties, supplying milled grades to continental European bulk buyers. Estonian bog reserves face carbon-border adjustment mechanism scrutiny, accelerating restoration commitment documentation. Tallinn ports handle volume exports to German and Dutch wholesale distributors.
Ireland
Bord na Mona operates remaining licensed extraction sites amid national peatland restoration mandates. Irish policy frameworks constrain new harvesting permits while creating rehabilitation-services revenue streams. The Midlands bog region transitions from active extraction to rewetting infrastructure deployment.
Growing Peat Market Competitive Landscape
Integrated extraction-to-formulation operators and specialized substrate blenders split the market along vertical scope lines. Baltic-based bog owners leverage reserve access for long-term supply contract security. Western European formulators compete on propagation-specific IP and certified carbon documentation. Capacity commitments and certification chain investments represent the dominant competitive moves as regulatory timelines compress.
Within the Nordic extraction tier, Neova Oy and Mikskaar exemplify reserve-based supply security. Klasmann-Deilmann GmbH occupies a position among German formulation specialists emphasizing propagation-grade precision. Sun Gro Horticulture anchors North American distribution depth across garden center networks. These three represent divergent strategic archetypes: captive resource control, formulation IP, and channel concentration.
| Leading Market Players |
|---|
| Neova Oy |
| AB Rėkyva |
| Lambert Peat Moss |
| Berger Peat Moss Ltd. |
| Premier Tech Ltd. |
| Sun Gro Horticulture |
| Bord na Mona |
| Mikskaar |
| Klasmann-Deilmann GmbH |
| Others |
Pricing and Supply Chain Analysis
Single-source dependency on Baltic bog reserves determines both pricing tier spreads and supply chain shape across the European substrate market. Buyers in the Netherlands and Germany absorb premium differentials for certified low-carbon chains while facing concentrated supply vulnerability from Estonian, Latvian, and Lithuanian extraction zones.
Pricing Analysis
Aftermarket soil amendment services drive lifetime value through multi-year propagation support contracts rather than transactional substrate sales. Three-tier pricing structure across premium, standard, and economy levels separates certified block peat for Dutch tomato propagators from bulk milled grades for municipal landscaping. Cost compression in economy tiers is intensifying because coconut coir substitution captures amateur gardening share. Commercial greenhouse operators exhibit lowest price sensitivity, while home gardeners consolidate toward private-label offerings through French and UK retail channels.
Supply Chain Analysis
Contract manufacturing concentration among Neova Oy, Klasmann-Deilmann GmbH, and Sun Gro Horticulture controls formulation capacity and certified carbon documentation. Supply concentrates in Estonia, Latvia, and Lithuania for raw peat extraction, with Germany and the Netherlands hosting downstream blending operations. Raw material dependencies include sphagnum moss reserves, diesel for mechanical harvesting, and coir fiber for precision-blended formulations. Single-source vulnerability from Baltic bog concentration creates geographic chokepoint exposure. Distribution runs through Rotterdam and Tallinn port hubs into continental European greenhouse clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Substitution defense defines strategic priority as coconut coir and wood fiber substrates capture amateur gardening segments. Incumbents must navigate performance tolerance gaps between professional horticulture requirements and mass-market alternatives.
For Market Incumbents: Build certification moats through verified low-carbon supply chains and REACH documentation depth. Secure long-term extraction licenses in Baltic zones before carbon-border adjustment mechanisms tighten licensing timelines. Invest in precision-blending IP for peat-coir formulations that resist pure-substitute displacement in Dutch and Spanish greenhouse operations.
For New Entrants and Emerging Players: Establish a beachhead in Poland and Romania greenhouse sectors where peat intensity per hectare remains below Western European levels. Target direct-to-grower substrate blending stations in Nordic markets to bypass traditional garden center markups. Lead with restoration-services positioning in Ireland where national peatland mandates create rehabilitation revenue streams for extraction contractors.
For Investors and Strategic Acquirers: EU F-Gas Regulation reshapes the acquisition landscape by privileging suppliers with documented carbon-stock verification and restoration commitments. Long-term viability favors integrated extraction-to-formulation operators over pure-play commodity harvesters. Watch substitution technology maturation in professional horticulture as the inflection signal for core market erosion.
| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Certification Investment | REACH and EU F-Gas Regulation compliance secures market access for Baltic-sourced material. |
| Precision-Blending Capacity Expansion | Peat-coir formulation IP captures margin from Dutch tomato propagators in Almeria and Westland. |
| Restoration Services Pivot | Ireland's national peatland mandate converts extraction contractors into rehabilitation infrastructure deployers. |
| Direct-to-Grower Distribution | Online substrate blending stations in Nordic markets bypass garden center markup compression. |
| Backward Integration into Bog Reserves | Captive supply from Estonian and Latvian extraction zones insulates long-term contract security. |
Research Methodology
The analysis maps milled peat, block peat, raised peat, and warm peat sub-sectors, each validated through greenhouse operators, substrate formulators, and extraction site managers. Primary interviews with Dutch tomato propagators, German nursery network procurement leads, and Baltic extraction contractors combined with secondary validation from EU F-Gas Regulation filings, national peatland restoration mandates, and customs trade data. Bottom-up volume modeling and top-down value triangulation anchored segmentation outputs.
Assumptions held fixed include EU carbon-border adjustment mechanism enforcement intensity and professional horticulture substitution tolerance thresholds, while energy price volatility and coir fiber supply expansion were varied across scenarios. Segmentation dimensions modeled encompass product grade, application intensity, end-user sophistication, and distribution channel concentration. CAGRs were derived from growth driver elasticity analysis calibrated against historical propagation cycle expansion rates and regulatory timeline compression effects.
Stress conditions across diesel price volatility, restoration mandate acceleration, and coir substitution penetration were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory enforcement pacing and technology maturation curves. Quarterly review of substitution share in amateur gardening segments and Baltic extraction licensing grant rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Commodities
Soybean Derivatives Market
Agricultural Commodities
Cattle Feed Market
Agricultural Commodities
Castor Oil Market
Agricultural Commodities
Astrocaryum Murumuru Seed Butter Market
Agricultural Commodities
Global Wood Chips Market
Agricultural Commodities
Roundwood Market
Agricultural Commodities
South America Feed Premix Market
Agricultural Commodities
Middle East Feed Amino Acids Market
Agricultural Commodities
Alfalfa Powder Market
Agricultural Commodities
Sod Peat Market
Agricultural Commodities
Marine Powder Market
Agricultural Commodities
Corn and Corn Starch Derivatives Market
Agricultural Commodities
Feed Sucrose Market
Agricultural Commodities
Feed Yeast Market
Agricultural Commodities
Artificial Fishing Baits Market
Agricultural Commodities
Vietnam Feed Concentrate and Basemix Market