
 Feed Sucrose Market | 2026-2036
Feed Sucrose Market Size, Share, and Industry Trends Forecast 2026-2036
Feed Sucrose Market Analytics
Consolidation among integrated livestock processors is recalibrating procurement volumes and contract structures for feed-grade sucrose. Cargill Incorporated leverages its North American grain-sweetener logistics network to bundle sucrose with amino acid premixes. Südzucker AG anchors European supply through beet-derived feed sucrose streams co-located with bioethanol assets. Mitr Phol Group dominates Southeast Asian origination via Thai mill complexes that directly supply aquaculture feed compounders.
Feed sucrose denotes purified crystalline or liquid saccharose refined to specified ash and moisture tolerances for non-human consumption, typically registering minimum polarimetric purity of 99.5 percent and serving as a rapid-digestibility carbohydrate source in formulated animal diets. Granulated sucrose leads volume in ruminant TMR applications where free-flowing properties reduce mixer segregation, while liquid sucrose gains fastest uptake in automated poultry drinking systems that demand precise viscosity control. Powdered sucrose occupies premium positioning within milk replacer formulations where instantized dissolution protects calf gut integrity.
The EPA regulates feed sucrose under the Federal Food, Drug, and Cosmetic Act when cross-contamination risks trigger medicated feed compliance, while the EU F-Gas Regulation constrains refining energy profiles through fluorinated gas phase-out mandates. Brazil's ANVISA and Thailand's FDA-equivalent national food and drug administration both enforce import residue thresholds that shape export-oriented quality specifications. Stakeholders must monitor evolving carbon border adjustment mechanisms and alternative carbohydrate substitutes that could restructure sucrose's cost position in energy ration formulations.
Market Dynamics
Integrated livestock processors in Brazil and Thailand are consolidating procurement volumes, forcing feed-grade sucrose suppliers toward long-term offtake contracts with embedded carbon accounting clauses tied to EU F-Gas Regulation compliance.
Growth Catalysts
- EU F-Gas Regulation phase-out mandates:Refiners investing in fluorinated gas-free crystallization lines capture premium positioning in European feed compounder networks.
- Aquaculture feed expansion:Thai mill complexes serving shrimp and finfish operations are driving liquid sucrose uptake for automated delivery systems.
- São Paulo cane clustering:Proximity between crushing facilities and integrated livestock processors compresses logistics costs for energy-dense rations.
Market Restraints
- Beet molasses substitution:Ruminant feed compounders in temperate zones are reformulating toward lower-cost carbohydrate alternatives during sucrose price spikes.
- Single-origin supply risk:Thailand's central plains concentrate over half of Southeast Asian feed sucrose origination, exposing buyers to monsoon-driven crush variability.
- Carbon border adjustment exposure:Brazilian exporters face accumulating scope-three liability under forthcoming EU CBAM implementation for agricultural inputs.
Strategic Opportunities
- Indian dairy sector penetration:Crossbred cattle operations in Gujarat and Maharashtra remain underpenetrated by instantized milk replacer formulations.
- Precision fermentation feedstocks:Sucrose refiners co-locating with cellular agriculture facilities can pivot crystalline output toward microbial growth media.
- Renewable diesel co-location:Beet processors in France and Germany are repurposing idle bioethanol infrastructure for feed sucrose streams serving integrated protein producers.
Industry Challenges
- ANVISA residue testing timelines:Brazilian export batches face extended clearance cycles at Thailand's FDA-equivalent border facilities.
- Mixer segregation engineering:Free-flowing granulated grades require reformulation when humidity conditions compromise TMR uniformity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Feed Sucrose Market |
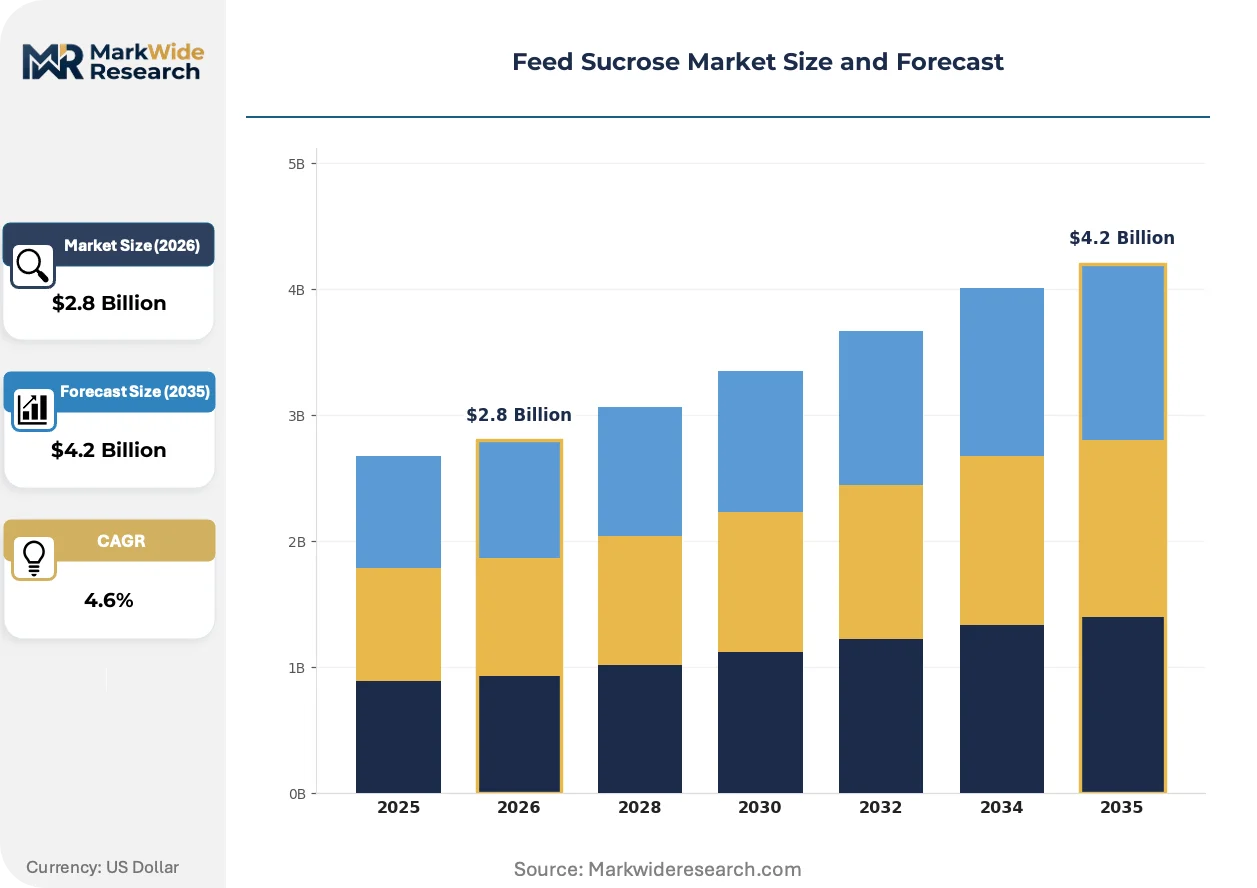
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.2 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granulated Sucrose, Liquid Sucrose, Powdered Sucrose, Brown Sugar Application: Livestock Feed, Poultry Nutrition, Aquaculture, Pet Food End User: Feed Manufacturers, Agriculture Producers, Livestock Owners, Aquaculture Farms Distribution Channel: Online Retail, Direct Sales, Wholesalers, Distributors |
| Companies Covered | Südzucker AG, Cargill Incorporated, Associated British Foods plc, Tereos, Raizen, Mitr Phol Group, Louis Dreyfus Company, ASR Group, Tate & Lyle PLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Feed Sucrose Market Evolving Landscape
Membrane filtration and enzymatic refining are compressing energy intensity in cane processing, while digital procurement platforms restructure how livestock processors contract carbohydrate inputs.
Membrane filtration technology is absorbing thermal energy previously consumed by traditional evaporative stages. Brazilian mill operators deploying ceramic nanofiltration modules report crystallization efficiency gains that translate directly to carbon intensity reductions. Aquaculture feed compounders sourcing from these retrofitted facilities are absorbing certified-low-carbon sucrose into their scope-three reporting frameworks.
The EU F-Gas Regulation is mandating complete phase-out of hydrofluorocarbon-based refrigeration in beet refining by 2030. German and French processors are retrofitting absorption heat pump systems that extract waste energy from adjacent bioethanol distillation. Livestock feed manufacturers purchasing from these facilities face compressed certification timelines but gain preferential access to sustainability-linked credit facilities.
Livestock processors are consolidating carbohydrate procurement through integrated commodity platforms that bundle sucrose with amino acid premixes and lipid supplements. Traditional spot-market purchasing through sugar brokers is contracting in favor of multi-year offtake agreements with embedded price collars. This behavioral shift is most visible across North American cattle feeding operations and Southeast Asian aquaculture integrators seeking input cost predictability.
Feed Sucrose Market Segmentation
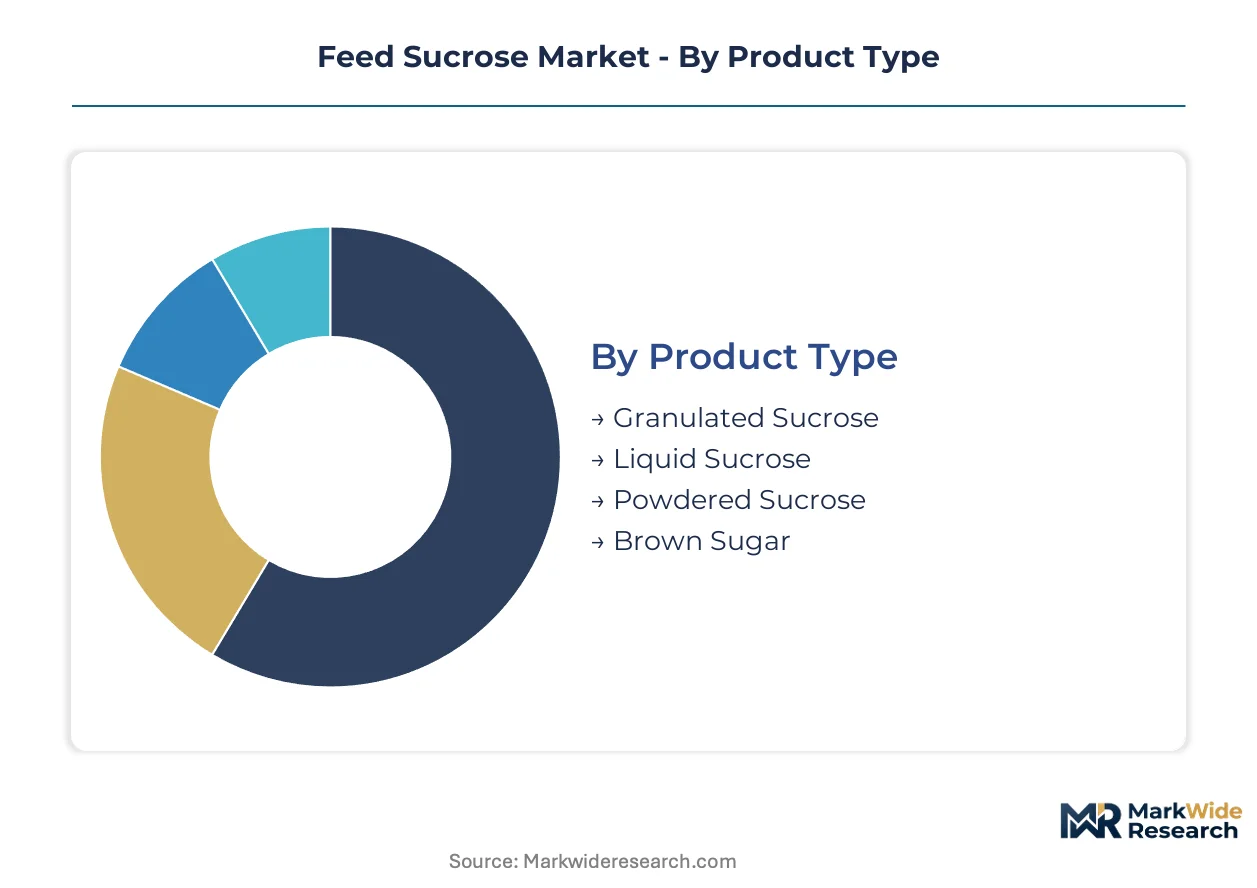
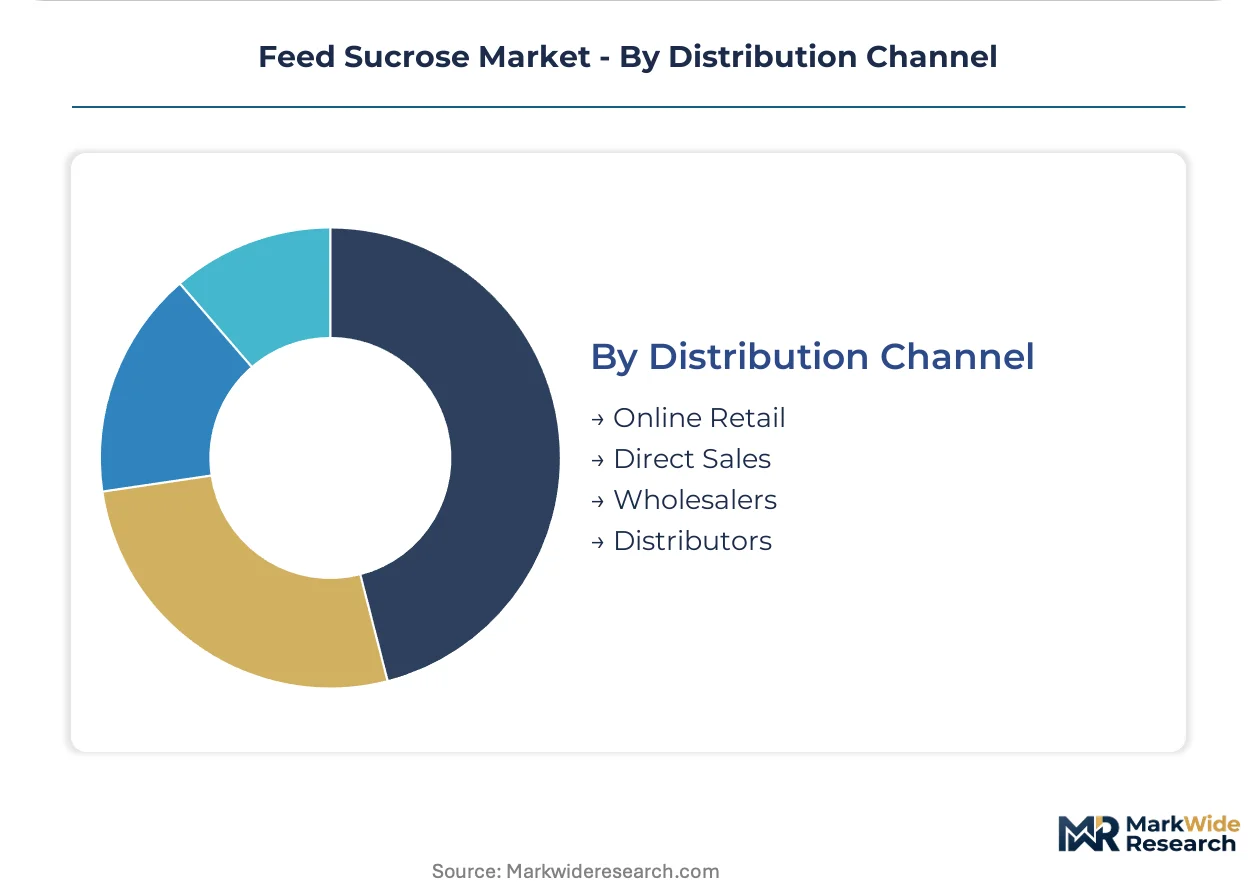
Feed sucrose procurement patterns diverge sharply across physical forms, end-use specifications, and channel structures. Buyers optimize crystalline geometry, moisture content, and logistics configuration against species-specific digestive requirements and automated system compatibility.
Product Type:
Crystalline structure and moisture tolerance define handling economics and metabolic availability across species.
- Granulated Sucrose:Free-flowing crystals with specified particle size distribution minimize segregation in total mixed rations. Brazilian cattle feeding operations in São Paulo state specify this grade for mechanical mixing systems where humidity-stable flow properties protect ration uniformity.
- Liquid Sucrose:Invert syrup solutions with controlled viscosity enable precision dosing in automated drinking lines. Thai shrimp aquaculture integrators are absorbing expanding volumes for continuous delivery systems that demand pumpable consistency.
- Powdered Sucrose:Instantized fine crystals protect gut integrity in neonatal milk replacers. Indian dairy operations in Gujarat remain underpenetrated by this specification.
- Brown Sugar:Molasses-retained sucrose carries elevated mineral content suitable for mineral-deficient forage regions. Southeast Asian smallholder ruminant operations specify this grade for cost-sensitive energy supplementation.
Mature deployment sits with granulated grades. Newer deployment is concentrated in liquid systems for aquaculture automation.
Application:
Species-specific digestive physiology and production intensity determine carbohydrate specification and inclusion rates.
- Livestock Feed:Ruminant operations leverage sucrose for rapid rumen fermentable energy that spares protein for tissue deposition. Brazilian integrated processors specify high-purity crystalline grades for feedlot finishing rations where starch-sucrose blends optimize gain efficiency.
- Aquaculture:Finfish and crustacean formulations require low-ash sucrose to protect osmotic balance in saline environments. Thai central plains mill complexes are retrofitting dedicated liquid sucrose lines for shrimp feed compounders.
- Poultry Nutrition:Broiler and layer operations utilize sucrose for palatability enhancement and rapid energy mobilization during heat stress periods. Automated drinking system penetration is climbing fastest in this segment.
- Pet Food:Premium extruded formulations specify low-moisture sucrose for texture binding and palatability modulation. North American specialty manufacturers drive specification development for glycemic-sensitive companion animal diets.
Volume concentration rests with livestock feed. Steepest expansion trajectory belongs to aquaculture applications.
End User:
Scale and integration level determine procurement sophistication and contract structure preferences.
- Feed Manufacturers:Integrated compounders with captive milling capacity negotiate multi-year offtake agreements with embedded carbon accounting clauses. Southeast Asian aquaculture integrators are consolidating procurement through bundled amino acid-carbohydrate platforms.
- Agriculture Producers:Cooperative and estate-level operations with on-farm mixing specify bulk granulated delivery. Brazilian sugarcane estates with integrated cattle operations compress logistics through direct mill-to-feedlot transfer.
- Livestock Owners:Small-to-mid scale operations purchase through distributor channels with spot-price exposure. Reformulation toward beet molasses substitutes accelerates during sucrose price spikes.
- Aquaculture Farms:Intensive pond and recirculating system operators demand certified-low-carbon liquid sucrose for scope-three reporting frameworks. Thai FDA-equivalent residue thresholds shape import-oriented quality specifications.
Contract sophistication concentrates with feed manufacturers. Spot-market exposure persists among livestock owners.
Distribution Channel:
Channel selection reflects shipment scale, urgency tolerance, and technical service requirements.
- Direct Sales:Large-volume integrated processors contract directly with refinery assets for dedicated stream allocation. Cargill's North American network bundles sucrose with amino acid premixes through this channel.
- Distributors:Regional carbohydrate specialists inventory multiple physical grades for just-in-time delivery to mid-scale compounders. Brazilian ANVISA residue testing timelines create clearance cycle variability.
- Wholesalers:Bulk commodity aggregators serve price-sensitive reformulators with standard-grade crystalline sucrose. Spot-market liquidity concentrates through this channel during harvest crush windows.
- Online Retail:Digital procurement platforms emerging for smallholder operations and specialty pet food formulators. Limited penetration reflects bulk shipment economics and moisture-sensitive handling requirements.
Volume concentration sits with direct sales. Platform-based procurement is expanding fastest among small-scale end users.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Feed sucrose demand concentrates in cane-processing regions where integrated livestock and aquaculture operations cluster near refining assets. Brazil, Thailand, Germany, the United States, and India collectively shape procurement patterns through distinct regulatory and logistical configurations.
Brazil
São Paulo state cane mills supply integrated cattle feedlots with granulated sucrose for energy-dense finishing rations. ANVISA enforces residue thresholds that shape export-oriented quality specifications. São Paulo's sugarcane belt feeds direct mill-to-feedlot transfer systems that compress logistics costs for protein processors.
Thailand
Central plains mill complexes drive liquid sucrose uptake for shrimp aquaculture automation and finfish feed compounders. The FDA-equivalent national food and drug administration regulates import residue testing timelines that create clearance cycle variability. Thai mill retrofits with membrane filtration are absorbing certified-low-carbon sucrose into scope-three reporting frameworks.
Germany
Beet processors in Lower Saxony and Bavaria repurpose bioethanol infrastructure for feed sucrose streams serving integrated protein producers. The EU F-Gas Regulation mandates hydrofluorocarbon phase-out in crystallization lines by 2030. French and German absorption heat pump retrofits extract waste energy from adjacent distillation operations.
United States
North American cattle feeding operations and poultry integrators bundle sucrose procurement with amino acid premixes through consolidated commodity platforms. The EPA regulates cross-contamination risks under the Federal Food, Drug, and Cosmetic Act when medicated feed compliance triggers. Midwest grain-sweetener logistics networks anchor multi-year offtake agreements with embedded price collars.
India
Gujarat and Maharashtra crossbred cattle operations remain underpenetrated by instantized milk replacer formulations using powdered sucrose. FSSAI standards shape import quality specifications for neonatal dairy nutrition. Cooperative dairy structures in these western states are consolidating procurement through regional distributor networks.
Feed Sucrose Market Competitive Landscape
Brazilian and Thai producers anchor one tier of supply through cane-based origination; European beet specialists hold another through co-located bioethanol assets. The vendor base organizes around three strategic archetypes: integrated agribusiness conglomerates with captive logistics networks, regional mill operators with direct livestock processor relationships, and diversified sweetener processors pivoting idled capacity toward feed-grade streams. Competitive moves concentrate on multi-year offtake contracting with embedded carbon accounting clauses and membrane filtration retrofits that reduce crystallization energy intensity.
Within the integrated conglomerate tier, Cargill Incorporated and Südzucker AG exemplify divergent geographic and feedstock strategies. Cargill leverages North American grain-sweetener infrastructure to bundle carbohydrates with amino acid premixes. Südzucker anchors European supply through beet-derived streams co-located with bioethanol assets. Mitr Phol Group represents the Southeast Asian archetype, with Thai mill complexes directly supplying aquaculture feed compounders. These three occupy positions that reflect broader structural splits between cane and beet origination, between export-oriented and regionally captive demand, and between legacy bioethanol pivot strategies and greenfield automation investments.
| Leading Market Players |
|---|
| Südzucker AG |
| Cargill Incorporated |
| Associated British Foods plc |
| Tereos |
| Raizen |
| Mitr Phol Group |
| Louis Dreyfus Company |
| ASR Group |
| Tate & Lyle PLC |
| Others |
Value Network & Pricing Analysis
Captive mill-to-feedlot integration in São Paulo state anchors supply positioning and pricing power for Brazilian integrated processors, compressing logistics costs while enabling long-term offtake premiums that spot-market buyers cannot match. Thai aquaculture integrators leveraging direct mill relationships similarly command preferential liquid sucrose allocations, leaving distributor-dependent livestock owners exposed to harvest-season volatility and carbon-accounting surcharges.
Pricing Analysis
Volume concentration in granulated grades for ruminant TMR applications compresses margins, while liquid sucrose for aquaculture automation commands premium positioning. Three-tier pricing structure across certified-low-carbon, standard-refined, and economy-molasses-adjacent levels differentiates by EU F-Gas Regulation compliance status and membrane filtration certification. Pricing pressure stems from beet molasses substitution in temperate-zone ruminant formulations during cane price spikes. Smallholder livestock owners purchasing through wholesale channels exhibit highest price sensitivity; integrated aquaculture processors with multi-year contracts show lowest.
Supply Chain Analysis
Dual-sourcing requirements from Thai aquaculture integrators and Brazilian protein processors mandate ANVISA-qualified and EU F-Gas-compliant supplier qualification. Geographic supply concentration centers on Brazil, Thailand, and Germany as cane and beet origination hubs. Raw material dependencies include sugarcane crush volumes, beet harvest cycles, and fluorinated gas alternatives for crystallization lines. Single-origin exposure to Thailand's central plains monsoon variability constitutes primary supply chain risk. Distribution runs through direct sales for integrated processors and regional distributors for mid-scale compounders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Membrane filtration retrofits are displacing conventional evaporative crystallization as the dominant refining technology, forcing legacy thermal processors toward energy-intensity compliance or asset obsolescence.
For Market Incumbents: To counter membrane filtration cost advantages from Brazilian mill operators, deploy absorption heat pump retrofits extracting waste energy from adjacent bioethanol distillation, and secure multi-year offtake agreements with embedded EU F-Gas Regulation compliance certification to lock in premium positioning. For New Entrants and Emerging Players: Indian dairy cooperatives in Gujarat and Maharashtra represent the most penetrable buyer archetype, with instantized milk replacer formulations using powdered sucrose remaining underdeployed. Target precision fermentation feedstock supply to cellular agriculture facilities as a greenfield entry angle, leveraging crystalline sucrose purity specifications for microbial growth media. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated agribusiness conglomerates seeking captive carbohydrate supply. Long-term viability favors processors with membrane filtration assets and co-located bioethanol infrastructure. The signal to watch is EU CBAM implementation intensity for agricultural inputs, which would accelerate consolidation toward certified-low-carbon supply chains.| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Filtration Retrofit | Brazilian mill operators deploying ceramic nanofiltration capture carbon-intensity reductions for EU compliance. |
| Absorption Heat Pump Installation | German and French processors extract waste energy from bioethanol distillation to meet EU F-Gas phase-out mandates. |
| Multi-year Offtake Contracting | Southeast Asian aquaculture integrators bundle sucrose with amino acid premixes through embedded price collars. |
| Precision Fermentation Pivot | Sucrose refiners co-locating with cellular agriculture facilities pivot crystalline output toward microbial growth media. |
| Direct Mill-to-Feedlot Integration | São Paulo cane estates compress logistics costs through captive supply to integrated cattle feeding operations. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced against primary interviews with refinery operations managers, livestock feed procurement leads, aquaculture integrator supply chain directors, and EU F-Gas compliance officers. ANVISA residue testing databases, Thai FDA-equivalent import clearance records, and EU ETS carbon accounting disclosures supplied validation. Bottom-up volume modeling across cane and beet origination clusters triangulated against top-down macroeconomic demand projections for protein consumption.
Granularity-level modeling captured physical form segmentation at crystalline structure resolution, end-use specifications by species digestive physiology, and channel structure by procurement sophistication tier. CAGRs derived from regression analysis against livestock production intensity indices and aquaculture automation penetration curves. Forecast inputs included crush volume variability in Thailand's central plains, EU CBAM agricultural input scope-three liability accumulation, and membrane filtration deployment rates across Brazilian mill complexes.
Revisions become necessary when EU F-Gas Regulation phase-out timelines accelerate, EU CBAM implementation extends to agricultural inputs, or monsoon-driven crush variability in Thailand exceeds historical bands. Deviation in carbon border adjustment mechanism scope or membrane filtration cost curves would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Commodities
Global Wood Chips Market
Agricultural Commodities
Corn Hydrolysate Market
Agricultural Commodities
Asia-Pacific Ruminant Feed Premix Market
Agricultural Commodities
Marine Powder Market
Agricultural Commodities
Cattle Feed Market
Agricultural Commodities
Global Seed Cotton Market
Agricultural Commodities
Middle East Feed Amino Acids Market
Agricultural Commodities
Gorse Market
Agricultural Commodities
Bladderpod Oil Market
Agricultural Commodities
Citrus Pulp Pellets Market
Agricultural Commodities
Africa Feed Amino Acids Market
Agricultural Commodities
Corn and Corn Starch Derivatives Market
Agricultural Commodities
South America Feed Amino Acids Market
Agricultural Commodities
Europe Ruminant Feed Market
Agricultural Commodities
Alfalfa Powder Market
Agricultural Commodities
Copra Meal Market