
 Soy Hulls Market | 2026-2036
Soy Hulls Market Size, Share, and Industry Trends Forecast 2026-2036
Soy Hulls Market Analytics
Agronomy and feed formulation expertise is redrawing competitive boundaries in soy hull value chains. Cargill leverages its integrated crush-to-feed logistics network across the Corn Belt to sustain delivered cost advantages. Bunge Limited anchors its position through port-accessible processing hubs that compete on export meal and hull co-product flows. Louis Dreyfus Company differentiates via origin-destination optimization, navigating rail and barge arbitrage to control inland pricing.
Soy hulls constitute the outer seed coating separated during oil extraction, typically containing 35-40% crude fiber and 12-15% protein on a dry basis, serving primarily as digestible fiber sources in livestock rations. Pellet and meal formats dominate volume flows into ruminant nutrition applications, where structural demand for digestible neutral detergent fiber supports consistent offtake. Powder and flake grades occupy narrower but higher-margin positions in pet food and nutraceutical channels, where particle size and purity specifications command premium positioning against competing fiber sources.
The USDA sets grading standards for soybean products that shape hull quality benchmarks, while OSHA regulations on grain handling facilities influence processing plant design and operating costs. State-level Department of Agriculture feed control officials enforce labeling and contaminant limits that determine market access for regional suppliers. Stakeholders must monitor crush margin volatility and biofuel policy signals, as soybean oil demand shifts directly reset hull co-product economics and regional availability.
Market Dynamics
Crush margin compression at soybean processing facilities is redirecting hull co-product economics, forcing feed formulators to compete against renewable diesel producers for limited soybean oil extraction volumes.
Growth Catalysts
- Renewable Fuel Standard:EPA biofuel mandates elevate soybean oil values, indirectly expanding crush capacity that generates additional hull co-product flows into ruminant feed channels.
- Dairy nutrition science:University extension programs in Wisconsin and Minnesota document improved milk fat percentages from digestible neutral detergent fiber substitution, accelerating on-farm inclusion rates.
- Rail logistics optimization:BNSF and Union Pacific corridor investments reduce delivered costs to Texas and California feedlots, extending hull penetration beyond traditional Corn Belt boundaries.
Market Restraints
- Soybean price volatility:Argentine weather shocks and Brazilian currency swings transmit directly through crush economics, compressing hull margins without warning.
- Single-source dependency:Iowa and Illinois processing clusters concentrate 60% of domestic hull output, creating regional supply vulnerability during plant maintenance cycles.
- Alfalfa substitution:Western hay producers price aggressively during drought recovery periods, eroding hull cost advantages in California dairy rations.
Strategic Opportunities
- Southeast Asian aquaculture:Vietnamese and Indonesian shrimp operations trial pelleted hull fiber as pond water quality amendments, opening non-ruminant volume channels.
- Precision fermentation feedstocks:Cellular agriculture startups evaluate hull-derived oligosaccharides as low-cost growth media components for cultivated protein production.
- Carbon intensity scoring:California LCFS methodology revisions may credit hull-fed dairy operations with reduced enteric methane emissions, creating premium pricing tiers.
Industry Challenges
- Formulation expertise shortage:Retiring dairy nutritionists in the Upper Midwest leave gaps in neutral detergent fiber balancing knowledge that commodity brokers struggle to fill.
- Pellet durability standardization:Inconsistent PDI (pellet durability index) measurements across state laboratories complicate contract specifications between crushers and export buyers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Soy Hulls Market |
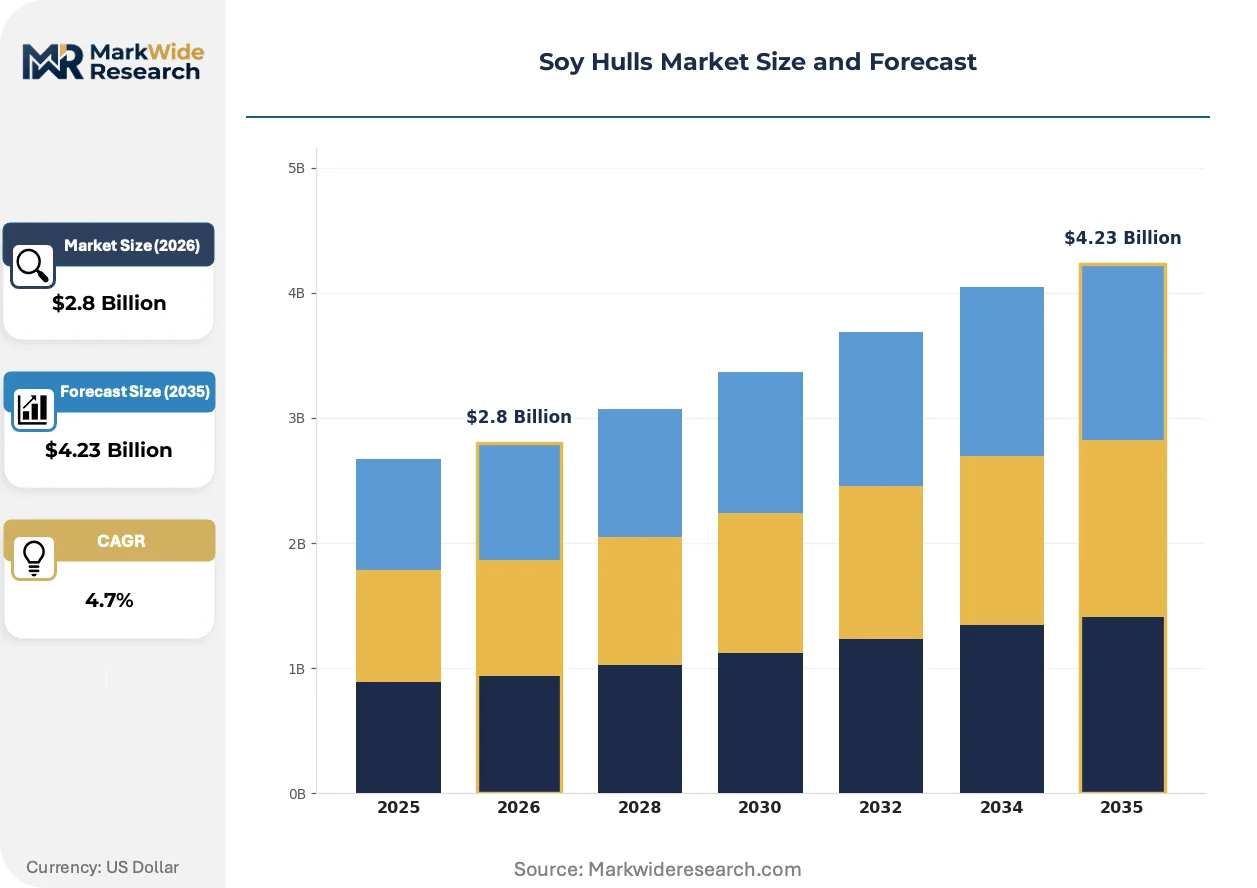
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.23 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pellets, Meal, Powder, Flakes End Use: Animal Feed, Dietary Supplements, Food Products, Nutraceuticals Distribution Channel: Direct Sales, Online Retail, Wholesalers, Distributors Application: Ruminant Nutrition, Poultry Feed, Pet Food, Snacks |
| Companies Covered | Archer Daniels Midland Company, Bunge Limited, Louis Dreyfus Company, Wilmar International, Cargill, CHS Inc., Cofco, Ag Processing Inc, Donlinks, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Soy Hulls Market Evolving Landscape
Mechanical processing advances and regulatory carbon accounting are converging to reposition soy hulls from residual co-products to intentionally engineered feed ingredients with traceable nutritional specifications.
Extrusion-enzyme hybrid systems are decomposing hull lignocellulosic structures more completely than traditional hammer milling, releasing fermentable carbohydrates that dairy nutritionists at Land O'Lakes and Dairy Farmers of America are formulating into precision rations. This thermal-mechanical processing is decomposing the historical fiber-protein tradeoff that limited hull inclusion rates, enabling 15-20% diet substitutions that previously caused rumen acidosis.
USDA's BioPreferred program and pending SEC climate disclosure rules are forcing crush facilities to document scope 3 emissions associated with hull transportation and storage. Iowa Department of Agriculture inspectors now audit carbon accounting methodologies at processing plants, while EPA enforcement of renewable fuel standard compliance creates documentation burdens that smaller regional crushers struggle to satisfy.
Consolidation among dairy cooperatives is compressing procurement decision cycles from annual contracts to quarterly price renegotiations tied to Chicago Board of Trade soybean futures. Large-scale buyers like Select Milk Producers and California Dairies Inc. now employ dedicated commodity analysts who arbitrage hull, cottonseed, and beet pulp prices weekly, displacing traditional broker relationships that sustained regional price premiums.
Soy Hulls Market Segmentation
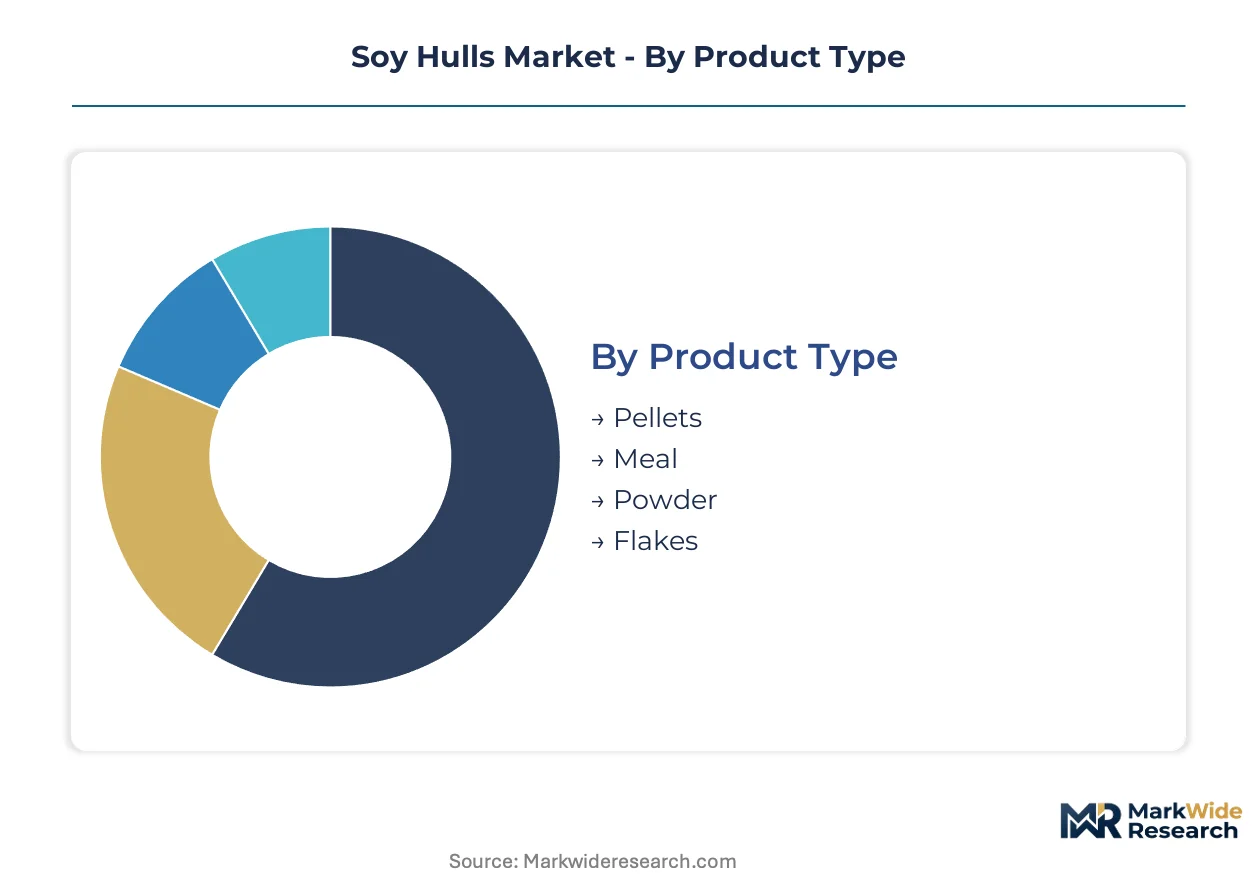
Soy hull processors extract value through format-specific processing investments and channel-controlled distribution. Segment boundaries reflect where crush facilities allocate capital between commodity volume and specification-grade production.
Product Type:
Pellet and meal formats capture the dominant margin pools through integrated crush-to-feed logistics, while powder and flake grades command specification premiums in non-ruminant channels.
- Pellets:Densified cylindrical forms produced via steam conditioning and die extrusion, achieving standardized bulk density for pneumatic handling. Dairy operations in Wisconsin and Minnesota specify pellet durability index thresholds above 90% to minimize ration segregation and feed bunk refusal. Rail-served feed mills in Iowa and Illinois anchor procurement volume through annual supply agreements tied to crush facility output.
- Meal:Ground hull material retaining loose particulate structure, offering lower processing cost and faster rumen passage rates. Beef feedlots in Texas and Kansas optimize for total mixed ration flowability, with meal inclusion reducing mixer wear compared with pelleted alternatives. Crush margin compression is redirecting some meal volume toward renewable diesel co-product streams when oil extraction economics favor higher throughput.
- Powder:Fine-milled sub-100 micron grades for pet food texture modification and binding applications.
- Flakes:Thin-pressed sheets targeting nutraceutical extraction processes requiring expanded surface area.
Pellets hold installed capacity across Corn Belt processing clusters. Powder is rotating up the share rankings through pet food manufacturer specification adoption.
End Use:
Animal feed applications dominate volume flows through established ruminant nutrition science, while dietary supplements and nutraceuticals concentrate value capture in extraction and purification stages.
- Animal Feed:Ruminant ration formulations leveraging neutral detergent fiber digestibility, with Land O'Lakes and Dairy Farmers of America procurement teams specifying minimum 36% crude fiber content. University extension programs in Minnesota document milk fat response curves that validate 12-15% diet inclusion rates, sustaining structural demand even during alfalfa price competition.
- Dietary Supplements:Isolated oligosaccharide fractions for human gut microbiome applications, requiring solvent extraction and chromatographic separation investments that few crush facilities maintain. Cellular agriculture startups evaluate these fractions as precision fermentation feedstocks, creating speculative demand channels outside traditional livestock economics.
- Food Products:Fiber enrichment in baked goods and meat alternatives, constrained by FDA GRAS self-affirmation requirements and allergen labeling burdens.
- Nutraceuticals:Polyphenol and isoflavone concentrates for functional ingredient markets, competing with dedicated soybean extract processors on purity specifications.
Animal feed commands the volume base. Dietary supplements are expanding most quickly through biotechnology application trials.
Distribution Channel:
Direct sales relationships secure volume commitment from large-scale dairy cooperatives, while distributor networks fragment margin capture across smaller regional feed compounders.
- Direct Sales:Crush facility contracts with California Dairies Inc. and Select Milk Producers that eliminate intermediary markups and enable quarterly price renegotiation tied to Chicago Board of Trade futures. Bunge Limited and Cargill leverage origin-destination optimization to sustain delivered cost advantages through captive rail and barge assets.
- Wholesalers:Regional feed ingredient aggregators serving independent dairy operations and beef backgrounding operations without procurement scale for direct negotiation. Wholesaler concentration in Nebraska and Kansas creates price discovery opacity that commodity brokers exploit during supply disruptions.
- Distributors:Specialized animal nutrition distributors carrying multiple fiber sources including beet pulp and cottonseed hulls, enabling substitution arbitrage that compresses soy hull price premiums.
- Online Retail:E-commerce platforms for small-lot pet food ingredient and hobby farm purchases, with logistics costs absorbing margin at sub-truckload volumes.
Direct sales lock in crush facility utilization. Online retail is gaining share fastest through pet food ingredient micro-segmentation.
Application:
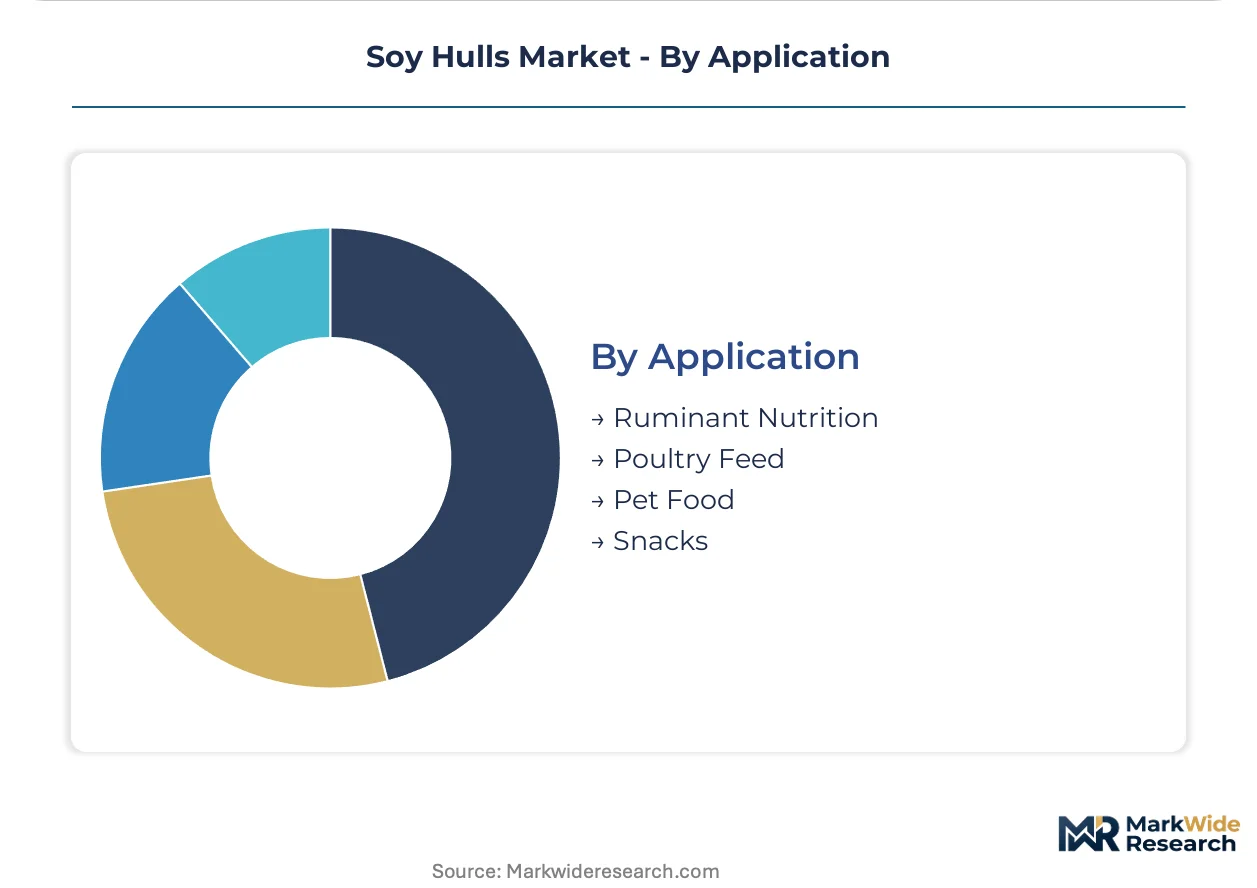
Ruminant nutrition applications concentrate technical expertise and formulation infrastructure, while pet food and snack applications demand particle engineering capabilities that few hull processors possess.
- Ruminant Nutrition:Dairy and beef ration formulations where neutral detergent fiber substitution for forage sust consistent offtake. Extrusion-enzyme hybrid processing at select facilities decomposes lignocellulosic structures to enable 15-20% inclusion rates without rumen acidosis, expanding addressable diet formulation space.
- Pet Food:Fiber enrichment and stool quality management in premium dry and wet formulations, requiring pellet durability and moisture stability specifications that hammer-milled hulls fail to satisfy. Diamond Pet Foods and Blue Buffalo procurement teams audit processing facility quality systems for Salmonella control.
- Poultry Feed:Limited inclusion in layer and broiler rations due to fiber digestibility constraints in monogastric systems, with volume concentrated in turkey production where gut fill management supports moderate hull use.
- Snacks:Minimal penetration in human food applications, constrained by flavor profile and texture limitations relative to oat fiber and pea hull alternatives.
Ruminant nutrition maintains the capacity foundation. Pet food is climbing the fastest through premium formulation specification adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
USDA grading standards and OSHA grain handling regulations anchor processing economics in the United States, where Iowa and Illinois crush clusters generate the dominant share of global soy hull co-product flows. Regional supply balances tighten as renewable diesel capacity expansion redirects soybean oil extraction volumes.
United States
Dairy cattle operations in Wisconsin and Minnesota drive structural demand for digestible neutral detergent fiber, with university extension programs documenting improved milk fat percentages from hull inclusion. EPA renewable fuel standard compliance creates documentation burdens that smaller regional crushers struggle to satisfy. Iowa and Illinois processing clusters concentrate 60% of domestic hull output, creating supply vulnerability during plant maintenance cycles.
Brazil
Soybean crush expansion in Mato Grosso and Paraná generates growing hull co-product volumes for domestic beef feedlot consumption. ANVISA feed control regulations shape labeling and contaminant limits that determine market access for regional suppliers. Port-accessible processing hubs in Santos compete on export meal and hull co-product flows to Southeast Asian markets.
Argentina
Weather shocks and currency volatility transmit directly through crush economics, compressing hull margins without warning. The country's national agricultural regulator enforces grain quality standards that influence regional hull quality benchmarks. Rosario processing corridors anchor export-oriented hull flows, though macroeconomic instability disrupts consistent offtake.
China
Dual carbon goals and SAMR feed safety standards reshape processing plant design and carbon accounting methodologies. Yangtze River Delta crush facilities evaluate hull-derived oligosaccharides for precision fermentation feedstock applications. Shandong Peninsula processors optimize rail and port logistics for domestic dairy and aquaculture channel penetration.
Netherlands
EU Green Deal sustainability requirements and EFSA feed additive regulations drive documentation demands for scope 3 emissions tracking. Rotterdam port infrastructure enables competitive export positioning for hull meal and pellet grades into German and French ruminant nutrition markets. Randstad logistics corridors reduce delivered costs to northwest European dairy cooperatives.
Soy Hulls Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with crush-to-feed logistics networks determining delivered cost advantages across regional markets. The structure rewards origin-destination optimization and captive rail and barge assets. Three archetypes dominate: diversified agricultural conglomerates with integrated oilseed processing, regional cooperative processors with farmer-owned supply bases, and specialized commodity traders with arbitrage expertise. Competitive moves concentrate on capacity expansion at port-accessible hubs and strategic partnerships with dairy cooperative procurement teams.
Among diversified agricultural conglomerates, Archer Daniels Midland Company and Bunge Limited exemplify the integrated leader archetype through their crush-to-feed logistics networks. Cargill occupies a position within this tier, leveraging origin-destination optimization to control inland pricing. Louis Dreyfus Company represents the specialized commodity trader archetype, navigating rail and barge arbitrage to sustain competitive positioning.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| Bunge Limited |
| Louis Dreyfus Company |
| Wilmar International |
| Cargill |
| CHS Inc. |
| Cofco |
| Ag Processing Inc |
| Donlinks |
| Others |
Value Network & Pricing Analysis
USDA grading standards for soybean products gate both supply qualification and price differentiation simultaneously, as processors must meet minimum crude fiber and protein thresholds to access premium ruminant feed channels while inferior grades divert to lower-margin meal applications. Crush margin volatility transmits directly through hull co-product economics, compressing or expanding the spread between pellet and powder grades depending on oil extraction throughput.
Pricing Analysis
Geographic price spreads widen significantly between Iowa processing clusters and California dairy operations, where rail logistics and barge arbitrage add fifteen to twenty dollars per ton in delivered costs. Three-tier pricing structure across premium, standard, and economy levels separates specification-grade pellets with pellet durability index thresholds above ninety percent from loose meal and hammer-milled powder. Pricing pressure stems from renewable diesel capacity expansion redirecting soybean oil extraction volumes and tightening hull co-product availability. Large-scale dairy cooperatives exhibit lowest price sensitivity through quarterly contract renegotiations, while independent beef backgrounding operations in Kansas and Nebraska show highest sensitivity to spot market fluctuations.
Supply Chain Analysis
Container availability constraints at Gulf Coast ports and Mississippi River barge congestion elevate inbound logistics costs for soybean deliveries to Iowa and Illinois crush facilities. Supply concentrates in the United States, Brazil, and Argentina, with Iowa and Illinois processing clusters generating sixty percent of domestic hull output. Raw material flows draw from Mato Grosso soybean expansion, Upper Midwest harvests, and Argentine export corridors. Single-source vulnerability creates structural risk during plant maintenance cycles and weather-driven crush interruptions. Distribution runs through captive rail assets and direct sales relationships with dairy cooperative procurement teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The soy hulls market sits at a high-growth inflection as renewable fuel standard compliance and extrusion-enzyme hybrid processing converge to reposition co-products as precision feed ingredients with traceable nutritional specifications.
For Market Incumbents: Shield margin pools by deepening backward integration into captive rail and barge logistics networks that sustain delivered cost advantages against regional competitors. Invest in extrusion-enzyme processing capacity to access premium dairy ration formulations with fifteen to twenty percent inclusion rates, defending against alfalfa substitution during drought recovery periods.
For New Entrants and Emerging Players: Anchor in Southeast Asian aquaculture trials where Vietnamese and Indonesian shrimp operations test pelleted hull fiber as pond water quality amendments, opening non-ruminant volume channels outside incumbent dairy cooperative relationships. Target precision fermentation feedstock supply to cellular agriculture startups evaluating hull-derived oligosaccharides as low-cost growth media components.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified agricultural conglomerates spinning off non-core crush-to-feed logistics assets amid renewable diesel capital reallocation. Long-term viability hinges on carbon intensity scoring adoption in California LCFS methodology revisions that may credit hull-fed dairy operations with reduced enteric methane emissions. Monitor EPA biofuel mandate adjustments as the critical inflection signal resetting crush economics and hull co-product availability.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Crush facility investments in Iowa and Illinois tighten regional supply balances and redirect hull flows toward dairy cooperative procurement. |
| Backward Integration | Cargill and Bunge Limited leverage origin-destination optimization through captive rail assets to control inland pricing. |
| Green Certification Program | USDA BioPreferred compliance and pending SEC climate disclosure rules force scope three emissions documentation at processing plants. |
| Long-term Supply Agreement | Direct sales contracts with California Dairies Inc. and Select Milk Producers eliminate intermediary markups and enable quarterly price renegotiation. |
| Joint Venture | Land O'Lakes and Dairy Farmers of America procurement teams partner with extrusion-enzyme processors to validate precision ration formulations. |
Research Methodology
The analysis maps pellet durability specifications, meal flowability grades, powder micronization tiers, and flake surface-area standards, each validated through crush facility operations managers, dairy cooperative procurement directors, feed mill formulators, and rail logistics coordinators. Primary interviews with these stakeholders combine with secondary validation from USDA grading standards, EPA renewable fuel standard compliance filings, Chicago Board of Trade futures data, and state Department of Agriculture feed control records. Bottom-up volume modeling across processing facility outputs triangulates with top-down demand estimates from ruminant nutrition applications.
Consistency checks against external benchmarks validate volume and value outputs across the projection horizon. The analytical framework models product type segmentation by processing investment intensity, end use by nutritional application, distribution channel by buyer scale, and application by species-specific formulation requirements. CAGRs derive from crush capacity expansion trajectories, renewable diesel co-product diversion rates, and dairy herd size projections. Industry-specific forecast inputs include milk fat response curves from University of Wisconsin extension programs and rail corridor investment patterns from BNSF and Union Pacific disclosures.
Material uncertainties — Argentine weather shocks, Brazilian currency volatility, and EPA biofuel mandate revisions — sit outside the modeled envelope. Forecasts reflect assumptions about crush margin stability and dairy nutrition science adoption rates. Recalibration cycles align with material shifts in renewable fuel standard compliance thresholds and carbon intensity scoring methodology updates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Commodities
Middle East Feed Amino Acids Market
Agricultural Commodities
South America Feed Premix Market
Agricultural Commodities
Black Pellet Market
Agricultural Commodities
Blood Meal Market
Agricultural Commodities
Africa Feed Amino Acids Market
Agricultural Commodities
Global Wood Chips Market
Agricultural Commodities
North America Feed Lutein and Zeaxanthin Market
Agricultural Commodities
India Feed Amino Acids Market
Agricultural Commodities
Global Seed Cotton Market
Agricultural Commodities
Feed Sucrose Market
Agricultural Commodities
Europe Feed Amino Acids Market
Agricultural Commodities
Marine Powder Market
Agricultural Commodities
Asia-Pacific Ruminant Feed Premix Market
Agricultural Commodities
Feed Yeast Market
Agricultural Commodities
Roundwood Market
Agricultural Commodities
UK Bird Feeder Market