
 France Seed Treatment Market | 2026-2036
France Seed Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
France Seed Treatment Market Foresight
Agricultural cooperative consolidation across northern France is expanding the buyer landscape for treated seed, as fewer but larger cooperatives negotiate volume contracts with input suppliers. Corteva Agriscience leverages its integrated seed-and-crop-protection pipeline to serve these consolidated buyers. Syngenta anchors its position through proprietary fungicide-seed integration platforms. Bayer CropScience AG competes via biological seed treatment portfolios aligned with French sustainability protocols.
Seed treatment encompasses the application of chemical or biological agents to seeds before planting, with formulations typically containing active ingredients at concentrations between 0.1% and 40% by weight depending on target pest and crop species; the process protects germinating seeds from soil-borne pathogens and early-season insects to secure establishment rates and yield potential. Fungicide-based treatments dominate current volume given persistent pressure from Fusarium and Pythium complexes in French cereal rotations, while biostimulant formulations represent the fastest-expanding margin pool as growers seek alternatives under tightening pesticide regulations. Liquid suspensions lead formulation demand due to coating uniformity and compatibility with high-speed treaters, though water dispersible granules gain traction for reduced dust exposure during handling.
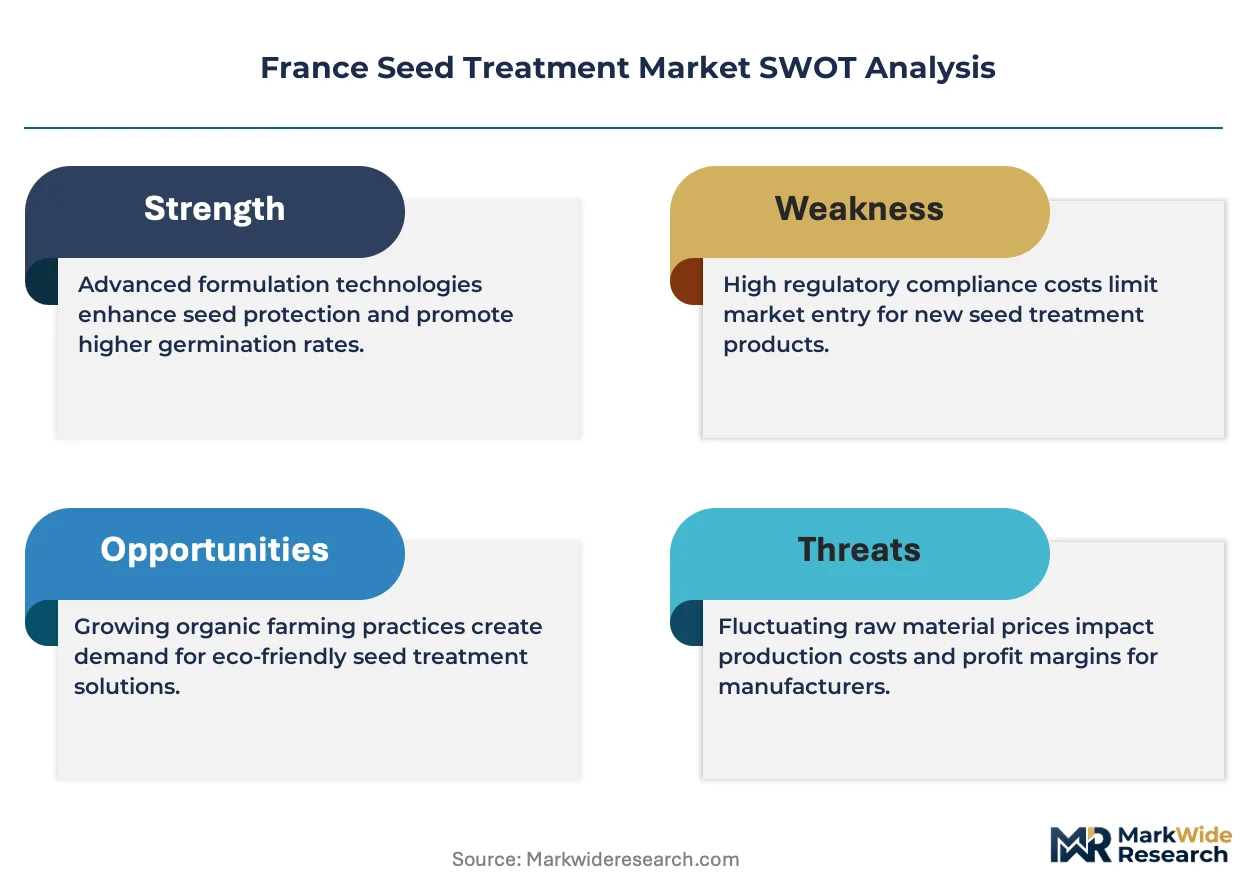
ANSM oversees chemical active substance approvals for seed-applied products, while the EU Green Deal's pesticide reduction targets and France's national Ecophyto plan collectively restrict conventional chemistry volumes and accelerate biological agent registrations. ECHA's REACH framework governs co-formulant toxicity thresholds, forcing reformulation of legacy products. Stakeholders must monitor the pace of biological product efficacy validation against the tightening regulatory calendar for chemical withdrawals.
Market Dynamics
The EU Green Deal's pesticide reduction targets are compressing chemical seed treatment volumes while accelerating biological formulation registrations across French cereal rotations. This regulatory pivot is restructuring supplier R&D priorities and cooperative procurement criteria.
Growth Catalysts
- Ecophyto Plan Mandates:France's national pesticide reduction framework creates guaranteed demand pull for biostimulant-based seed treatments, with treated seed stocks qualifying for direct subsidies under sustainable farming protocols.
- Cooperative Consolidation:Fewer but larger agricultural cooperatives in Hauts-de-France and Grand Est negotiate multi-year volume contracts, stabilizing input demand and enabling supplier capacity planning.
- Fungicide-Seed Integration:Proprietary coating technologies that combine fungicide protection with biostimulant priming are capturing premium positioning in wheat and barley seed procurement.
Market Restraints
- Active Substance Withdrawal Calendar:ECHA's REACH framework and ANSM re-evaluation timelines are scheduled to remove legacy neonicotinoid chemistries from approved seed-applied products, forcing rapid portfolio turnover.
- Biological Efficacy Validation Lag:Biostimulant formulations face extended field trial requirements under EU regulatory frameworks, delaying market entry relative to tightening chemical withdrawal deadlines.
- Input Cost Volatility:Petroleum-derived polymer binders and synthetic active ingredient precursors expose formulators to energy price fluctuations that compress margin stability.
Strategic Opportunities
- Grand Est Specialty Crops:Underpenetrated vegetable and industrial hemp seed treatment demand in eastern France offers expansion vectors beyond saturated cereal markets.
- Water Dispersible Granule Formats:Reduced dust exposure regulations favor dry formulation transitions, creating first-mover advantage for treater-compatible granule technologies.
- Carbon Credit Integration:Biostimulant-treated seeds qualifying for EU carbon farming certification can capture price premiums through verified emission reduction claims.
Industry Challenges
- Formulation Chemist Scarcity:Expertise in biological active stabilization and seed-coating adhesion science is concentrating among legacy agrichemical firms, constraining new entrant technical capacity.
- Treater Retrofit Requirements:High-speed seed treatment equipment in cooperative facilities requires hardware modifications to handle viscous biological suspensions, creating capital friction during transition periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Seed Treatment Market |
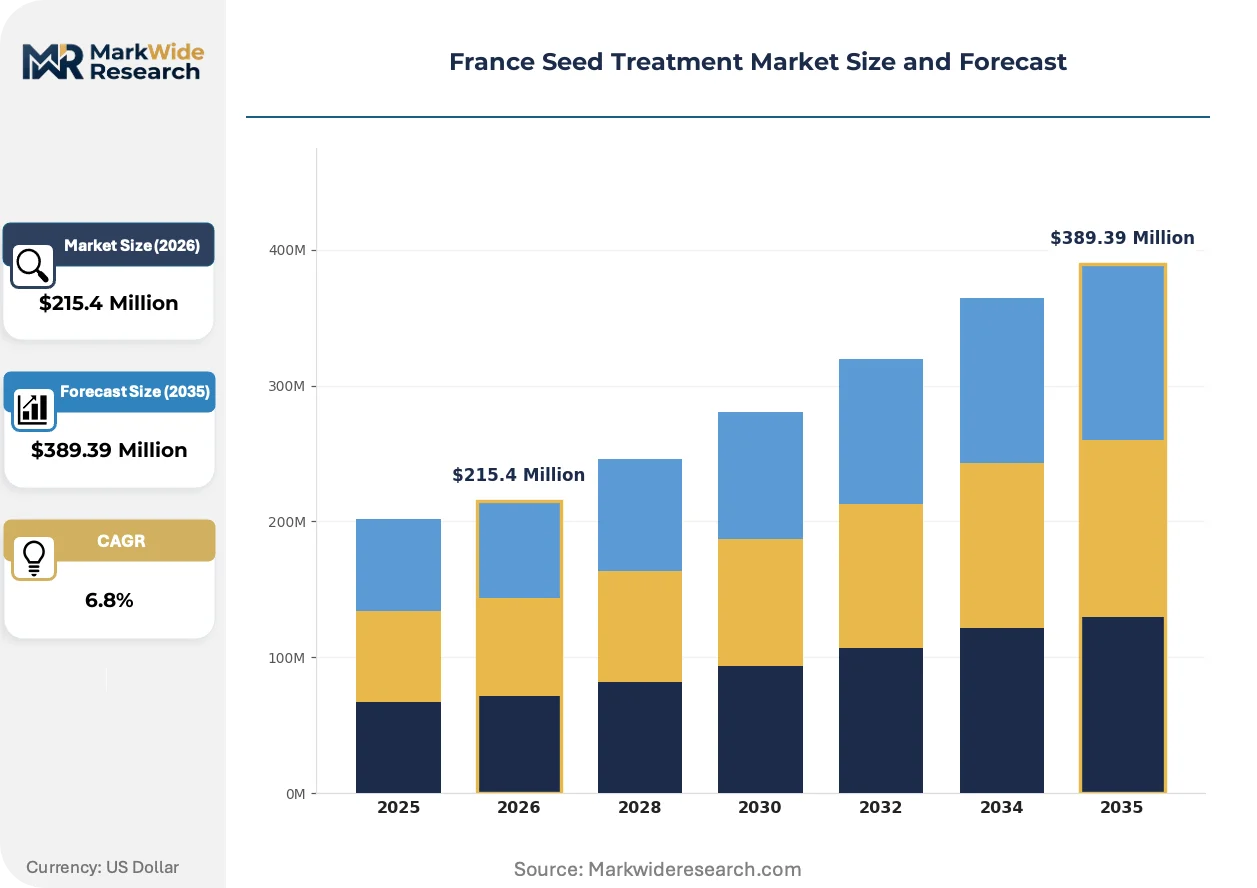
| Market Size in 2026 | $215.4 Million |
| Market Size in 2035 | $389.39 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fungicides, Insecticides, Nematicides, Biostimulants, Herbicides Application Crop: Cereals, Oilseeds, Vegetables, Pulses, Forage Crops Formulation: Wettable Powders, Liquid Suspensions, Granules, Emulsifiable Concentrates, Water Dispersible Granules End User Type: Seed Producers, Agricultural Cooperatives, Specialty Growers, Contract Growers |
| Companies Covered | Corteva Agriscience, Semences de France, Syngenta, ADAMA Agricultural Solutions, FMC Corporation, Bayer CropScience AG, UPL Limited, Nufarm, BASF SE, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Seed Treatment Market Shifts & Advancements
Biological active integration is disrupting formulation chemistry while precision application hardware and carbon-accounting seed credentials are reshaping buyer value assessment. These shifts are compressing traditional chemical-dominant supplier positioning.
Microbial inoculant coatings containing rhizobia and Trichoderma strains are unifying nitrogen fixation and pathogen suppression functions in single-pass applications. Specialty vegetable growers in the Loire Valley are piloting these platforms at commercial scale. The technology is unifying previously separate input purchases into bundled seed procurement, altering distributor margin structures.
France's implementation of the EU Sustainable Use of Pesticides Regulation tightens maximum residue thresholds for seed-applied chemicals entering the food chain. Formulators must document environmental fate profiles under ECHA guidance, accelerating reformulation investments. Cereal seed suppliers are responding by pre-registering biological alternatives ahead of scheduled chemical withdrawals.
Cooperative buyers are consolidating input procurement into multi-year framework agreements that bundle treated seed with crop protection and agronomic advisory services. Traditional distributor networks face disintermediation pressure as direct supplier-cooperative relationships deepen. This pattern is most visible in the Pays de la Loire, where large-scale arable cooperatives have shifted to centralized purchasing committees.
France Seed Treatment Market Segmentation
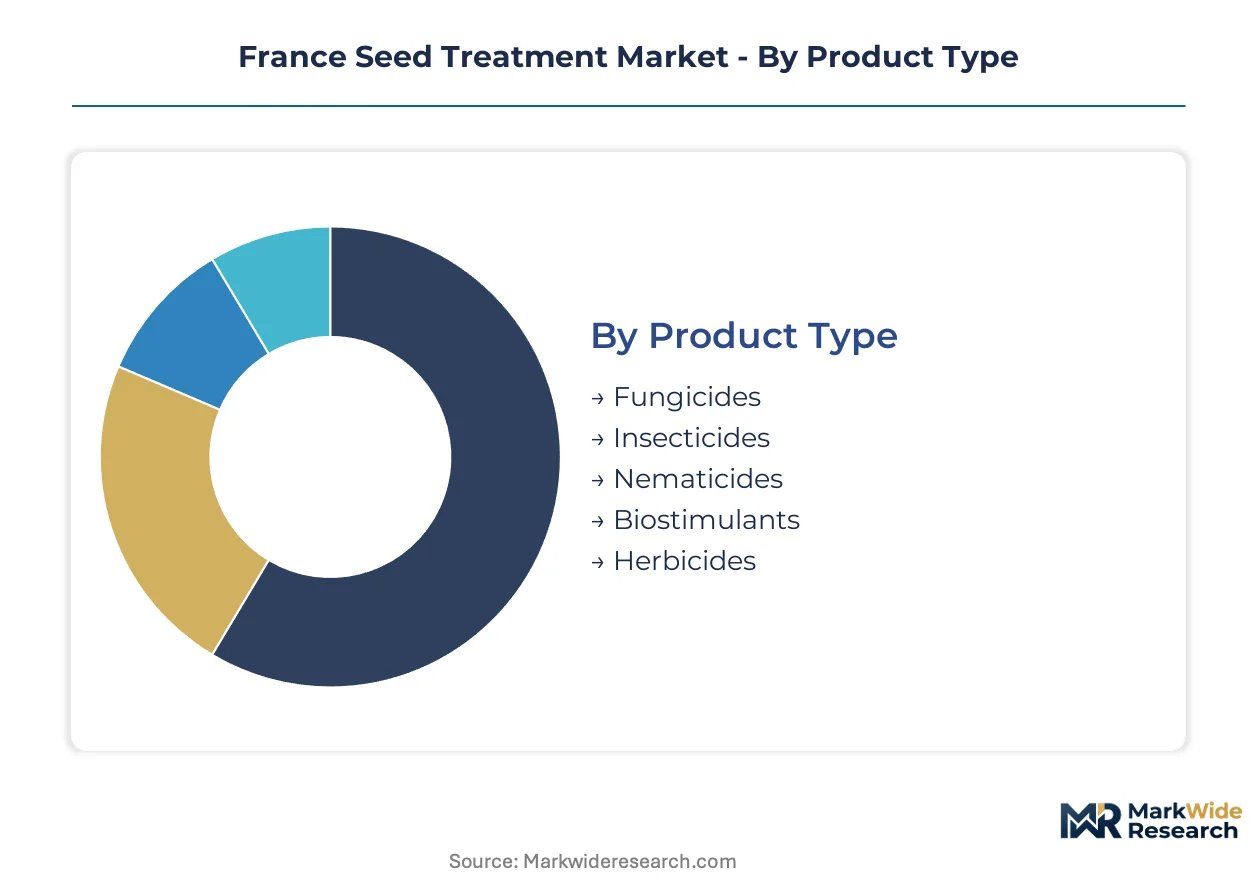
France's seed treatment market segments reflect divergent regulatory pathways under ANSM oversight and the EU Green Deal's pesticide reduction mandates. Understanding these divisions clarifies which product categories face accelerated chemical withdrawals versus biological fast-tracking.
Product Type:
ANSM approval timelines and ECHA REACH re-evaluation schedules create asymmetric compliance burdens across chemical and biological categories.
- Fungicides:Azole and strobilurin-based formulations dominate current volumes in French cereal rotations, particularly against Fusarium and Pythium complexes. Hauts-de-France cooperatives specify these treatments in multi-year procurement frameworks despite tightening residue thresholds.
- Biostimulants:Microbial inoculants and plant extract formulations qualify for Ecophyto subsidy eligibility, accelerating registrations ahead of neonicotinoid withdrawal deadlines. Grand Est specialty growers are piloting rhizobia-Trichoderma combination coatings at commercial scale.
- Insecticides:Neonicotinoid seed coatings face phased withdrawal under EU regulations, forcing rapid portfolio transitions.
- Nematicides:Limited adoption concentrates in vegetable seed treatments for Loire Valley producers.
- Herbicides:Pre-emergent seed-applied chemistries remain marginal amid mechanical weeding preferences.
Leading the category by volume: Fungicides. Growing fastest: Biostimulants.
Application Crop:
Regional cropping patterns in northern France concentrate procurement volumes and shape formulation requirements.
- Cereals:Wheat and barley seed treatments absorb the majority of cooperative purchasing power across Hauts-de-France and Grand Est, with fungicide-biostimulant integration capturing premium positioning in framework contracts.
- Vegetables:Specialty growers in the Loire Valley and Pays de la Loire drive biological formulation demand, with microbial coatings unifying nitrogen fixation and pathogen suppression in single-pass applications.
- Oilseeds:Rapeseed rotations in Champagne-Ardenne require distinct phoma and sclerotinia protection protocols.
- Pulses:Rhizobium inoculant demand concentrates in Bourgogne-Franche-Comté production zones.
- Forage Crops:Alfalfa and clover seed treatments follow dairy cooperative procurement cycles.
Volume concentrates in: Cereals. Margin expansion centers on: Vegetables.
Formulation:
Cooperative treater infrastructure and dust exposure regulations are restructuring format preferences across French handling facilities.
- Liquid Suspensions:Aqueous coating systems deliver uniformity at high-speed application rates, dominating cooperative treater throughput in northern France. Petroleum-derived polymer binders expose formulators to energy price volatility.
- Water Dispersible Granules:Reduced dust exposure during handling aligns with workplace safety regulations, gaining traction as treater retrofit investments proceed.
- Wettable Powders:Legacy format faces displacement amid dust containment requirements.
- Granules:Limited seed treatment adoption outside specialty horticultural applications.
- Emulsifiable Concentrates:Solvent-based systems declining under environmental fate scrutiny.
Current installed base favors: Liquid Suspensions. Regulatory tailwinds support: Water Dispersible Granules.
End User Type:
Buyer consolidation patterns are restructuring supplier access and contract structures across French distribution channels.
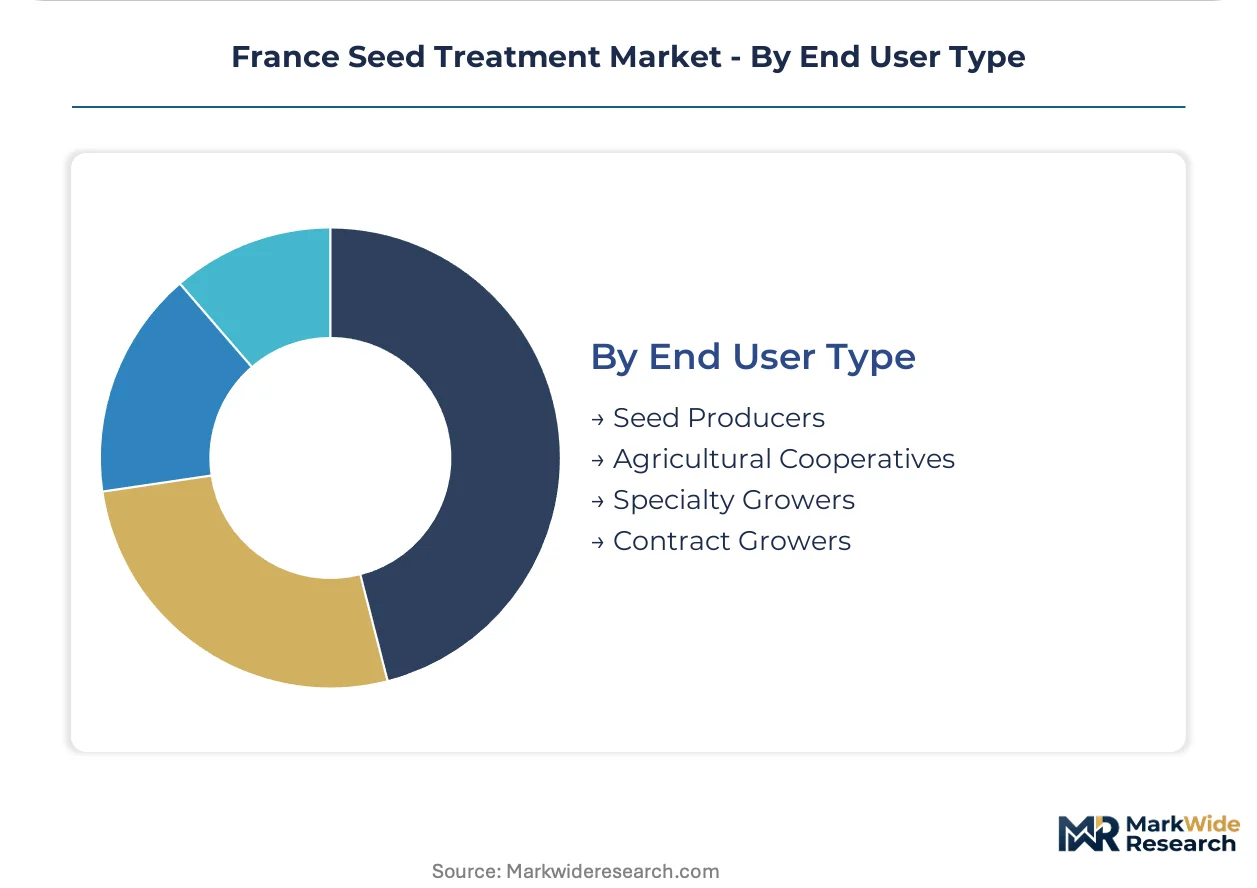
- Agricultural Cooperatives:Consolidated purchasing committees in Hauts-de-France and Grand Est negotiate multi-year framework agreements bundling treated seed with crop protection and advisory services, disintermediating traditional distributors.
- Seed Producers:Integrated seed-and-treatment operations leverage proprietary coating technologies for direct cooperative supply relationships.
- Specialty Growers:Loire Valley vegetable producers pilot microbial inoculant platforms, altering input bundling patterns.
- Contract Growers:Price-taker positioning limits direct supplier engagement, channeling through cooperative procurement.
Procurement volume aggregates with: Agricultural Cooperatives. Technology adoption leads among: Specialty Growers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Petroleum-derived polymer supply chains from the Port of Rotterdam and the Rhine chemical corridor feed formulator operations across northern France. These feedstock arteries anchor the geographic concentration of seed treatment manufacturing capacity.
Hauts-de-France
Cereal cooperative purchasing power concentrates in this northern belt, with wheat and barley seed treatments absorbing the majority of procurement volume. France's Ecophyto plan mandates pesticide reduction targets that redirect cooperative investment toward biostimulant-qualified treated seed stocks. The Lille metropolitan area hosts treater infrastructure retrofits for biological suspension handling.
Grand Est
Specialty crop diversification into industrial hemp and vegetable rotations creates underpenetrated demand beyond saturated cereal markets. The EU Green Deal's Sustainable Use of Pesticides Regulation tightens residue thresholds for seed-applied chemicals entering food chains. Strasbourg-based cooperatives pilot microbial inoculant coatings containing rhizobia and Trichoderma strains.
Pays de la Loire
Large-scale arable cooperatives have shifted to centralized purchasing committees, disintermediating traditional distributor networks. ANSM oversight of chemical active substance approvals governs product registrations for regional treater facilities. The Loire Valley corridor anchors specialty vegetable grower demand for nitrogen-fixing seed coatings.
Bourgogne-Franche-Comté
Pulse crop rotations concentrate rhizobium inoculant demand in this eastern production zone. ECHA's REACH framework governs co-formulant toxicity thresholds, forcing reformulation of legacy seed treatment products. Dijon-based agricultural cooperatives negotiate multi-year framework agreements bundling treated seed with advisory services.
France Seed Treatment Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue biological formulation niches as regulatory calendars compress chemical portfolios. The supplier base consolidates around integrated seed-and-crop-protection pipelines and proprietary coating technology platforms. Three archetypes dominate: legacy agrichemical conglomerates with biological R&D pivots, regional seed producers with captive treatment operations, and specialty biological formulators targeting subsidy-qualified sustainable agriculture protocols. Competitive moves center on portfolio diversification into biostimulant registrations and strategic partnerships with consolidated cooperative buyers.
Among integrated agrichemical conglomerates, Corteva Agriscience, Syngenta, and Bayer CropScience AG exemplify the dominant competitive archetype. These entities occupy positions spanning proprietary fungicide-seed integration platforms and biological portfolio alignments with French sustainability protocols. Their market presence anchors supplier-cooperative direct relationships that bypass traditional distribution channels. Regional seed producers such as Semences de France represent the captive treatment operation model, leveraging proximity to northern French cereal belts for cooperative supply contracts.
| Leading Market Players |
|---|
| Corteva Agriscience |
| Semences de France |
| Syngenta |
| ADAMA Agricultural Solutions |
| FMC Corporation |
| Bayer CropScience AG |
| UPL Limited |
| Nufarm |
| BASF SE |
| Others |
Supply & Pricing Matrix
Biological formulation transitions from petroleum-derived polymer binders to plant-based coating matrices simultaneously compress synthetic input costs and redistribute supplier power toward specialty biochemical producers in northern France. This dual shift tightens margin structures for legacy chemical formulators while elevating procurement leverage for consolidated agricultural cooperatives negotiating multi-year framework agreements.
Pricing Analysis
Service-bundling separates chemical warranty coverage from biological efficacy guarantees, with unbundled biological treatments commanding lower entry points but requiring separate agronomic advisory subscriptions. Three-tier pricing structure across premium fungicide-biostimulant integration, standard azole-based protection, and economy generic chemistries differentiates on certification grade and volume scale. Pricing pressure stems from ECHA REACH re-evaluation timelines forcing rapid portfolio turnover before patent cliff losses. Contract growers exhibit highest price sensitivity, while integrated seed producers absorb premiums for proprietary coating technologies.
Supply Chain Analysis
Petroleum-derived polymer supply rests on Rotterdam refinery outputs and Rhine corridor petrochemical complexes feeding formulator operations across Hauts-de-France. Active ingredient precursors draw from German specialty chemical producers and Belgian co-formulant specialists, with microbial inoculant cultures sourced from Dutch fermentation facilities. Single-source vulnerability concentrates in neonicotinoid alternative supply chains as biological registrations lag chemical withdrawal deadlines. Distribution runs through cooperative treater infrastructure retrofitted for viscous biological suspension handling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
France's seed treatment sector occupies a formulation chemistry transition phase, with microbial inoculant coatings displacing synthetic fungicide dominance under Ecophyto plan mandates. This technology pivot restructures competitive positioning around biological stabilization expertise and seed-coating adhesion science.
For Market Incumbents: To counter biological efficacy validation lags threatening market share erosion, accelerate captive R&D partnerships with French national agricultural research institutes for field trial acceleration. Prioritize backward integration into plant-based polymer binder production to insulate margin structures from petroleum price volatility and secure Ecophyto subsidy qualification pathways.
For New Entrants and Emerging Players: Agricultural cooperative purchasing committees represent the most penetrable channel partner type for bypassing entrenched distributor networks. Target Grand Est specialty crop diversification into industrial hemp and vegetable rotations where incumbent coverage remains thin. Lead with water dispersible granule format compatibility to exploit treater retrofit investment cycles and capture first-mover positioning on dust exposure compliance.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated agrichemical conglomerates seeking biological portfolio augmentation ahead of regulatory deadlines. Long-term viability hinges on validation throughput capacity rather than patent moats, favoring targets with established ANSM pre-registration pipelines. Monitor biological product efficacy data publication velocity as the critical inflection signal for portfolio revaluation timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Biological Formulation Registration Acceleration | Pre-positions portfolios ahead of ECHA neonicotinoid withdrawal deadlines under ANSM fast-track pathways. |
| Cooperative Direct Supply Agreements | Bypasses distributor disintermediation pressure in Hauts-de-France and Grand Est procurement consolidation. |
| Treater Infrastructure Retrofit Partnerships | Locks in biological suspension handling capacity at cooperative facilities during transition investment windows. |
| Carbon Farming Certification Integration | Captures Ecophyto subsidy eligibility and EU carbon credit price premiums for biostimulant-treated seed stocks. |
| Rhizobia-Trichoderma Coating Platform Development | Unifies nitrogen fixation and pathogen suppression in single-pass applications for Loire Valley vegetable growers. |
Research Methodology
ANSM regulatory filings, ECHA REACH substance evaluations, and French Ministry of Agriculture Ecophyto progress reports formed the secondary backbone for compliance timeline mapping and withdrawal schedule validation. Primary interviews with seed treatment formulator R&D directors, cooperative procurement committee chairs, and ANSM registration affairs specialists combined with this documentary base. Customs data on polymer binder imports and cooperative purchasing volume disclosures enabled bottom-up demand estimation triangulated against top-down market size reconciliation.
Historical trendline analysis of treated seed penetration rates across French cereal rotations established baseline growth trajectories without forward-year specificity. Segmentation modeling spanned product type, application crop, formulation format, and end user archetype dimensions across the projection horizon. CAGRs derived from volume-weighted average of segment trajectories, incorporating Ecophyto subsidy uptake curves and biological registration approval velocity as industry-specific forecast inputs.
Caveats apply where ECHA re-evaluation acceleration or ANSM biological efficacy trial backlog could materially shift the outlook for chemical-to-biological transition timing. Forecasts embed assumptions on cooperative consolidation pace and treater retrofit investment cycles. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seed Technology
Japan Seed Treatment Market
Seed Technology
Global Wheat Seed Treatment Market
Seed Technology
India Seed Treatment Market
Seed Technology
Seed Additives Market
Seed Technology
Seed Coating Ingredients Market
Seed Technology
North America Cotton Seed Treatment Market
Seed Technology
Europe Seed Coating Materials Market
Seed Technology
Canada Seed Treatment Market
Seed Technology
Seed Storage Systems Market
Seed Technology
Seed Coating Materials Market
Seed Technology
Germany Seed Treatment Market
Seed Technology
China Seed Treatment Market
Seed Technology
North America Seed Coating Materials Market
Seed Technology
Asia-Pacific Seed Coating Materials Market
Seed Technology
Chitosan-based Seed Coatings Market
Seed Technology
Seed Quality Imaging and Germination Prediction Test Systems Market