
 India Molecular Diagnostic Controls Market | 2026-2036
India Molecular Diagnostic Controls Market Size, Share, and Industry Trends Forecast 2026-2036
India Molecular Diagnostic Controls Market Foresight
Synthetic matrix materials are expanding their share against traditional blood-derived controls, cutting batch-to-batch variability and cold-chain dependency. Bio-Rad Laboratories leverages its long-standing distribution network to anchor the premium assayed controls tier across metropolitan diagnostic chains. Thermo Fisher Scientific sustains R&D intensity in multiplexed control panels, while Molbio Diagnostics Pvt. Ltd competes aggressively on price-point for point-of-care applications in district-level laboratories.
Molecular diagnostic controls comprise stabilized nucleic acid preparations with defined analyte concentrations, manufactured through recombinant expression or chemically synthesized sequences, used to verify analytical accuracy across PCR, NGS, LAMP, and microarray workflows. Assayed controls dominate current procurement volumes due to their pre-characterized target ranges that simplify regulatory documentation for clinical laboratories. Unassayed controls represent the fastest-expanding category as large reference laboratories internalize characterization protocols to reduce per-test costs. Diagnostic laboratories absorb the majority of end-user demand, though research facilities are carving out a specialized niche for custom control development.
CDSCO mandates lot-release documentation for imported IVD controls, while BIS certification requirements for molecular diagnostics are tightening material traceability standards. The Indian Council of Medical Research issues periodic proficiency testing mandates that directly stimulate replacement demand for expired or depleted control inventories. Stakeholders must track evolving PLI scheme eligibility for domestic control manufacturing, as tariff structures and local content thresholds will determine whether indigenous suppliers can displace incumbent import-dependent models.
Market Dynamics
CDSCO's tightened IVD quality guidelines and the rise of indigenous LAMP-based platforms are redirecting procurement toward locally manufactured controls, compressing import-dependent supply chains while expanding domestic production capacity.
Growth Catalysts
- PLI scheme eligibility:Domestic control manufacturers gain tariff advantages and local content thresholds that displace incumbent import-dependent models across Maharashtra and Karnataka laboratory networks.
- ICMR proficiency testing mandates:Periodic replacement requirements for expired control inventories stimulate recurring demand from diagnostic laboratories in western and southern India.
- Synthetic matrix materials:These stabilized nucleic acid preparations cut batch-to-batch variability and cold-chain dependency, accelerating adoption in district-level point-of-care applications.
Market Restraints
- Import documentation burden:CDSCO lot-release requirements for foreign IVD controls create regulatory friction that delays supply to metropolitan diagnostic chains.
- Blood-derived control scarcity:Traditional plasma-sourced materials face donor pool limitations and infectious disease screening costs that inflate input pricing.
- Reference laboratory internalization:Large diagnostic networks are developing in-house characterization protocols, eroding commercial assayed control volumes.
Strategic Opportunities
- District laboratory penetration:Unassayed controls represent expansion potential in tier-2 and tier-3 cities where cost-sensitive buyers internalize quality verification.
- Oncology testing corridor expansion:Western India's concentrated cancer diagnostic demand creates specialized control panel requirements for multiplexed mutation detection.
- Tuberculosis testing workflow integration:LAMP-TB platforms in government health programs require matched indigenous controls that bypass import licensing delays.
Industry Challenges
- BIS certification timelines:Material traceability standards for molecular diagnostics extend product approval cycles, compressing commercialization windows for new entrants.
- Multiplexed panel complexity:NGS and microarray control development demands cross-functional expertise in bioinformatics and synthetic biology that outpaces current workforce supply.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Molecular Diagnostic Controls Market |
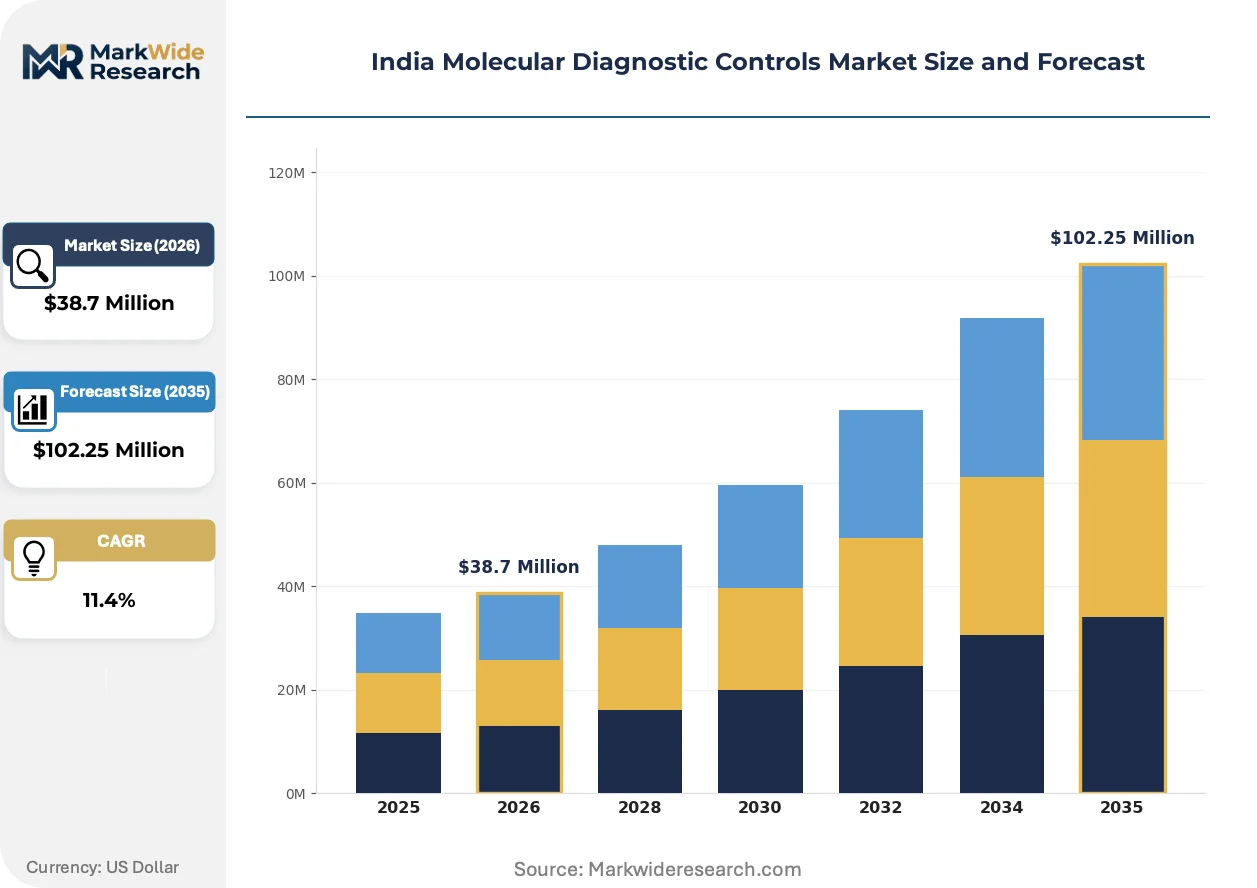
| Market Size in 2026 | $38.7 Million |
| Market Size in 2035 | $102.25 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Assayed Controls, Unassayed Controls, External Controls, Internal Controls Technology: PCR, NGS, LAMP, Microarray End User: Hospitals, Diagnostic Laboratories, Academic Institutions, Research Facilities Application: Infectious Diseases, Genetic Disorders, Cancer Diagnostics, Personalized Medicine |
| Companies Covered | Bio-Rad Laboratories, Thermo Fisher Scientific, F. Hoffmann-La Roche Ltd, Abbott Laboratories, bioMérieux SA, Danaher Corporation, QIAGEN, LGC Limited, Molbio Diagnostics Pvt. Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Molecular Diagnostic Controls Market Shifts & Advancements
Synthetic nucleic acid manufacturing and regulatory localization are compressing traditional supply hierarchies while enabling new domestic production capabilities across India's diagnostic corridors.
Lyophilized synthetic matrix materials are unifying quality control workflows by eliminating cold-chain logistics and standardizing analyte concentrations across PCR, LAMP, and NGS platforms. District-level laboratories in Karnataka are adopting these materials fastest, drawn by ambient-temperature stability that reduces infrastructure investment. This unification is compressing the premium tier that blood-derived controls once commanded in metropolitan chains.
CDSCO's 2023 IVD quality guideline revisions mandate enhanced lot-release documentation and traceability protocols for imported controls. Diagnostic laboratories now face extended procurement cycles for foreign-manufactured materials, accelerating substitution toward BIS-certified domestic suppliers. Maharashtra's reference laboratory networks have responded by qualifying indigenous control vendors ahead of scheduled regulatory deadlines.
Assayed-to-unassayed procurement migration is fragmenting buyer concentration as large reference laboratories internalize target-range characterization. Research facilities in southern India are pioneering custom control development partnerships that bypass commercial catalog limitations. This behavioral shift is most visible in Bangalore's biotechnology cluster, where institutional procurement committees now prioritize flexible sourcing agreements over long-term supply contracts.
India Molecular Diagnostic Controls Market Segmentation
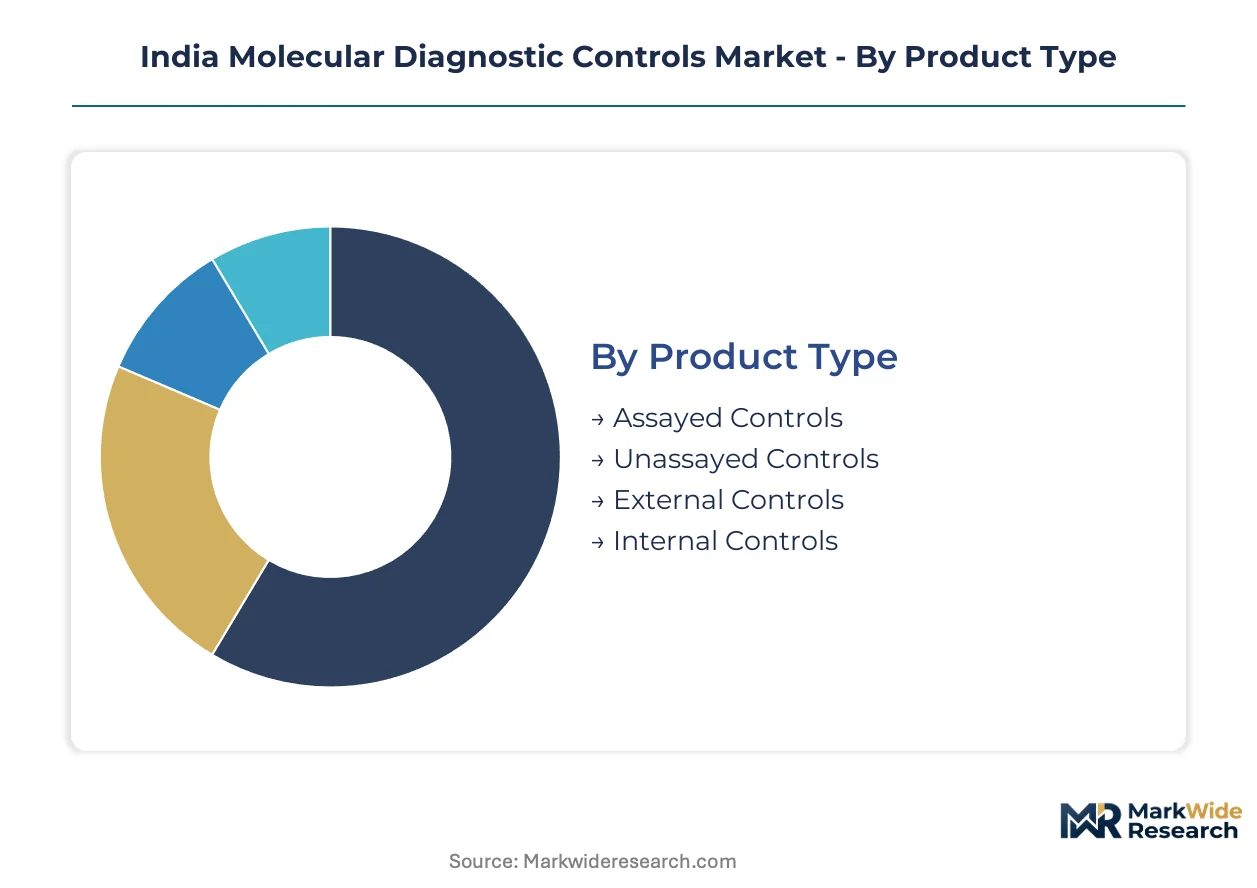
Molecular diagnostic controls in India fragment across four structural dimensions that determine procurement patterns, regulatory pathways, and margin profiles. Each segmentation axis reveals distinct competitive battlegrounds between import-dependent premium tiers and emerging domestic alternatives.
Product Type:
Standalone controls dominate laboratory workflows where external verification is mandatory, while embedded internal controls integrate directly into assay kits for point-of-care deployment.
- Assayed Controls:Pre-characterized nucleic acid preparations with defined target ranges and established measurement uncertainty. Maharashtra's metropolitan diagnostic chains prioritize these materials to streamline CDSCO documentation requirements for infectious disease testing workflows.
- Unassayed Controls:Stabilized nucleic acid matrices without manufacturer-assigned values, requiring in-house characterization. Large reference laboratories in Bangalore and Hyderabad internalize these protocols to reduce per-test quality control costs below commercial assay premiums.
- External Controls:Independent quality verification materials run separately from patient samples. District-level laboratories in Karnataka deploy these for LAMP-TB platform validation under government health program mandates.
- Internal Controls:Co-amplified sequences embedded within diagnostic reactions to detect PCR inhibition or extraction failure. Indigenous kit manufacturers integrate these to satisfy BIS certification requirements for IVD registration.
Volume placements concentrate in Assayed Controls; the faster expansion belongs to Unassayed Controls.
Technology:
Cost tiers separate established amplification methods from capital-intensive sequencing platforms, with district-level applications clustering at the economy tier and reference laboratories absorbing premium technology investments.
- PCR:Thermocycler-dependent amplification remains the backbone of infectious disease diagnostics. Western India's oncology testing corridors deploy PCR controls for multiplexed mutation detection in centralized laboratory networks.
- NGS:Next-generation sequencing demands complex control panels spanning multiple genomic loci. Research facilities in southern India source custom NGS controls to validate variant calling pipelines for cancer genomics applications.
- LAMP:Loop-mediated isothermal amplification eliminates thermal cycler requirements. Government TB control programs across Maharashtra and Karnataka drive procurement of matched indigenous LAMP controls that bypass import licensing delays.
- Microarray:Solid-phase hybridization platforms for high-throughput genotyping. Academic institutions in Bangalore utilize microarray controls for pharmacogenomics research under ICMR-funded initiatives.
PCR captures the largest installed base; LAMP is gaining share fastest through government procurement channels.
End User:
Customer type determines specification intensity, with hospital laboratories demanding turnkey solutions and research facilities tolerating uncharacterized materials for protocol development.
- Hospitals:Clinical laboratories within tertiary care centers require lot-traceable controls for accreditation compliance. CDSCO-mandated documentation drives preference toward BIS-certified domestic suppliers in government hospital networks.
- Diagnostic Laboratories:Independent testing chains and reference networks constitute the primary demand sink. Maharashtra's private diagnostic chains balance cost pressures against ICMR proficiency testing requirements through mixed sourcing strategies.
- Academic Institutions:Medical colleges and universities utilize controls for training and method validation. Southern India's biotechnology clusters source discounted materials through institutional procurement frameworks.
- Research Facilities:Specialized genomics and molecular biology centers develop custom control formulations. Bangalore's research institutes increasingly partner with domestic manufacturers for synthetic nucleic acid production.
Diagnostic Laboratories absorb the highest absolute volumes; Research Facilities are expanding most quickly through custom development partnerships.
Application:
Disease-specific demand concentrates in government priority programs and emerging precision medicine corridors, with procurement authority fragmented across public health budgets and private oncology networks.
- Infectious Diseases:Controls for HIV, hepatitis, and tuberculosis diagnostics dominate procurement volumes. Karnataka's district laboratories prioritize lyophilized synthetic matrices for ambient-temperature storage in TB testing workflows.
- Genetic Disorders:Carrier screening and prenatal diagnostic controls serve specialized referral centers. Western India's concentrated genetic counseling infrastructure drives demand for multiplexed control panels.
- Cancer Diagnostics:Oncology companion diagnostic controls for targeted therapy selection command premium pricing. Mumbai-Pune corridor laboratories invest in mutation-specific controls for EGFR, ALK, and BRAF testing.
- Personalized Medicine:Pharmacogenomics and minimal residual disease monitoring require custom control development. Research collaborations in Hyderabad and Bangalore pioneer patient-derived reference materials for precision oncology applications.
Infectious Diseases anchor current procurement volumes; Cancer Diagnostics demonstrate the steepest expansion trajectory as molecular profiling becomes standard of care.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Maharashtra's pharmaceutical special economic zones concentrate diagnostic manufacturing capacity alongside Karnataka's biotechnology corridors, anchoring procurement networks for molecular diagnostic controls across western and southern India.
Maharashtra
Mumbai-Pune corridor laboratories drive demand for oncology companion diagnostic controls in targeted therapy selection. CDSCO's tightened IVD quality guidelines accelerate BIS-certified domestic supplier qualification ahead of regulatory deadlines. Metropolitan diagnostic chains in Mumbai balance cost pressures against ICMR proficiency testing requirements through mixed sourcing strategies.
Karnataka
Bangalore's biotechnology cluster pioneers custom control development partnerships that bypass commercial catalog limitations. District-level laboratories adopt lyophilized synthetic matrices fastest for ambient-temperature storage in TB testing workflows. Research facilities increasingly prioritize flexible sourcing agreements over long-term supply contracts.
Telangana
Hyderabad's life sciences infrastructure supports precision oncology applications through patient-derived reference material development. PLI scheme eligibility for domestic control manufacturers gains traction among emerging suppliers seeking tariff advantages. Genome Valley research collaborations stimulate specialized demand for multiplexed mutation detection panels.
Gujarat
Ahmedabad-Surat pharmaceutical networks expand diagnostic reagent manufacturing into quality control materials for infectious disease testing. State industrial policy incentives attract synthetic nucleic acid producers seeking alternative locations to Maharashtra-Karnataka concentration. Emerging laboratory networks in tier-2 cities create price-sensitive demand for unassayed control categories.
Tamil Nadu
Chennai's medical device manufacturing base extends into diagnostic consumables as PLI scheme benefits redirect investment from import-dependent models. Government hospital laboratory networks prioritize BIS-certified controls for accreditation compliance under tightened material traceability standards. Academic medical centers develop institutional procurement frameworks for training and method validation materials.
India Molecular Diagnostic Controls Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with multinational assay manufacturers commanding premium positioning in metropolitan diagnostic chains while domestic synthetic biology specialists capture district-level price-sensitive procurement. The vendor base concentrates around three strategic archetypes: global life sciences conglomerates with distribution depth, indigenous platform developers with regulatory localization advantages, and emerging synthetic matrix specialists with ambient-stability value propositions. Competitive moves center on CDSCO pre-qualification partnerships and lyophilization capacity expansion.
Within the premium-tier vector, Bio-Rad Laboratories and Thermo Fisher Scientific occupy positions defined by distribution network reach and multiplexed panel R&D intensity respectively. Molbio Diagnostics Pvt. Ltd exemplifies the indigenous specialist archetype competing aggressively on price-point for point-of-care applications. These three anchors illustrate the market's structural tension between import-dependent quality assurance and domestic production incentives.
| Leading Market Players |
|---|
| Bio-Rad Laboratories |
| Thermo Fisher Scientific |
| F. Hoffmann-La Roche Ltd |
| Abbott Laboratories |
| bioMérieux SA |
| Danaher Corporation |
| QIAGEN |
| LGC Limited |
| Molbio Diagnostics Pvt. Ltd |
| Others |
Supply & Pricing Matrix
ICMR proficiency testing mandates for diagnostic laboratories across Maharashtra and Karnataka are forcing procurement committees to maintain larger safety stocks of quality control materials, compressing supplier lead times and inflating premiums for rapid-turnaround inventory. This demand-side pressure is reshaping how domestic manufacturers configure lyophilization capacity and cold-chain logistics to capture price premiums from accreditation-urgent buyers.
Pricing Analysis
Short lead-time premiums dominate contract negotiations as laboratories facing CDSCO audit cycles pay substantial markups for BIS-certified domestic inventory versus imported alternatives with extended lot-release timelines. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and cold-chain dependency, with lyophilized synthetic matrices commanding top tier positioning. Pricing pressure stems from large reference laboratories internalizing unassayed control characterization, eroding commercial assay premiums. District-level government laboratories exhibit highest price sensitivity, while metropolitan oncology chains absorb premium pricing for mutation-specific multiplexed panels.
Supply Chain Analysis
Single-source vulnerability sits with recombinant nucleic acid precursor suppliers concentrated in the United States, Germany, and China, where specialized fermentation capacity for stabilized RNA matrices remains limited. Domestic Indian manufacturers draw from imported synthetic oligonucleotide building blocks, lyophilization excipients, and precision dispensing equipment to assemble finished controls. Tariff exposure on BIS-uncertified imports creates regulatory friction that delays supply to diagnostic chains. Distribution runs through authorized distributors serving metropolitan laboratory networks, with direct manufacturer relationships penetrating tier-2 and tier-3 district facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Domestic lyophilization capacity constraints are propping pricing power for qualified suppliers, creating supply-constrained conditions that favor early movers in BIS certification pipelines.
For Market Incumbents: To counter large reference laboratories internalizing unassayed control characterization, Bio-Rad and Thermo Fisher should deepen backward integration into synthetic nucleic acid production within Indian pharmaceutical special economic zones. Capacity addition in Maharashtra-based lyophilization facilities would compress lead times for accreditation-urgent buyers. CDSCO pre-qualification partnerships with emerging domestic vendors can extend channel control into district-level procurement. For New Entrants and Emerging Players: District government health programs represent the most penetrable segment, with LAMP-TB platform integration creating demand for ambient-stable indigenous controls that bypass import licensing delays. Karnataka's tier-2 city laboratory networks offer white-space expansion for price-competitive unassayed control suppliers. Go-to-market execution should prioritize flexible sourcing agreements over long-term supply contracts to match Bangalore research facility procurement preferences. For Investors and Strategic Acquirers: The window for entry favors synthetic matrix specialists with ambient-stability intellectual property and BIS certification pipelines already initiated. Over the projection horizon, consolidation around lyophilization capacity and regulatory localization capabilities will determine competitive viability. Acquisition target archetype: domestic manufacturers with CDSCO pre-qualified control panels and established Maharashtra or Karnataka distribution relationships. The signal to watch is PLI scheme eligibility expansion for molecular diagnostic control manufacturing.| Strategic Initiative | Industry Significance |
|---|---|
| CDSCO Pre-Qualification Partnership | Accelerates BIS certification timelines for domestic control manufacturers seeking to displace imports. |
| Lyophilization Capacity Expansion | Captures premium pricing from laboratories requiring ambient-stable synthetic matrices for district-level deployment. |
| Backward Integration into Synthetic Nucleic Acids | Reduces dependency on US, German, and Chinese precursor suppliers while improving batch-to-batch consistency. |
| LAMP-TB Platform Control Development | Aligns with government health program procurement mandates across Maharashtra and Karnataka laboratory networks. |
| Flexible Sourcing Agreement Framework | Matches Bangalore research facility procurement preferences and captures custom control development partnerships. |
Research Methodology
CDSCO regulatory filings, ICMR proficiency testing circulars, and BIS certification databases formed the secondary backbone for supply-side mapping and regulatory timeline analysis. Primary interviews with diagnostic laboratory quality managers, IVD procurement officers at hospital networks, synthetic biology R&D directors, and PLI scheme implementation officers at state industrial development corporations validated demand assumptions and pricing dynamics. Bottom-up and top-down triangulation reconciled manufacturer capacity disclosures with end-user inventory cycle data.
Bottom-up modeling anchored volume projections in segment-level adoption curves across PCR, NGS, LAMP, and microarray technology platforms, while top-down cross-checks applied healthcare expenditure elasticity assumptions. Segmentation dimensions spanned product type, technology, end user, and application with regional regulatory cluster differentiation. CAGRs were derived from fitted growth curves calibrated to historical procurement patterns and policy intervention timelines. Forecast inputs incorporated PLI scheme uptake trajectories and CDSCO guideline revision implementation lags.
Caveats apply where CDSCO enforcement intensity, PLI scheme eligibility expansion, or synthetic precursor supply disruptions could materially shift the outlook. Forecasts reflect assumptions about regulatory localization pace and district laboratory infrastructure buildout that remain sensitive to state health budget allocations. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Global Immunoassay Market
Diagnostics
Global Prostate Specific Antigen (PSA) Test Market
Diagnostics
Psychosis Diagnostics Market
Diagnostics
North America and Europe Companion Animal Diagnostics Imaging Market
Diagnostics
Meningitis Diagnosis and Treatment Market
Diagnostics
In Vitro Diagnostic Antibodies Market
Diagnostics
Middle East and Africa Ovarian Cancer Diagnostics Market
Diagnostics
Veterinary Rapid Diagnostic Tests Market
Diagnostics
Diagnostic Exosome Biomarkers Market
Diagnostics
Global Phytopathological Disease Diagnostics Market
Diagnostics
Microdialysis Market
Diagnostics
Cancer IVD Market
Diagnostics
Melioidosis Diagnostic Market
Diagnostics
Fertility Testing Devices Market
Diagnostics
Cancer Tissue Diagnostics Market
Diagnostics
Global Inflammatory Bowel Disease (IBD) Diagnostic Market