
 Global Women's Health Diagnostics Market | 2026-2036
Global Women's Health Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Women's Health Diagnostics Market Foresight
Hospital procurement consolidation is collapsing the traditional independent laboratory channel. Large health systems now negotiate enterprise-wide diagnostic contracts that bundle imaging, molecular testing, and digital pathology. Abbott Laboratories leverages its point-of-care portfolio to anchor shelf space in emerging market clinics. Hologic, Inc. dominates breast tomosynthesis installations through dedicated field service density. Siemens Healthineers AG extends its imaging informatics platform to connect radiology workflows with laboratory data streams.
Women's health diagnostics encompasses clinical assays, imaging modalities, and molecular platforms designed to detect, monitor, and predict conditions specific to female physiology, including hormonal profiling through chemiluminescent immunoassay and fetal aneuploidy screening via cell-free DNA analysis. These technologies serve obstetric risk management, gynecologic oncology surveillance, and reproductive endocrinology decision-making across inpatient, outpatient, and decentralized settings. Prenatal testing commands premium pricing due to non-invasive sequencing workflows and genetic counselor dependency. Imaging solutions sustain recurring revenue through equipment leases and contrast media contracts. Infectious disease diagnostics competes on turnaround time in sexually transmitted infection panels, where same-day results alter prescribing behavior.
FDA premarket review pathways, EMA companion diagnostic guidelines, and WHO prequalification standards collectively determine market access timelines and reimbursement eligibility for novel biomarker assays. The FDA's evolving stance on artificial intelligence-enabled cytology screening creates uncertainty for algorithm developers seeking De Novo classification. Stakeholders must monitor how payer coverage policies for multi-cancer early detection tests intersect with established cervical and breast screening paradigms.
Market Dynamics
Hospital laboratory consolidation is collapsing the independent reference channel as integrated health networks bundle molecular testing, imaging, and digital pathology into enterprise contracts spanning multi-state footprints.
Growth Catalysts
- Cell-free DNA sequencing:Non-invasive prenatal testing workflows command premium reimbursement through genetic counselor networks in the United States.
- FDA De Novo pathway expansion:Artificial intelligence-enabled cytology screening algorithms gain market access through novel device classification.
- Point-of-care decentralization:Chemiluminescent immunoassay platforms migrate into obstetric clinics across India and Brazil.
Market Restraints
- Reimbursement compression:CMS physician fee schedule revisions squeeze margins on established cervical cytology screening.
- Supply concentration in sequencing reagents:Three vendors control polymerase and library preparation kit manufacturing.
- Genetic counselor workforce scarcity:Interpretation bottlenecks limit throughput for complex variant reporting in hereditary cancer panels.
Strategic Opportunities
- Multi-cancer early detection:Blood-based methylation assays intersect with established breast and ovarian surveillance paradigms in Germany.
- EMA companion diagnostic guidelines:Parallel drug-test development creates co-commercialization pathways for PARP inhibitor pairings.
- Remote patient monitoring integration:Home-based hormonal profiling connects to fertility clinic dashboards through Bluetooth-enabled readers.
Industry Challenges
- Laboratory information system interoperability:Legacy HL7 v2 interfaces require expensive middleware upgrades to receive structured genomic results.
- Variant of uncertain significance resolution:Ambiguous genetic findings demand costly confirmatory testing and extended clinical counseling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Women's Health Diagnostics Market |
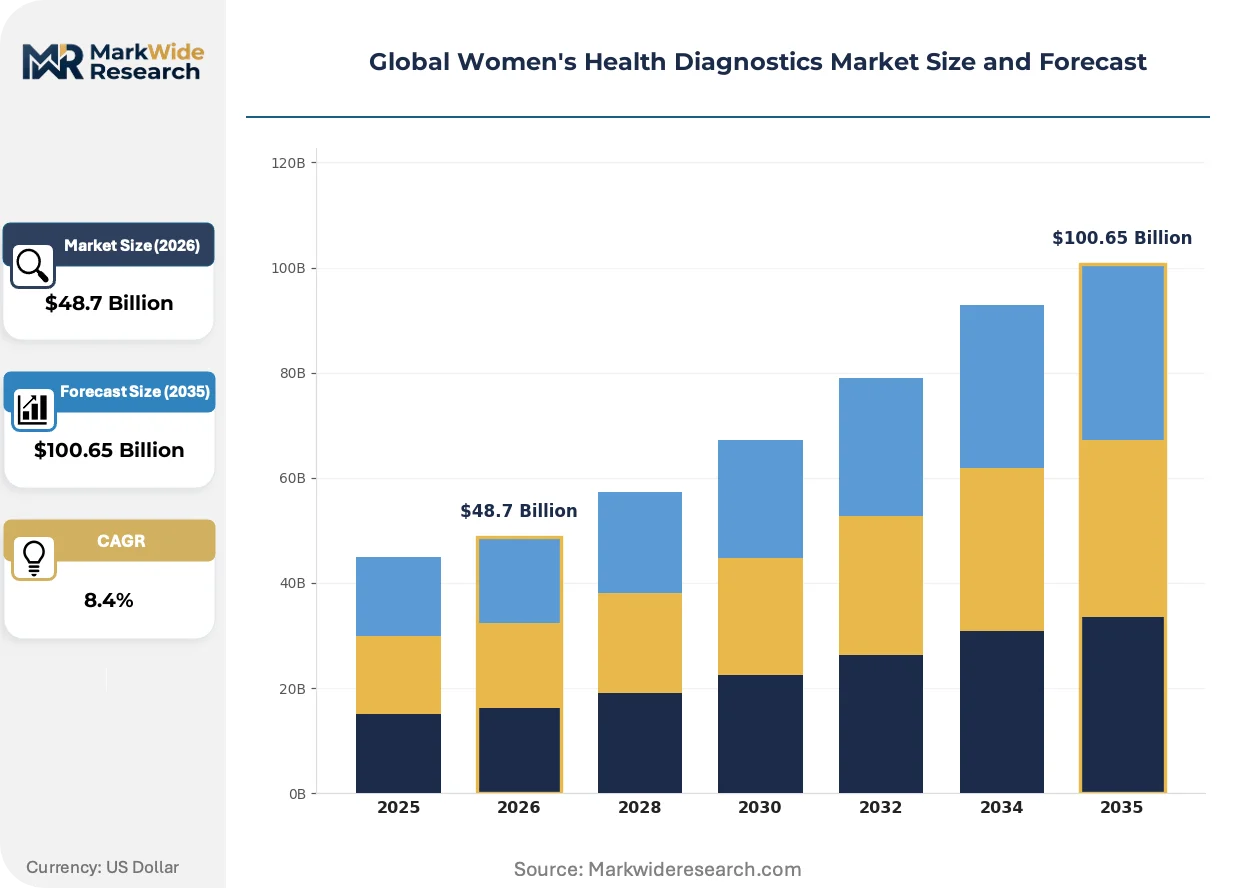
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $100.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hormonal Assays, Genetic Testing Kits, Imaging Solutions, Infectious Disease Diagnostics, Prenatal Testing, Biochemical Markers Application: Fertility Monitoring, Menopause Management, Osteoporosis Detection, Breast Screening, Cervical Cancer Screening, Endometriosis Diagnosis End User: Specialty Clinics, Diagnostic Laboratories, Home Care, Academic Research Institutes, Independent Testing Centers, Telehealth Providers Technology: Immunoassay, Polymerase Chain Reaction, Next-Generation Sequencing, Ultrasound Imaging, Enzyme-Linked Immunosorbent Assay, Flow Cytometry |
| Companies Covered | Abbott Laboratories, Hologic, Inc., GE HealthCare, F. Hoffmann-La Roche Ltd, Becton Dickinson and Company, Koninklijke Philips N.V., Quest Diagnostics, Siemens Healthineers AG, Thermo Fisher Scientific Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Women's Health Diagnostics Market Shifts & Advancements
Artificial intelligence classification, regulatory pathway evolution, and procurement centralization are compressing traditional commercialization timelines while opening new access points for molecular platforms.
Cell-free DNA analysis is bifurcating prenatal screening into high-risk referral centers and routine obstetric practices. Academic medical centers deploy whole-genome sequencing for rare disease detection while community hospitals adopt targeted aneuploidy panels. This technology is bifurcating the market into premium comprehensive offerings and standardized screening commodities.
EMA's In Vitro Diagnostic Regulation implementation is forcing retrospective reclassification of legacy gynecologic assays. Manufacturers face compressed timelines to renew technical documentation and clinical evidence packages. Breast cancer biomarker tests face the steepest compliance burden as notified body capacity concentrates in Germany and the Netherlands.
Health system procurement teams now unbundle equipment leases from consumable contracts to optimize total cost of ownership. Radiology departments negotiate separate digital pathology agreements from laboratory service lines. This pattern is most visible in United States integrated delivery networks consolidating vendor relationships across twelve or more hospital campuses.
Global Women's Health Diagnostics Market Segmentation
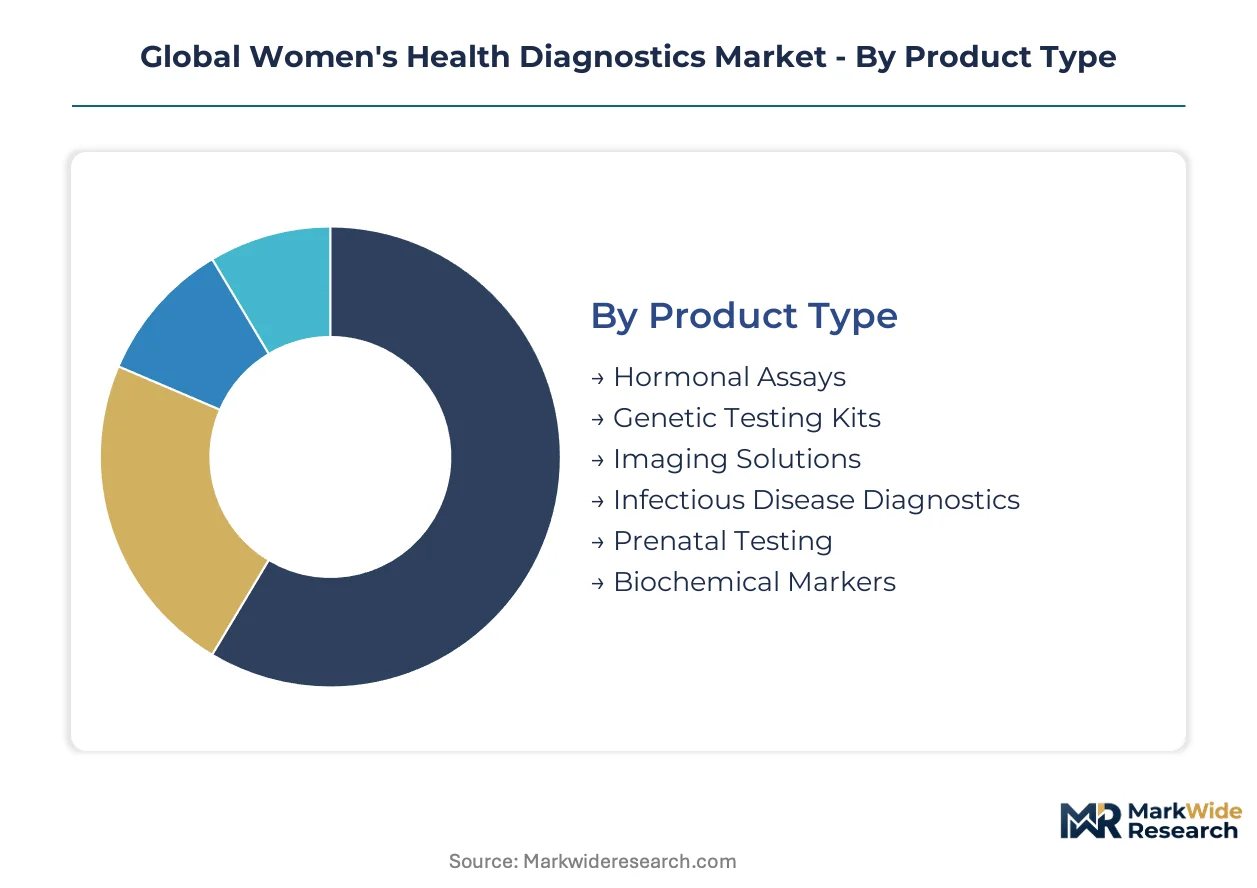
Segmentation reveals how procurement consolidation and technology migration are restructuring commercial pathways across diagnostic modalities. Hospital systems now bundle cross-category contracts, while point-of-care decentralization opens alternative access channels in obstetric and gynecologic settings.
Product Type:
Domestic demand concentrates in imaging and biochemical platforms, while genetic testing kits and prenatal assays follow export-led patterns into emerging markets with expanding private healthcare infrastructure.
- Imaging Solutions:Breast tomosynthesis and ultrasound systems anchor enterprise procurement contracts across United States integrated delivery networks. Field service density determines vendor selection in multi-hospital deployments spanning twelve or more campuses.
- Prenatal Testing:Cell-free DNA sequencing workflows command premium positioning through genetic counselor networks in high-risk referral centers. Community hospitals adopt targeted aneuploidy panels while academic centers deploy whole-genome sequencing for rare disease detection.
- Hormonal Assays:Chemiluminescent immunoassay platforms migrate into obstetric clinics across India and Brazil, driving point-of-care decentralization.
- Genetic Testing Kits:Hereditary cancer panels face interpretation bottlenecks from genetic counselor workforce scarcity in Germany and the Netherlands.
- Infectious Disease Diagnostics:Sexually transmitted infection panels compete on turnaround time where same-day results alter prescribing behavior.
- Biochemical Markers:Osteoporosis and metabolic indicators sustain recurring revenue through equipment leases and reagent contracts.
Imaging solutions command the established base. The steepest expansion runs through prenatal testing.
Application:
Cost tier stratification separates premium molecular surveillance from standardized screening commodities, with reimbursement compression squeezing margins on established cytology workflows.
- Breast Screening:Digital mammography and tomosynthesis installations generate recurring service revenue through multiyear equipment leases. FDA De Novo pathway expansion for artificial intelligence-enabled cytology screening creates novel classification opportunities for algorithm developers.
- Fertility Monitoring:Home-based hormonal profiling connects to clinic dashboards through Bluetooth-enabled readers, integrating remote patient monitoring into treatment protocols. Demand concentrates in private fertility networks across Spain and Italy.
- Cervical Cancer Screening:CMS physician fee schedule revisions compress margins on established Pap smear and HPV testing workflows.
- Prenatal and Genetic Screening:Non-invasive sequencing workflows require genetic counselor interpretation, creating throughput constraints in high-volume markets.
- Menopause Management:Hormonal profiling supports treatment decisions in specialty clinics with dedicated reproductive endocrinology services.
- Osteoporosis Detection:Dual-energy x-ray absorptiometry anchors bone health surveillance in Medicare-eligible populations.
- Endometriosis Diagnosis:Laparoscopic confirmation remains standard, with biomarker development seeking non-invasive alternatives.
Breast screening absorbs the largest equipment investment. Fertility monitoring is gaining share fastest through home-based technology integration.
End User:
Customer type fragmentation reflects procurement centralization at the top and point-of-care decentralization at the bottom, with telehealth providers emerging as a distinct channel for remote monitoring integration.
- Diagnostic Laboratories:Hospital laboratory consolidation collapses the independent reference channel as integrated health networks bundle molecular testing, imaging, and digital pathology into enterprise contracts. Multi-state footprints concentrate purchasing decisions among three to five vendor relationships.
- Home Care:Bluetooth-enabled readers and self-collection kits bypass traditional clinical access points for fertility and hormonal monitoring. Regulatory clarity from FDA and Health Canada determines market entry timelines for direct-to-consumer genetic tests.
- Specialty Clinics:Obstetric and gynecologic practices adopt targeted aneuploidy panels and rapid STI diagnostics.
- Academic Research Institutes:Whole-genome sequencing for rare disease detection drives technology evaluation partnerships.
- Independent Testing Centers:Marginalized by health system procurement consolidation, surviving operators specialize in rapid turnaround or esoteric testing.
- Telehealth Providers:Remote patient monitoring integration creates demand for home-based sample collection and digital result delivery platforms.
Diagnostic laboratories command the established base. The steepest expansion runs through home care.
Technology:
Maturity curves separate established immunoassay platforms from emerging sequencing workflows, with supply concentration in polymerase and library preparation kits creating procurement risk for NGS-dependent assays.
- Next-Generation Sequencing:Cell-free DNA analysis bifurcates into premium comprehensive offerings and standardized screening commodities. Three vendors control polymerase and library preparation kit manufacturing, concentrating supply risk.
- Immunoassay:Chemiluminescent platforms anchor hormonal profiling with established reimbursement pathways and mature supply chains. Point-of-care migration into obstetric clinics across India and Brazil extends addressable market reach.
- Polymerase Chain Reaction:Rapid turnaround capabilities sustain infectious disease diagnostic competitiveness where same-day results alter prescribing behavior.
- Ultrasound Imaging:Equipment leases and contrast media contracts generate recurring revenue streams in breast and prenatal applications.
- Enzyme-Linked Immunosorbent Assay:Cost-positioned alternatives to chemiluminescence in resource-constrained settings.
- Flow Cytometry:Specialized applications in hematologic and immunologic monitoring within academic medical centers.
Immunoassay commands the established base. The steepest expansion runs through next-generation sequencing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sequencing reagent manufacturing concentrates among three vendors in the United States, Germany, and China, concentrating supply risk for cell-free DNA workflows. Diagnostic procurement decisions increasingly centralize within integrated health networks spanning multi-state footprints. Regulatory divergence across FDA, EMA, and China's NMPA creates fragmented market access timelines for molecular platforms.
United States
Hospital laboratory consolidation bundles molecular testing, imaging, and digital pathology into enterprise contracts across twelve or more campuses. FDA premarket review pathways and CMS physician fee schedule revisions determine reimbursement eligibility for novel biomarker assays. The Greater Boston and San Francisco Bay Area clusters anchor academic medical center adoption of whole-genome sequencing for rare disease detection.
Germany
EMA companion diagnostic guidelines and In Vitro Diagnostic Regulation implementation drive retrospective reclassification of legacy gynecologic assays. Notified body capacity concentrates in Germany and the Netherlands, creating compliance bottlenecks for breast cancer biomarker tests. The Rhine-Ruhr and Munich metropolitan regions host diagnostic manufacturers renewing technical documentation packages under compressed timelines.
China
Point-of-care chemiluminescent immunoassay platforms extend into obstetric clinics across tier-two and tier-three cities. NMPA oversight of artificial intelligence-enabled cytology screening creates uncertainty for algorithm developers seeking market authorization. The Yangtze River Delta and Pearl River Delta clusters concentrate domestic manufacturing of hormonal profiling equipment for export to Southeast Asian markets.
India
Private healthcare infrastructure expansion in Maharashtra and Karnataka drives import demand for prenatal testing kits and imaging systems. CDSCO regulatory pathways for in vitro diagnostics remain fragmented across central and state jurisdictions. Mumbai and Bangalore host diagnostic service providers negotiating enterprise contracts with emerging corporate hospital chains.
Brazil
Rapid sexually transmitted infection diagnostics compete on turnaround time in São Paulo and Rio de Janeiro outpatient networks. ANVISA prequalification standards intersect with WHO guidelines for cervical cancer screening program procurement. The São Paulo metropolitan region concentrates independent testing centers specializing in rapid turnaround esoteric testing marginalized by health system consolidation elsewhere.
Global Women's Health Diagnostics Market Competitive Landscape
Concentration sits with diversified medtech conglomerates and specialized diagnostics manufacturers. Hospital procurement consolidation favors vendors with integrated portfolios spanning imaging, molecular testing, and informatics. Three strategic archetypes dominate: imaging-heavy conglomerates with field service density, molecular specialists with sequencing workflows, and point-of-care platform providers. Competitive moves center on enterprise contract anchoring and reagent supply chain vertical integration.
Among United States-based diversified manufacturers, Abbott Laboratories and Hologic, Inc. exemplify contrasting archetypes within hospital procurement networks. Abbott leverages point-of-care portfolio breadth to secure shelf space in decentralized settings. Hologic represents imaging-centric positioning through dedicated field service infrastructure for breast tomosynthesis deployments. Siemens Healthineers AG anchors the European conglomerate tier with imaging informatics platform integration. These three occupy positions across the contract bundling spectrum from equipment leasing to consumable supply agreements.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Hologic, Inc. |
| GE HealthCare |
| F. Hoffmann-La Roche Ltd |
| Becton Dickinson and Company |
| Koninklijke Philips N.V. |
| Quest Diagnostics |
| Siemens Healthineers AG |
| Thermo Fisher Scientific Inc. |
| Others |
Supply & Pricing Matrix
Multi-year enterprise contracts with integrated health networks lock in both sequencing reagent supply access and price visibility across United States hospital systems. These agreements bundle imaging equipment leases, molecular testing consumables, and digital pathology services into single-source arrangements that collapse independent laboratory channels.
Pricing Analysis
Volume-discount tiering structures separate premium comprehensive offerings from standardized screening commodities across prenatal testing workflows. Three-tier pricing structure across premium, standard, and economy levels reflects genetic counselor dependency and turnaround time guarantees. Cost compression in cervical cytology screening intensifies because CMS physician fee schedule revisions squeeze established Pap smear margins. Community hospitals exhibit highest price sensitivity due to constrained capital budgets, while academic medical centers prioritize comprehensive panels regardless of cost.
Supply Chain Analysis
Strategic stockpile preferences dominate for polymerase and library preparation kits given single-source vulnerability in next-generation sequencing workflows. Manufacturing concentrates in the United States, Germany, and China for sequencing reagents and chemiluminescent immunoassay platforms. Supply chains draw from specialized enzymes, optical detection components, and rare earth minerals for imaging systems. Tariff exposure on Chinese-manufactured hormonal profiling equipment creates procurement risk for emerging market clinics. Distribution runs through hospital procurement consortia and GPO contracts in developed markets, with direct manufacturer-to-clinic relationships expanding in India and Brazil.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform-economics inflection centers on laboratory information system interoperability demands that favor vendors with integrated imaging-informatics-molecular portfolios. EHR connectivity and structured genomic data exchange are reshaping competitive positioning.
For Market Incumbents: Compound field service density advantages in breast tomosynthesis installations to anchor enterprise contract renewals. Backward integration into polymerase manufacturing mitigates supply concentration risk from the three dominant reagent vendors. Prioritize middleware development for HL7 FHIR genomic data exchange to defend against software-native entrants.
For New Entrants and Emerging Players: Remote patient monitoring integration for home-based fertility tracking represents an under-served service layer where incumbents lack direct-to-consumer capabilities. Bluetooth-enabled hormonal readers with clinic dashboard connectivity offer the most penetrable entry point. Pursue regulatory clarity from FDA and Health Canada for direct-to-consumer genetic tests before scaling manufacturing.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors molecular specialists with sequencing workflows and point-of-care platform providers with emerging market distribution. Long-term viability hinges on reimbursement strategy execution for multi-cancer early detection tests intersecting with established screening paradigms. Watch EMA companion diagnostic guideline implementation as the inflection indicator for PARP inhibitor pairing opportunities.
| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Enterprise contracts spanning twelve or more campuses lock out independent reference laboratories. |
| Reimbursement Strategy | CMS coverage determinations for cell-free DNA screening dictate addressable market expansion. |
| Software Companion Development | AI-enabled cytology algorithms require De Novo pathway navigation for FDA market authorization. |
| CE Marking Pathway | EMA In Vitro Diagnostic Regulation implementation forces retrospective reclassification of legacy assays. |
| Backward Integration | In-house polymerase production reduces dependency on three-vendor sequencing reagent concentration. |
Research Methodology
The analysis maps imaging modalities, molecular testing platforms, and point-of-care diagnostics, each validated through hospital procurement managers, genetic counselors, biomedical engineers, and GPO contracts managers. Primary interviews with these stakeholders combined with secondary validation against FDA 510(k) filings, EMA CE marking databases, CMS Medicare reimbursement schedules, and hospital procurement databases. Bottom-up and top-down triangulation reconciles equipment installation counts with consumable volume estimates.
Consistency checks validated model outputs against external benchmarks including academic medical center technology adoption surveys and notified body capacity reports. The analytical framework segments by product type, application, end user, and technology across the projection horizon. CAGRs were derived from equipment lease renewal rates and consumable pull-through coefficients. Forecast inputs include genetic counselor workforce growth projections and NMPA authorization timelines for AI-enabled cytology.
Forecasts assume regulatory continuity in FDA premarket review, EMA companion diagnostic guidelines, and NMPA oversight; material policy shifts would require re-modeling. Variant of uncertain significance resolution protocols and payer coverage decisions for multi-cancer early detection represent specific risk factors. Revision becomes warranted when genetic counselor throughput constraints cross thresholds that limit panel interpretation capacity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
North America Thyroid Cancer Diagnostics Market
Diagnostics
Global Non-Small Cell Lung Cancer Diagnostics Market
Diagnostics
North America and Europe Companion Animal Diagnostics Imaging Market
Diagnostics
Anatomic Pathology Market
Diagnostics
US in Vitro Diagnostics Market
Diagnostics
North America Antinuclear Antibody Test Market
Diagnostics
Global Hepatitis Diagnostic Test Market
Diagnostics
Rapid RNA Testing Kits Market
Diagnostics
Immunodiagnostics Market
Diagnostics
Global Rabies Diagnostics Market
Diagnostics
Global Artificial Intelligence (AI) in Diagnostics Market
Diagnostics
Meningitis Diagnosis and Treatment Market
Diagnostics
Global Coagulation Analyzers Market
Diagnostics
Global Lyme Disease Diagnostic Market
Diagnostics
Non-Alcoholic Steatohepatitis (NASH) Biomarkers Market
Diagnostics
Shrimps Disease Diagnostics Market