
 North America Sports Medicine Market | 2026-2036
North America Sports Medicine Market Size, Share, and Industry Trends Forecast 2026-2036
North America Sports Medicine Market Analytics
Polyetheretherketone is recalibrating implant economics across anterior cruciate ligament reconstruction and joint repair procedures. Arthrex leverages its vertically integrated manufacturing in Southwest Florida to control suture anchor quality from polymer to finished device. Smith & Nephew sustains R&D intensity in biologic augmentation, competing with synthetic mesh alternatives through proprietary collagen scaffolding. Stryker anchors its position in arthroscopic instrumentation, dominating the powered shaver segment through hospital system contracts.
Sports medicine encompasses the prevention, diagnosis, treatment, and rehabilitation of athletic injuries through orthopedic devices, biologic therapies, and rehabilitative equipment, typically operating under tensile strength specifications exceeding 50 MPa for load-bearing implants. Its primary commercial purpose is restoring musculoskeletal function in high-activity populations. Surgical devices command the largest revenue pool among product types, reflecting the irreversible shift toward arthroscopic minimally invasive procedures. Rehabilitation applications are expanding fastest as professional athletes and recreational competitors extend career longevity through structured recovery protocols. Online retail channels are capturing share from hospital procurement, though clinics remain the dominant fulfillment node for brace fitting and custom orthotic delivery.
The FDA's 510(k) clearance framework governs implantable device market access, while the Centers for Medicare & Medicaid Services reimbursement schedules directly shape provider adoption of premium biologic products. State-level athletic trainer licensing requirements in Texas and California create fragmented compliance burdens for equipment distributors serving scholastic and collegiate programs. OSHA workplace injury reporting standards indirectly expand corporate wellness program budgets for preventive sports medicine services. Stakeholders must monitor whether CMS moves toward bundled payment models for outpatient joint repair, as this would compress margins for implant manufacturers while favoring integrated service providers.
Market Dynamics
The FDA's evolving oversight of biologic implants is compressing product development timelines while simultaneously fragmenting approval pathways, forcing manufacturers to maintain parallel regulatory strategies for synthetic and tissue-derived devices.
Growth Catalysts
- Professional Sports Infrastructure:Major league franchises in California and Texas are expanding dedicated medical facilities, creating captive demand for arthroscopic instrumentation and rehabilitation equipment.
- 510(k) Clearance Framework:The FDA's streamlined predicate device pathway accelerates market access for incremental implant innovations, reducing time-to-revenue for suture anchors and fixation screws.
- Polyetheretherketone Adoption:This high-performance polymer is displacing metal in load-bearing applications, enabling radiolucent implants that improve post-operative imaging clarity.
Market Restraints
- Biologic Input Volatility:Human tissue and collagen sourcing faces unpredictable donor availability, creating batch-to-batch inconsistency in scaffolding products.
- Reimbursement Compression:CMS outpatient procedure schedules limit provider willingness to adopt premium-priced biologic augmentation over synthetic alternatives.
- State Licensing Fragmentation:Athletic trainer certification requirements vary between Texas and California, complicating equipment distribution to scholastic programs.
Strategic Opportunities
- Corporate Wellness Penetration:OSHA workplace injury reporting standards are expanding employer-funded preventive sports medicine programs beyond traditional athletic populations.
- Online Retail Expansion:Direct-to-consumer channels for braces and compression garments bypass hospital procurement delays, capturing recreational athlete segments.
- Bundled Payment Readiness:Anticipated CMS shifts toward episode-based reimbursement favor integrated service providers capable of spanning diagnosis through rehabilitation.
Industry Challenges
- Specialized Surgical Training:Arthroscopic technique proficiency requires cadaver lab investment and proctored case volumes that strain smaller orthopedic practice economics.
- Supply Chain Reconfiguration:Polymer resin and biologic material dual sourcing demands redundant quality systems, elevating working capital requirements for mid-tier manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Sports Medicine Market |
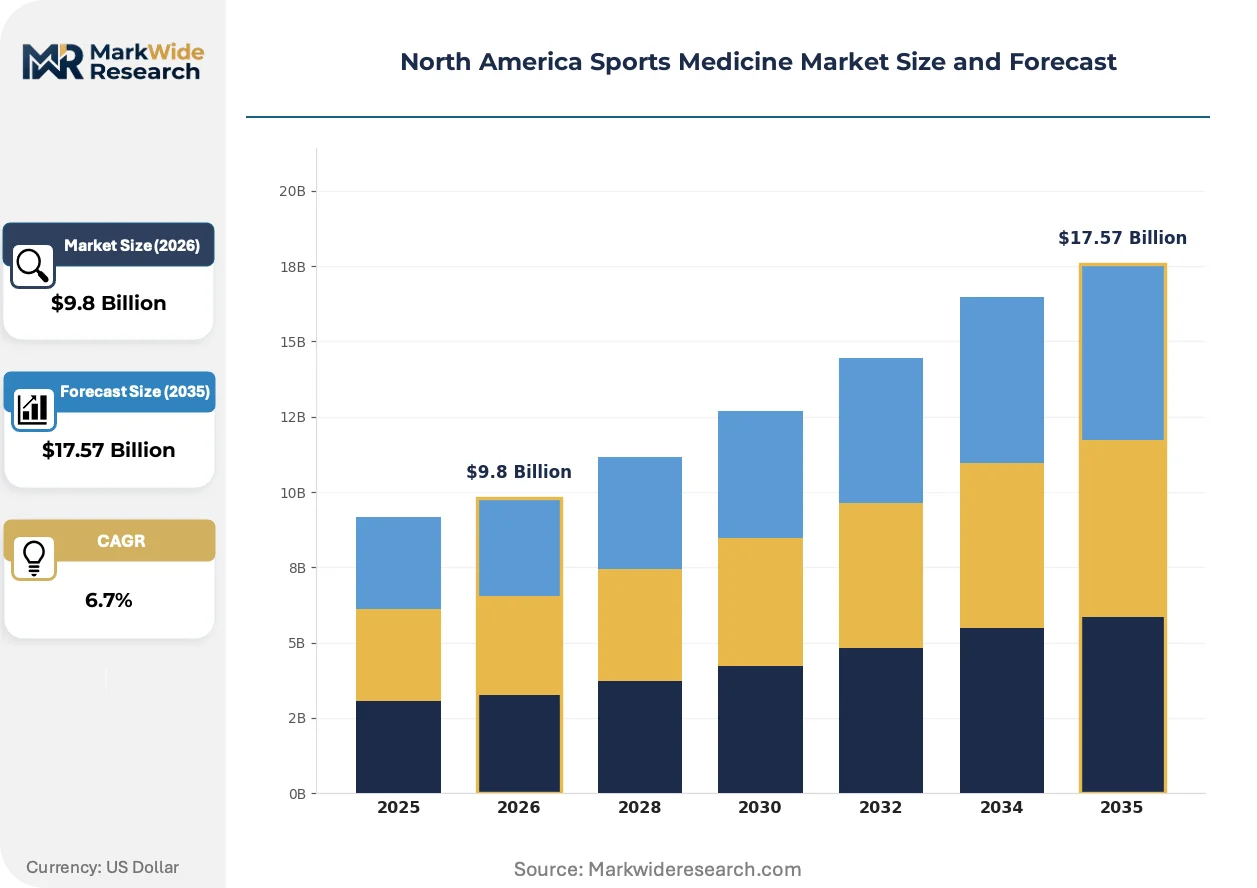
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $17.57 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Braces, Physiotherapy Equipment, Surgical Devices, Implants Distribution Channel: Online Retail, Hospitals, Clinics, Pharmacies End User: Professional Athletes, Recreational Athletes, Coaches, Physical Therapists Application: Injury Prevention, Rehabilitation, Pain Management, Performance Enhancement |
| Companies Covered | Arthrex, Smith & Nephew, DePuy Synthes, Stryker, Zimmer Biomet Holdings, CONMED Corporation, Johnson & Johnson Services, Medtronic, Enovis, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Sports Medicine Market Evolving Landscape
Minimally invasive techniques are absorbing capital and talent from open surgical approaches, while regulatory scrutiny intensifies around biologic-synthetic hybrid implants. Three developments warrant particular attention.
Patient-specific instrumentation is absorbing manufacturing complexity through 3D-printed surgical guides matched to preoperative imaging. Academic medical centers in Texas are adopting these tools for complex revision procedures, compressing operative time and reducing instrument tray sterilization costs. The technology is absorbing share from conventional arthroscopic setups in high-volume joint repair centers.
The FDA's 510(k) Third Party Review Program is expanding eligible device categories, allowing accredited organizations to conduct substantive equivalence determinations. This industrial consequence accelerates clearance timelines for Class II implants while maintaining statutory safety thresholds. Suture anchor manufacturers serving California's outpatient surgery centers are responding by submitting predicates through this alternative pathway.
Direct procurement by collegiate athletic departments is displacing traditional distributor intermediaries for high-volume consumables. Equipment managers at Division I programs now negotiate suture and fixation contracts directly with manufacturers, bypassing regional medical supply houses. This pattern is most visible in Texas and California, where consolidated conference purchasing alliances aggregate demand across multiple institutions.
North America Sports Medicine Market Segmentation
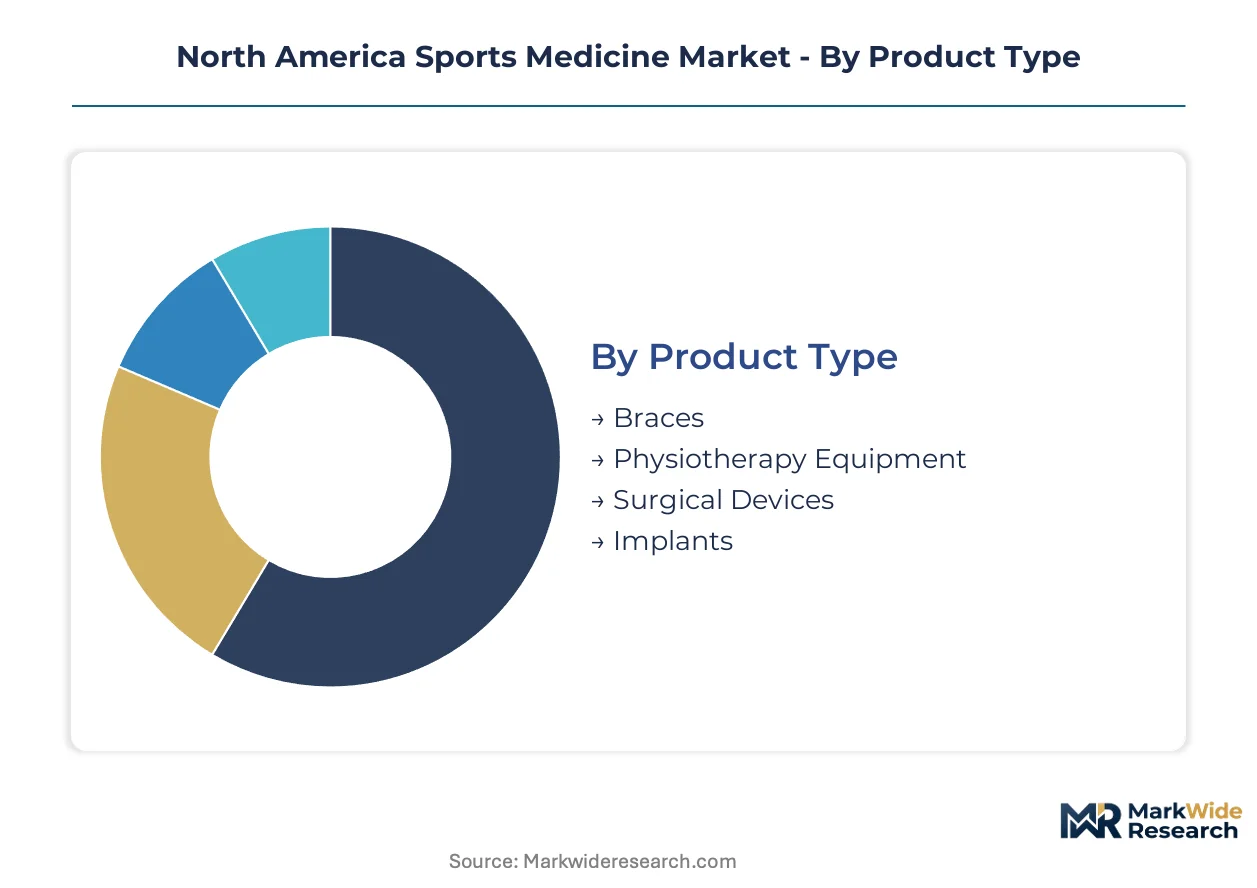
Segmentation in North America sports medicine reveals divergent margin profiles across product categories. Surgical devices and implants command premium pricing through FDA 510(k) regulatory barriers, while rehabilitation equipment scales through volume penetration of athletic training facilities.
Product Type:
Surgical devices anchor revenue concentration through arthroscopic procedure volume, while implants capture margin through material differentiation and biologic augmentation.
- Surgical Devices:Arthroscopic shavers, suture anchors, and fixation systems dominate hospital procurement budgets. Demand clusters in Texas and California where major league training facilities drive procedure volume through captive orthopedic partnerships.
- Implants:Polyetheretherketone and biologic scaffolding compete for load-bearing applications. CMS reimbursement compression favors radiolucent polymer alternatives in outpatient settings across the Southwest and Southeast.
- Braces:Custom-fitted and off-the-shelf stabilization products serve injury prevention and post-operative protocols.
- Physiotherapy Equipment:Modalities and resistance systems support structured recovery programs in collegiate and professional settings.
Mature deployment sits with Surgical Devices. Newer deployment is concentrated in Implants.
Distribution Channel:
Channel selection tracks urgency and customization requirements, with institutional procurement favoring contracted supply relationships.
- Hospitals:Integrated delivery networks negotiate system-wide contracts for implant and device procurement. Texas Medical Center and Cedars-Sinai anchor purchasing concentration through high arthroscopic case volumes.
- Clinics:Orthopedic and sports medicine practices deliver brace fitting and custom orthotic services. California's outpatient surgery center density creates fragmented but high-frequency replenishment demand.
- Online Retail:Direct-to-consumer compression garments and recovery accessories bypass traditional distribution delays.
- Pharmacies:Over-the-counter analgesics and basic support products serve acute injury management.
Established volume flows through Hospitals. Channel expansion is climbing the fastest in Online Retail.
End User:
User type determines product specification intensity, with professional populations demanding performance-optimized solutions.
- Professional Athletes:Career longevity investments drive adoption of premium biologic augmentation and custom-fitted equipment. NFL and MLB franchise medical departments in Dallas-Fort Worth and Los Angeles procure directly from manufacturers.
- Recreational Athletes:Weekend competitors and amateur leagues generate volume demand for braces and rehabilitation accessories. YMCA and municipal recreation programs in Texas and California aggregate this segment.
- Physical Therapists:Licensed practitioners prescribe and supervise recovery protocols using clinic-based equipment.
- Coaches:Scholastic and collegiate programs manage preventive equipment inventory for team sports.
Revenue concentration aligns with Professional Athletes. Participation growth is expanding most quickly among Recreational Athletes.
Application:
Application focus shifts from acute intervention toward sustained performance maintenance as athletic career spans extend.
- Rehabilitation:Structured recovery protocols span surgical recovery and chronic injury management. Academic medical centers in Houston and Stanford deploy patient-specific instrumentation to compress operative timelines.
- Injury Prevention:Pre-habilitation and biomechanical screening reduce downstream surgical incidence. Corporate wellness programs in California integrate these services for non-athletic occupational populations.
- Pain Management:Modalities and pharmacologic adjuncts address acute and chronic musculoskeletal complaints.
- Performance Enhancement:Biomechanical optimization and recovery acceleration serve competitive advantage objectives.
Clinical infrastructure concentrates in Rehabilitation. Service expansion is gaining share fastest in Injury Prevention.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Professional sports infrastructure investments concentrate demand in the United States, with Canada and Mexico expanding through cross-border training partnerships and medical tourism corridors.
United States
California and Texas dominate procedure volume through major league franchise medical facilities and academic orthopedic centers. FDA 510(k) clearance pathways accelerate market access for implant manufacturers serving outpatient surgery centers. The Dallas-Fort Worth metro anchors concentration for arthroscopic instrumentation procurement.
Canada
Provincial health system procurement consolidates demand through Ontario and Quebec hospital networks. Health Canada oversight aligns with FDA predicate device frameworks, easing cross-border product registration for US manufacturers. Toronto's University Health Network drives adoption of patient-specific instrumentation for complex joint revisions.
Mexico
Medical tourism corridors near the US border attract sports injury patients seeking cost-advantaged surgical procedures. COFEPRIS regulatory harmonization with FDA standards streamlines importation of arthroscopic devices. Tijuana and Monterrey cluster ambulatory surgery centers serving North American athlete populations.
North America Sports Medicine Market Competitive Landscape
Portfolio diversification dominates the current landscape as manufacturers balance synthetic polymer and biologic augmentation capabilities. The vendor base separates into three tiers: integrated orthopedic conglomerates with hospital system contracts, mid-tier specialists in arthroscopic instrumentation, and emerging players in direct-to-consumer rehabilitation products. Strategic archetypes include vertically integrated manufacturers controlling polymer-to-device production, biologic-focused developers navigating tissue sourcing volatility, and platform players spanning surgical through rehabilitation segments. M&A activity and capacity expansion in high-performance polymers represent the dominant competitive vectors.
Among the integrated tier, Arthrex exemplifies vertically controlled manufacturing through its Florida-based polymer processing and finished device operations. Smith & Nephew occupies a position within the biologic augmentation archetype, competing against synthetic alternatives through proprietary scaffolding approaches. Stryker anchors the arthroscopic instrumentation segment, maintaining presence in powered shaver systems through hospital procurement relationships. These three represent distinct strategic postures rather than exhaustive market coverage.
| Leading Market Players |
|---|
| Arthrex |
| Smith & Nephew |
| DePuy Synthes |
| Stryker |
| Zimmer Biomet Holdings |
| CONMED Corporation |
| Johnson & Johnson Services |
| Medtronic |
| Enovis |
| Others |
Value Network & Pricing Analysis
Biologic-synthetic implant divergence splits the North America sports medicine market into premium tissue-derived scaffolding and commodity polymer alternatives, with FDA 510(k) clearance tiers determining both reimbursement eligibility and supplier qualification requirements across hospital procurement networks.
Pricing Analysis
Volume concentration in arthroscopic shavers and fixation screws competes with margin capture in patient-specific instrumentation and biologic augmentation. Three-tier pricing structure across premium, standard, and economy levels tracks FDA predicate device complexity and CMS reimbursement codes. Cost compression in synthetic polymer anchors is intensifying because hospital GPOs aggregate demand across integrated delivery networks. Recreational athletes and municipal recreation programs exhibit highest price sensitivity, while NFL and MLB franchise medical departments prioritize performance outcomes over unit cost.
Supply Chain Analysis
Dual-sourcing mandates from hospital procurement committees require qualified backup suppliers for polyetheretherketone resin and collagen scaffolding inputs. Manufacturing concentrates in the United States, Switzerland, and Ireland for FDA-registered implant production. Raw material dependencies center on high-performance polymer feedstocks, human tissue banking networks, and precision-machined instrumentation components. Single-source vulnerability persists in proprietary suture anchor designs protected by predicate device patents. Distribution runs through integrated delivery network contracts and direct-to-collegiate athletic department channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America sports medicine market is consolidating around vertically integrated manufacturers capable of absorbing FDA regulatory complexity and biologic input volatility that marginalizes pure-play distributors.
For Market Incumbents: Anchor hospital system relationships through exclusive arthroscopic instrumentation contracts that bundle powered shavers with suture anchor replenishment programs. Invest in captive polymer processing capabilities to insulate margin from PEEK resin price swings. Defensive consolidation should target biologic scaffolding specialists facing donor availability constraints. For New Entrants and Emerging Players: Begin with direct-to-consumer rehabilitation accessories and compression garments where brand building bypasses hospital procurement gatekeepers. Online retail channels for recreational athletes offer lowest regulatory barrier to entry. White-space concentration sits with corporate wellness programs serving OSHA-mandated workplace injury prevention. For Investors and Strategic Acquirers: Re-rating potential sits with mid-tier arthroscopic device manufacturers possessing FDA 510(k) clearance pipelines and untapped hospital GPO contracts given anticipated CMS bundled payment shifts. Long-term viability favors platforms spanning surgical intervention through rehabilitation protocols. Watch for FDA Third Party Review Program expansion as signal for accelerated clearance timelines compressing competitive moats.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Third Party Review Submission | Accelerates predicate device clearance for suture anchor manufacturers serving California outpatient centers. |
| Hospital System Partnership | Texas Medical Center and Cedars-Sinai contracts anchor volume concentration for arthroscopic instrumentation. |
| Backward Integration into Polymer Processing | Captive PEEK resin production insulates margin from specialty chemical supplier pricing volatility. |
| Reimbursement Strategy | CMS outpatient procedure code alignment determines provider adoption of premium biologic augmentation. |
| Direct-to-Collegiate Procurement Channel | Bypasses regional medical supply houses through Division I athletic department consolidated purchasing alliances. |
Research Methodology
Multi-period observation of arthroscopic procedure volumes, implant clearance timelines, and rehabilitation equipment procurement patterns anchored the trend analysis, supplemented by interviews with orthopedic surgeons, hospital purchasing committee members, biomedical engineers, and GPO contracts managers. Secondary validation drew from FDA 510(k) database filings, CMS Medicare reimbursement schedules, hospital procurement databases, and SEC filings of publicly traded device manufacturers. Bottom-up demand modeling across surgical devices, implants, braces, and physiotherapy equipment categories was triangulated against top-down market sizing.
Segment-weighting across product type, distribution channel, end user, and application dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from installed base growth, procedure volume trajectories, and pricing trend extrapolation. Industry-specific forecast inputs incorporated FDA review timeline variability and state-level athletic trainer licensing fragmentation effects on equipment distribution.
Underlying measurement precision varies by segment; surgical devices and implants carry tighter precision due to hospital procurement transparency than direct-to-consumer rehabilitation accessories. Forecasts reflect documented assumptions around CMS reimbursement stability, PEEK resin supply continuity, and biologic tissue banking availability. Deviation in FDA biologic implant oversight stringency would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Bartonellosis Therapeutics Market
Specialty Medicine
Hermansky Pudlak Syndrome Therapeutics Market
Specialty Medicine
Piriformis Syndrome Treatment Market
Specialty Medicine
Global Interstitial Cystitis Market
Specialty Medicine
Animal Hormone Therapy Market
Specialty Medicine
TIL Therapy Market
Specialty Medicine
Hairy Cell Leukemia Therapeutics Market
Specialty Medicine
Progressive Pulmonary Fibrosis (PPF) Treatment Market
Specialty Medicine
Ankylosing Spondylitis Treatment Market
Specialty Medicine
HER2 Positive Gastric Cancer Market
Specialty Medicine
Peripheral Neuropathy Market
Specialty Medicine
Facial Paralysis Market
Specialty Medicine
Ovarian Cancer Therapeutics Market
Specialty Medicine
Optic Atrophy Management Market
Specialty Medicine
Odontogenic Tumor Market
Specialty Medicine
Epilepsy Treatment Market