

Swine Disease Diagnostic Kit Market Size, Share, and Industry Trends Forecast 2026-2036
Swine Disease Diagnostic Kit Market Insights
Multiplex nucleic acid amplification is narrowing the gap between centralized laboratory accuracy and point-of-need convenience in swine disease detection. IDEXX Laboratories leverages its veterinary channel density to sustain instrument placement rates across North American hog operations. Zoetis anchors its competitive position through backward integration into assay reagent manufacturing, while Thermo Fisher Scientific competes on the breadth of its PCR chemistry portfolio.
Swine disease diagnostic kits are consumable test systems designed to detect viral, bacterial, or parasitic pathogens in porcine serum, tissue, or oral fluid specimens, typically achieving analytical sensitivity below 10² copies per reaction for nucleic acid targets. Their primary commercial purpose is to enable timely herd health decisions that limit mortality, trade restrictions, and zoonotic transmission risk. ELISA kits retain the largest installed base among veterinary laboratories due to lower per-test cost and minimal equipment requirements, though PCR kits are capturing the fastest expansion as African Swine Fever surveillance intensifies across commercial farms. Lateral flow assays occupy a distinct margin pool in field-side screening where turnaround time outweighs sensitivity thresholds.
The USDA enforces assay validation standards through its National Veterinary Services Laboratories, while the OIE Terrestrial Animal Health Code shapes cross-border test acceptance criteria for international pork trade. China's Ministry of Agriculture and Rural Affairs mandates African Swine Fever reporting through designated diagnostic protocols, directly conditioning kit registration requirements. Stakeholders must monitor how divergent national approval timelines for emergency-use pathogen assays reshape competitive access in outbreak-responsive procurement cycles.
Market Dynamics
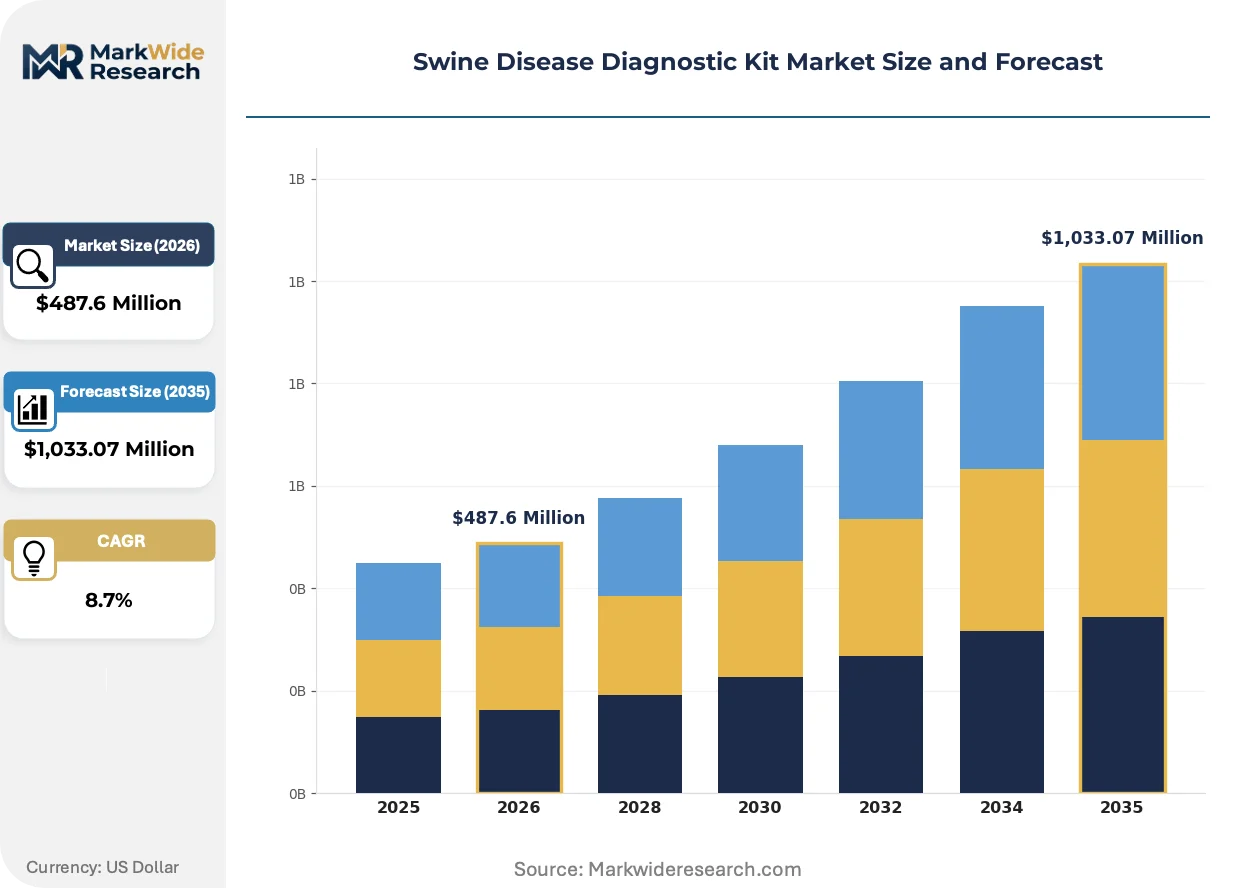
African Swine Fever surveillance mandates across commercial pork operations are compressing test turnaround requirements from days to hours, forcing diagnostic workflows toward point-of-need nucleic acid platforms and away from centralized laboratory batch processing.
Growth Catalysts
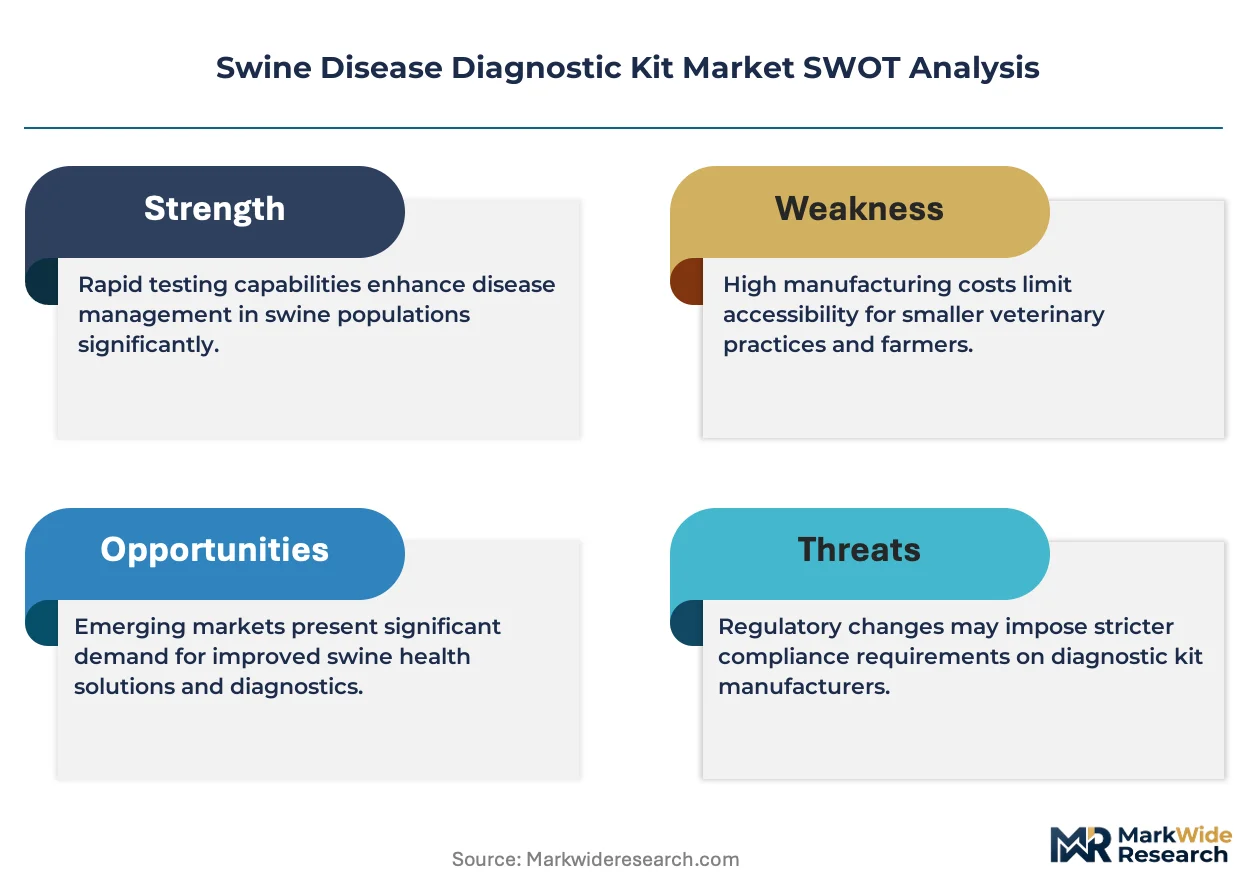
- USDA National Veterinary Services Laboratories validation protocols:Accelerated assay approval timelines for emergency-use pathogens are expanding kit manufacturer access to federal procurement channels.
- Guangdong and Shandong province clustering:Large-scale integrated pig farming operations in these Chinese provinces generate concentrated demand for high-throughput multiplex screening panels.
- CRISPR-based isothermal amplification:Field-deployable nucleic acid detection without thermal cycling infrastructure is extending molecular diagnostic reach to remote veterinary operations.
Market Restraints
- Reagent supply concentration:Taq polymerase and fluorescent probe manufacturing clusters in specific Asian supply zones create vulnerability to regional logistics disruptions.
- USDA National Animal Health Laboratory Network accreditation costs:Quality system compliance requirements impose fixed cost burdens that disadvantage smaller kit manufacturers.
- Lateral flow sensitivity ceilings:Immunoassay detection limits above 10³ copies per milliliter fail to meet early-stage infection screening thresholds required for trade certification.
Strategic Opportunities
- Oral fluid specimen workflows:Non-invasive sample collection methods are opening penetration pathways in sow farm environments where blood draws disrupt production cycles.
- Cloud-connected reader devices:Internet-of-Things integration in point-of-need instruments enables real-time herd health data aggregation for predictive analytics services.
- OIE Terrestrial Animal Health Code harmonization:Cross-border test standardization initiatives are reducing kit registration duplication costs for manufacturers targeting export markets.
Industry Challenges
- Veterinary diagnostic molecular biology expertise gaps:Field technicians lacking PCR troubleshooting competency generate false-negative rates that erode trust in on-farm platforms.
- Legacy ELISA instrument compatibility:Existing installed bases of colorimetric plate readers slow capital replacement cycles for fluorescent detection systems.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Swine Disease Diagnostic Kit Market Trends and Innovations
Digital connectivity and assay miniaturization are collapsing the distance between specimen collection and actionable results, reconfiguring how veterinary diagnostics integrate with farm management software and supply chain traceability systems.
Loop-mediated isothermal amplification (LAMP) chemistry operates at constant temperature without thermal cyclers, enabling battery-powered field devices. Commercial sow farms in Denmark and the Netherlands are deploying these platforms for same-day African Swine Fever screening prior to animal transport. This architecture is virtualizing the laboratory function, compressing infrastructure requirements from climate-controlled facilities to handheld units operable in barn environments.
China's Ministry of Agriculture and Rural Affairs designated diagnostic protocol mandates require real-time PCR confirmation for all suspected African Swine Fever cases, establishing nucleic acid methods as the regulatory gold standard. Kit manufacturers must align assay design with these specific primer-probe sequences to maintain registration validity. The compliance burden falls heaviest on imported diagnostic brands, which face extended validation timelines compared to domestic suppliers with established ministry relationships.
Integrated pork producers are consolidating diagnostic procurement under centralized veterinary service contracts, displacing ad hoc kit purchasing by individual farm managers. This concentration shifts bargaining power toward large-scale operators in Brazil's Mato Grosso and Iowa's corn belt regions, which now demand volume-based pricing and dedicated technical support attachments. The service bundling pressures smaller kit vendors to develop distributor partnerships or exit commercial farm segments entirely.
Swine Disease Diagnostic Kit Market Segmentation
Diagnostic kit segmentation in swine disease detection reflects divergent technical capabilities, cost structures, and regulatory acceptance thresholds across testing environments. Each dimension shapes procurement patterns differently—product type determines capital requirements, technology governs sensitivity specifications, application drives emergency-use authorization priorities, and end user dictates service bundling expectations.
Product Type:
Mature ELISA platforms coexist with emerging point-of-need molecular formats, creating tiered infrastructure demands across veterinary settings.
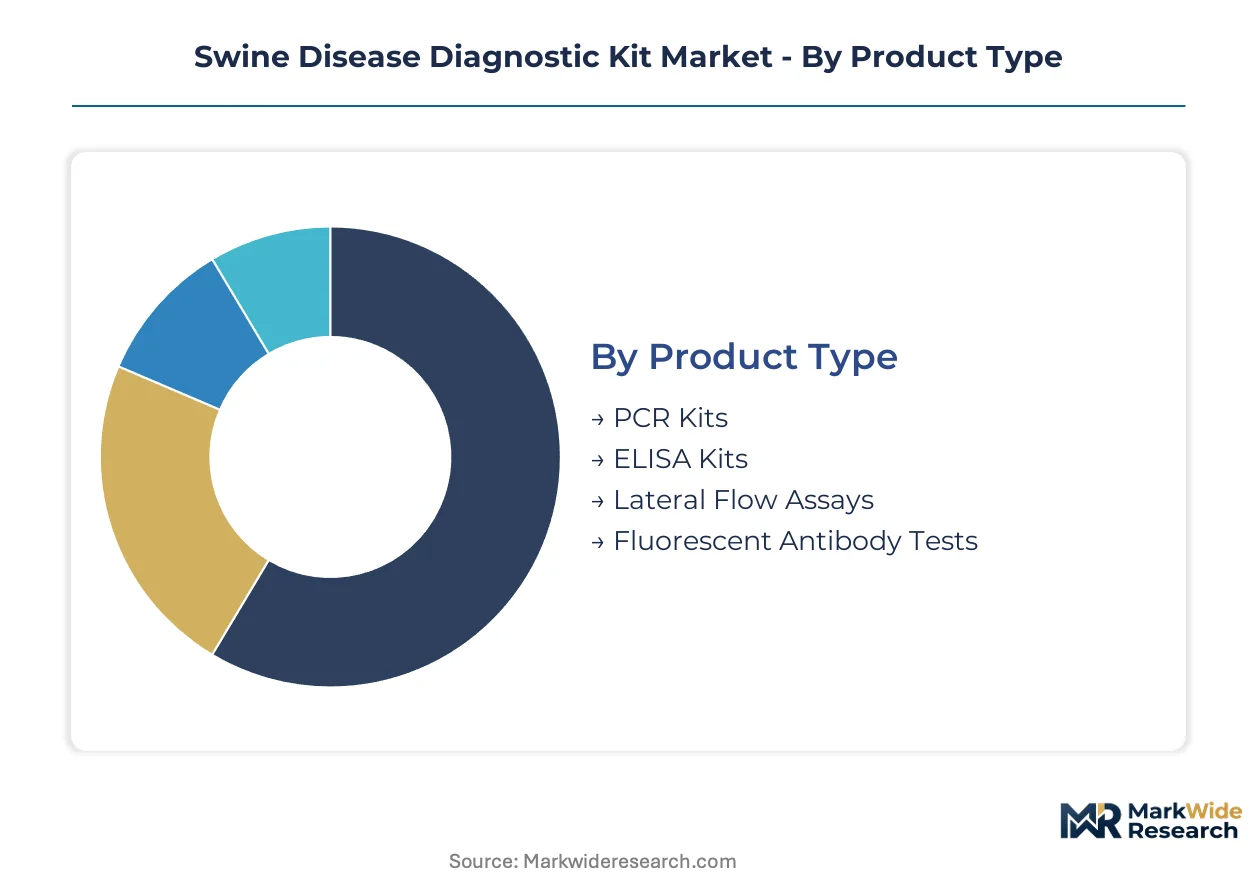
- PCR Kits:Real-time thermal cycling platforms achieve analytical sensitivity below 10² copies per reaction through fluorogenic probe detection. Demand concentrates in China's Guangdong province, where Ministry of Agriculture and Rural Affairs mandates nucleic acid confirmation for African Swine Fever reporting, compressing turnaround requirements to under four hours.
- ELISA Kits:Enzyme-linked immunosorbent assays detect antibody or antigen presence through colorimetric substrate conversion, requiring only standard plate readers. USDA National Veterinary Services Laboratories maintains extensive validation libraries for these platforms, sustaining their dominance in high-volume screening contracts across Iowa and North Carolina commercial operations.
- Lateral Flow Assays:Immunochromatographic strips deliver visual results in fifteen minutes without instrumentation.
- Fluorescent Antibody Tests:Direct immunofluorescence microscopy detects viral antigens in tissue specimens with moderate throughput.
ELISA kits retain volume leadership; PCR kits hold the steepest expansion curve.
Technology:
Cost tier stratification separates capital-intensive thermal cycling infrastructure from minimal-equipment immunoassay alternatives.
- Nucleic Acid Amplification:Polymerase chain reaction and isothermal methods amplify pathogen genetic material for ultrasensitive detection. Loop-mediated isothermal amplification chemistry enables battery-powered field deployment in Denmark's commercial sow farms, eliminating climate-controlled laboratory requirements.
- Immunoassay:Antibody-antigen binding reactions form the operational basis of ELISA and lateral flow platforms, trading sensitivity for cost efficiency and workflow simplicity. These systems dominate veterinary laboratories in Brazil's Mato Grosso region where per-test economics govern procurement decisions.
- Biosensor:Electrochemical and optical transducers convert biological recognition events into quantifiable signals.
- Microarray:High-density probe grids enable simultaneous detection of multiple pathogens on single specimens.
Immunoassay technology commands installed base dominance; nucleic acid amplification is gaining share fastest.
Application:
Geography-specific outbreak dynamics reshape priority rankings among target pathogens, with regulatory mandates directly conditioning kit registration requirements.
- African Swine Fever:Highly contagious hemorrhagic disease with near-total mortality in domestic pigs, triggering strict surveillance protocols. China's designated diagnostic protocol requirements and USDA foreign animal disease preparedness initiatives generate concentrated procurement for validated nucleic acid assays.
- Porcine Reproductive & Respiratory Syndrome:Endemic viral infection causing reproductive failure and respiratory disease, necessitating continuous monitoring in breeding herds. Integrated pork producers in the Netherlands deploy multiplex PCR panels for routine surveillance, bundling diagnostics with veterinary service contracts.
- Swine Influenza:Zoonotic respiratory pathogen with pandemic potential, monitored through antigen detection and subtyping assays.
- Classical Swine Fever:OIE-listed notifiable disease subject to eradication programs in multiple jurisdictions, requiring differential diagnostic capability.
Porcine Reproductive & Respiratory Syndrome retains testing volume leadership; African Swine Fever surveillance shows the steepest procurement acceleration.
End User:
Customer type determines service intensity, with centralized veterinary operations demanding technical support attachments absent from research procurement.
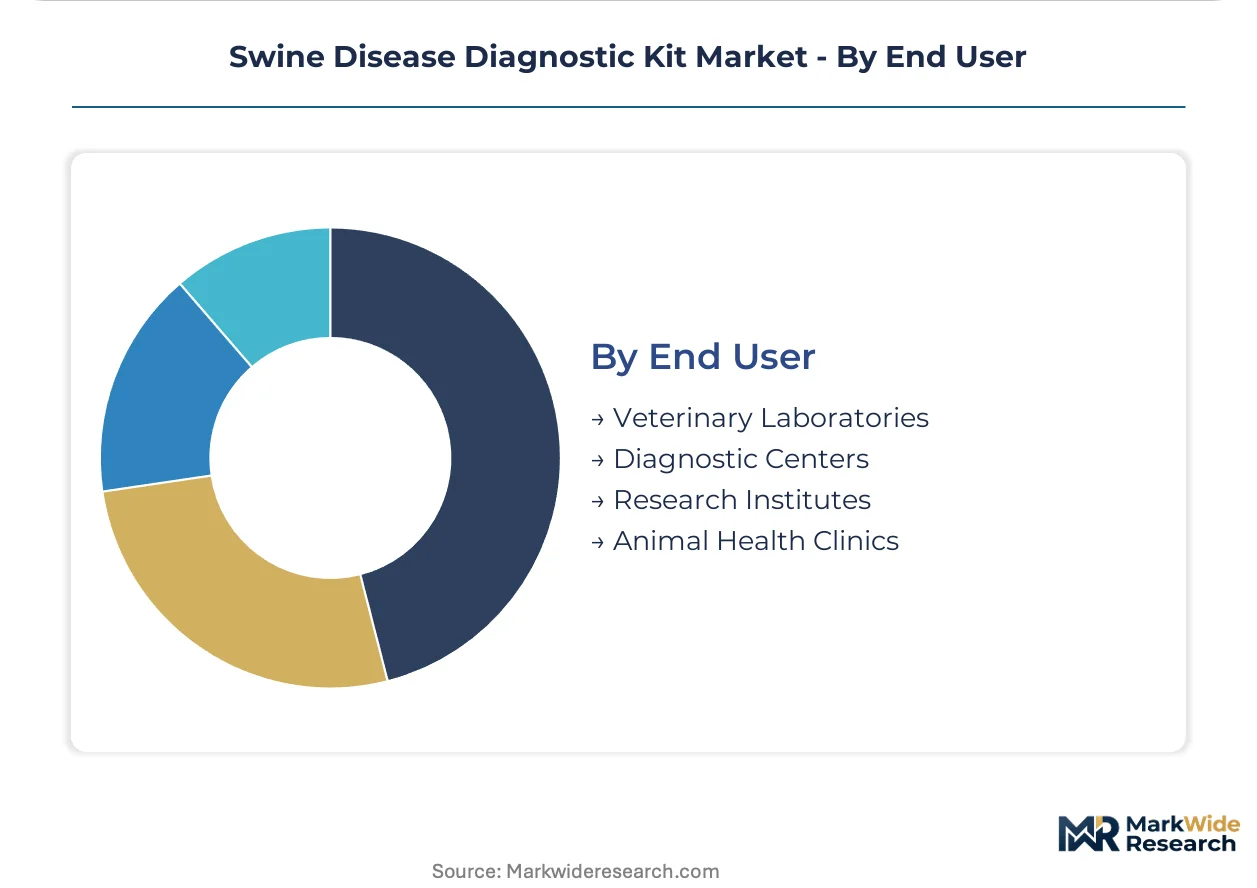
- Veterinary Laboratories:Accredited facilities processing high specimen volumes under quality management systems, typically USDA National Animal Health Laboratory Network certified. These operations in Germany's Lower Saxony region specify automated nucleic acid extraction platforms to maintain throughput during outbreak surges.
- Diagnostic Centers:Regional testing hubs serving multiple farm operations with rapid turnaround requirements. Facilities in Vietnam's Dong Nai province specialize in African Swine Fever screening for smallholder cooperatives, bridging centralized laboratory accuracy with distributed access needs.
- Research Institutes:Academic and government facilities conducting assay development, validation studies, and epidemiological surveillance.
- Animal Health Clinics:Field-based practitioners requiring portable equipment for on-farm decision support.
Veterinary laboratories retain volume leadership; diagnostic centers are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports veterinary diagnostic instruments to Denmark's commercial sow farms, while China sources PCR reagents from domestic manufacturers in Guangdong province to meet African Swine Fever surveillance mandates.
United States
Iowa's corn belt operations and North Carolina's integrated pork producers drive demand for high-throughput ELISA screening panels. USDA National Veterinary Services Laboratories maintains extensive validation libraries that condition kit registration requirements for federal procurement channels. The USDA's National Animal Health Laboratory Network accreditation standards tighten quality compliance for diagnostic consumables used across commercial hog operations.
China
Guangdong and Shandong provinces generate concentrated procurement for multiplex nucleic acid panels as large-scale pig farming clusters expand. The Ministry of Agriculture and Rural Affairs mandates real-time PCR confirmation for all suspected African Swine Fever cases, establishing nucleic acid methods as the regulatory gold standard. Domestic kit manufacturers with established ministry relationships secure faster validation timelines than imported brands.
Germany
Lower Saxony's veterinary laboratories specify automated nucleic acid extraction platforms to maintain throughput during outbreak surges. EMA-aligned quality standards shape assay validation protocols for cross-border trade certification within the European Union. Bavaria's diagnostic equipment fabricators supply PCR thermal cyclers to Poland and Denmark's commercial farm segments.
Brazil
Mato Grosso's integrated pork producers consolidate diagnostic procurement under centralized veterinary service contracts, displacing ad hoc kit purchasing. ANVISA registration requirements govern import approval timelines for nucleic acid reagents used in herd health monitoring. São Paulo state's diagnostic distributors bridge supply gaps for smallholder cooperatives in southern production zones.
Denmark
Commercial sow farms deploy loop-mediated isothermal amplification platforms for same-day African Swine Fever screening prior to animal transport. EU Green Deal sustainability metrics increasingly condition veterinary service contract specifications for environmental compliance reporting. The Netherlands imports Danish-designed field devices for battery-powered barn-side pathogen detection.
Swine Disease Diagnostic Kit Market Competitive Landscape
On the supply side, the industry is consolidating around three structural tiers: multinational life science conglomerates with veterinary channel density, specialized diagnostic manufacturers with backward integration into reagent production, and regional suppliers serving price-sensitive farm segments. Strategic archetypes include instrument-anchored platform vendors, assay-specialist reagent houses, and distributor-dependent local brands. Dominant competitive moves encompass strategic partnerships with integrated pork producers and geographic expansion through ministry registration acquisitions.
Among diversified life science conglomerates, IDEXX Laboratories and Thermo Fisher Scientific exemplify instrument-anchored platform strategies, while Zoetis occupies a position representing backward-integrated assay manufacturing. These three entities anchor the premium tier through channel control and regulatory registration breadth, with regional specialists like Ring Biotechnology and Bionote sitting within cost-competitive segments serving Asia-Pacific procurement patterns.
| Leading Market Players |
|---|
| IDEXX Laboratories |
| Zoetis |
| Thermo Fisher Scientific |
| Neogen |
| BioChek |
| INDICAL BIOSCIENCE |
| bioMérieux |
| Ring Biotechnology |
| Bionote |
| Others |
Pricing and Supply Chain Analysis
Single-source dependency on Taq polymerase manufacturing clusters in specific Asian supply zones compresses margin spreads between premium PCR reagent tiers and economy-grade immunoassay alternatives, while simultaneously forcing diagnostic kit vendors toward regional inventory buffering strategies that inflate working capital requirements.
Pricing Analysis
Current-generation real-time PCR chemistry platforms command substantial premiums over prior-generation ELISA colorimetric systems and emerging next-generation CRISPR-based isothermal formats. Three-tier pricing structure across premium, standard, and economy levels separates USDA-validated multiplex panels from single-pathogen screening kits and unvalidated research-use-only reagents. Price differentiation hinges on National Animal Health Laboratory Network certification status and volume-scale procurement contracts with integrated pork producers. Pricing pressure stems from procurement consolidation under centralized veterinary service agreements in Iowa and Mato Grosso. Smallholder cooperatives in Vietnam exhibit acute price sensitivity; accredited reference laboratories in Germany's Lower Saxony demonstrate minimal elasticity.
Supply Chain Analysis
Extended payment terms from integrated pork producers to diagnostic distributors are compressing cash conversion cycles for reagent manufacturers, forcing supply-chain finance facility adoption among mid-tier kit vendors. Manufacturing concentration spans China for PCR thermal cyclers, Germany for automated nucleic acid extraction platforms, and the United States for fluorogenic probe chemistries. Raw material dependencies encompass Taq polymerase, magnetic bead extraction matrices, and nitrocellulose membrane substrates. Single-source vulnerability in fluorescent probe synthesis creates exposure to regional logistics disruptions. Distribution runs through veterinary distributor networks serving farm clusters in Guangdong province and North Carolina's hog operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The swine disease diagnostic kit market is entering a cyclical upswing driven by African Swine Fever surveillance mandate expansion across commercial pork operations, creating favorable conditions for strategic repositioning across all participant categories.
For Market Incumbents: Build regulatory registration breadth as the primary competitive moat. IDEXX Laboratories and Zoetis should accelerate Ministry of Agriculture and Rural Affairs assay validations in China to preempt domestic manufacturer encroachment. Backward integration into fluorescent probe manufacturing reduces exposure to Asian supply zone disruptions. Channel control through exclusive veterinary service contracts with Brazil's Mato Grosso integrated producers defends against emerging reagent house competition. For New Entrants and Emerging Players: Vietnam's Dong Nai province diagnostic centers represent the most penetrable white-space target, bridging centralized laboratory accuracy with smallholder cooperative access needs. CRISPR-based isothermal amplification platforms offer technical differentiation against entrenched PCR incumbents without thermal cycling infrastructure requirements. A go-to-market angle emphasizing battery-powered field deployment for same-day African Swine Fever screening prior to animal transport addresses unmet turnaround requirements. For Investors and Strategic Acquirers: USDA National Veterinary Services Laboratories emergency-use assay approval pathway acceleration reshapes the acquisition landscape toward validated nucleic acid platform developers. Long-term viability over the coming decade rests on OIE Terrestrial Animal Health Code harmonization progress reducing kit registration duplication costs. Acquisition target archetype: regional specialists with established ministry relationships in outbreak-responsive procurement markets. Monitor China's designated diagnostic protocol mandate enforcement intensity as the critical inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Ministry Registration Acquisition | Domestic manufacturers with established Ministry of Agriculture and Rural Affairs relationships secure faster validation timelines than imported brands. |
| Backward Integration into Reagent Manufacturing | Zoetis-style captive supply of assay chemistries reduces cost volatility and insulates margins from Asian supply zone disruptions. |
| Cloud-Connected Reader Device Launch | Internet-of-Things integration enables real-time herd health data aggregation for predictive analytics service bundling. |
| Oral Fluid Specimen Workflow Development | Non-invasive sample collection methods open penetration pathways in sow farm environments where blood draws disrupt production cycles. |
| Geographic Expansion through Distributor Partnerships | Regional specialists like Ring Biotechnology leverage local channel density to serve price-sensitive Asia-Pacific procurement patterns. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with veterinary diagnostic laboratory directors, integrated pork producer veterinary service managers, diagnostic distributor procurement leads, and assay development scientists; alongside secondary validation through USDA National Veterinary Services Laboratories validation library records, OIE Terrestrial Animal Health Code documentation, China's Ministry of Agriculture and Rural Affairs designated diagnostic protocol filings, and customs trade data on PCR thermal cycler imports. Bottom-up segment sizing across product type, technology, application, and end user dimensions was triangulated against top-down market consolidation estimates.
Forecast inputs encompassed historical kit placement rates, instrument installed base depreciation curves, and regulatory mandate expansion trajectories across the projection horizon. Segmentation dimensions modeled include nucleic acid amplification versus immunoassay technology tiers, African Swine Fever versus Porcine Reproductive & Respiratory Syndrome application priorities, and veterinary laboratory versus diagnostic center end-user service intensity differentials. CAGRs were derived from elasticity-adjusted demand projections incorporating outbreak-responsive procurement cycle patterns and ministry validation timeline differentials between domestic and imported assay brands.
Practitioners should monitor African Swine Fever outbreak geography shifts, ministry registration timeline changes, and thermal cycler versus isothermal platform adoption rates for early signals necessitating forecast revision. Macroeconomic volatility affecting pork commodity prices, regulatory divergence in emergency-use assay approval pathways, or technological disruption in CRISPR-based detection sensitivity would prompt reassessment of projection assumptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.