
 Global Lateral Flow Assay Market | 2026-2036
Global Lateral Flow Assay Market Size, Share, and Industry Trends Forecast 2026-2036
Global Lateral Flow Assay Market Outlook
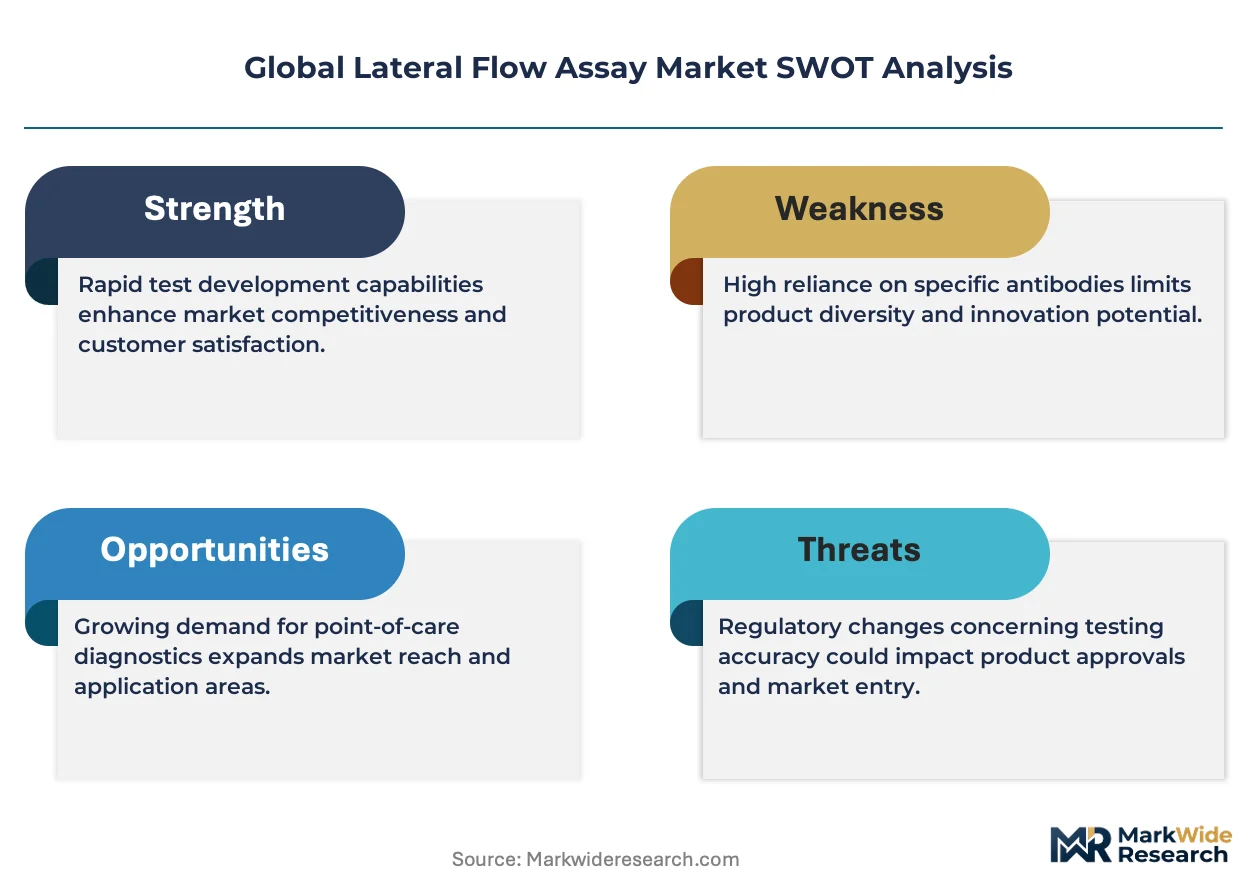
Project finance for distributed diagnostic manufacturing is narrowing the competitive field to firms with capital-market access. Abbott Laboratories leverages its vertically integrated supply chain to sustain cost advantages in high-volume strip production. Danaher Corporation anchors its position through precision manufacturing capabilities that dominate the devices segment.
A lateral flow assay consists of a porous membrane strip, typically nitrocellulose, with capture reagents immobilized at defined zones and a conjugate pad containing labeled detection antibodies that migrate via capillary action to produce a visual signal within minutes. The technology serves decentralized diagnostic screening where laboratory infrastructure is unavailable or time-critical decisions are required. Immunoassay-based formats occupy the largest share of current revenue, while nucleic acid lateral flow platforms represent the fastest-growing category as multiplexed pathogen detection gains clinical traction. Point-of-care end users command the deepest margin pools due to premium pricing on CLIA-waived and over-the-counter configurations.
The FDA regulates lateral flow devices through the 510(k) and De Novo pathways, with recent guidance tightening performance standards for over-the-counter infectious disease tests. The European Medicines Agency and the EU In Vitro Diagnostic Medical Devices Regulation impose stringent clinical evidence requirements that reshape product development timelines and market access costs for manufacturers seeking CE marking. Stakeholders must monitor how decentralized regulatory frameworks across the United States, Germany, and China evolve to determine where to prioritize clinical validation investments and manufacturing partnerships.
Market Dynamics
Decentralized healthcare infrastructure is fragmenting demand across home care, retail clinics, and ambulatory settings, compressing the addressable window for centralized laboratory testing while elevating CLIA-waived and over-the-counter configurations.
Growth Catalysts
- FDA De Novo pathway expansion:Accelerated clearance timelines for multiplexed infectious disease panels are enabling faster commercialization of next-generation devices in the United States.
- Home care diagnostics:Post-pandemic patient preference for self-testing is sustaining volume momentum in respiratory, fertility, and chronic disease monitoring applications.
- Capillary action engineering:Advances in nitrocellulose membrane porosity and conjugate pad chemistry are reducing time-to-result below ten minutes without sacrificing sensitivity thresholds.
Market Restraints
- Nitrocellulose supply concentration:Three specialized chemical manufacturers control membrane substrate output, exposing producers to input volatility and allocation risk.
- EU MDR clinical evidence burdens:Expanded post-market surveillance and performance validation requirements are extending CE marking timelines and inflating regulatory compliance costs.
- Central laboratory automation:High-throughput analyzer systems in hospital networks retain cost advantages for high-volume screening, limiting lateral flow penetration in institutional settings.
Strategic Opportunities
- Nucleic acid lateral flow hybridization:Convergence of isothermal amplification with visual readout formats is opening molecular diagnostic access to resource-limited settings lacking thermal cycler infrastructure.
- India's Ayushman Bharat expansion:Universal health coverage rollout is creating procurement pathways for affordable point-of-care screening devices at primary health centers.
- Pharmacy channel integration:Direct-to-patient distribution through retail pharmacy chains is bypassing traditional clinical sales cycles and capturing margin pools previously held by distributors.
Industry Challenges
- Multiplex assay development complexity:Cross-reactivity management and signal interference in multi-analyte configurations demand specialized biochemistry talent that remains scarce across the sector.
- 510(k) predicate device erosion:FDA's tightening of substantial equivalence standards for infectious disease claims is forcing more sponsors toward higher-evidence De Novo submissions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Lateral Flow Assay Market |
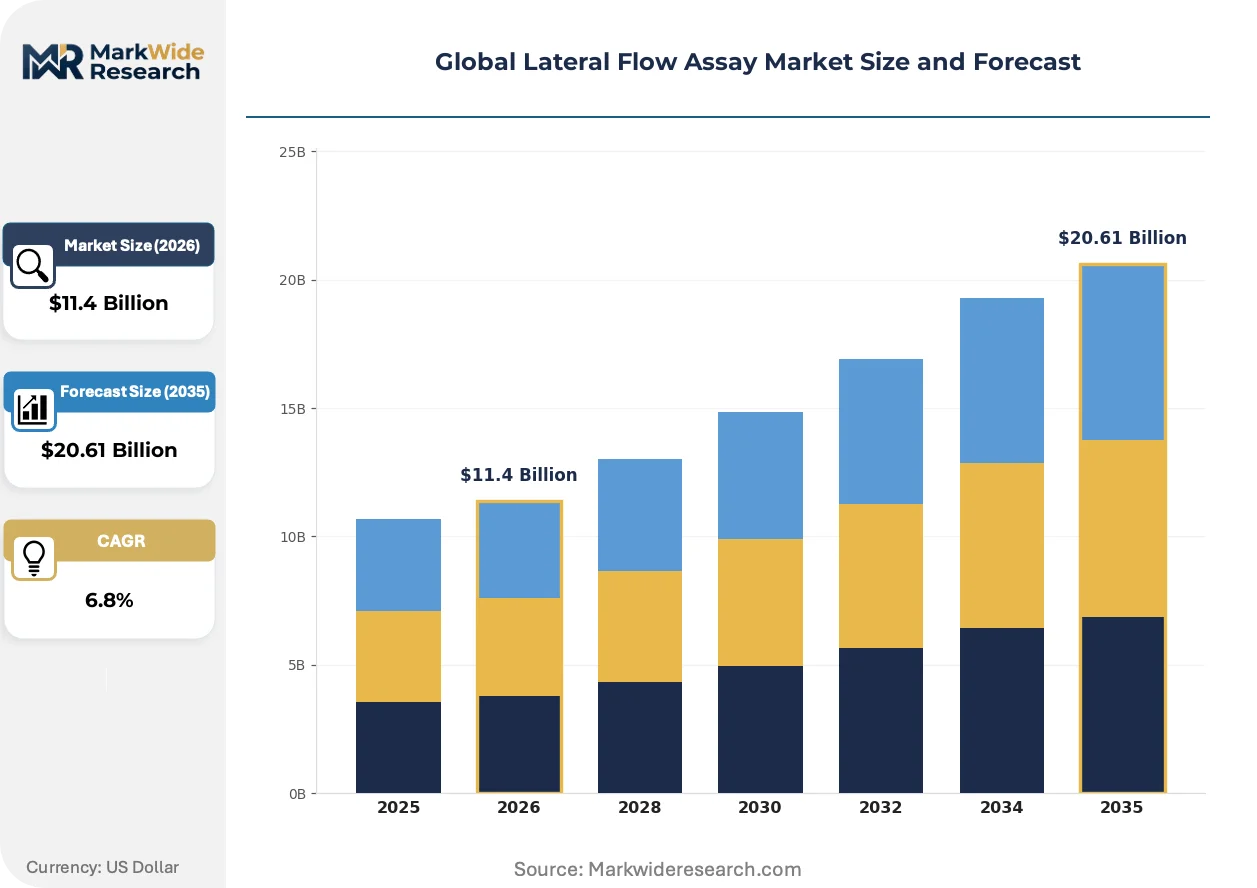
| Market Size in 2026 | $11.4 Billion |
| Market Size in 2035 | $20.61 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rapid Test Kits, Devices, Strips, Panels End User: Hospitals, Laboratories, Home Care, Point-of-Care Technology: Immunoassay, Nucleic Acid, Dual-Read, Single-Read Application: Infectious Diseases, Pregnancy Testing, Drug Testing, Cancer Screening |
| Companies Covered | Abbott Laboratories, F. Hoffmann-La Roche Ltd., Danaher Corporation, Thermo Fisher Scientific, Siemens Healthineers, QuidelOrtho Corporation, Merck KGaA, Becton Dickinson, bioMérieux, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Lateral Flow Assay Market Strategic Shifts
Convergence between molecular detection methods and conventional immunoassay formats is redefining performance benchmarks, while regulatory frameworks and procurement patterns are simultaneously compressing development cycles and elongating validation requirements.
Fluorescent nanoparticle conjugates are replacing colloidal gold as the dominant signal generation system in high-sensitivity applications. Reference laboratories and specialty diagnostics manufacturers are adopting these materials to achieve quantitative readouts compatible with reader devices. This transition is hybridizing the cost structure of lateral flow manufacturing, merging disposable economics with capital equipment dependencies.
The EU In Vitro Diagnostic Medical Devices Regulation is imposing clinical performance study requirements that exceed prior directive standards. Manufacturers must now generate diagnostic sensitivity and specificity data from intended-use populations rather than contrived analytical validations. European notified bodies are prioritizing review resources toward high-risk device categories, creating backlog pressure for self-certified Class A and B lateral flow products.
Hospital procurement consortia are consolidating purchasing authority across integrated delivery networks, compressing vendor counts and standardizing device specifications. Group purchasing organizations are extracting volume commitments in exchange for formulary placement, displacing individual facility autonomy in test selection. This concentration is most pronounced in the United States, where three national GPOs control the majority of acute care diagnostic spend.
Global Lateral Flow Assay Market Segmentation
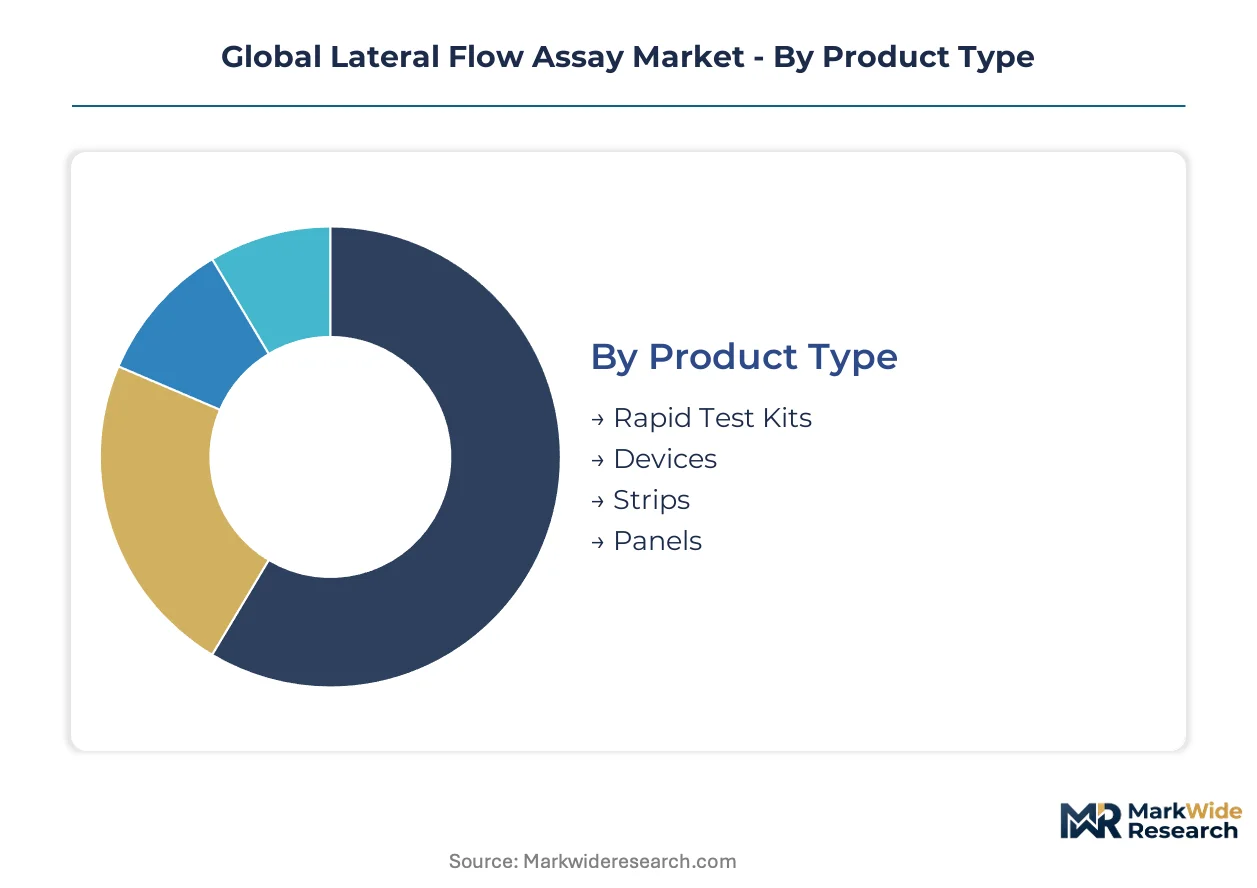
Lateral flow assay segmentation reveals how technical specifications align with care delivery settings. Product configurations vary dramatically across centralized laboratories versus decentralized home environments, while detection chemistry choices determine sensitivity thresholds and reader device requirements.
Product Type:
Mature formats dominate high-volume screening, while emerging configurations target multiplexed detection and quantitative readout capabilities.
- Rapid Test Kits:Complete packaged systems containing membrane strips, buffer solutions, and collection accessories in single-use pouches. Demand concentrates in United States retail pharmacy channels where CLIA-waived configurations command premium positioning for infectious disease and pregnancy applications.
- Devices:Reader-equipped platforms delivering quantitative fluorescence or reflectance measurements beyond visual line interpretation. Germany's hospital procurement consortia are standardizing on these systems for antimicrobial stewardship programs requiring documented sensitivity thresholds.
- Strips:Unmounted nitrocellulose membranes requiring manual sample application and buffer dispensing.
- Panels:Multi-analyte configurations with spatially separated capture zones enabling simultaneous pathogen or biomarker detection.
Rapid Test Kits retain volume leadership; Devices hold the steepest expansion curve.
End User:
Customer type determines pricing tolerance, regulatory pathway complexity, and technical support requirements across the value chain.
- Home Care:Self-testing environments where untrained users perform sample collection and result interpretation without clinical supervision. China's expanding pharmacy network in tier-2 cities is driving procurement volume for fertility and chronic disease monitoring applications.
- Point-of-Care:Clinical settings including physician offices, retail clinics, and emergency departments where trained staff operate waived or moderately complex devices. FDA's De Novo pathway expansion is accelerating clearance timelines for multiplexed respiratory panels in these settings.
- Hospitals:Acute care facilities with laboratory accreditation performing higher-complexity testing.
- Laboratories:Centralized reference facilities with automated workflow integration and quality management systems.
Point-of-Care commands the deepest margin pools; Home Care is climbing the fastest.
Technology:
Detection chemistry maturity spans decades-old colloidal gold methods to emerging isothermal amplification hybrids.
- Immunoassay:Antibody-antigen binding formats using colloidal gold or fluorescent nanoparticle reporters on nitrocellulose substrates. India's Ayushman Bharat primary health centers are procuring these for affordable infectious disease screening at massive scale.
- Nucleic Acid:Isothermal amplification combined with sequence-specific probe capture enabling molecular detection without thermal cycler infrastructure. Resource-limited settings lacking laboratory infrastructure represent the concentrated demand zone.
- Dual-Read:Combined visual and instrumental interpretation modes accommodating both rapid screening and quantitative documentation.
- Single-Read:Visual-only formats dependent on operator judgment without electronic verification.
Immunoassay retains volume leadership; Nucleic Acid holds the steepest expansion curve.
Application:
Clinical utility maturity ranges from commoditized consumer diagnostics to emerging cancer screening platforms.
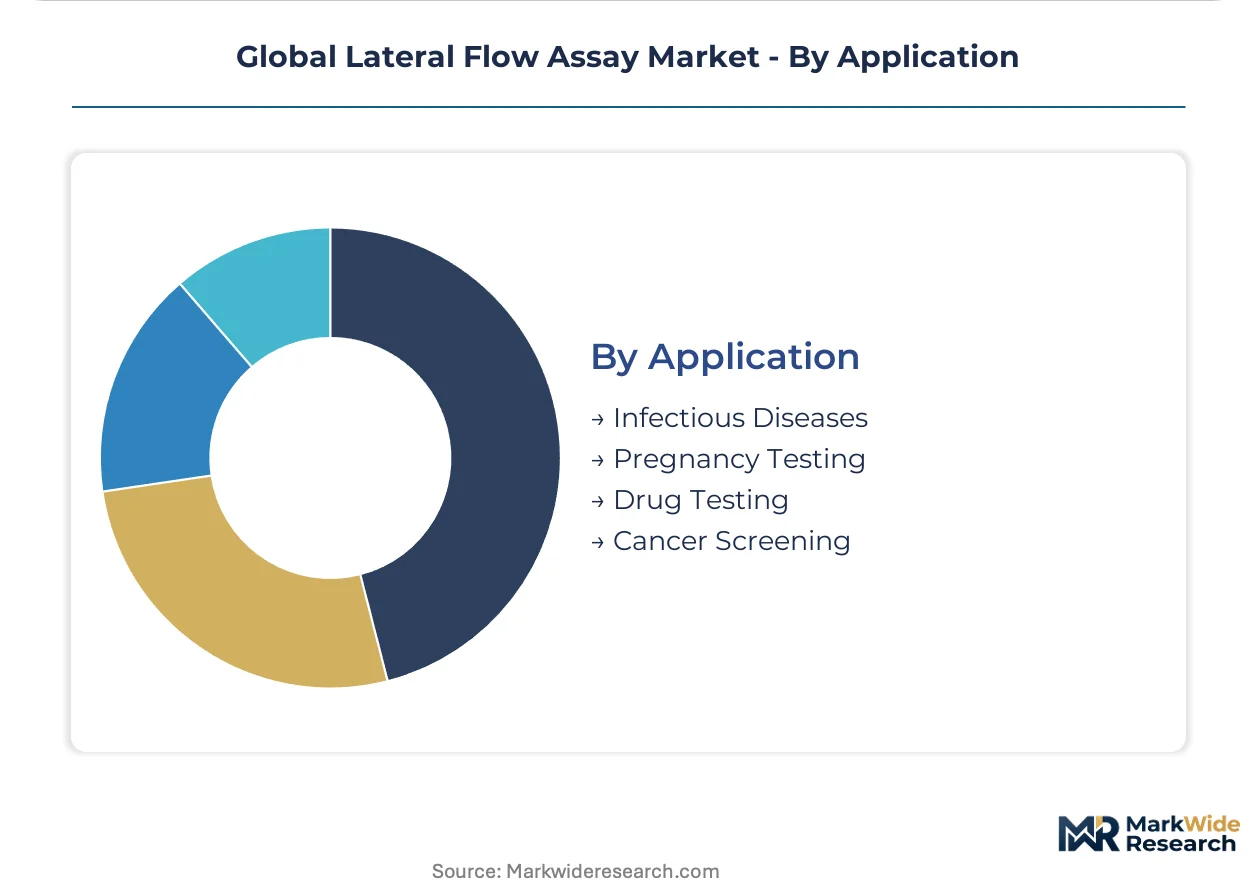
- Infectious Diseases:Respiratory, sexually transmitted, and gastrointestinal pathogen detection with pandemic-era validation data supporting regulatory submissions. United States over-the-counter clearance pathways are tightening performance standards for these claims.
- Pregnancy Testing:Human chorionic gonadotropin detection in urine samples with decades of manufacturing optimization and established consumer behavior patterns.
- Drug Testing:Workplace and forensic applications for substance abuse screening with chain-of-custody documentation requirements.
- Cancer Screening:Emerging tumor marker detection with biomarker specificity challenges limiting commercial penetration.
Infectious Diseases retains volume leadership; Cancer Screening holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in lateral flow diagnostics favor manufacturing concentration in Germany, China, and the United States, with finished device flows tracking regulatory clearance velocity and membrane substrate availability. Trade balances reflect captive nitrocellulose production versus kit assembly outsourcing patterns.
United States
Home care self-testing and retail pharmacy distribution dominate demand generation, with CVS and Walgreens procurement cycles setting volume benchmarks for CLIA-waived configurations. FDA's De Novo pathway expansion accelerates clearance timelines for multiplexed respiratory panels. Greater Boston anchors nucleic acid lateral flow R&D clustering, with isothermal amplification startups concentrating near MIT and Harvard medical research corridors.
Germany
Hospital procurement consortia and antimicrobial stewardship programs drive reader-equipped platform adoption, with standardized sensitivity thresholds mandated for formulary placement. EU MDR clinical evidence requirements extend CE marking timelines while elevating post-market surveillance burdens. Baden-Württemberg hosts precision membrane manufacturing clusters, with nitrocellulose substrate specialists supplying European kit assemblers.
China
Tier-2 city pharmacy network expansion and fertility monitoring applications sustain volume momentum in home care segments. NMPA oversight of over-the-counter diagnostic devices tightens performance validation for infectious disease claims. Yangtze River Delta manufacturing zones concentrate strip assembly capacity, with Suzhou and Shanghai hubs exporting finished kits to Southeast Asian markets.
India
Ayushman Bharat primary health center procurement creates mass-scale demand for affordable immunoassay screening at the point of care. CDSCO regulatory harmonization with WHO prequalification standards streamlines import substitution pathways for domestic manufacturers. Gujarat pharmaceutical clusters integrate lateral flow production into existing API-to-formulation supply chains, reducing import dependency for membrane substrates.
Global Lateral Flow Assay Market Competitive Environment
On the supply side, the industry is consolidating around three strategic archetypes: diversified life science conglomerates with captive diagnostics divisions, precision manufacturing specialists with membrane engineering capabilities, and emerging molecular diagnostic platforms bridging isothermal amplification with visual readout formats. Competitive moves center on backward integration into nitrocellulose substrate production and strategic partnerships with retail pharmacy distribution networks.
Among diversified conglomerates, Abbott Laboratories and Danaher Corporation exemplify scale-driven positioning through vertically integrated supply chains and precision manufacturing capabilities respectively. F. Hoffmann-La Roche Ltd. occupies a position within the premium-tier diagnostics segment, anchoring high-sensitivity applications through fluorescent nanoparticle conjugate systems. These three entities represent the dominant competitive archetypes shaping procurement standards and regulatory engagement across United States, German, and Chinese markets.
| Leading Market Players |
|---|
| Abbott Laboratories |
| F. Hoffmann-La Roche Ltd. |
| Danaher Corporation |
| Thermo Fisher Scientific |
| Siemens Healthineers |
| QuidelOrtho Corporation |
| Merck KGaA |
| Becton Dickinson |
| bioMérieux |
| Others |
Value Chain & Pricing Dynamics
German and Chinese nitrocellulose membrane specialists command upstream pricing leverage, funneling margin capture toward capture reagent suppliers and conjugate pad chemists while compressing kit assemblers in United States retail pharmacy channels.
Pricing Analysis
Home care self-test buyers anchor a three-tier pricing structure across premium, standard, and economy levels. FDA De Novo clearance tier and CLIA-waiver status differentiate price bands, with OTC configurations commanding 40-60% premiums over prescription-limited equivalents. Cost compression in economy strips is intensifying because India's Ayushman Bharat procurement mandates sub-dollar unit economics. Pharmacy chain buyers exhibit highest price sensitivity; hospital GPOs tolerate premium reader-equipped platforms.
Supply Chain Analysis
Foundry capacity for nitrocellulose substrate production concentrates with Merck KGaA's Darmstadt operations, Sartorius Stedim Biotech's Göttingen facilities, and select Yangtze River Delta chemical processors. Raw material flows draw from cotton linter pulp, nitric acid, and specialized polymer coatings. Single-source vulnerability runs through German membrane engineering clusters. Distribution runs through retail pharmacy chains and hospital procurement consortia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The lateral flow assay market is exiting a pandemic-driven demand spike and entering a normalized replacement cycle anchored by respiratory seasonality and chronic disease monitoring refresh rates.
For Market Incumbents: Pre-empt nucleic acid lateral flow hybridization entrants by accelerating isothermal amplification R&D partnerships in Greater Boston. Secure captive nitrocellulose supply through backward integration into Yangtze River Delta membrane manufacturing or long-term offtake agreements with Baden-Württemberg substrate specialists. FDA's tightening 510(k) predicate standards threaten substantial equivalence pathways for infectious disease claims. For New Entrants and Emerging Players: India's Ayushman Bharat primary health centers represent the most penetrable entry point for affordable immunoassay screening at massive procurement scale. Nucleic acid lateral flow platforms for resource-limited settings lacking thermal cycler infrastructure offer white-space access in Southeast Asian and African markets. Partner with established retail pharmacy distributors to bypass clinical sales cycle friction. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed molecular diagnostic platforms bridging isothermal amplification with visual readout formats. Five-to-ten year viability hinges on multiplexed panel regulatory clearance velocity and pharmacy channel integration depth. Watch FDA De Novo submission volumes for respiratory and sexually transmitted infection panels as inflection indicators.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR clinical evidence requirements extend timelines for European market access. |
| Backward Integration | Captive nitrocellulose production insulates margin from German chemical supplier allocation risk. |
| Hospital System Partnership | Antimicrobial stewardship programs in Germany mandate reader-equipped platform standardization. |
| Software Companion Development | Quantitative fluorescence readout apps extend device utility into chronic disease monitoring. |
| Reimbursement Strategy | CLIA-waived configuration coding determines pharmacy channel volume economics. |
Study Parameters
A standing panel of regulatory affairs directors at IVD manufacturers, GPO contracts managers at United States hospital systems, and CDSCO liaison officers provided ongoing calibration across the analysis window. Primary interviews with biomedical engineers at point-of-care settings and nitrocellulose substrate procurement leads supplemented secondary validation through FDA 510(k) and De Novo submission databases, EMA CE marking registries, and WHO prequalification listings. Bottom-up kit volume estimates triangulated against top-down healthcare expenditure flows.
Scenario-bracketing anchored the analytical framework across the modeling period. Segmentation dimensions spanned product format, end-user setting, detection chemistry maturity, and regional regulatory cluster. CAGRs derived from fitted growth curves applied to validated base-year estimates. Forecast inputs incorporated CLIA-waiver expansion rates and retail pharmacy channel penetration assumptions.
Macroeconomic conditions sit as an overlay; deviation in healthcare reimbursement rates and nitrocellulose feedstock pricing would shift the trajectory. Forecasts reflect assumptions about FDA pathway efficiency and EU notified body capacity. Quarterly review of De Novo submission approval timelines and German membrane substrate allocation indicators is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Global Meningitis Diagnostic Testing Market
Diagnostics
Global Serological Testing Market
Diagnostics
Microdialysis Market
Diagnostics
Heart Attack Diagnostics Market
Diagnostics
Sperm Density Testing Market
Diagnostics
Latent Tuberculosis Infection Detection Market
Diagnostics
Global Kidney Cancer Diagnostics Market
Diagnostics
Influenza Diagnostic Tests Market
Diagnostics
Multiplex Molecular Diagnostics Market
Diagnostics
Global Rheumatoid Arthritis Diagnostic Tests Market
Diagnostics
Artificial Intelligence in IVD Market
Diagnostics
Global Phytopathological Disease Diagnostics Market
Diagnostics
Global Respiratory Syncytial Virus (RSV) Diagnostic Market
Diagnostics
In-Vitro Diagnostics (IVD) Instruments Market
Diagnostics
Global Digital Diagnostics Market
Diagnostics
Diabetes Diagnostics Market