
 Global Autoimmune Disease Diagnostics Market | 2026-2036
Global Autoimmune Disease Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Autoimmune Disease Diagnostics Market Foresight
A shortage of board-certified immunopathologists is redrawing competitive dynamics in autoimmune testing. F. Hoffmann-La Roche Ltd leverages its installed base of cobas analyzers to sustain high-throughput ANA screening in centralized labs. Siemens Healthineers anchors its position through integrated chemiluminescence platforms that span rheumatology and endocrinology workflows.
Autoimmune disease diagnostics encompasses laboratory assays that detect autoantibodies, immune complexes, or lymphocyte markers to identify conditions where the immune system attacks host tissues; these tests typically achieve analytical sensitivity below 10 IU/mL and rely on recombinant antigen production to minimize lot-to-lot variability. The primary commercial purpose is to enable differential diagnosis before irreversible organ damage occurs. Enzyme-Linked Immunosorbent Assay retains the largest revenue share due to its compatibility with existing open-system instrumentation, while Next-Generation Sequencing represents the fastest-expanding technology dimension as HLA typing and autoimmune gene panels migrate from research to clinical validation. Diagnostic Laboratories command the dominant end-user channel, though Specialty Clinics are capturing margin pools through rapid point-of-care rheumatoid factor testing.
The FDA's classification of high-complexity immunology assays under CLIA regulations shapes product development timelines and quality management systems for manufacturers seeking US market access. In Europe, the MDR's clinical evidence requirements for Class C in vitro diagnostics are forcing reassessment of legacy assay portfolios. The EU AI Act's risk-based framework for diagnostic software will soon extend to algorithm-assisted pattern recognition in antinuclear antibody immunofluorescence. Stakeholders must weigh capital deployment between decentralized near-patient platforms and centralized mega-lab automation as reimbursement pathways diverge across health systems.
Market Dynamics
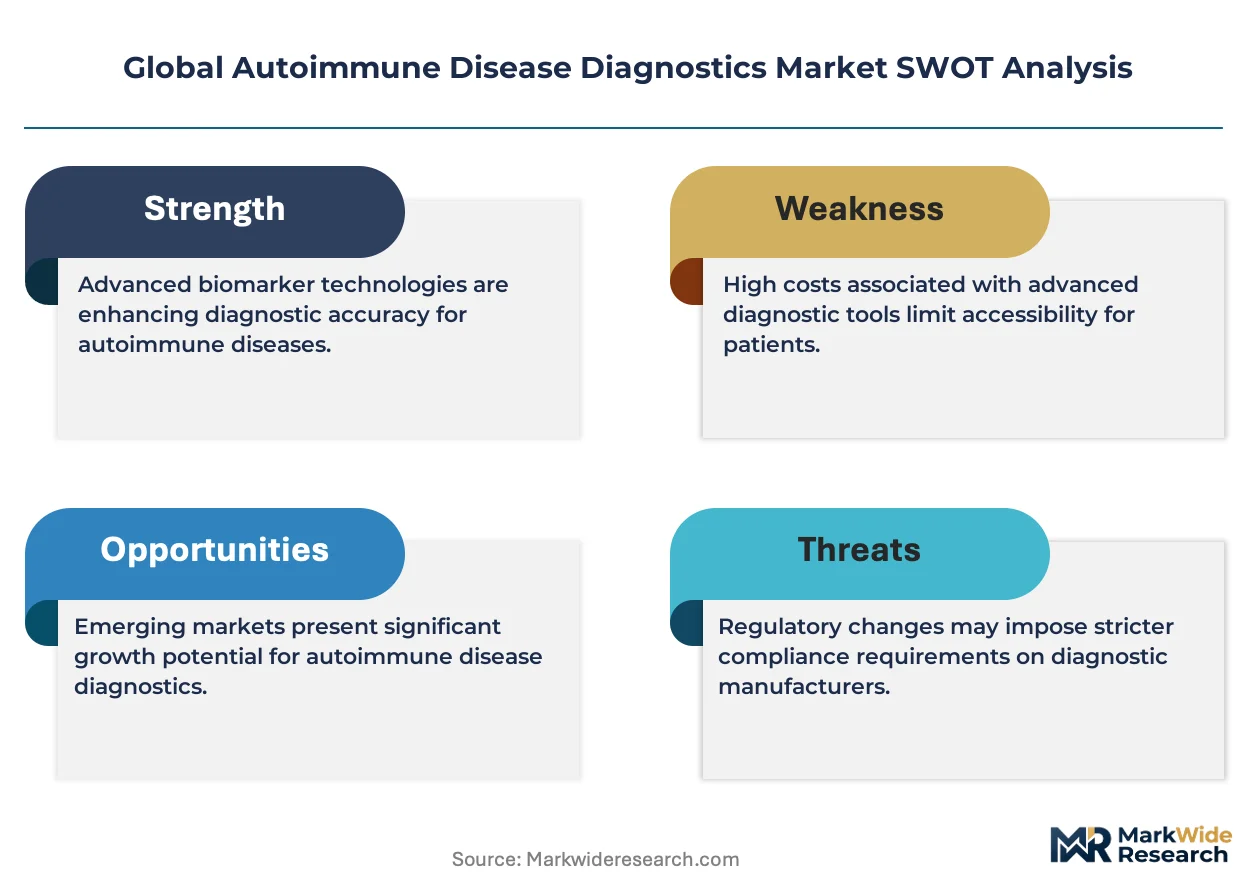
CLIA high-complexity classification and EU MDR clinical evidence mandates are compressing development timelines while fragmenting assay portfolios across regulatory jurisdictions. Manufacturers now face divergent validation requirements that favor either centralized mega-lab automation or decentralized near-patient platforms depending on reimbursement pathway maturity.
Growth Catalysts
- EU MDR Class C evidence requirements:Stricter clinical validation standards are accelerating assay standardization and consolidating demand toward manufacturers with robust quality management systems.
- Rheumatology referral networks:Specialist concentration in the United States, Germany, and Japan creates predictable volume pipelines for high-throughput immunology testing.
- Recombinant antigen production:Advances in protein engineering minimize lot-to-lot variability and reduce false-positive rates in antinuclear antibody screening.
Market Restraints
- Reagent supply concentration:Critical raw materials for chemiluminescence substrates concentrate among a limited supplier base in Germany and Switzerland.
- FDA CLIA categorization friction:High-complexity assay classification extends quality control burdens and limits point-of-care deployment for rheumatoid factor testing.
- Next-Generation Sequencing substitution pressure:HLA typing migration toward gene panels threatens legacy serological assay volumes in transplant immunology workflows.
Strategic Opportunities
- India's diagnostic laboratory consolidation:Chain laboratory expansion in Mumbai and Delhi creates demand for open-system ELISA platforms compatible with existing instrumentation.
- EU AI Act algorithmic diagnostics pathway:Risk-based framework for pattern recognition software enables automated antinuclear antibody immunofluorescence interpretation.
- Specialty clinic channel development:Rapid rheumatoid factor testing at point-of-care captures margin pools currently held by centralized reference laboratories.
Industry Challenges
- Board-certified immunopathologist scarcity:Training pipeline gaps in the United States and Japan constrain test interpretation capacity and extend turnaround times.
- Legacy analyzer integration complexity:Chemiluminescence platform upgrades require middleware reconciliation with existing laboratory information systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Autoimmune Disease Diagnostics Market |
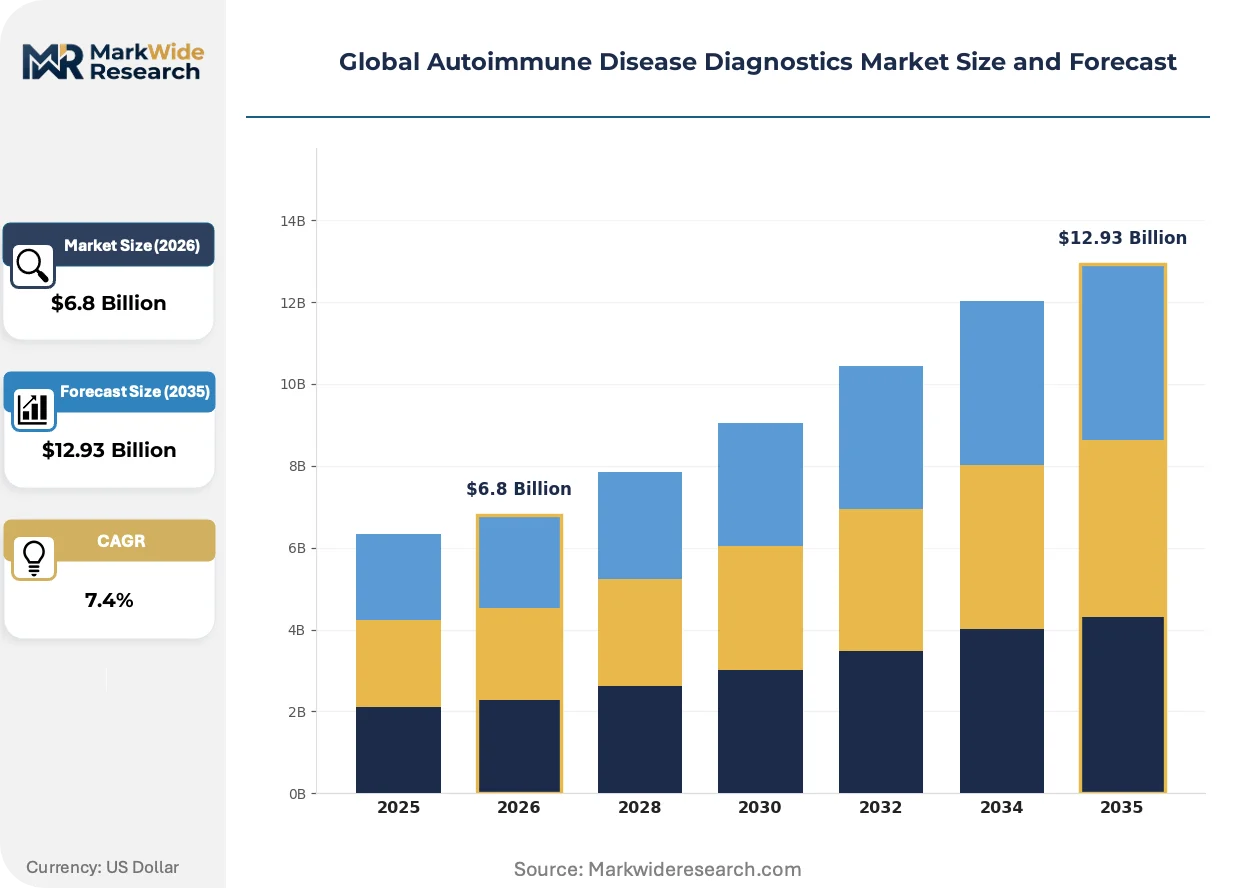
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $12.93 Billion |
| CAGR (2026 – 2036) | 7.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antinuclear Antibody Test, Enzyme-Linked Immunosorbent Assay, Rheumatoid Factor Test, Immunofluorescence Assay, Multiplex Assay Technology: Polymerase Chain Reaction, Flow Cytometry, Western Blotting, Chemiluminescence Immunoassay, Next-Generation Sequencing Application: Systemic Lupus Erythematosus, Rheumatoid Arthritis, Multiple Sclerosis, Type 1 Diabetes, Sjogren Syndrome End User: Diagnostic Laboratories, Research Institutes, Specialty Clinics, Blood Banks, Academic Centers |
| Companies Covered | F. Hoffmann-La Roche Ltd, Abbott Laboratories, Siemens Healthineers, Thermo Fisher Scientific Inc., Bio-Rad Laboratories, Quest Diagnostics, Danaher Corp, Revvity, Inc., DiaSorin SpA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Autoimmune Disease Diagnostics Market Shifts & Advancements
Multiplex assay architectures and algorithmic pattern recognition are compressing the traditional serology-to-molecular diagnostic transition timeline. These shifts reconfigure capital deployment priorities between high-throughput centralized automation and distributed near-patient testing.
Multiplex bead-based immunoassays enable simultaneous detection of multiple autoantibodies from single serum samples. Reference laboratories in the United States and Germany are adopting these platforms to consolidate previously discrete ELISA workflows. The technology is miniaturizing reagent consumption while expanding test menus without proportional footprint expansion.
The EU AI Act's risk-based classification for diagnostic software is extending to automated antinuclear antibody pattern interpretation. Manufacturers must now generate clinical evidence for algorithm-assisted fluorescence microscopy reads previously validated through manual expert consensus. Rheumatology diagnostic laboratories in France and Germany are piloting these systems under notified body supervision.
Hospital procurement committees are unbundling after-sales service contracts from analyzer placement agreements. Diagnostic laboratories now negotiate reagent supply and maintenance separately, compressing vendor lock-in duration. This pattern is most visible in Japan's university hospital networks and Germany's municipal laboratory consortia.
Global Autoimmune Disease Diagnostics Market Segmentation
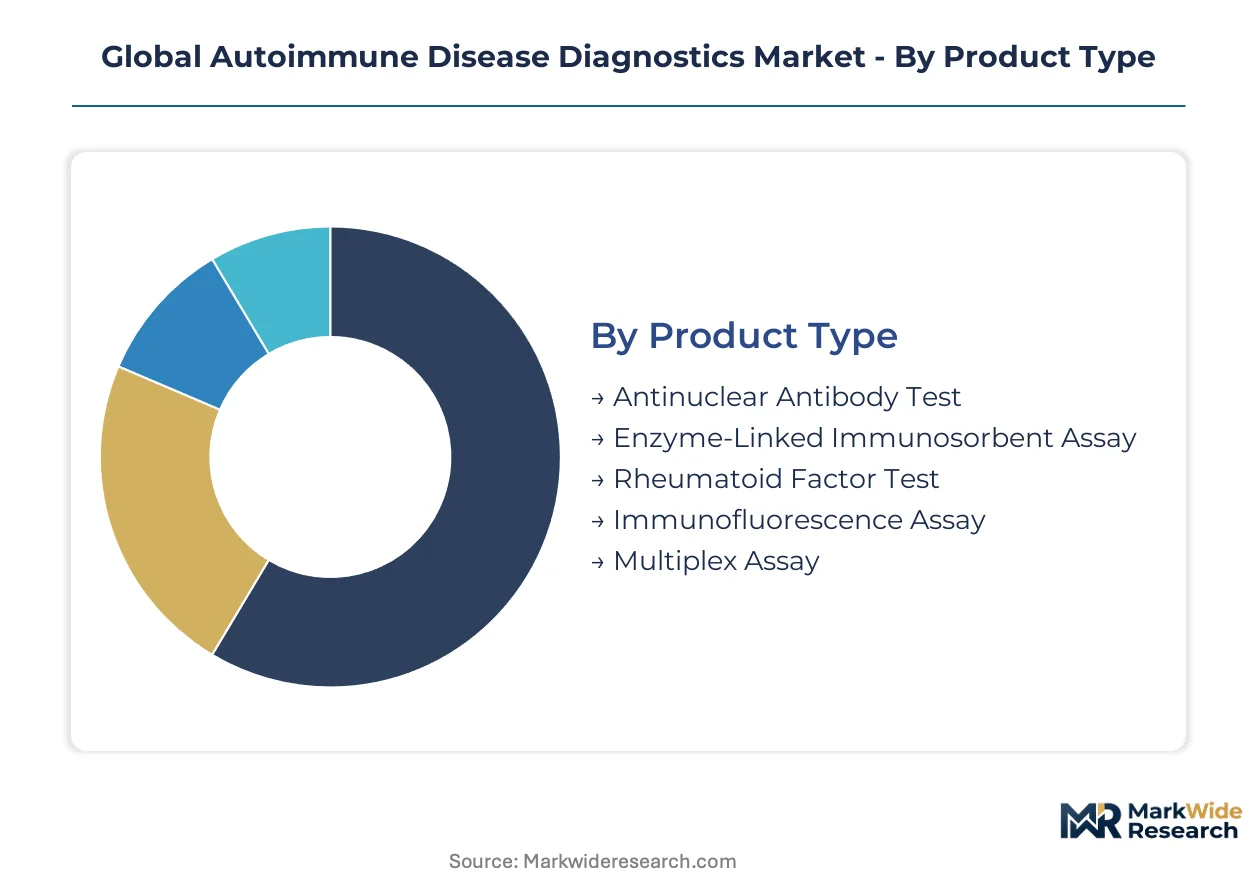
Segmentation in autoimmune disease diagnostics reveals how test volumes flow through distinct procurement channels. Each dimension—product format, detection technology, clinical application, and site of care—carries different margin profiles and regulatory burdens.
Product Type:
Channel mix varies sharply by assay format, with centralized laboratories favoring high-throughput platforms while specialty clinics prioritize rapid turnaround formats.
- Enzyme-Linked Immunosorbent Assay:Open-system compatibility drives continued dominance in hospital laboratories across the United States and Germany. Reagent rental agreements and existing installed bases create switching costs that sustain manufacturer relationships.
- Multiplex Assay:Bead-based architectures consolidate multiple autoantibody detections into single serum samples, compressing workflow steps in reference laboratories. Adoption concentrates in high-volume rheumatology centers seeking menu expansion without footprint growth.
- Antinuclear Antibody Test:Screening workloads flow through automated immunofluorescence platforms in centralized settings.
- Rheumatoid Factor Test:Point-of-care deployment in specialty clinics captures margin pools from reference laboratory outsourcing.
- Immunofluorescence Assay:Pattern interpretation requirements sustain demand for specialist pathologist networks.
Enzyme-Linked Immunosorbent Assay dominates installed base. Multiplex Assay is where expansion concentrates.
Technology:
Cost tier stratification separates capital-intensive platform investments from reagent-light methodologies, with procurement committees weighing total cost of ownership against clinical specificity requirements.
- Chemiluminescence Immunoassay:Integrated random-access analyzers deliver quantitative autoantibody results with throughput exceeding 200 tests per hour. Siemens Healthineers and Roche anchor positions through closed-system reagent contracts in German and Japanese university hospitals.
- Next-Generation Sequencing:HLA typing and autoimmune gene panels migrate from research to clinical validation, threatening legacy serological volumes in transplant immunology. Clinical evidence generation under FDA and EMA frameworks extends development timelines.
- Polymerase Chain Reaction:Viral trigger detection complements autoantibody panels in differential diagnosis workflows.
- Flow Cytometry:Lymphocyte subset enumeration supports monitoring in systemic lupus erythematosus treatment protocols.
- Western Blotting:Confirmatory testing for extractable nuclear antigen specificity retains niche demand.
Chemiluminescence Immunoassay anchors current revenue. Next-Generation Sequencing is gaining share fastest.
Application:
Volume concentration tracks rheumatology referral network density, with predictable pipelines forming around specialist concentrations in the United States, Germany, and Japan.
- Rheumatoid Arthritis:Anti-CCP and rheumatoid factor testing volumes correlate directly with rheumatologist density and early intervention protocols. Medicare reimbursement for serological markers sustains test frequency in US outpatient settings.
- Systemic Lupus Erythematosus:Multi-organ involvement drives comprehensive autoantibody panels including anti-dsDNA, anti-Smith, and complement level monitoring. Disease flare prediction algorithms are integrating with laboratory data in French and German pilot programs.
- Multiple Sclerosis:Oligoclonal banding and aquaporin-4 antibody testing flow through neurology referral pathways.
- Type 1 Diabetes:Islet cell and GAD65 antibody screening concentrates in pediatric endocrinology centers.
- Sjogren Syndrome:Anti-SSA/Ro and anti-SSB/La testing supports differential diagnosis in sicca presentation workups.
Rheumatoid Arthritis commands the largest test volume. Systemic Lupus Erythematosus shows the steepest expansion trajectory.
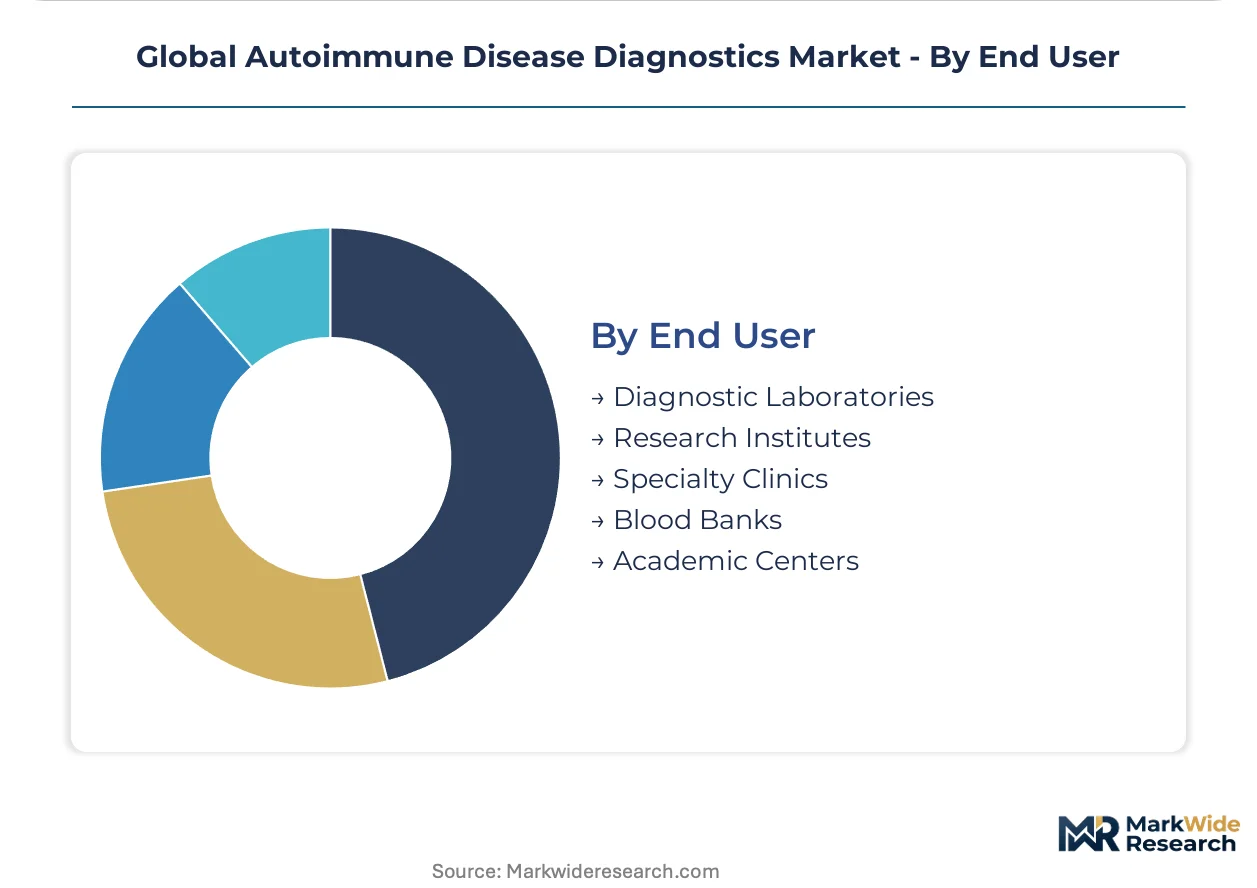
End User:
Customer type determines pricing power and contract structure, with procurement scale inversely correlated with per-test margin.
- Diagnostic Laboratories:High-throughput centralized facilities negotiate reagent supply and maintenance contracts separately, compressing vendor lock-in duration. Chain laboratory consolidation in India and Brazil creates demand for open-system platforms compatible with existing instrumentation.
- Specialty Clinics:Rheumatology and endocrinology practices deploy rapid rheumatoid factor testing to capture margin pools from reference laboratory outsourcing. CLIA high-complexity classification limits point-of-care deployment in the United States.
- Research Institutes:Discovery workflows drive demand for novel biomarker assay development services.
- Blood Banks:Transfusion-related acute lung injury prevention protocols sustain granulocyte antibody screening.
- Academic Centers:Teaching hospitals balance clinical service with assay validation for regulatory submission.
Diagnostic Laboratories dominate installed base. Specialty Clinics is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA's CLIA high-complexity classification anchors the United States as the dominant geography for autoimmune diagnostics, with reimbursement pathways and specialist referral networks concentrating demand in specific metropolitan corridors.
United States
Medicare reimbursement for serological markers and dense rheumatology referral networks drive test volumes. FDA's in vitro diagnostic rules and CLIA regulations shape assay validation timelines for manufacturers seeking market access. The Mayo Clinic corridor in Minnesota and Cleveland Clinic network in Ohio anchor high-throughput immunology testing capacity.
Germany
University hospital networks and municipal laboratory consortia sustain demand for integrated chemiluminescence platforms. EU MDR Class C clinical evidence requirements are forcing reassessment of legacy assay portfolios. The Rhine-Ruhr metropolitan region and Munich cluster concentrate reference laboratory automation investments.
Japan
PMDA regulatory frameworks and METI industrial policy support domestic reagent production. Specialist pathologist scarcity is extending turnaround times in regional hospitals. Tokyo's university hospital networks and Osaka's diagnostic laboratory chains anchor high-volume ANA screening workflows.
India
Chain laboratory consolidation in Mumbai and Delhi creates procurement scale for open-system ELISA platforms. CDSCO medical device regulations are tightening quality management system requirements. Bangalore's diagnostic laboratory networks and Hyderabad's research institutes drive adoption of automated immunofluorescence systems.
Switzerland
Swissmedic oversight of in vitro diagnostics and proximity to German supply chains position the country as a reagent production hub. Chemiluminescence substrate manufacturing concentrates in Basel's pharmaceutical corridor. Zurich's university hospital networks and Geneva's specialty clinics sustain demand for high-specificity autoantibody panels.
Global Autoimmune Disease Diagnostics Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with the top tier commanding installed base advantages through closed-system reagent contracts. Mid-scale players compete on open-system compatibility and menu breadth. Two strategic archetypes dominate: platform-integrated conglomerates with diagnostic divisions spanning multiple therapeutic areas, and pure-play immunology specialists with concentrated assay expertise. Competitive moves center on middleware integration capabilities and geographic expansion through chain laboratory partnerships.
Among Swiss-German integrated conglomerates, F. Hoffmann-La Roche Ltd and Siemens Healthineers exemplify the platform-anchored archetype through their analyzer installed bases and reagent supply relationships. Thermo Fisher Scientific Inc. occupies a position bridging research-grade and clinical-validated assay development. These three represent the scale-driven tier where capital deployment favors mega-lab automation over point-of-care decentralization.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche Ltd |
| Abbott Laboratories |
| Siemens Healthineers |
| Thermo Fisher Scientific Inc. |
| Bio-Rad Laboratories |
| Quest Diagnostics |
| Danaher Corp |
| Revvity, Inc. |
| DiaSorin SpA |
| Others |
Supply & Pricing Matrix
Long-term reagent rental agreements with closed-system clauses lock in supply access and price visibility for manufacturers of chemiluminescence platforms across German and Japanese university hospitals. These contracts bundle analyzer placement with minimum volume commitments, compressing buyer negotiating leverage while securing predictable revenue streams for platform-integrated conglomerates.
Pricing Analysis
Geographic price spreads between the United States and India exceed threefold for equivalent ELISA reagent kits, reflecting after-sales service bundling and regulatory compliance cost differentials. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated assays from CE-marked alternatives and open-system compatible reagents. Pricing pressure stems from chain laboratory consolidation in Mumbai and Delhi demanding volume discounts. Diagnostic laboratories exhibit highest price sensitivity, while academic centers prioritize assay specificity over per-test cost.
Supply Chain Analysis
Germany and Switzerland anchor chemiluminescence substrate manufacturing, with Basel's pharmaceutical corridor hosting concentrated reagent production facilities. Critical raw materials including acridinium ester derivatives and magnetic microparticles draw from limited supplier bases in these jurisdictions. Single-source vulnerability in high-purity enzyme supply creates exposure to export licensing restrictions. Distribution runs through authorized distributor networks with regional exclusivity clauses, limiting direct manufacturer access to end-user laboratories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The autoimmune disease diagnostics market is recovering from pandemic-depressed routine testing volumes, with rheumatology referral network reactivation serving as the primary cyclical driver restoring baseline demand.
For Market Incumbents: Fortify installed base retention through middleware integration investments that reduce laboratory information system reconciliation friction during platform upgrades. Deepen captive supply of recombinant antigens to minimize lot-to-lot variability exposure. Counter Next-Generation Sequencing substitution pressure by expanding multiplex assay menus that consolidate previously discrete workflows. For New Entrants and Emerging Players: Lead with open-system ELISA compatibility targeting India's consolidating chain laboratories in Mumbai and Delhi, where procurement scale favors instrumentation-agnostic reagent suppliers. Specialty clinic point-of-care rheumatoid factor testing represents the most penetrable channel, constrained only by CLIA high-complexity classification friction that modular cartridge designs can circumvent. For Investors and Strategic Acquirers: Pure-play immunology specialists with concentrated assay expertise and validated EU MDR Class C portfolios represent the most attractive acquisition targets for platform-integrated conglomerates seeking menu breadth. Long-term viability hinges on algorithmic diagnostics capabilities under the EU AI Act framework. Watch FDA CLIA categorization shifts as the inflection indicator for point-of-care market access expansion.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Class C Clinical Evidence Generation | Accelerates assay standardization while consolidating demand toward manufacturers with robust quality management systems. |
| Multiplex Assay Platform Integration | Enables reference laboratories to consolidate discrete ELISA workflows without proportional footprint expansion. |
| Algorithmic ANA Pattern Recognition Development | Positions manufacturers for EU AI Act compliance in automated immunofluorescence interpretation. |
| Chain Laboratory Partnership Expansion | Captures procurement scale effects in India's consolidating diagnostic laboratory networks. |
| Point-of-Care Rheumatoid Factor Cartridge Miniaturization | Unlocks specialty clinic channel access by circumventing CLIA high-complexity deployment barriers. |
Research Methodology
Operator-level perspectives from clinical laboratory directors, hospital procurement committee members, regulatory affairs specialists at IVD manufacturers, and rheumatology practice administrators anchored the qualitative base. These primary interviews combined with secondary validation from FDA 510(k) filings, EMA IVD guidance documents, CMS Medicare reimbursement databases, and EU MDR notified body opinions. Bottom-up test volume modeling across hospital, reference, and specialty clinic settings triangulated against top-down market sizing from manufacturer revenue disclosures.
Sensitivity analysis around rheumatology referral network density and CLIA categorization scenarios shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include assay format, detection technology, autoimmune indication, and site of care, with regional regulatory cluster as the industry-specific overlay. CAGRs derived from test volume trajectory analysis and pricing trend extrapolation incorporated recombinant antigen adoption curves and Next-Generation Sequencing substitution elasticities as forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained Medicare reimbursement stability, EU MDR implementation timelines, and immunopathologist training pipeline recovery would require recalibration. Forecasts reflect documented assumptions about referral network concentration and regulatory pathway maturity. Specific risk factors including FDA CLIA reclassification, EU AI Act enforcement patterns, and chemiluminescence substrate supply disruptions could revise projections. Recalibration cycles align with material shifts in reimbursement policy and regulatory guidance issuance.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Global Oral Cancer Rapid Test Kit Market
Diagnostics
Saudi Arabia in-Vitro Diagnostics (IVD) Market
Diagnostics
Global Phytopathological Disease Diagnostics Market
Diagnostics
Animal Diagnostics Market
Diagnostics
Europe Colorectal Cancer Diagnostics Market
Diagnostics
Cancer Tissue Diagnostics Market
Diagnostics
Digital Companion Diagnostics Market
Diagnostics
Canada Latent Tuberculosis Infection Detection Market
Diagnostics
Cancer IVD Market
Diagnostics
Fertility Testing Devices Market
Diagnostics
Fructosamine Reagents Market
Diagnostics
In Vitro Diagnostics (IVD) Quality Control Market
Diagnostics
Microdialysis Market
Diagnostics
Middle East and Africa Ovarian Cancer Diagnostics Market
Diagnostics
Direct Fluorescent Antibody Test Kits Market
Diagnostics
Febrile Antigen Kits Market