
 Alfalfa Market | 2026-2036
Alfalfa Market Size, Share, and Industry Trends Forecast 2026-2036
Alfalfa Market Analysis
Asset-light leasing models for hay-processing equipment are reconfiguring competitive entry barriers across the alfalfa value chain. Anderson Hay & Grain Co., Inc. leverages its vertical integration from field operations to export logistics, sustaining cost advantages in Pacific Rim shipments. Grupo Osés anchors Iberian supply through specialized dehydration facilities, while Standlee Hay Company dominates premium pelleted product lines for equine and small-animal channels.
Alfalfa, Medicago sativa, is a perennial legume containing 15-22% crude protein and high fiber digestibility, cultivated through irrigated or dryland systems and harvested at early bloom for optimal nutritional retention; its primary purpose is protein-rich forage for ruminant livestock and specialized pet nutrition. Dehydrated and pelleted formats command margin concentration due to extended shelf stability and reduced transport costs relative to fresh cut bales. Dairy feed represents the dominant end-use consumption pool, though pet feed segments are expanding as urban households seek premium small-animal nutrition.
The USDA Natural Resources Conservation Service and state-level water boards shape planting decisions through groundwater withdrawal permits and conservation compliance requirements, while FDA feed safety regulations under the Food Safety Modernization Act govern contamination thresholds for interstate commerce. Stakeholders must monitor evolving water-rights adjudication and carbon accounting methodologies, as these frameworks will determine which production basins retain cost-competitive access to dairy and livestock procurement networks.
Market Dynamics
Groundwater withdrawal restrictions across the western United States are compressing planted acreage and forcing capital reallocation toward precision irrigation infrastructure and dehydration capacity upgrades.
Growth Catalysts
- Dairy protein demand:Large-scale dairy operations in California's Central Valley and Idaho's Snake River Plain are expanding herd counts and requiring higher-protein forage rations to maximize milk solids output per cow.
- FSMA compliance infrastructure:FDA feed safety regulations under the Food Safety Modernization Act are mandating contamination monitoring systems that favor suppliers with certified dehydration and pelletization capabilities.
- Equine nutrition premiumization:Urban households with disposable income are purchasing pelleted alfalfa products for companion animals, creating margin expansion in specialty retail channels.
Market Restraints
- Water-rights adjudication:State-level water boards in California, Arizona, and Nevada are reducing groundwater allocation permits for agricultural use, directly constraining expansion of irrigated alfalfa acreage.
- Input cost volatility:Fertilizer and diesel prices fluctuate with energy markets, compressing margins for dryland producers who lack irrigation infrastructure to guarantee yield consistency.
- Substitution by alternative forages:Corn silage and sorghum-sudangrass hybrids compete for dairy feed rations in regions where water constraints make alfalfa production uneconomical.
Strategic Opportunities
- Carbon credit monetization:USDA conservation programs and emerging carbon accounting methodologies may compensate perennial legume growers for soil carbon sequestration, creating new revenue streams.
- Asset-light equipment leasing:Hay-processing machinery leasing models lower entry barriers for new dehydration operators seeking to serve regional dairy cooperatives without full capital commitment.
- Pacific Rim export expansion:Dehydrated and pelleted formats with extended shelf stability enable containerized shipment to Japanese and South Korean dairy and equine markets.
Industry Challenges
- Skilled equipment operator shortage:Precision irrigation system management and dehydration facility operation require technical training that rural labor pools currently undersupply.
- Conservation compliance timelines:USDA Natural Resources Conservation Service enrollment processes and groundwater permit modifications create administrative delays that disrupt planting schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Alfalfa Market |
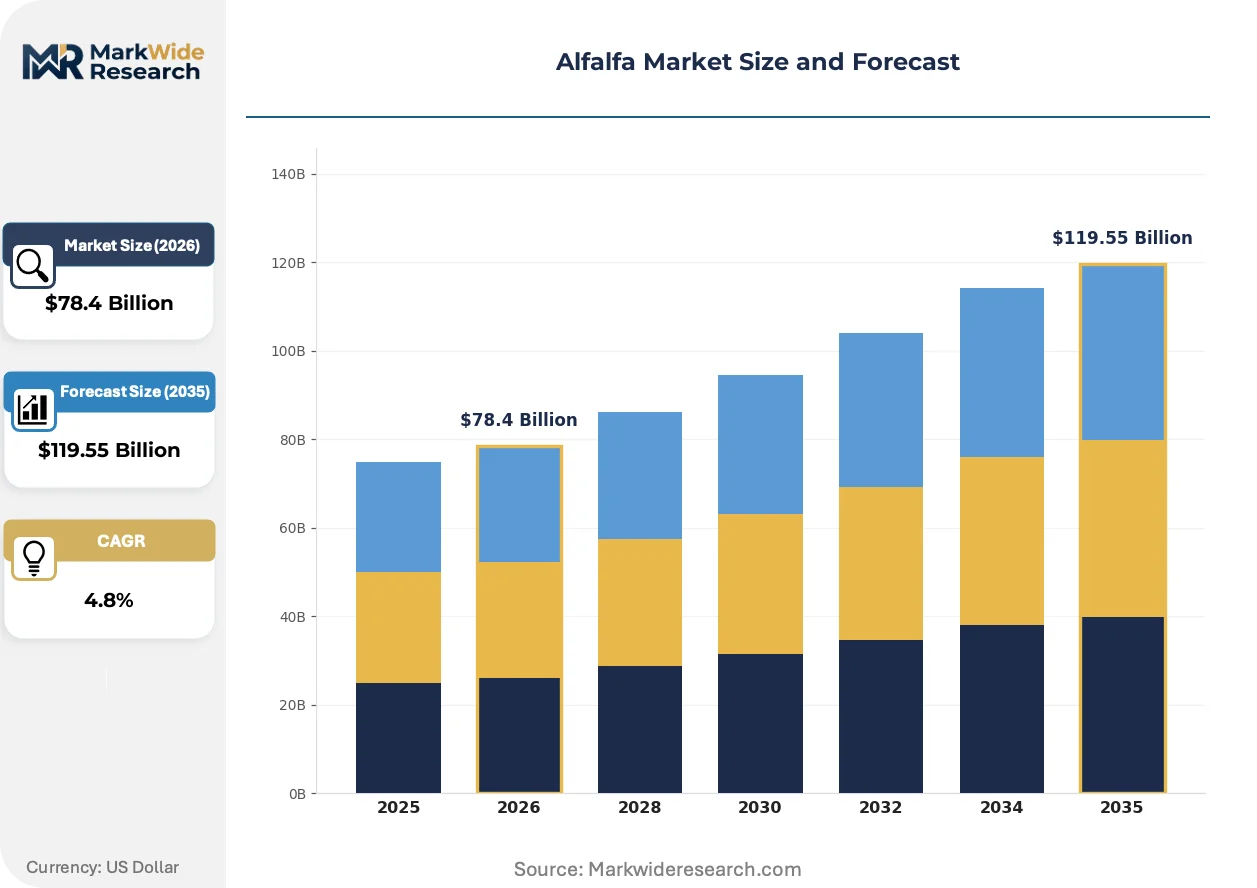
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $119.55 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fresh Cut, Dehydrated, Pelleted, Cubed End Use: Dairy Feed, Livestock Feed, Poultry Feed, Pet Feed Distribution Channel: Direct Sales, Online Sales, Distributors, Retailers Packaging Type: Bales, Bags, Bulk, Boxes |
| Companies Covered | Bailey Farms, Grupo Osés, Anderson Hay & Grain Co., Inc., Green Prairie International Inc., Alfalfa Monegros SL, Al Dahra ACX Global Inc., Aldahra Fagavi, Standlee Hay Company, Border Valley Trading, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Alfalfa Market Emerging Trajectories
Digital soil moisture monitoring and automated irrigation control systems are virtualizing field management decisions, reducing water application rates while maintaining yield targets across drought-stressed growing regions.
Variable-rate irrigation technology paired with satellite-based evapotranspiration mapping is virtualizing water allocation decisions. Dairy cooperatives in California's San Joaquin Valley are deploying these systems at scale. The technology is virtualizing traditional field-walk irrigation scheduling and enabling real-time groundwater use reporting to state water boards.
EPA and state environmental quality agencies are tightening nitrate runoff monitoring requirements for concentrated animal feeding operations. These rules cascade backward to forage suppliers who must document nutrient management practices. Dairy procurement networks in the Upper Midwest are requiring supplier sustainability certifications that exceed baseline federal compliance.
Consolidated dairy operations are unbundling traditional hay broker relationships and establishing direct procurement contracts with dehydration facilities. This disintermediation compresses margin capture for intermediaries while rewarding suppliers with certified food safety systems. The pattern is most visible across Idaho and Utah where large herd operations anchor regional forage demand.
Alfalfa Market Segmentation
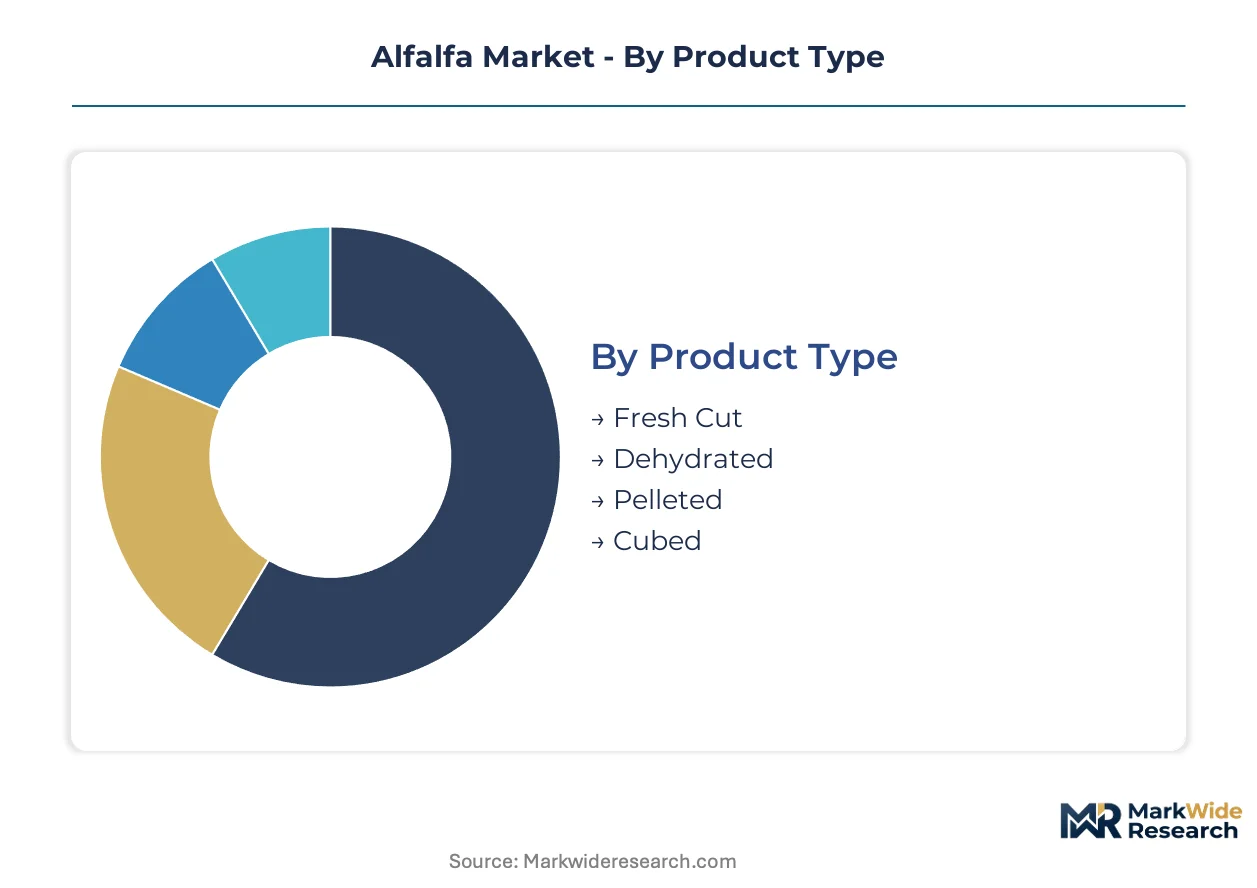
Segmentation in alfalfa markets reveals how processing intensity, end-use nutrition requirements, and logistics economics partition value capture across the value chain. Product format and distribution channel choices determine working capital needs and margin durability for suppliers serving distinct buyer segments.
Product Type:
After-sales service intensity varies sharply across product types, with dehydration and pelletization equipment demanding technical support contracts that reshape supplier-customer relationships.
- Dehydrated:Rapid moisture reduction to below 12% preserves crude protein and carotene content for extended storage. Dairy operations in Idaho's Snake River Plain specify dehydrated formats for year-round ration consistency under FSMA traceability requirements.
- Pelleted:Compression into standardized 6-8mm pellets reduces transport volume by 60% and enables automated feeding systems. Japanese and South Korean importers prefer pelleted products for containerized shipment efficiency and reduced handling labor.
- Fresh Cut:Field-dried hay baled at 15-18% moisture retains leaf integrity for premium equine markets. Regional dairy cooperatives within 200 miles of production source fresh cut for cost minimization.
- Cubed:Compressed 3-4cm cubes suit small-animal feeding systems and companion animal retail channels. Urban pet specialty retailers stock cubed formats for shelf presentation advantages.
By volume, Fresh Cut leads. By growth pace, Pelleted is ahead.
End Use:
Cost tier segmentation separates commodity livestock rations from premium companion animal nutrition, with protein specification thresholds determining procurement contract structures.
- Dairy Feed:High-protein forage rations maximize milk solids output per cow in large-scale operations. California's Central Valley dairies contract directly with dehydration facilities to secure 18-20% crude protein consistency.
- Pet Feed:Premium small-animal nutrition commands retail price multiples through specialized packaging and certification. Urban households in metropolitan areas drive pelleted and cubed product demand through specialty channels.
- Livestock Feed:Beef cattle backgrounding operations utilize mid-protein alfalfa for weight gain efficiency. Intermountain West feedlots source regional production to minimize freight cost absorption.
- Poultry Feed:Limited incorporation into layer rations for yolk pigmentation and amino acid supplementation. Niche applications constrain volume relative to ruminant feed categories.
Dairy Feed dominates procurement volume. Pet Feed climbs the fastest on margin expansion.
Distribution Channel:
Customer type segmentation distinguishes integrated dairy operations from fragmented equine and companion animal buyers, with channel choice reflecting purchase scale and technical service requirements.
- Direct Sales:Large herd operations negotiate multi-year supply agreements with dehydration facilities. FSMA compliance documentation and lot traceability accompany direct procurement contracts.
- Distributors:Regional hay brokers aggregate production from multiple growers for resale to smaller livestock operations. Credit terms and logistics coordination justify distributor margin capture.
- Retailers:Farm supply stores and pet specialty channels serve companion animal owners with bagged pelleted products. Shelf placement fees and promotional support structure retailer relationships.
- Online Sales:E-commerce platforms enable small-lot purchases by urban pet owners seeking subscription delivery convenience. Shipping cost economics limit online channel penetration for bulk forage.
Direct Sales anchors volume concentration. Online Sales expands most quickly from a small base.
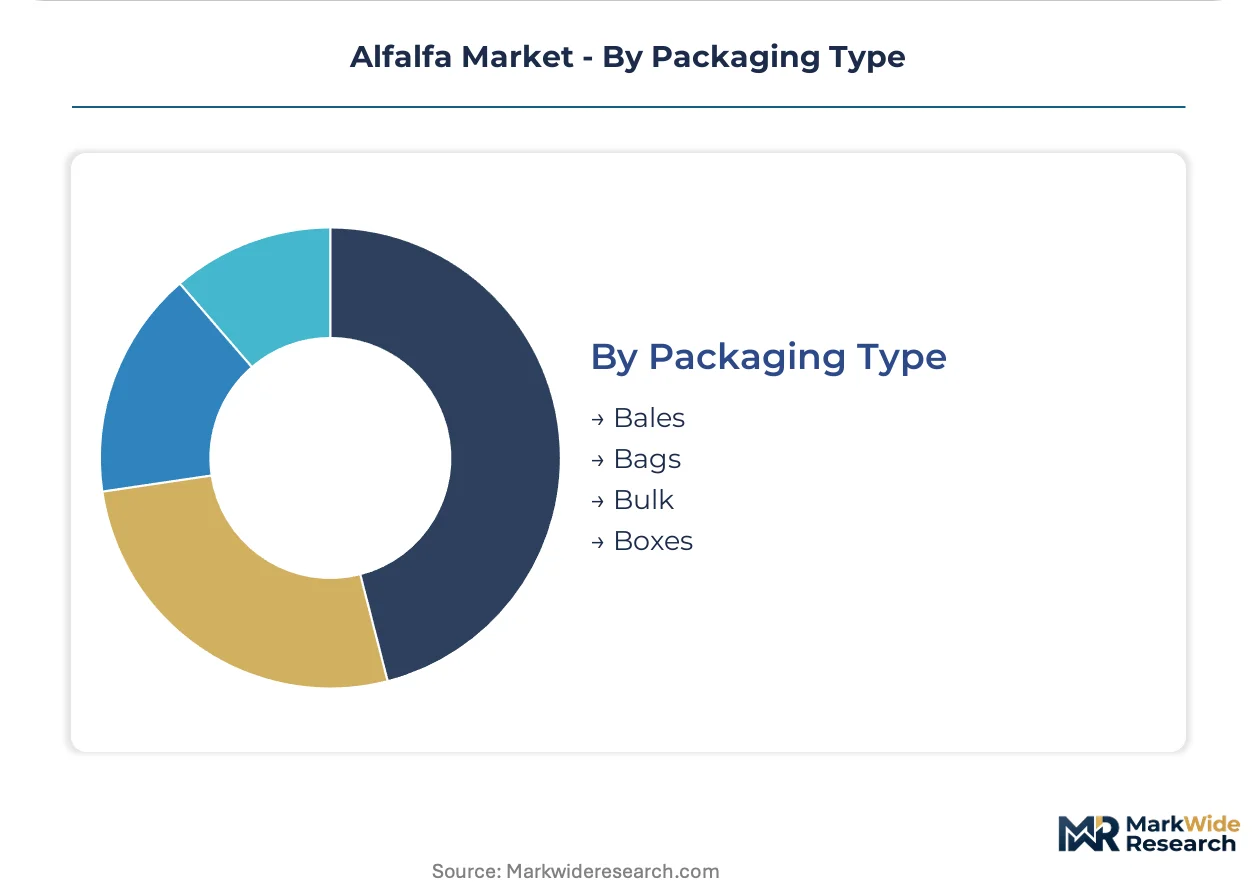
Packaging Type:
Supply concentration in large-scale dairy procurement favors bulk and bale formats, while geographic fragmentation in companion animal channels sustains bag and box demand.
- Bales:Standard 3x4x8 foot rectangular bales optimize truckload cube utilization for dairy feedlot delivery. Field baling equipment represents significant capital investment recovered through volume throughput.
- Bulk:Loose dehydrated product pneumatically conveyed into silos eliminates packaging cost for integrated operations. California dairies with on-site storage capacity specify bulk delivery for cost minimization.
- Bags:50-pound poly-woven bags protect pelleted products from moisture during retail distribution. Pet specialty channels require branded bag presentation for consumer shelf appeal.
- Boxes:Corrugated containers suit premium equine products requiring damage protection and stacking stability. Direct-to-consumer shipments utilize box packaging for parcel carrier compatibility.
Bales lead by volume. Bags gain share fastest on pet channel expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-oriented dehydration capacity concentrates in water-stressed basins where dairy procurement networks pull volume, while import demand clusters in protein-deficient regions with limited arable land. Trade flows favor pelleted and dehydrated formats that withstand containerized shipment. Production economics hinge on groundwater access adjudication and energy costs for thermal processing.
United States
California's Central Valley dairies contract directly with dehydration facilities for 18-20% crude protein consistency, anchoring domestic procurement volume. The USDA Natural Resources Conservation Service enforces groundwater withdrawal permits under the Sustainable Groundwater Management Act, compressing planted acreage in the San Joaquin Valley. Idaho's Snake River Plain hosts large-scale dairy operations that specify dehydrated formats for year-round ration traceability.
Spain
Iberian dehydration facilities serve European dairy and equine markets through specialized thermal processing infrastructure. Spain's national water authority implements basin-level allocation plans that restrict agricultural groundwater extraction in the Ebro Valley. Aragon's Monegros region clusters alfalfa dehydration capacity to supply Mediterranean livestock operations and Middle Eastern export contracts.
United Arab Emirates
Al Dahra ACX Global Inc. anchors forage import and re-export logistics through Abu Dhabi-based processing and distribution infrastructure. The UAE's Ministry of Climate Change and Environment regulates fodder import standards and biosecurity protocols for regional livestock markets. Jebel Ali Free Zone concentrates transshipment capacity serving Saudi Arabian and Qatari dairy operations with limited domestic forage production.
Canada
Prairie province hay production supplies US border-state dairy operations through integrated cross-border logistics networks. Health Canada and the Canadian Food Inspection Agency administer feed safety regulations aligned with FDA Food Safety Modernization Act traceability requirements. Alberta's irrigated valleys sustain dehydration facility operations serving Pacific Northwest dairy cooperatives.
Australia
Murray-Darling Basin irrigators face cumulative water recovery targets under the Basin Plan, constraining perennial legume expansion despite strong Asian export demand. The Australian Pesticides and Veterinary Medicines Authority governs chemical residue thresholds for forage destined to Japanese and South Korean dairy markets. Victoria's northern irrigation districts concentrate dehydration capacity for containerized pelleted shipment to Southeast Asian livestock operations.
Alfalfa Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream. The vendor base arranges across three tiers: multinational forage traders with integrated dehydration and logistics infrastructure, regional hay processors serving single-basin dairy cooperatives, and field-operating growers supplying fresh-cut volume to nearby feedlots. Consolidation pressure intensifies as large herd operations unbundle traditional broker relationships. Dominant competitive moves include direct procurement contract establishment with dehydration facilities and precision irrigation technology deployment to secure yield consistency under water allocation constraints.
Among North American forage specialists, Anderson Hay & Grain Co., Inc. and Standlee Hay Company exemplify divergent strategic positions. Anderson Hay represents integrated field-to-export logistics platforms with Pacific Rim shipment capabilities. Standlee Hay occupies premium pelleted product positioning for companion animal channels. Grupo Osés anchors European dehydration infrastructure with Iberian basin concentration. These three entities illustrate how geographic production access and processing format specialization partition competitive terrain.
| Leading Market Players |
|---|
| Bailey Farms |
| Grupo Osés |
| Anderson Hay & Grain Co., Inc. |
| Green Prairie International Inc. |
| Alfalfa Monegros SL |
| Al Dahra ACX Global Inc. |
| Aldahra Fagavi |
| Standlee Hay Company |
| Border Valley Trading |
| Others |
Supply Flow & Price Mechanics
Containerized shipment corridors from Los Angeles-Long Beach to Yokohama and Busan transmit freight cost volatility directly into Pacific Rim price differentiation, compressing margins for non-integrated exporters while rewarding dehydration operators with captive port logistics. Water-rights scarcity in California's San Joaquin Valley and Idaho's Snake River Plain concentrates supply-side leverage among irrigated producers with precision infrastructure, forcing dryland growers into spot-market price acceptance.
Pricing Analysis
Large-scale dairy operations anchor a contract-based long-term offtake structure, with multi-year supply agreements locking in protein-grade premiums and FSMA traceability compliance. Price differentiation separates certified organic dehydration from conventional commodity bales, while volume scale and geographic proximity to processing infrastructure determine freight absorption capacity. Cost compression in fresh-cut tiers is intensifying because groundwater withdrawal restrictions are shrinking planted acreage and elevating irrigation energy costs. Regional dairy cooperatives within 200 miles of production exhibit highest price sensitivity, whereas Japanese and South Korean importers absorbing containerized pelleted shipments demonstrate lowest sensitivity due to protein-deficient domestic forage bases.
Supply Chain Analysis
Specialized dehydration capacity concentrates in the United States, Spain, and the United Arab Emirates, with each hub serving distinct regional dairy procurement networks. Raw material flows draw from perennial legume cultivation tethered to adjudicated water basins, thermal energy inputs for moisture reduction, and certified seed stock for protein consistency. Single-source vulnerability runs through California's Central Valley groundwater allocation permits, where Sustainable Groundwater Management Act enforcement threatens planted acreage stability. Distribution runs through direct procurement contracts between dehydration facilities and integrated dairy operations, bypassing traditional hay broker intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are reshaping competitive positioning as dairy cooperatives unbundle traditional broker relationships and establish direct digital procurement interfaces with dehydration operators, creating interoperability standards around FSMA traceability and lot-level nutrient certification.
For Market Incumbents: Pre-empt margin compression from asset-light equipment leasing models by securing exclusive multi-year supply agreements with Snake River Plain and Central Valley dairy cooperatives. Invest in backward integration into precision irrigation infrastructure to guarantee yield consistency under state water board allocation constraints. Certify dehydration facilities for Japanese and South Korean export protocols before regional competitors capture Pacific Rim shelf space. For New Entrants and Emerging Players: Build out regional dehydration capacity serving mid-sized dairy operations in Utah and Colorado that lack direct procurement scale but demand FSMA-compliant traceability. Target companion animal pet feed channels in metropolitan areas where pelleted and cubed product premiums exceed livestock feed commodity returns by substantial multiples. Pursue carbon credit monetization partnerships with USDA Natural Resources Conservation Service to differentiate sourcing narratives for sustainability-conscious procurement officers. For Investors and Strategic Acquirers: Carve-out targets emerge from family-owned field operations in the Intermountain West possessing irrigated water rights but lacking dehydration infrastructure or export logistics capabilities. Long-term viability hinges on groundwater adjudication outcomes and carbon accounting methodology standardization across dairy procurement networks. Monitor state water board permit modification timelines as the critical inflection signal for production basin cost competitiveness.| Strategic Initiative | Industry Significance |
|---|---|
| Dehydration Capacity Expansion | Idaho and Utah facilities capture direct procurement contracts from consolidating dairy cooperatives requiring FSMA traceability. |
| Backward Integration into Irrigation Infrastructure | Precision system deployment secures yield consistency under Sustainable Groundwater Management Act allocation constraints. |
| Pacific Rim Export Certification | Japanese Ministry of Agriculture, Forestry and Fisheries and South Korean MFDS compliance enables containerized pelleted shipment premiums. |
| Carbon Credit Program Enrollment | USDA conservation program participation creates revenue streams from soil carbon sequestration in perennial legume cultivation. |
| Direct Procurement Platform Development | Digital interfaces between dehydration facilities and dairy operations disintermediate traditional hay brokers and compress intermediary margins. |
Methodological Framework
Initial hypotheses were tested against primary input from dehydration facility operators, dairy cooperative procurement managers, state water board regulators, precision irrigation system vendors, and export logistics coordinators, and refined through secondary validation against USDA National Agricultural Statistics Service crop reports, FDA Food Safety Modernization Act guidance documents, state groundwater basin adjudication records, and containerized agricultural export trade data. Bottom-up field-level cultivation estimates were triangulated against top-down dairy ration demand modeling.
Demand-supply balance framing anchored the analytical approach across the projection horizon, with segmentation dimensions spanning product format, end-use application, distribution channel, and regional production basin. CAGRs were derived from iterative convergence of supply-side capacity constraints and demand-pull from protein-intensive livestock operations. Forecast inputs incorporated groundwater withdrawal permit trajectories under state-level sustainable management mandates and thermal energy cost curves for dehydration processing.
Stress conditions across water allocation enforcement intensity, diesel and natural gas price bands, and Pacific Rim import tariff schedules were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding dairy herd expansion rates and companion animal nutrition premiumization trajectories. Quarterly review of state water board permit modification calendars and USDA conservation program enrollment data is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Seaweed Algae Market
Agriculture and Agri Products
Global Ruminant Feed Market
Agriculture and Agri Products
Egypt Compound Feed Market
Agriculture and Agri Products
Algae-Based Animal Feed Market
Agriculture and Agri Products
Canada Ornamental Horticulture Market
Agriculture and Agri Products
Corn Gluten Feed Concentrates Market
Agriculture and Agri Products
Germany Animal Protein Market
Agriculture and Agri Products
Compound Feed Market
Agriculture and Agri Products
Global Quail Eggs Market
Agriculture and Agri Products
United States Floriculture Market
Agriculture and Agri Products
Agriculture in Egypt Market
Agriculture and Agri Products
Africa Olive Market
Agriculture and Agri Products
Potting Soil Market
Agriculture and Agri Products
Specialty Egg Market
Agriculture and Agri Products
LAMEA Artificial Humus Market
Agriculture and Agri Products
United Arab Emirates Poultry Meat Market