
 Global Forage Sorghum Seed Market | 2026-2036
Global Forage Sorghum Seed Market Size, Share, and Industry Trends Forecast 2026-2036
Global Forage Sorghum Seed Market Foresight
Premium certified seed tiers is rotating demand away from commodity open-pollinated lines across major dairy and beef production belts. Corteva Agriscience leverages its trait pipeline to dominate hybrid development programs. KWS SAAT SE anchors European breeding operations while extending drought-tolerance genetics into semi-arid zones. Bayer AG competes through integrated crop science platforms that bundle seed with digital agronomy tools.
Forage sorghum seed comprises genetically improved sorghum bicolor germplasm selected for high biomass yield, digestible fiber content exceeding 55% neutral detergent fiber, and photoperiod sensitivity suited to multi-cut silage systems. Its primary purpose is to supply fermentable carbohydrate and protein feedstock for ruminant livestock operations. Hybrid seed types command the dominant value share due to proprietary trait protection and consistent yield premiums over conventional alternatives. Silage production applications generate the fastest demand expansion as dairy processors scale herd sizes and seek alternative forages to alfalfa amid water constraints.
USDA Plant Variety Protection regulations, Brazil's MAPA seed certification mandates, and Australia's PBR Act collectively shape market access by enforcing distinct purity standards and royalty collection frameworks for improved germplasm. The EU's F-Gas Regulation indirectly pressures livestock operators toward lower-methane feed rations, elevating interest in brown midrib sorghum hybrids with reduced lignin. Stakeholders must monitor evolving seed patent enforcement across Brazil and Argentina, where intellectual property gaps continue to divert procurement toward uncertified farm-saved seed channels.
Market Dynamics
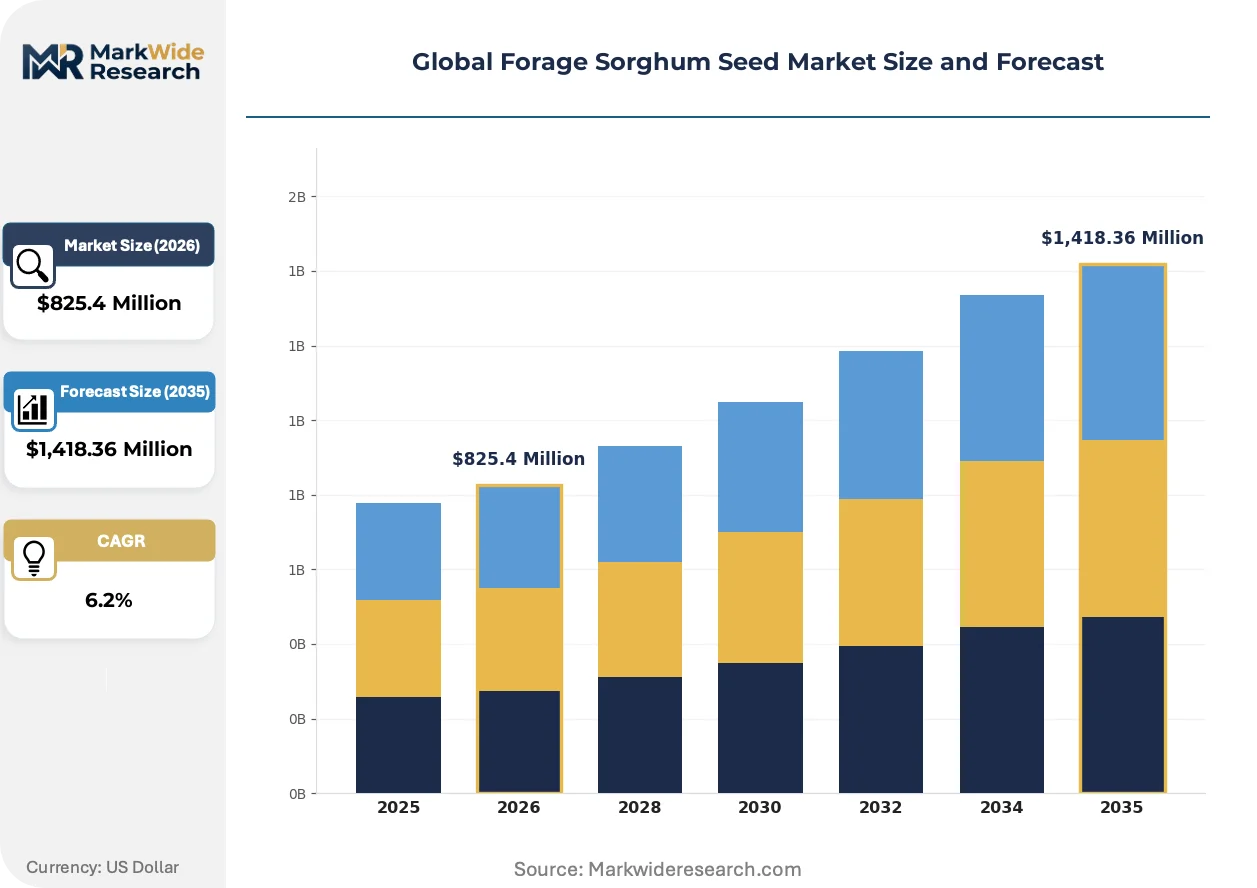
Climate-adaptive breeding protocols are redirecting procurement toward certified seed tiers across major livestock production belts, compressing demand for open-pollinated commodity lines and elevating trait-protected hybrid premiums.
Growth Catalysts
- Drought-Tolerance Trait Stacking:Multi-gene pyramiding for water-stress resilience is expanding addressable acreage in semi-arid zones. Argentina's Cerrado and Australia's Darling Downs are converting marginal lands to forage sorghum silage systems.
- EU F-Gas Regulation:Pressure toward lower-methane feed rations is elevating brown midrib sorghum hybrids with reduced lignin content. Dairy processors in Northern Europe are reformulating rations to comply with emissions benchmarks.
- Multi-Cut Silage Systems:Photoperiod-sensitive varieties enabling three to four harvest cycles per season are displacing single-cut alternatives. Large-scale dairy operations in Brazil's Minas Gerais state are retrofitting equipment for sequential harvesting.
Market Restraints
- Input Cost Volatility:Nitrogen fertilizer price swings compress margins for seed multiplication programs. Parent line maintenance in isolated breeding nurseries requires sustained nutrient-intensive cultivation cycles.
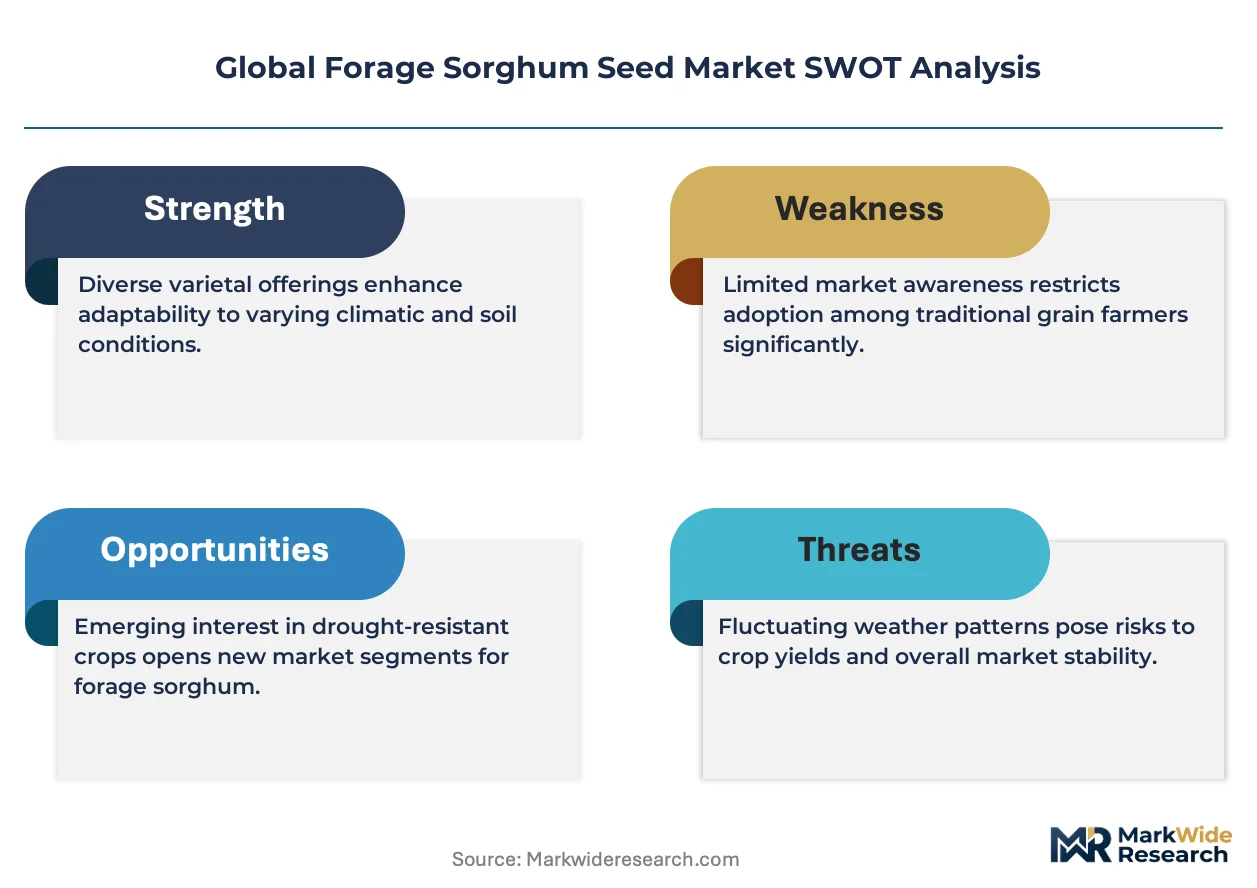
- Supply Concentration Risk:Proprietary germplasm pools concentrate among three major breeding houses. Argentina and Brazil exhibit persistent intellectual property enforcement gaps that divert volume toward uncertified farm-saved seed channels.
- Technical Limitation:Cytoplasmic male sterility systems impose genetic bottlenecks. Narrow cytoplasmic diversity in hybrid seed production increases vulnerability to race-specific pathogen outbreaks.
Strategic Opportunities
- Underpenetrated Geography:India's rainfed Deccan Plateau offers expansion potential for dual-purpose grain-forage sorghum hybrids. State agricultural universities are evaluating photoperiod-insensitive introductions for kharif season integration.
- Regulatory Tailwind:Australia's Plant Breeders Rights Act amendments strengthen royalty collection on farm-saved seed. Certified seed penetration in Queensland's Darling Downs could replicate patterns established in US Great Plains jurisdictions.
- Technology Convergence:Genomic selection platforms combined with rapid generation advance protocols compress breeding cycle duration. Private breeding programs are integrating predictive analytics with field phenotyping networks.
Industry Challenges
- Quantitative Genetics Expertise Gap:Commercial breeding programs face scarcity of specialists in multi-environment trial design and genotype-by-environment interaction modeling. University pipeline output lags industry expansion requirements.
- Seed Certification Timeline Compression:Distinctness, uniformity, and stability testing protocols extend variety release schedules. Brazil's MAPA mandate for field inspection and laboratory analysis creates regulatory lag relative to competitor jurisdictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Forage Sorghum Seed Market |
| Market Size in 2026 | $825.4 Million |
| Market Size in 2035 | $1,418.36 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Seed Type: Hybrid, Conventional, Genetically Modified, Open Pollinated Application: Livestock Feed, Silage Production, Erosion Control, Biofuel Feedstock End User: Dairy Farms, Beef Producers, Poultry Farms, Aquaculture Facilities Packaging Type: Bulk Bags, Retail Packs, Vacuum Sealed Bags, Sacks |
| Companies Covered | Advanta Seeds, Royal Barenbrug Group, Corteva Agriscience, Seed Co Limited, S&W Seed Company, Bayer AG, DLF A/S, Richardson Seeds, KWS SAAT SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Forage Sorghum Seed Market Shifts & Advancements
Digital agronomy platforms are converging with molecular breeding tools to compress variety development timelines and redirect farmer purchasing behavior toward performance-guaranteed seed tiers.
CRISPR-based gene editing for lignin biosynthesis pathway modification is fragmenting conventional brown midrib trait licensing structures. Seed companies with stacked proprietary edits are bypassing royalty obligations to public-sector germplasm sources. Multi-national breeding houses are renegotiating material transfer agreements to capture edited-line value.
The EU's F-Gas Regulation is indirectly elevating feed ration reformulation requirements across member state dairy sectors. Processors are mandating lower-methane forage ingredients in procurement specifications. Brown midrib sorghum hybrids with reduced acid detergent lignin are capturing premium positioning in Danish and Dutch supply contracts.
Large dairy cooperatives are consolidating seed purchasing through centralized procurement consortia. Volume aggregation platforms are displacing distributor-mediated transactions in the US Upper Midwest and São Paulo state. Direct contracting with breeding houses enables price transparency and performance-based rebate structures previously intermediated by regional dealers.
Global Forage Sorghum Seed Market Segmentation
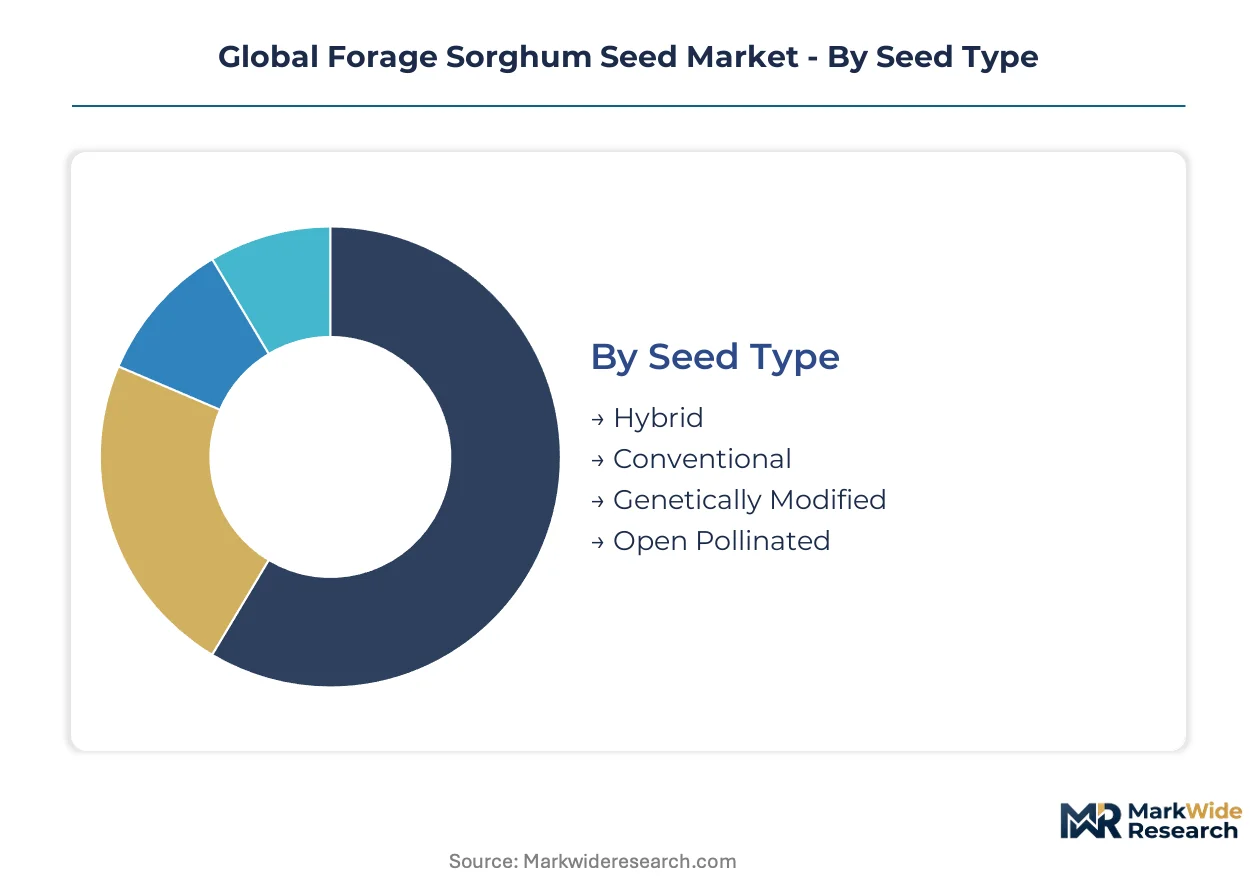
Segmentation in forage sorghum seed tracks how proprietary genetics, certification tiers, and feed-system specifications redirect procurement budgets across distinct customer workflows. Breeders calibrate trait packages and distribution channels to match the technical requirements of large-scale silage operators versus commodity livestock producers.
Seed Type:
Certified hybrid seed flows through distributor networks and direct breeding-house contracts, while conventional and farm-saved alternatives concentrate in informal local channels with minimal quality assurance.
- Hybrid:Proprietary trait-protected germplasm combining cytoplasmic male sterility systems with stacked drought-tolerance genetics. Dairy operations in Brazil's Minas Gerais and the US Great Plains are consolidating procurement through volume aggregation platforms that bypass traditional dealer markups. Premium positioning reflects consistent yield premiums and royalty-enforced intellectual property protection.
- Conventional:Open-pollinated lines without proprietary trait licensing, typically sourced from public breeding programs or expired-patent germplasm. Beef producers in Argentina's Córdoba province and Australia's Queensland maintain demand for lower-input systems where seed cost minimization outweighs yield optimization.
- Genetically Modified:Transgenic events incorporating herbicide tolerance or insect resistance traits approved under jurisdiction-specific biosafety frameworks. Regulatory fragmentation between USDA deregulation and EU GMO restrictions limits addressable geography.
- Open Pollinated:Farmer-saved seed from established varieties with no varietal purity guarantees or performance certification. Persistent intellectual property enforcement gaps in Brazil and Argentina divert substantial volume into uncertified channels.
Hybrid dominates installed base. Genetically Modified is where expansion concentrates.
Application:
Margin structures diverge sharply between high-specification silage contracts and commodity feed rations, with erosion control and biofuel applications commanding minimal breeding investment.
- Silage Production:Photoperiod-sensitive varieties selected for multi-cut harvest cycles, high fermentable carbohydrate content, and digestible fiber exceeding 55% neutral detergent fiber. Large dairy processors in Denmark and the Netherlands are mandating brown midrib hybrids with reduced acid detergent lignin to comply with EU F-Gas Regulation methane benchmarks.
- Livestock Feed:Dual-purpose grain-forage types supplying direct grazing or green chop systems. India's Deccan Plateau rainfed districts are evaluating photoperiod-insensitive introductions for kharif season integration by state agricultural universities.
- Erosion Control:Rapid-establishment biomass types prioritized for ground cover rather than nutritional quality. Highway and mining reclamation contractors in Australia's Darling Downs specify quick canopy closure.
- Biofuel Feedstock:High-cellulose, low-moisture varieties for lignocellulosic ethanol conversion. Limited commercial traction due to competing feedstock economics from corn stover and sugarcane bagasse.
Silage Production commands premium pricing. Livestock Feed retains volume leadership.
End User:
Customer scale and technical sophistication determine whether procurement flows through centralized consortia or fragmented dealer networks.
- Dairy Farms:Large-scale operations with nutritionist-formulated rations and silage infrastructure. Consolidated purchasing consortia in the US Upper Midwest and São Paulo state are displacing distributor-mediated transactions.
- Beef Producers:Extensive grazing operations prioritizing cost efficiency over feed conversion metrics. Argentina's Cerrado expansion is converting marginal lands to forage sorghum from native pasture.
- Poultry Farms:Limited adoption due to sorghum's inferior amino acid profile versus soybean meal and corn. Niche applications in organic systems seeking non-GMO feed ingredients.
- Aquaculture Facilities:Experimental inclusion in herbivorous fish diets. No established commercial demand from shrimp or salmon operations.
Dairy Farms anchor certified seed demand. Beef Producers represent the steepest expansion trajectory.
Packaging Type:
Logistics configuration aligns with customer scale and seed viability requirements under tropical storage conditions.
- Bulk Bags:Unitized totes for large-scale operators with on-farm seed treatment and planting equipment. Direct-to-farm delivery from breeding house conditioning facilities.
- Retail Packs:Small-unit packaging for hobby farmers and specialty livestock operations. Agrochemical dealer networks handle final-mile distribution.
- Vacuum Sealed Bags:Extended viability preservation for humid climates and long-distance export. Australia's Plant Breeders Rights Act amendments are strengthening royalty collection on farm-saved seed, elevating certified packaging penetration in Queensland.
- Sacks:Woven polypropylene for conventional varieties with minimal quality assurance. Informal markets in Brazil's Mato Grosso and Argentina's Santa Fe.
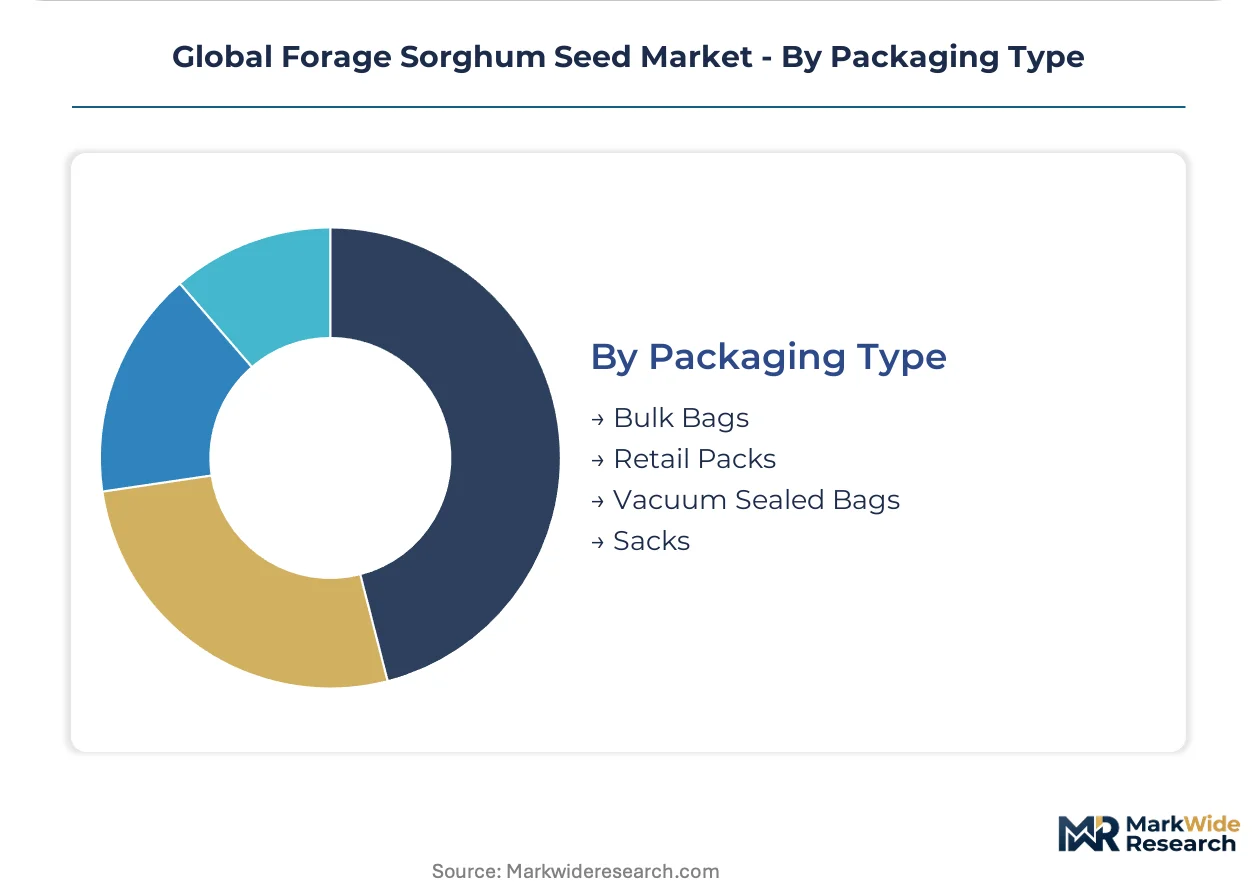
Bulk Bags dominate commercial throughput. Vacuum Sealed Bags is where quality-tier expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Proprietary germplasm development concentrates among breeding houses with established operations in water-stressed agricultural zones. Certified seed demand clusters where dairy herd expansion intersects with irrigation constraints and regulatory pressure on feed emissions. Each major production belt exhibits distinct procurement patterns shaped by intellectual property enforcement intensity and farm-scale consolidation.
United States
Dairy operations across the Great Plains are retrofitting silage infrastructure for multi-cut harvest systems. USDA Plant Variety Protection regulations enforce royalty collection on farm-saved seed, compressing uncertified channels. Kansas and Nebraska field stations are evaluating photoperiod-sensitive hybrids for sequential cutting cycles.
Brazil
Minas Gerais dairy processors are mandating brown midrib hybrids to meet processor sustainability specifications. MAPA seed certification mandates extend field inspection timelines, creating regulatory lag versus competitor jurisdictions. São Paulo state purchasing consortia are displacing traditional distributor networks with direct breeding-house contracts.
Argentina
Córdoba beef producers are converting marginal Cerrado lands from native pasture to forage sorghum silage systems. Intellectual property enforcement gaps persist, diverting substantial volume toward uncertified farm-saved seed channels. Santa Fe informal markets maintain demand for woven polypropylene sack packaging without quality assurance.
Australia
Queensland's Darling Downs operations face Plant Breeders Rights Act amendments strengthening royalty collection on farm-saved seed. Vacuum-sealed packaging penetration is expanding as certified seed displaces informal channels. Highway and mining reclamation contractors specify rapid-establishment biomass types for ground cover applications.
India
State agricultural universities across the Deccan Plateau are evaluating photoperiod-insensitive dual-purpose hybrids for kharif season integration. Rainfed districts maintain demand for lower-input open-pollinated lines where seed cost minimization outweighs yield optimization. Maharashtra and Karnataka field trials are assessing drought-tolerance trait stacking for marginal land conversion.
Global Forage Sorghum Seed Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with trait-protected hybrid developers commanding premium positioning while open-pollinated suppliers compete on price. The market exhibits tiered consolidation: multinational breeding houses with integrated crop science platforms occupy the premium segment, regional specialists with localized germplasm adaptation serve mid-tier demand, and informal farm-saved channels capture residual volume. Strategic moves center on genomic selection platform deployment and direct-to-farm contracting structures that bypass distributor markups.
Within the multinational breeding house tier, Corteva Agriscience leverages its trait pipeline for hybrid development programs, while KWS SAAT SE anchors European operations with drought-tolerance genetics extension into semi-arid zones. Bayer AG competes through integrated platforms bundling seed with digital agronomy tools. Among regional specialists, Advanta Seeds and S&W Seed Company occupy positions in certified hybrid distribution networks across water-stressed production belts.
| Leading Market Players |
|---|
| Advanta Seeds |
| Royal Barenbrug Group |
| Corteva Agriscience |
| Seed Co Limited |
| S&W Seed Company |
| Bayer AG |
| DLF A/S |
| Richardson Seeds |
| KWS SAAT SE |
| Others |
Supply & Pricing Matrix
Parent line maintenance in isolated breeding nurseries demands sustained nutrient-intensive cultivation cycles, creating scale economies that concentrate germplasm development among three multinational breeding houses and compress price floors for certified hybrid tiers. This concentration elevates royalty-enforced premiums while informal farm-saved channels in Argentina and Brazil capture residual volume at cost-minimized price points.
Pricing Analysis
USDA Plant Variety Protection regulations dictate the pricing tier structure across the North American Great Plains, establishing royalty collection frameworks that separate certified hybrid premiums from uncertified commodity alternatives. Price differentiation rests on intellectual property enforcement intensity and volume scale, with large dairy cooperatives in São Paulo state extracting performance-based rebates through direct breeding-house contracts. Cost compression in conventional open-pollinated tiers is intensifying because nitrogen fertilizer volatility erodes seed multiplication margins. Beef producers in Argentina's Córdoba province exhibit highest price sensitivity, while consolidated dairy operations in Denmark and the Netherlands absorb brown midrib premiums to comply with EU F-Gas Regulation methane benchmarks.
Supply Chain Analysis
Strategic stockpile preferences dominate breeding house inventory management, with parent line reserves maintained across multi-year multiplication cycles to buffer against climatic disruption in isolated nursery locations. Germplasm development concentrates in the United States, Germany, and Brazil, drawing from proprietary cytoplasmic male sterility systems, drought-tolerance trait stacks, and rapid generation advance protocols. Supply chain risk centers on narrow cytoplasmic diversity that increases vulnerability to race-specific pathogen outbreaks. Distribution runs through direct-to-farm contracting structures that displace traditional dealer networks in the US Upper Midwest and São Paulo state, while vacuum-sealed packaging extends viability for humid climate exports to Queensland's Darling Downs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Multi-environment trial design expertise and genotype-by-environment interaction modeling capability gaps constrain commercial breeding program expansion, creating competitive advantage for organizations with captive quantitative genetics talent pipelines.
For Market Incumbents: Shield proprietary trait pipelines through accelerated genomic selection platform deployment and backward integration into rapid generation advance facilities. Corteva Agriscience and KWS SAAT SE must deepen cytoplasmic diversity reserves to mitigate pathogen outbreak vulnerability. Patent enforcement investment in Brazil and Argentina closes farm-saved seed diversion channels that erode royalty capture. For New Entrants and Emerging Players: Differentiate on localized germplasm adaptation for India's rainfed Deccan Plateau, where state agricultural university partnerships unlock kharif season integration pathways. The most penetrable geography remains Queensland's Darling Downs under Australia's amended Plant Breeders Rights Act, where vacuum-sealed certified packaging displaces informal channels. Pursue direct contracting with mid-scale dairy operations bypassed by multinational volume aggregation platforms. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors regional specialists with established field phenotyping networks and genomic selection infrastructure. Long-term viability over the projection horizon hinges on breeding cycle compression capabilities that match multinational R&D throughput. Acquisition targets should display integrated rapid generation advance protocols and predictive analytics deployment. The signal to watch is CRISPR-based lignin pathway editing patent filings that fragment conventional brown midrib licensing structures and renegotiate material transfer agreement economics.| Strategic Initiative | Industry Significance |
|---|---|
| Genomic Selection Platform Deployment | Compresses breeding cycle duration for drought-tolerance trait stacking programs. |
| Direct-to-Farm Contracting Expansion | Displaces distributor markups in São Paulo and US Upper Midwest procurement. |
| Cytoplasmic Diversity Reserve Buildout | Mitigates pathogen vulnerability in hybrid seed production systems. |
| CRISPR-Based Lignin Editing Patent Portfolio | Bypasses royalty obligations to public-sector brown midrib germplasm sources. |
| Multi-Cut Silage Infrastructure Retrofit | Enables sequential harvesting for large-scale dairy operations in Minas Gerais. |
Research Methodology
Initial hypotheses were tested against primary input from breeding program directors, dairy nutritionists, seed certification officers, and agricultural procurement managers at large cooperatives and refined through secondary validation. Primary fieldwork combined structured interviews with germplasm development executives and distributor network operators across the United States, Brazil, Argentina, and Australia. Secondary sources included USDA Plant Variety Protection filings, Brazil's MAPA seed certification records, Australia's Plant Breeders Rights Act amendments, EU F-Gas Regulation implementation guidance, and trade flow data from customs authorities. Bottom-up acreage and pricing estimates were triangulated against top-down market sizing from breeding house revenue disclosures.
Variance decomposition across seed type, application, end user, and packaging format segments drove analytical framework construction over the projection horizon. CAGRs were derived from modeled adoption curves for certified hybrid penetration and displacement rates of farm-saved channels under strengthening intellectual property enforcement. Industry-specific forecast inputs incorporated nitrogen fertilizer price elasticity effects on seed multiplication margins and photoperiod-sensitive variety adoption rates in multi-cut silage systems.
The analysis sits within stated boundaries; outcomes outside sustained drought-tolerance trait stacking efficacy and regulatory enforcement intensity in Brazil and Argentina would require recalibration. Forecasts reflect assumptions regarding cytoplasmic male sterility system stability and EU F-Gas Regulation methane benchmark stringency. Revision becomes warranted when pathogen resistance breakthroughs or gene editing regulatory reclassification cross thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seeds
Punnet Market
Seeds
Africa Sorghum Seed Market
Seeds
Nepal Seeds Market
Seeds
India Forage Seed Market
Seeds
South Africa Forage Seed Market
Seeds
Europe Flaxseeds Market
Seeds
Europe Vegetable Seed Market
Seeds
North America Cannabis Seeds Market
Seeds
Fruit Seed Waste Market
Seeds
Russia Seed Market
Seeds
South America Quinoa Seeds Market
Seeds
Psyllium Seed Market
Seeds
Vietnam Seed Market
Seeds
Asia-Pacific Forage Seed Market
Seeds
Flax Seed Market
Seeds
South Africa Seed Market