
 Potting Soil Market | 2026-2036
Potting Soil Market Size, Share, and Industry Trends Forecast 2026-2036
Potting Soil Market Analysis
Multi-source procurement of raw peat and alternative fibers is consolidating around vertically integrated suppliers with captive bog reserves. Scotts Miracle-Gro anchors North American volume through controlled distribution at home improvement chains. Klasmann-Deilmann dominates European professional-grade supply with exacting substrate specifications for greenhouse operators. Sun Gro Horticulture leverages Canadian peat moss access to sustain bulk pricing leverage across commercial grower accounts.
Potting soil is a formulated growing medium engineered from peat moss, composted bark, perlite, vermiculite, and stabilized organic matter, blended to achieve specific air-filled porosity, water-holding capacity, and electrical conductivity parameters for containerized plant cultivation. Organic formulations now command premium positioning as peat-based lines face sustainability headwinds from retailer procurement policies. Coco coir segments are expanding fastest among hydroponic and controlled-environment agriculture operators seeking renewable substrate alternatives. Commercial growers represent the deepest margin pool, with nursery and greenhouse operations demanding batch-consistent, custom-blended substrates at scale.
EPA wetland protections constrain peat harvesting permits in Minnesota and Florida, while ECHA's REACH framework governs chemical additive disclosure across European formulations. The EU Green Deal's peatland restoration targets are directly reshaping product development roadmaps for manufacturers serving EU member states. Stakeholders must monitor substrate innovation pipelines and regulatory filing timelines to secure positioning before peat-restriction thresholds tighten procurement requirements.
Market Dynamics
The EU Green Deal's peatland restoration mandates are forcing substrate manufacturers to reformulate product lines around renewable fiber alternatives, compressing development timelines and rewiring raw-material procurement networks across Northern Europe.
Growth Catalysts
- Urban Gardening Surge:Retail consumers in dense metropolitan clusters are converting balconies and rooftops into cultivation spaces, pulling bagged substrate volumes through home improvement channels and specialty garden centers.
- REACH Framework Compliance:ECHA's chemical disclosure requirements are standardizing additive transparency across European formulations, creating competitive advantage for early-compliant suppliers in professional horticulture segments.
- Hydroponic Substrate Demand:Controlled-environment agriculture operators are adopting coco coir and rockwool blends for precision irrigation systems, displacing conventional peat in greenhouse vegetable production.
Market Restraints
- Peat Harvest Permit Constraints:EPA wetland protections in Minnesota and Florida are constricting domestic raw material access, forcing North American blenders toward costlier Canadian import dependence.
- Alternative Fiber Supply Concentration:Coco coir processing clusters in Sri Lanka and India create single-origin vulnerability for manufacturers pivoting from peat-based lines.
- Batch Consistency Limitations:Composted bark and organic waste streams exhibit higher variability than sphagnum peat, complicating quality assurance for greenhouse operators requiring electrical conductivity stability.
Strategic Opportunities
- Professional Grower Custom Blending:Nursery and greenhouse operators in the Netherlands and Belgium are contracting bespoke substrate formulations with precise air-filled porosity specifications, opening margin-rich service revenue streams.
- EU Carbon Border Adjustment:The CBAM's phased implementation is incentivizing regional sourcing of renewable fibers, advantaging European manufacturers with established alternative supply chains.
- Direct-to-Grower Digital Channels:E-commerce platforms are disintermediating traditional distributor relationships for mid-scale commercial operators, enabling subscription-based substrate replenishment models.
Industry Challenges
- Substrate Science Talent Scarcity:Formulation chemists with expertise in engineered growing media physics are concentrated among legacy peat companies, constraining innovation capacity at alternative-fiber entrants.
- Composting Infrastructure Capex:Localized aerobic digestion facilities for bark and green waste processing require substantial capital deployment, delaying regional self-sufficiency timelines for manufacturers.
- Organic Certification Timelines:OMRI and EU organic input approval processes extend 18-24 months, compressing product launch windows for peat-free lines targeting premium positioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Potting Soil Market |
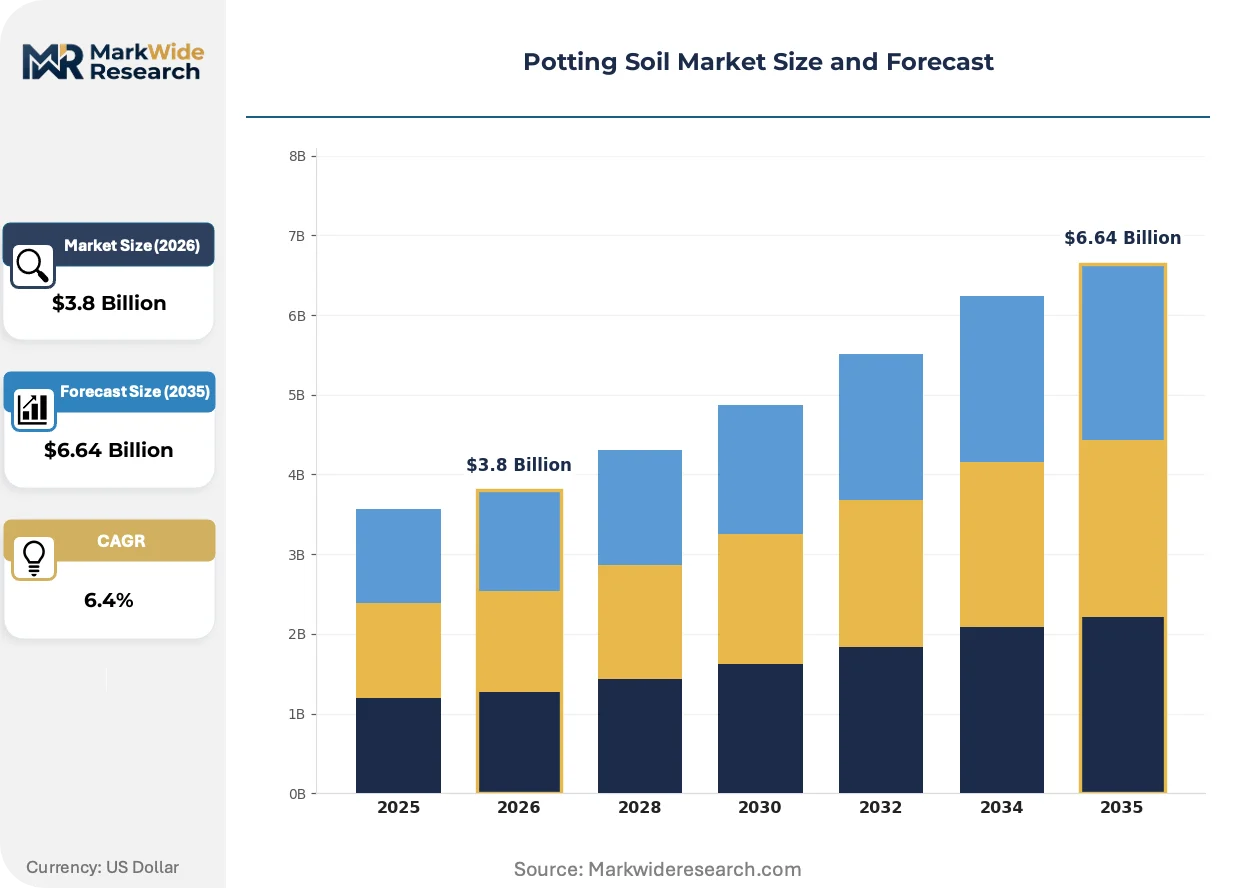
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic, Inorganic, Peat-based, Coco Coir End User: Retail Consumers, Commercial Growers, Plant Nurseries, Landscape Professionals Packaging Type: Bags, Bulk, Boxes, Tubs Distribution Channel: Online Retail, Garden Centers, Home Improvement Stores, Agricultural Supply Stores |
| Companies Covered | ASB Greenworld, FoxFarm Soil & Fertilizer, Scotts Miracle-Gro, Lambert, Compo, Sun Gro Horticulture, Espoma, Premier Tech, Klasmann-Deilmann, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Potting Soil Market Emerging Trajectories
Substrate engineering is fragmenting from standardized peat-based commodities toward precision-formulated growing media, with digital monitoring integration and renewable fiber processing driving the most consequential product architecture shifts.
Engineered biochar incorporation is modularizing carbon sequestration functionality directly into potting soil matrices. Greenhouse operators in the Netherlands are piloting biochar-amended substrates for tomato and pepper propagation, attracted by permanent carbon storage credentials and enhanced cation exchange capacity. This technology is modularizing sustainability reporting capabilities into substrate specifications, enabling growers to document Scope 3 emissions reductions for retail buyer compliance.
REACH chemical restriction expansions are tightening allowable additive portfolios for European substrate formulations. ECHA's proposed microplastic limitations are forcing manufacturers to eliminate synthetic wetting agents and colorants from professional-grade lines, accelerating natural surfactant research programs. Greenhouse vegetable producers in Spain and Italy are reformulating irrigation protocols to compensate for reduced water retention performance in compliant substrates.
Consolidated buying cooperatives are aggregating substrate demand among mid-scale nursery operators, compressing supplier negotiation leverage. In Germany, Rhineland-Palatinate horticulture associations are pooling annual volume commitments to secure custom-blended specifications at standardized pricing tiers, displacing individual procurement relationships. This collective purchasing behavior is most visible among ornamental plant propagators facing margin pressure from energy-intensive climate control operations.
Potting Soil Market Segmentation
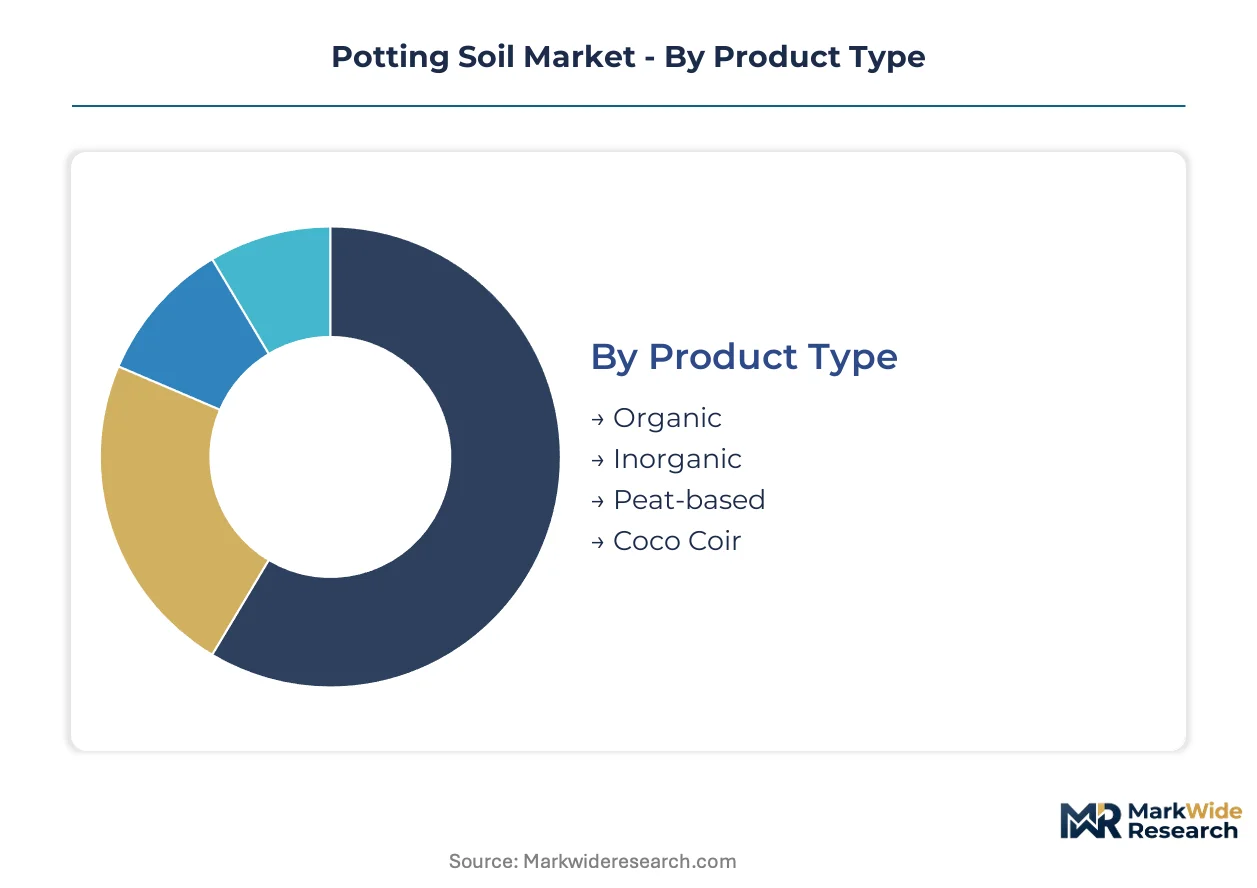
Potting soil segmentation reveals divergent margin architectures across consumer and professional channels. Product formulation, packaging economics, and distribution access each create distinct competitive battlegrounds for substrate suppliers.
Product Type:
Volume concentrates in peat-based commodity lines, while premium positioning clusters around certified organic and renewable fiber alternatives.
- Peat-based:Formulated from sphagnum moss with controlled decomposition grades, this segment dominates greenhouse propagation for vegetables and ornamentals. German professional horticulture clusters in Lower Saxony and North Rhine-Westphalia sustain bulk procurement despite EU Green Deal pressure.
- Organic:Composted bark, green waste, and stabilized manure blends certified under EU organic input regulations. Netherlands-based greenhouse operators are converting propagation lines to meet retailer sustainability procurement mandates.
- Coco Coir:Processed coconut husk fiber with high lignin content and superior drainage characteristics. Sri Lankan and Indian processing clusters supply hydroponic vegetable producers.
- Inorganic:Perlite, vermiculite, and rockwool blends for precision irrigation systems in controlled-environment agriculture.
Today's leader: Peat-based. Tomorrow's challenger: Organic.
End User:
Customer type determines specification intensity, with commercial accounts demanding batch consistency and retail consumers prioritizing convenience and price accessibility.
- Commercial Growers:Large-scale greenhouse and nursery operations requiring custom-blended substrates with exacting air-filled porosity and electrical conductivity parameters. Belgian tomato propagators in Flanders contract annual volumes with embedded quality assurance protocols.
- Plant Nurseries:Mid-scale propagation facilities serving regional landscaping and retail garden center channels. Rhineland-Palatinate ornamental specialists are consolidating purchasing through cooperative buying arrangements.
- Retail Consumers:Urban balcony and rooftop gardeners purchasing bagged substrates through home improvement and specialty retail. Metropolitan density in Paris, Berlin, and Amsterdam drives volume.
- Landscape Professionals:Installation contractors requiring bulk delivery and project-scale consistency for municipal and commercial grounds maintenance.
Commercial Growers capture the deepest margin pool. Retail Consumers are gaining share fastest.
Packaging Type:
Packaging economics separate high-frequency replenishment models from project-based procurement, with logistics cost structures dictating channel viability.
- Bulk:Loose substrate delivered by pneumatic trailer or tipper truck for greenhouse operators with on-site storage infrastructure. Netherlands logistics hubs optimize last-mile distribution to concentrated greenhouse zones.
- Bags:Standard retail formats ranging from small consumer packs to professional 80-liter sacks. German garden center chains specify pallet configurations for automated warehousing.
- Boxes:E-commerce optimized packaging with dimensional weight efficiency for direct-to-consumer subscription models.
- Tubs:Reusable containers for premium organic lines targeting sustainability-conscious urban gardeners.
Bulk commands professional volume. Bags anchor retail accessibility.
Distribution Channel:
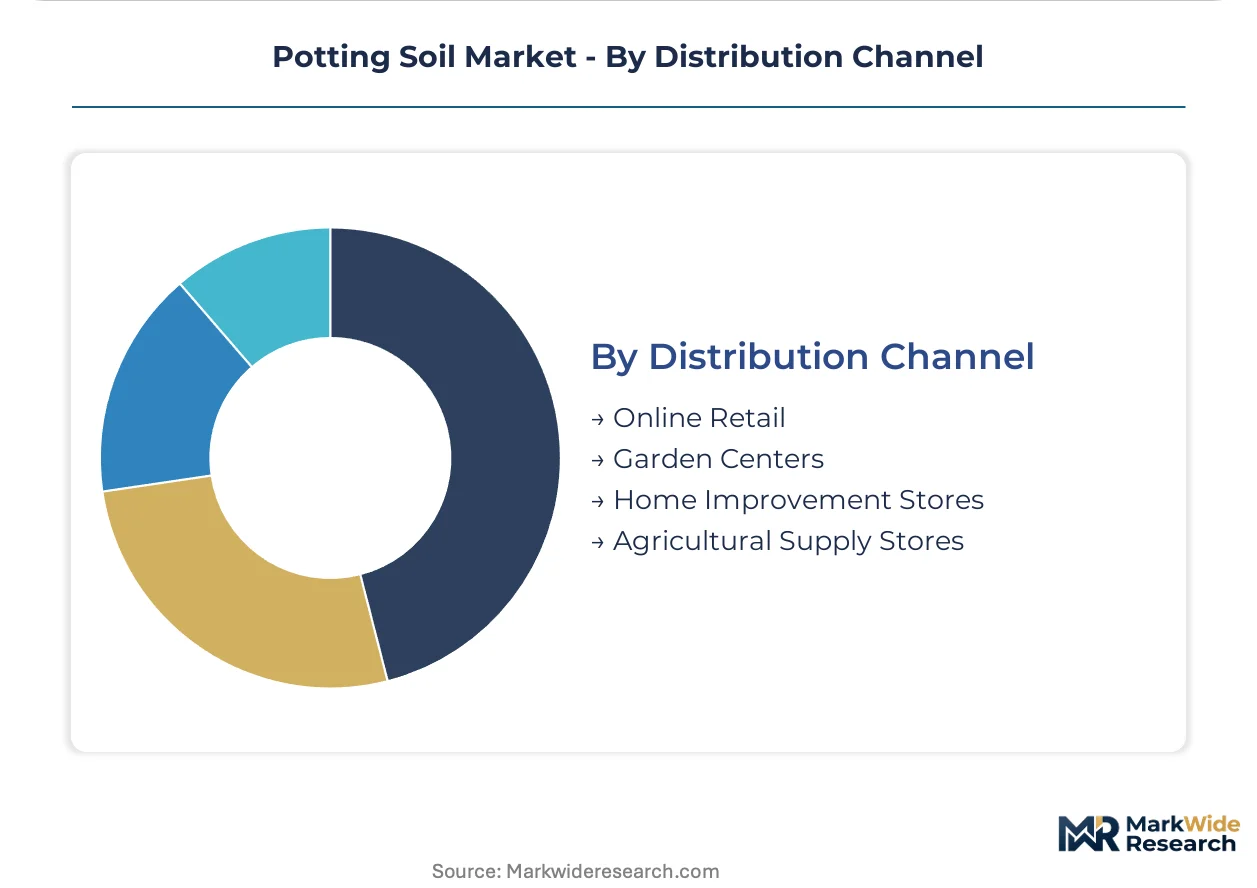
Channel selection determines customer access costs and brand positioning latitude, with digital platforms disintermediating traditional wholesale relationships.
- Garden Centers:Specialty retail with trained staff and premium product assortment. Independent centers in Bavaria and Baden-Württemberg sustain regional substrate brands through consultative selling.
- Home Improvement Stores:Mass retail with high-visibility placement and promotional velocity. Category management agreements with major chains standardize shelf space allocation.
- Online Retail:Direct-to-consumer and B2B platforms enabling subscription replenishment and mid-scale commercial procurement. Dutch greenhouse cooperatives are piloting collective digital purchasing.
- Agricultural Supply Stores:Rural-focused distribution serving conventional farming and large-scale nursery operations with commodity-grade substrates.
Garden Centers defend premium positioning. Online Retail is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting substrate manufacturing capacity toward jurisdictions with permissive peat extraction regimes, while EU Green Deal compliance costs accelerate facility relocation from Northern Europe to Baltic and North American production zones.
United States
Urban balcony gardening in New York, Chicago, and Los Angeles sustains retail bagged substrate volumes through home improvement channels. EPA wetland protections in Minnesota and Florida constrain domestic peat harvesting permits, forcing blenders toward Canadian import dependence. The Pacific Northwest hosts emerging composted bark processing clusters serving West Coast greenhouse operators.
Germany
Professional horticulture clusters in Lower Saxony and North Rhine-Westphalia drive premium substrate consumption for vegetable propagation. EU Green Deal peatland restoration mandates are forcing immediate reformulation of product lines around renewable fiber alternatives. Bavarian garden center chains sustain regional substrate brands through consultative selling arrangements.
Netherlands
Greenhouse cooperatives in Flanders and the Randstad are piloting collective digital purchasing platforms for substrate replenishment. REACH framework chemical disclosure requirements standardize additive transparency across formulations. Westland tomato propagators contract annual substrate volumes with embedded quality assurance protocols.
Canada
Quebec and New Brunswick peat moss reserves sustain bulk pricing leverage for North American commercial grower accounts. Provincial wetland management frameworks govern extraction permits with stricter buffers than US counterparts. Prairie provinces host expanding composting infrastructure for bark and green waste processing.
Belgium
Rhineland-Palatinate ornamental specialists are consolidating purchasing through cooperative buying arrangements to secure custom-blended specifications. ECHA's proposed microplastic limitations accelerate natural surfactant research programs. Flanders greenhouse vegetable producers are reformulating irrigation protocols to compensate for reduced water retention in compliant substrates.
Potting Soil Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue renewable fiber specialization and digital direct-to-grower channels. The market structure concentrates around vertically integrated suppliers with captive bog reserves and controlled distribution networks. Three archetypes dominate: legacy peat operators with extraction assets, regional blenders serving professional horticulture clusters, and alternative-fiber specialists targeting hydroponic operators. Competitive moves center on backward integration into raw material reserves and portfolio diversification toward certified organic lines.
Among North American volume leaders, Scotts Miracle-Gro anchors mass retail positioning through home improvement chain relationships, while Sun Gro Horticulture exemplifies the captive-reserve archetype with Canadian peat moss access. Klasmann-Deilmann represents the professional-grade European tier, serving greenhouse operators with exacting substrate specifications. FoxFarm Soil & Fertilizer occupies the specialty organic positioning vector for premium consumer segments.
| Leading Market Players |
|---|
| ASB Greenworld |
| FoxFarm Soil & Fertilizer |
| Scotts Miracle-Gro |
| Lambert |
| Compo |
| Sun Gro Horticulture |
| Espoma |
| Premier Tech |
| Klasmann-Deilmann |
| Others |
Supply Flow & Price Mechanics
EU Green Deal peatland restoration mandates are compressing development timelines and rewiring procurement economics, simultaneously elevating alternative fiber processing costs and consolidating supply around vertically integrated operators with captive reserves.
Pricing Analysis
Distributor margin compression in professional horticulture channels is intensifying as greenhouse cooperatives aggregate demand. Pricing stratifies across premium organic-certified lines, standard peat-based formulations, and economy-grade bulk substrates, with certification tier and volume scale as primary differentiation drivers. Cost compression in peat-based tiers stems from Canadian import dependence forced by EPA wetland permit constraints. Retail consumers exhibit highest price sensitivity, while commercial growers prioritize batch consistency over unit economics.
Supply Chain Analysis
EU Carbon Border Adjustment mechanisms are reshaping local-content sourcing requirements, advantaging European manufacturers with established alternative fiber networks. Raw material supply concentrates in Canada for sphagnum peat, Sri Lanka and India for coco coir processing, and Germany for composted bark refinement. Formulation chemistry draws from perlite deposits in Greece and vermiculite from South Africa. Single-origin vulnerability in Sri Lankan coir processing creates structural risk. Distribution runs through pneumatic bulk trailer networks for greenhouse operators and palletized bag configurations for retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The potting soil market functions as a stable compounder anchored by irreversible urban gardening adoption and professional horticulture's structural demand for precision-formulated substrates.
For Market Incumbents: Deploy backward integration into captive peat reserves and alternative fiber processing assets to secure raw material access against EU Green Deal restriction thresholds. Acquire composting infrastructure in Lower Saxony and North Rhine-Westphalia to defend position against regional blenders. Invest in OMRI certification pipelines to capture premium organic positioning before compliance windows tighten. For New Entrants and Emerging Players: The mid-tier price gap between premium organic-certified substrates and economy bulk lines offers white-space entry for renewable fiber specialists. Target hydroponic vegetable propagators in the Netherlands seeking coco coir consistency guarantees. Pursue direct-to-grower digital channels to disintermediate cooperative buying arrangements and capture subscription replenment revenue. For Investors and Strategic Acquirers: Roll-up economics work for regional blenders with professional horticulture cluster access because substrate science talent scarcity constrains formulation capabilities at alternative-fiber entrants. Acquire mid-scale operators with established greenhouse relationships in Belgium and Germany. Monitor ECHA microplastic restriction implementation timelines as inflection indicator for natural surfactant R&D investment signals.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Reserves | Secures peat moss access against EPA wetland permit constraints in Minnesota and Florida. |
| Alternative Fiber Processing Capacity | Builds coco coir and composted bark infrastructure to meet EU Green Deal compliance deadlines. |
| Professional Grower Custom Blending Service | Captures margin-rich revenue from Belgian tomato propagators requiring exacting porosity specifications. |
| Direct-to-Grower Digital Platform Launch | Disintermediates cooperative buying arrangements among Rhineland-Palatinate nursery associations. |
| Organic Certification Pipeline Investment | Accelerates OMRI and EU input approval timelines for peat-free premium positioning. |
Methodological Framework
Direct dialogue with substrate formulation chemists, greenhouse operations managers, garden center category buyers, and peatland extraction permit officers grounded the qualitative foundation. Secondary validation drew from EU ECHA REACH filings, EPA wetland protection permit databases, Canadian provincial extraction records, and customs trade data for coco coir imports. Bottom-up volume estimates from professional horticulture cluster consumption patterns were triangulated against top-down substrate production capacity assessments.
Segmented outputs across product type, end user, packaging format, and distribution channel were generated through the projection horizon. CAGRs were derived from regression analysis against urban gardening participation rates, greenhouse vegetable production acreage, and regulatory compliance cost trajectories. Forecast inputs incorporated EU Green Deal implementation timelines, REACH chemical restriction expansion schedules, and peatland restoration mandate enforcement intensity.
Caveats apply where ECHA microplastic limitation finalization or EPA wetland buffer expansion could materially shift the outlook for conventional formulation economics. Peat harvest permit litigation outcomes and alternative fiber supply disruptions from South Asian processing clusters represent additional revision triggers. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Bee Pollen Market
Agriculture and Agri Products
Europe Poultry Feed Market
Agriculture and Agri Products
Post-Harvest Treatment Market
Agriculture and Agri Products
Tunisia Agriculture Market
Agriculture and Agri Products
LAMEA Rapeseed Oil Market
Agriculture and Agri Products
North America Swine Feed Premix Market
Agriculture and Agri Products
Asia Pacific Poultry Feed Market
Agriculture and Agri Products
Alfalfa Market
Agriculture and Agri Products
High Fiber Feed Market
Agriculture and Agri Products
South Africa Alfalfa Hay Market
Agriculture and Agri Products
Rice Straw Market
Agriculture and Agri Products
Ethiopia Agriculture Sector Market
Agriculture and Agri Products
Poultry Fat Market
Agriculture and Agri Products
Middle East Animal Protein Market
Agriculture and Agri Products
Canada Ornamental Horticulture Market
Agriculture and Agri Products
Italy Animal Protein Market