
 North America Alfalfa Hay Market | 2026-2036
North America Alfalfa Hay Market Size, Share, and Industry Trends Forecast 2026-2036
North America Alfalfa Hay Market Analytics
Modular bale sizing and customized pellet-to-cube bundling is restructuring how dairy nutritionists and export buyers configure feed rations. Anderson Hay and Grain Company leverages its Pacific Northwest production base to anchor long-term supply contracts with Asian export channels. Standlee Premium Western Forage differentiates through vertical control from Idaho fields to retail bagging, sustaining premium positioning in the horse feed segment.
North America alfalfa hay denotes the dried aerial biomass of Medicago sativa cultivated for animal forage, typically harvested at early bloom with crude protein content ranging from 16% to 22% on a dry matter basis and baled at moisture levels below 18% to prevent spontaneous combustion and mold degradation. Its primary commercial purpose centers on delivering metabolizable energy and rumen-degradable protein to high-producing dairy cattle and performance horses. Small bales command persistent loyalty in the horse owner segment where manual handling and portion control outweigh per-ton economics, while cubes and pellets capture margin pools in automated dairy feeding systems and containerized export logistics where density and uniformity reduce freight costs. Large bales dominate volume throughput in domestic dairy supply chains, though their bulk-to-value ratio limits intermodal transport reach compared to densified formats.
The USDA Agricultural Marketing Service administers hay grading standards that condition price discovery and contract terms across U.S. terminal markets, while the EPA enforces Clean Water Act provisions affecting nutrient runoff from concentrated hay production zones in the Imperial and San Joaquin Valleys. California's State Water Resources Control Board imposes agricultural water-use restrictions that directly constrain alfalfa acreage in favor of higher-value crops, reshaping regional supply availability. Canadian Food Inspection Agency phytosanitary protocols govern cross-border hay movement and determine eligibility for export to Japan and South Korea. Stakeholders must monitor how cumulative regulatory load on water access and foreign market entry protocols reshapes optimal production geography and capital deployment timing.
Market Dynamics
Water scarcity in California's Central Valley and Imperial Valley is forcing acreage abandonment and migration of alfalfa production toward the Pacific Northwest and Canadian Prairie provinces, fundamentally restructuring regional supply geography.
Growth Catalysts
- USDA Grading Standards:Standardized quality metrics reduce transaction friction in terminal markets and enable long-distance contract formation between dairy nutritionists and hay merchants.
- Dairy herd consolidation:Large-scale operations in Wisconsin and Idaho demand consistent, high-volume forage supply, pulling investment into mechanized baling and densification infrastructure.
- Phytosanitary alignment:Canadian Food Inspection Agency protocols harmonizing with Japanese and South Korean import requirements unlock premium export channels for Pacific Northwest producers.
Market Restraints
- Input cost volatility:Diesel, fertilizer, and irrigation energy costs swing with crude oil and natural gas markets, compressing margins for rain-fed operations in Montana and the Dakotas.
- Supply concentration risk:California and Arizona together account for disproportionate premium-grade output, exposing buyers to simultaneous drought and regulatory curtailment events.
- Substitution pressure:Corn silage and synthetic amino acid supplements displace alfalfa in dairy rations when relative protein economics invert.
Strategic Opportunities
- Underpenetrated Canadian Prairie:Saskatchewan and Manitoba hay acres remain below agronomic potential, with expanding rail links to Vancouver port offering Asian export access.
- Pellet-to-cube bundling innovation:Customized feed configurations for automated dairy systems capture margin pools unavailable in commodity bale markets.
- Conservation Reserve Program incentives:USDA cost-share mechanisms for sustainable forage establishment reduce establishment risk for growers transitioning marginal cropland.
Industry Challenges
- Certification timeline compression:Organic and non-GMO verification processes lag planting decisions by 18-36 months, stranding capital in transitioning acreage.
- Specialized equipment scarcity:Large-square balers and tub grinders require six-figure capital commitments with thin secondary markets for resale.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Alfalfa Hay Market |
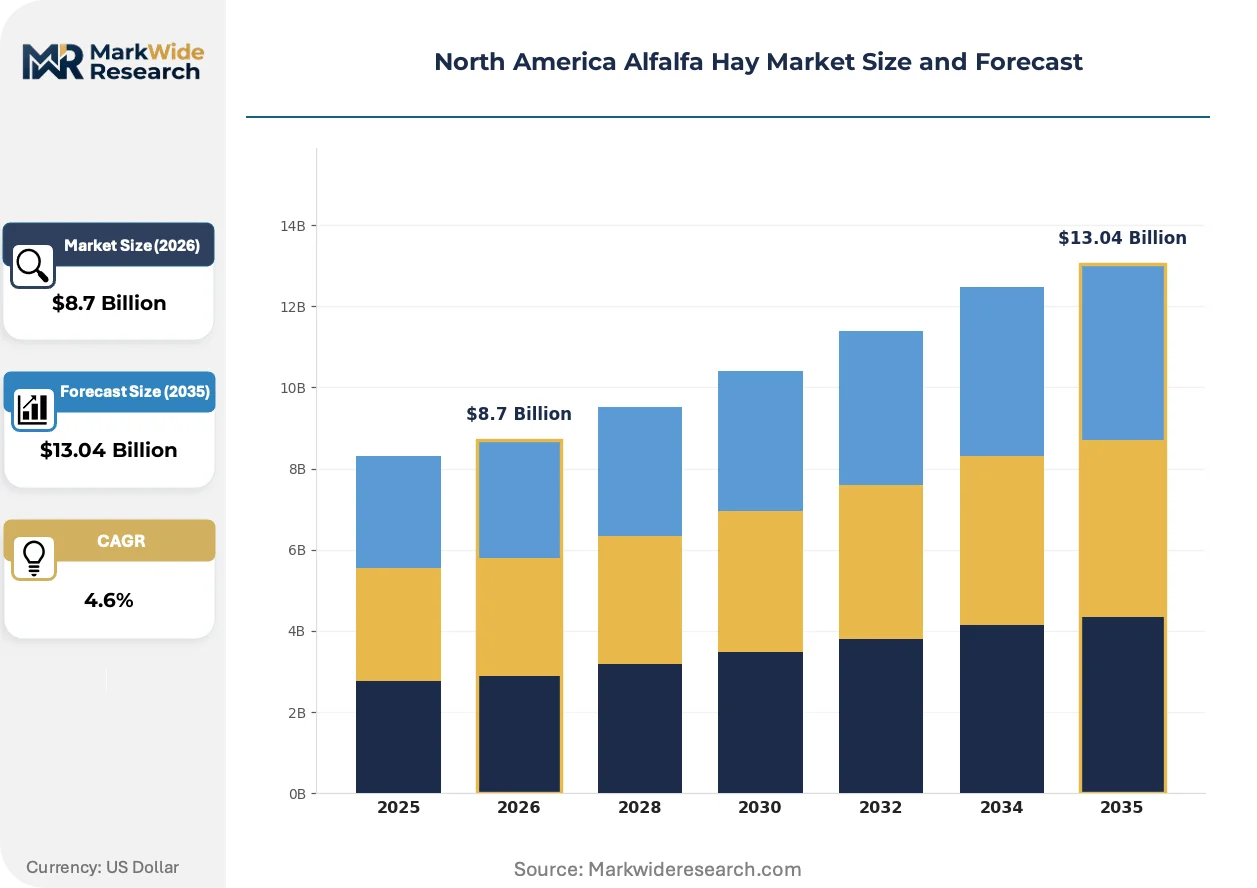
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Small Bales, Large Bales, Cubes, Pellets End User: Dairy Farms, Beef Cattle, Horses, Export Markets Cutting Method: Conventional, Organic, No-Till, Rotary Packaging Type: Plastic Wrap, Netting, Bulk, Bags |
| Companies Covered | Anderson Hay and Grain Company, Al Dahra ACX, Green Prairie International, Border Valley Trading, Standlee Premium Western Forage, Bailey Farms, Hay USA, Cubeit Hay Company, Knight Ag Sourcing, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Alfalfa Hay Market Evolving Landscape
Automation in harvest timing and densification is compressing the gap between field and feed bunk, while regulatory pressure on water use accelerates geographic rotation of production.
Precision moisture sensing and in-field NIR spectroscopy is rewriting how cut timing and baling decisions get made. Dairy nutritionists in the Upper Midwest now specify exact crude protein and relative feed value thresholds in procurement contracts. This technology is compressing price variance between advertised grade and delivered quality, penalizing growers without sensor infrastructure.
California's State Water Resources Control Board agricultural water-use restrictions are forcing permanent fallowing of alfalfa acreage in favor of higher-value permanent crops. Growers in the San Joaquin Valley face simultaneous curtailment of surface water allocations and groundwater pumping limits under the Sustainable Groundwater Management Act. The displacement is concentrating premium hay production in Idaho's Snake River Plain and Washington's Columbia Basin, where irrigation remains relatively secure.
Consolidated dairy operations are displacing spot-market hay purchases with forward-contracted supply agreements spanning multiple growing seasons. Large herds in Texas and New Mexico now secure 80-90 percent of annual forage needs through direct grower relationships rather than auction or dealer channels. This shift is most visible in the Southwest, where feedlot and dairy density has outstripped local hay production capacity, forcing logistics innovation in long-haul trucking and unit-train configurations.
North America Alfalfa Hay Market Segmentation
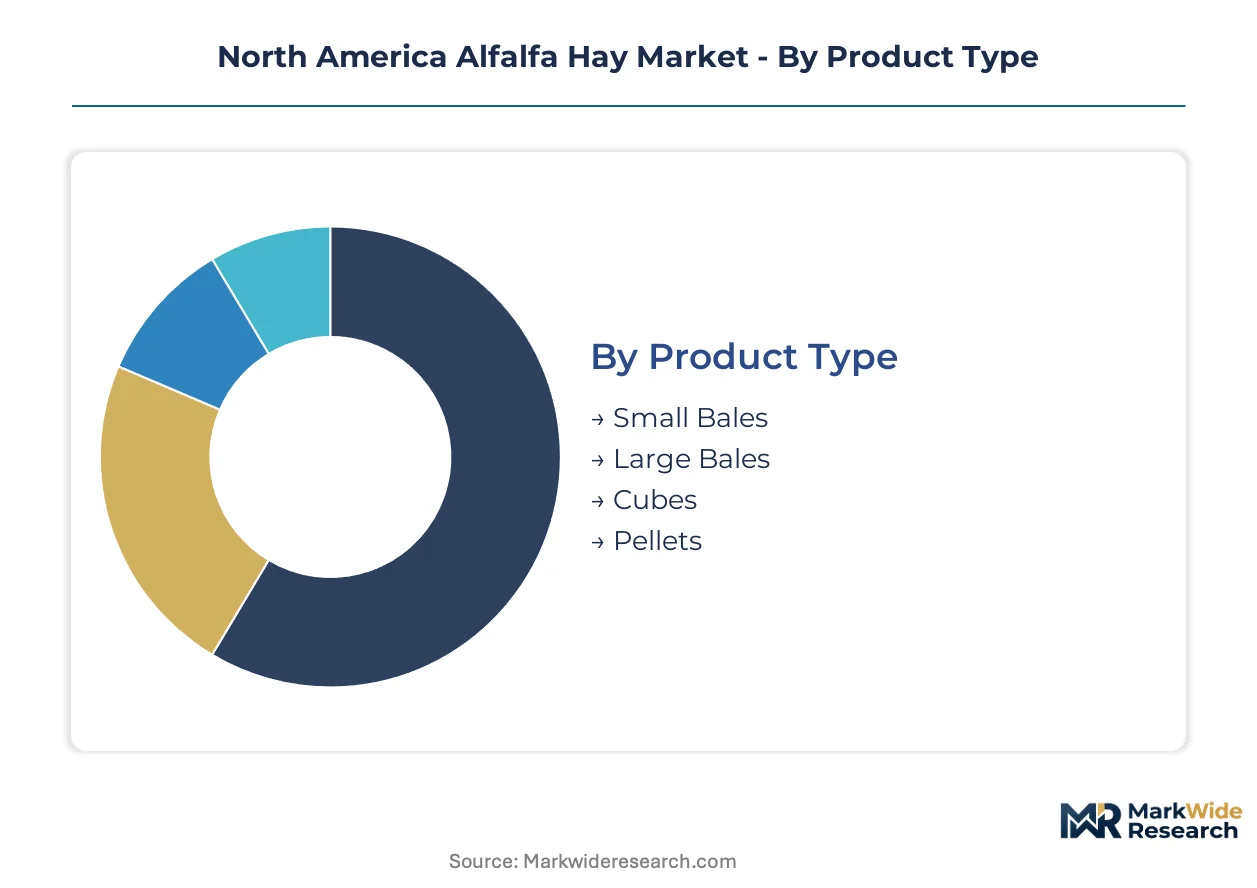
Segmentation in the North America alfalfa hay market reflects divergent buyer economics across handling methods, feeding systems, and export logistics. Dairy nutritionists, horse owners, and Asian importers each impose distinct specifications that reshape product configuration and regional production priorities.
Product Type:
Buyers in this category separate by handling infrastructure and feed system automation rather than intrinsic forage quality.
- Small Bales:Rectangular bales of 40-100 pounds suit manual handling and portion-controlled feeding. Horse owners in Texas and Florida prefer these for stable management despite 30-40% freight cost premiums per ton. Demand persists where labor costs stay below mechanized system investments.
- Large Bales:Round and large-square formats of 750-1,500 pounds dominate dairy farm procurement in Wisconsin and Idaho. Automated handling equipment and bunker storage systems in these states reward density and throughput over flexibility.
- Cubes:Compressed 1-2 inch cubes reduce dust and waste in automated dairy feeders. Idaho dairies with TMR mixing systems specify cube dimensions to prevent bridging in distribution augers.
- Pellets:Densified 1/4-inch pellets maximize containerized export payload to Japan and South Korea. Vancouver port logistics favor pellet uniformity for weight optimization in 40-foot containers.
Large bales lead volumes today; pellets are gaining share fastest through Asian export channel expansion.
End User:
Feeding system sophistication and protein substitution economics determine how each buyer segment values alfalfa relative to alternatives.
- Dairy Farms:High-producing Holstein herds in California's Central Valley and Wisconsin's Fox River Valley demand 18-22% crude protein with consistent relative feed value above 150. Nutritionists specify RFV minimums in multi-year supply contracts.
- Beef Cattle:Backgrounding operations in Nebraska and Kansas use lower-grade hay for roughage fill when corn silage prices spike. Seasonal demand fluctuates with feedlot placement cycles.
- Horses:Performance and pleasure horse owners prioritize low-dust, leaf-retentive hay for respiratory health. Kentucky and Florida equine facilities pay 25-35% premiums for certified weed-free certification.
- Export Markets:Japanese dairy cooperatives and South Korean beef feedlots import premium-grade cubes and pellets through Vancouver and Long Beach ports. CFIA phytosanitary protocols condition eligibility.
Dairy farms command the largest volume share; export markets are climbing the fastest as Asian protein demand intensifies.
Cutting Method:
Certification premiums and establishment cost recovery timelines differentiate buyer willingness to pay across production systems.
- Conventional:Standard tillage and synthetic input protocols deliver predictable yields of 6-8 tons per acre under irrigation. Washington's Columbia Basin growers favor this method for cost certainty in forward contracts.
- Organic:Three-year transition without prohibited substances captures 40-60% price premiums in horse and specialty dairy channels. Saskatchewan growers face 18-36 month certification lags that strand capital in transitioning acreage.
- No-Till:Direct seeding into standing residue reduces soil moisture loss and fuel costs in Montana dryland operations. Equipment availability limits adoption in the Northern Plains.
- Rotary:Specialized swathers with conditioning rolls accelerate dry-down in humid Ontario and Quebec summers. Moisture management determines baling window success.
Conventional cutting leads volumes today; organic is expanding most quickly through premium channel development.
Packaging Type:
Storage duration and handling automation requirements shape buyer preferences for protective and transport formats.
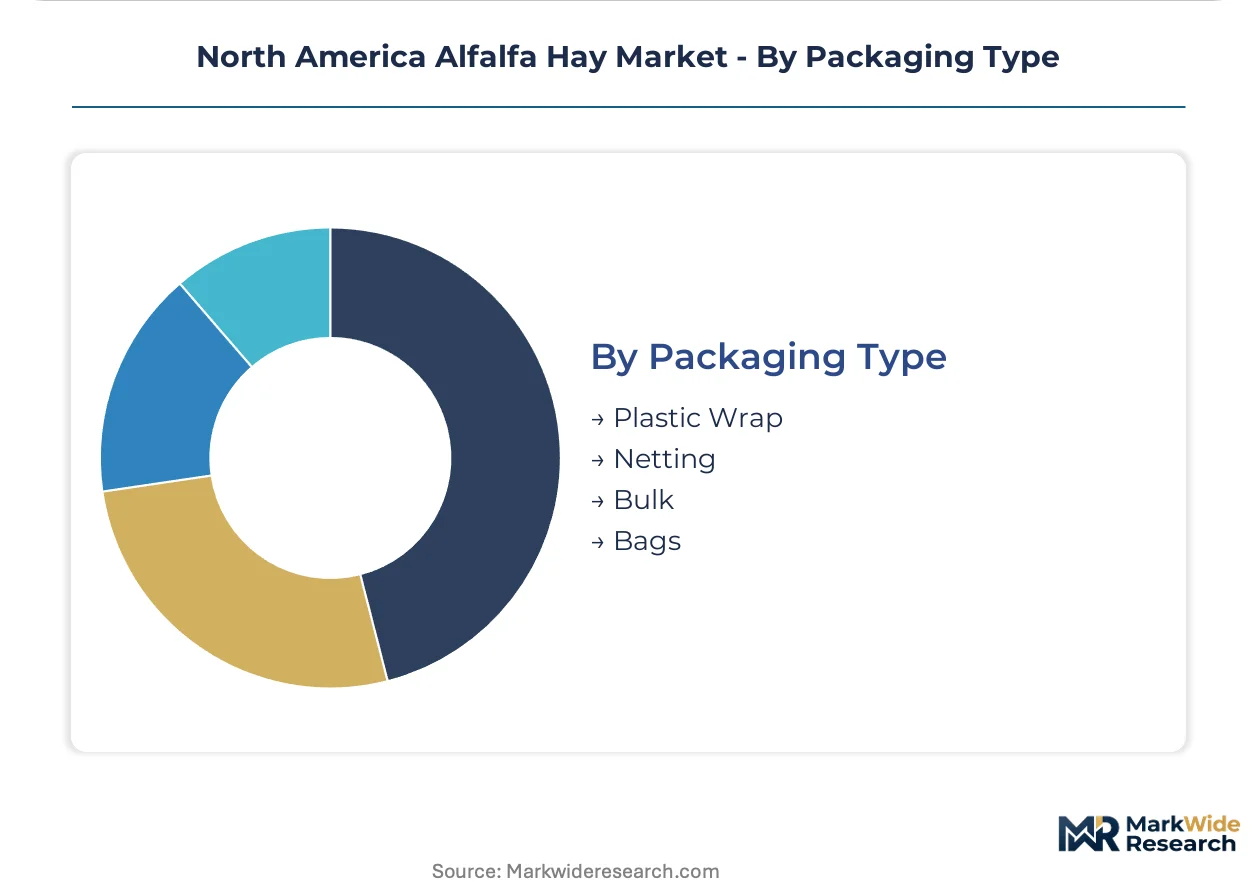
- Plastic Wrap:UV-stabilized polyethylene film enables outdoor storage of high-moisture baleage in Pacific Northwest rainfall zones. Film costs fluctuate with petroleum feedstock prices.
- Netting:Polypropylene mesh replaces twine for faster baling and cleaner unwrapping in large-scale Idaho dairy operations. Net-wrapped rounds shed precipitation better than twine-tied equivalents.
- Bulk:Loose hay in bunker silos serves captive dairy supply chains with minimal handling stages. California's Central Valley vertical integration favors this format.
- Bags:Retail-scale 40-50 pound poly bags dominate horse owner distribution through farm supply stores. Standlee's Idaho-to-retail vertical control exemplifies this channel.
Plastic wrap leads volumes today; bags are gaining share fastest through equestrian retail channel expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Alfalfa hay cultivation in North America traces its commercial scale to early twentieth-century irrigation development in the western United States, where railroad expansion enabled hay movement from interior valleys to eastern dairy markets and Pacific ports.
United States
California's Central Valley and Imperial Valley dairies consume premium-grade hay for high-producing Holstein herds, while Wisconsin's Fox River Valley operations source consistent volumes for cheese production pipelines. The USDA Agricultural Marketing Service administers hay grading standards that condition price discovery across terminal markets. Idaho's Snake River Plain has emerged as the fastest-expanding production zone as water curtailments displace California acreage.
Canada
Saskatchewan and Manitoba prairie provinces hold substantial unexploited hay acreage below agronomic potential, with expanding rail links to Vancouver port infrastructure. The Canadian Food Inspection Agency enforces phytosanitary protocols governing cross-border movement and Asian export eligibility. Alberta's Peace River region anchors established hay production serving Pacific Rim dairy cooperatives.
Mexico
Chihuahua and Sonora northern states concentrate irrigated alfalfa production for domestic dairy expansion and cross-border supply to Texas feedlots. Mexico's national agricultural water authority regulates groundwater extraction from the Alto Rio Bravo aquifer system. The Mexicali Valley maintains specialized acreage for horse feed export to southwestern United States markets.
Pacific Northwest
Washington's Columbia Basin and Oregon's Umatilla Basin combine secure Columbia River irrigation with proximity to Vancouver and Long Beach export terminals. State-level water rights adjudication in Washington constrains new acreage expansion. The Moses Lake industrial cluster hosts densification facilities processing regional hay into cube and pellet formats for containerized Asian shipment.
North America Alfalfa Hay Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification grade and export channel access, with quality-verified supply commanding persistent price premiums in dairy nutritionist procurement contracts. The vendor base arranges into three tiers: integrated producers controlling field-to-bale operations, regional aggregators sourcing from grower networks, and specialized densification processors serving export logistics. Two dominant competitive moves define current positioning: backward integration into captive hay production to secure volume commitments, and geographic diversification of sourcing bases to mitigate drought concentration risk.
Among integrated Western producers, Anderson Hay and Grain Company and Standlee Premium Western Forage exemplify divergent strategic archetypes. Anderson leverages Pacific Northwest production positioning to anchor long-term supply agreements with Asian export channels. Standlee occupies a position emphasizing vertical control from Idaho field operations through retail bagging infrastructure, sustaining premium positioning in specialized horse feed segments. Border Valley Trading represents the regional aggregator archetype, sourcing across grower networks to assemble export-grade volumes without direct production ownership.
| Leading Market Players |
|---|
| Anderson Hay and Grain Company |
| Al Dahra ACX |
| Green Prairie International |
| Border Valley Trading |
| Standlee Premium Western Forage |
| Bailey Farms |
| Hay USA |
| Cubeit Hay Company |
| Knight Ag Sourcing |
| Others |
Value Network & Pricing Analysis
Dairy nutritionist procurement contracts specifying exact crude protein and relative feed value thresholds force growers to invest in precision moisture sensing and in-field NIR spectroscopy, compressing margins for operations without sensor infrastructure and widening price spreads between verified and unverified supply.
Pricing Analysis
Contract-based long-term offtake agreements dominate premium-grade transactions, with pricing stratifies across certified premium, standard utility, and economy roughage tiers based on USDA grade and phytosanitary certification status. Price differentiation rests on relative feed value thresholds and CFIA export eligibility, with organic and non-GMO verification commanding substantial premiums in horse and specialty dairy channels. Cost compression in standard utility hay is intensifying because diesel and fertilizer input volatility erodes rain-fed operation margins in Montana and the Dakotas. Beef cattle backgrounding operations exhibit highest price sensitivity, while Japanese dairy cooperatives show lowest sensitivity due to protein security priorities.
Supply Chain Analysis
Regional distribution centers in Idaho's Snake River Plain and Washington's Columbia Basin anchor hub-and-spoke patterns feeding Vancouver and Long Beach export terminals. Geographic supply concentrates in the United States, Canada, and Mexico, with production gravity shifting northward as California water curtailments displace acreage. Raw material dependencies include irrigation water access, diesel fuel for harvest mechanization, and synthetic fertilizer inputs. Single-source vulnerability runs through California and Arizona's disproportionate premium-grade output exposure to simultaneous drought and regulatory curtailment events. Distribution runs through direct grower relationships displacing auction channels in consolidated dairy procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in North American alfalfa hay rests on densification technology adoption reducing per-ton freight costs and organic certification premiums widening in undersupplied premium channels.
For Market Incumbents: Deploy backward integration into captive hay production to secure multi-year volume commitments from consolidating dairy operations. Invest in Idaho and Washington densification infrastructure to capture Asian export channel growth as California acreage contracts. Water curtailment risk in the Imperial and San Joaquin Valves threatens legacy supply positions. For New Entrants and Emerging Players: The price-point gap between certified organic and conventional utility hay creates entry space for Saskatchewan and Manitoba operations with rail access to Vancouver port. Target underpenetrated Canadian Prairie production with no-till establishment protocols and CFIA phytosanitary alignment for Japanese market eligibility. Pursue direct supply agreements with expanding Upper Midwest dairy herds as a beachhead. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-scale Western producers possessing established water rights and densification capabilities. Long-term viability favors operations with geographic diversification across multiple irrigation-secure basins. Watch for Sustainable Groundwater Management Act implementation pace as inflection indicator for California production displacement velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Production | Secures volume commitments from consolidating dairy operations reducing spot-market exposure. |
| Geographic Diversification of Sourcing Bases | Mitigates drought concentration risk across Imperial Valley and Central Valley supply zones. |
| Pellet-to-Cube Bundling Innovation | Captures margin pools in automated dairy feeding systems and containerized export logistics. |
| Organic Certification Investment | Unlocks 40-60% price premiums in horse and specialty dairy channels with three-year transition. |
| CFIA Phytosanitary Protocol Alignment | Determines eligibility for premium Japanese and South Korean export channels through Vancouver. |
Research Methodology
Direct dialogue with dairy nutritionists, hay merchant procurement managers, Idaho and Washington growers, and CFIA regulatory affairs specialists grounded qualitative findings in operational reality. Secondary validation drew from USDA Agricultural Marketing Service grading data, Canadian Food Inspection Agency phytosanitary protocols, state water board curtailment orders, and customs export records. Bottom-up acreage and yield modeling triangulated against top-down dairy herd forage demand estimates across the analysis window.
Segment-level projections across product type, end user, cutting method, and packaging format generated volume and value trajectories over the projection horizon. CAGRs derived from irrigation water availability constraints, dairy herd consolidation velocity, and Asian import demand elasticity. Forecast inputs incorporated Sustainable Groundwater Management Act implementation timelines and Pacific Northwest rail capacity expansion.
Caveats apply where drought severity, regulatory curtailment acceleration, or protein substitution economics could materially shift the outlook. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Marine Algae Market
Agriculture and Agri Products
Africa Orange Market
Agriculture and Agri Products
France Animal Protein Market
Agriculture and Agri Products
Egypt Compound Feed Market
Agriculture and Agri Products
Global Ruminant Feed Market
Agriculture and Agri Products
Ethiopia Agriculture Sector Market
Agriculture and Agri Products
Asia-Pacific Poultry Meat Market
Agriculture and Agri Products
Africa Animal Protein Market
Agriculture and Agri Products
Global Animal Feed Dietary Fibers Market
Agriculture and Agri Products
E-Commerce of Agricultural Products Market
Agriculture and Agri Products
Asia-Pacific Chaga Mushroom Market
Agriculture and Agri Products
Colombia Hemp Market
Agriculture and Agri Products
United States Alfalfa Market
Agriculture and Agri Products
India Compound Feed Market
Agriculture and Agri Products
African Swine Feed Market
Agriculture and Agri Products
Tunisia Agriculture Market