
 Global Ruminant Feed Market | 2026-2036
Global Ruminant Feed Market Size, Share, and Industry Trends Forecast 2026-2036
Global Ruminant Feed Market Foresight
Precision fermentation and enzyme supplementation technologies are rewriting how cattle nutritionists optimize rumen degradable protein and bypass amino acid ratios. Cargill Inc. leverages its captive oilseed processing network to control lysine and methionine input costs across North American dairy operations. DSM-Firmenich anchors its position through R&D intensity in vitamin premixes and mycotoxin binders that sustain herd health under heat stress conditions. De Heus competes in Southeast Asia with localized formulation expertise for smallholder buffalo and cattle systems.
Ruminant feed comprises formulated mixtures of concentrates, forages, silage, and additives designed to meet metabolizable energy and crude protein specifications for cattle, sheep, goats, and buffaloes, typically processed through grinding, pelleting, or total mixed ration blending to optimize dry matter intake and rumen fermentation efficiency. The primary commercial purpose centers on converting roughage and grain inputs into processor-compliant milk, meat, and fiber outputs while managing feed conversion ratios. Concentrates and additives capture disproportionate margin pools due to formulation complexity and veterinary prescription requirements in regulated dairy supply chains. Forages and silage dominate volume throughput but operate at thinner margins tied to regional hay and crop residue availability, with organic and fortified production methods gaining traction among premium dairy processors.
The FDA, EPA, and EU Green Deal collectively shape ruminant feed demand through antibiotic residue limits, methane emissions accounting, and sustainable protein sourcing mandates that restrict fishmeal and soy expansion. BIS and FSSAI in India enforce aflatoxin thresholds and mineral premix labeling that determine market access for imported and domestic formulations. Stakeholders must monitor how carbon border adjustments and deforestation-free supply chain certifications reshape sourcing economics for soy and palm kernel cake.
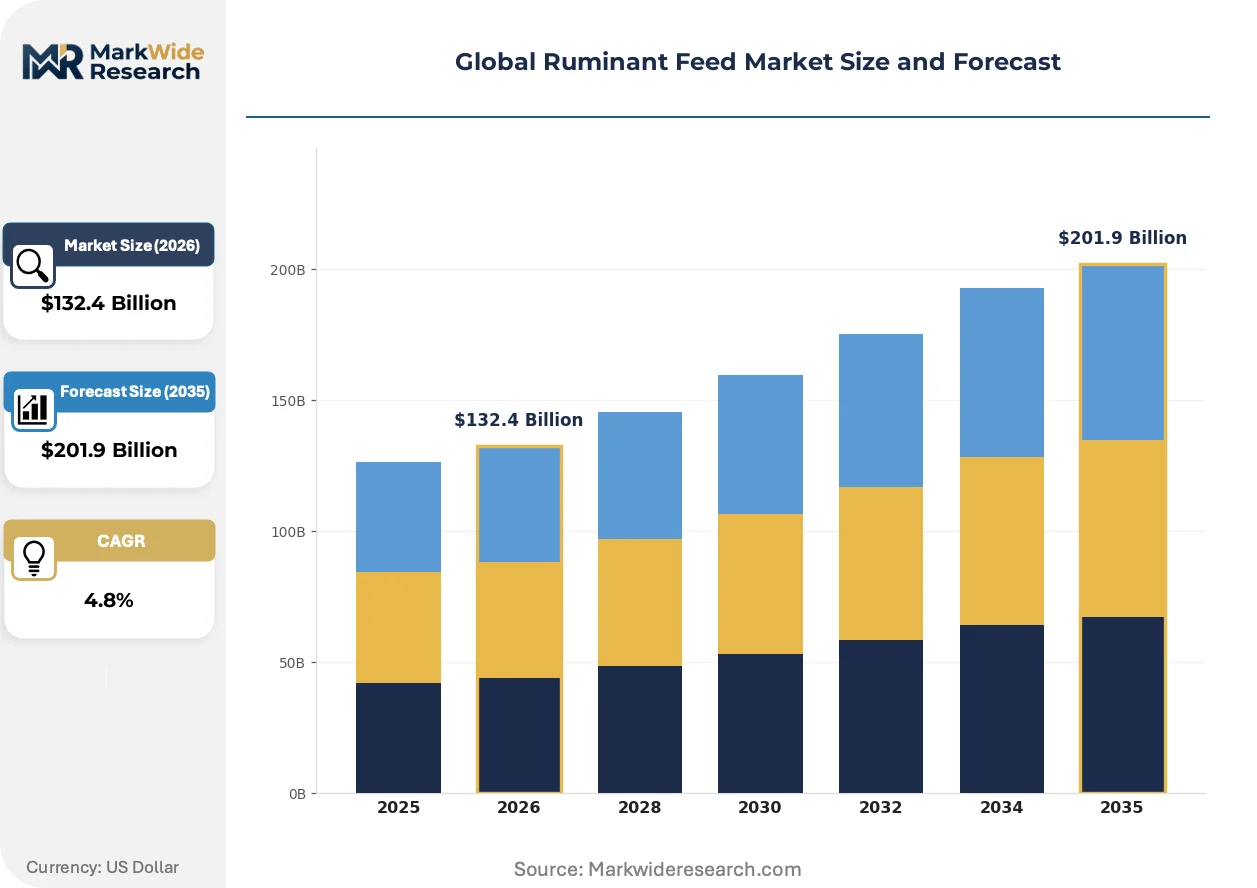
Market Dynamics
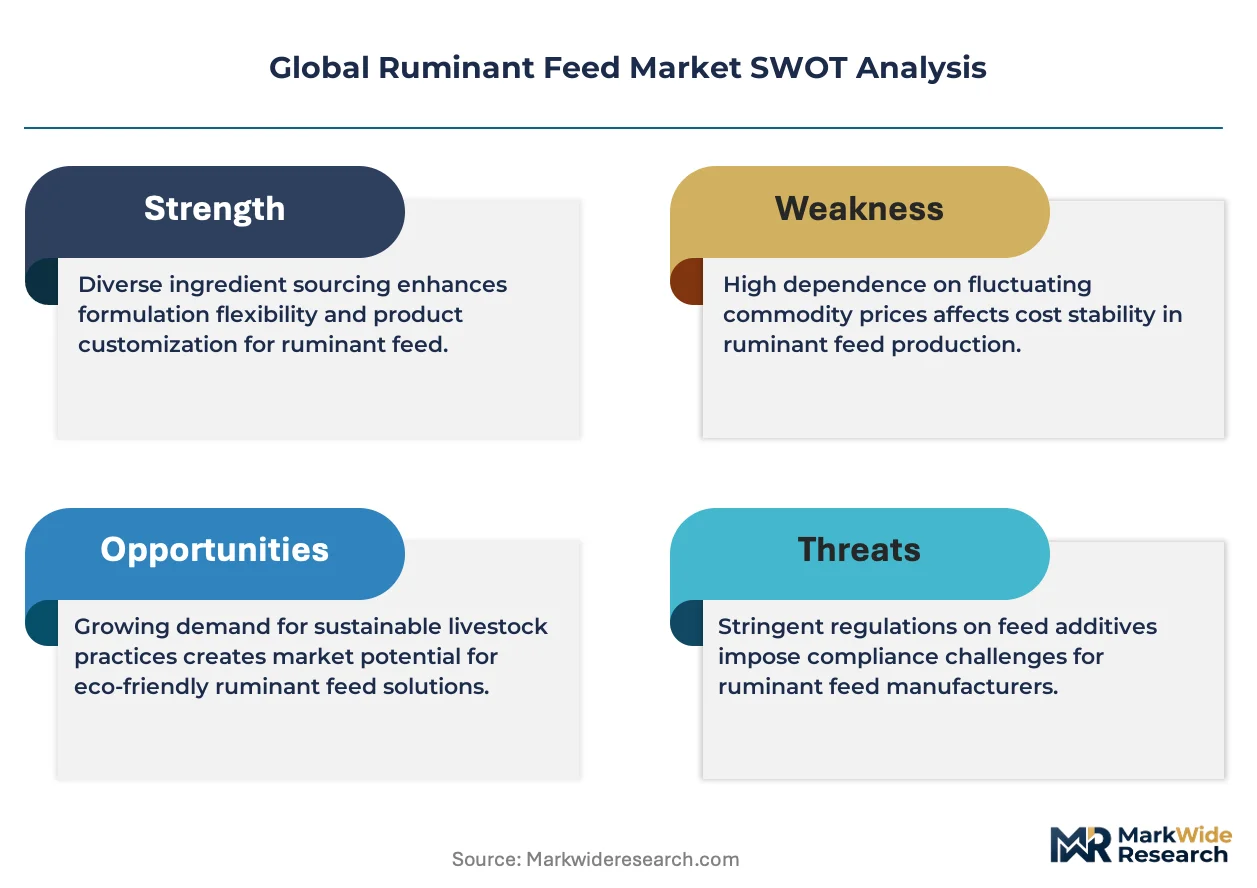
Precision fermentation for amino acid production is compressing formulation costs and redrawing competitive boundaries between integrated oilseed processors and specialty additive suppliers across dairy supply chains.
Growth Catalysts
- EU Green Deal methane accounting:Dairy processors in the Netherlands and Denmark now require feed suppliers to document enteric fermentation emissions, pulling enzyme-supplemented rations into standard procurement specifications.
- Smallholder cooperative consolidation:India's state-level milk federations are aggregating feed demand across millions of producers, creating volume pools that justify compound feed mill investments in Uttar Pradesh and Gujarat.
- Heat-adapted vitamin premixes:DSM-Firmenich and regional competitors are deploying stabilized vitamin formulations that maintain bioavailability above 35°C ambient temperatures, expanding addressable herd days in tropical dairy belts.
Market Restraints
- Soy and palm kernel cake sourcing restrictions:Deforestation-free supply chain certifications from the EU Green Deal are constraining protein meal availability and inflating landed costs for Southeast Asian feed compounders.
- Captive lysine production concentration:Control over fermentation capacity sits with a handful of integrated agribusiness groups, limiting price negotiation leverage for independent dairy nutrition consultants.
- Rumen bypass fat technical limitations:Calcium soap and prilled fat technologies deliver inconsistent metabolizable energy yields across high-producing Holstein genetics, capping milk response predictability.
Strategic Opportunities
- Buffalo feed formulation gaps in Vietnam:De Heus and regional specialists can extend localized expertise from dairy cattle to the country's 2.5 million head water buffalo population, where commercial compound feed penetration remains minimal.
- Carbon credit monetization pathways:Methane-reducing feed additives qualifying under California's Low Carbon Fuel Standard and emerging EU carbon farming certification create new revenue streams for nutrition service providers.
- Direct-to-farm digital distribution:Mobile-enabled feed ordering platforms are bypassing traditional agricultural cooperative hierarchies in Brazil's Minas Gerais dairy triangle, shortening payment cycles and capturing margin.
Industry Challenges
- Rumen microbiome modeling talent scarcity:Commercial nutrition teams lack sufficient computational biologists to operationalize metagenomic data from on-farm NIR sensors into real-time ration adjustments.
- FSSAI aflatoxin compliance timelines:Indian feed mills face 90-120 day certification delays for imported mycotoxin binder premixes, freezing formulation updates during seasonal contamination spikes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Ruminant Feed Market |
| Market Size in 2026 | $132.4 Billion |
| Market Size in 2035 | $201.9 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Feed Type: Concentrates, Forages, Silage, Additives Animal Category: Cattle, Sheep, Goats, Buffaloes Distribution Channel: Direct Sales, Retail Stores, Wholesalers, E-Commerce Platforms Production Method: Conventional, Organic, Non-GMO, Fortified |
| Companies Covered | Cargill Inc., Archer Daniels Midland, Land O Lakes Feed, ForFarmers, De Heus, DSM-Firmenich, Nutreco, Charoen Pokphand Foods, Biomin, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Ruminant Feed Market Shifts & Advancements
Active pharmaceutical ingredient manufacturing methods borrowed from human health biotechnology are crossing into cattle nutrition, collapsing production economics for precision ingredients previously sourced from extraction or chemical synthesis.
Precision fermentation for methionine and lysine production is rendering obsolete the soybean meal price linkage that historically governed amino acid supplementation decisions in North American dairy rations. Large herd nutrition consultants in Wisconsin and Idaho are specifying fermented amino acids at 40-60% inclusion rates versus conventional protein sources. This input cost decoupling is compressing working capital requirements for feed mills while shifting supplier power toward fermentation technology holders.
REACH and the EU Green Deal are mandating full supply chain traceability for soy and palm derivatives entering European compound feed manufacturing. Dutch and German dairy cooperatives now require geolocation verification and mass balance certification from their ingredient suppliers. Feed compounders with backward integration into European oilseed crushing or alternative protein cultivation are capturing preferential procurement status with processor-owned milk brands.
Dairy farmer buying committees are disintermediating traditional agricultural supply cooperatives through direct contracting with regional feed mills and additive distributors. This procurement model change concentrates order volumes among fewer supplier relationships while demanding technical service bundling that cooperative trading desks struggle to match. The shift is most visible in Brazil's southern dairy states and Poland's Masovian production cluster, where farmer associations negotiate multi-year supply agreements with embedded nutrition consulting.
Global Ruminant Feed Market Segmentation
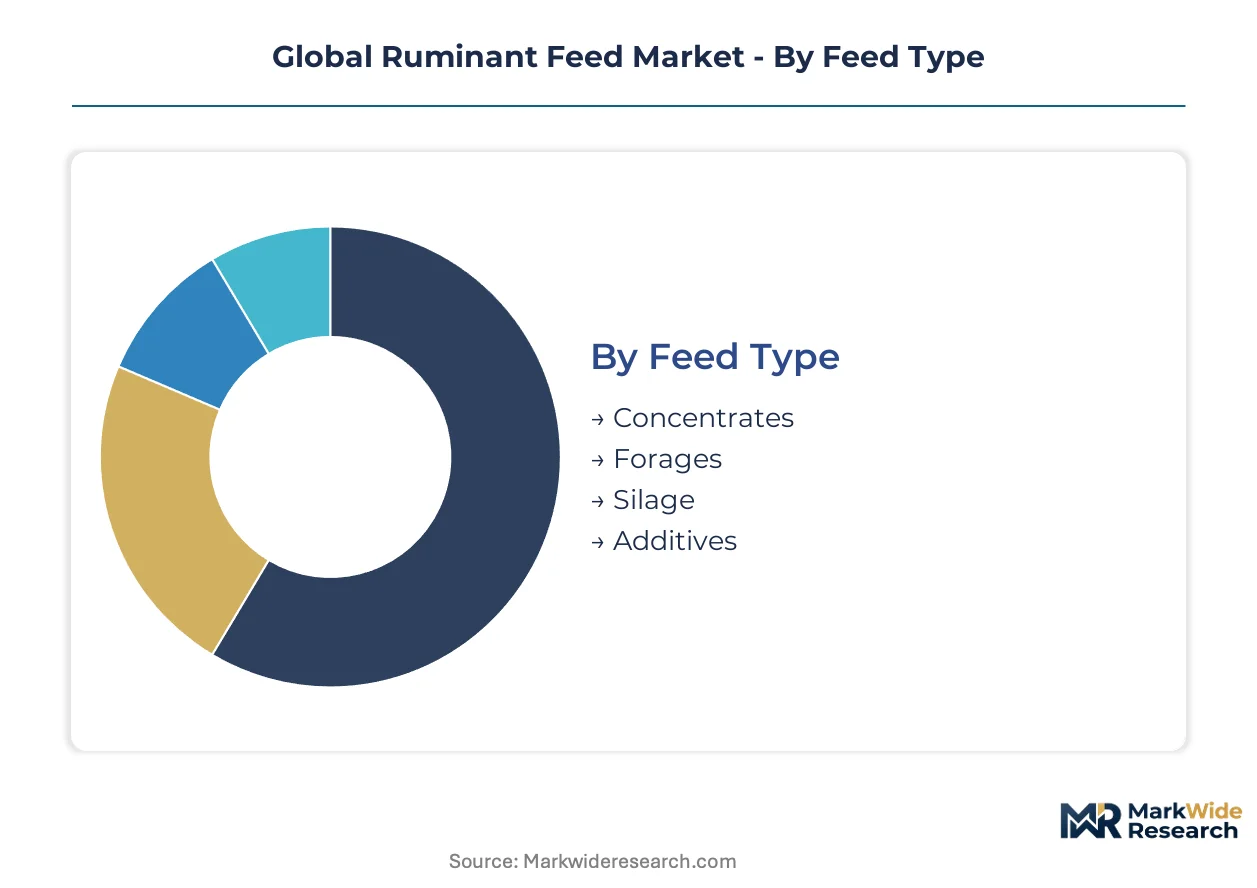
Feed type segmentation determines margin architecture, with concentrates and additives commanding premium pricing through formulation complexity while forages and silage compete on volume throughput. Animal category splits reveal divergent nutritional specifications between high-producing dairy cattle and small ruminant systems. Distribution channel and production method dimensions increasingly shape procurement decisions as traceability mandates and carbon accounting reshape supplier relationships.
Feed Type:
Cost tier stratification separates high-margin specialty inputs from commodity bulk materials, with formulation intensity determining supplier power and working capital requirements.
- Concentrates:Energy-dense blends of grains, oilseed meals, and protein supplements delivering metabolizable energy and rumen-degradable protein for high-producing dairy herds. Demand concentrates in the Netherlands and Denmark where processor-owned cooperatives mandate enzyme-supplemented rations under EU Green Deal methane accounting protocols.
- Additives:Vitamin premixes, mycotoxin binders, rumen modifiers, and bypass amino acids requiring veterinary prescription or nutritionist specification in regulated supply chains. Expansion runs fastest in India's northern dairy belt where state-level milk federations aggregate smallholder demand for fortified compound feeds.
- Forages:Hay, straw, and fresh grasses supplying structural fiber and dry matter bulk, sourced regionally with thin margins tied to seasonal weather patterns and hay auction liquidity.
- Silage:Fermented high-moisture forages from corn, sorghum, or grass preserving nutritional value through anaerobic storage, dominant in European dairy regions with limited grazing seasons.
Concentrates command the established base. The steepest expansion runs through additives.
Animal Category:
Application-specific nutritional requirements create distinct formulation expertise barriers between monogastric-modeled small ruminants and complex rumen systems in large bovines.
- Cattle:Dairy and beef cattle requiring precision-balanced rations optimizing milk components or feed conversion ratios, with Holstein genetics demanding specialized bypass fat and amino acid protocols. Procurement concentrates in Brazil's Minas Gerais dairy triangle where farmer buying committees disintermediate traditional cooperatives.
- Buffaloes:Water and river buffalo systems prevalent across South Asia and Southeast Asia with lower metabolic rates and distinct fiber digestion kinetics, where commercial compound feed penetration remains minimal despite 2.5 million head in Vietnam alone.
- Sheep:Finishing lambs and breeding ewes with lower absolute intake volumes but high sensitivity to copper toxicity and metabolic disorders, served by regional premix specialists.
- Goats:Dairy and meat goat operations requiring browse-adapted mineral supplementation and toxin tolerance for varied forage bases, concentrated in Mediterranean and Middle Eastern production clusters.
Cattle anchor volume throughput. Buffaloes present the most underdeveloped commercial opportunity.
Distribution Channel:
Customer type fragmentation separates institutional procurement through cooperative hierarchies from disintermediated direct contracting and emerging digital platforms.
- Direct Sales:Feed mill-to-farm contracting with embedded technical service and multi-year supply agreements, gaining share in Poland's Masovian production cluster and Brazil's southern dairy states.
- Wholesalers:Regional distributors aggregating smaller farm orders with warehousing and credit extension, dominant where cooperative trading desks retain procurement control.
- E-Commerce Platforms:Mobile-enabled ordering systems bypassing traditional agricultural cooperative hierarchies, shortening payment cycles in Brazil's Minas Gerais dairy triangle.
- Retail Stores:Farm supply outlets serving hobby farmers and small-scale producers with bagged feeds and limited technical support.
Direct sales command the established base. The steepest expansion runs through e-commerce platforms.
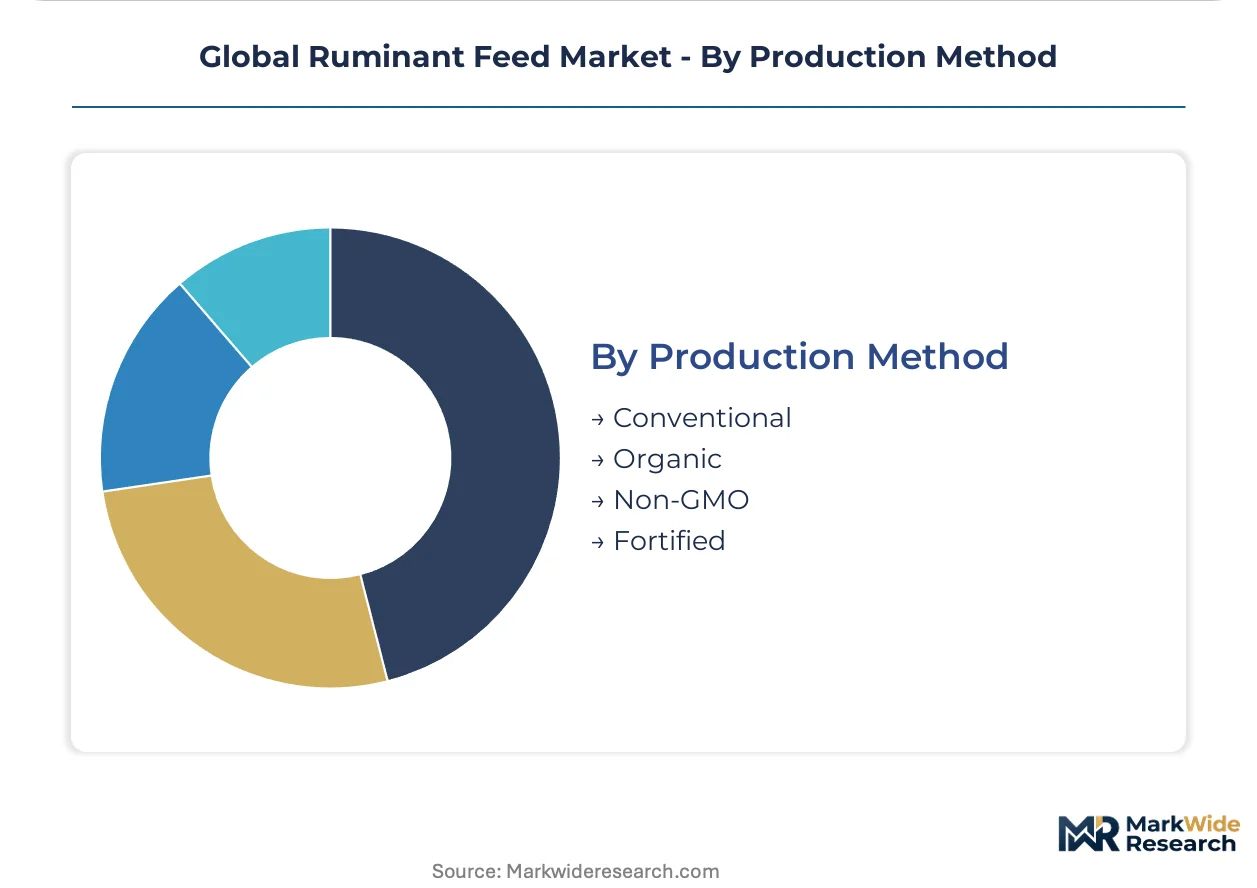
Production Method:
Margin and certification tiering separates commodity production from premium-positioned systems commanding processor preference and export eligibility.
- Conventional:Standard compound feed manufacturing with synthetic inputs and conventional grain and protein meal sourcing, facing cost pressure from fermentation-derived amino acid competition.
- Fortified:Enhanced formulations with stabilized vitamins, heat-adapted premixes, and targeted additives for stress conditions, expanding addressable herd days in tropical dairy belts above 35°C ambient temperatures.
- Organic:Certified organic production excluding synthetic pesticides and GMO inputs, required by premium dairy processors in the European Union with full supply chain traceability mandates under REACH and EU Green Deal.
- Non-GMO:Identity-preserved grain and protein sourcing without organic certification, serving intermediate market tiers with geolocation verification requirements from Dutch and German cooperatives.
Conventional methods command the established base. The steepest expansion runs through fortified production.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cooperative procurement managers in the Netherlands and India command the largest consolidated feed purchasing pools, while fragmented smallholder systems across Southeast Asia and East Africa still rely on informal distribution networks.
United States
Large herd nutrition consultants in Wisconsin and Idaho specify fermented amino acids at 40-60% inclusion rates, displacing conventional protein sources. The FDA enforces antibiotic residue limits that shape formulation choices for dairy processors. Cargill Inc. leverages its captive oilseed processing network to control lysine and methionine input costs across North American dairy operations.
Netherlands
Processor-owned cooperatives mandate enzyme-supplemented rations under EU Green Deal methane accounting protocols. REACH regulations mandate full supply chain traceability for soy and palm derivatives entering compound feed manufacturing. Dairy farmers in the Dutch dairy belt negotiate multi-year supply agreements with embedded nutrition consulting, disintermediating traditional agricultural cooperatives.
India
State-level milk federations aggregate smallholder demand for fortified compound feeds across Uttar Pradesh and Gujarat. FSSAI enforces aflatoxin thresholds and mineral premix labeling that determine market access for imported and domestic formulations. DSM-Firmenich deploys stabilized vitamin formulations that maintain bioavailability above 35°C ambient temperatures in the northern dairy belt.
Brazil
Farmer buying committees in Minas Gerais disintermediate traditional cooperatives through direct contracting with regional feed mills. ANVISA regulates veterinary prescription requirements for rumen modifiers in regulated dairy supply chains. Mobile-enabled feed ordering platforms shorten payment cycles and capture margin in the southern dairy states.
Vietnam
Commercial compound feed penetration remains minimal across 2.5 million head water buffalo population despite expanding dairy cattle operations. The country's national agricultural regulator enforces feed safety standards for imported premixes. De Heus competes with localized formulation expertise that could extend from dairy cattle to buffalo systems.
Global Ruminant Feed Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a tiered structure where integrated oilseed processors and fermentation technology holders capture disproportionate supplier power. The market consolidates around three strategic archetypes: captive amino acid producers leveraging precision fermentation, regional formulation specialists with localized expertise, and cooperative-linked distributors controlling procurement hierarchies. Dominant competitive moves include backward integration into oilseed crushing and strategic partnerships for heat-adapted premix development.
Within the integrated processing tier, Cargill Inc. and Archer Daniels Midland occupy positions anchored by captive supply networks that compress input costs for dairy nutritionists. DSM-Firmenich exemplifies the R&D-intensive additive specialist archetype, while De Heus represents regional formulation expertise tailored to smallholder buffalo and cattle systems. These three companies illustrate how supplier power concentrates with fermentation technology holders and localized service providers rather than commodity compounders.
| Leading Market Players |
|---|
| Cargill Inc. |
| Archer Daniels Midland |
| Land O Lakes Feed |
| ForFarmers |
| De Heus |
| DSM-Firmenich |
| Nutreco |
| Charoen Pokphand Foods |
| Biomin |
| Others |
Supply & Pricing Matrix
Captive lysine and methionine fermentation capacity concentrated among North American and European integrated agribusiness groups anchors margin capture downstream at dairy nutrition service providers and compound feed mills. This upstream control over precision amino acids reshapes how formulation economics flow through processor-compliant milk supply chains.
Pricing Analysis
Cost-plus contracts with soybean meal indexation dominate protein supplement procurement in North American dairy operations. Price differentiation rests on certification grade for EU Green Deal compliance and volume scale through state-level milk federation aggregation. Pricing pressure stems from precision fermentation compressing amino acid input costs for large herd nutrition consultants. Smallholder cooperatives in India's northern dairy belt exhibit highest price sensitivity, while processor-owned Dutch cooperatives prioritize methane-accounting compliance over unit cost.
Supply Chain Analysis
EU Green Deal deforestation-free certification requirements restrict soy and palm kernel cake flows into European compound feed manufacturing. Raw material sourcing draws from Brazilian oilseed crushing, Indian cottonseed extraction, and Southeast Asian palm kernel processing. Single-source vulnerability concentrates in fermentation-derived amino acid capacity controlled by integrated agribusiness groups. Distribution runs through direct mill-to-farm contracting with embedded technical service in Brazil's Minas Gerais and Poland's Masovian clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through cooperative consolidation across India's state-level milk federations and direct contracting by farmer buying committees in Brazil's southern dairy states.
For Market Incumbents: Pre-empt displacement by precision fermentation through backward integration into captive amino acid capacity or strategic partnerships with biotechnology holders. Defend formulation relationships by embedding real-time ration optimization services that independent consultants cannot replicate. Invest in heat-adapted vitamin premix R&D to capture expanded herd days in tropical dairy belts above 35°C ambient temperatures. For New Entrants and Emerging Players: Establish a beachhead in Vietnam's 2.5 million head water buffalo population where commercial compound feed penetration remains minimal. Target direct-to-farm digital distribution platforms in Brazil's Minas Gerais dairy triangle to bypass cooperative hierarchies and capture margin through shortened payment cycles. Lead with localized formulation expertise adapted from dairy cattle to buffalo fiber digestion kinetics. For Investors and Strategic Acquirers: Capital is best deployed toward fermentation technology holders with scalable amino acid platforms and regional formulation specialists with embedded service relationships in fragmented smallholder systems. Long-term viability favors suppliers capable of carbon credit monetization through methane-reducing feed additives qualifying under California's Low Carbon Fuel Standard. Watch for inflection when EU carbon farming certification protocols clarify additive qualification pathways.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Cargill and DSM-Firmenich are expanding captive amino acid capacity to compress formulation costs for dairy nutritionists. |
| Heat-Adapted Premix Development | DSM-Firmenich deploys stabilized vitamin formulations maintaining bioavailability above 35°C in India's northern dairy belt. |
| Direct-to-Farm Digital Platforms | Mobile-enabled ordering systems in Brazil's Minas Gerais bypass cooperative hierarchies to shorten payment cycles. |
| Carbon Credit Monetization Pathways | Methane-reducing additives qualifying under California's Low Carbon Fuel Standard create new revenue streams for nutrition providers. |
| Buffalo Formulation Localization | De Heus extends expertise from dairy cattle to Vietnam's 2.5 million head water buffalo population with minimal commercial feed penetration. |
Research Methodology
Operator-level perspectives from cattle nutritionists, dairy cooperative procurement managers, compound feed mill operators, and precision fermentation technology developers anchored the qualitative base. Secondary validation drew from FDA antibiotic residue guidance, EU Green Deal methane accounting protocols, FSSAI aflatoxin threshold notifications, and ANVISA veterinary prescription requirements. Bottom-up volume modeling across feed type and animal category segments triangulated with top-down macroeconomic drivers.
Scenario-bracketing around regulatory implementation timelines and precision fermentation adoption curves shaped the analytical framework across the analysis window. Segmentation dimensions modeled include feed type tier, animal category, distribution channel structure, and production method certification grade. CAGRs derived from weighted average growth across volume pools, with inputs from herd expansion projections in India and Brazil and processor-grade milk standard enforcement in the Netherlands and Denmark.
Sensitivities concentrate around EU Green Deal deforestation-free certification enforcement timelines and precision fermentation capacity expansion rates. Forecasts reflect assumptions on smallholder cooperative consolidation velocity and carbon credit monetization protocol development. Material shifts in EU methane emissions accounting scope or FSSAI premix certification timelines would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Germany Animal Protein Market
Agriculture and Agri Products
UAE Agriculture Market
Agriculture and Agri Products
Global Coco Peat Market
Agriculture and Agri Products
Henequen Market
Agriculture and Agri Products
Plant Antifreeze Market
Agriculture and Agri Products
High Fiber Feed Market
Agriculture and Agri Products
Malaysia Floriculture Market
Agriculture and Agri Products
Animal Derivatives Market
Agriculture and Agri Products
Spain Compound Feed Market
Agriculture and Agri Products
Cashew Market
Agriculture and Agri Products
Rapeseed Oil Market
Agriculture and Agri Products
Boswellia Market
Agriculture and Agri Products
Italy Alfalfa Market
Agriculture and Agri Products
Faba Beans Flour Market
Agriculture and Agri Products
LAMEA Rapeseed Oil Market
Agriculture and Agri Products
Honeysuckle Market