
 Specialty Egg Market | 2026-2036
Specialty Egg Market Size, Share, and Industry Trends Forecast 2026-2036
Specialty Egg Market Analytics
Pasture-raised certification is collapsing the gap between commodity and premium tiers as retailers rewrite procurement standards. Cal-Maine Foods leverages its vertically integrated feed-to-shelf network to sustain volume leadership across conventional and specialty grades. Vital Farms differentiates through a dedicated pasture-raised model that anchors brand equity in animal-welfare transparency.
Specialty eggs denote shell eggs produced under defined husbandry, nutritional, or environmental protocols that exceed conventional cage-system benchmarks, including omega-3 fatty acid enrichment through flaxseed-supplemented layer diets and outdoor access mandates measured in square feet per bird. Their primary commercial purpose is to command price premiums in retail and food-service channels by meeting verified welfare, nutritional, or sustainability claims. Cage-free product type dominates volume as quick-service chains and grocers convert procurement policies, while omega-3 enriched occupies concentrated margin pools in functional-food positioning. Online retail distribution channel is expanding fastest among direct-to-consumer subscription models that bypass traditional wholesale markups.
USDA Organic certification and FDA egg safety rules govern product identity and refrigeration standards in the United States, while the EU's Cage-Free Egg Directive and EFSA welfare guidelines shape barn infrastructure investments across member states. These frameworks elevate compliance costs for entrants but lock in shelf access for certified incumbents. Stakeholders must monitor divergence between state-level cage-free mandates and federal labeling thresholds to avoid stranded capacity in transitional housing systems.
Market Dynamics
The EU's Cage-Free Egg Directive is forcing barn-conversion investments across member states while North American quick-service chains rewrite procurement standards, compressing the timeline for specialty-grade supply expansion.
Growth Catalysts
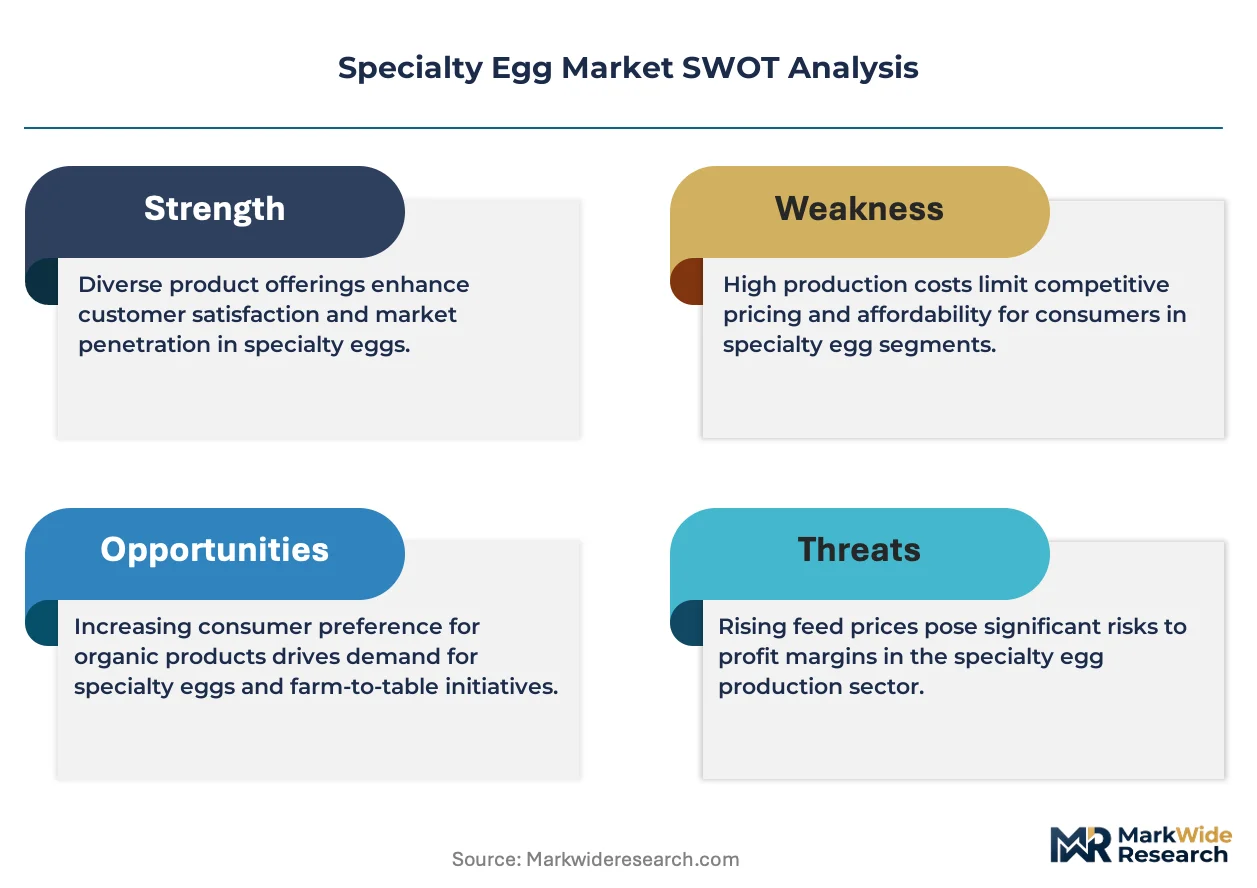
- EU Cage-Free Egg Directive:Germany's retail chains committed to 100% cage-free shelled egg assortments by 2026, accelerating barn infrastructure investments across Dutch and Danish producer networks.
- Quick-service procurement conversion:Restaurant kitchens across the United States and Canada now prioritize traceable sourcing, pulling volume through verified welfare channels.
- Flaxseed-supplemented layer diets:Omega-3 fatty acid enrichment protocols command functional-food premiums in health-conscious consumer segments.
Market Restraints
- Feed cost volatility:Organic soybean and flaxseed prices fluctuate with climate-driven harvest variability, compressing margins for pasture-raised operators.
- Supply concentration in Iowa and Ohio:Conventional shell egg production clusters in these states create logistical bottlenecks for specialty-grade distribution to coastal demand centers.
- Technical limitation in outdoor access verification:Square-foot-per-bird mandates lack standardized audit protocols, creating certification friction between competing welfare labels.
Strategic Opportunities
- Direct-to-consumer subscription models:Online retail channels bypass traditional wholesale markups, capturing margin pools previously lost to distributor networks.
- India's emerging urban premium segment:Metro consumers in Mumbai and Bangalore demonstrate willingness-to-pay for imported welfare-certified shell eggs.
- USDA Organic regulatory tailwind:Federal labeling thresholds for organic certification create shelf-access moats against uncertified entrants.
Industry Challenges
- Veterinarian specialization gap:Poultry welfare auditing requires trained professionals conversant in pasture-raised health management, a credential scarce outside veterinary schools in California and Texas.
- Transitional housing stranded capacity:Producers investing in enriched colony systems face obsolescence risk as state-level cage-free mandates outpace federal harmonization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Specialty Egg Market |
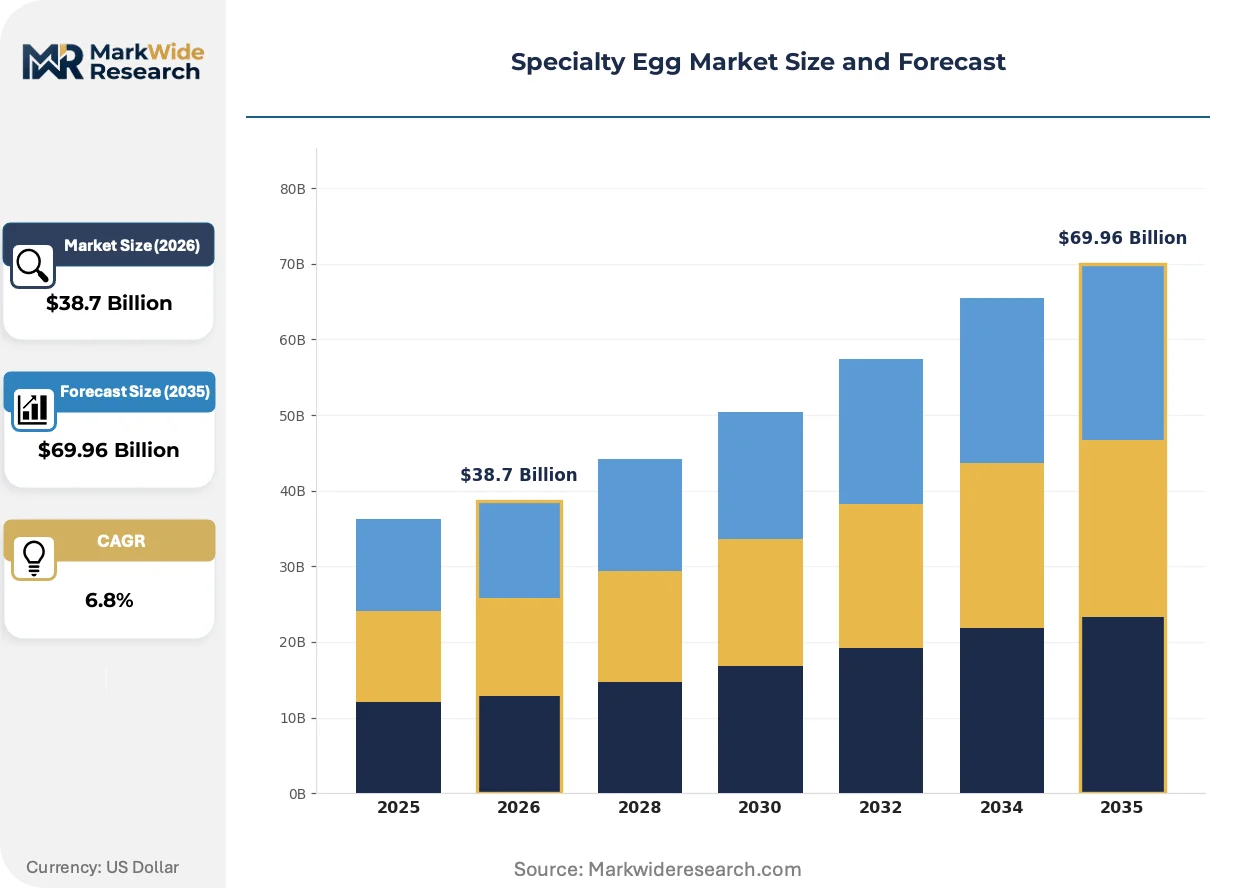
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic, Free-Range, Cage-Free, Omega-3 Enriched Distribution Channel: Supermarkets, Online Retail, Farmers Markets, Food Service Customer Type: Households, Restaurants, Caterers, Bakeries Packaging Type: Cartons, Bulk, Trays, Biodegradable |
| Companies Covered | Cal-Maine Foods, Rose Acre Farms, Vital Farms, Eggland's Best, Happy Egg Co, Michael Foods, Hillandale Farms, Rembrandt Foods, Farmhouse Eggs, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Specialty Egg Market Evolving Landscape
Pasture-raised certification protocols are collapsing historical tier distinctions as retailers consolidate procurement around single welfare standards, while digital traceability tools embed provenance data directly into consumer-facing packaging.
Blockchain-enabled supply chain verification is bifurcating the market between operators with capital to deploy sensor networks and legacy producers dependent on paper-based audit trails. Premium retail banners in the United Kingdom and Netherlands now mandate real-time flock monitoring as a listing prerequisite. This technology is compressing price premiums for non-verified specialty grades while expanding margin capture for integrated feed-to-shelf networks.
The EU's Cage-Free Egg Directive triggered mandatory barn conversions across France, Spain, and Poland by 2027. Producers in these markets face accelerated depreciation schedules for existing cage infrastructure. Germany and Austria responded fastest, with completed conversions already capturing shelf space in REWE and Billa retail networks.
Subscription-based home delivery is displacing conventional grocery purchase patterns among millennial and Gen-Z households in urban United States markets. Vital Farms and regional cooperatives bypass distributor markups through direct-to-consumer platforms. This channel shift concentrates most visibly in Austin, Denver, and Portland metro areas where density supports cold-chain logistics at viable unit economics.
Specialty Egg Market Segmentation
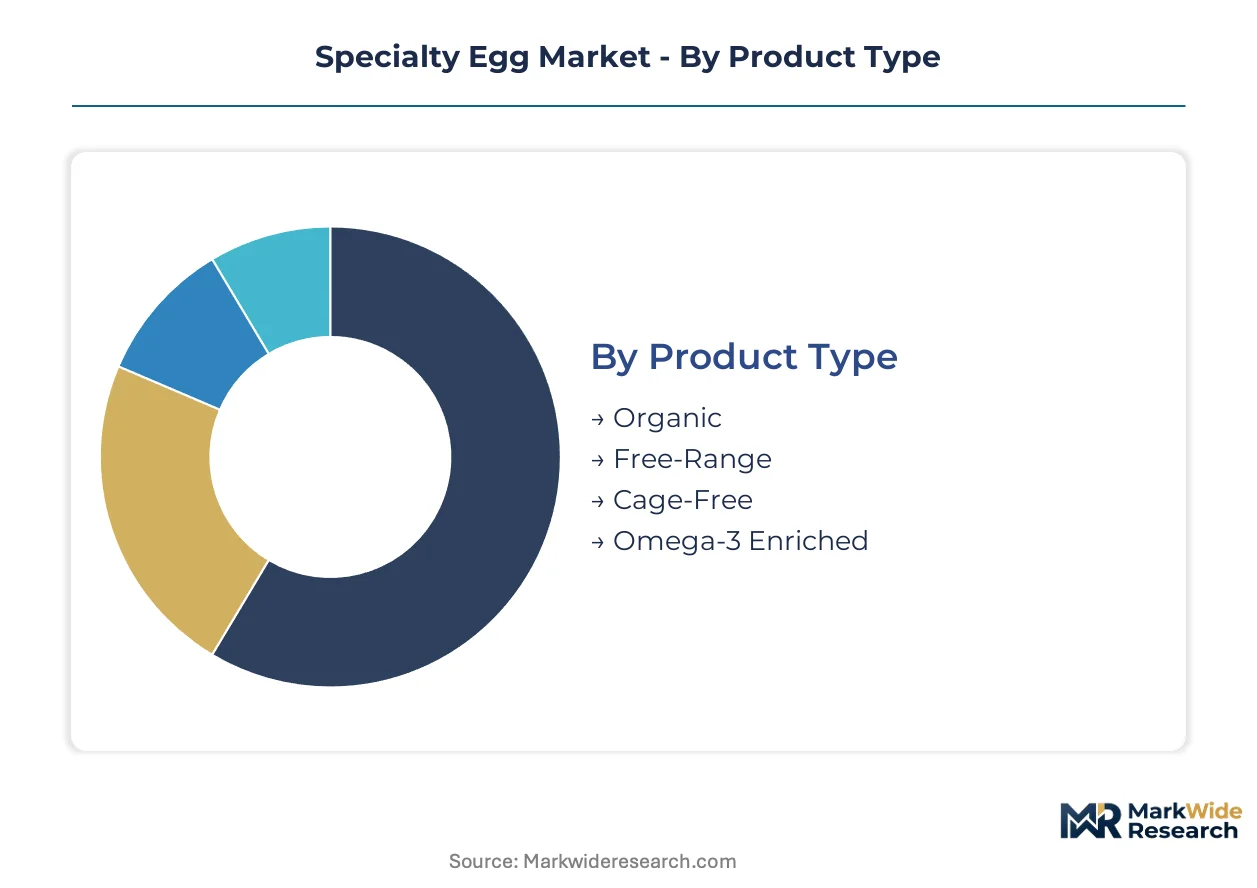
Specialty egg procurement standards diverge sharply across regulatory jurisdictions, forcing suppliers to maintain parallel certification tracks for shelf access. Segmentation reveals how compliance costs stratify the supplier base while channel fragmentation creates divergent margin structures.
Product Type:
USDA Organic and EU organic equivalence agreements create the steepest compliance barriers, while cage-free mandates spread fastest through quick-service procurement policies.
- Cage-Free:Hens housed in barn systems without restrictive enclosures, meeting the EU Cage-Free Egg Directive baseline and matching quick-service chain procurement floors. Volume concentrates in German REWE and Austrian Billa retail networks where completed conversions already lock in shelf placement.
- Omega-3 Enriched:Flaxseed-supplemented layer diets elevate alpha-linolenic acid content for functional-food positioning. Demand clusters in health-conscious urban households across Denver and Portland metro areas where subscription models bypass wholesale markups.
- Organic:USDA-certified feed and outdoor access protocols command the steepest premiums. FDA egg safety rules叠加 with organic standards elevate cold-chain compliance costs.
- Free-Range:Square-foot-per-bird outdoor access mandates lack standardized audit protocols, creating certification friction between competing welfare labels.
Established volume favors cage-free; emerging adoption favors omega-3 enriched.
Distribution Channel:
Channel economics separate operators by capital intensity, with cold-chain infrastructure requirements filtering participation.
- Supermarkets:Traditional retail banners dominate volume through established distributor relationships. REWE in Germany and regional cooperatives in the United States leverage existing logistics networks to maintain price competitiveness.
- Online Retail:Direct-to-consumer subscription platforms capture margin pools previously lost to wholesale intermediaries. Austin, Denver, and Portland metro areas demonstrate viable unit economics for cold-chain home delivery.
- Food Service:Restaurant and hospitality procurement prioritizes traceable sourcing through verified welfare channels. Quick-service chains in the United States and Canada now mandate cage-free baselines.
- Farmers Markets:Local producer-direct sales support pasture-raised premiums through face-to-face welfare verification. Seasonal availability limits year-round volume capture.
Supermarkets retain volume leadership; online retail climbs the fastest.
Customer Type:
End-use specifications fragment by preparation method and certification requirements.
- Households:Urban millennial and Gen-Z consumers drive subscription adoption through welfare transparency preferences.
- Restaurants:Fine-dining establishments source pasture-raised grades for menu storytelling; quick-service chains convert procurement to cage-free baselines.
- Bakeries:Volume buyers prioritize shell stability and yolk color consistency over welfare certification tiers.
- Caterers:Event-driven demand concentrates in metropolitan corridors with established specialty egg distribution.
Restaurants anchor premium tier demand; households expand most quickly.
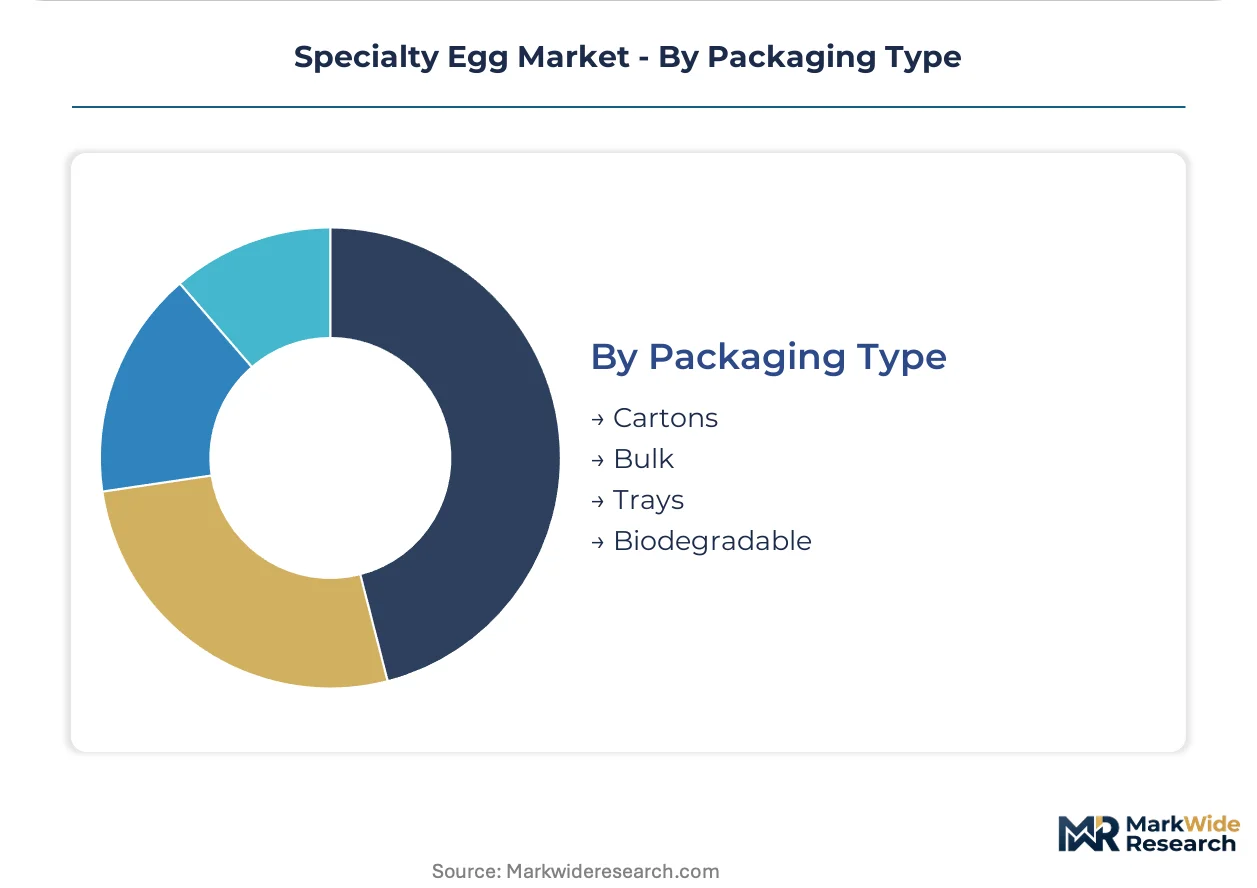
Packaging Type:
Packaging innovation responds to retailer sustainability mandates and logistics optimization.
- Cartons:Standard retail format with established recycling infrastructure dominates supermarket shelves.
- Bulk:Food service and bakery procurement favors unboxed volume for operational efficiency.
- Trays:Commercial kitchens utilize stackable formats for high-throughput environments.
- Biodegradable:Emerging formats align with EU Green Deal circular economy targets and retailer ESG commitments.
Cartons hold volume dominance; biodegradable formats gain share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across consuming regions. German buyers accept steep premiums for verified welfare credentials, while Indian metropolitan consumers remain highly sensitive to price-to-quality ratios despite nascent premium interest.
United States
Quick-service procurement mandates and millennial subscription adoption drive demand concentration. FDA egg safety rules overlay with USDA Organic standards to elevate compliance costs. Austin, Denver, and Portland metro areas anchor direct-to-consumer cold-chain logistics for pasture-raised distribution.
Germany
Retail chain commitments to 100% cage-free assortments by 2026 pull volume through verified channels. The EU Cage-Free Egg Directive accelerates barn infrastructure investments across Dutch and Danish producer networks. REWE and Billa retail networks lock in shelf placement for completed conversions.
Netherlands
Export-oriented producer networks supply welfare-certified shell eggs to German and Belgian retail banners. EFSA welfare guidelines shape barn design specifications for cross-border compliance. Producer cooperatives in Gelderland and Overijssel concentrate conversion investments ahead of 2027 deadlines.
India
Urban premium segments in Mumbai and Bangalore demonstrate willingness-to-pay for imported welfare-certified grades. FSSAI labeling standards create baseline safety thresholds without mandating welfare tiers. Metro cold-chain infrastructure gaps limit year-round specialty-grade availability outside top-tier cities.
United Kingdom
Premium retail banners mandate real-time flock monitoring as a listing prerequisite. EU Green Deal circular economy targets accelerate biodegradable packaging adoption. Producer networks in East Anglia and the Midlands consolidate around single welfare standards as retailers collapse historical tier distinctions.
Specialty Egg Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the specialty egg market. Vertically integrated feed-to-shelf networks command volume positions through captive supply control, while pasture-raised specialists capture brand equity through animal-welfare transparency. Three archetypes dominate: scale-driven commodity converters, welfare-certified premium specialists, and direct-to-consumer subscription platforms. Competitive moves concentrate on barn infrastructure conversion ahead of regulatory deadlines and backward integration into organic feed production.
Among publicly traded operators, Cal-Maine Foods occupies a position exemplifying scale-driven vertical integration across conventional and specialty grades. Vital Farms represents the dedicated pasture-raised archetype anchoring brand equity in transparency protocols. Rose Acre Farms sits within the diversified producer tier spanning cage-free, organic, and value-added nutritional enrichment lines.
| Leading Market Players |
|---|
| Cal-Maine Foods |
| Rose Acre Farms |
| Vital Farms |
| Eggland's Best |
| Happy Egg Co |
| Michael Foods |
| Hillandale Farms |
| Rembrandt Foods |
| Farmhouse Eggs |
| Others |
Value Network & Pricing Analysis
Feed mill scale economies in Iowa and Ohio shape both supply concentration and price floors for conventional grades, while specialty operators absorb organic soybean premiums that reset baseline costs across pasture-raised tiers. Cage-free mandates from quick-service chains compress margin recovery timelines as barn conversion depreciation loads fixed costs onto early production cycles.
Pricing Analysis
The EU Cage-Free Egg Directive dictates the pricing tier structure across European markets, with Germany's REWE and Austria's Billa retail networks capturing completed conversions at shelf. Pricing stratifies across premium, standard, and economy tiers based on certification grade and volume scale, with USDA Organic commanding the steepest premiums. Cost compression in cage-free tiers is intensifying because organic feed input volatility outpaces contract pricing adjustments. Quick-service chains demonstrate the least price sensitivity due to procurement mandate compliance deadlines, while household subscription buyers in Austin and Denver show moderate elasticity.
Supply Chain Analysis
The United States and Netherlands anchor shell egg production for their respective domestic and export markets, with Iowa and Ohio feed mills supplying conventional grades and Gelderland cooperatives specializing in welfare-certified exports. Layer hen operations rest on organic soybean, flaxseed, and specialized veterinary services as critical inputs. Single-source vulnerability concentrates in organic feed supply channels where climate-driven harvest variability disrupts contracted volumes. Distribution runs through integrated feed-to-shelf networks for retail placement, while direct-to-consumer subscription platforms bypass wholesale markups in dense urban corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialty egg markets reward service-attach models where subscription platforms and cold-chain logistics layers expand faster than shell production capacity, embedding recurring revenue through direct consumer relationships.
For Market Incumbents: Consolidate barn infrastructure investments ahead of state-level cage-free mandate divergence to avoid stranded capacity in transitional housing systems. Lock in organic feed supply through backward integration or long-term offtake agreements with Iowa and Ohio grain cooperatives, neutralizing input cost volatility that compresses pasture-raised margins. For New Entrants and Emerging Players: Anchor in direct-to-consumer subscription channels where Austin, Denver, and Portland metro density supports viable cold-chain unit economics. Target India's Mumbai and Bangalore urban premium segments where FSSAI baseline standards create entry thresholds lower than EU or USDA certification barriers, leveraging imported welfare-certified positioning. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertically integrated operators with captive organic feed production and completed barn conversions. Five-to-ten year viability hinges on regulatory harmonization between federal labeling thresholds and accelerating state mandates. Watch for divergence in EU member state conversion timelines as an inflection indicator for export-oriented producer valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Barn Infrastructure Conversion | EU Cage-Free Egg Directive deadlines in France, Spain, and Poland accelerate depreciation schedules for cage systems. |
| Organic Feed Backward Integration | Iowa and Ohio grain cooperatives lock in supply control against climate-driven soybean price volatility. |
| Direct-to-Consumer Platform Launch | Subscription models in Austin, Denver, and Portland bypass distributor markups and capture household margin pools. |
| Blockchain Traceability Deployment | Real-time flock monitoring satisfies REWE and Billa listing prerequisites for premium shelf placement. |
| India Market Entry Partnership | Mumbai and Bangalore metro cold-chain gaps create first-mover advantage for imported welfare-certified grades. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with layer farm managers, retail category buyers at REWE and regional cooperatives, quick-service chain procurement directors, and veterinary welfare auditors from California and Texas programs. Secondary validation drew from USDA AMS reports, EU Commission agriculture statistics, FDA egg safety guidance documents, and customs trade data for shell egg flows. Bottom-up volume estimates from producer capacity filings triangulated against top-down consumption surveys across household, restaurant, and bakery end-use segments.
Across the analysis window, the analytical framework modeled product type segmentation by certification tier, distribution channel by cold-chain infrastructure intensity, and customer type by preparation method and welfare verification requirements. CAGRs were derived from regression analysis of historical price-volume relationships and regulatory mandate implementation schedules. Forecast inputs incorporated organic feed cost indices and quick-service chain procurement policy conversion timelines as industry-specific demand drivers.
Material uncertainties — feed commodity price spikes, veterinary credential scarcity, and regulatory harmonization failures — sit outside the modeled envelope. Forecasts reflect documented assumptions about barn conversion completion rates and subscription platform penetration ceilings. Recalibration cycles align with material shifts in EU directive enforcement and state-level cage-free mandate adoption.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Global Warm Water Aquaculture Feed Market
Agriculture and Agri Products
Aquatic Feed Ingredients and Products Market
Agriculture and Agri Products
North America Hemp Market
Agriculture and Agri Products
Global Coco Peat Market
Agriculture and Agri Products
Brazil Rice Market
Agriculture and Agri Products
Arnica Oil Market
Agriculture and Agri Products
France Animal Protein Market
Agriculture and Agri Products
Corn Co-Products Market
Agriculture and Agri Products
Africa Rice Market
Agriculture and Agri Products
Primary Feed Materials Market
Agriculture and Agri Products
North America Swine Feed Premix Market
Agriculture and Agri Products
Boswellia Market
Agriculture and Agri Products
Compound Feed Market
Agriculture and Agri Products
India Palm Oil Market
Agriculture and Agri Products
Cattle Feed Concentrate Market
Agriculture and Agri Products
Europe Compound Feed Market