
 Tractor Implements Market | 2026-2036
Tractor Implements Market Size, Share, and Industry Trends Forecast 2026-2036
Tractor Implements Market Intelligence
Aftermarket service revenue is tilting toward telemetry-enabled predictive maintenance as OEMs seek recurring income streams. Deere & Company leverages its integrated precision agriculture platform to lock in long-term service contracts across North American farm operations. AGCO Corporation anchors its competitive stance through deep specialization in high-horsepower tillage systems for Black Sea grain producers. Kubota Corporation competes aggressively in compact implement segments for Southeast Asian smallholder mechanization.
Tractor implements are mechanically coupled soil preparation, planting, and cultivation attachments engineered to specific three-point hitch geometries and power-take-off speed ratings, typically fabricated from boron steel to withstand abrasive field conditions. Their primary commercial purpose is to extend tractor utility across seasonal field operations while reducing per-acre labor inputs. Harrows and cultivators within the product type dimension command established replacement demand in mature North American markets where no-till adoption drives disc harrow refresh cycles. The application split reveals horticulture as the fastest-expanding demand pool, particularly in protected cropping systems across Mediterranean climates where bed-forming implements reduce water application rates.
The EPA's Tier 4 Final emission standards and the EU F-Gas Regulation jointly constrain hydraulic system designs, pushing implement manufacturers toward electric actuator architectures that eliminate refrigerant-dependent auxiliary power units. India's BIS certification requirements for agricultural equipment safety are tightening market access for unbranded Asian imports. Stakeholders must monitor how precision agriculture data ownership disputes between equipment manufacturers and farm cooperatives reshape attachment interoperability standards and software subscription bundling.
Market Dynamics
Precision agriculture telemetry is compressing equipment replacement cycles across commercial farming operations, while sustainability mandates from the EU Green Deal's Farm to Fork strategy are forcing redesigns of soil management attachments toward lower-impact architectures.
Growth Catalysts
- Precision Agriculture Platforms:Large-scale soybean operations in Brazil's Cerrado region are accelerating mechanized cultivation, driving demand for GPS-guided tillage and planting implements that optimize input application rates.
- EU Green Deal Compliance:The Farm to Fork strategy's soil health targets are mandating reduced tillage intensity, creating replacement demand for specialized disc harrows and strip-till equipment engineered for minimal soil disturbance.
- Horticulture Mechanization:Protected cropping expansion across Mediterranean climates is pulling bed-forming implements and precision irrigation attachments into high-value vegetable and berry production systems.
Market Restraints
- Boron Steel Price Volatility:Abrasion-resistant implement fabrication depends on alloy steel inputs subject to mining supply concentration and energy cost fluctuations, pressuring OEM margins on entry-tier product lines.
- Hydraulic System Redesign Costs:EPA Tier 4 Final and EU F-Gas Regulation constraints on refrigerant-dependent auxiliary power units are forcing costly electric actuator migrations that disadvantage smaller fabricators.
- Three-Point Hitch Standard Lock-in:Mechanical coupling geometries standardized decades ago limit architectural innovation and create compatibility barriers for novel attachment form factors.
Strategic Opportunities
- Smallholder Mechanization:Southeast Asian rice and palm oil producers present untapped demand for compact, affordable tillage implements compatible with sub-50 horsepower tractors.
- Telemetry-Enabled Service Contracts:Predictive maintenance platforms allow OEMs to capture recurring revenue streams by monitoring implement wear and scheduling proactive component replacement.
- Electric Actuator Convergence:Integration of precision agriculture sensors with electric drive systems enables section-control tillage that reduces overlap and input waste in irregular field geometries.
Industry Challenges
- Data Ownership Disputes:Precision agriculture platforms generate field-level yield and soil data whose control remains contested between equipment manufacturers and farm cooperatives, complicating attachment interoperability standards.
- BIS Certification Timelines:India's tightening safety requirements for agricultural equipment are extending market access timelines for unbranded Asian imports and raising compliance costs for new entrants.
- Software Subscription Bundling Complexity:OEMs face execution risk in unbundling hardware sales from precision agriculture software tiers without triggering customer churn to independent implement suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tractor Implements Market |
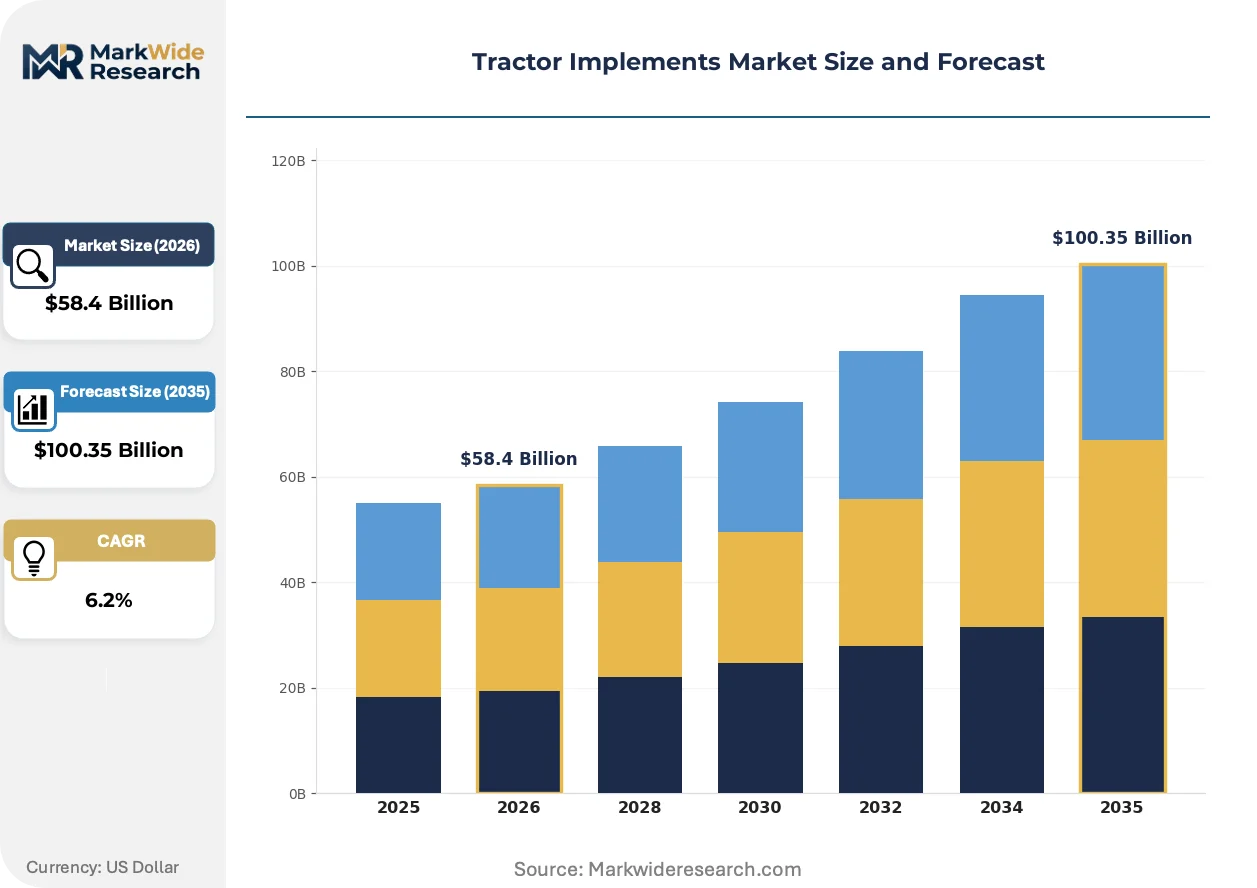
| Market Size in 2026 | $58.4 Billion |
| Market Size in 2035 | $100.35 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plows, Harrows, Seeders, Cultivators Application: Agriculture, Horticulture, Landscaping, Gardening End User: Farmers, Agricultural Cooperatives, Contractors, Government Technology: Manual, Hydraulic, Electric, Pneumatic |
| Companies Covered | Deere & Company, CNH Industrial, AGCO Corporation, Kubota Corporation, Mahindra & Mahindra, CLAAS, SDF Group, Kuhn Group, Tractors and Farm Equipment Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tractor Implements Market Strategic Shifts & Innovations
Implement manufacturers are racing to embed sensor networks and autonomous control systems into mechanical soil preparation tools, transforming attachments from passive pull-behind equipment into data-generating precision agriculture nodes.
Variable-rate application technology is digitizing tillage depth and seed placement across commercial grain operations. Large-scale corn and wheat producers in the US Corn Belt are retrofitting existing planters with real-time soil sensing and hydraulic adjustment modules. This capability is digitizing field management by enabling sub-acre prescription maps that optimize input placement and reduce waste.
The EU F-Gas Regulation is phasing down hydrofluorocarbon use in agricultural equipment auxiliary systems. Implement manufacturers are eliminating refrigerant-dependent power units in favor of electric architectures and mechanical drive alternatives. High-horsepower tillage systems for Black Sea grain producers face the steepest redesign costs, with Ukrainian and Romanian operators postponing fleet refresh decisions pending clarity on retrofit pathways.
Service unbundling is fragmenting traditional dealer networks as farm cooperatives negotiate direct telemetry access. North American equipment purchasers are separating hardware acquisition from precision agriculture software subscriptions, pressuring OEMs to maintain attachment compatibility with third-party control platforms. This behavior is most pronounced among mid-scale operations in Iowa and Illinois seeking to avoid vendor lock-in across mixed-brand fleets.
Tractor Implements Market Segmentation
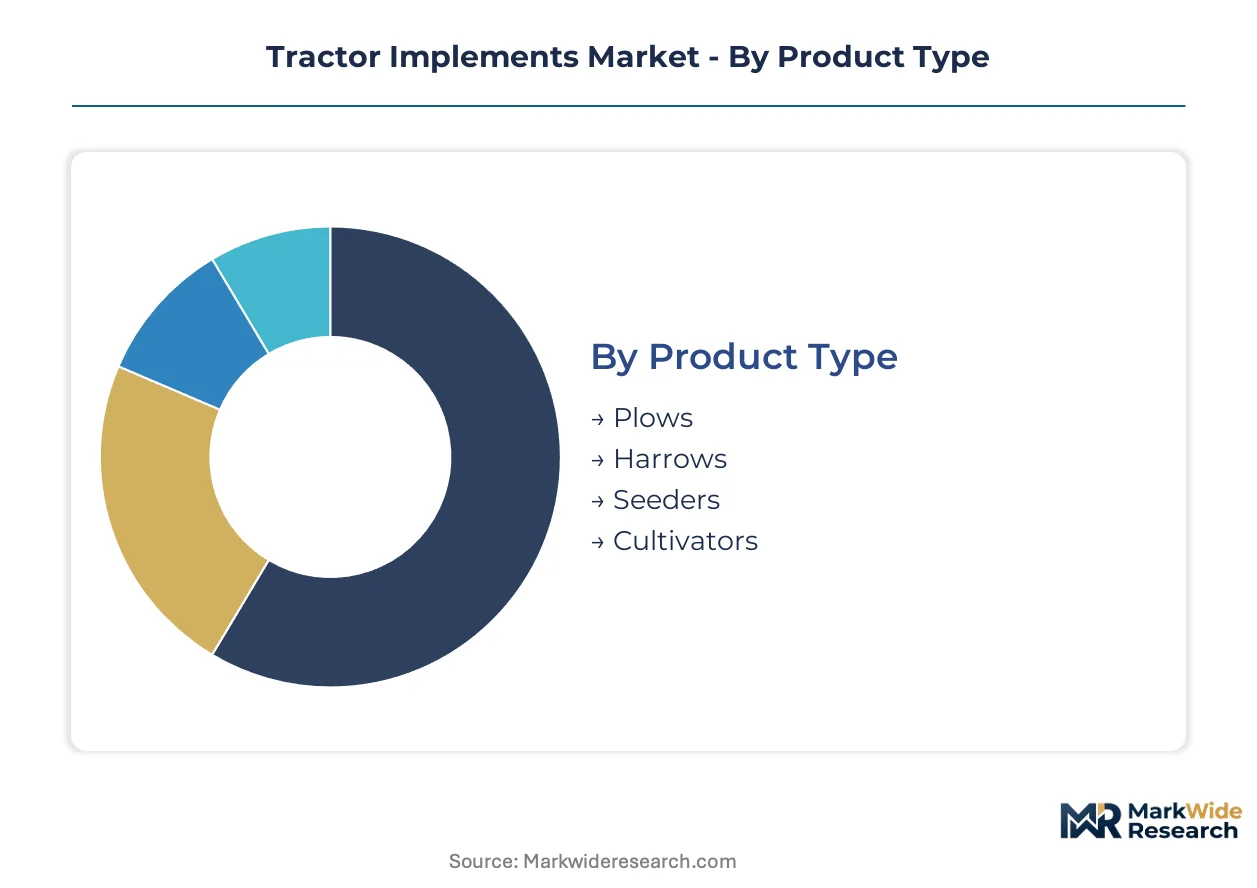
Tractor implements manufacturers configure product portfolios around distinct mechanical interfaces and field operation requirements. Each segment demands specialized aftermarket service intensity, from wear-part replacement schedules to precision agriculture calibration protocols.
Product Type:
After-sales-service intensity varies sharply across implement categories, with soil-engaging tools requiring frequent component replacement versus planting equipment needing precision calibration support.
- Harrows:Fabricated from boron steel with replaceable disc gangs and bearing assemblies, these implements face accelerated refresh cycles in North American no-till systems where residue management drives annual blade replacement. Disc harrow demand concentrates in Iowa and Illinois corn-soy rotations.
- Cultivators:Spring-tooth and rigid-shank configurations dominate weed control operations across Black Sea grain belts. Ukrainian operators prioritize tine durability given abrasive loess soils and extended field seasons.
- Plows:Moldboard and chisel plows retain steady demand in conventional tillage regions of Brazil's Cerrado, though precision agriculture adoption is compressing their replacement timelines.
- Seeders:Air drill and planter units integrate GPS-guided section control, pulling horticulture and broadacre grain producers toward telemetry-enabled service contracts for meter calibration.
Harrows hold the largest share; momentum sits with seeders as precision planting platforms displace conventional drill configurations.
Application:
Margin structures diverge across application segments, with high-value horticulture commanding premium pricing for specialized bed-forming tools versus commodity agriculture's volume-driven replacement cycles.
- Agriculture:Broadacre grain and oilseed operations in Brazil, the US Corn Belt, and Ukraine's steppe zones drive bulk implement demand through seasonal field preparation windows.
- Horticulture:Protected cropping across Spain's Almería province and Italy's Po Valley is expanding fastest, with bed-forming implements and precision irrigation attachments reducing water application rates in high-value vegetable systems.
- Landscaping:Municipal and commercial ground maintenance in suburban US corridors sustains demand for compact tillage and seeding attachments compatible with sub-40 horsepower tractors.
- Gardening:Small-scale cultivation in Japan's peri-urban zones and France's market garden regions favors lightweight rotary tillers and precision seeders for intensive vegetable plots.
Agriculture dominates volume; horticulture is climbing the fastest as protected cropping systems mechanize.
End User:
Procurement authority concentrates differently across customer types, with cooperatives negotiating fleet-scale telemetry contracts versus individual farmers prioritizing implement durability and parts availability.
- Farmers:Individual owner-operators in India's Punjab and Haryana states drive compact implement demand, with BIS certification requirements increasingly filtering equipment choices toward branded suppliers.
- Agricultural Cooperatives:Large-scale operations across Iowa, Illinois, and Brazil's Mato Grosso negotiate direct precision agriculture platform access, unbundling hardware from software subscriptions to avoid vendor lock-in.
- Contractors:Custom tillage and planting service providers in Ukraine and Romania face steep fleet refresh decisions pending clarity on EU F-Gas Regulation retrofit pathways for high-horsepower hydraulic systems.
- Government:Municipal and state procurement in US conservation programs and India's farm mechanization subsidies shapes entry-tier implement specifications and pricing floors.
Farmers represent the largest installed base; agricultural cooperatives are gaining share fastest through consolidated fleet purchasing.
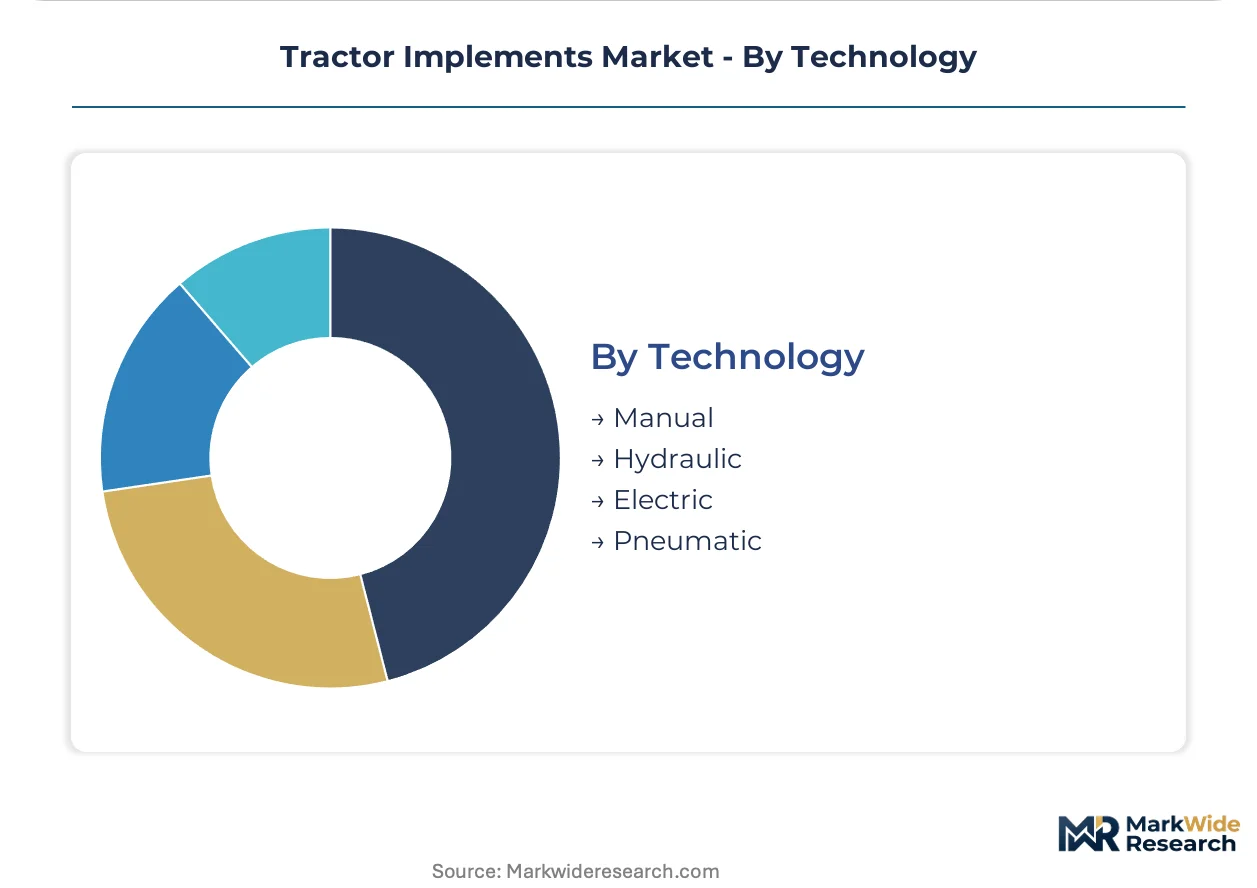
Technology:
Supply concentration for electric actuator components is reshaping competitive positioning as EPA Tier 4 Final and EU F-Gas Regulation constraints eliminate refrigerant-dependent auxiliary power units.
- Hydraulic:Conventional three-point hitch-powered systems retain dominance in Brazilian soybean operations and Black Sea grain belts, though redesign costs for emission-compliant architectures pressuring smaller fabricators.
- Electric:Section-control tillage with integrated precision agriculture sensors is displacing hydraulic alternatives in US Corn Belt operations seeking overlap reduction in irregular field geometries.
- Manual:Hand-guided tillage tools persist in Southeast Asian smallholder rice systems and India's fragmented landholdings where sub-50 horsepower tractor compatibility limits automation adoption.
- Pneumatic:Air-powered seed metering and fertilizer distribution systems serve specialized horticulture applications in Mediterranean climate zones requiring precise input placement.
Hydraulic systems hold the largest share; electric architectures are expanding most quickly as emission regulations force actuator migration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indian smallholders exhibit acute price sensitivity toward compact tillage attachments, while Brazilian commercial operators absorb premium pricing for GPS-guided precision systems. This demand-elasticity contrast structures procurement patterns across major agricultural economies.
United States
Corn-soy rotations across Iowa and Illinois drive disc harrow replacement cycles as no-till residue management accelerates blade wear. The EPA's Tier 4 Final emission standards compel hydraulic system redesigns toward electric actuator architectures. Equipment purchasers in the Midwest increasingly unbundle hardware acquisition from precision agriculture software subscriptions.
Brazil
Commercial soybean expansion across Mato Grosso and the Cerrado region pulls GPS-guided tillage and planting implements into large-scale mechanized operations. ANVISA alignment with international agricultural equipment safety protocols shapes import certification timelines. São Paulo-based dealer networks consolidate fleet-scale telemetry contracts for precision agriculture platforms.
Germany
High-horsepower tillage demand concentrates in Bavaria and Lower Saxony as arable operations optimize seedbed preparation across consolidated landholdings. The EU F-Gas Regulation phases out hydrofluorocarbon-dependent auxiliary power units in agricultural equipment. Stuttgart-area engineering clusters specialize in electric drive systems for section-control tillage applications.
India
Punjab and Haryana states drive compact implement demand as individual owner-operators mechanize rice-wheat rotations on fragmented landholdings. BIS certification requirements for agricultural equipment safety increasingly filter equipment choices toward branded suppliers. Gujarat-based fabricators expand production capacity for sub-50 horsepower tractor compatibility.
Ukraine
Black Sea grain producers across Odessa and Kharkiv oblasts prioritize tine durability for cultivators operating in abrasive loess soils. Contractors face deferred fleet refresh decisions pending clarity on EU F-Gas Regulation retrofit pathways for high-horsepower hydraulic systems. Romanian border regions mirror this procurement hesitation as operators await regulatory clarity.
Tractor Implements Market Key Industry Players
Full-line agricultural equipment manufacturers and specialized implement fabricators split the market along precision agriculture integration depth. The vendor base concentrates among three tiers: integrated platform providers capturing telemetry-enabled service revenue, regional specialists dominating localized tillage segments, and emerging Asian fabricators competing on compact equipment cost structures. Dominant competitive moves include precision agriculture platform unbundling from hardware sales and electric actuator supply chain consolidation for emission-compliant architectures.
Within the integrated platform tier, Deere & Company and AGCO Corporation exemplify contrasting geographic anchoring strategies. Deere leverages its North American precision agriculture installed base to lock in long-term service contracts across farm operations. AGCO occupies a position as a Black Sea region specialist through high-horsepower tillage system concentration. Kubota Corporation represents the compact implement archetype, competing aggressively in Southeast Asian smallholder mechanization segments where sub-50 horsepower tractor compatibility determines market access.
| Leading Market Players |
|---|
| Deere & Company |
| CNH Industrial |
| AGCO Corporation |
| Kubota Corporation |
| Mahindra & Mahindra |
| CLAAS |
| SDF Group |
| Kuhn Group |
| Tractors and Farm Equipment Limited |
| Others |
Cost & Logistics Intelligence
The Shanghai-Rotterdam container corridor's freight rate volatility feeds directly into landed cost spreads between Asian fabricators and European end-users, compressing margin buffers for entry-tier boron steel implements while amplifying pricing power for telemetry-integrated OEMs with captive service revenue streams.
Pricing Analysis
Aftermarket parts and predictive maintenance contracts generate the dominant lifetime value capture, with telemetry-enabled service subscriptions now exceeding hardware margins across North American farm operations. Three-tier pricing structure across premium GPS-integrated, standard mechanical, and economy manual configurations stratifies by precision agriculture sensor density and calibration support intensity. Cost compression in economy tiers is intensifying because Indian BIS certification timelines extend market access for unbranded imports. Individual owner-operators in Southeast Asian smallholder systems exhibit acute price sensitivity, while Brazilian commercial cooperatives absorb premium positioning for section-control tillage platforms.
Supply Chain Analysis
Export controls on precision agriculture sensor technologies and GPS guidance systems limit component flows from US and EU suppliers to certain end-markets, forcing secondary sourcing through Japanese and South Korean distributors. Boron steel fabrication concentrates in China, India, and Germany, with abrasion-resistant alloy supply anchored in Ukrainian mining corridors subject to disruption risk. Component sourcing draws from electric actuator specialists in Stuttgart engineering clusters, hydraulic system providers in Italian industrial districts, and compact drivetrain fabricators in Gujarat. Single-source vulnerability in high-grade boron steel concentrates supply risk for disc harrow and cultivator manufacturers. Distribution runs through OEM-captive dealer networks in mature markets and independent agricultural equipment traders in emerging mechanization zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of electric actuator engineering talent and precision agriculture platform integration capability is constraining competitive repositioning, with only a handful of suppliers capable of delivering emission-compliant architectures with embedded telemetry.
For Market Incumbents: Insulate precision agriculture installed bases through multi-year telemetry service contracts that raise switching costs for Iowa and Illinois farm cooperatives. Deepen backward integration into electric actuator component supply to offset Tier 4 Final compliance cost inflation. Lock in boron steel offtake agreements with Ukrainian and Russian suppliers before alternative alloy sourcing premiums harden. For New Entrants and Emerging Players: Compact tillage attachments for sub-50 horsepower tractors in Vietnam and Indonesia represent the most penetrable entry point, with local fabrication partnerships bypassing BIS certification barriers for Indian market access. Target horticulture bed-forming implements in Spain's Almería province where protected cropping mechanization outpaces incumbent service coverage. Pursue direct-to-cooperative sales models that unbundle hardware from precision agriculture subscriptions, mirroring successful procurement patterns in Brazil's Mato Grosso. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underoptimized agricultural equipment divisions lacking precision agriculture platform integration. Long-term viability hinges on telemetry-enabled recurring revenue capture rather than transactional implement sales. Monitor EU F-Gas Regulation retrofit pathway clarity as the inflection signal for Black Sea fleet refresh timing and Ukrainian contractor purchasing sentiment.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Agriculture Platform Integration | Transforms passive implements into data-generating nodes that lock in subscription revenue across Corn Belt operations. |
| Electric Actuator Supply Chain Consolidation | Captures scarce engineering capacity in Stuttgart and Osaka clusters ahead of Tier 4 Final compliance deadlines. |
| Telemetry-Enabled Service Contract Expansion | Shifts revenue mix toward recurring streams with higher lifetime value than transactional hardware sales. |
| Compact Implement Localization | Establishes cost-competitive production in Gujarat and Vietnam for Southeast Asian smallholder penetration. |
| Boron Steel Sourcing Diversification | Reduces concentration risk in Ukrainian mining corridors subject to geopolitical supply disruption. |
Research Approach
Operator-level perspectives from farm equipment procurement managers, agricultural cooperative fleet directors, OEM aftermarket service heads, and precision agriculture platform engineers anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation through SEC 10-K filings of listed equipment manufacturers, customs trade data on boron steel and alloy imports, EPA Tier 4 Final regulatory dockets, and EU F-Gas Regulation implementation guidance. Bottom-up demand modeling across implement categories triangulated against top-down macroeconomic agriculture investment indicators.
Scenario-bracketing around regulatory compliance timelines and commodity price volatility shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, application, end user archetype, and technology architecture. CAGRs derived from fitted growth curves incorporating precision agriculture adoption rates, fleet replacement cycle compression, and mechanization intensity indices for emerging markets. Industry-specific inputs encompassed GPS guidance system penetration data and hydraulic-to-electric actuator migration schedules.
Macroeconomic conditions sit as an overlay; deviation in agricultural commodity prices, interest rate environments affecting farm equipment financing, and currency volatility in Brazilian real and Indian rupee would shift the trajectory. Forecasts reflect documented assumptions on regulatory implementation timing and technology cost curves. Material shifts in EU F-Gas Regulation retrofit requirements or Indian BIS certification enforcement would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Machinery
South America Agricultural Machinery Market
Agricultural Machinery
Japan Agricultural Machinery Market
Agricultural Machinery
Agricultural Haying and Forage Machinery Market
Agricultural Machinery
Spain Agricultural Machinery Market
Agricultural Machinery
Hay Making Machinery Market
Agricultural Machinery
US Agriculture Drone Market
Agricultural Machinery
Garden and Orchard Tractors Market
Agricultural Machinery
United States Haying and Forage Machinery Market
Agricultural Machinery
Europe Agricultural Irrigation Machinery Market
Agricultural Machinery
Asia-Pacific Utility Tractor Market
Agricultural Machinery
Autonomous Farm Equipment Market
Agricultural Machinery
Rice Mill Machine Market
Agricultural Machinery
Africa Agricultural Tractor Market
Agricultural Machinery
Electric Tractors Market
Agricultural Machinery
Germany Agricultural Machinery Market
Agricultural Machinery
Agricultural Forestry Machinery Market