
 Algae-Based Animal Feed Market | 2026-2036
Algae-Based Animal Feed Market Size, Share, and Industry Trends Forecast 2026-2036
Algae-Based Animal Feed Market Insights
Buyer concentration in aquaculture feed is rebalancing as Norwegian salmon integrators consolidate procurement while smaller organic poultry and ruminant operations fragment across new regional cooperatives. Cargill leverages its integrated supply chain to control algae protein distribution into North American livestock channels. Corbion sustains technology leadership through specialized fermentation platforms for omega-3 algal oil. BioMar Group anchors Nordic aquaculture demand with captive formulation expertise in marine replacement diets.
Algae-based animal feed comprises processed microalgae and macroalgae biomass formulated into protein concentrates, whole cell meals, lipid extracts, and powdered supplements for nutritional enrichment across livestock and aquaculture systems. Production employs heterotrophic fermentation or photobioreactor cultivation followed by spray-drying or solvent extraction to preserve amino acid profiles and long-chain polyunsaturated fatty acids. Whole algae formulations dominate volume flows into aquaculture species diets where fishmeal displacement rates are highest. Algal oil captures concentrated margin pools in premium pet food and equine nutrition segments where omega-3 labeling commands price premiums. Protein concentrates compete most aggressively in poultry and swine rations where amino acid density determines formulation economics.
EFSA novel food registration requirements shape product entry pathways for European suppliers, while EU Green Deal protein transition targets mandate feed ingredient diversification timelines that algae producers must meet. The US FDA Center for Veterinary Medicine maintains ingredient definition authority over algae-derived feed additives, creating parallel compliance tracks for domestic and imported products. China's SAMR and GB standards govern algae feed safety thresholds for heavy metals and microcystins in the world's largest aquaculture production base. Stakeholders must monitor how novel protein qualification timelines in Brussels and Beijing synchronize with customer certification requirements.
Market Dynamics
The EU Green Deal protein transition targets are forcing feed formulators to accelerate marine ingredient substitution, reshaping supplier qualification timelines and procurement volumes across European aquaculture integrators.
Growth Catalysts
- EFSA Novel Food Registration Pathways:Streamlined approval frameworks for algae-derived ingredients are reducing market entry barriers for European suppliers targeting aquaculture feed channels.
- Salmon Producer Consolidation in Norway:Large-scale integrators are standardizing algae-based formulations across their captive feed operations, creating predictable offtake volumes.
- Heterotrophic Fermentation Platforms:Closed-system bioreactor technology is decoupling algae protein production from seasonal sunlight constraints, enabling year-round supply security.
Market Restraints
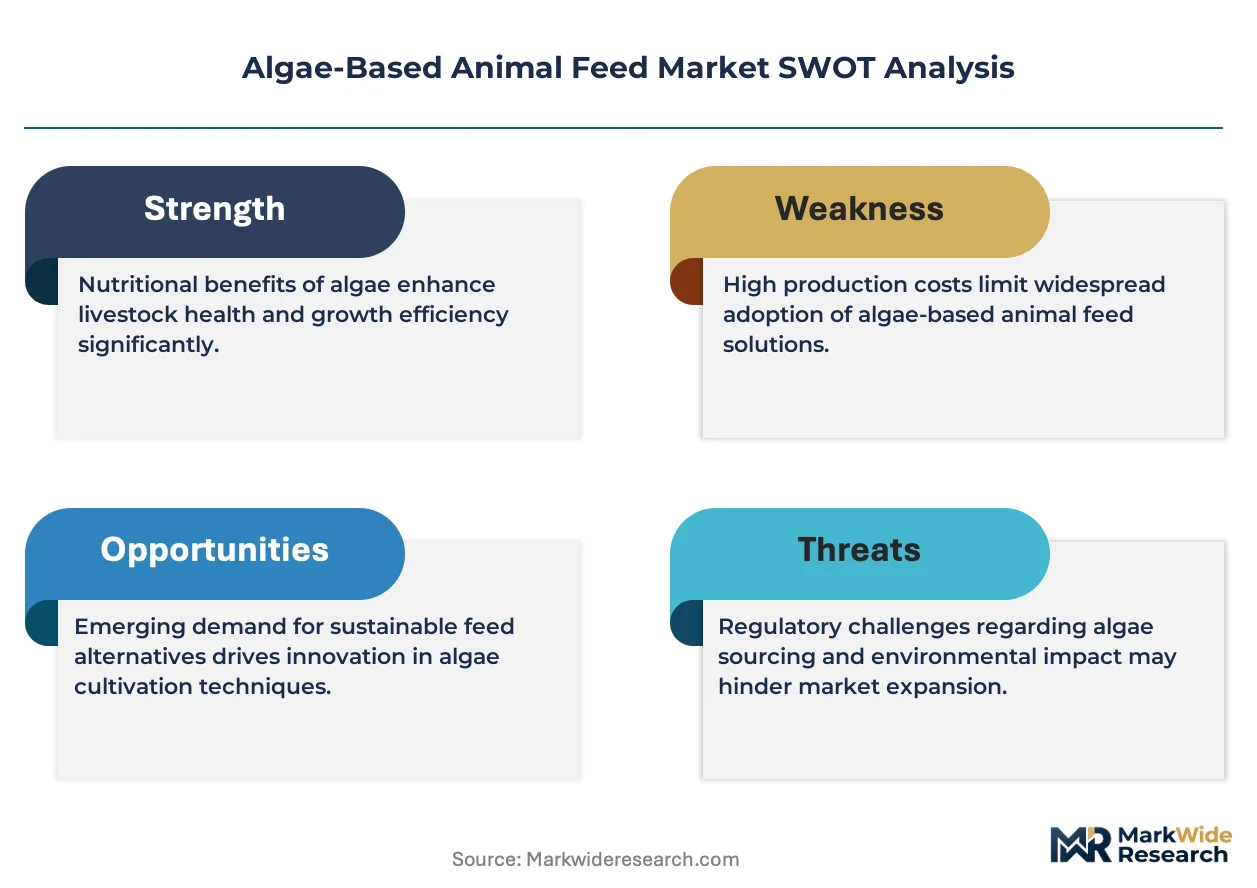
- Input Cost Volatility in Carbon Feedstocks:Glucose and glycerol price swings directly compress margins for fermentation-based algae producers operating at commercial scale.
- Photobioreactor Capex Intensity:Open-pond cultivation in Spain and Portugal faces land competition from solar PV installations, constraining expansion sites for low-cost biomass.
- Fishmeal Substitution Ceilings:Formulation limits on algal inclusion rates in certain marine species diets cap displacement potential regardless of price competitiveness.
Strategic Opportunities
- Organic Poultry Cooperatives in France:Fragmented regional buyer groups are consolidating procurement to access algae protein concentrates previously reserved for aquaculture volume contracts.
- US FDA Center for Veterinary Medicine Ingredient Definitions:Pending clarifications on algae-derived feed additive classifications could unlock domestic livestock channel access for imported products.
- CRISPR-Enhanced Strain Development:Convergence of gene editing with high-throughput screening is compressing strain optimization cycles for lipid-rich microalgae variants.
Industry Challenges
- Omega-3 Oxidation Stability Expertise:Formulators lack sufficient technical personnel to manage algal oil shelf-life protocols during feed pelleting thermal exposure.
- Dual Certification Timelines:Suppliers must simultaneously satisfy EU organic feed standards and ASC chain-of-custody requirements, extending qualification periods by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Algae-Based Animal Feed Market |
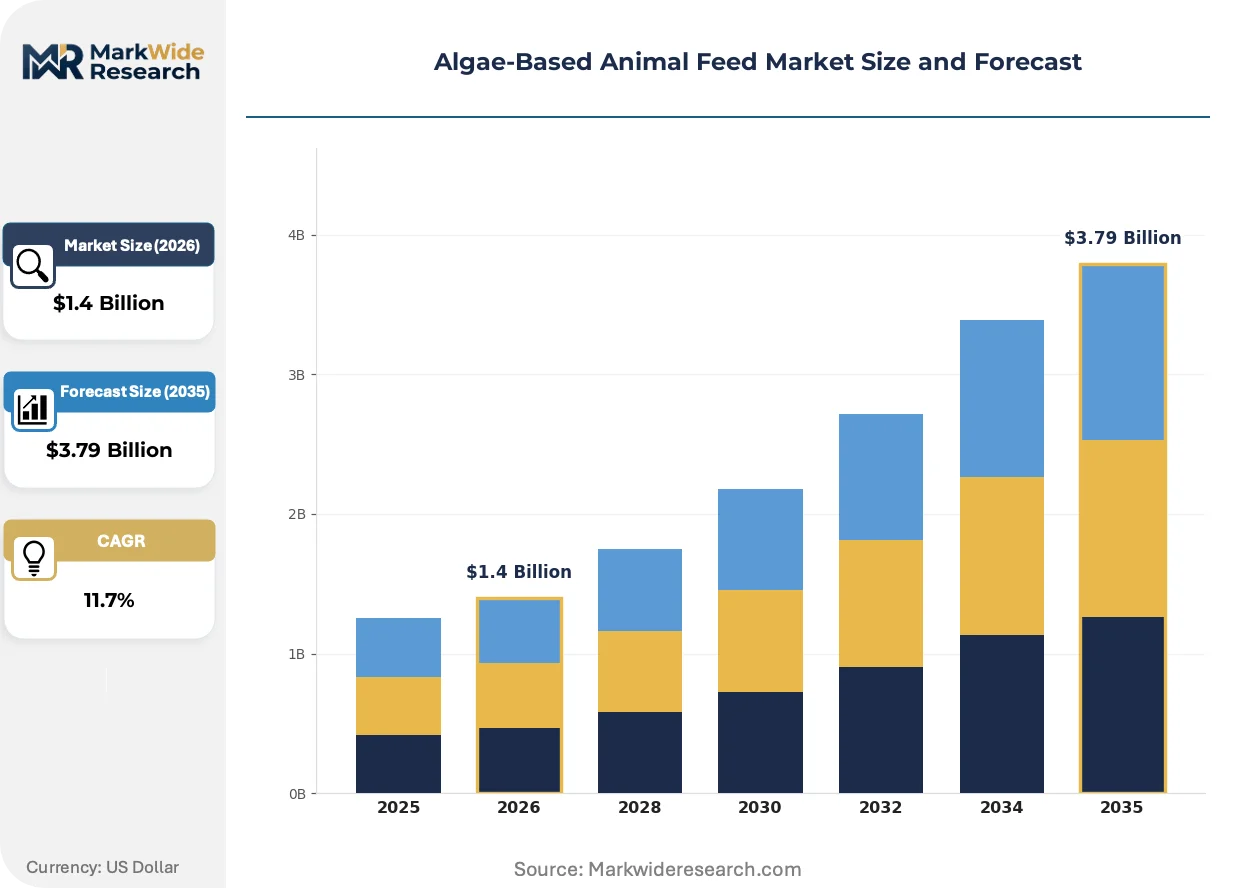
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $3.79 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Feed Type: Protein Concentrates, Whole Algae, Algal Meal, Algal Oil, Algal Powder Target Species: Ruminants, Poultry, Aquaculture, Swine, Equine Formulation Technology: Extrusion, Pelletizing, Liquid Suspension, Dry Blend, Microencapsulation End Use Industry: Livestock Farming, Fish Hatcheries, Pet Food Manufacturers, Organic Farms, Feed Distributors |
| Companies Covered | Cargill, Archer Daniels Midland, Alltech, Corbion, BioMar Group, DSM, Cellana, DIC Corporation, Algatech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Algae-Based Animal Feed Market Trends and Innovations
Technology convergence between synthetic biology and precision fermentation is compressing product development cycles, while regulatory clarity on novel protein classifications accelerates commercial deployment timelines.
Algal oil concentrates are expanding into premium pet food formulations as brands seek marine-origin omega-3 alternatives free from heavy metal contamination risks. North American pet food manufacturers are adopting these ingredients at pace, with specialty retailers now demanding third-party testing documentation. This technology shift is expanding into adjacent equine nutrition segments where coat quality claims command formulation premiums.
China's SAMR is tightening GB standard enforcement on microcystin thresholds for algae feed imports, raising compliance costs for exporters targeting the world's largest aquaculture production base. Domestic algae producers are investing in in-house HPLC testing capabilities to preempt inspection failures. This regulatory tightening most affects whole-cell algae meal shipments from Southeast Asian suppliers.
Buyer concentration among Norwegian salmon integrators is compressing supplier negotiation leverage and standardizing contract terms around volume-commitment clauses. Smaller algae producers are responding by forming supply cooperatives to aggregate biomass and meet minimum order thresholds. This behavioral shift is most visible in the Nordic region where three integrators control over sixty percent of formulated feed procurement.
Algae-Based Animal Feed Market Segmentation
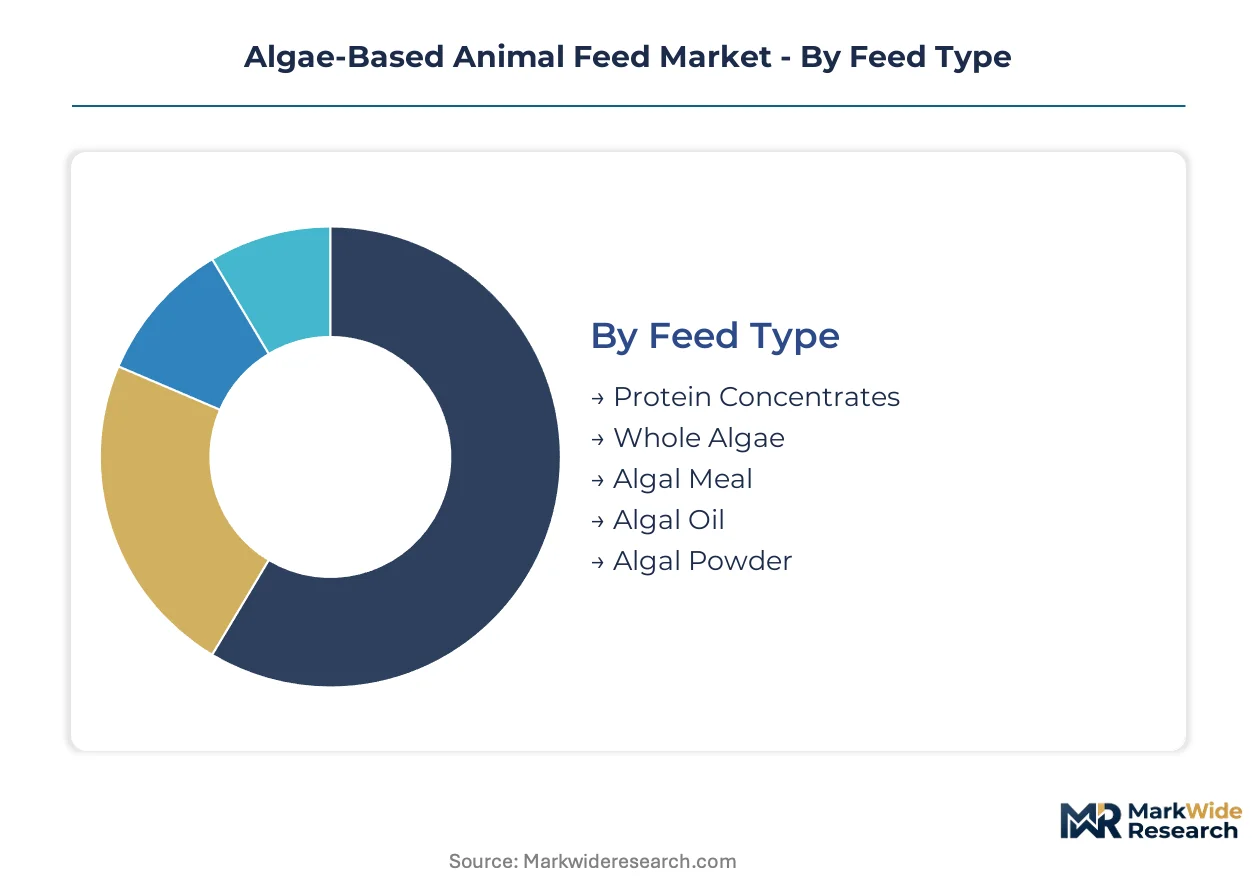
Algae-based animal feed segmentation reveals how formulation technology and species-specific nutritional requirements drive procurement decisions. Feed type selection determines margin capture, while target species concentration shapes regional production investments.
Feed Type:
Upgrade cycles from commodity fishmeal to functional algae ingredients are accelerating as marine substitution targets tighten across European and North American aquaculture.
- Protein Concentrates:Dehydrated biomass with protein content exceeding 50% by dry weight, processed through cell disruption and solvent extraction. Poultry integrators in France and Spain are scaling procurement as soybean price volatility disrupts formulation economics.
- Algal Oil:Refined lipid extracts rich in EPA and DHA omega-3 fatty acids, stabilized through antioxidant addition. Pet food manufacturers in the United States command premium pricing for heavy-metal-free marine alternatives, with third-party testing now standard contractual requirement.
- Whole Algae:Intact cell biomass delivered as wet paste or spray-dried meal for direct inclusion.
- Algal Meal:Ground dried biomass with standardized protein and ash content specifications.
- Algal Powder:Fine-milled particulate for specialized supplement applications and premix integration.
Whole algae sits at the top of the volume ranking, with algal oil climbing the fastest as premium pet food and equine nutrition channels expand.
Target Species:
Customer type concentration varies dramatically by species, with aquaculture integrators demanding multi-year supply contracts while organic poultry cooperatives purchase through spot aggregators.
- Aquaculture:Salmon, trout, and shrimp production systems requiring marine-origin lipid and protein inputs. Norwegian integrators operate the most intensive substitution programs, with captive feed mills standardizing algae inclusion across all marine diets.
- Poultry:Broiler and layer operations seeking alternative protein to reduce soybean dependency. Organic certification requirements in France and Germany are driving regional cooperative formation to access volume pricing.
- Ruminants:Cattle and dairy operations utilizing algae for methane reduction and omega-3 enriched milk output.
- Swine:Pig production systems incorporating algae protein into grower and finisher rations.
- Equine:Performance and breeding operations targeting coat quality and joint health through omega-3 supplementation.
Aquaculture dominates procurement volume, though poultry is expanding most quickly as organic feed certification timelines synchronize with algae supplier qualification.
Formulation Technology:
Margin structure across technologies separates high-capex extrusion specialists from flexible dry blend operators serving fragmented livestock channels.
- Extrusion:High-temperature high-pressure processing producing floating and sinking feeds with precise density control. Aquaculture feed mills in Norway and Scotland deploy continuous twin-screw systems optimized for algae oil thermal stability.
- Microencapsulation:Lipid core-shell structures protecting omega-3 from oxidation through spray-dried or complex coacervation methods. Pet food manufacturers in the United States specify encapsulation for premium shelf-life claims.
- Pelletizing:Compression forming of conditioned feed mash through ring or flat die presses.
- Liquid Suspension:Aqueous delivery systems for hatchery and early-life stage feeding.
- Dry Blend:Mechanical mixing of powdered ingredients for on-farm supplementation.
Extrusion commands the largest installed base, while microencapsulation shows the steepest expansion trajectory as oxidation-sensitive premium formulations proliferate.
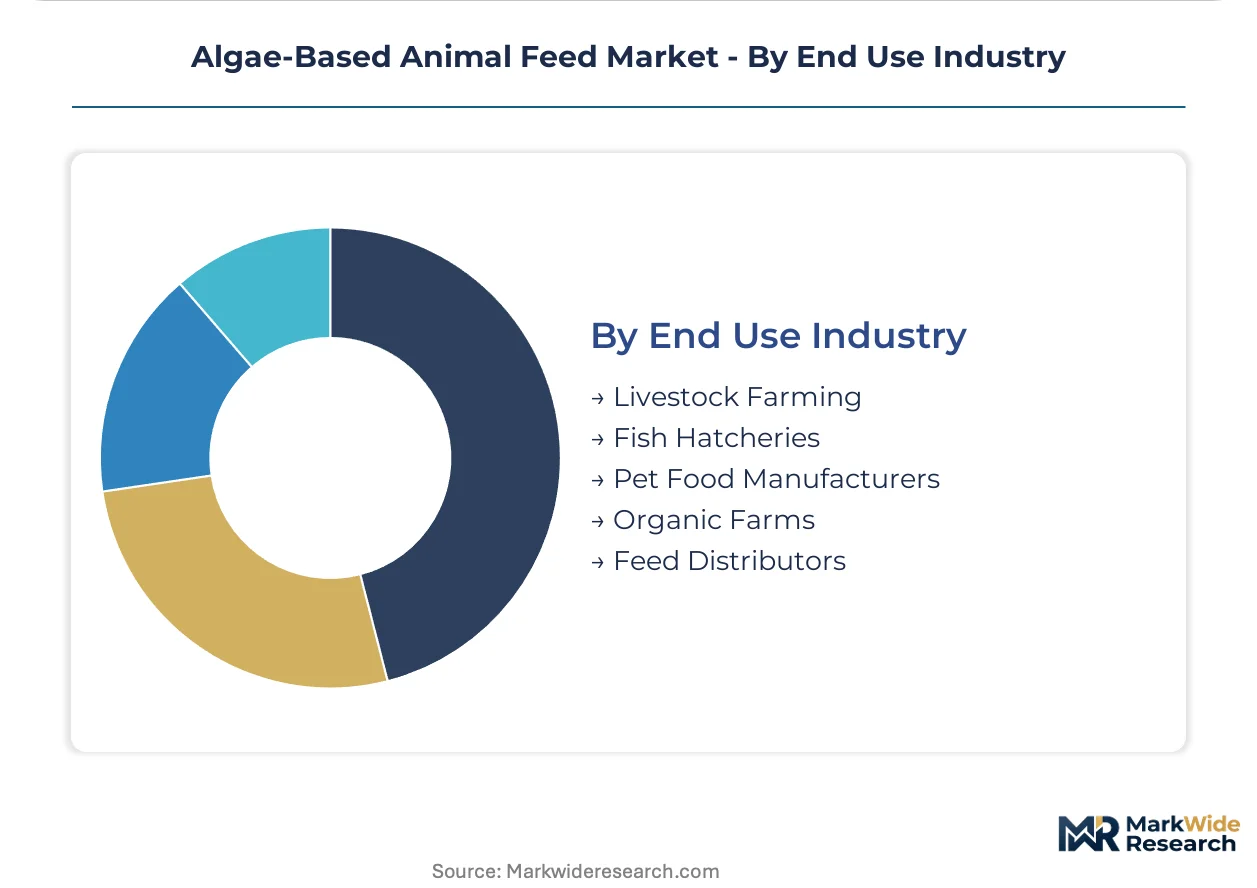
End Use Industry:
Supply concentration by channel tier separates vertically integrated aquaculture operators from distributor-mediated livestock access.
- Livestock Farming:Direct procurement by cattle, poultry, and swine operations for on-farm feeding. Organic farms in France are consolidating through regional cooperatives to meet minimum order thresholds previously reserved for aquaculture volume.
- Pet Food Manufacturers:Branded and private label producers targeting premium and super-premium segments. North American specialty retailers now mandate third-party heavy metal and microcystin testing documentation.
- Fish Hatcheries:Early-stage aquatic species production requiring specialized live feed and formulated microdiets.
- Organic Farms:Certified operations meeting EU organic feed standards and national equivalency requirements.
- Feed Distributors:Regional and national wholesalers aggregating demand across fragmented livestock operations.
Livestock farming represents the deepest volume pool, with pet food manufacturers gaining share fastest as premiumization accelerates omega-3 ingredient substitution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Norway operates the most intensive algae feed substitution programs globally, while the United States builds regulatory clarity for domestic livestock channels. China enforces stricter import standards, and France consolidates organic poultry procurement. Germany anchors EU protein transition compliance.
Norway
Salmon integrators drive captive feed mill standardization of algae inclusion across all marine diets. The country's aquaculture regulator mandates marine ingredient reduction timelines under national sustainability frameworks. Bergen and Trondheim host formulation R&D clusters where three integrators control over sixty percent of procurement volume.
United States
Pet food manufacturers adopt algal oil concentrates for premium omega-3 positioning free from heavy metal contamination risks. The FDA Center for Veterinary Medicine maintains ingredient definition authority over algae-derived feed additives. Specialty retailers in the Pacific Northwest and Northeast corridors now mandate third-party testing documentation as standard contractual requirement.
China
The world's largest aquaculture production base tightens GB standard enforcement on microcystin thresholds for algae feed imports. SAMR inspection protocols raise compliance costs for exporters targeting domestic hatcheries. Shandong and Jiangsu provinces invest in in-house HPLC testing capabilities to preempt inspection failures at port of entry.
France
Organic poultry cooperatives consolidate fragmented regional procurement to access algae protein concentrates previously reserved for aquaculture volume contracts. EU organic feed standards and national equivalency requirements synchronize supplier qualification timelines. Brittany and Pays de la Loire clusters form supply aggregators to meet minimum order thresholds.
Germany
Livestock operations incorporate algae protein into grower and finisher rations to reduce soybean dependency amid price volatility. The EU Green Deal protein transition targets mandate feed ingredient diversification timelines that algae producers must meet. Bavaria and Lower Saxony house integrated compound feed mills testing heterotrophic fermentation platforms for year-round supply security.
Algae-Based Animal Feed Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across distinct margin tiers. The vendor base separates into three structural camps: integrated agribusiness conglomerates controlling distribution infrastructure, specialized fermentation technology providers capturing premium lipid segments, and regional aquaculture formulators anchoring captive demand. Consolidation pressure intensifies as Norwegian salmon integrators standardize procurement terms around volume-commitment clauses. Strategic moves concentrate on backward integration into fermentation capacity and geographic expansion through distributor partnerships.
Among integrated agribusiness conglomerates, Cargill and Archer Daniels Midland occupy positions spanning North American livestock channels through controlled distribution infrastructure. Corbion exemplifies the specialized fermentation archetype with technology leadership in omega-3 algal oil platforms. BioMar Group anchors Nordic aquaculture demand through captive formulation expertise in marine replacement diets.
| Leading Market Players |
|---|
| Cargill |
| Archer Daniels Midland |
| Alltech |
| Corbion |
| BioMar Group |
| DSM |
| Cellana |
| DIC Corporation |
| Algatech |
| Others |
Pricing and Supply Chain Analysis
Private-equity-rolled-up fermentation specialists in the Nordic region and California have consolidated production assets, tightening supply discipline and anchoring contract pricing to volume-commitment clauses that favor multi-year offtake agreements over spot market exposure.
Pricing Analysis
Capacity additions in Portugal and Spain are reshaping price floors for open-pond whole algae meal, compressing margins for incumbent photobioreactor operators. Contract-based long-term offtake dominates aquaculture procurement, with price differentiation resting on ASC chain-of-custody certification and EU organic feed standards. Pricing pressure stems from glucose feedstock volatility in heterotrophic fermentation. Poultry cooperatives in France exhibit highest price sensitivity, while Norwegian salmon integrators prioritize supply security over unit cost.
Supply Chain Analysis
EFSA novel food qualification timelines and ASC certification requirements gate supplier entry, extending onboarding periods. Production concentrates in Norway, the United States, and China. Raw material flows draw from agricultural glucose streams, glycerol byproducts, and marine lipid inputs. Single-source vulnerability runs through heterotrophic fermentation carbon feedstock suppliers. Distribution runs through captive feed mill networks in aquaculture and regional cooperatives in organic livestock channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The algae-based animal feed market functions as a stable compounder, with EU Green Deal protein transition mandates providing predictable demand visibility across the analysis window.
For Market Incumbents: To counter buyer consolidation among Norwegian salmon integrators, secure backward integration into heterotrophic fermentation capacity in Germany or the United States. Prioritize dual certification investment in EFSA novel food pathways and ASC chain-of-custody to extend contract renewal rates. For New Entrants and Emerging Players: Enter via organic poultry cooperatives in France and Spain, where fragmented procurement creates white-space access previously reserved for aquaculture volume contracts. Target microencapsulation technology partnerships with North American pet food manufacturers seeking heavy-metal-free omega-3 alternatives. For Investors and Strategic Acquirers: Valuations sit cheapest among regional aquaculture formulators lacking captive fermentation assets. Five-to-ten year viability hinges on regulatory synchronization between Brussels and Beijing. Watch EFSA approval velocity for algae protein concentrates as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation Capacity | Cargill and Corbion have secured year-round supply security independent of seasonal sunlight constraints. |
| Dual Certification Investment | Suppliers meeting both EFSA novel food and ASC standards compress qualification timelines for Norwegian integrators. |
| Regional Cooperative Formation | French organic poultry clusters aggregate procurement to access volume pricing previously reserved for aquaculture. |
| Microencapsulation Technology Licensing | Pet food manufacturers in the United States specify encapsulated algal oil for premium shelf-life claims. |
| HPLC Testing Capability Buildout | Chinese domestic producers preempt SAMR inspection failures at port of entry under tightened GB standards. |
Research Methodology
Coverage spans Norway, the United States, China, France, and Germany, with primary inputs from each market. The research combines interviews with aquaculture feed formulators, EFSA regulatory affairs specialists, organic certification officers, and heterotrophic fermentation plant managers with secondary validation from customs trade data, SEC filings, EFSA novel food registers, and GB standard enforcement bulletins. Bottom-up volume modeling and top-down value triangulation anchor the analytical framework.
Granularity extends to feed type, target species, and formulation technology dimensions across the projection horizon. The analytical framework models protein concentrate, algal oil, and whole algae segments separately, with CAGRs derived from trajectory fitting to historical substitution rates and regulatory compliance timelines. Industry-specific inputs include marine ingredient displacement curves in Norwegian salmon diets and EU organic feed certification velocity.
Inputs from EFSA approval databases and SAMR inspection records were available through the study window; gaps in real-time fermentation capacity utilization data introduce uncertainty bands around supply-side forecasts. A model refresh is warranted upon material change in EU Green Deal protein transition enforcement timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
LAMEA Artificial Humus Market
Agriculture and Agri Products
Global Medicated Feed Market
Agriculture and Agri Products
Consumer Floriculture Market
Agriculture and Agri Products
Asia-Pacific Artificial Humus Market
Agriculture and Agri Products
Fermented Soybean Meal Protein for Animal Feed Market
Agriculture and Agri Products
France Animal Protein Market
Agriculture and Agri Products
Brazil Rice Market
Agriculture and Agri Products
Global Ruminant Feed Market
Agriculture and Agri Products
Global Palm Oil Market
Agriculture and Agri Products
Elaeis Guineensis (Palm) Fruit Extract Market
Agriculture and Agri Products
Live Goods Market
Agriculture and Agri Products
Forage Feed Market
Agriculture and Agri Products
Sudan Alfalfa Market
Agriculture and Agri Products
Saudi Arabia Alfalfa Market
Agriculture and Agri Products
Seaweed Algae Market
Agriculture and Agri Products
Organic Hemp Market