
 Canada Ornamental Horticulture Market | 2026-2036
Canada Ornamental Horticulture Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Ornamental Horticulture Market Outlook
Nursery sales channels are reshaping how growers reach end buyers across Canadian provinces. Monrovia leverages its coast-to-coast distribution network to supply independent retailers with finished container stock. Ball Horticultural Company anchors its position through proprietary genetics and trialing programs tailored to Canadian hardiness zones. Sheridan Nurseries competes by operating one of the largest production footprints in Ontario, giving it volume flexibility during seasonal peaks.
Ornamental horticulture encompasses the cultivation, breeding, and sale of decorative plants including flowers, shrubs, trees, and ground covers, typically propagated through vegetative cutting, tissue culture, or grafting techniques for aesthetic and environmental enhancement in managed landscapes. The sector serves residential property owners, commercial developers, and municipal planners seeking immediate visual impact, erosion control, and pollinator habitat. Flowers and shrubs together command the dominant share of product value, with shrubs capturing stronger margin pools due to longer production cycles and lower per-unit shipping losses. Trees represent a mature, slower-turn category where demand concentrates in urban canopy replacement programs, while ground covers are gaining traction among landscaping companies managing steep grades and low-maintenance commercial installations.
Health Canada PMRA regulates pesticide registrations for nursery stock, directly influencing which chemistries growers can apply and how integrated pest management protocols evolve across propagation facilities. The Canadian Food Inspection Agency administers phytosanitary certification requirements that govern cross-border movement of live plants, shaping sourcing strategies for imported liners and finished material. Provincial environmental ministries in British Columbia and Ontario enforce water-taking permits that constrain irrigation expansion during drought declarations. Stakeholders must monitor how municipal green infrastructure mandates and evolving pollinator-protection bylaws redirect specification lists toward native species and reduced-input cultivars.
Market Dynamics
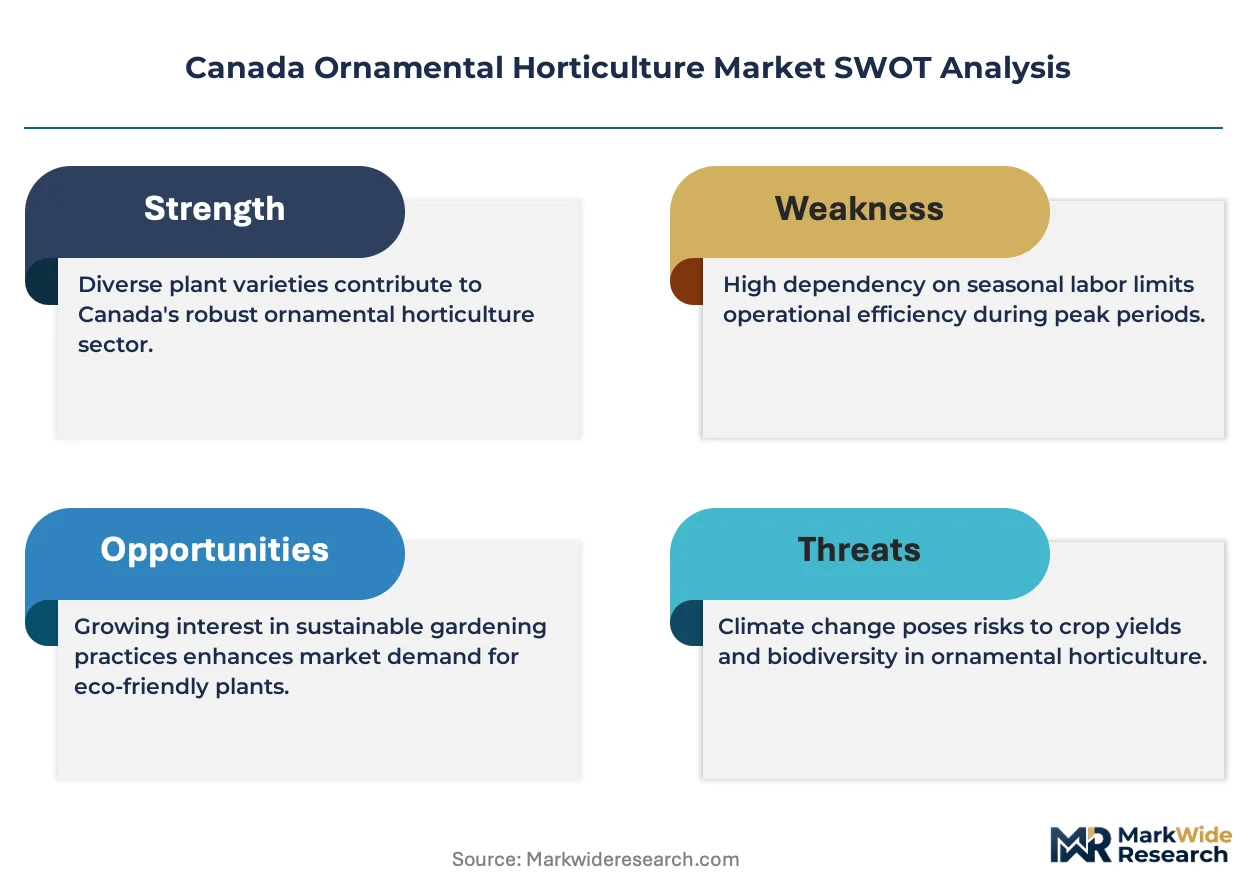
Canadian municipal water-use restrictions are forcing nursery operators to retool propagation schedules around drought-tolerant genetics, while university breeding programs accelerate cultivar release timelines to match tightening landscape codes across Ontario and British Columbia.
Growth Catalysts
- Native Plant Procurement Mandates:Municipal green infrastructure bylaws in Vancouver and Toronto now require minimum native species ratios in public landscaping contracts, redirecting commercial nursery output toward locally adapted stock.
- PMRA Reduced-Risk Pesticide Pathway:Health Canada's expedited registration track for biological pest control products is accelerating integrated pest management adoption across propagation facilities.
- Urban Canopy Replacement Programs:Ontario's municipal tree-planting targets are sustaining demand for caliper-sized shade trees despite residential construction volatility.
Market Restraints
- Cross-Border Phytosanitary Friction:CFIA certification delays for imported liners from the United States are extending production lead times for growers dependent on foreign propagation material.
- Peak Season Labor Compression:The Temporary Foreign Worker Program's housing and wage requirements are constraining available harvest labor during May-June container shipping windows.
- Input Cost Volatility:Peat moss extraction moratoria in New Brunswick are pressuring substrate formulations and forcing growers toward coconut coir alternatives at higher unit cost.
Strategic Opportunities
- Pollinator-Protection Bylaw Tailwinds:Quebec's restrictions on neonicotinoid-treated nursery stock are creating first-mover advantage for growers with verified clean propagation protocols.
- Direct-to-Landscaper Digital Channels:Online procurement platforms are disintermediating traditional garden center distribution for commercial installation contractors in Alberta.
- Green Roof Specification Growth:Toronto's mandatory green roof bylaw and Vancouver's voluntary density bonusing are expanding demand for lightweight, shallow-root ground cover cultivars.
Industry Challenges
- CFIA Certification Timeline Compression:Phytosanitary documentation requirements for interprovincial movement are creating bottlenecks during spring shipping peaks when inspection staff capacity is constrained.
- Specialized Propagation Skill Scarcity:Tissue culture and grafting technician training programs at Canadian agricultural colleges are not graduating sufficient candidates to replace retiring master propagators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Ornamental Horticulture Market |
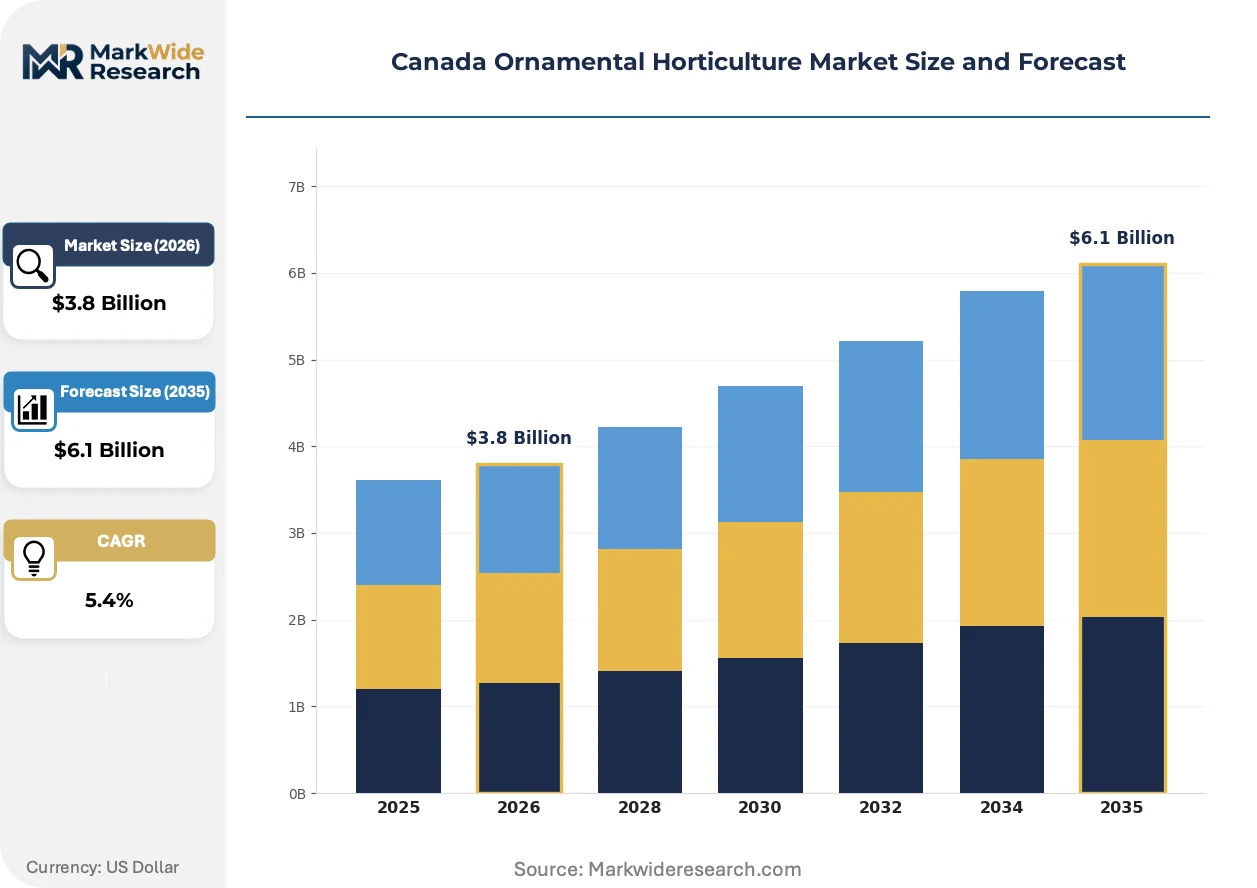
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.1 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flowers, Shrubs, Trees, Ground Covers End User: Retailers, Landscaping Companies, Garden Centers, Distributors Distribution Channel: Online Sales, Wholesale, Direct Sales, Nursery Sales Application: Residential, Commercial, Public Spaces, Greenhouses |
| Companies Covered | Monrovia, Ball Horticultural Company, Sheridan Nurseries, Beekenkamp, Syngenta Flowers, Pioneer Flower Farms Ltd., Dümmen Orange, Selecta One, Willowbrook Nurseries Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Ornamental Horticulture Market Strategic Shifts
Digital propagation management and climate-adaptive breeding are compressing traditional nursery production cycles while regulatory pressure on chemical inputs accelerates biological control integration across Canadian growing regions.
Sensor networks and automated irrigation systems are virtualizing moisture monitoring across large container yards. Ontario growers operating multi-site footprints are adopting cloud-based soil moisture telemetry to consolidate irrigation decisions. This infrastructure is virtualizing the role of field scouts, compressing labor allocation toward propagation and away from routine monitoring.
Health Canada PMRA's cumulative risk assessment framework for pollinator-exposed pesticides is narrowing the approved chemistry list for nursery stock. The regulatory revision is forcing growers to revalidate entire pest management protocols before the 2026 growing season. British Columbia's berry nursery sector, which shares pollinator pressure with ornamental producers, is experiencing the most acute reformulation urgency.
Landscape architects are bundling plant procurement with multi-year establishment warranties, transferring survival risk from property owners back to installation contractors. Commercial developers in Calgary and Edmonton are accepting these terms, prioritizing single-source accountability over lowest-bid plant supply. Alberta's design-build firms are responding by deepening relationships with specific nursery partners capable of backing five-year performance guarantees.
Canada Ornamental Horticulture Market Segmentation
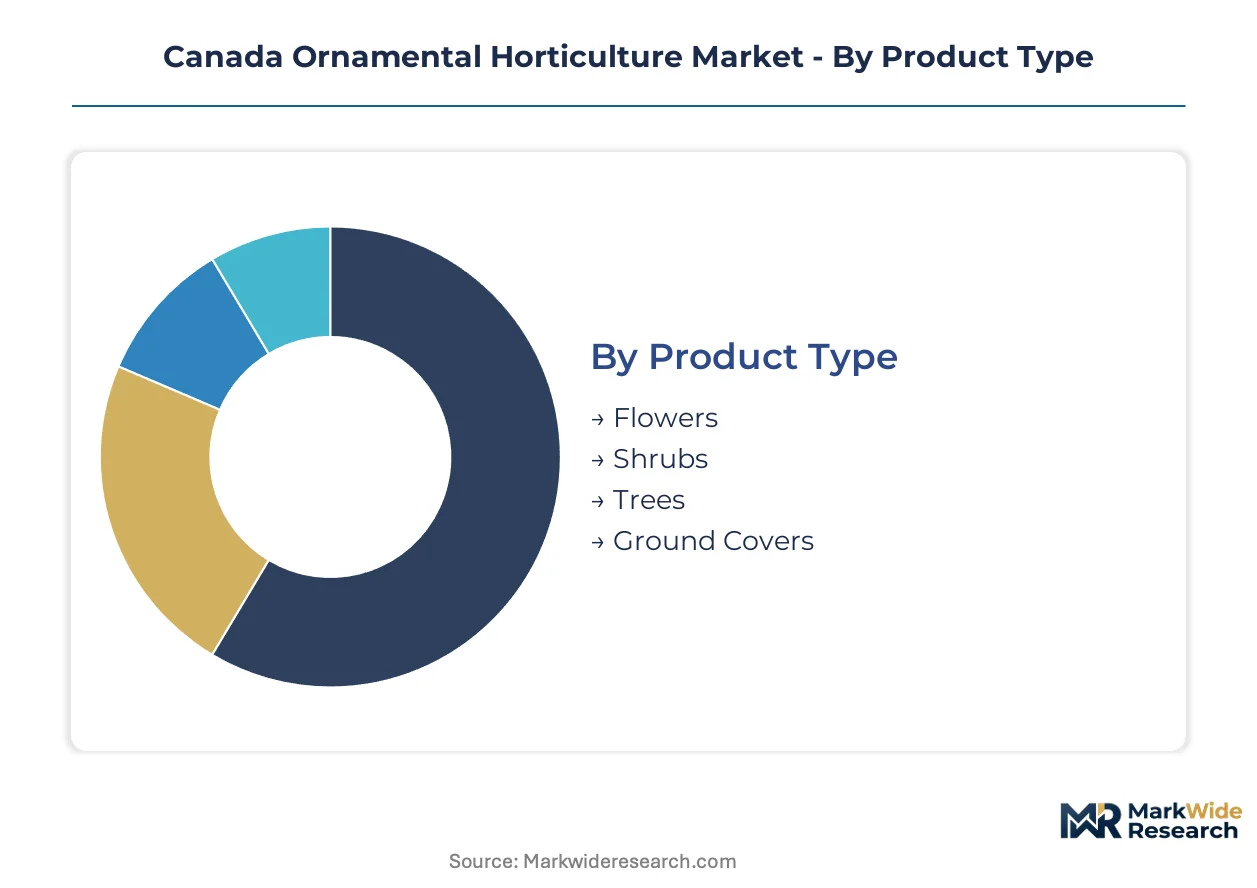
Segmentation in Canadian ornamental horticulture exposes how procurement patterns diverge across buyer sophistication levels. Municipal water restrictions and native plant mandates are compressing demand toward drought-tolerant cultivars, while digital channels reshape how commercial landscapers source material.
Product Type:
After-sales service intensity varies sharply across plant categories, with woody perennials demanding multi-year establishment support that herbaceous annuals rarely require.
- Flowers:Annual and perennial flowering plants deliver immediate visual impact through seasonal color rotations. Demand concentrates in Ontario garden centers serving residential DIY renovators, constrained by compressed spring selling windows and labor-intensive deadheading requirements. By volume, flowers lead. By growth pace, ground covers are ahead.
- Shrubs:Woody perennials with multi-year lifecycles command premium positioning through landscape architect specifications. British Columbia municipalities specify native shrub ratios in erosion-control contracts, tightening procurement toward locally propagated stock with verified provenance.
- Trees:Caliper-sized shade specimens anchor urban canopy replacement programs with extended production cycles and heavy freight logistics.
- Ground Covers:Low-spreading cultivars for slope stabilization and green roof assemblies are expanding most quickly among Calgary commercial developers seeking density bonusing credits.
Shrubs capture stronger margin pools due to longer production cycles, while flowers turn inventory fastest.
End User:
Buyer sophistication tiers separate price-sensitive mass retailers from specification-driven commercial contractors with technical staff capable of cultivar performance evaluation.
- Retailers:Independent garden centers and mass merchandisers move finished container stock to residential consumers. Alberta big-box chains are consolidating procurement through centralized buying offices, pressuring nursery margins on volume contracts.
- Landscaping Companies:Commercial installation contractors manage multi-year establishment warranties and specification compliance. Toronto-area firms are deepening direct nursery relationships to bypass distributor markups on large-scale municipal contracts.
- Garden Centers:Specialty retailers with trained horticultural staff command premium positioning through cultivar knowledge and localized growing advice.
- Distributors:Regional wholesalers aggregate liner stock and finished material across multiple propagation sources for fragmented retail networks.
Landscaping companies are gaining procurement leverage fastest as warranty bundling concentrates volume with fewer nursery partners.
Distribution Channel:
Channel economics hinge on freight density and perishability, with live plant material penalizing distant sourcing through shipping stress and moisture loss.
- Online Sales:Digital procurement platforms connect commercial buyers with nursery inventory systems for specification matching. Alberta landscaping contractors are adopting these channels for off-season pre-booking of caliper-sized trees.
- Wholesale:Volume aggregation through regional distributors serves fragmented retail networks with mixed-truck logistics. Ontario wholesale yards near Highway 401 corridors minimize stem time for perishable spring shipments.
- Direct Sales:Nursery-to-contractor relationships eliminate intermediary margins on large commercial projects with recurring annual volumes.
- Nursery Sales:On-site retail at propagation facilities captures consumer traffic through destination garden center experiences with production transparency.
Direct sales are climbing the fastest among commercial contractors, while wholesale retains volume dominance in fragmented retail supply.
Application:
Application segments separate cyclical residential renovation demand from institutional procurement with multi-year capital planning horizons.
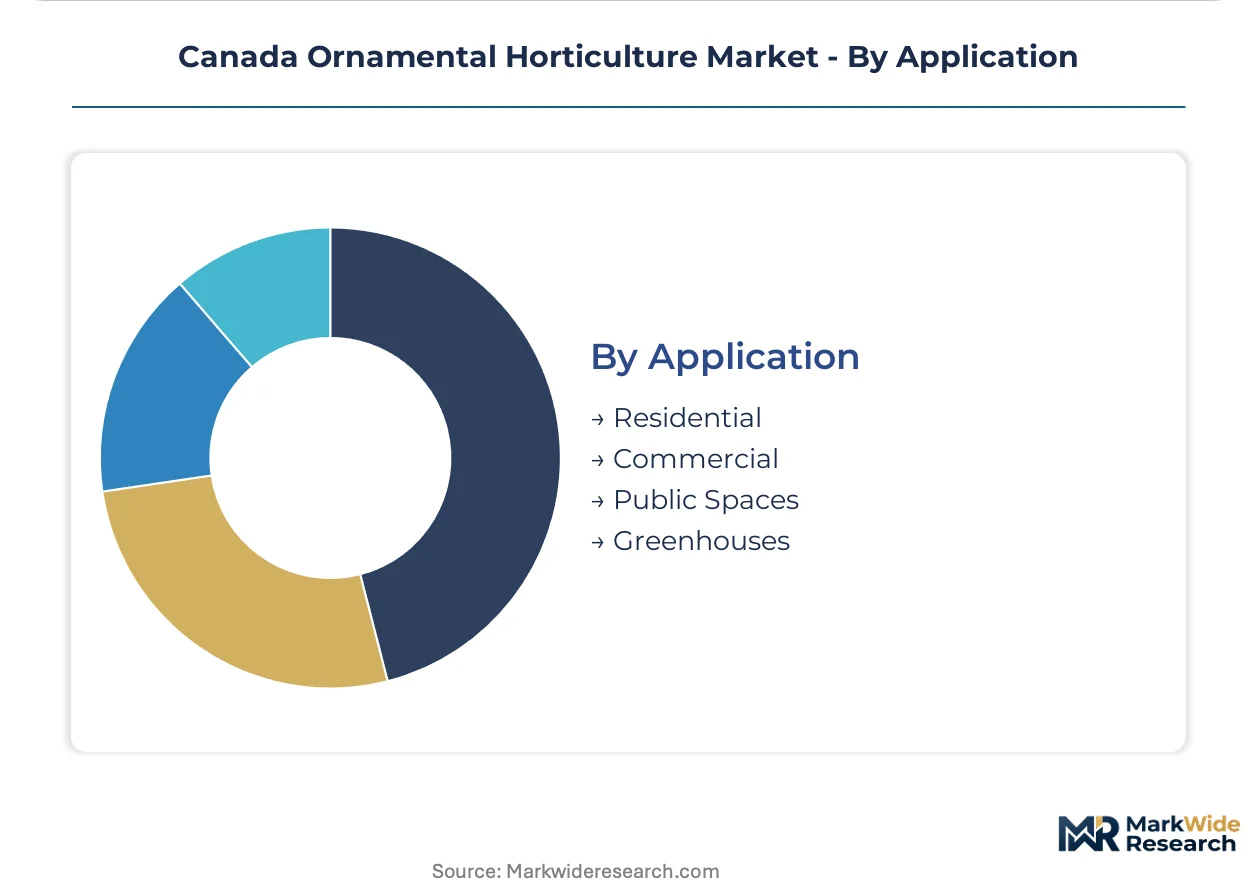
- Residential:Homeowner-driven projects exhibit weather-dependent seasonality with compressed spring purchasing windows. Vancouver's density constraints are shifting demand toward balcony-suitable container cultivars and vertical garden systems.
- Commercial:Corporate campuses and retail developments prioritize immediate visual impact with establishment warranties transferring survival risk to installers. Calgary developers are accepting five-year performance guarantees in exchange for single-source accountability.
- Public Spaces:Municipal parks and streetscape programs operate through competitive bidding with native species mandates and water-use restrictions. Toronto's green infrastructure bylaws specify minimum native ratios, redirecting nursery output toward locally adapted stock.
- Greenhouses:Controlled-environment production facilities supply out-of-season material and propagation services for contract growers.
Commercial applications are gaining share fastest as warranty bundling consolidates procurement, while residential retains absolute volume leadership.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ontario growers command premium pricing through proximity to Toronto's municipal procurement, while Prairie operators absorb freight penalties to reach Alberta's landscaping contractors. Quebec's neonicotinoid restrictions have created regulatory arbitrage that favors propagation facilities with verified clean-stock protocols.
Ontario
Toronto's green infrastructure bylaws mandate minimum native species ratios in public contracts, redirecting nursery output toward locally adapted stock. Health Canada PMRA regulates pesticide registrations that constrain chemistries available to propagation facilities near the Niagara fruit belt. The Golden Horseshoe corridor concentrates container production capacity, with growers retooling schedules around drought-tolerant university breeding releases.
British Columbia
Vancouver's density bonusing and mandatory green roof specifications expand demand for lightweight ground cover cultivars. Provincial environmental ministry water-taking permits constrain irrigation expansion during drought declarations, forcing operators toward moisture-monitoring sensor networks. The Fraser Valley hosts the province's largest propagation clusters, where berry nursery operations share pollinator pressure with ornamental producers.
Alberta
Calgary and Edmonton developers accept five-year plant establishment warranties, prioritizing single-source accountability over lowest-bid supply. Municipal tree-planting targets sustain demand for caliper-sized shade specimens despite residential construction volatility. Design-build firms in the Calgary-Edmonton corridor deepen direct nursery relationships to back performance guarantees.
Quebec
Neonicotinoid-treated nursery stock restrictions create first-mover advantage for growers with verified clean propagation protocols. Provincial environmental regulations on pollinator protection redirect specification lists toward reduced-input cultivars. Montreal-area garden centers serve as distribution nodes for pollinator-safe material moving into Ontario and Atlantic markets.
Canada Ornamental Horticulture Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream supplying genetics and propagation infrastructure. The Canadian ornamental horticulture market presents a bifurcated structure where coast-to-coast distribution networks compete against regional production specialists with volume flexibility. Two archetypes dominate: proprietary genetics holders with trialing programs calibrated to Canadian hardiness zones, and scale-driven operators leveraging multi-site footprints for seasonal peak management. Competitive dynamics center on direct-to-landscaper digital channel expansion and backward integration into captive liner production.
Within the genetics and distribution tier, Monrovia and Ball Horticultural Company exemplify contrasting approaches to market access. Monrovia occupies a position as a platform integrator with established independent retail networks, while Ball Horticultural Company anchors the proprietary genetics segment through cultivar development. Sheridan Nurseries represents the regional scale archetype, with production concentration in Ontario delivering volume responsiveness during compressed spring shipping windows.
| Leading Market Players |
|---|
| Monrovia |
| Ball Horticultural Company |
| Sheridan Nurseries |
| Beekenkamp |
| Syngenta Flowers |
| Pioneer Flower Farms Ltd. |
| Dümmen Orange |
| Selecta One |
| Willowbrook Nurseries Inc. |
| Others |
Value Chain & Pricing Dynamics
CFIA phytosanitary certification delays for imported liners from the United States determine both the premium spread for domestic propagation material and the geographic shape of Canadian nursery supply chains. This regulatory chokepoint forces Ontario and British Columbia growers toward captive liner production or premium-priced verified clean-stock protocols.
Pricing Analysis
Configured-to-order pricing for specification-grade native cultivars commands substantial premiums over standard container stock. Three-tier pricing structure across premium, standard, and economy levels separates architect-specified provenance-verified material from volume garden center lines. Pricing pressure stems from Alberta big-box chains consolidating procurement through centralized buying offices. Residential DIY buyers exhibit highest price sensitivity, while commercial developers accepting five-year establishment warranties show lowest.
Supply Chain Analysis
Contract propagation concentration rests with Ontario's Golden Horseshoe corridor and British Columbia's Fraser Valley clusters. Geographic supply concentration draws from domestic university breeding programs, Dutch genetics licensors, and Pacific Northwest liner suppliers. Raw material dependencies center on peat moss substrates, coconut coir alternatives, and biological pest control inputs. Single-source vulnerability runs through New Brunswick peat extraction moratoria forcing formulation shifts. Distribution runs through Highway 401 wholesale yards, direct-to-landscaper digital platforms, and independent garden center networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment around CFIA certification and PMRA pesticide pathways creates durable barriers to displacement.
For Market Incumbents: Build switching-cost moats through five-year establishment warranty partnerships with Calgary and Edmonton design-build firms. Deepen backward integration into captive tissue culture capacity to offset CFIA import delays. Expand drought-tolerant cultivar trialing with Ontario and British Columbia university breeding programs before PMRA protocol revalidation deadlines compress competitor response windows. For New Entrants and Emerging Players: Pursue white-space positioning in Quebec's neonicotinoid-restricted pollinator-safe propagation segment where verified clean-stock protocols command first-mover premiums. Target Alberta's direct-to-landscaper digital procurement channels where incumbent garden center relationships remain underdeveloped. Anchor go-to-market strategy through green roof specification expertise for Toronto density bonusing and Vancouver voluntary compliance projects. For Investors and Strategic Acquirers: Regional scale specialists with multi-site Ontario production footprints represent the priority acquisition archetype for volume flexibility during compressed spring shipping peaks. Long-term viability centers on irrigation water rights security and municipal native procurement mandate alignment. Monitor PMRA cumulative risk assessment implementation pace as inflection indicator for biological control infrastructure valuation.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Liner Production Expansion | Reduces CFIA certification dependency for Ontario propagation facilities. |
| University Breeding Program Partnership | Accelerates drought-tolerant cultivar release timelines for British Columbia water restrictions. |
| Direct-to-Landscaper Digital Platform Launch | Disintermediates garden center markups for Alberta commercial installation contractors. |
| Pollinator-Safe Propagation Certification | Captures Quebec regulatory arbitrage for neonicotinoid-restricted nursery stock. |
| Green Roof Specification Development | Aligns ground cover cultivar portfolios with Toronto mandatory and Vancouver voluntary bylaws. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through primary interviews with nursery propagation managers, landscape architect specification writers, municipal procurement officers, and garden center category buyers. Secondary validation drew from Health Canada PMRA registration databases, CFIA phytosanitary certification records, provincial environmental ministry water-taking permits, and municipal green infrastructure bylaws. Bottom-up volume modeling triangulated against top-down expenditure estimates across product type, end user, distribution channel, and application segments.
Calibration anchored historical shipment patterns to university breeding program release schedules and municipal contract award databases. Segmentation dimensions modeled included product type, end user sophistication tier, distribution channel economics, and application cyclicality across residential, commercial, and public space procurement. CAGRs were derived from regression analysis of provincial nursery sales against construction permit flows and municipal capital budget trajectories. Forecast inputs incorporated drought declaration frequency and pollinator-protection bylaw adoption curves.
Sensitivities concentrate around CFIA inspection staff capacity during spring shipping peaks, Temporary Foreign Worker Program housing requirement changes, and peat moss extraction moratoria expansion. Forecasts embed assumptions regarding municipal native species mandate enforcement consistency and PMRA reduced-risk pesticide pathway throughput. Quarterly review of provincial water restriction declarations and municipal green infrastructure contract awards is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Plant Breeding Market
Agriculture and Agri Products
Clover Leaf Oil Market
Agriculture and Agri Products
Guarana Market
Agriculture and Agri Products
Dairy Cattle Feed Market
Agriculture and Agri Products
LAMEA Rapeseed Oil Market
Agriculture and Agri Products
Brazil Compound Feed Market
Agriculture and Agri Products
North America Alfalfa Hay Market
Agriculture and Agri Products
Japan Compound Feed Market
Agriculture and Agri Products
Colombia Agriculture Market
Agriculture and Agri Products
Canada Backyard Poultry Feed Market
Agriculture and Agri Products
Global Specialty Crop Market
Agriculture and Agri Products
United States Alfalfa Market
Agriculture and Agri Products
Pure Plant Oil Market
Agriculture and Agri Products
Rapeseed Oil Market
Agriculture and Agri Products
Singapore Floriculture Market
Agriculture and Agri Products
Asia-Pacific Animal Protein Market