
 Compound Fertilizer Market | 2026-2036
Compound Fertilizer Market Size, Share, and Industry Trends Forecast 2026-2036
Compound Fertilizer Market Outlook
ISO 9001 quality management certification is unwinding competitive access for smaller blenders who lack documented process controls. Nutrien Ltd. leverages its integrated potash-phosphate network across Western Canada and the US Midwest to sustain cost advantages in bulk NPK production. Yara International ASA anchors its position through ammonia manufacturing scale in Norway and deliberate expansion of low-carbon fertilizer lines. The Mosaic Company competes on phosphate rock reserve depth in Florida and Brazil, giving it upstream control over DAP and MAP feedstock costs.
Compound fertilizers are homogeneous or blended products containing two or more primary nutrients—nitrogen, phosphorus, and potassium—formulated to specific NPK ratios through granulation, compaction, or bulk blending processes. These formulations deliver balanced nutrition tailored to soil tests and crop removal rates, replacing single-nutrient applications that risk leaching or fixation losses. Granular forms dominate volume in broad-acre agriculture due to mechanical spreader compatibility and reduced drift, while liquid formulations capture premium placement in horticulture and fertigation systems where precision dosing matters. NPK blends lead value pools in Asia-Pacific import markets, whereas water-soluble specialty grades command margin concentration in protected cultivation across Spain, the Netherlands, and Mexico.
The EPA oversees nutrient management plans and water quality standards affecting phosphorus application rates in Chesapeake Bay and Mississippi River watersheds, while REACH and EU Fertilizing Products Regulation set contaminant limits and labeling requirements for products entering European markets. India's FSSAI and BIS standards govern micronutrient fortification claims and heavy-metal thresholds in packaged fertilizers distributed through the government subsidy channel. Stakeholders must monitor how carbon-accounting rules at farm-gate and border levels reshape procurement criteria for nitrogen-intensive products.
Market Dynamics
Carbon-border accounting and nutrient-based subsidy reforms are forcing wholesale reformulation of nitrogen-intensive products across import-dependent agricultural economies.
Growth Catalysts
- EU F-Gas Regulation:Phasedown of fluorinated greenhouse gases is accelerating investment in low-carbon ammonia production pathways across European manufacturing clusters.
- Precision agriculture:Variable-rate application technology in Brazil's Cerrado is expanding compound fertilizer penetration among specialty crop growers managing diverse soil zones.
- India's NBS reforms:Nutrient-based subsidy restructuring is redirecting smallholder wheat-rice belt demand toward balanced NPK formulations away from urea-heavy regimes.
Market Restraints
- Phosphate rock concentration:Upstream feedstock control rests with a handful of reserve-holding jurisdictions, exposing blenders to geopolitical supply disruptions.
- Natural gas price volatility:Ammonia synthesis costs swing with European and Asian benchmark gas indices, compressing margins for nitrogen-heavy product lines.
- REACH compliance burden:Heavy-metal contaminant thresholds and extended safety dossier requirements are lengthening product registration timelines for entrants.
Strategic Opportunities
- Water-soluble specialty grades:Protected cultivation expansion in Spain, the Netherlands, and Mexico is opening premium margin pools outside commodity NPK channels.
- ISO 9001 certification gap:Documented process control requirements are creating acquisition targets among smaller regional blenders lacking compliance infrastructure.
- Fertigation system integration:Liquid formulation demand in horticulture is converging with drip irrigation upgrades across Mediterranean and Latin American export zones.
Industry Challenges
- Blender qualification timelines:Government subsidy channel entry in India requires BIS standard compliance and FSSAI micronutrient fortification verification, stretching onboarding to 18-24 months.
- Legacy equipment incompatibility:Bulk blending infrastructure in North American farm cooperatives requires capital retrofit to handle enhanced-efficiency coated granule formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Compound Fertilizer Market |
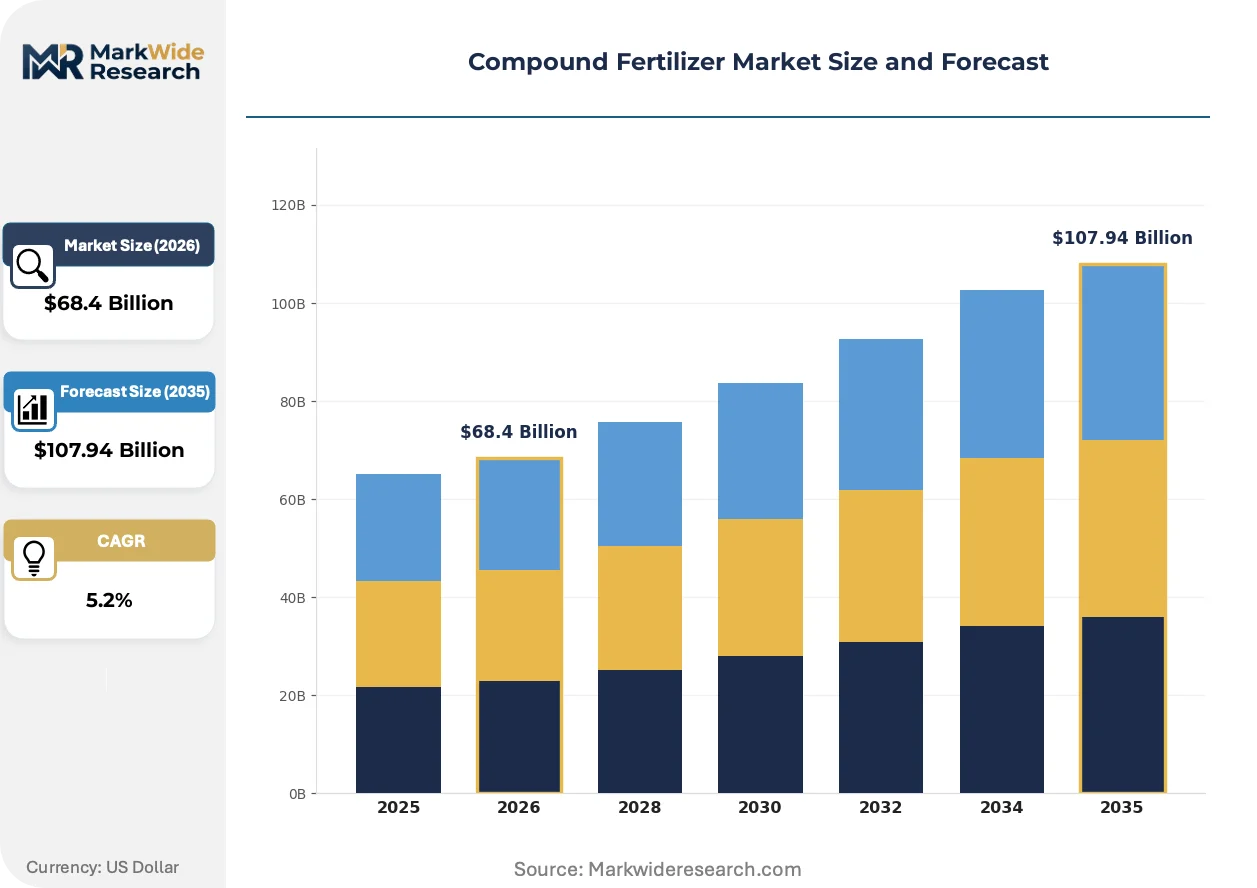
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $107.94 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: NPK, DAP, MAP, SOP Form: Granular, Liquid, Soluble, Powder End Use Industry: Agriculture, Horticulture, Landscaping, Turf Distribution Channel: Retail, Wholesale, Online, Direct Sales |
| Companies Covered | Nutrien Ltd., Yara International ASA, The Mosaic Company, OCP Group, CF Industries Holdings, Inc., ICL Group Ltd., K+S Aktiengesellschaft, Grupa Azoty, SQM S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Compound Fertilizer Market Strategic Shifts
Formulation science and application hardware are converging to displace single-nutrient broadcasting with precision-placed compound products tailored to sub-field variability.
Controlled-release polymer coating technology is fragmenting traditional seasonal fertilizer purchasing patterns. Specialty crop operators in California's Central Valley and Florida's citrus belt are adopting split-application programs enabled by 60-90 day nutrient availability windows. This is fragmenting historical volume concentration around spring planting windows and spreading procurement across the growing calendar.
REACH and the EU Fertilizing Products Regulation are mandating contaminant limits and digital labeling standards for products entering European markets. Manufacturers must now document cadmium and nickel content below threshold levels and maintain batch traceability through blockchain-enabled systems. Blended products targeting the German and French retail channels are restructuring supply chains to exclude high-impurity phosphate rock sources.
Buyer aggregation through agricultural input cooperatives is compressing supplier negotiation cycles. Midwestern US corn-soy growers are consolidating annual compound fertilizer tenders through regional purchasing alliances, displacing individual farm-level procurement. This concentration is most visible across Iowa, Illinois, and Indiana, where cooperative volume commitments now determine blender production scheduling priority.
Compound Fertilizer Market Segmentation
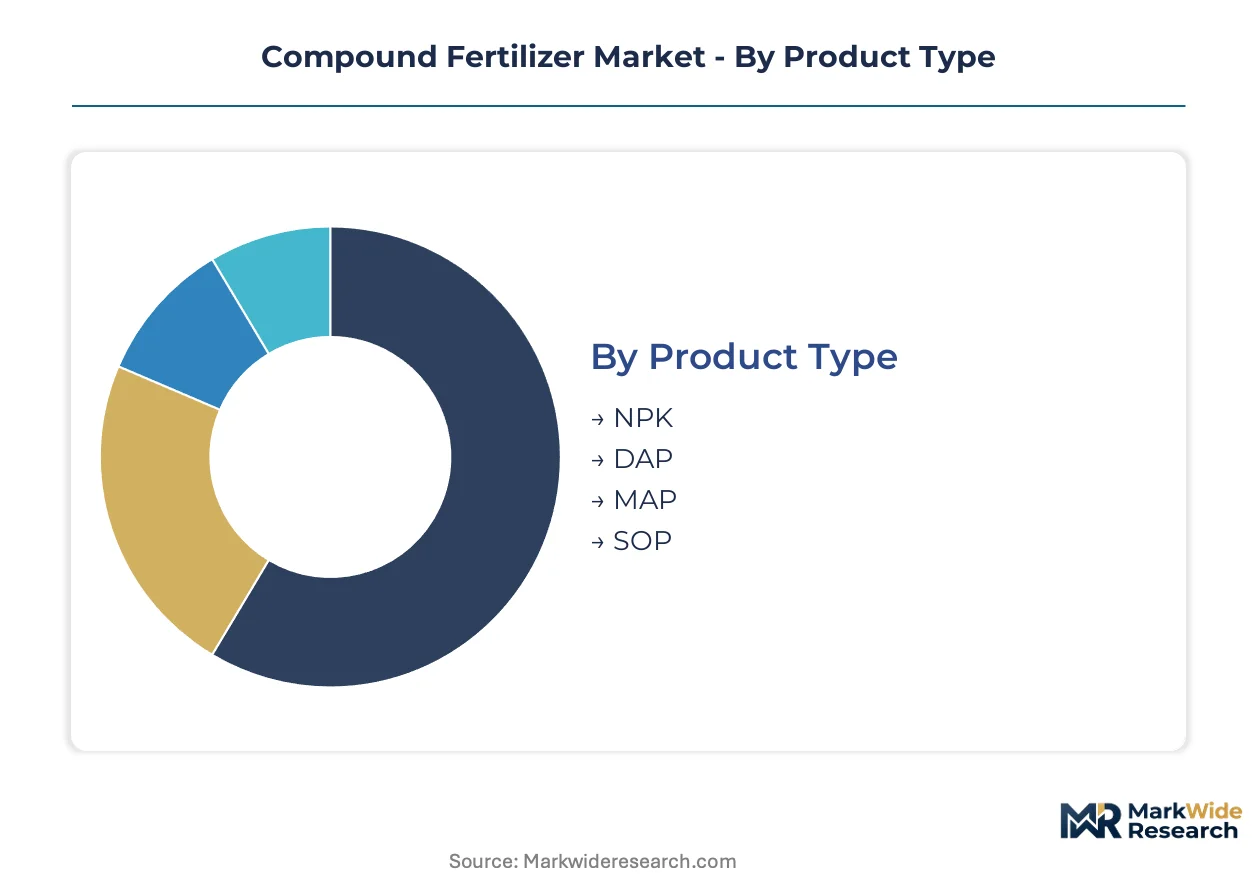
Compound fertilizer procurement patterns diverge sharply across product forms and customer channels. Granular formulations dominate commodity grain belts where mechanical spreading prevails, while specialty grades capture premium placement in export-oriented horticulture clusters.
Product Type:
NPK formulations serve domestic food security programs across import-dependent economies, whereas phosphate-rich DAP and MAP grades flow disproportionately into export agriculture zones.
- NPK:Balanced nitrogen-phosphorus-potassium granules or blends deliver complete nutrition in single applications. India's wheat-rice belt is concentrating procurement here as nutrient-based subsidy reforms displace urea-heavy regimes.
- DAP:Di-ammonium phosphate provides high phosphorus content for root development in cereal establishment phases. Brazil's Cerrado soybean expansion is absorbing rising DAP volumes for phosphate-deficient oxisols.
- MAP:Mono-ammonium phosphate offers lower nitrogen-to-phosphorus ratios preferred for starter fertilizer placement in no-till systems.
- SOP:Sulfate of potash supplies potassium without chloride, essential for chloride-sensitive crops in specialty vegetable production.
NPK commands the established base. The steepest expansion runs through DAP.
Form:
Application hardware compatibility and labor cost gradients determine form selection across farming systems.
- Granular:Hard granules engineered for mechanical spreader compatibility dominate broad-acre grain production. Midwestern US corn-soy cooperatives schedule blender production around granular volume commitments.
- Liquid:Solution or suspension formulations enable precision placement through fertigation infrastructure. California's Central Valley specialty crop operators are adopting split-application programs enabled by liquid delivery systems.
- Soluble:Rapidly dissolving crystalline products serve protected cultivation in Spain, the Netherlands, and Mexico where drip irrigation upgrades demand complete nutrient solution compatibility.
- Powder:Fine-ground materials support bulk blending operations and manual application in smallholder contexts lacking mechanized equipment.
Granular forms anchor volume leadership. Soluble grades are climbing the fastest.
End Use Industry:
Customer margin profiles separate commodity volume from premium pricing pools.
- Agriculture:Row-crop cereal and oilseed production consumes standardized NPK blends through cooperative purchasing alliances. Government subsidy channels in India direct the majority of compound fertilizer flow here.
- Horticulture:Protected cultivation and fresh produce export operations demand water-soluble specialty grades with documented contaminant thresholds. EU Fertilizing Products Regulation compliance is restructuring supply chains serving German and French retail channels.
- Landscaping:Commercial property maintenance and municipal green space programs seek uniform visual results with controlled-release formulations.
- Turf:Golf course and sports field managers prioritize rapid green-up and wear tolerance through seasonal fertilizer programs.
Agriculture retains the volume core. Horticulture delivers the margin expansion.
Distribution Channel:
Channel structure reflects customer scale and technical service requirements.
- Retail:Farm supply stores and agronomy centers serve individual growers with bagged products and soil testing services. India's FSSAI and BIS standard compliance stretches blender onboarding to 18-24 months for packaged fertilizers entering this channel.
- Wholesale:Regional distributors aggregate volume for cooperative purchasing alliances across Iowa, Illinois, and Indiana, compressing supplier negotiation cycles.
- Online:Digital platforms are emerging for specialty product access in remote cultivation zones lacking physical infrastructure.
- Direct Sales:Large integrated operations contract directly with manufacturers for bulk delivery to on-farm storage.
Wholesale channels handle the dominant flow. Direct sales are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government nutrient-based subsidy reforms in India and precision agriculture incentives in Brazil are redirecting procurement toward balanced NPK formulations. The EU F-Gas Regulation and carbon-border adjustments are forcing low-carbon ammonia investment across European manufacturing clusters.
United States
Midwestern corn-soy cooperatives in Iowa, Illinois, and Indiana are consolidating annual compound fertilizer tenders through regional purchasing alliances. The EPA oversees nutrient management plans and water quality standards affecting phosphorus application rates in Chesapeake Bay and Mississippi River watersheds. Florida's phosphate rock reserves give upstream feedstock control to manufacturers serving the domestic DAP and MAP markets.
Brazil
Specialty crop growers in the Cerrado region are expanding compound fertilizer use as precision agriculture techniques spread across diverse soil zones. Federal agricultural credit programs through Banco do Brasil and subsidized rural financing accelerate input adoption among commercial operators. The Matopiba frontier—spanning Maranhão, Tocantins, Piauí, and Bahia—is absorbing rising DAP volumes for phosphate-deficient oxisols in soybean expansion zones.
India
Smallholder farmers in the wheat-rice belt are accelerating NPK adoption as government nutrient-based subsidy reforms displace urea-heavy regimes. The FSSAI and BIS standards govern micronutrient fortification claims and heavy-metal thresholds in packaged fertilizers distributed through subsidy channels. Blender qualification timelines for retail channel entry stretch onboarding to 18-24 months, concentrating procurement among established suppliers in Punjab and Haryana.
Germany
REACH and the EU Fertilizing Products Regulation are mandating contaminant limits and digital labeling standards for products entering German retail channels. The national carbon-border adjustment mechanism is reshaping procurement criteria for nitrogen-intensive imports. Manufacturers serving the Rhine-Ruhr and Bavarian agricultural clusters are restructuring supply chains to exclude high-impurity phosphate rock sources and maintain blockchain-enabled batch traceability.
China
Domestic NPK production serves food security programs while export-oriented water-soluble specialty grades target protected cultivation markets in Spain and the Netherlands. Dual carbon goals under national climate commitments are pressuring ammonia synthesis operations to adopt lower-emission production pathways. The Shandong Peninsula and Yangtze River Delta manufacturing clusters are upgrading granulation infrastructure to meet EU contaminant thresholds for export-bound product lines.
Compound Fertilizer Market Competitive Environment
Player mix skews toward integrated resource holders with captive phosphate rock or ammonia synthesis capacity. Tiered structure separates bulk commodity producers from specialty formulation specialists serving horticulture and fertigation segments. Strategic archetypes include upstream-integrated majors controlling feedstock costs, regional blenders leveraging distribution proximity, and precision-agriculture technology bundlers. Dominant competitive moves center on backward integration into phosphate mining and ammonia manufacturing, plus portfolio diversification into low-carbon and enhanced-efficiency product lines.
Among North American integrated producers, Nutrien Ltd. and The Mosaic Company exemplify the upstream-control archetype through their respective positions in the potash-phosphate network and Florida phosphate rock reserves. Yara International ASA occupies a position within the European low-carbon manufacturing tier, leveraging ammonia scale in Norway to serve reformulation demands under EU F-Gas Regulation compliance timelines. These three entities represent the scale-driven end of competitive positioning, with their geographic and feedstock configurations shaping procurement prioritization across import-dependent agricultural economies.
| Leading Market Players |
|---|
| Nutrien Ltd. |
| Yara International ASA |
| The Mosaic Company |
| OCP Group |
| CF Industries Holdings, Inc. |
| ICL Group Ltd. |
| K+S Aktiengesellschaft |
| Grupa Azoty |
| SQM S.A. |
| Others |
Value Chain & Pricing Dynamics
Ninety-day inventory cycles at Indian subsidy-channel distributors concentrate procurement leverage among established blenders while compressing margins for new entrants lacking documented process controls. This lead-time band reflects how BIS standard compliance and FSSAI verification requirements stretch blender qualification to 18-24 months, entrenching pricing power with incumbents who have already absorbed these fixed costs.
Pricing Analysis
Certification level creates the primary spread between premium ISO 9001-compliant grades and unverified economy blends in wholesale channels. Three-tier pricing structure across premium, standard, and economy levels tracks documented contaminant thresholds, batch traceability systems, and micronutrient fortification claims. Cost compression in nitrogen-heavy product lines is intensifying because European and Asian natural gas benchmark volatility feeds directly into ammonia synthesis economics. Government subsidy channel buyers in India's wheat-rice belt exhibit highest price sensitivity, while protected cultivation operators in Spain and the Netherlands accept premium positioning for water-soluble specialty grades with REACH-compliant documentation.
Supply Chain Analysis
Strategic stockpile preferences dominate phosphate rock sourcing, with reserve-holding jurisdictions in Morocco, the United States, and China anchoring upstream feedstock security. Ammonia synthesis draws from natural gas feedstocks concentrated in Russia, Qatar, and Trinidad and Tobago, while potash extraction centers on Canada, Belarus, and Russia. Single-source vulnerability runs through phosphate rock concentration, where OPEC-like supply coordination among reserve holders exposes blenders to geopolitical disruption. Distribution runs through agricultural input cooperatives in the US Midwest and government subsidy depots in India, with direct sales gaining share among large integrated farming operations contracting for bulk delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Carbon-border accounting and low-carbon ammonia production pathways are disrupting competitive positioning in nitrogen-intensive product lines, creating acquisition opportunities among certification-deficient regional blenders.
For Market Incumbents: Shield margin position by accelerating backward integration into phosphate mining and ammonia manufacturing to insulate against feedstock volatility. Invest in blockchain-enabled batch traceability systems ahead of EU Fertilizing Products Regulation digital labeling mandates. Prioritize ISO 9001 certification acquisition among smaller regional blenders who lack compliance infrastructure.
For New Entrants and Emerging Players: Lead with water-soluble specialty grades targeting protected cultivation expansion in Mexico and Mediterranean export zones, where premium margins offset scale disadvantages. Penetrate the fertigation system integration segment through partnerships with drip irrigation upgrade providers in California's Central Valley. Anchor initial positioning through agronomic advisory services bundled with precision placement technology.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because certification barriers and subsidy channel qualification timelines are structurally fragmenting the regional blender base. Target acquisition profiles center on ISO 9001-deficient blenders with established distribution in India's wheat-rice belt or Brazil's Cerrado expansion zones. Watch for inflection when carbon-border adjustment mechanisms trigger procurement criteria shifts among import-dependent agricultural economies.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Phosphate Mining | Captive rock reserves in Florida and Brazil insulate DAP/MAP feedstock costs from OPEC-like supply coordination. |
| Low-Carbon Ammonia Manufacturing Transition | Norwegian electrolysis-based production aligns with EU F-Gas Regulation phasedown timelines and carbon-border compliance. |
| Water-Soluble Specialty Grade Expansion | Protected cultivation demand in Spain and the Netherlands commands margin concentration outside commodity NPK channels. |
| Blockchain-Enabled Batch Traceability | Digital labeling standards under REACH and EU Fertilizing Products Regulation mandate contaminant documentation for retail channel entry. |
| ISO 9001 Certification Acquisition Program | Documented process control requirements are creating distressed acquisition targets among smaller regional blenders lacking compliance infrastructure. |
Study Parameters
A spread of perspectives from agronomy directors at agricultural cooperatives, procurement leads at government subsidy depots, plant managers at ammonia synthesis facilities, and regulatory affairs specialists at fertilizer manufacturers converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation through customs and trade data, SEC 10-K filings of listed producers, and national fertilizer association statistics. Bottom-up triangulation across product-grade volume estimates and top-down reconciliation against national nutrient consumption surveys anchored the analytical framework.
Segmentation dimensions modeled include product type, formulation grade, end-use industry, distribution channel, and regional regulatory cluster across the projection horizon. CAGRs were derived through trend extrapolation of historical consumption patterns adjusted for policy inflection points including India's nutrient-based subsidy reforms and EU carbon-border implementation timelines. Industry-specific forecast inputs incorporated ammonia synthesis capacity utilization rates and phosphate rock reserve depletion curves.
Underlying assumptions cover subsidy program continuity, natural gas price band stability, and REACH compliance timeline adherence, with deviation risk concentrated in geopolitical supply disruptions and carbon-accounting rule acceleration. Revision becomes warranted when carbon-border adjustment thresholds or phosphate export restriction intensity crosses policy signaling thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fertilizers
United States Controlled Release Fertilizer Market
Fertilizers
Potash Market
Fertilizers
Vietnam Biofertilizer Market
Fertilizers
Vietnam Organic Fertilizer Market
Fertilizers
Global Controlled Release Fertilizer Market
Fertilizers
Fertilizer Tester Market
Fertilizers
Global Specialty Fertilizer Market
Fertilizers
South America Specialty Fertilizer Market
Fertilizers
China Organic Fertilizers Market
Fertilizers
Europe Specialty Fertilizer Market
Fertilizers
Soil Conditioners Market
Fertilizers
Italy Foliar Fertilizer Market
Fertilizers
Ammonium Sulfate Fertilizer Market
Fertilizers
Global Nitrogen Fertilizers Market
Fertilizers
Single Superphosphate (SSP) Market
Fertilizers
India Controlled Release Fertilizer Market