
 Corn Gluten Feed Concentrates Market | 2026-2036
Corn Gluten Feed Concentrates Market Size, Share, and Industry Trends Forecast 2026-2036
Corn Gluten Feed Concentrates Market Analytics
REACH compliance in the European Union is repositioning the cost-of-entry calculus for corn gluten feed concentrate exporters seeking market access. Archer Daniels Midland Company leverages its integrated wet milling footprint across North America to sustain supply chain control from corn receipt to finished feed output. Cargill Incorporated anchors its competitive stance through deep procurement relationships with large-scale livestock operations. Tate & Lyle differentiates by concentrating on higher-protein concentrate grades that command premium placement in dairy nutrition programs.
Corn gluten feed concentrates consist of the bran, steep liquor, and germ cake fractions remaining after corn starch extraction, typically containing 21-25% crude protein and 10-12% crude fiber on a dry matter basis. These concentrates serve primarily as mid-protein feed ingredients for ruminant animals, substituting for soybean meal and other oilseed meals in cost-sensitive ration formulations. The dry feed segment dominates volume throughput due to superior storage stability and lower freight costs, while the liquid feed category captures specialized applications in large dairy operations with on-site blending infrastructure. Pelleted feed formats are gaining traction among poultry end users seeking reduced feed waste and improved handling characteristics.
The FDA's Center for Veterinary Medicine oversees feed safety protocols under the Food Safety Modernization Act, while the USDA monitors grain inspection and grading standards that affect corn gluten feed classification and trade terms. In the European market, EFSA nutritional guidelines and the EU Feed Hygiene Regulation establish maximum contaminant thresholds and labeling requirements that shape product specifications. Stakeholders must monitor evolving renewable fuel mandates and their co-product implications, as ethanol policy directly governs the available supply volume and geographic distribution of corn gluten feed concentrates.
Market Dynamics
The EPA's Renewable Fuel Standard mandates are expanding ethanol production volumes, which directly amplifies corn gluten feed concentrate supply as an unavoidable co-product stream. This structural coupling between fuel policy and feed ingredient availability concentrates supply growth in the US Midwest wet milling corridor.
Growth Catalysts
- EPA Renewable Fuel Standard expansion:Mandated ethanol volume increases automatically scale corn wet milling output, flooding the feed market with low-cost protein co-products that undercut soybean meal pricing in ruminant rations.
- Dairy herd consolidation:Large-scale dairy operations in Wisconsin and Minnesota are standardizing corn gluten feed concentrates as a mid-protein staple, locking in multi-year procurement contracts with wet millers.
- Pelletization technology adoption:Poultry integrators in the southeastern United States are demanding pelleted formats that reduce feed waste and improve handling, opening new volume channels beyond traditional ruminant markets.
Market Restraints
- Input cost volatility at corn origination:Weather-driven yield variability across Iowa and Illinois directly compresses wet miller margins when basis spreads widen unexpectedly.
- Supply concentration in wet milling corridor:Seventy percent of domestic capacity clusters within a 300-mile radius of Decatur, creating freight disadvantage for coastal livestock operations.
- Regulatory friction from EU REACH compliance:Export-oriented wet millers face escalating registration costs and contaminant testing burdens that screen out smaller volume players from European dairy markets.
Strategic Opportunities
- Underpenetrated Brazilian beef feedlot sector:Corn gluten feed concentrates remain absent from most Brazilian finishing rations despite competitive protein pricing against cottonseed meal.
- Incentive alignment from USDA BioPreferred program:Federal procurement preference for biobased products creates labeling advantages for corn-derived feed ingredients in government-supplied school nutrition programs.
- Liquid feed infrastructure convergence:Large dairy operations with on-site blending tanks are integrating liquid corn gluten feed with precision dosing systems that automate ration formulation.
Industry Challenges
- Specialized fermentation technologist scarcity:Wet milling facilities struggle to recruit process engineers capable of optimizing steep liquor protein recovery rates amid tight labor markets.
- Mycotoxin certification timelines:Third-party testing for aflatoxin and fumonisin compliance adds 72-hour delays to spot market transactions, compressing working capital cycles.
- Legacy feed formulation software integration:Dairy nutritionists using outdated ration balancing platforms lack real-time corn gluten feed nutrient variability data, creating formulation safety margins that dilute cost advantages.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Corn Gluten Feed Concentrates Market |
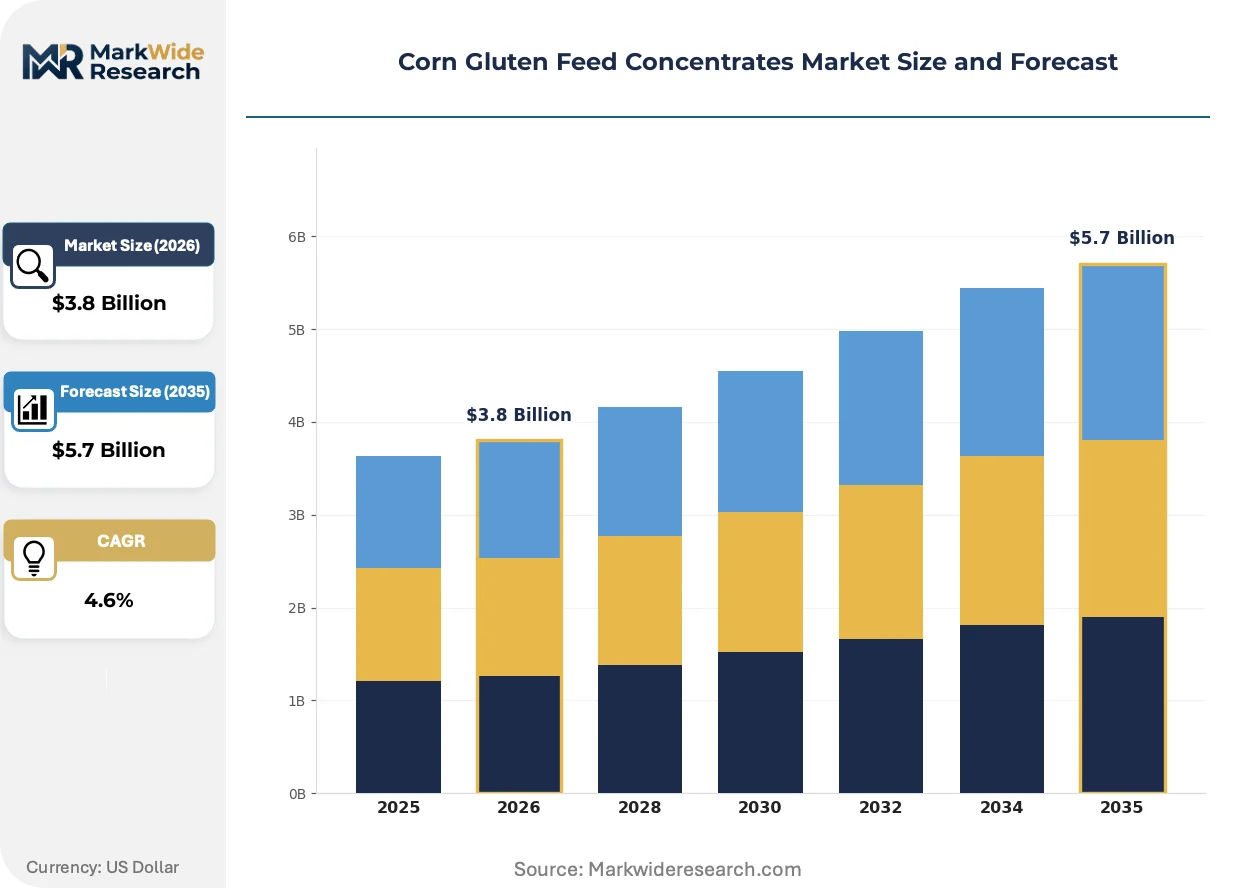
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dry Feed, Liquid Feed, Pelleted Feed, Granulated Feed End Use: Livestock, Poultry, Aquaculture, Pet Food Form: Coarse, Fine, Meal, Crude Distribution Channel: Online, Retail, Wholesale, Direct Sales |
| Companies Covered | Archer Daniels Midland Company, Cargill Incorporated, Tate & Lyle, Bunge Ltd., Ingredion Incorporated, Roquette Frères, Grain Processing Corporation, AGRANA Beteiligungs-AG, HL Agro, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Corn Gluten Feed Concentrates Market Evolving Landscape
Protein extraction efficiency is becoming the decisive competitive variable as wet millers squeeze additional value from every bushel. Technology deployment, regulatory adaptation, and buyer behavior are converging to reshape how corn gluten feed concentrates move from ethanol plants to animal stomachs.
Near-infrared spectroscopy calibration for real-time protein measurement is electrifying quality assurance protocols at wet milling facilities. Large dairy cooperatives in Michigan and Ohio are adopting these inline sensors to reject substandard loads before unloading. This precision is compressing price variance between delivered loads and enabling true spot-market commoditization of protein content.
REACH registration deadlines under ECHA oversight are forcing export-oriented North American wet millers to consolidate contaminant testing protocols. The industrial consequence is a bifurcation between facilities with in-house analytical laboratories and those dependent on third-party certification. European dairy compounders are responding by tightening supplier qualification lists to exclude non-compliant origins.
Long-term offtake contracting is displacing spot market dominance among the largest integrated poultry producers. Tyson Foods and Pilgrim's Pride operations in Arkansas and Georgia are locking in eighteen-month supply agreements with fixed protein floors. This behavior is most visible across the US Southeast where feed mill consolidation has concentrated buying power among three major integrators.
Corn Gluten Feed Concentrates Market Segmentation
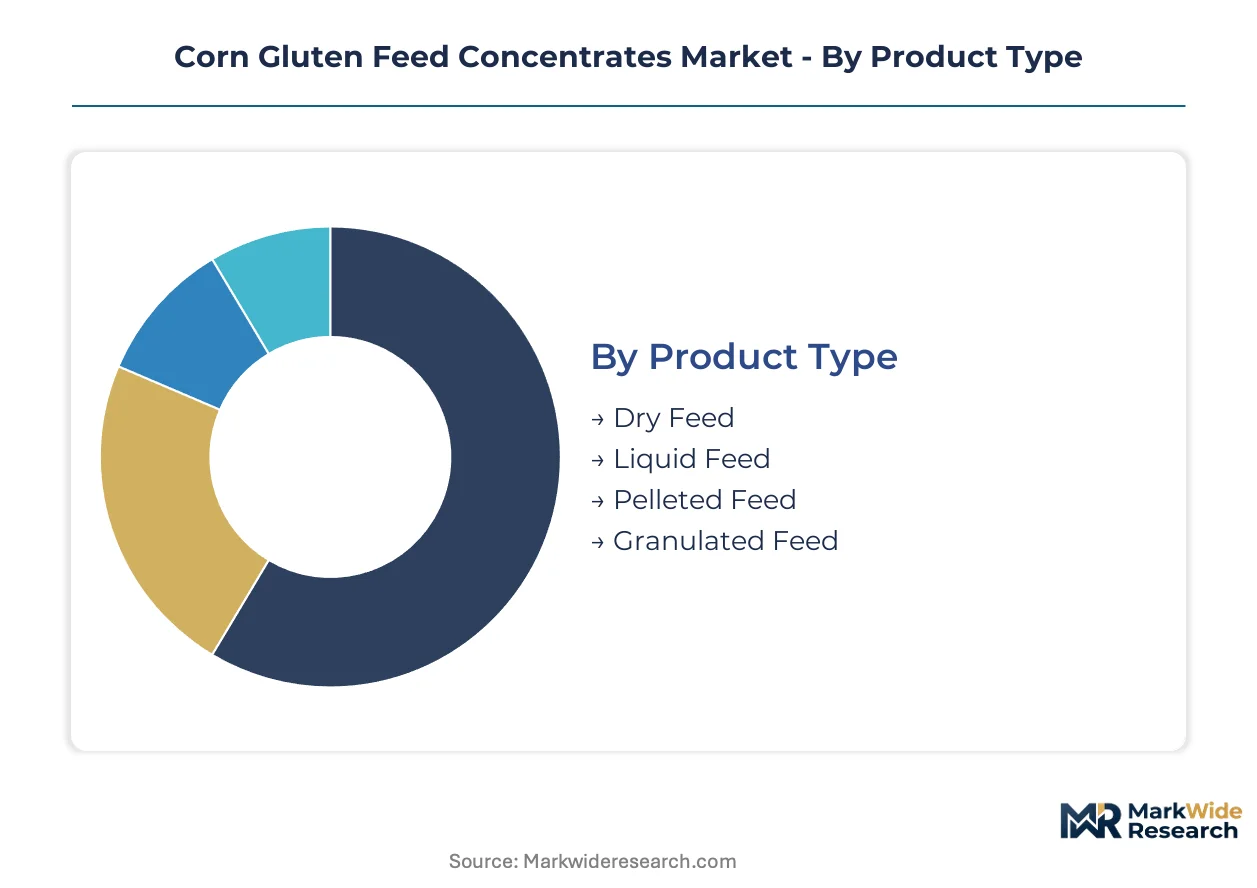
Corn gluten feed concentrate buyers upgrade formulations based on handling economics, storage constraints, and precision feeding requirements. Each segment category reflects distinct trade-offs between protein delivery efficiency and operational compatibility across livestock and companion animal channels.
Product Type:
Upgrade cycles in corn gluten feed concentrate procurement revolve around moisture tolerance, freight economics, and mechanized handling infrastructure at recipient facilities.
- Dry Feed:Contains 10-12% moisture with 21-25% crude protein on a dry matter basis, enabling year-round storage without spoilage risk. Demand concentrates across dairy operations in Wisconsin and Minnesota where 50,000+ head facilities require stable inventory positions. The format commands volume leadership due to lower per-ton freight costs and compatibility with existing feed mill equipment.
- Liquid Feed:Incorporates steep liquor fractions with 45-60% moisture content, demanding on-site blending tanks and precision dosing systems. Large dairy cooperatives in Michigan and Ohio are retrofitting receiving infrastructure to capture protein cost advantages. The segment climbs fastest where automated ration formulation justifies capital investment in storage and mixing hardware.
- Pelleted Feed:Compacted dry feed with reduced dust and improved flowability for mechanized handling systems.
- Granulated Feed:Intermediate particle size offering faster hydration rates for specific aquaculture applications.
Dry feed sits at the top of the volume ranking, with liquid feed climbing the fastest.
End Use:
Cost tier differentiation separates commodity protein substitution from specialized nutrition programs where ingredient premiums command placement.
- Livestock:Dairy and beef cattle operations represent the foundational demand tier, substituting corn gluten feed concentrates for soybean meal in cost-sensitive ruminant rations. Herd consolidation across the US Midwest locks in multi-year procurement contracts with wet millers. The segment anchors volume throughput due to per-animal consumption scale and standardized inclusion rates.
- Poultry:Broiler and layer operations demand pelleted formats with precise protein consistency to optimize feed conversion ratios. Tyson Foods and Pilgrim's Pride operations in Arkansas and Georgia are driving specification tightening through consolidated buying power. The segment gains share fastest as integrators seek alternative proteins amid oilseed meal price volatility.
- Aquaculture:Emerging demand from catfish and tilapia producers seeking mid-protein ingredients with favorable amino acid profiles.
- Pet Food:Premium positioning in grain-inclusive formulations targeting digestibility marketing claims.
Livestock dominates current volume, with poultry expanding most quickly.
Form:
Application-specific particle sizing determines inclusion methodology across mash feeds, top-dressing protocols, and extruded product manufacturing.
- Coarse:Retains fibrous bran fractions with 10-12% crude fiber, suited for dairy TMR rations where rumen fill and cud chewing drive formulation decisions. Demand clusters in Wisconsin heifer-raising operations.
- Fine:Milled to pass 4mm screens, optimizing surface area for pelleting binders and extrusion processes in poultry feed manufacturing.
- Meal:Standard grind specification for bulk inclusion in complete feeds across species.
- Crude:Minimally processed fraction with highest fiber retention for maintenance rations in beef backgrounding.
Coarse form leads volume rankings, with fine form gaining fastest.
Distribution Channel:
Customer type and procurement scale determine channel selection between spot market flexibility and contract security.
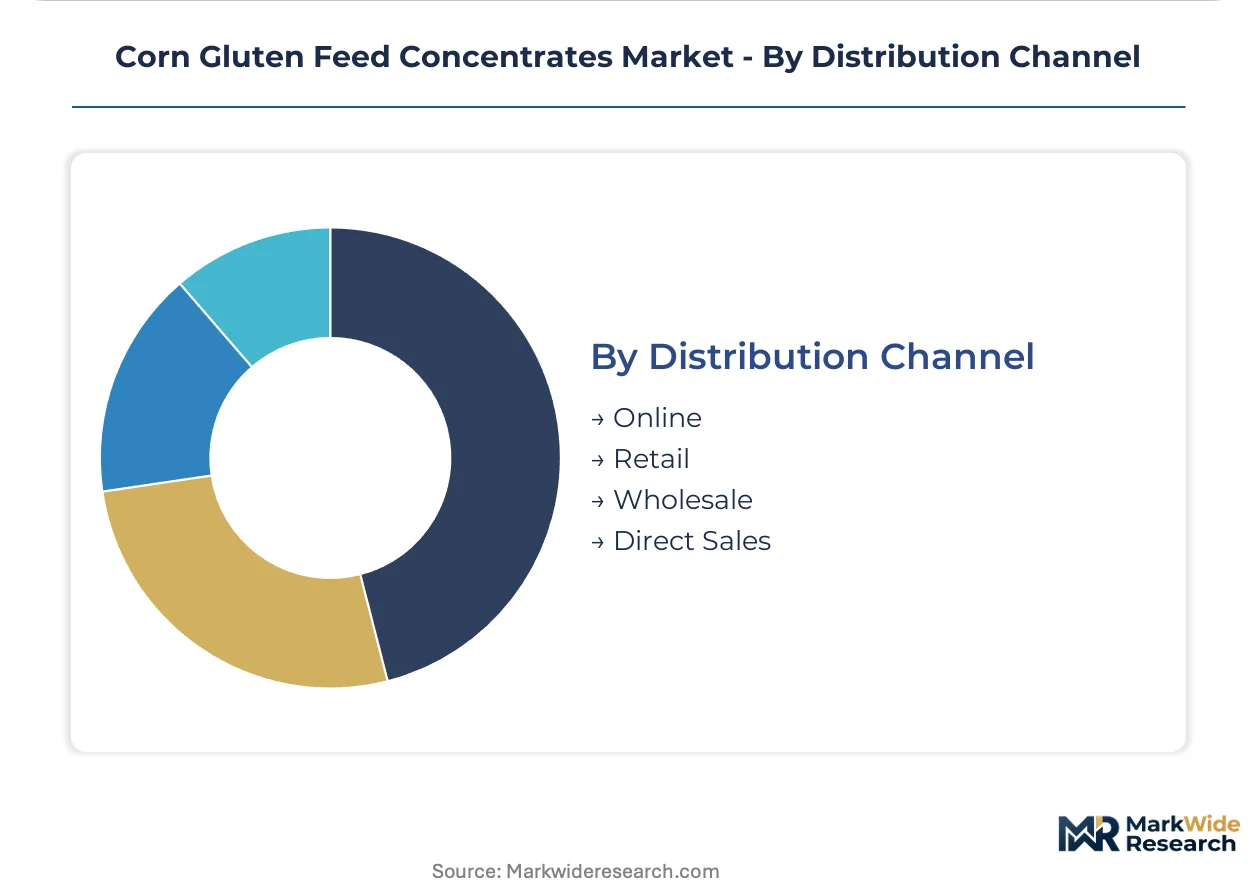
- Wholesale:Aggregators and regional feed distributors consolidate truckload volumes for redistribution to mid-size livestock operations. The channel captures procurement efficiency for buyers lacking direct wet miller relationships.
- Direct Sales:Large integrated producers negotiate eighteen-month supply agreements with fixed protein floors, bypassing intermediary markups. The segment expands most quickly as dairy herd consolidation concentrates buying power.
- Online:Digital platforms facilitating spot market price discovery for smaller livestock operations.
- Retail:Bagged product for hobby farms and companion animal channels with premium pricing tolerance.
Wholesale sits at the top of the volume ranking, with direct sales climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Wet milling technologists and fermentation specialists cluster most densely across the US Midwest corn belt, anchoring supply capacity near origination points. This workforce concentration shapes where production capacity expands and which regions capture downstream value.
United States
Dairy herd consolidation across Wisconsin and Minnesota locks in multi-year procurement contracts with wet millers. The EPA's Renewable Fuel Standard mandates expand ethanol volumes, automatically scaling corn gluten feed concentrate supply as a co-product stream. Decatur, Illinois anchors the densest capacity cluster, with seventy percent of domestic production sitting within a three-hundred-mile radius.
Brazil
Beef feedlot operators in São Paulo and Mato Grosso states remain underpenetrated despite competitive protein pricing against cottonseed meal. ANVISA feed safety protocols govern import registration for co-product ingredients entering Brazilian livestock channels. Campinas-based distributors are testing containerized shipments from US Gulf ports to bypass traditional oilseed meal supply chains.
Germany
Compound feed manufacturers in Lower Saxony seek mid-protein alternatives to soybean meal amid volatile oilseed markets. EFSA nutritional guidelines and EU Feed Hygiene Regulation establish maximum contaminant thresholds that shape import specifications. The Hamburg port cluster handles transshipment volumes destined for Danish and Dutch dairy operations.
China
Swine restocking programs in Sichuan and Henan provinces drive demand for cost-competitive protein ingredients in commercial rations. SAMR feed safety standards and GB quality classifications govern domestic trading terms for corn processing co-products. The Yangtze River Delta wet milling corridor near Shanghai processes imported corn for both starch and feed ingredient output.
Canada
Alberta cattle backgrounding operations substitute corn gluten feed concentrates for barley-based protein supplements during drought-stressed grain years. Health Canada and the Canadian Food Inspection Agency oversee feed safety protocols under the Safe Food for Canadians Regulations. Lethbridge feedlot clusters source truckload volumes from US Midwest millers via Montana and North Dakota rail terminals.
Corn Gluten Feed Concentrates Market Competitive Landscape
The competitive structure tilts toward integrated agribusiness conglomerates with captive wet milling footprints. Three to four multinational processors control the majority of North American and European supply capacity, while regional specialists capture niche premium segments. Dominant archetypes include starch-to-ethanol integrators, diversified grain traders with downstream feed operations, and protein-specialist refiners. Capacity expansion and backward integration into corn origination networks constitute the primary competitive moves.
Within the integrated processor tier, Archer Daniels Midland Company exemplifies the starch-to-ethanol model with North American wet milling coverage. Cargill Incorporated represents the diversified grain trading archetype with procurement relationships anchoring livestock supply chains. Tate & Lyle occupies a position among protein-specialist refiners concentrating on higher-grade concentrate fractions. These three entities collectively illustrate how scale, integration depth, and product focus differentiate positioning across the value chain.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| Cargill Incorporated |
| Tate & Lyle |
| Bunge Ltd. |
| Ingredion Incorporated |
| Roquette Frères |
| Grain Processing Corporation |
| AGRANA Beteiligungs-AG |
| HL Agro |
| Others |
Value Network & Pricing Analysis
The EPA's Renewable Fuel Standard gates both qualified supply and premium-tier pricing access for corn gluten feed concentrates, as ethanol mandate compliance determines wet milling output volumes and geographic distribution of co-product streams. Buyers in coastal livestock markets face freight-adjusted premiums while Midwest dairy operations capture basis advantages from proximity to Decatur-area production clusters.
Pricing Analysis
Spot market transactions coexist with eighteen-month offtake agreements featuring fixed protein floors, creating a bifurcated pricing architecture. Price differentiation separates liquid feed with precision dosing infrastructure from dry bulk formats, while mycotoxin certification tiers screen out uncertified origins from European compounders. Cost compression in standard-grade concentrates is intensifying because corn basis volatility across Iowa and Illinois compresses wet miller margins. Large integrated poultry producers exhibit lowest price sensitivity due to consolidated buying power, while regional distributors face margin squeeze from spot market exposure.
Supply Chain Analysis
Domestic-content mandates under the USDA BioPreferred program reshape sourcing toward US-origin corn derivatives for federal nutrition procurement. Supply concentrates in the United States, Brazil, and Germany, with seventy percent of North American capacity anchored within three hundred miles of Decatur. Raw material flows draw from corn origination networks across Illinois, Iowa, and Indiana, with steep liquor protein recovery rates tethered to fermentation technologist availability. Single-source vulnerability concentrates in the Midwest wet milling corridor, where weather-driven yield variability disrupts input security. Distribution runs through wholesale aggregators and direct sales channels, with large dairy cooperatives bypassing intermediaries through captive procurement relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The corn gluten feed concentrates market functions as a geographic-arbitrage play, with Brazilian feedlot operators capturing protein cost advantages against cottonseed meal while European buyers absorb REACH compliance premiums for qualified supply access.
For Market Incumbents: Cement supply chain control through backward integration into corn origination networks across Illinois and Iowa, locking in basis spreads before weather volatility widens procurement costs. Expand wet milling capacity near Brazilian port infrastructure to preempt ANVISA-registered competitors from capturing São Paulo feedlot demand. Certification investment in EFSA-compliant testing protocols defends European dairy compounder relationships against screened-out smaller volume players. For New Entrants and Emerging Players: Precision fermentation technology for steep liquor protein recovery offers entry leverage into liquid feed segments where automated dosing infrastructure justifies premium positioning. Target underpenetrated Brazilian beef finishing rations through Campinas-based distributor partnerships, bypassing established oilseed meal supply chains. White-space exists in pelleted format production for southeastern US poultry integrators demanding reduced feed waste specifications. For Investors and Strategic Acquirers: Roll-up economics work for regional wet milling specialists with captive corn origination assets because ethanol policy co-product coupling creates structural supply advantages for scaled processors. Acquisition targets include protein-specialist refiners with EFSA-registered laboratory infrastructure and Brazilian distribution licenses. Watch EPA Renewable Fuel Standard volume mandate revisions as inflection indicators for co-product supply availability and pricing power shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Corn Origination | Captive supply from Iowa and Illinois locks in basis advantages before weather-driven volatility widens spreads. |
| EFSA-Compliant Laboratory Certification | In-house contaminant testing protocols qualify supply for European dairy compounder procurement lists. |
| Liquid Feed Infrastructure Convergence | Automated dosing system partnerships with Michigan and Ohio dairy cooperatives capture precision feeding premiums. |
| Brazilian Distribution Licensing | ANVISA-registered containerized shipments from US Gulf ports bypass traditional oilseed meal supply chains. |
| Pelletization Technology Deployment | Reduced dust formats meet Tyson Foods and Pilgrim's Pride specifications for mechanized handling efficiency. |
Research Methodology
Coverage spans North America, South America, and Europe, with primary inputs from each region combining executive interviews with wet milling plant managers, procurement leads at integrated poultry operations, dairy nutritionists, and distribution channel partners. Secondary validation draws from EPA Renewable Fuel Standard volume filings, USDA grain inspection reports, EFSA nutritional guidelines, and customs trade data for corn processing co-products. Bottom-up capacity modeling and top-down demand estimation triangulate volume outputs.
Granularity-level modeling disaggregates product type, end use, form specification, and distribution channel across the projection horizon, with additional dimensioning by protein grade tier and regional wet milling hub. CAGRs derive from segment-level demand elasticity analysis against ethanol policy co-product supply curves, incorporating dairy herd consolidation rates and poultry integrator procurement contract tenors as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EPA mandate revisions, Brazilian feedlot adoption curves, and REACH registration deadline compliance rates. Assumptions reflect current regulatory frameworks and documented procurement patterns, with material revision risk from renewable fuel policy shifts or mycotoxin contamination events. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Global Industrial Hemp Market
Agriculture and Agri Products
North America Shiitake Mushroom Market
Agriculture and Agri Products
France Alfalfa Hay Market
Agriculture and Agri Products
Asia-Pacific Compound Feed Market
Agriculture and Agri Products
Egypt Compound Feed Market
Agriculture and Agri Products
North America Poultry Feed Market
Agriculture and Agri Products
North America Palm Oil Market
Agriculture and Agri Products
North America Bonsai Market
Agriculture and Agri Products
Organic Quinoa Market
Agriculture and Agri Products
Sorghum by-Products Market
Agriculture and Agri Products
African Swine Feed Market
Agriculture and Agri Products
Rice Straw Market
Agriculture and Agri Products
E-Commerce of Agricultural Products Market
Agriculture and Agri Products
Italy Alfalfa Market
Agriculture and Agri Products
Australia Floriculture Market
Agriculture and Agri Products
Live Goods Market