
 Africa Olive Market | 2026-2036
Africa Olive Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Olive Market Outlook
Precision fermentation and near-infrared spectroscopy for real-time oil quality assessment is narrowing the gap between artisanal and industrial output consistency in African olive processing. Willow Creek Olive Estate leverages estate-grown fruit and on-site pressing to anchor premium positioning in South Africa's domestic channel. CHO Group competes through integrated milling and bottling infrastructure that controls cost structures across Maghreb supply chains. Med Oil Company specializes in bulk extra virgin shipments that sustain European buyer relationships through certified origin protocols.
Africa olives comprise Olea europaea fruit and extracted oils containing monounsaturated fatty acids, polyphenols, and squalene, with extra virgin grades requiring cold-pressing below 27 degrees Celsius and free acidity below 0.8 percent for commercial classification. The primary purpose spans culinary consumption, cosmetic formulation, and nutraceutical extraction across Mediterranean-adjacent economies. Extra virgin olive oil commands the dominant value share due to health-positioned retail and food service demand, while table olives generate volume throughput through North African canning operations. Olive pomace oil occupies a cost-driven industrial niche serving regional soap and lubricant manufacturers with lower acidity tolerance.
Morocco's Ministry of Agriculture and the country's national food safety regulator enforce geographic indication standards and maximum residue limits that shape export eligibility for European-bound shipments. Tunisia's compliance with EFSA and REACH-aligned contaminant thresholds determines market access for bulk oil consignments entering EU refining channels. Egypt Olive Company and Al Wadi Al Akhdar navigate these frameworks through certified laboratory partnerships. Stakeholders must monitor evolving EU deforestation regulation traceability requirements and irrigation water allocation policies that will determine which cultivation basins can scale certified output.
Market Dynamics
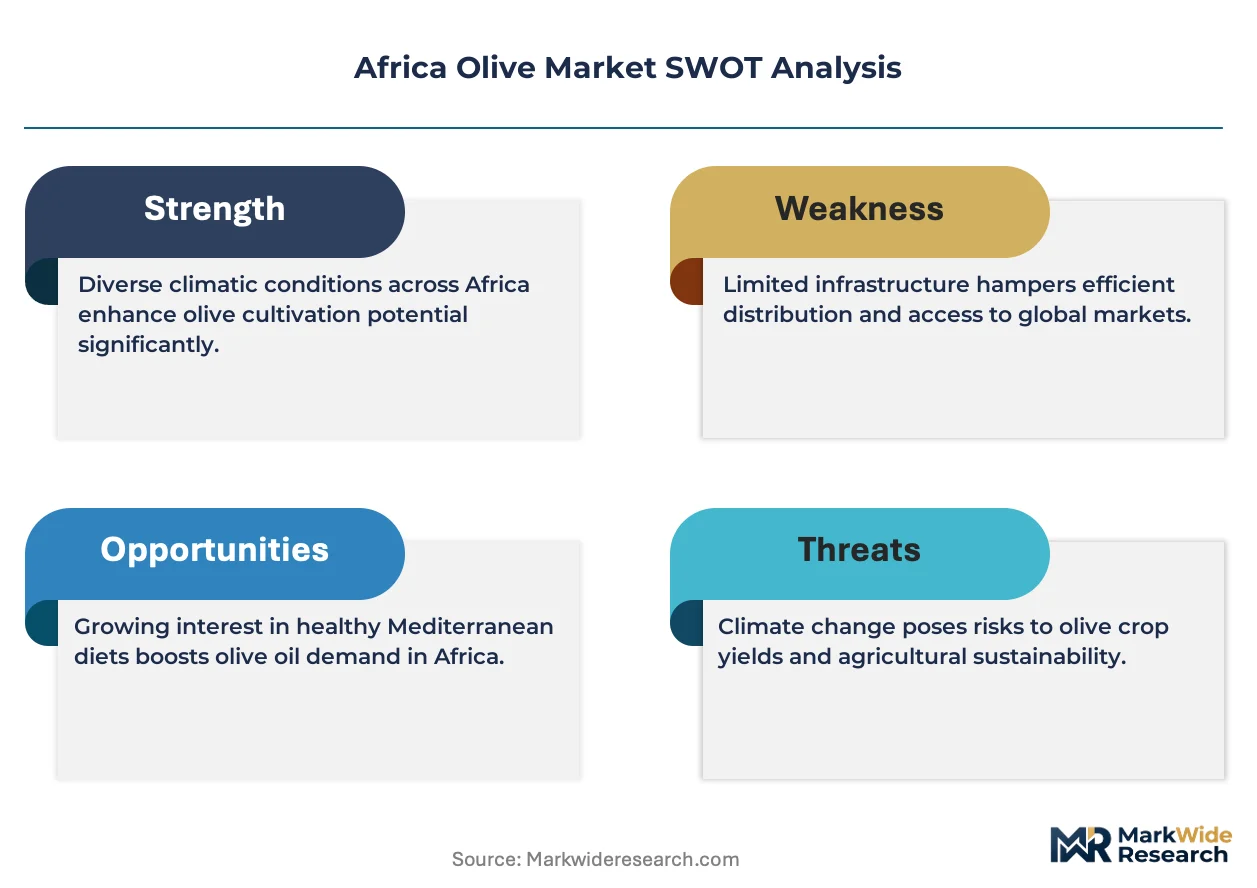
EU deforestation regulation traceability requirements are forcing African olive exporters to rebuild supply chain documentation from orchard to port, compressing margins for uncertified bulk operators while rewarding integrated estate producers.
Growth Catalysts
- Food service expansion:North African hospitality chains are standardizing extra virgin grades across restaurant portfolios, creating steady offtake for certified-origin suppliers.
- REACH-aligned contaminant thresholds:Tunisia's alignment with EFSA standards maintains EU market access for bulk refining channels, preserving export revenue stability.
- Drip irrigation adoption:Moroccan cultivation basins deploying precision water systems are lifting per-hectare oil yields and reducing input volatility.
Market Restraints
- Input cost volatility:Fertilizer and fuel price swings in Egypt and Morocco destabilize smallholder production economics.
- Supply concentration risk:European refining dependence leaves Tunisian bulk exporters exposed to single-buyer pricing power.
- Substitution threat:Sunflower and soybean oils undercut olive oil in price-sensitive North African retail segments.
Strategic Opportunities
- Underpenetrated geography:West African urban markets in Nigeria and Ghana present untapped retail channels for packaged extra virgin grades.
- Regulatory tailwind:Morocco's geographic indication standards create premium positioning for certified estate oils in European specialty retail.
- Technology convergence:Near-infrared spectroscopy combined with blockchain traceability enables real-time quality verification for export shipments.
Industry Challenges
- Skill gap in mill operations:Shortage of trained technicians for cold-pressing equipment maintenance limits capacity utilization in Tunisian cooperatives.
- Certification timeline compression:EU deforestation regulation documentation requirements demand 18-month orchard mapping cycles that outpace existing audit infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Olive Market |
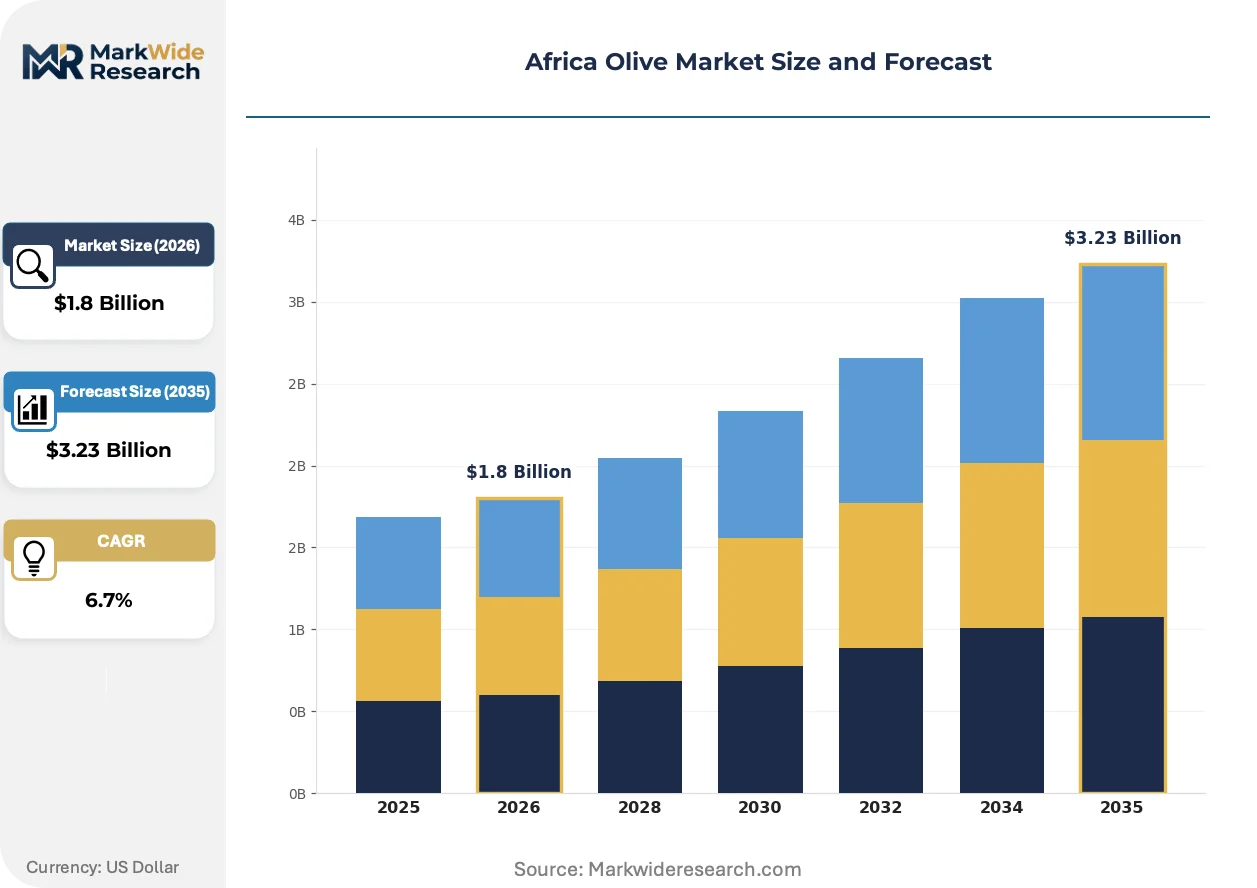
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Extra Virgin Olive Oil, Pure Olive Oil, Olive Pomace Oil, Table Olives Distribution Channel: Supermarkets, Online Retail, Local Markets, Wholesale End User: Food Service Sector, Retail Consumers, Manufacturers, Exporters Application: Culinary Use, Cosmetic Products, Nutraceuticals, Industrial Use |
| Companies Covered | Willow Creek Olive Estate, Cape Olive Holdings, Olivko, Lesieur Cristal, CHO Group, Société Tunisienne de l’Industrie de Raffinage, Med Oil Company, Al Wadi Al Akhdar, Egypt Olive Company, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Olive Market Strategic Shifts
Processing technology and compliance architecture are converging to reshape competitive advantage in African olive supply chains, with digitization and sustainability verification becoming primary differentiators.
Near-infrared spectroscopy systems for real-time free acidity and polyphenol measurement are migrating from laboratory settings to on-farm mobile units. Moroccan estate producers and Tunisian cooperatives are adopting handheld devices for harvest-time quality segregation. This capability is migrating from artisanal guesswork toward data-driven milling decisions that compress quality variance between small-batch and industrial output.
EU deforestation regulation traceability mandates now require geolocation documentation for every production plot above defined thresholds. Bulk exporters in Tunisia and Egypt must retrofit supply chains with satellite-verified polygon mapping and mass-balance accounting. North African processing cooperatives are responding by consolidating fragmented smallholder sourcing into certified estate blocks to maintain EU eligibility.
Certification-driven procurement is restructuring food service buying patterns across Egypt, Morocco, and Tunisia. Restaurant groups and hotel chains are replacing spot-market olive oil purchases with contracted estate supply carrying organic or geographic indication credentials. This shift is most visible in Cairo and Casablanca, where hospitality procurement teams now specify cold-pressed extra virgin with documented origin as a menu-marketing requirement rather than a cost-minimization input.
Africa Olive Market Segmentation
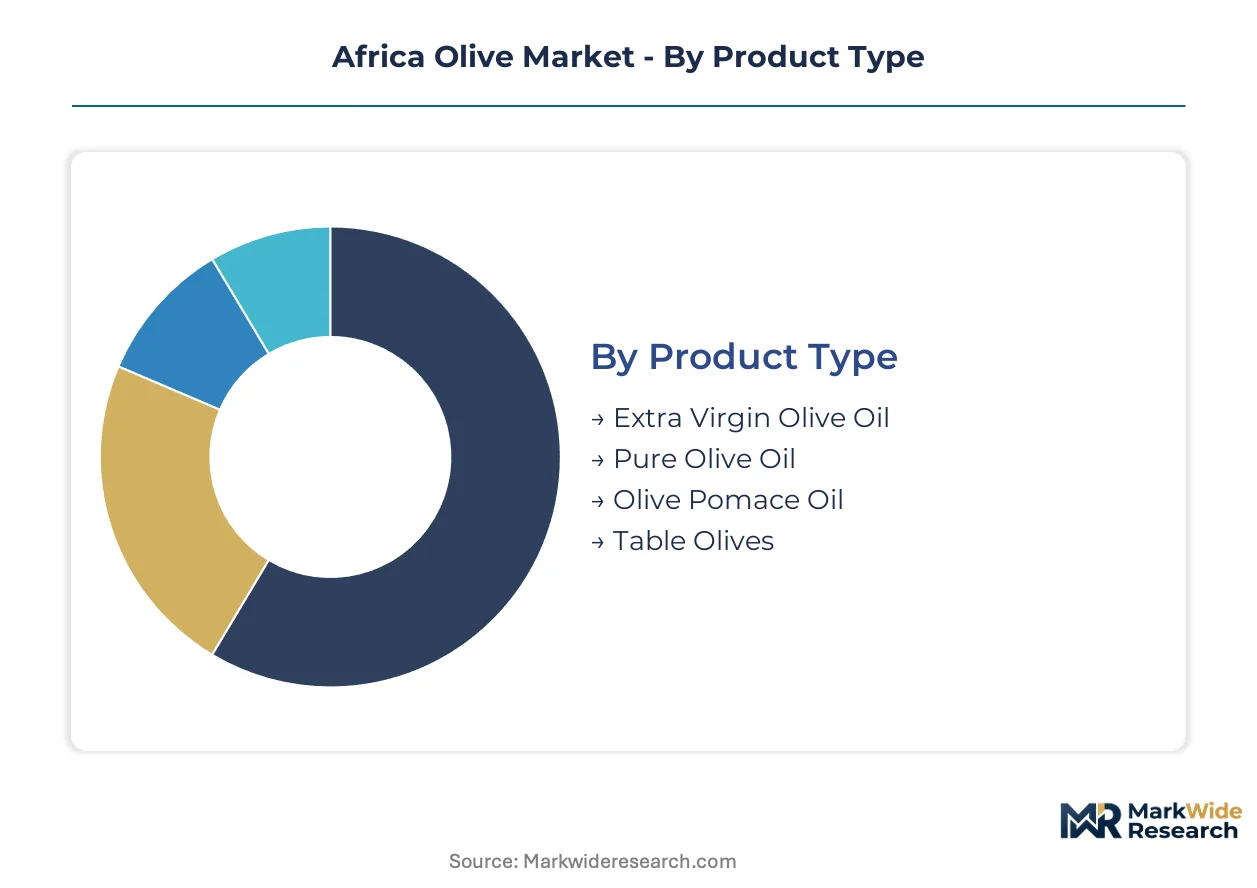
Olive oil and table olive supply chains in Africa fragment across product grades, channel structures, and end-use specifications that each carry distinct margin profiles and compliance burdens. Segmentation reveals where value concentrates versus where volume flows, guiding capital allocation toward certified estate production or bulk refining infrastructure.
Product Type:
Mature extra virgin grades coexist with emerging industrial oil categories across North African processing clusters, with quality thresholds determining export eligibility versus domestic absorption.
- Extra Virgin Olive Oil:Cold-pressed below 27 degrees Celsius with free acidity capped at 0.8 percent, this grade carries geographic indication credentials that unlock European specialty retail placement. Egyptian and Moroccan estate producers concentrate supply here to capture premium positioning under EFSA-aligned contaminant protocols.
- Pure Olive Oil:Refined-virgin blends meeting standard acidity tolerances serve price-sensitive North African retail segments where sunflower and soybean oils exert substitution pressure. Tunisian bulk operators dominate this tier through integrated milling infrastructure serving regional consumer markets.
- Olive Pomace Oil:Solvent-extracted from pressed fruit residue for industrial soap and lubricant manufacturing with minimal acidity requirements.
- Table Olives:Brined and canned fruit processed through Egyptian and Moroccan canning operations targeting Middle Eastern import demand.
Extra Virgin Olive Oil retains volume leadership; Olive Pomace Oil holds the steepest expansion curve as industrial manufacturers seek cost-advantaged feedstocks.
Distribution Channel:
Channel cost tiers separate formal retail infrastructure from fragmented traditional trade, with digitization penetration varying sharply by country regulatory environment.
- Supermarkets:Modern retail chains in Casablanca, Cairo, and Tunis consolidate packaged extra virgin purchases under procurement contracts specifying certified origin documentation. These outlets enforce cold-chain standards and barcode traceability that filter out uncertified bulk repackagers.
- Online Retail:E-commerce platforms in Nigeria and Ghana present emerging direct-to-consumer pathways for South African estate brands seeking West African market development without physical distribution investment.
- Local Markets:Traditional souks and bazaars across Morocco and Tunisia sustain bulk oil sales through unbranded dispensing operations with minimal quality verification.
- Wholesale:Tanker and drum shipments to European refiners and regional food manufacturers concentrate in Tunisian port corridors.
Supermarkets dominate value capture; Online Retail is expanding most quickly as urban connectivity penetrates secondary African cities.
End User:
Customer type segmentation maps procurement sophistication against volume scale, with hospitality buyers driving certification requirements that smallholders struggle to meet.
- Food Service Sector:North African hospitality chains in Cairo and Casablanca now specify cold-pressed extra virgin with documented origin as menu-marketing collateral, replacing spot-market purchasing with contracted estate supply.
- Retail Consumers:Urban households across Egypt, Morocco, and Tunisia absorb packaged grades through supermarket and online channels, with purchasing decisions increasingly influenced by health-positioned labeling.
- Manufacturers:Cosmetic and nutraceutical processors extract polyphenols and squalene for formulation into skincare and supplement products.
- Exporters:Tunisian and Egyptian bulk operators ship unbranded oil to European refiners under REACH-aligned contaminant thresholds.
Food Service Sector commands margin premiums; Exporters retain shipment volume leadership despite pricing pressure from single-buyer concentration.
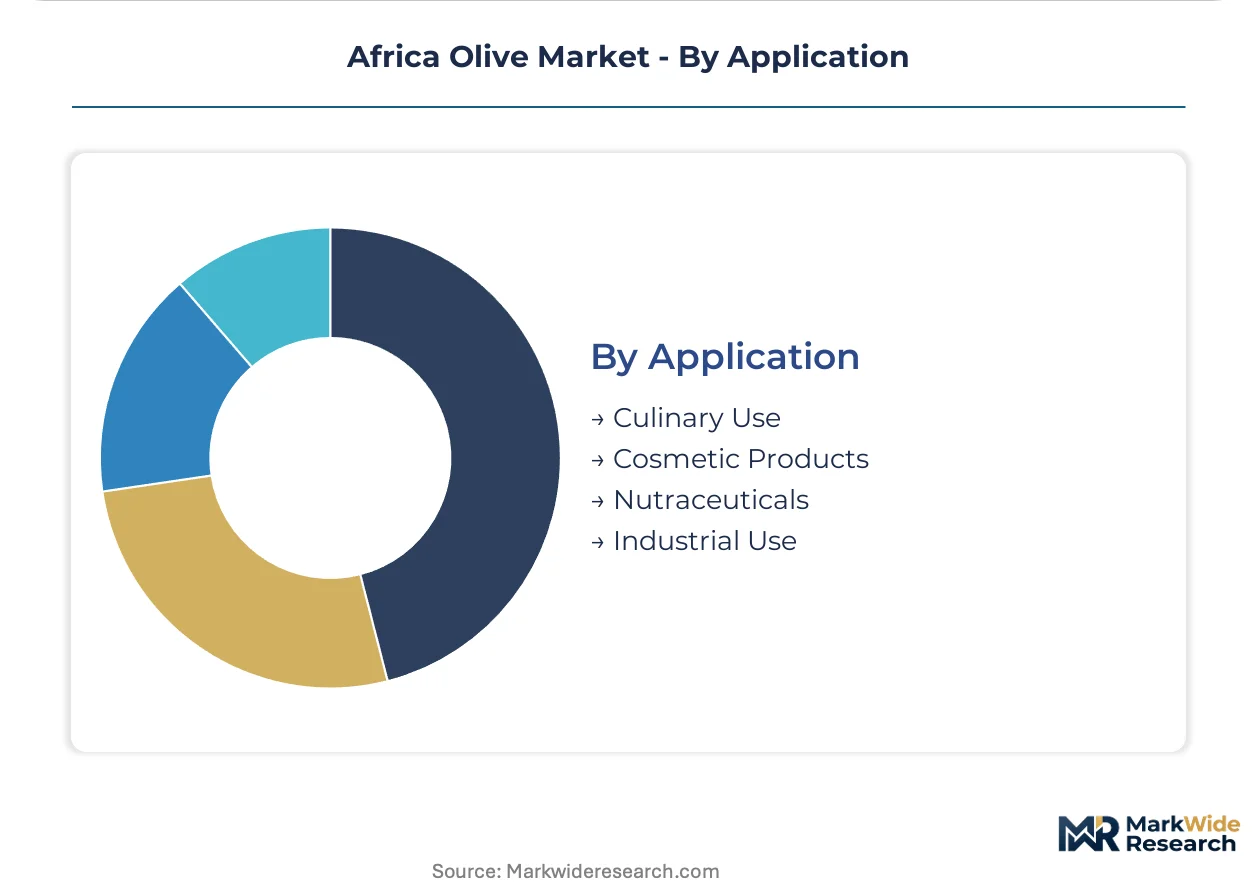
Application:
Application segmentation tracks value migration from commodity culinary consumption toward functional ingredient extraction, with regulatory frameworks diverging sharply by end-use.
- Culinary Use:Direct consumption across frying, dressing, and preservation applications absorbs the majority of African olive oil output, with extra virgin grades commanding household premium positioning.
- Cosmetic Products:Squalene and polyphenol extraction for skincare formulation targets European and Gulf beauty markets with ingredient-grade specifications exceeding food safety thresholds.
- Nutraceuticals:Antioxidant concentrate production for supplement encapsulation requires laboratory-verified polyphenol content documentation.
- Industrial Use:Pomace oil feeds regional soap manufacturing and lubricant blending with minimal processing investment.
Culinary Use anchors volume throughput; Cosmetic Products shows the steepest value-per-kilogram trajectory as functional ingredient demand climbs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tunisia ships bulk extra virgin consignments to Italian and Spanish refiners, while Morocco's estate producers target European specialty retail through geographic indication credentials. Egyptian operators balance domestic food service absorption with residual export volumes.
Morocco
Casablanca-based hospitality chains now contract cold-pressed extra virgin with documented origin for menu marketing. The Ministry of Agriculture enforces geographic indication standards and maximum residue limits that shape EU export eligibility. Drip irrigation deployment in the Marrakech-Safi cultivation basin is lifting per-hectare oil yields while reducing water input volatility.
Tunisia
Bulk refining channels into European Union markets sustain the majority of national export revenue. EFSA-aligned contaminant thresholds and REACH compliance determine market access for unbranded oil shipments. The Sfax port corridor concentrates tanker loading infrastructure serving Italian and Spanish refiners with certified-origin consignments.
Egypt
Food service expansion across Cairo and Alexandria is absorbing growing volumes of packaged extra virgin grades. The national food safety regulator enforces maximum residue limits that parallel EU import requirements. Cultivation clusters in the Nile Delta support both domestic canning operations and residual bulk shipments to Middle Eastern buyers.
South Africa
Domestic retail channels in Johannesburg and Cape Town absorb estate-grown premium grades for health-positioned positioning. Agricultural product standards and labeling requirements shape supermarket procurement specifications. The Western Cape olive belt concentrates on-site pressing infrastructure that anchors premium positioning without export scale.
Algeria
State-led irrigation investment in the Aurès Mountains and Tlemcen highlands is expanding cultivated hectarage for import substitution. The national agricultural development agency channels subsidies toward modern milling equipment adoption. Kabylie region cooperatives are consolidating fragmented smallholder output to achieve volume thresholds for regional trade.
Africa Olive Market Competitive Environment
Channel-controlling players compete with product-specialist players across three discernible tiers. Integrated estate operators with captive milling and bottling infrastructure sit at the premium vector, while bulk refining specialists dominate commodity flow into European processing channels. Cooperative associations and regional canning operators occupy a fragmented mid-tier serving domestic retail and food service. Competitive moves concentrate on certification acquisition for EU deforestation regulation compliance and drip irrigation deployment for yield stabilization.
Within the integrated estate tier, Willow Creek Olive Estate and CHO Group exemplify geographic indication positioning through on-site pressing and origin documentation. Med Oil Company occupies the bulk export channel, anchoring commodity flow into European refining networks. Al Wadi Al Akhdar and Egypt Olive Company represent food service and retail channel specialists navigating certified laboratory partnerships for contaminant threshold compliance.
| Leading Market Players |
|---|
| Willow Creek Olive Estate |
| Cape Olive Holdings |
| Olivko |
| Lesieur Cristal |
| CHO Group |
| Société Tunisienne de l'Industrie de Raffinage |
| Med Oil Company |
| Al Wadi Al Akhdar |
| Egypt Olive Company |
| Others |
Value Chain & Pricing Dynamics
The Sfax port corridor concentrates Tunisian bulk oil loading capacity that feeds European refiners, creating asymmetric pricing power where single-buyer concentration in Italian and Spanish processing channels compresses margins for uncertified shipments while rewarding Moroccan estate producers with geographic indication credentials.
Pricing Analysis
Cold-pressing technology separates artisanal-grade pricing from industrial-scale output, with extra virgin grades commanding premium positioning against refined-virgin blends and pomace oil tiers. Price differentiation rests on certification level—EFSA-aligned contaminant thresholds versus uncertified bulk—and volume scale, where estate producers capture brand premiums against cooperative bulk shipments. Pricing pressure intensifies in pure olive oil segments as sunflower and soybean oils undercut olive oil in price-sensitive North African retail channels. Food service buyers show least price sensitivity, prioritizing documented origin for menu marketing over cost minimization.
Supply Chain Analysis
EU deforestation regulation traceability requirements now restrict market access for African olive exporters lacking geolocation documentation, forcing supply chain reconstruction from orchard to port. Geographic supply concentration centers on Tunisia, Morocco, and Egypt, where cultivation clusters support export-oriented processing infrastructure. Raw material dependencies include irrigation water allocation, fertilizer inputs, and cold-pressing equipment maintenance capacity. Single-source vulnerability runs through European refining dependence that exposes Tunisian bulk exporters to buyer concentration risk. Distribution runs through supermarket chains in Casablanca and Cairo, tanker shipments via Sfax, and emerging e-commerce channels in West African urban markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Blockchain-enabled traceability platforms are restructuring procurement relationships across North African olive supply chains, with interoperability between farm-management software and export documentation systems creating network effects that favor early standardization adopters.
For Market Incumbents: Build certification moats through EU deforestation regulation compliance investments that lock in European market access before audit infrastructure bottlenecks harden. Integrate backward into drip irrigation deployment across Moroccan cultivation basins to stabilize yield volatility against fertilizer price swings. Channel control through contracted estate supply agreements with Cairo and Casablanca hospitality chains defends margin position against spot-market commoditization.
For New Entrants and Emerging Players: Build out direct-to-consumer e-commerce infrastructure targeting Nigerian and Ghanaian urban markets where packaged extra virgin penetration remains minimal and brand loyalty is unformed. White-space opportunity concentrates in cosmetic-grade polyphenol extraction for Gulf beauty markets, where ingredient specifications exceed food safety thresholds and competition from established estate producers is attenuated. Go-to-market leverage rests on near-infrared spectroscopy quality verification as a trust-building mechanism for quality-assured shipments.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated estate operators with captive milling and multi-year hospitality supply contracts that reduce spot-market exposure. Long-term viability across the projection horizon favors targets with geographic indication credentials and satellite-verified orchard mapping already completed. The signal to watch is consolidation velocity among Tunisian cooperatives as EU documentation deadlines compress uncertified operators toward certified estate block aggregation.
| Strategic Initiative | Industry Significance |
|---|---|
| Geographic Indication Certification | Morocco's Ministry of Agriculture standards unlock European specialty retail placement for estate producers. |
| Blockchain Traceability Integration | Real-time quality verification meets EU deforestation regulation documentation requirements for export eligibility. |
| Drip Irrigation Deployment | Precision water systems in Marrakech-Safi basin lift per-hectare yields while reducing input cost volatility. |
| Food Service Contracting | Cairo and Casablanca hospitality chains now specify cold-pressed extra virgin with documented origin as procurement standard. |
| Cosmetic Ingredient Extraction | Polyphenol and squalene recovery for Gulf beauty markets commands value-per-kilogram premiums above culinary grades. |
Study Parameters
Desk research of customs trade records, EFSA contaminant threshold documentation, and national agricultural ministry filings preceded structured interviews with olive mill operations managers, export logistics coordinators, European refining procurement leads, and food service category buyers across North African markets. Primary fieldwork combined with secondary validation from trade association publications and irrigation technology supplier disclosures enabled bottom-up cultivation yield modeling and top-down export volume triangulation.
Forecast assumptions held EU deforestation regulation implementation timelines and REACH-aligned contaminant standards fixed while varying fertilizer price trajectories, hospitality sector growth rates, and West African retail channel penetration speeds across the analysis window. Segmentation dimensions modeled include product grade tier, distribution channel structure, end-user procurement sophistication, and application value intensity. CAGRs were derived from production capacity buildout schedules, per-hectare yield improvement curves, and price elasticity estimates for substitution-threatened retail segments.
Stress conditions across irrigation water allocation policy shifts, European buyer concentration changes, and sunflower oil price volatility were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions and risk factor weightings. Material shifts in EU traceability documentation deadlines or Moroccan geographic indication enforcement intensity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Asia-Pacific Animal Protein Market
Agriculture and Agri Products
United States Compound Feed Market
Agriculture and Agri Products
Spain Compound Feed Market
Agriculture and Agri Products
Alfalfa Protein Concentrate Market
Agriculture and Agri Products
Animal Feed Market
Agriculture and Agri Products
Frozen Egg Market
Agriculture and Agri Products
Feed Grade Oils Market
Agriculture and Agri Products
Global Ruminant Feed Market
Agriculture and Agri Products
Brazil Rice Market
Agriculture and Agri Products
Asia-Pacific Compound Feed Market
Agriculture and Agri Products
Germany Compound Feed Market
Agriculture and Agri Products
Non GMO Soybean Market
Agriculture and Agri Products
Animal Feed Ingredients Market
Agriculture and Agri Products
Canada Compound Feed Market
Agriculture and Agri Products
Indonesia Bamboos Market
Agriculture and Agri Products
African Swine Feed Market