
 United States Floriculture Market | 2026-2036
United States Floriculture Market Size, Share, and Industry Trends Forecast 2026-2036
United States Floriculture Market Analytics
USDA Organic certification is rotating the competitive landscape by filtering out smaller soil-based growers who cannot absorb compliance and record-keeping burdens. Costa Farms leverages its scale across multiple state operations to spread certification costs efficiently. Ball Horticultural Company anchors its position through intensive R&D in cultivar development and disease resistance. Monrovia Nursery Company differentiates via branded container programs and controlled-environment production systems that meet exacting retail specifications.
United States Floriculture encompasses the commercial cultivation, propagation, and distribution of ornamental plants including cut flowers, potted specimens, bedding plants, and foliage varieties, typically grown under controlled light, temperature, and humidity parameters to optimize bloom timing and shelf stability. The sector serves aesthetic and environmental remediation purposes across residential, commercial, and ceremonial applications. Cut flowers command premium logistics infrastructure due to perishability and cold-chain requirements, while potted plants generate recurring volume through big-box retail partnerships. Hydroponic growing methods are gaining structural share in regions facing water allocation constraints or soil-borne disease pressure.
FDA oversight of agricultural chemical residues, EPA regulation of pesticide applications under FIFRA, and state-level departments of agriculture inspection protocols collectively shape product marketability and interstate shipment eligibility. Organic certification through USDA-accredited agents creates price-tier separation that rewards capital-intensive conversion investments. Stakeholders must monitor evolving water rights adjudication in western production zones and assess whether controlled-environment expansion justifies energy cost exposure against climate risk mitigation benefits.
Market Dynamics
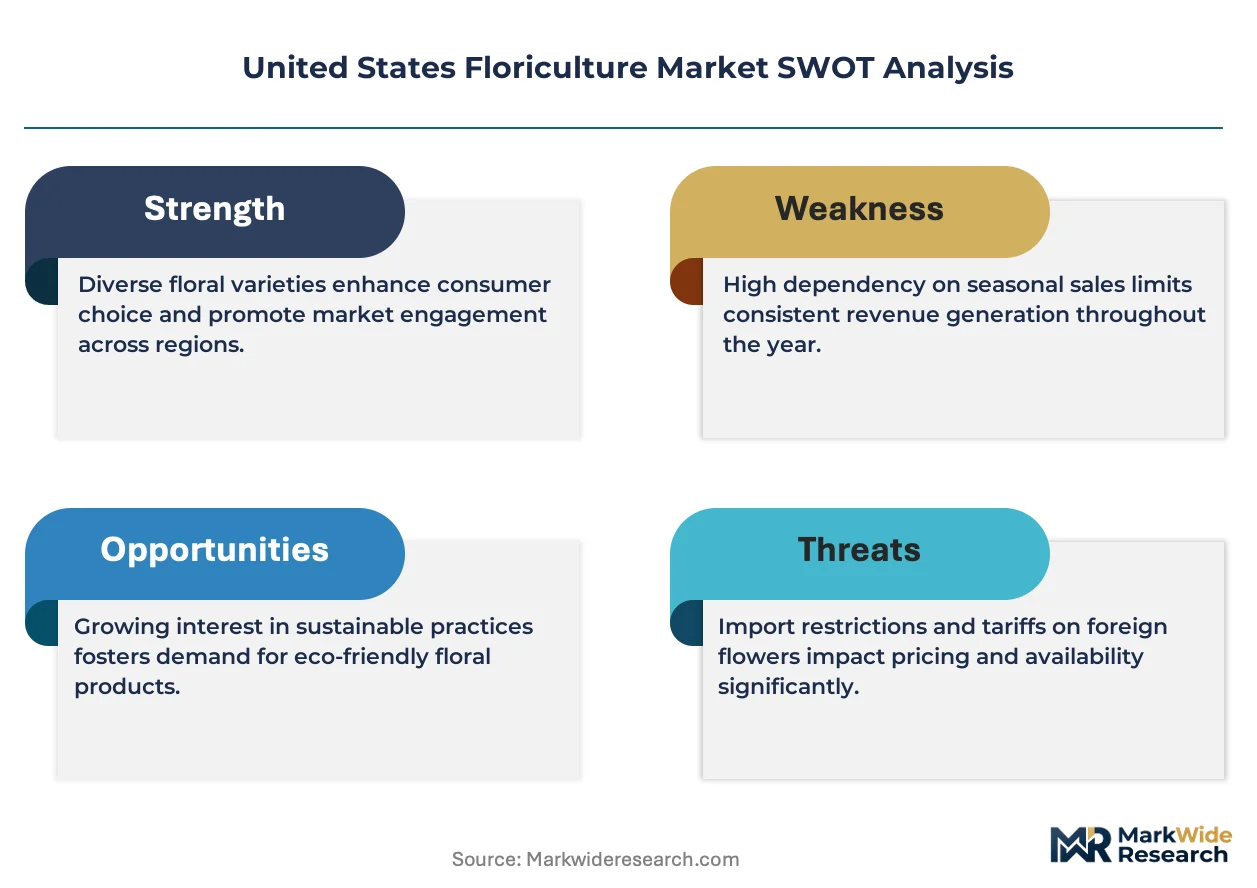
USDA organic certification requirements are filtering out smaller soil-based growers who cannot absorb compliance and record-keeping burdens, concentrating production among capital-intensive operations with multi-state footprints.
Growth Catalysts
- EPA FIFRA pesticide frameworks:State-level departments of agriculture are tightening inspection protocols, creating competitive separation for growers with established compliance infrastructure.
- Commercial interior plant programs:Corporate campuses and hospitality chains are expanding living wall installations and biophilic design specifications faster than residential segments.
- Hydroponic propagation methods:Water allocation constraints in California's Central Valley are pushing adoption of soilless systems that reduce disease pressure and optimize nutrient delivery.
Market Restraints
- Energy cost exposure:Controlled-environment agriculture requires substantial electricity for lighting and climate control, compressing margins when utility rates spike.
- Perishability infrastructure:Cut flowers demand specialized cold-chain logistics that limit distribution radius and concentrate supply near coastal freight hubs.
- Organic conversion timelines:USDA-accredited certification requires three-year transition periods that lock land out of premium pricing during soil remediation.
Strategic Opportunities
- Florida Gulf Coast expansion:Subtropical climate and established nursery infrastructure offer year-round production capacity for potted foliage varieties.
- Big-box retail partnerships:Recurring volume contracts with home improvement chains provide demand visibility that justifies greenhouse capital deployment.
- Biophilic workplace mandates:Corporate wellness programs are codifying indoor plant requirements into building standards and lease agreements.
Industry Challenges
- Horticultural technician shortage:Controlled-environment systems require specialized expertise in integrated pest management and climate automation that outpaces vocational training pipelines.
- Legacy soil-borne pathogen remediation:Fusarium and Pythium outbreaks in established growing regions force costly substrate replacement and facility sterilization protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Floriculture Market |
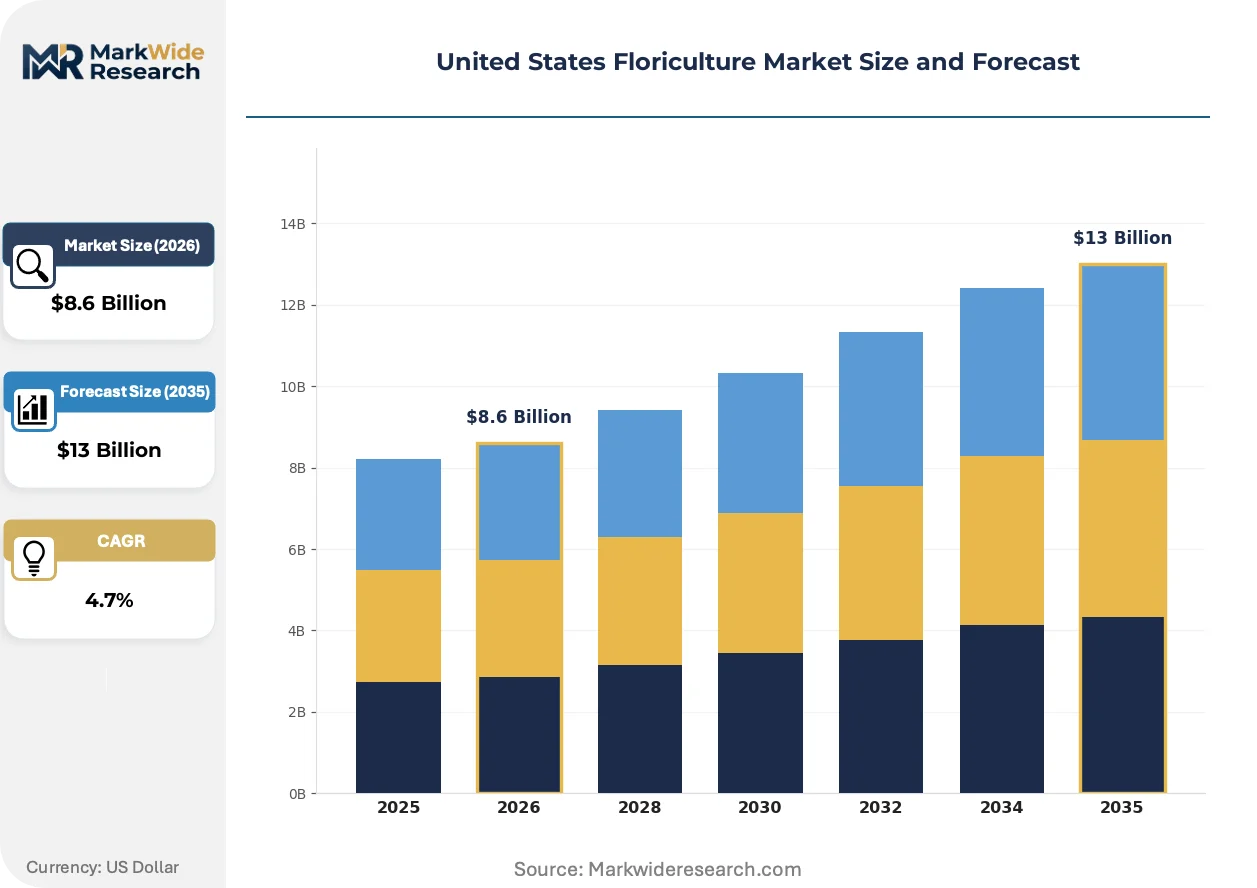
| Market Size in 2026 | $8.6 Billion |
| Market Size in 2035 | $13 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cut Flowers, Potted Plants, Bedding Plants, Foliage Plants Sales Channel: Wholesale, Retail, Online, Direct Sales End User: Households, Commercial Establishments, Event Planners, Florists Growing Method: Soil-Based, Hydroponics, Aquaponics, Organic |
| Companies Covered | Kurt Weiss Greenhouses, Inc., Costa Farms, Monrovia Nursery Company, Green Circle Growers, Sun Valley Floral Farms, Terra Nova Nurseries, Inc., Ball Horticultural Company, Greenheart Farms, The Queen’s Flowers, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Floriculture Market Evolving Landscape
LED spectral tuning and substrate automation are compressing production cycles while regulatory pressure on chemical inputs accelerates biological control adoption across propagation facilities.
Spectral-specific LED arrays are fragmenting the traditional greenhouse lighting market by enabling wavelength-optimized growth protocols for different crop stages. Large-scale bedding plant producers are retrofitting high-pressure sodium systems with tunable diodes to compress flowering schedules. This technology is fragmenting regional production calendars by allowing northern facilities to match southern photoperiod advantages.
USDA organic certification through accredited state agencies is creating price-tier separation that rewards capital-intensive conversion investments. The three-year land transition requirement is compressing available organic supply and widening premiums for certified product. California's Central Valley growers are responding by consolidating acreage to spread compliance costs across larger certified blocks.
Corporate procurement departments are consolidating vendor relationships for interior plant maintenance contracts, displacing fragmented local service providers with national facility management platforms. Hospitality chains and commercial real estate operators are bundling design, installation, and replacement services into multi-year agreements. This consolidation is most visible in urban office markets where standardized service levels override local supplier relationships.
United States Floriculture Market Segmentation
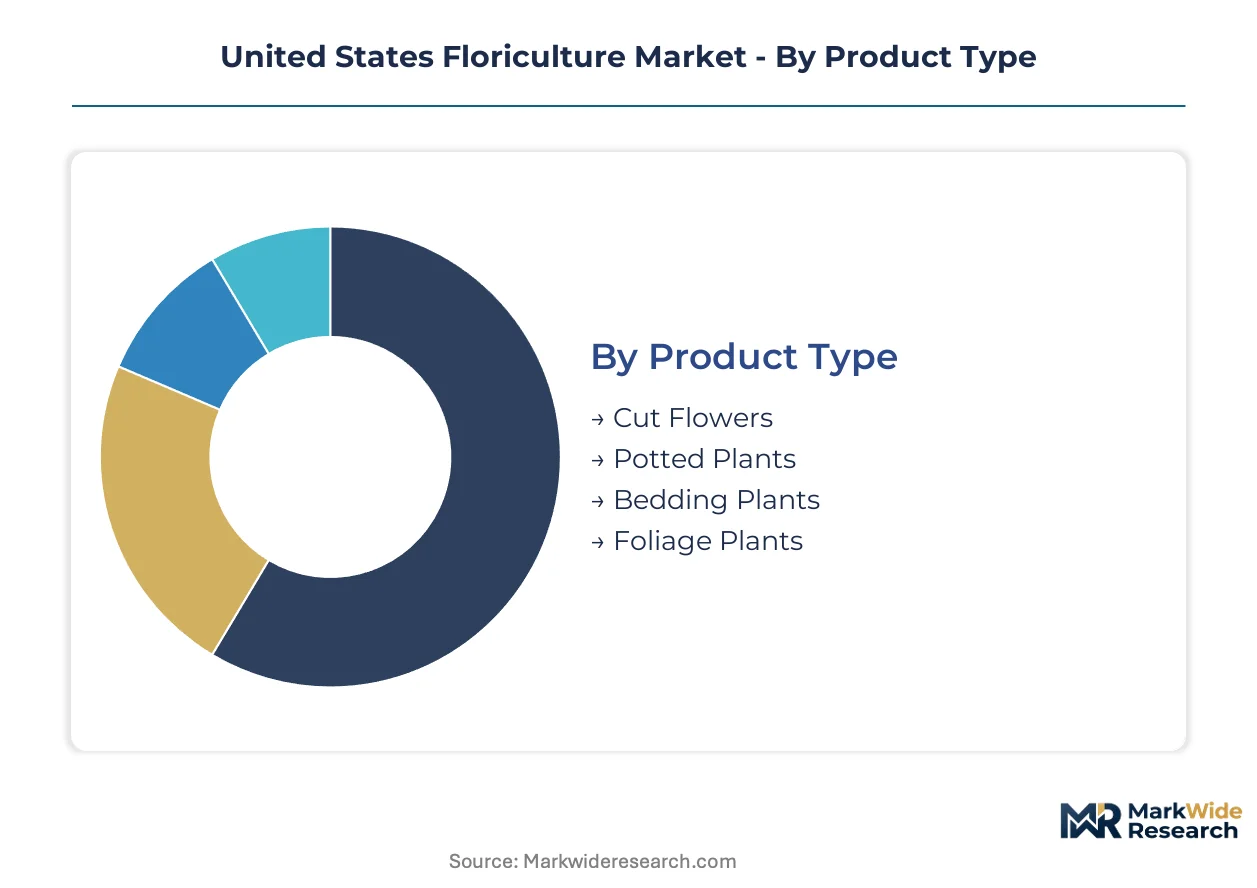
Floriculture segmentation reveals distinct channel economics where perishability dictates logistics infrastructure and margin profiles vary sharply by production method. Understanding these structural divisions exposes where capital deployment earns superior returns versus commodity exposure.
Product Type:
Channel mix diverges sharply: cut flowers flow through wholesale auction houses and event procurement, while potted plants anchor big-box retail partnerships with recurring volume contracts.
- Cut Flowers:Roses, lilies, and chrysanthemums require specialized cold-chain logistics from field to vase. Demand concentrates in California's coastal clusters serving Los Angeles and San Francisco event markets, where perishability compresses distribution radius and rewards proximity to freight hubs.
- Potted Plants:Orchids, succulents, and seasonal specimens generate recurring volume through Home Depot and Lowe's national programs. Florida's Gulf Coast nurseries supply year-round inventory, with propagation cycles tuned to retail promotional calendars.
- Bedding Plants:Annuals and vegetable starters for residential gardens.
- Foliage Plants:Interior specimens including ferns and tropical varieties for commercial biophilic installations.
Cut flowers dominate installed base. Potted plants is where expansion concentrates.
Sales Channel:
Cost tier stratification separates capital-intensive wholesale operations from fragmented retail service models.
- Wholesale:Auction houses and distribution centers consolidate supply from multiple growers for downstream resale. Miami's flower district and Los Angeles terminal markets handle volume aggregation, with USDA inspection protocols governing interstate shipment eligibility.
- Retail:Garden centers and grocery floral departments serve immediate consumption needs. California's Central Valley growers bypass wholesale layers through direct store delivery arrangements with Safeway and Kroger regional divisions.
- Online:Subscription services and direct-to-consumer platforms.
- Direct Sales:Wedding planners and corporate accounts sourcing straight from propagation facilities.
Wholesale channels dominate installed base. Online is where expansion concentrates.
End User:
Application focus separates aesthetic consumption from environmental remediation mandates.
- Commercial Establishments:Corporate campuses, hotels, and healthcare facilities deploy living walls and interior plant programs for wellness certification points. CBRE and JLL facility management platforms consolidate vendor relationships across multi-site portfolios, displacing fragmented local service providers.
- Households:Residential consumers purchase through seasonal peaks. Texas and Florida metropolitan areas show strongest per-capita spending on ornamental specimens, with millennial homebuyers driving demand for low-maintenance succulents.
- Event Planners:Weddings and corporate functions requiring temporary installations.
- Florists:Independent shops assembling custom arrangements from wholesale supply.
Households dominate installed base. Commercial establishments is where expansion concentrates.
Growing Method:
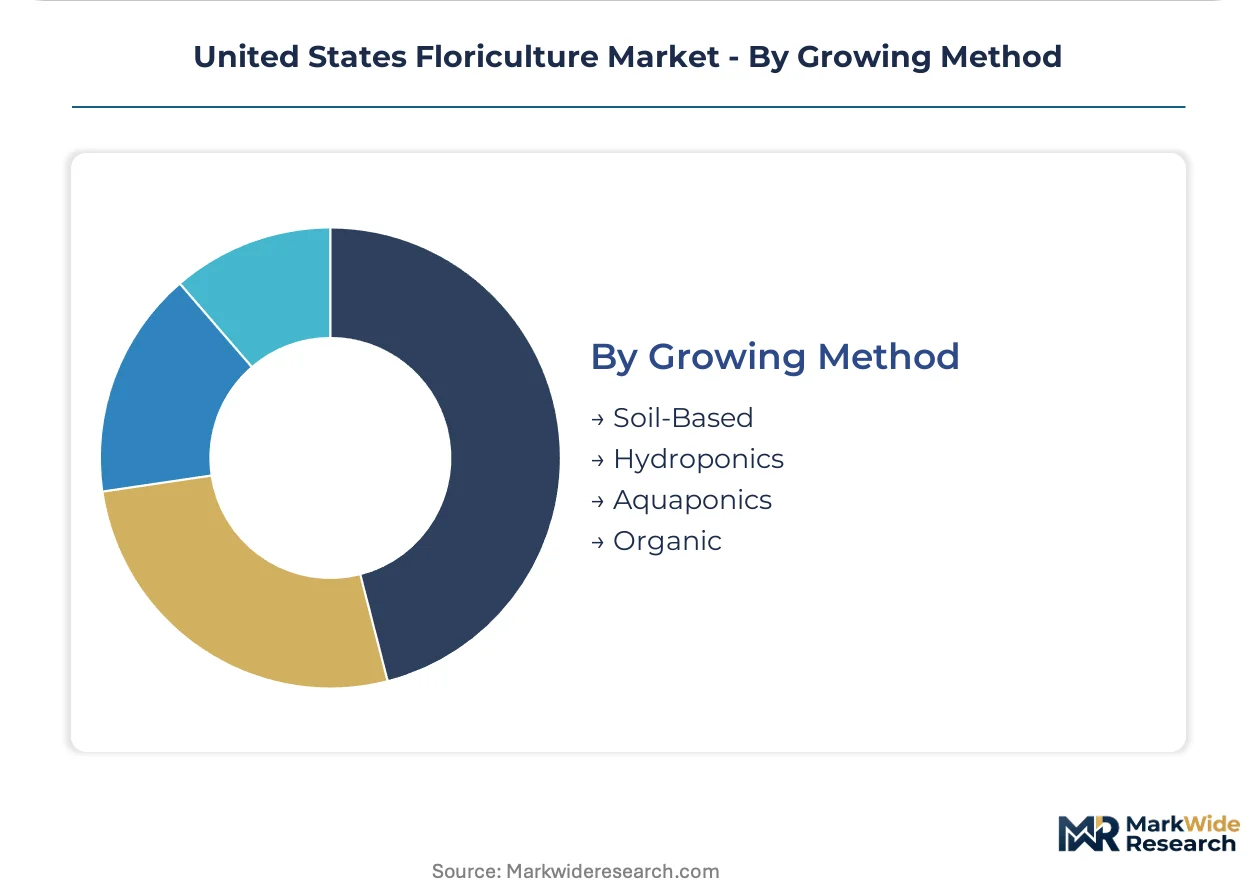
Margin structure separates certified organic premium capture from input-intensive conventional production.
- Organic:USDA-accredited certification requires three-year land transition and exhaustive record-keeping. California growers consolidate acreage to spread compliance costs, with certified product commanding shelf price separation at Whole Foods and regional co-ops.
- Hydroponics:Soilless systems recirculate nutrient solutions in controlled environments. Arizona and Nevada operations adopt these methods to circumvent water allocation constraints, with substrate automation reducing labor exposure.
- Soil-Based:Traditional field and greenhouse production using amended native substrates.
- Aquaponics:Integrated fish-plant systems using nutrient-rich effluent for propagation.
Soil-based methods dominate installed base. Hydroponics is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
USDA organic certification incentives and state-level water conservation programs are redistributing production capacity toward regions with favorable regulatory environments and established nursery infrastructure. Capital deployment follows these policy signals.
California
Central Valley growers dominate cut flower and bedding plant supply chains, leveraging proximity to Los Angeles and San Francisco wholesale markets. State Water Resources Control Board allocation restrictions accelerate hydroponic conversion in Fresno and Kern counties. Monterey Bay area operations specialize in high-value organic certification for premium retail channels.
Florida
Gulf Coast nurseries supply year-round potted foliage to national big-box programs, with subtropical climate eliminating heating costs. Florida Department of Agriculture and Consumer Services enforces strict plant health inspection protocols for interstate shipment eligibility. Miami-Dade and Orange County clusters concentrate propagation facilities serving eastern seaboard distribution.
Texas
Metropolitan Houston and Dallas-Fort Worth drive residential demand for low-maintenance succulents and seasonal color. Texas A&M AgriLife Extension provides grower education on integrated pest management compliance. Rio Grande Valley operations exploit extended growing seasons for early spring bedding plant production.
Ohio
Green Circle Growers anchors regional greenhouse capacity near Oberlin, supplying Midwest retail chains through direct store delivery networks. Ohio Department of Agriculture nursery inspection programs govern certification for shipment to neighboring states. Lake Erie climate moderates energy exposure for controlled-environment production.
New York
Long Island and Hudson Valley operations serve metropolitan event markets and corporate interior plant programs. New York State Department of Agriculture and Markets regulates pesticide application near watershed protection zones. Brooklyn and Queens urban agriculture initiatives experiment with vertical production for local consumption.
United States Floriculture Market Competitive Landscape
Listed greenhouse operators compete with multi-generational family nurseries across certification compliance and retail contract access. Market structure tilts toward scale-driven consolidation as three-year organic transition timelines filter marginal participants. Strategic archetypes separate vertically integrated propagators, branded container specialists, and regional wholesale distributors. Dominant competitive moves include multi-state certification spreading and controlled-environment capacity expansion.
Within the scale-driven tier, Costa Farms and Ball Horticultural Company exemplify operational footprints spanning multiple climate zones. Monrovia Nursery Company occupies a differentiated position through branded container programs. Kurt Weiss Greenhouses, Inc. represents regional concentration in the Northeast corridor. These anchors illustrate how capital intensity and certification infrastructure separate sustainable competitive positions from commodity exposure.
| Leading Market Players |
|---|
| Kurt Weiss Greenhouses, Inc. |
| Costa Farms |
| Monrovia Nursery Company |
| Green Circle Growers |
| Sun Valley Floral Farms |
| Terra Nova Nurseries, Inc. |
| Ball Horticultural Company |
| Greenheart Farms |
| The Queen's Flowers |
| Others |
Value Network & Pricing Analysis
Recurring volume contracts with home improvement chains lock in both supply access and price visibility for large-scale propagators, insulating them from spot-market volatility while compressing margins for smaller growers excluded from national programs. California's Central Valley and Florida's Gulf Coast production clusters concentrate supply power, enabling certified organic producers to command shelf price separation at premium retail channels.
Pricing Analysis
Certification level creates the primary spread between conventional and USDA organic tiers, with three-year transition timelines compressing certified supply and widening premiums. Pricing stratifies across organic, hydroponic, and soil-based production methods, with energy-intensive controlled-environment operations facing margin pressure from utility rate spikes. Residential consumers through big-box retail show highest price sensitivity, while corporate interior plant programs prioritize service reliability over unit cost.
Supply Chain Analysis
Cold-chain logistics capacity at Miami's flower district and Los Angeles terminal markets serves as the critical chokepoint for cut flower distribution, limiting viable supply radius from coastal production clusters. The United States floriculture supply chain draws from California's Central Valley, Florida's Gulf Coast, and Ohio's greenhouse corridors, with propagation facilities clustered near freight hubs to minimize perishability exposure. Single-source vulnerability concentrates in specialized substrate suppliers and biological control agent providers. Distribution runs through wholesale auction houses consolidating multi-grower supply for downstream retail and event procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across local service providers creates acquisition opportunities as corporate facility management platforms consolidate vendor relationships for interior plant programs. Biophilic design mandates in commercial real estate are spawning specialized niches for certified organic propagation and living wall installation expertise.
For Market Incumbents: Compound market position through multi-state organic certification spreading and controlled-environment capacity expansion in water-constrained regions. Acquire regional wholesale distributors to secure downstream channel control against emerging hydroponic specialists. Prioritize R&D investment in disease-resistant cultivars to reduce biological control costs. For New Entrants and Emerging Players: Differentiate on USDA organic certification and localized production for urban agriculture initiatives in Brooklyn, Queens, and other dense metropolitan markets. Target the corporate interior plant maintenance segment, where fragmented local service providers face displacement from national facility management platforms. Pursue direct procurement relationships with hospitality chains and healthcare systems bypassing wholesale layers. For Investors and Strategic Acquirers: Capital is best deployed toward mid-scale propagators with established organic certification infrastructure and big-box retail contract access across the analysis window. Acquisition targets should demonstrate multi-state production footprints capable of spreading compliance costs. Monitor water rights adjudication outcomes in western production zones as inflection indicators for regional competitive positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-State Organic Certification | Spreads USDA compliance costs across larger certified blocks, filtering smaller soil-based competitors from premium channels. |
| Controlled-Environment Capacity Expansion | Mitigates climate risk and water allocation constraints in California's Central Valley production clusters. |
| Big-Box Retail Partnership Consolidation | Locks in recurring volume visibility that justifies greenhouse capital deployment against spot-market exposure. |
| Biological Control Agent Integration | Reduces chemical input dependency as EPA FIFRA frameworks tighten pesticide application protocols. |
| Corporate Facility Management Integration | Captures living wall installation and maintenance contracts as CBRE and JLL platforms displace local providers. |
Research Methodology
Desk research of USDA agricultural census data, EPA pesticide application records, and state water resource board allocation filings preceded structured interviews with greenhouse operations managers, big-box retail category buyers, commercial facility management procurement leads, and biological control system suppliers. Primary fieldwork with propagation facility directors and wholesale distribution operators was cross-validated against secondary trade association reports and customs records for substrate and equipment imports. Bottom-up grower capacity estimates were triangulated against top-down retail channel volume data.
Variance in projected outcomes was decomposed across product type, growing method, sales channel, and end-user application dimensions throughout the forecast period. CAGRs were derived from segment-level growth trajectory modeling incorporating input cost inflation assumptions and regulatory compliance burden estimates. Forecast inputs included water rights adjudication timelines, energy price scenario pathways, and corporate biophilic design adoption curves.
Material uncertainties — drought severity in western production zones, EPA FIFRA enforcement intensity, and corporate wellness program budget allocations — sit outside the modeled envelope. Forecasts reflect assumptions about certification transition timelines and cold-chain infrastructure investment continuity. Practitioners should keep alternative scenarios live as water resource control board rulings and utility rate restructuring evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Netherlands Floriculture Market
Agriculture and Agri Products
Germany Compound Feed Market
Agriculture and Agri Products
North America Hemp Market
Agriculture and Agri Products
Plant Breeding Market
Agriculture and Agri Products
Rapeseed Oil Market
Agriculture and Agri Products
France Alfalfa Hay Market
Agriculture and Agri Products
US Greenhouse Horticulture Market
Agriculture and Agri Products
Taro Market
Agriculture and Agri Products
Flower and Ornamental Plants Market
Agriculture and Agri Products
Australia Compound Feed Market
Agriculture and Agri Products
Poultry Fat Market
Agriculture and Agri Products
Mushroom Substrate Market
Agriculture and Agri Products
Forage Feed Market
Agriculture and Agri Products
Saudi Arabia Agriculture Market
Agriculture and Agri Products
Saudi Arabia Alfalfa Market
Agriculture and Agri Products
Corn Co-Products Market