
 Seaweed Algae Market | 2026-2036
Seaweed Algae Market Size, Share, and Industry Trends Forecast 2026-2036
Seaweed Algae Market Analytics
Multi-source procurement across wild harvest and aquaculture operations is consolidating as processors seek supply security. Cargill, Incorporated leverages its global commodity infrastructure to secure bulk kelp volumes from Atlantic and Pacific suppliers. DSM-Firmenich anchors its position through carrageenan and alginate extraction technologies for pharmaceutical and nutraceutical applications. Qingdao Bright Moon Seaweed Group Co., Ltd. dominates coastal cultivation zones in Shandong Province with integrated drying and refining facilities.
Seaweed algae comprises macroscopic marine organisms rich in polysaccharides such as alginate, carrageenan, and agar, typically harvested from intertidal zones or cultivated on submerged long-line systems for hydrocolloid extraction, human consumption, and soil amendment applications. Kelp leads product type volume due to its scale in Chinese aquaculture and established food additive demand, while nori sustains premium pricing through sushi-grade quality tiers in Japanese and Korean supply chains. Biofuel application remains nascent but attracts R&D investment from energy majors seeking marine biomass feedstocks with lower land-use competition than terrestrial crops.
The EU Green Deal and F-Gas Regulation restrict synthetic fertilizer and refrigerant use, redirecting agricultural and industrial buyers toward seaweed-derived biostimulants and natural hydrocolloids. China's SAMR enforces GB standards on heavy metal limits in edible seaweed, conditioning export access for Indonesian and Philippine suppliers. EFSA novel food assessments govern European market entry for emerging species, creating compliance bottlenecks that favor established processors with regulatory affairs capacity. Stakeholders must monitor carbon credit eligibility for seaweed farming under evolving national blue carbon frameworks.
Market Dynamics
EU F-Gas Regulation and China's dual carbon goals are compressing synthetic chemical demand while redirecting agricultural and industrial buyers toward seaweed-derived biostimulants and natural hydrocolloids. This regulatory pivot is restructuring procurement priorities across food, pharma, and farming sectors.
Growth Catalysts
- EU Green Deal agricultural mandates:Synthetic fertilizer restrictions under the Farm to Fork Strategy redirect European farmers toward seaweed-based biostimulants for soil amendment and crop nutrition.
- Plant-based protein formulation:Food manufacturers integrate kelp-derived hydrocolloids into meat analogues and dairy alternatives to improve texture and binding properties.
- Shandong-Indonesia cultivation corridors:Integrated drying and refining infrastructure along China's Yellow Sea coast and Sulawesi's macroalgae zones secure year-round supply for hydrocolloid processors.
Market Restraints
- Heavy metal bioaccumulation:Arsenic and cadmium uptake in wild-harvested species triggers GB standard rejections at China's SAMR border inspections, blocking Philippine and Indonesian export batches.
- Carrageenan substitution threat:Cellulose derivatives and microbial fermentation gums displace red seaweed extracts in cost-sensitive dairy and pet-food applications.
- Intertidal lease concentration:Coastal aquaculture permits cluster in Fujian and Jeollanam-do provinces, creating supply vulnerability during monsoon and red tide events.
Strategic Opportunities
- Biofuel feedstock valorization:Energy majors pilot kelp-to-ethanol pathways in Norwegian and Scottish waters, exploiting marine biomass yields that bypass terrestrial land-use competition.
- EFSA novel food pathway:Asparagopsis taxiformis and other emerging species await regulatory clearance for European human consumption, creating first-mover advantage for dossier-ready processors.
- Blue carbon credit monetization:National frameworks in Australia, Canada, and South Korea are developing certification standards for seaweed farm carbon sequestration.
Industry Challenges
- Phycocolloid extraction expertise gap:Specialized chemical engineers capable of optimizing alginate and agar yield rates remain scarce outside Qingdao, Tokyo, and Copenhagen technical clusters.
- EFSA dossier timeline compression:Novel food safety assessments require 18-36 months of toxicology and exposure data, straining smaller suppliers without dedicated regulatory affairs capacity.
- Long-line system capex intensity:Offshore cultivation infrastructure demands significant upfront investment in anchoring, flotation, and monitoring equipment before first harvest cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Seaweed Algae Market |
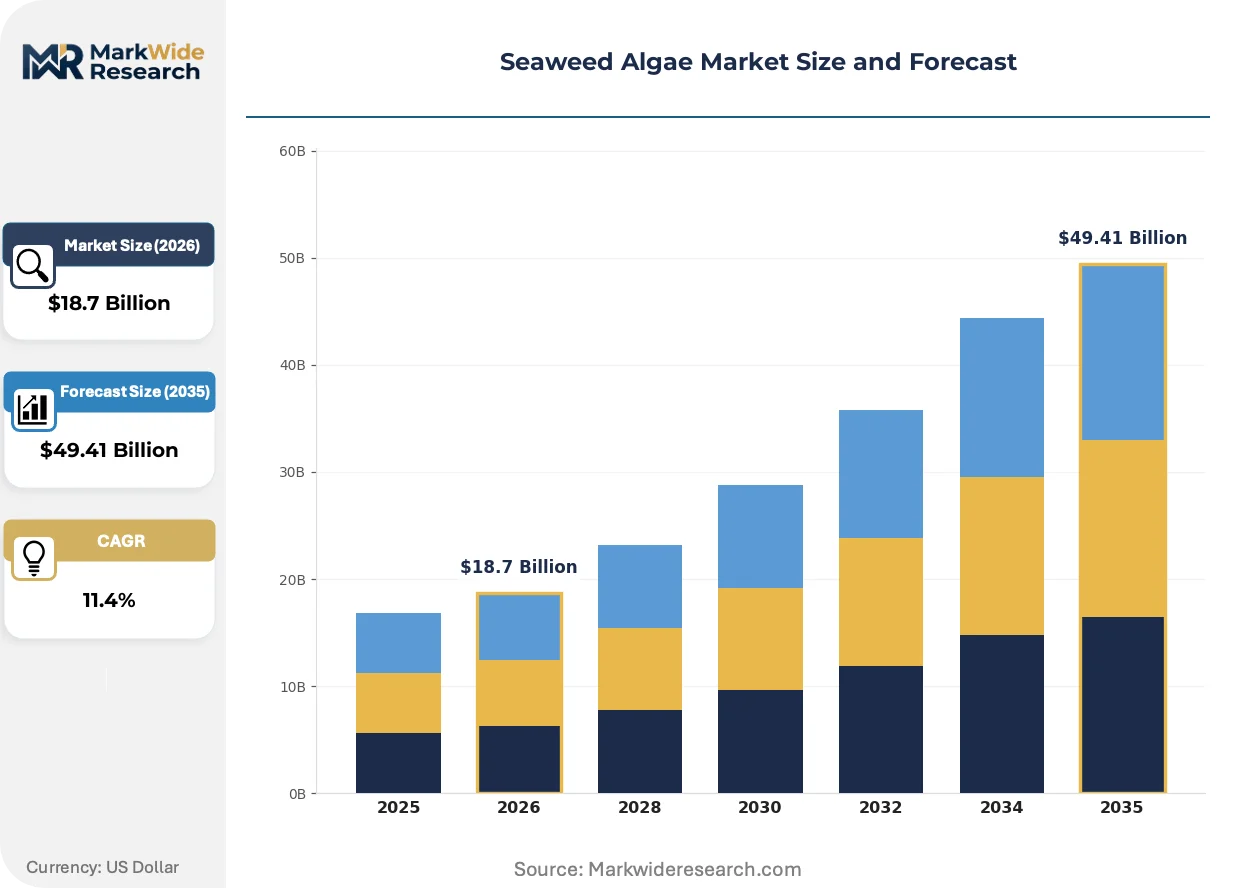
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Kelp, Dulse, Nori, Wakame Application: Food Additive, Biofuel, Cosmetics, Agriculture End User: Food Industry, Pharmaceutical Sector, Nutraceuticals, Personal Care Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesalers |
| Companies Covered | Cargill, Incorporated, CP Kelco U.S., Inc., DuPont de Nemours, Inc., Gelymar S.A., DSM-Firmenich, Acadian Seaplants Limited, Algaia S.A., Qingdao Bright Moon Seaweed Group Co., Ltd., Ceamsa, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Seaweed Algae Market Evolving Landscape
Biorefinery process intensification and offshore cultivation automation are compressing extraction costs while expanding viable production zones beyond sheltered coastal waters. These shifts are redrawing competitive boundaries between wild-harvest and aquaculture supply models.
Integrated biorefinery systems combining enzymatic hydrolysis with membrane filtration are rewriting extraction economics for high-value fucoidan and phlorotannin fractions. Pharmaceutical and nutraceutical formulators in Germany and Japan are adopting these outputs at pilot scale. The technology is compressing the premium that wild-harvested Irish and Norwegian kelp previously commanded for bioactive concentrates.
China's GB 19643-2016 edible seaweed heavy metal limits and SAMR enforcement protocols are reshaping export compliance architecture for Southeast Asian suppliers. Indonesian and Philippine processors must install in-house inductively coupled plasma mass spectrometry testing or lose supermarket channel access. The regulation is forcing consolidation among smaller dryers unable to absorb laboratory capital expenditure.
Direct contracting between food manufacturers and designated aquaculture zones is displacing spot-market procurement through commodity traders. Cargill and DSM-Firmenich are establishing offtake agreements with specific Shandong and Jeju Island farms, securing lot traceability for EFSA and FDA documentation. This pattern is most visible in European and North American hydrocolloid sourcing for infant formula and organic-labeled products.
Seaweed Algae Market Segmentation
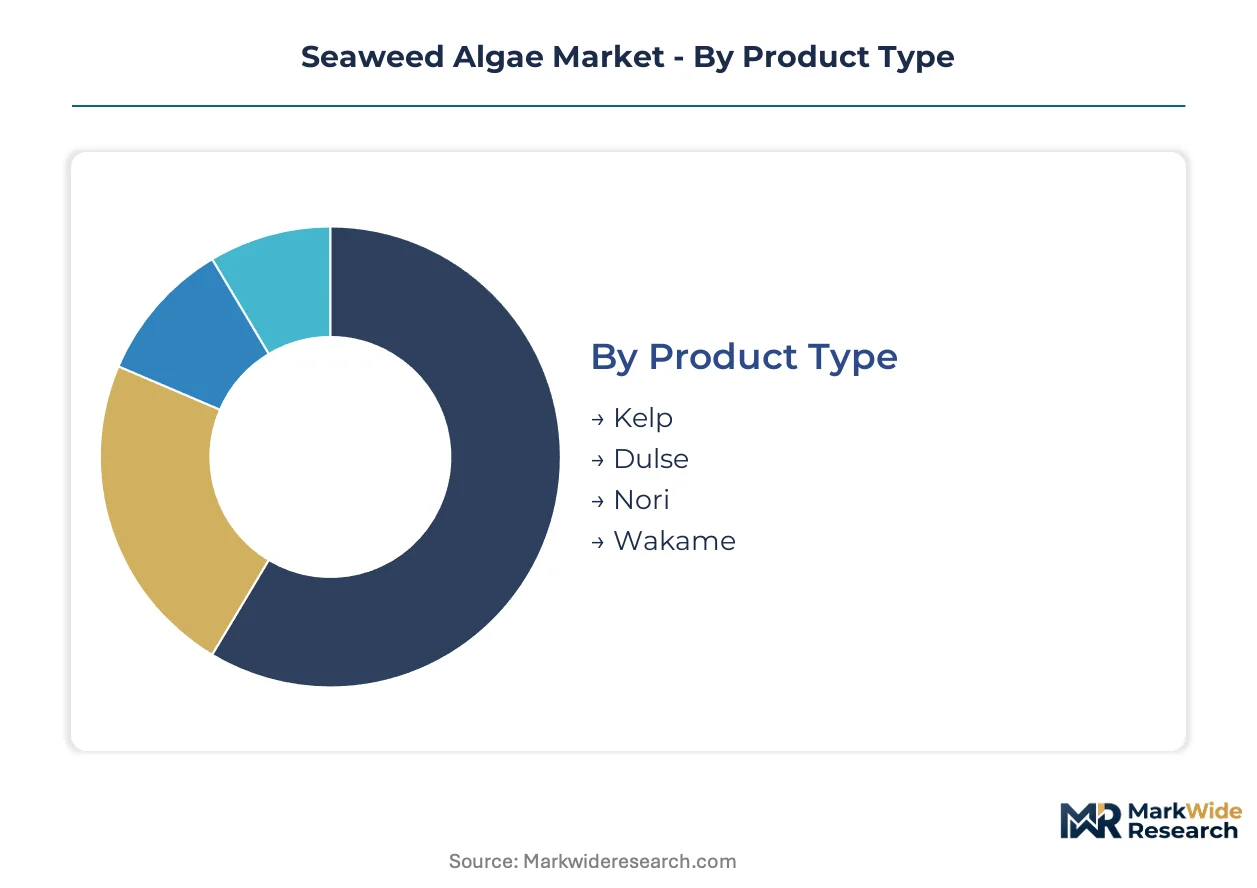
Seaweed algae markets fragment across cultivation biology, extraction chemistry, and end-use specifications. Each segmentation axis carries distinct margin profiles and regulatory burdens that reshape supplier positioning.
Product Type:
Kelp dominates volume through Chinese aquaculture scale, while nori commands premium tiers via Japanese and Korean quality grading systems.
- Kelp:Brown macroalgae rich in alginate and laminarin, cultivated on long-line systems across Shandong Province and Jeju Island. Food additive manufacturers in Europe and North America absorb bulk volumes for hydrocolloid extraction, though biofuel pilots in Norwegian waters are creating competing offtake demand.
- Nori:Porphyra species dried into paper-thin sheets for sushi and snack applications. Japanese and Korean supply chains enforce strict grade tiers—gold-label nori from Ariake Bay fetches multiples over standard Chinese imports, with EFSA novel food pathways now opening for European cultivation entrants.
- Dulse:Red algae harvested wild in Ireland and Atlantic Canada, gaining traction in plant-based bacon analogues and specialty food retail.
- Wakame:Undaria pinnatifida cultivated primarily in China and South Korea, with miso soup and salad applications driving steady food service demand.
Today's leader: Kelp. Tomorrow's challenger: Nori.
Application:
Food additive applications anchor revenue stability, while biofuel R&D attracts capital seeking land-use-efficient biomass alternatives.
- Food Additive:Carrageenan, alginate, and agar extraction for dairy, confectionery, and meat processing. DSM-Firmenich and Cargill secure multi-year offtake agreements with Shandong processors to guarantee supply for infant formula and organic-labeled products.
- Biofuel:Kelp-to-ethanol and anaerobic digestion pathways piloted by energy majors in Scottish and Norwegian waters. Marine biomass yields bypass terrestrial crop competition, though extraction economics remain unproven at commercial scale.
- Cosmetics:Fucoidan and phlorotannin fractions for anti-aging and hydration formulations, with German and Japanese pharmaceutical formulators adopting biorefinery outputs at pilot scale.
- Agriculture:Seaweed-based biostimulants and soil amendments, with EU Green Deal fertilizer restrictions redirecting European farmers toward marine-derived crop nutrition inputs.
Food additive revenue sustains processor margins. Biofuel represents the steepest expansion trajectory if pilot projects achieve cost parity.
End User:
Pharmaceutical and nutraceutical buyers pay extraction premiums, while food industry procurement prioritizes volume security over bioactive concentration.
- Food Industry:Hydrocolloid demand from dairy, bakery, and meat analogue manufacturers. Direct contracting with designated aquaculture zones is displacing spot-market procurement through commodity traders.
- Pharmaceutical Sector:Alginate wound dressings and controlled-release drug delivery systems. EMA and FDA documentation requirements favor processors with lot traceability and GMP-certified refining facilities.
- Nutraceuticals:Iodine, fucoxanthin, and omega-3 fatty acid supplements. Japanese and Korean consumers drive premium demand for kombu and wakame-derived health products.
- Personal Care:Marine collagen alternatives and seaweed extract skincare, with clean-label positioning attracting indie beauty brands in North American and European markets.
Food industry volume anchors supply chains. Nutraceuticals climb fastest as aging demographics expand preventive health spending.
Distribution Channel:
Supermarket and wholesaler channels consolidate bulk hydrocolloid flows, while specialty stores and online retail capture premium branded products.
- Supermarkets:Packaged nori, wakame, and kelp products for mainstream consumers. China's SAMR heavy metal enforcement is forcing Indonesian and Philippine suppliers to install in-house testing or lose shelf access.
- Wholesalers:Industrial-scale alginate and carrageenan distribution to food manufacturers. Cargill leverages global commodity infrastructure to aggregate Atlantic and Pacific supply into standardized bulk offerings.
- Specialty Stores:Premium Japanese and Korean imports, organic-certified dried seaweed, and sushi-grade products. Lot traceability documentation supports EFSA and FDA compliance for discerning buyers.
- Online Retail:Direct-to-consumer supplements, skincare, and specialty food items. Emerging species like Asparagopsis taxiformis reach early adopters ahead of regulatory clearance for broader retail distribution.
Wholesalers control industrial volume. Online retail gains share fastest as novel species and premium extracts bypass traditional import channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redrawing cultivation maps as processors relocate drying and refining capacity toward jurisdictions with lighter compliance burdens or preferential trade access. This migration pattern favors coastal zones with established aquaculture infrastructure and evolving environmental frameworks.
China
Shandong Province's integrated kelp cultivation and hydrocolloid extraction infrastructure processes bulk volumes for global food additive supply. SAMR enforces GB 19643-2016 heavy metal limits that condition domestic market access and export eligibility. Qingdao's technical clusters concentrate specialized chemical engineering talent for alginate and agar yield optimization.
Indonesia
Sulawesi and Nusa Tenggara's macroalgae zones supply raw dried seaweed to Chinese and European processors seeking cost-competitive feedstock. The national government promotes aquaculture zone development through marine spatial planning initiatives. Makassar's port infrastructure handles growing export volumes to Shandong refining facilities.
South Korea
Jeollanam-do province's nori and wakame cultivation sustains premium pricing through Japanese and Korean quality grading systems. MFDS food safety protocols govern heavy metal testing and export certification for edible seaweed products. Busan-Ulsan industrial corridors host specialized drying operations serving domestic and regional markets.
Norway
Scottish and Norwegian waters host kelp-to-ethanol pilot projects by energy majors seeking marine biomass feedstocks with minimal land-use competition. National blue carbon frameworks are developing certification standards for seaweed farm carbon sequestration. Bergen and Trondheim research clusters advance offshore cultivation automation and biorefinery process intensification.
United States
Maine and Pacific Northwest wild-harvest operations supply specialty food and nutraceutical markets with Irish moss and bull kelp extracts. FDA documentation requirements favor processors with lot traceability and GMP-certified refining facilities. Atlantic Canada and New England coastal zones attract direct contracting from European infant formula manufacturers seeking organic-labeled hydrocolloid sources.
Seaweed Algae Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue biofuel feedstock valorization and novel food regulatory pathways. The market structures around three distinct tiers: integrated multinationals with global commodity infrastructure, regional specialists with captive cultivation assets, and technology-focused biorefinery operators. Competitive dynamics center on supply security through direct farm contracting and extraction yield optimization. Consolidation pressures favor processors with in-house regulatory affairs capacity and GMP-certified refining facilities.
Within the integrated multinational tier, Cargill, Incorporated and DSM-Firmenich represent archetypal positions—leveraging global distribution networks and multi-year offtake agreements with designated aquaculture zones. Qingdao Bright Moon Seaweed Group Co., Ltd. anchors the regional specialist category, exemplifying captive supply integration across Shandong coastal cultivation corridors.
| Leading Market Players |
|---|
| Cargill, Incorporated |
| CP Kelco U.S., Inc. |
| DuPont de Nemours, Inc. |
| Gelymar S.A. |
| DSM-Firmenich |
| Acadian Seaplants Limited |
| Algaia S.A. |
| Qingdao Bright Moon Seaweed Group Co., Ltd. |
| Ceamsa |
| Others |
Value Network & Pricing Analysis
Specialized chemical engineers concentrated in Qingdao, Tokyo, and Copenhagen technical clusters command wage premiums that compress margins at the premium extraction tier while widening spreads between artisanal wild-harvest and industrial aquaculture supply. Labor-cost differentials between these engineering hubs and Southeast Asian processing zones directly shape three-tier pricing stratification across pharmaceutical-grade, food-additive, and agricultural-input markets.
Pricing Analysis
Distributor margins on hydrocolloid extracts absorb the heaviest compression as Cargill and DSM-Firmenich negotiate direct-to-processor offtake agreements that bypass traditional commodity trading layers. Contract-based long-term offtake dominates kelp and carrageenan procurement, with price differentiation driven by EFSA/FDA certification tier and volume scale commitments. Pricing pressure stems from cellulose derivative substitution in cost-sensitive dairy applications, squeezing red seaweed extract margins. Food manufacturers exhibit highest price sensitivity in bulk hydrocolloid procurement, while pharmaceutical formulators pay extraction premiums for GMP-certified alginate with minimal volume negotiation.
Supply Chain Analysis
Refurbishment flows for long-line cultivation infrastructure remain underdeveloped, though Norwegian and Scottish pilot operators are exploring equipment redeployment across seasonal harvest cycles. Raw biomass concentrates in China, Indonesia, and South Korea, with extraction chemistry resting on alginate, carrageenan, and agar yield optimization. Sulawesi-to-Qingdao shipping corridors face monsoon disruption risk and SAMR heavy metal enforcement variability. Distribution runs through integrated processors with captive drying capacity rather than spot-market commodity traders, consolidating procurement leverage among multinationals with designated farm contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in seaweed algae processing hinges on biorefinery yield improvements that compress unit extraction costs while premium-tier nori and pharmaceutical-grade alginate capture widening certification spreads.
For Market Incumbents: Deepen backward integration into Shandong and Jeju Island cultivation zones to secure lot traceability for EFSA novel food dossiers, insulating against cellulose gum substitution in dairy hydrocolloid applications. Expand in-house ICP-MS testing capacity to preempt SAMR border rejections on heavy metal compliance. For New Entrants and Emerging Players: Begin with Asparagopsis taxiformis cultivation for European novel food pathways, exploiting regulatory whitespace before established processors complete toxicology submissions. Target direct-to-supplement online retail for fucoidan and phlorotannin extracts, bypassing wholesale channel consolidation. For Investors and Strategic Acquirers: Energy majors seeking marine biomass feedstocks are the most active acquirer in this space, prioritizing kelp-to-ethanol technology platforms over commodity hydrocolloid assets. Long-term viability across the analysis window rests on blue carbon credit certification maturation. Watch for Australian and Canadian national framework finalization as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Biorefinery Process Intensification | Enzymatic hydrolysis with membrane filtration compresses fucoidan extraction costs for German pharmaceutical formulators. |
| Direct Farm Contracting | Designated aquaculture zone offtake agreements secure EFSA traceability for European infant formula manufacturers. |
| Blue Carbon Certification | National framework alignment in South Korea and Australia unlocks carbon credit monetization for seaweed farm operators. |
| Novel Food Dossier Investment | EFSA toxicology data preparation creates first-mover advantage for Asparagopsis taxiformis European market entry. |
| Heavy Metal Testing Infrastructure | In-house ICP-MS installation preserves Chinese supermarket channel access for Indonesian and Philippine suppliers. |
Research Methodology
Multiple input streams — primary interviews with hydrocolloid extraction engineers and aquaculture zone managers, secondary validation through customs data and GB standard enforcement records, and regulatory filing analysis — were reconciled through bottom-up and top-down triangulation. Stakeholder consultations included kelp cultivation operators in Shandong Province, carrageenan procurement leads at European dairy manufacturers, SAMR compliance officers, and biorefinery technology directors in Bergen and Trondheim research clusters.
Data-stream reconciliation across supply volume tracking, price benchmarking, and regulatory timeline mapping informed the analytical framework. Segmentation dimensions modeled encompass product biology, extraction chemistry, end-use specification, and regional regulatory cluster. CAGRs were derived from supply expansion trajectories and demand elasticity estimates across food additive, pharmaceutical, and emerging biofuel applications.
Several conditions sit outside the modeled scope, including speculative biofuel cost parity achievement and EFSA novel food approval timelines for emerging species. Forecasts reflect assumptions on regulatory enforcement consistency and cultivation infrastructure deployment rates. Practitioners should monitor blue carbon certification standard finalization and cellulose gum substitution velocity in dairy applications for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Limestone for Agriculture Market
Agriculture and Agri Products
Mushroom Substrate Market
Agriculture and Agri Products
Clover Leaf Oil Market
Agriculture and Agri Products
Honeysuckle Market
Agriculture and Agri Products
Cassava Starch Market
Agriculture and Agri Products
Thailand Compound Feed Market
Agriculture and Agri Products
Specialty Egg Market
Agriculture and Agri Products
Agrimony Market
Agriculture and Agri Products
Europe Compound Feed Market
Agriculture and Agri Products
Europe Poultry Feed Market
Agriculture and Agri Products
Date Palm Market
Agriculture and Agri Products
Tunisia Agriculture Market
Agriculture and Agri Products
Brazil Cashew Market
Agriculture and Agri Products
Netherlands Commercial Greenhouse Market
Agriculture and Agri Products
Poultry Fat Market
Agriculture and Agri Products
Centella Asiatica Market