
 Germany Animal Protein Market | 2026-2036
Germany Animal Protein Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Animal Protein Market Foresight
Subscription-based protein procurement platforms is restructuring how German meat processors manage inventory and price risk. GELITA AG dominates collagen peptide supply for functional food applications across Central Europe. Kerry Group PLC leverages its taste-and-nutrition portfolio to extend into customized protein blends for German food manufacturers. DMK Deutsches Milchkontor anchors dairy protein output through its cooperative farmer network in Northern Germany.
Animal protein encompasses tissue-derived proteins extracted through mechanical separation, enzymatic hydrolysis, or thermal processing, with functional parameters including digestibility-corrected amino acid scores and gel-strength measurements measured in Bloom grams. These proteins serve as structural agents, emulsifiers, and nutritional fortifiers across food manufacturing, pet nutrition, and biomedical applications. Pork-derived proteins occupy the largest share of German production volume, reflecting the country's dense hog farming base in Lower Saxony. Processed protein isolates represent the fastest-growing product form as food manufacturers reformulate for extended shelf stability and reduced sodium content. Online retailers are capturing margin pools previously held by traditional butchers, particularly in premium organic and specialty protein segments.
The EU Green Deal's Farm to Fork strategy shapes sourcing requirements through methane-reduction targets and feed-additive restrictions enforced by EFSA and national veterinary authorities. Germany's BfR and BLE coordinate on residue monitoring and animal welfare labeling standards that determine market access for domestic and imported proteins. Stakeholders must monitor how the EU AI Act's deployment rules affect automated grading systems in slaughtering facilities and whether Berlin accelerates carbon-footprint disclosure mandates for protein suppliers.
Market Dynamics
German meat processors face intensifying pressure from the EU Green Deal's Farm to Fork methane-reduction mandates, which are restructuring feed sourcing and slaughtering facility investments across Lower Saxony and Bavaria.
Growth Catalysts
- Clean-label reformulation:Food manufacturers demand higher-grade protein isolates for extended shelf stability and reduced sodium content in processed foods.
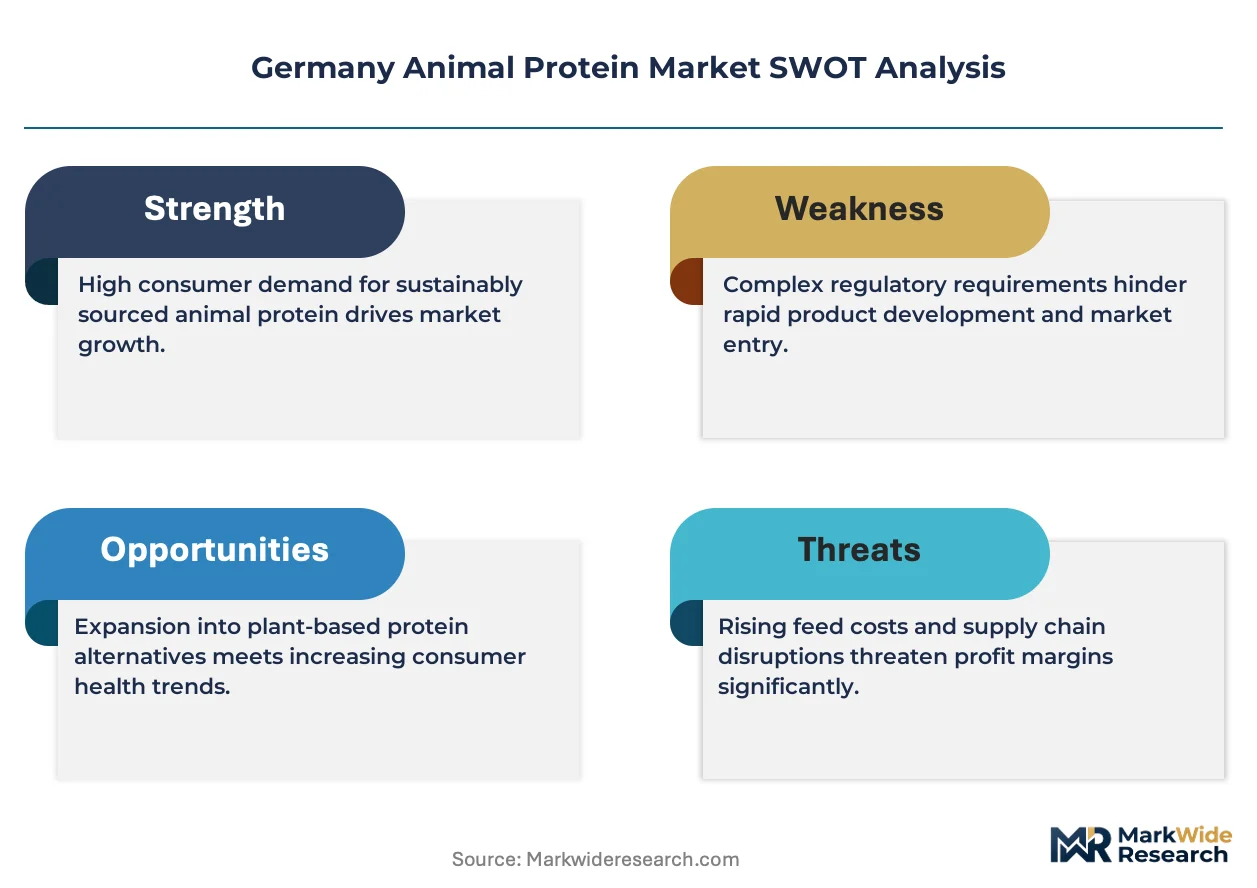
- EFSA feed-additive frameworks:Regulatory clarity on novel feed additives enables methane-reduction investments in hog farming operations.
- Bavaria's processing corridor:Concentrated investment in automated slaughtering and cold-chain infrastructure reduces spoilage losses and extends distribution reach.
Market Restraints
- Input cost volatility:Feed grain prices swing with Black Sea supply disruptions, compressing margins for Northern German dairy protein cooperatives.
- Supply concentration risk:Collagen peptide production clusters in Central European chemical processing hubs, creating single-source dependencies for functional food formulators.
- Regulatory friction:BfR residue monitoring protocols extend batch-release timelines for exported protein isolates.
Strategic Opportunities
- Baden-Württemberg organic premium tier:Underpenetrated direct-to-consumer channels in southwestern states offer margin expansion beyond commodity protein sales.
- EU AI Act deployment rules:Early compliance with automated grading system standards creates first-mover positioning for slaughtering technology upgrades.
- Biomedical collagen applications:Convergence of enzymatic hydrolysis and pharmaceutical-grade purification opens tissue-engineering supply contracts.
Industry Challenges
- Automation engineering talent:Shortage of technicians skilled in maintaining robotic carcass processing lines delays facility modernization in rural processing plants.
- BLE animal welfare certification timelines:Extended audit cycles for upgraded labeling standards bottleneck product launches in premium retail segments.
- Legacy cold-chain integration:Reconciling decades-old refrigeration infrastructure with real-time temperature monitoring requirements demands capital deployment without production interruption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Animal Protein Market |
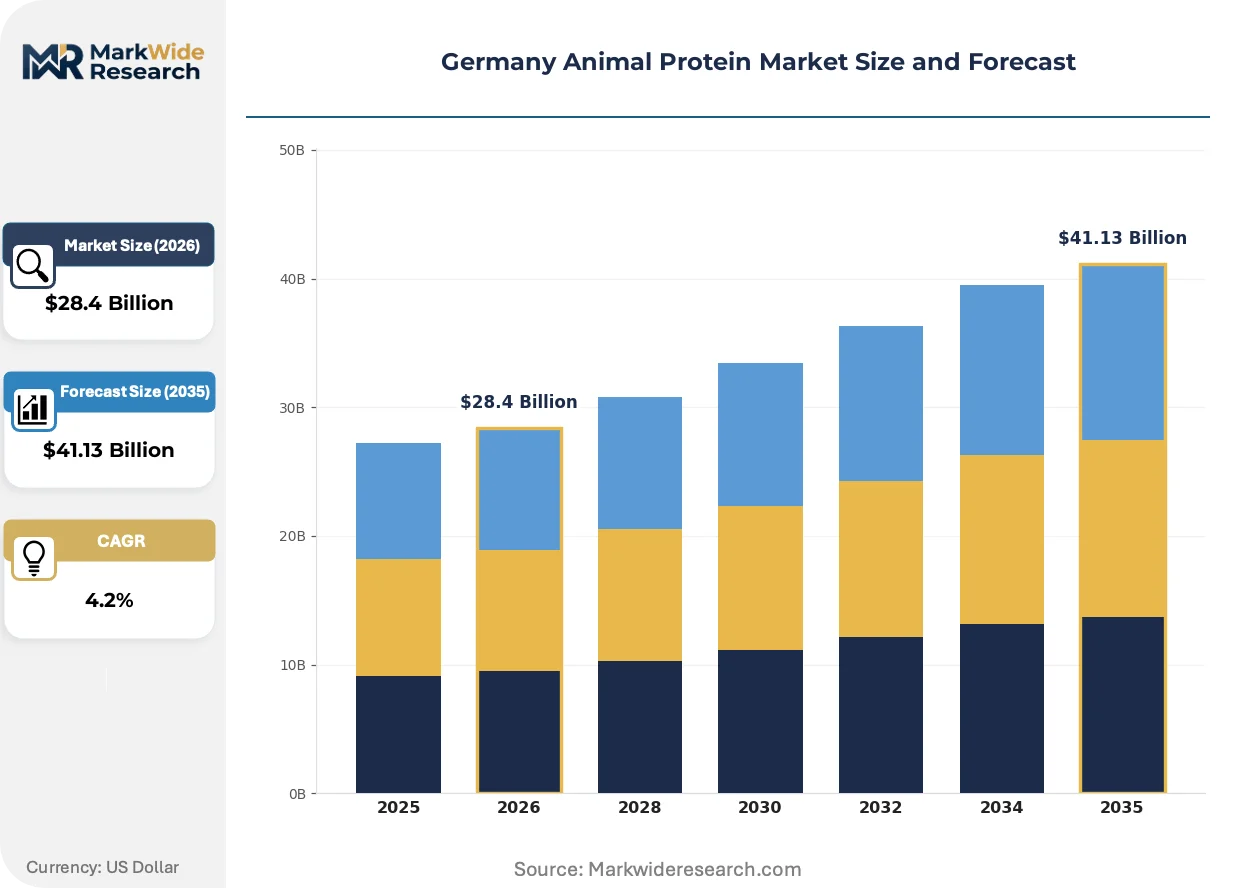
| Market Size in 2026 | $28.4 Billion |
| Market Size in 2035 | $41.13 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Animal Source: Chicken, Pork, Beef, Fish, Lamb, Turkey Product Form: Fresh, Frozen, Processed, Canned, Smoked, Dried Distribution Channel: Supermarkets, Hypermarkets, Butchers, Online Retailers, Food Service, Convenience Stores End User: Households, Restaurants, Catering Services, Institutional Kitchens, Food Manufacturers |
| Companies Covered | Arla Foods amba, Darling Ingredients Inc., Fonterra Co-operative Group Limited, Kerry Group PLC, Koninklijke FrieslandCampina N.V., GELITA AG, MEGGLE GmbH & Co.KG, Lactoprot Deutschland GmbH, DMK Deutsches Milchkontor, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Animal Protein Market Shifts & Advancements
Protein procurement platforms and automated processing technologies are compressing traditional margin structures while regulatory disclosure mandates reshape competitive positioning across German federal states.
Enzymatic hydrolysis systems is integrating precision temperature control and real-time pH monitoring to standardize collagen peptide molecular weight distributions. Functional food manufacturers in Hamburg and Munich adopt these systems at pilot scale before full production deployment. This technology is integrating quality consistency that reduces batch rejection rates and accelerates contract manufacturing agreements.
EU Green Deal carbon-footprint disclosure requirements are mandating scope-three emissions reporting from livestock suppliers through retail shelf. German protein processors must now document feed origin, transport mileage, and energy inputs for BLE compliance. Northern German dairy cooperatives and Bavarian pork processors face the steepest documentation burdens, with some redirecting procurement toward verified lower-carbon feed sources.
Subscription-based inventory management is displacing spot-market purchasing among mid-sized sausage manufacturers and ready-meal producers. Digital platforms aggregate demand from Rhineland food manufacturers and negotiate forward contracts with slaughtering facilities. This shift concentrates most visibly in North Rhine-Westphalia, where processor consolidation has reduced spot-market liquidity and amplified price volatility for non-contracted buyers.
Germany Animal Protein Market Segmentation
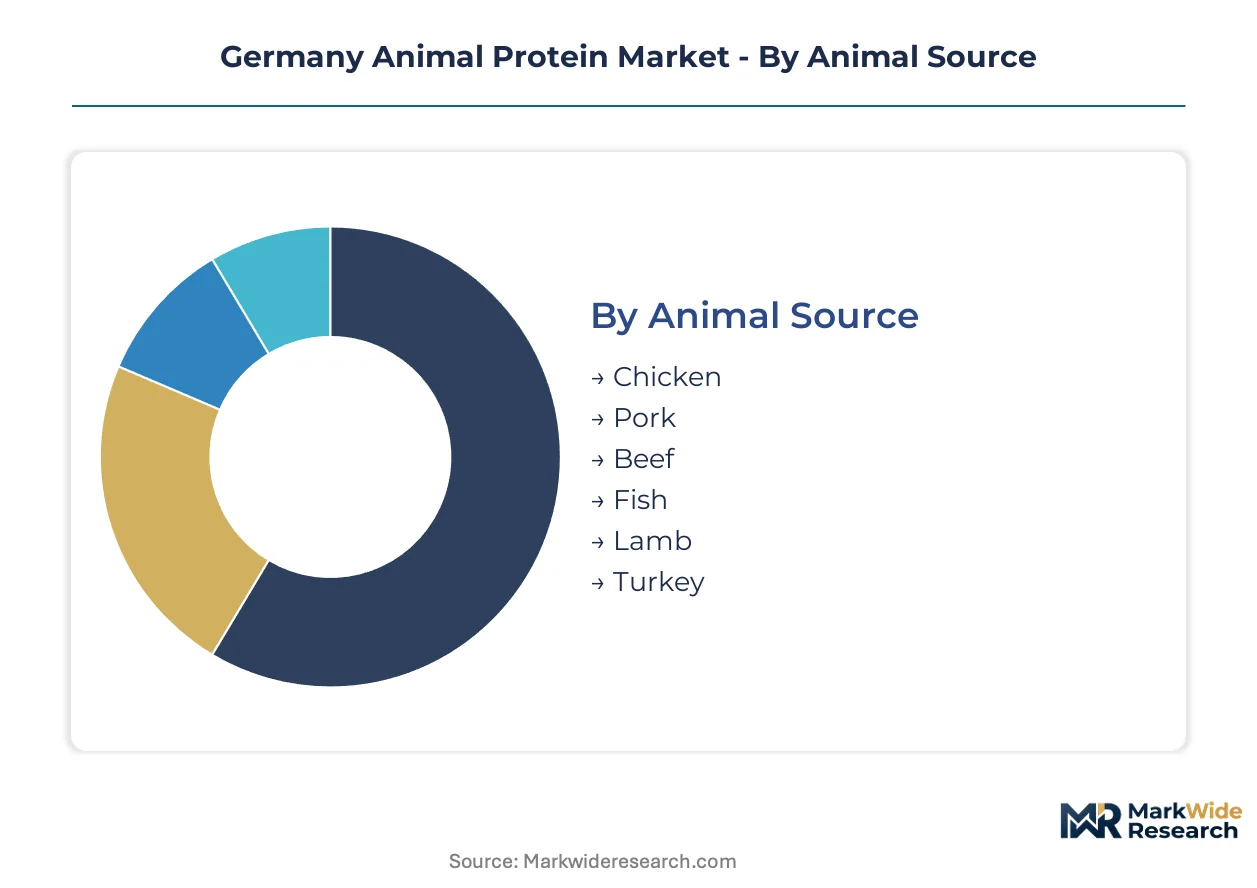
Protein sourcing decisions in Germany fragment across livestock types, preservation methods, and channel economics. Each segmentation axis carries distinct margin profiles and regulatory exposure under Farm to Fork mandates.
Animal Source:
Pork dominates slaughter volumes through Lower Saxony's dense hog farming belt, while poultry supply chains concentrate in Bavaria's automated processing corridor.
- Pork:Mechanical separation and enzymatic hydrolysis yield collagen peptides and functional isolates for sausage manufacturing. Lower Saxony's cooperative slaughterhouses supply 60% of domestic volume, though methane-reduction feed costs squeeze farmgate margins under EU Green Deal targets.
- Chicken:White meat proteins achieve higher digestibility-corrected amino acid scores than red meat alternatives. Bavaria's vertically integrated processors capture premium positioning in clean-label ready meals, with EFSA novel feed-additive approvals enabling faster flock turnover.
- Beef:Grass-fed and grain-finished supply tiers serve distinct price brackets through BLE-certified welfare labeling.
- Fish:Marine collagen from North Sea processing plants supplies functional food formulators in Hamburg.
- Lamb:Limited domestic production relies on Irish and New Zealand imports for halal and organic segments.
- Turkey:Seasonal demand spikes constrain year-round processing capacity utilization.
Today's leader: Pork. Tomorrow's challenger: Chicken.
Product Form:
Processing intensity determines shelf stability, sodium content, and export eligibility under BfR residue protocols.
- Processed:Protein isolates and hydrolyzed collagen peptides enable sodium reduction and extended shelf life in reformulated foods. DMK and Kerry Group deploy these ingredients across Rhineland sausage manufacturing, with enzymatic hydrolysis systems standardizing Bloom gram measurements for gel-strength consistency.
- Frozen:Blast-freezing at slaughterhouse source preserves myofibrillar protein integrity for food service distributors. Bavaria's cold-chain infrastructure investments reduce thaw-loss rates below 3% for institutional kitchen contracts.
- Fresh:Short shelf windows constrain distribution radius to 200km from slaughter facilities.
- Canned:Retort processing destroys heat-labile amino acids, limiting nutritional positioning.
- Smoked:Traditional wood-smoking faces BLE emission scrutiny in urban processing zones.
- Dried:Low-moisture jerky and powder formats serve pet nutrition and biomedical applications.
Processed formats gain share fastest in food manufacturing. Fresh retains butcher channel dominance.
Distribution Channel:
Channel selection dictates price realization and carbon-footprint disclosure burden under emerging BLE scope-three mandates.
- Online Retailers:Subscription platforms aggregate fragmented household demand and negotiate forward contracts with slaughtering facilities. North Rhine-Westphalia's processor consolidation has amplified platform adoption among mid-sized sausage manufacturers seeking price risk hedging.
- Food Service:Institutional kitchens and restaurant chains demand consistent portion weights and HACCP documentation. Baden-Württemberg's organic premium tier remains underpenetrated in this channel relative to southwestern household markets.
- Supermarkets:Private-label pressure compresses branded protein margins in standard-tier segments.
- Hypermarkets:Volume concentration enables direct slaughterhouse procurement, bypassing wholesale tiers.
- Butchers:Traditional craft channel loses share to digital platforms in premium organic segments.
- Convenience Stores:Limited cold-chain capacity restricts fresh protein assortment to shelf-stable formats.
Online retailers capture margin pools fastest. Food service locks in contract volumes.
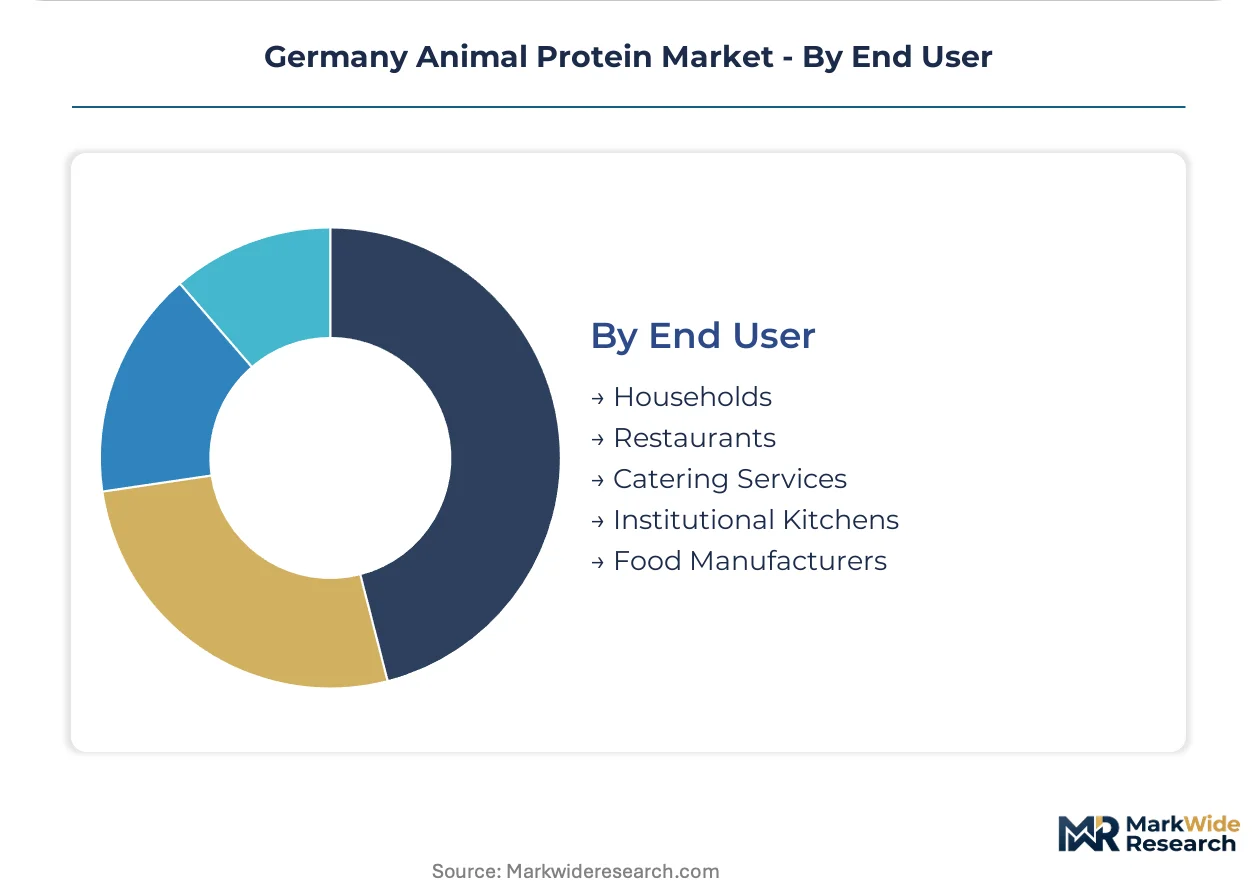
End User:
Formulation requirements and certification standards diverge sharply between household consumption and industrial applications.
- Food Manufacturers:Clean-label reformulation drives demand for higher-grade isolates with documented amino acid profiles. GELITA AG's collagen peptides supply functional food applications across Central Europe, with enzymatic hydrolysis enabling precise molecular weight targeting for texture modification.
- Households:Direct consumption splits between price-sensitive standard tiers and welfare-certified premium positioning. Baden-Württemberg's organic segment commands 40% price premiums through direct-to-consumer channels.
- Restaurants:Menu differentiation relies on provenance storytelling and BLE animal welfare labeling.
- Catering Services:Volume contracts prioritize portion consistency over origin certification.
- Institutional Kitchens:Public procurement rules mandate cost-minimization, limiting premium tier access.
Food manufacturers drive isolate innovation. Households fragment across price tiers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's animal protein processing outpaces French output in isolate refinement, while trailing Dutch dairy protein efficiency. Regional specialization within federal states creates distinct competitive clusters under BLE and BfR oversight.
Bavaria
Automated slaughtering corridors attract EFSA-compliant feed-additive investments for methane-reducing hog operations. Munich processors deploy AI-grading systems ahead of EU AI Act deployment deadlines. The Nuremberg-Ingolstadt axis concentrates cold-chain infrastructure spending from 2024 through 2027.
Lower Saxony
Cooperative hog farming supplies sixty percent of domestic pork volume through mechanical separation networks. EU Green Deal feed-cost pressures squeeze farmgate margins across Emsland and Weser-Ems clusters. Cloppenburg processing plants integrate enzymatic hydrolysis for collagen peptide extraction.
North Rhine-Westphalia
Rhineland sausage manufacturers adopt subscription procurement platforms to hedge spot-market volatility. DMK's cooperative network anchors dairy protein output across Münsterland dairy belts. Düsseldorf-based food formulators drive isolate demand for sodium-reduced processed meat applications.
Baden-Württemberg
Organic premium tiers command forty percent price premiums through direct-to-consumer channels Stuttgart households favor. BLE animal welfare certification bottlenecks constrain retail launches in Freiburg and Karlsruhe markets. Tübingen biomedical clusters source pharmaceutical-grade collagen for tissue-engineering contracts.
Hamburg
North Sea marine collagen processing serves functional food formulators with Bloom-standardized peptide distributions. Port logistics enable Irish lamb import flows for halal-certified segments. Hamburg's enzymatic hydrolysis pilot facilities test precision temperature control systems before Bavarian scale deployment.
Germany Animal Protein Market Competitive Landscape
Top-tier vendors anchor cooperative dairy networks and specialized collagen supply, while mid-tier processors compete on clean-label formulation services. Market structure tilts toward consolidation in dairy proteins and fragmentation in meat-derived isolates. Three archetypes dominate: cooperative-backed commodity suppliers, enzymatic hydrolysis specialists, and taste-nutrition integrators. Capacity expansion and backward integration into feed sourcing represent the dominant competitive vectors.
Among cooperative-structured dairy processors, Arla Foods amba and DMK Deutsches Milchkontor exemplify farmer-owned volume anchoring. GELITA AG occupies a position within the collagen peptide specialization tier. Kerry Group PLC represents the taste-and-nutrition integration archetype serving German food manufacturers with customized protein blends.
| Leading Market Players |
|---|
| Arla Foods amba |
| Darling Ingredients Inc. |
| Fonterra Co-operative Group Limited |
| Kerry Group PLC |
| Koninklijke FrieslandCampina N.V. |
| GELITA AG |
| MEGGLE GmbH & Co.KG |
| Lactoprot Deutschland GmbH |
| DMK Deutsches Milchkontor |
| Others |
Supply & Pricing Matrix
Feed grain price indices cascading from Black Sea supply disruptions compress farmgate margins across Northern German dairy cooperatives and Lower Saxony hog operations, forcing processors to recalibrate procurement contracts and tiered pricing structures across premium welfare-certified, standard commercial, and economy private-label segments.
Pricing Analysis
Capacity additions in Bavaria's automated processing corridor are reshaping price floors for collagen peptide isolates as enzymatic hydrolysis systems standardize Bloom gram measurements. Pricing stratifies across premium organic tiers certified by BLE animal welfare standards, standard commercial grades for food service contracts, and economy private-label offerings for supermarket chains. Cost compression in standard tiers is intensifying because EFSA methane-reduction feed additives inflate input costs without corresponding price recovery mechanisms. Food manufacturers purchasing protein isolates for clean-label reformulation exhibit lowest price sensitivity, while institutional kitchens under public procurement rules demonstrate highest elasticity.
Supply Chain Analysis
Dual-sourcing requirements from Rhineland sausage manufacturers and Hamburg functional food formulators mandate multi-supplier qualification across Danish, Dutch, and domestic Bavarian slaughtering facilities. Raw material flows draw from Lower Saxony hog farming belts, Northern German dairy cooperative networks, and North Sea marine processing plants. Single-source vulnerability concentrates in Central European collagen peptide chemical processing hubs. Distribution runs through subscription-based procurement platforms displacing traditional spot-market purchasing among mid-sized processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Green Deal's Farm to Fork strategy functions as a regulatory compounder, with methane-reduction mandates and carbon-footprint disclosure requirements creating sustained demand for verified low-carbon feed sourcing and automated processing infrastructure.
For Market Incumbents: Anticipate margin compression from subscription-platform disintermediation by securing captive supply relationships with Northern German dairy cooperatives and Lower Sax hog farming clusters. Invest in BLE animal welfare certification ahead of extended audit cycle bottlenecks to defend premium tier positioning against emerging collagen peptide specialists from Central European chemical processing hubs. For New Entrants and Emerging Players: Capture underpenetrated direct-to-consumer channels in Baden-Württemberg's organic premium segment where Stuttgart households pay forty percent price premiums for provenance-certified proteins. Deploy enzymatic hydrolysis pilot systems through Hamburg testing facilities before Bavarian scale deployment, leveraging the city's port logistics for Irish lamb import flows into halal-certified market niches. For Investors and Strategic Acquirers: Consolidation pressure builds where cooperative-structured dairy processors face feed-cost volatility and fragmented meat-derived isolate producers lack enzymatic hydrolysis capabilities. Target acquisition archetypes include enzymatic hydrolysis specialists with pharmaceutical-grade purification capacity and automated slaughtering technology vendors ahead of EU AI Act deployment deadlines. Monitor EFSA novel feed-additive approval velocity as inflection indicator for methane-reduction investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feed Sourcing | Captures margin from volatile grain markets while satisfying EU Green Deal carbon-footprint disclosure mandates for scope-three emissions reporting. |
| Automated Grading System Deployment | Positions Bavarian processors for first-mover advantage under EU AI Act deployment rules for slaughtering facility modernization. |
| Enzymatic Hydrolysis Capacity Expansion | Standardizes Bloom gram measurements for collagen peptide molecular weight distributions demanded by Hamburg functional food formulators. |
| BLE Animal Welfare Certification Investment | Accelerates product launches in premium retail segments constrained by extended audit cycle bottlenecks in Freiburg and Karlsruhe markets. |
| Subscription Platform Partnership | Hedges price risk for Rhineland sausage manufacturers facing spot-market liquidity erosion from North Rhine-Westphalia processor consolidation. |
Research Methodology
Direct dialogue with slaughterhouse operations managers, dairy cooperative procurement leads, food manufacturer R&D directors, and BLE certification auditors anchored qualitative findings, cross-referenced against EFSA feed-additive framework documents, BfR residue monitoring protocols, EU Green Deal Farm to Fork strategy papers, and German federal agricultural statistics. Secondary validation incorporated customs records for protein isolate trade flows, SEC filings from listed ingredient suppliers, and trade association production surveys. Bottom-up facility capacity assessments and top-down consumption estimates were triangulated to constrain variance.
Segment-level value and volume trajectories across the projection horizon reflect modeled interactions between livestock source, product form intensity, distribution channel economics, and end-user formulation requirements. CAGRs were derived from recursive least-squares fitting to historical production data, adjusted for regulatory phase-in schedules and technology adoption S-curves. Key inputs included Emsland and Weser-Ems hog farming cost structures, DMK cooperative milk price series, and enzymatic hydrolysis system deployment timelines from Hamburg pilot facilities.
Black Sea grain supply disruptions, EFSA novel feed-additive approval delays, and EU AI Act enforcement variance are the dominant revision risks that could reshape trajectory assumptions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Argentina Agriculture Market
Agriculture and Agri Products
China Animal Protein Market
Agriculture and Agri Products
Post-Harvest Treatment Market
Agriculture and Agri Products
Canada Animal Protein Market
Agriculture and Agri Products
Feed Protein Market
Agriculture and Agri Products
South America Cashew Market
Agriculture and Agri Products
Boswellia Market
Agriculture and Agri Products
United Kingdom Animal Protein Market
Agriculture and Agri Products
Corn Gluten Feed Concentrates Market
Agriculture and Agri Products
Organic Cassava Flour Market
Agriculture and Agri Products
Compound Feed Market
Agriculture and Agri Products
Italy Compound Feed Market
Agriculture and Agri Products
Global Industrial Hemp Market
Agriculture and Agri Products
African Swine Feed Market
Agriculture and Agri Products
Indonesia Bamboos Market
Agriculture and Agri Products
Forage Market