
 Agriculture in Egypt Market | 2026-2036
Agriculture in Egypt Market Size, Share, and Industry Trends Forecast 2026-2036
Agriculture in Egypt Market Insights
Premium-grade horticultural certification is unwinding traditional commodity pricing in Egyptian agriculture. Modern Agriculture Co. (PICO) leverages integrated greenhouse complexes to sustain year-round tomato and pepper supply. Dinafarms anchors the potato processing segment with cold-chain infrastructure reaching European buyers. Daltex for Agriculture competes through organic acreage accredited under EU-equivalent standards.
Agriculture in Egypt encompasses the cultivation of cereals, vegetables, fruits, and pulses across Nile Delta alluvial soils, utilizing flood irrigation, center-pivot systems, and controlled-environment agriculture with salinity tolerance thresholds below 2,000 ppm for export-grade produce. The sector primarily supplies food security, foreign exchange earnings through fresh produce exports, and raw materials for domestic food manufacturing. Cereals occupy the largest planted area but generate thinner margins amid wheat import dependence, while vegetables command premium pricing through supermarket retail and wholesale channels serving Gulf and European markets. Food Processing as an end-use industry is expanding fastest as ICAPP and Raya Foods build tomato paste and frozen vegetable capacity near Alexandria's port zone.
Egypt's Ministry of Agriculture and Land Reclamation enforces seed certification protocols and pesticide residue limits aligned with EFSA thresholds for European market access. BIS-equivalent quality mandates through the Egyptian Organization for Standardization and Quality (EOS) shape packaging and labeling rules for retail distribution. Stakeholders must monitor water allocation reforms under the National Water Resources Plan and decide whether to relocate production to new desert reclamation zones with groundwater access.
Market Dynamics
Water scarcity and European export certification requirements are forcing Egyptian producers to abandon flood irrigation for precision agriculture systems that cut consumption while meeting EFSA residue thresholds.
Growth Catalysts
- Drip Irrigation Expansion:The National Water Resources Plan mandates efficiency upgrades across Nile Delta farms, cutting per-hectare consumption by half while maintaining yields.
- EFSA-Aligned Certification:Egypt's Ministry of Agriculture and Land Reclamation enforces pesticide residue protocols that unlock supermarket retail channels in Germany and the Netherlands.
- Desert Reclamation Zones:New groundwater-accessible production clusters near Toshka and East Oweinat bypass delta land scarcity for year-round cultivation.
Market Restraints
- Seed Import Dependence:Certified vegetable seed stock originates from Dutch and Israeli suppliers, exposing growers to currency volatility and shipping delays.
- Salinity Thresholds:Export-grade produce requires irrigation water below 2,000 ppm total dissolved solids, disqualifying most Nile sources without reverse osmosis treatment.
- Energy-Intensive Cold Chain:Diesel-powered refrigeration for potato and frozen vegetable exports faces cost pressure from fuel subsidy reductions.
Strategic Opportunities
- Organic Acreage Accreditation:EU-equivalent certification programs open premium pricing tiers for tomatoes and peppers in Scandinavian retail.
- Alexandria Port Zone Processing:Tomato paste and frozen vegetable facilities co-located with container terminals cut logistics costs for Red Sea and Mediterranean routes.
- Hydroponic Convergence:Integration of greenhouse climate control with nutrient film technique enables pepper production during off-peak import windows in Gulf markets.
Industry Challenges
- Agronomy Skill Shortage:Precision agriculture deployment outpaces trained technicians capable of calibrating fertigation systems and interpreting soil moisture sensors.
- Certification Timeline Compression:EU-equivalent organic accreditation requires 36-month conversion periods that strain working capital for smallholders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Agriculture in Egypt Market |
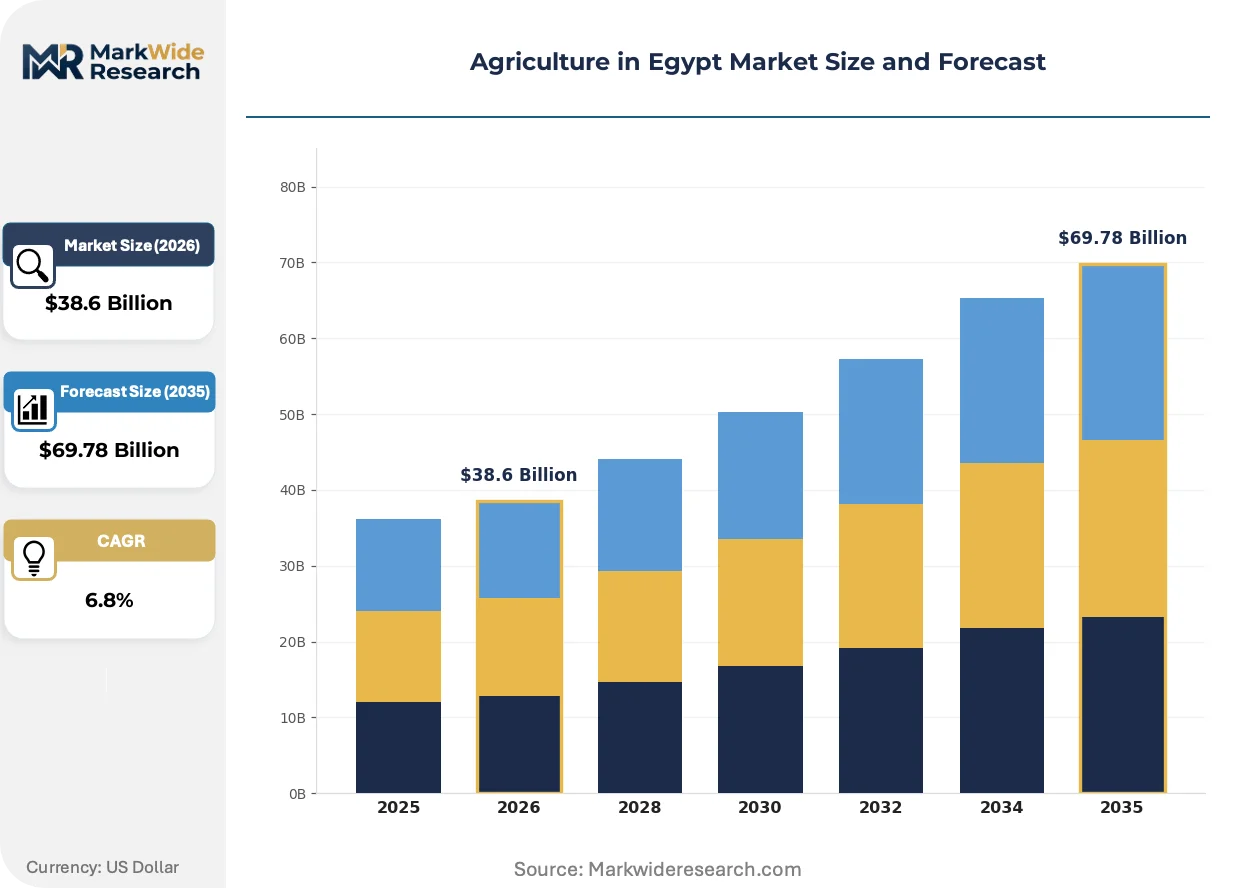
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $69.78 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cereals, Vegetables, Fruits, Pulses End Use Industry: Food Processing, Export, Local Consumption, Animal Feed Packaging Type: Bags, Pallets, Bins, Bulk Distribution Channel: Retail, Wholesale, Direct Sales, Online Platforms |
| Companies Covered | Modern Agriculture Co. (PICO), Dinafarms, Daltex for Agriculture, Raya Foods, Cairo 3A for Agricultural and Animal Production, International Co. for Agri Production and Processing (ICAPP), Magrabi Agricultural, Galina, Farm Frites-Egypt, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Agriculture in Egypt Market Trends and Innovations
Controlled-environment agriculture is rewriting crop calendars and supply relationships across Egyptian horticulture, compressing traditional seasonality while elevating quality consistency for export buyers.
Greenhouse climate control systems with automated ventilation and fertigation are displacing open-field cultivation for tomato and pepper production. Large-scale exporters in Beheira and Kafr El Sheikh governorates have adopted these structures at accelerated rates since 2022. The technology is displacing seasonal price volatility by enabling harvest continuity through summer heat peaks that previously halted field production.
EFSA-aligned maximum residue limits enforced by Egypt's Ministry of Agriculture and Land Reclamation are tightening pesticide application windows. Integrated pest management protocols now dominate greenhouse operations near Damietta and Port Said. Vegetable exporters to Germany and the Netherlands bear primary compliance burden, with testing laboratory capacity expanding in Alexandria to reduce clearance delays.
Supermarket procurement consolidation across Gulf Cooperation Council markets is compressing supplier qualification cycles. Egyptian pepper and tomato growers now face direct audits from Saudi and UAE retail chains that previously relied on Dubai-based intermediaries. The shift is most visible in Sharqia Governorate packing houses, where traceability software investments have become mandatory for contract eligibility.
Agriculture in Egypt Market Segmentation
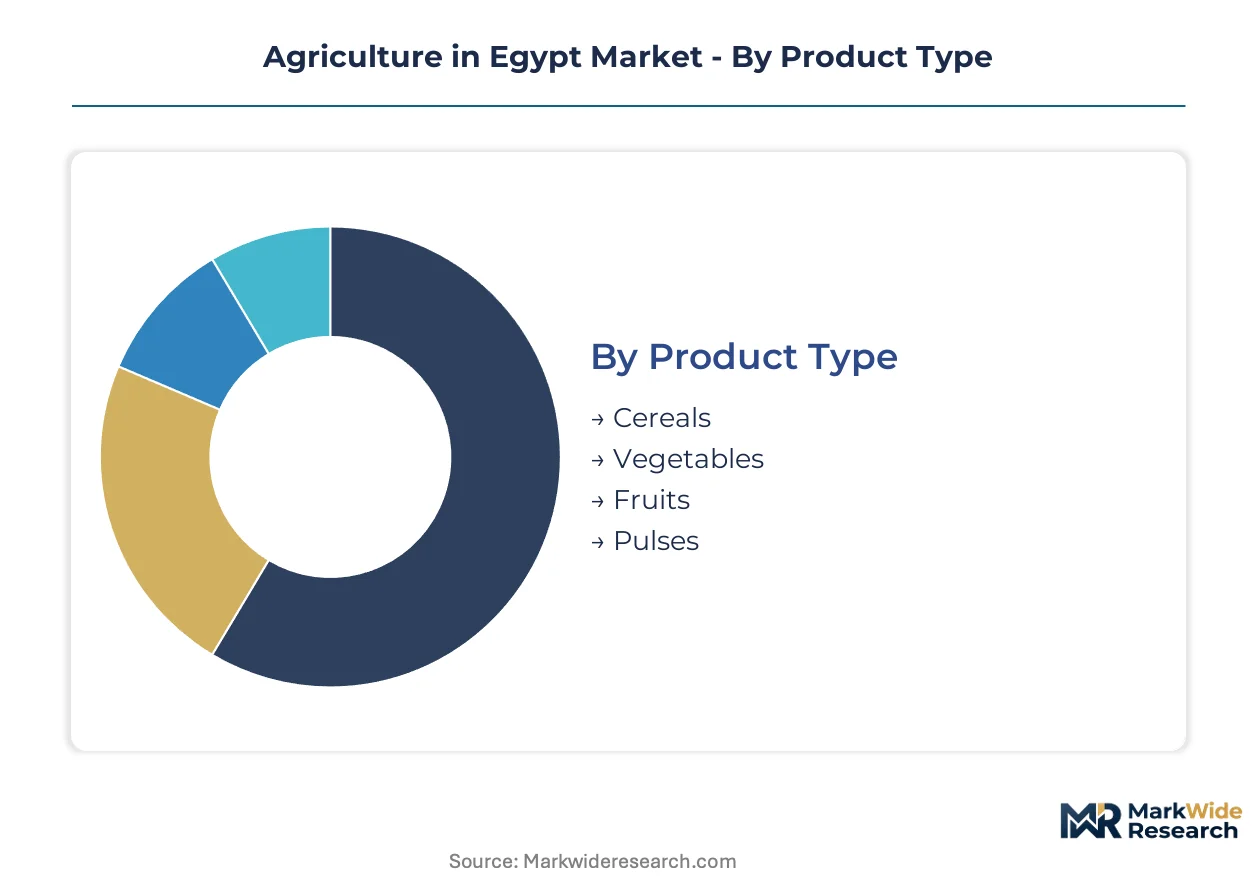
Segmentation in Egyptian agriculture reveals how Nile Delta production clusters align with distinct demand channels. Each category maps specific crop types to their dominant offtake routes, from domestic food security to European supermarket procurement.
Product Type:
Geographic spread splits sharply between domestic staple crops and export-oriented horticulture, with Delta governorates dominating both flows.
- Cereals:Wheat and maize cultivation occupies the largest planted area across Nile Delta alluvial soils. Beheira and Kafr El Sheikh governorates concentrate production for domestic milling and bread subsidy programs, though thin margins persist amid import dependence for high-quality seed stock.
- Vegetables:Tomato, pepper, and potato output from controlled-environment agriculture commands premium pricing through EFSA-aligned certification. Damietta and Port Said greenhouse clusters supply year-round harvests to German and Dutch supermarket chains, bypassing seasonal price volatility that halts open-field production.
- Fruits:Citrus and stone fruit cultivation concentrates in Ismailia and Sharqia governorates for Gulf Cooperation Council retail.
- Pulses:Fava bean and lentil production serves domestic protein demand with limited export traction.
Cereals holds the largest share; momentum sits with Vegetables.
End Use Industry:
Application flow determines infrastructure investment priority, with processing capacity expanding fastest near Alexandria's port zone.
- Food Processing:Tomato paste and frozen vegetable facilities co-located with container terminals cut logistics costs for Red Sea and Mediterranean routes. ICAPP and Raya Foods anchor capacity expansion near Alexandria, drawing supply from certified greenhouse networks in Beheira.
- Export:Fresh produce shipments to European Union markets require EFSA-aligned residue testing and cold-chain integrity. Alexandria laboratory capacity expansion reduces clearance delays for German and Dutch retail procurement.
- Local Consumption:Domestic retail and wholesale channels absorb cereal and pulse output under price stabilization mechanisms.
- Animal Feed:Maize and soybean meal demand links to poultry and dairy sector expansion in Qalyubia and Giza governorates.
Local Consumption holds the largest share; Food Processing is climbing the fastest.
Packaging Type:
Customer type differentiation separates bulk commodity flows from unitized retail-ready shipments.
- Bags:Woven polypropylene sacks dominate cereal and pulse handling through wholesale channels, with 50kg standards for domestic milling intake.
- Pallets:Unitized loads for supermarket retail require ISPM-15 compliant wood or plastic alternatives for European export.
- Bins:Bulk handling of processing tomatoes and peppers feeds Alexandria zone paste and freezing facilities.
- Bulk:Unpackaged cereal transfers from harvest to storage silos minimize handling costs for domestic security stocks.
Bags holds the largest share; Pallets is gaining share fastest.
Distribution Channel:
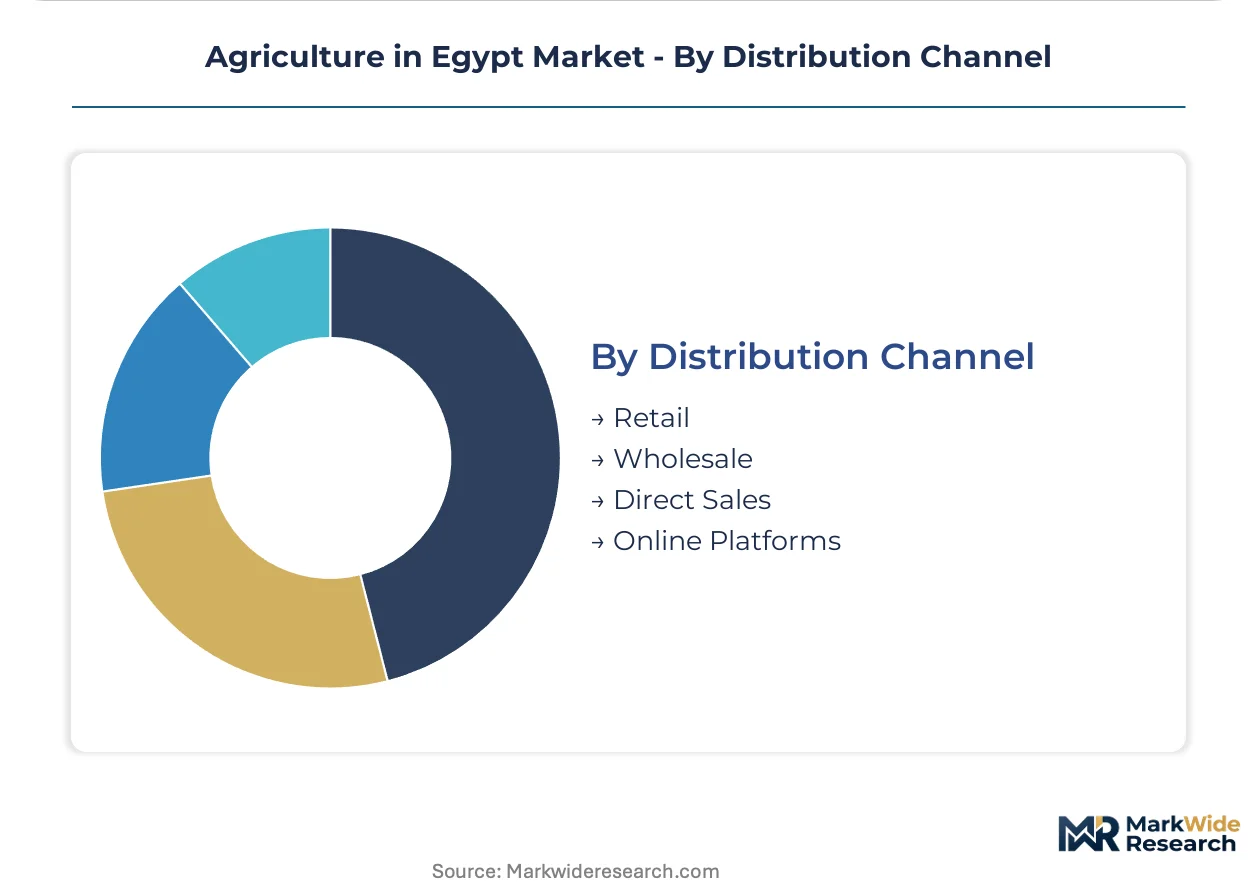
Supply concentration patterns reveal how consolidation across Gulf retail chains compresses supplier qualification cycles.
- Retail:Supermarket procurement consolidation across Saudi and UAE markets mandates traceability software investments in Sharqia Governorate packing houses. Direct audits now replace Dubai-based intermediary relationships.
- Wholesale:Traditional commission agents in Cairo's Bulaq and Alexandria's El-Max markets intermediate between Delta producers and domestic processors.
- Direct Sales:Large-scale exporters contract directly with European supermarket chains, bypassing wholesale layers for certified vegetable shipments.
- Online Platforms:Emerging channels for packaged specialty crops reach urban consumers in Cairo and Alexandria.
Wholesale holds the largest share; Retail shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Egypt's agricultural trade balance tilts toward import dependence for cereals while horticultural exports to Europe and the Gulf generate foreign exchange. Nile Delta governorates concentrate production infrastructure, though desert reclamation zones are shifting cultivation geography southward and westward.
Beheira Governorate
Greenhouse complexes for tomato and pepper production supply year-round harvests to German supermarket chains. Egypt's Ministry of Agriculture and Land Reclamation enforces EFSA-aligned residue protocols here. Kafr El Dawar and Damanhour host packing houses with direct cold-chain links to Alexandria Port.
Kafr El Sheikh Governorate
Wheat and maize cultivation dominates planted area under domestic food security programs. The National Water Resources Plan mandates drip irrigation retrofits across traditional flood-irrigated fields. Biyala and Desouk cluster processing tomatoes for Alexandria zone paste facilities.
Sharqia Governorate
Citrus and stone fruit cultivation targets Gulf Cooperation Council retail procurement. Supermarket chains from Saudi Arabia and the UAE now conduct direct supplier audits here. Zagazig packing houses have invested in traceability software to meet consolidated retail qualification cycles.
Damietta and Port Said Governorates
Controlled-environment agriculture clusters exploit Mediterranean port proximity for European fresh produce shipments. Integrated pest management protocols dominate greenhouse operations to satisfy EFSA maximum residue limits. New Borg El Arab laboratory capacity reduces customs clearance delays for Dutch retail buyers.
New Valley Governorate
Desert reclamation zones near Toshka and East Oweinat bypass Nile Delta land scarcity through groundwater-accessible production. The National Water Resources Plan allocates extraction permits for agricultural investors meeting salinity thresholds below 2,000 ppm total dissolved solids. Kharga and Dakhla oases host experimental year-round pepper cultivation for Gulf off-peak import windows.
Agriculture in Egypt Market Competitive Landscape
Concentration sits with integrated greenhouse operators and desert reclamation developers. The market structure spans three tiers: large-scale exporters with EFSA-aligned certification, mid-size processors co-located near Alexandria Port, and fragmented smallholders transitioning from flood irrigation. Two strategic archetypes dominate—vertically integrated horticultural specialists and food processing conglomerates backward-integrating into captive supply. Competitive moves center on cold-chain infrastructure expansion and organic acreage accreditation for Scandinavian retail access.
Within the integrated greenhouse tier, Modern Agriculture Co. (PICO) and Magrabi Agricultural exemplify controlled-environment agriculture scale. Among processing-focused operators, International Co. for Agri Production and Processing (ICAPP) and Raya Foods anchor Alexandria Port zone capacity. Dinafarms occupies a position linking cold-chain potato exports to European buyers. Daltex for Agriculture represents the organic accreditation vector competing through EU-equivalent standards.
| Leading Market Players |
|---|
| Modern Agriculture Co. (PICO) |
| Dinafarms |
| Daltex for Agriculture |
| Raya Foods |
| Cairo 3A for Agricultural and Animal Production |
| International Co. for Agri Production and Processing (ICAPP) |
| Magrabi Agricultural |
| Galina |
| Farm Frites-Egypt |
| Others |
Pricing and Supply Chain Analysis
Ninety-day seed inventory cycles at Dutch and Israeli suppliers concentrate pricing power among certified vegetable growers while amplifying exposure to currency volatility and shipping delays. This lead-time structure forces Egyptian producers to absorb input cost fluctuations or sacrifice EFSA-aligned certification tiers that unlock German supermarket contracts.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures for processing tomatoes and frozen vegetables bound for Alexandria Port facilities. Price differentiation rests on EFSA-aligned residue certification and cold-chain integrity grades, with premium tiers commanding substantial markups over domestic wholesale channels. Pricing pressure stems from diesel-powered refrigeration costs amid fuel subsidy reductions, squeezing margins for potato exporters serving European markets. Smallholders operating flood-irrigated cereal plots exhibit highest price sensitivity, while integrated greenhouse operators with captive processing contracts demonstrate lowest sensitivity due to volume scale and backward integration into paste and freezing capacity.
Supply Chain Analysis
Strategic stockpile preferences dominate seed and fertilizer procurement given import dependence and currency volatility, contrasting with just-in-time harvest logistics for perishable vegetable exports. Geographic supply concentration centers on the Netherlands and Israel for certified vegetable seed stock, Egypt's Nile Delta for cultivation, and Germany and the Netherlands for retail offtake. Raw material dependencies include drip irrigation equipment, cold-chain refrigeration components, and EFSA-aligned pesticide formulations. Single-source vulnerability pervades certified seed supply, with limited alternative suppliers meeting conversion timeline requirements. Distribution runs through Alexandria Port container terminals for European and Gulf routes, supplemented by direct cold-chain links from Beheira and Kafr El Sheikh packing houses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now governs Egyptian agriculture as traceability software investments become mandatory for direct procurement by Saudi and UAE supermarket chains, displacing Dubai-based intermediary relationships. This interoperability shift rewards operators integrating greenhouse climate control with port-proximate processing capacity.
For Market Incumbents: Secure EFSA-aligned organic acreage accreditation before 36-month conversion timelines elongate competitive moats for Scandinavian retail access. Deepen upstream control over cold-chain infrastructure to defend margin position against diesel cost volatility threatening potato and frozen vegetable exports. Acquire distressed smallholder operations in Kafr El Sheikh to consolidate drip irrigation retrofit compliance under National Water Resources Plan mandates.
For New Entrants and Emerging Players: Lead with hydroponic pepper production in New Valley Governorate desert reclamation zones to exploit off-peak import windows in Gulf markets. Target Toshka groundwater-accessible clusters where salinity thresholds below 2,000 ppm total dissolved solids remain achievable through reverse osmosis investment. Pursue direct supplier audit qualification with consolidated Saudi retail chains as primary go-to-market angle, bypassing traditional commission agent layers.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified conglomerates with underutilized greenhouse assets lacking EFSA-aligned certification infrastructure. Long-term viability hinges on water allocation security under National Water Resources Plan reforms and European market access continuity. Acquisition focus should center on mid-scale operators with Alexandria Port zone proximity and existing cold-chain assets. Watch for inflection when groundwater extraction permit issuance accelerates for agricultural investors meeting salinity compliance thresholds.
| Strategic Initiative | Industry Significance |
|---|---|
| EFSA-Aligned Certification Investment | Unlocks German and Dutch supermarket retail channels previously inaccessible to Egyptian exporters. |
| Backward Integration into Cold-Chain Infrastructure | Reduces diesel cost exposure for potato shipments to European buyers amid subsidy reductions. |
| Desert Reclamation Zone Development | Bypasses Nile Delta land scarcity through Toshka groundwater extraction permits for year-round cultivation. |
| Traceability Software Deployment | Meets direct audit requirements from Saudi and UAE retail chains consolidating procurement. |
| Alexandria Port Zone Co-Location | Cuts logistics costs for tomato paste and frozen vegetable exports via Red Sea and Mediterranean routes. |
Research Methodology
The analysis maps cereals, vegetables, fruits, and pulses segments, each validated through greenhouse operators, port zone processors, cold-chain logistics providers, and supermarket procurement officers. Primary interviews with executives at integrated agricultural companies and distributors were cross-referenced against customs records, EOS quality mandate filings, National Water Resources Plan documentation, and EFSA residue threshold guidelines. Bottom-up acreage and yield estimates were triangulated with top-down trade flow analysis across the analysis window.
Consistency checks validated volume and value outputs against Alexandria Port throughput data, European import statistics for Egyptian horticultural products, and Gulf Cooperation Council retail procurement disclosures. Segmentation dimensions modeled include product type, end-use industry, packaging format, and distribution channel, with additional granularity on certification tier and irrigation technology adoption. CAGRs were derived from trend extrapolation of drip irrigation expansion rates, greenhouse construction permits, and processing capacity additions near Alexandria, incorporating water allocation reform scenarios and European market access continuity assumptions.
Forecasts assume regulatory continuity in Egyptian Ministry of Agriculture seed certification protocols and EFSA residue limit enforcement; material policy shifts would require re-modeling. Specific risks include groundwater extraction permit revocation under National Water Resources Plan revisions, EFSA threshold tightening beyond current laboratory capacity, and fuel subsidy elimination accelerating cold-chain cost inflation. Revision becomes warranted when desert reclamation zone salinity compliance rates cross thresholds affecting investor permit eligibility.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Animal Feed Market
Agriculture and Agri Products
Cambodia Agriculture Market
Agriculture and Agri Products
Angola Agriculture Market
Agriculture and Agri Products
Colombia Hemp Market
Agriculture and Agri Products
Poultry Processing Product Market
Agriculture and Agri Products
Cut Flower Market
Agriculture and Agri Products
North America Eggs Market
Agriculture and Agri Products
Consumer Floriculture Market
Agriculture and Agri Products
North America Poultry Feed Market
Agriculture and Agri Products
Animal Feed Ingredients Market
Agriculture and Agri Products
Global Commercial Seaweeds Market
Agriculture and Agri Products
Henequen Market
Agriculture and Agri Products
North America Compound Feed Market
Agriculture and Agri Products
Canada Ornamental Horticulture Market
Agriculture and Agri Products
High Fiber Feed Market
Agriculture and Agri Products
China Compound Feed Market