
 Spain Forage Seed Market | 2026-2036
Spain Forage Seed Market Size, Share, and Industry Trends Forecast 2026-2036
Spain Forage Seed Market Analytics
Spain's Common Agricultural Policy alignment with ecological focus area mandates is restructuring the cost-of-entry calculus for forage seed suppliers. Corteva Agriscience leverages its transatlantic breeding pipeline to anchor certified lucerne portfolios across Castilian dairy corridors. DLF Seeds Ltd competes through specialized ryegrass varieties adapted to Iberian drought cycles. Grupo Batlle S.A. dominates domestic distribution through deep wholesale relationships with Andalusian cooperatives.
Forage seed comprises germplasm selected for fiber content, digestibility, and crude protein yield, typically bred through hybridization or phenotypic selection to produce cultivars with specified germination rates and varietal purity thresholds. Certified seed grades command premium positioning due to traceability requirements under EU seed marketing frameworks, while common grades serve price-sensitive extensive grazing operations in Extremadura. Lucerne retains structural leadership in irrigated systems for dairy protein supplementation, whereas ryegrass varieties capture expanding demand in Atlantic climate zones for silage-intensive beef finishing.
Spain's Ministry of Agriculture enforces EU seed certification protocols through its national variety registry, while BIS-equivalent quality inspections at regional level govern field multiplication standards. The EU Green Deal's nutrient management targets are redirecting procurement toward legume-dominant mixtures that reduce synthetic nitrogen dependency. Stakeholders must monitor CAP tranche negotiations and water allocation rulings from the Tagus and Guadiana basin authorities to anticipate varietal demand shifts.
Market Dynamics
Spain's Common Agricultural Policy alignment with ecological focus area mandates is restructuring farmer seed choices by redirecting procurement toward legume-dominant mixtures that reduce synthetic nitrogen dependency across Castilian dairy corridors and Extremadura's irrigated valleys.
Growth Catalysts
- EU Green Deal nutrient management targets:Legume incorporation mandates are accelerating certified lucerne uptake in dairy protein supplementation systems.
- Extremadura's irrigated valley concentration:Intensive livestock density in these basins supports premium certified seed demand from cooperatives managing water-allocation efficiency.
- Hybridization breeding pipelines:Phenotypic selection advances are improving germination rate consistency and varietal purity thresholds for drought-adapted ryegrass portfolios.
Market Restraints
- Water allocation uncertainty:Tagus and Guadiana basin authority rulings are creating irrigation reliability risk for seed multiplication field contracts.
- Certification cost structure:EU seed marketing framework traceability requirements impose premium pricing that excludes extensive grazing operations in marginal rainfall zones.
- Input concentration in breeding germplasm:Transatlantic breeding pipeline dependency limits domestic cultivar development speed for Iberian drought-cycle adaptation.
Strategic Opportunities
- Andalusian cooperative channel deepening:Wholesale relationship expansion through agricultural cooperative networks can capture price-sensitive volume segments.
- Atlantic climate zone ryegrass penetration:Silage-intensive beef finishing operations in northern Spain present underdeveloped demand for high-digestibility varieties.
- CAP tranche negotiation alignment:Upcoming agricultural policy incentive structures favor early positioning in ecological focus area-compliant seed portfolios.
Industry Challenges
- Field multiplication standard compliance:BIS-equivalent regional quality inspections create timeline compression for certified seed grade batch release.
- Variety registry navigation:Spain's Ministry of Agriculture national registry protocols require specialized regulatory affairs capacity for cultivar approval acceleration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain Forage Seed Market |
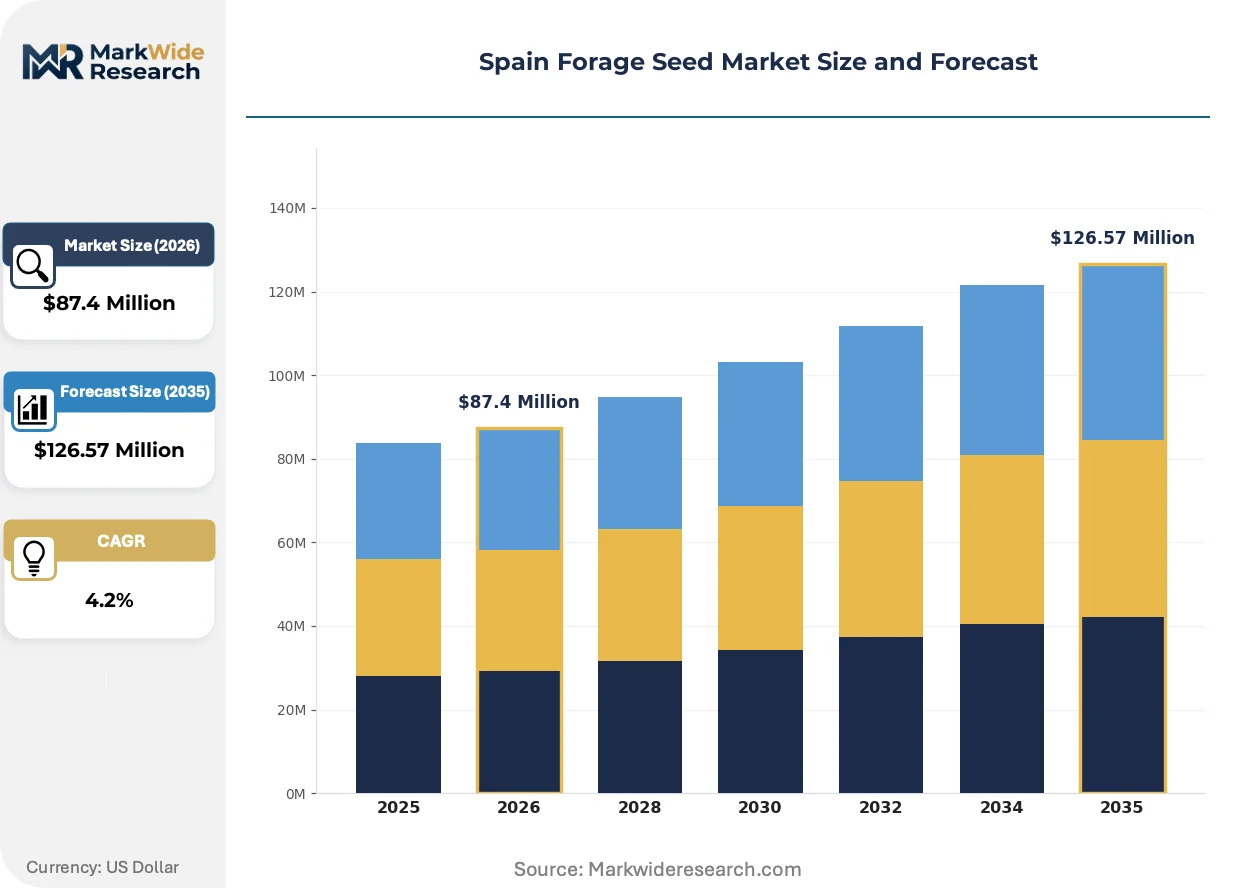
| Market Size in 2026 | $87.4 Million |
| Market Size in 2035 | $126.57 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Crop Type: Lucerne, Clover, Ryegrass, Timothy Seed Grade: Certified, Pre-Commercial, Basic, Common Application: Livestock Feed, Soil Improvement, Bioenergy, Erosion Control Distribution Channel: Wholesale, Retail, Online, Direct Sales |
| Companies Covered | Corteva Agriscience, Pure Seed Europe, DLF Seeds Ltd, Pennington Seed, Grupo Batlle S.A., Advanta Seeds, Semillas Fito, UPL, Tropical Seeds, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain Forage Seed Market Evolving Landscape
Genomic selection tools and precision phenotyping platforms are actively compressing breeding cycle timelines while CAP ecological conditionality rules rewrite procurement specifications across Spanish livestock regions.
Molecular marker-assisted selection is rewriting cultivar development economics by collapsing generational intervals for drought-tolerance traits. Dairy cooperatives in Castile and León are adopting these varieties at accelerated replacement rates. The technology is rewriting competitive positioning by favoring breeders with captive biotech infrastructure over conventional phenotypic programs.
The EU Green Deal's nutrient management targets are mandating legume proportion minimums in forage mixtures for CAP direct payment eligibility. This regulatory pressure is compressing ryegrass-dominant portfolio viability windows. Extremadura's irrigated valley operators are responding by locking multi-year certified lucerne contracts ahead of tranche implementation.
Spanish livestock cooperatives are consolidating procurement authority through centralized seed specification committees that displace individual farm-level purchasing. Andalusian wholesale channels are capturing this volume concentration through exclusive varietal distribution agreements. The behavioral shift is most visible in dairy-dense Castilian provinces where cooperative buying power now dictates certified seed grade tier access.
Spain Forage Seed Market Segmentation
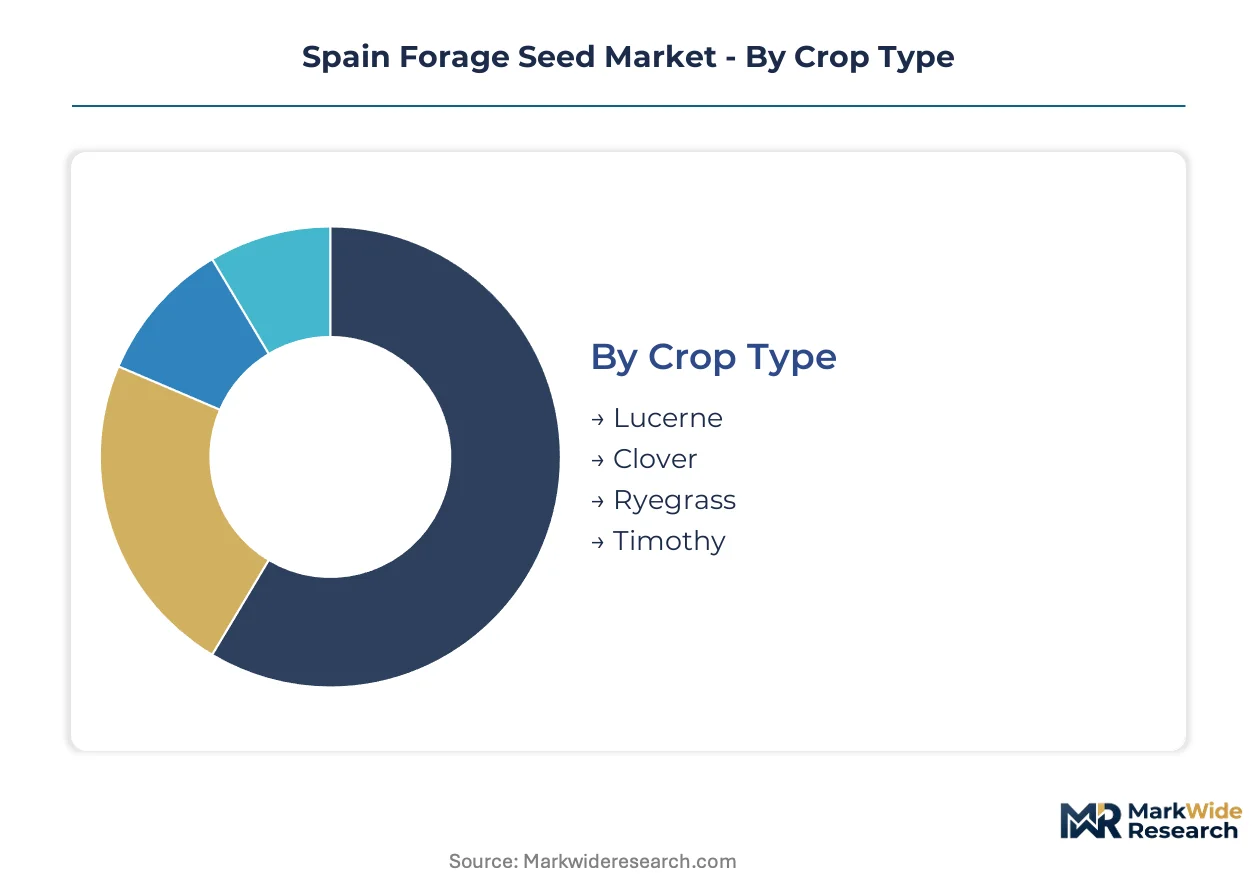
Segmentation in Spain's forage seed market reveals how regulatory pressure and irrigation geography fragment procurement behavior across livestock-dense regions. Distinct specification tiers, distribution channels, and crop-type preferences create divergent margin structures that suppliers must navigate.
Crop Type:
Genetic improvement trajectories and drought-adaptation breeding pipelines differentiate varietal competitiveness across Iberian climate zones.
- Lucerne:Deep-rooted perennial legume bred for crude protein yield and fiber digestibility. Certified lucerne varieties command premium positioning in Castile and León dairy corridors where EU Green Deal nitrogen-reduction mandates accelerate legume incorporation.
- Ryegrass:Annual and perennial varieties selected for rapid establishment and silage energy density. Atlantic climate zones in northern Spain present expanding demand for high-digestibility ryegrass in beef finishing operations.
- Clover:Nitrogen-fixing legume mixtures supporting ecological focus area compliance.
- Timothy:Late-maturing grass species valued for palatability in equine and specialty livestock systems.
Lucerne leads on scale; ryegrass leads on momentum.
Seed Grade:
Certification intensity and traceability requirements stratify pricing power across extensive versus intensive production systems.
- Certified:EU seed marketing framework compliance ensures varietal purity thresholds and germination rate guarantees. Extremadura's irrigated valley cooperatives concentrate procurement here to secure CAP direct payment eligibility through legume-dominant mixtures.
- Pre-Commercial:Intermediate grade supporting field multiplication scale-up before full certification.
- Basic:Foundation stock for certified seed production chains.
- Common:Uncertified seed serving price-sensitive extensive grazing operations in marginal rainfall zones where water allocation uncertainty discourages premium input investment.
Certified grade leads on scale; pre-commercial leads on momentum.
Application:
End-use functionality determines mixture composition and procurement channel selection across livestock cooperatives and individual farm operations.
- Livestock Feed:Dairy protein supplementation and silage-intensive beef finishing dominate volume. Andalusian cooperatives consolidate procurement authority through centralized seed specification committees.
- Soil Improvement:Legume-based mixtures for nitrogen fixation and soil organic matter enhancement.
- Bioenergy:High-biomass varieties for anaerobic digestion feedstock.
- Erosion Control:Deep-rooted perennial establishment for slope stabilization.
Livestock feed leads on scale; soil improvement leads on momentum.
Distribution Channel:
Channel concentration reflects cooperative buying power consolidation and wholesale relationship depth in agricultural input supply chains.
- Wholesale:Deep cooperative relationships capture volume concentration. Grupo Batlle S.A. anchors domestic distribution through Andalusian cooperative networks where centralized procurement now dictates certified seed grade tier access.
- Retail:Agricultural supply stores serving individual farm operations.
- Online:Emerging platform for specification transparency and price comparison.
- Direct Sales:Breeder-to-farm contracts for proprietary varieties.
Wholesale leads on scale; direct sales leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Forage seed cultivation in Spain traces its commercial lineage to the mid-20th century expansion of irrigated agriculture in the Guadiana and Tagus basins, where state-led hydraulic infrastructure enabled perennial legume production at scale.
Castile and León
Dairy cooperative consolidation drives certified lucerne procurement across the Duero basin. Spain's Ministry of Agriculture enforces EU seed certification protocols through regional field inspection offices in Valladolid. The provinces of León and Palencia host the densest concentration of certified seed multiplication contracts for protein-supplementation varieties.
Extremadura
Irrigated valley systems in the Guadiana basin support intensive livestock density that anchors premium seed demand. Water allocation rulings from the Guadiana River Basin Authority create operational uncertainty for seed multiplication field contracts. Cooperatives in Badajoz province are locking multi-year certified lucerne agreements ahead of CAP ecological conditionality implementation.
Andalusia
Wholesale distribution networks capture price-sensitive volume segments through cooperative procurement consolidation. The EU Green Deal's nutrient management targets are redirecting procurement toward legume-dominant mixtures in Córdoba and Seville provinces. Agricultural supply cooperatives in the Guadalquivir valley now dictate certified seed grade tier access through centralized specification committees.
Catalonia
Atlantic climate zones in the Pyrenean foothills present expanding demand for high-digestibility ryegrass in silage-intensive beef finishing. The region's alignment with CAP ecological focus area mandates accelerates legume incorporation in forage mixtures. Girona province hosts emerging field multiplication operations for drought-adapted perennial varieties.
Galicia
Smallholder dairy operations in the Atlantic corridor maintain fragmented procurement patterns resistant to cooperative consolidation. Spain's national variety registry protocols govern cultivar approval timelines for regional breeding programs. Lugo province retains extensive grazing systems where common-grade seed serves price-sensitive demand.
Spain Forage Seed Market Competitive Landscape
The competitive structure tilts toward transnational breeding conglomerates with captive germplasm pipelines. Two strategic tiers have crystallized: integrated agriscience multinationals leveraging transatlantic R&D infrastructure, and regional specialists with deep wholesale relationships in cooperative-dense territories. Dominant competitive moves include exclusive varietal distribution agreements with consolidated procurement committees and backward integration into field multiplication capacity to compress certification timelines.
Among the transnational tier, Corteva Agriscience and DLF Seeds Ltd exemplify divergent approaches to Iberian market penetration. Corteva leverages its transatlantic breeding pipeline to anchor certified lucerne portfolios. DLF competes through specialized ryegrass varieties. Grupo Batlle S.A. occupies a distinct position as a domestic S.A.-structured entity with wholesale channel depth in Andalusian cooperative networks.
| Leading Market Players |
|---|
| Corteva Agriscience |
| Pure Seed Europe |
| DLF Seeds Ltd |
| Pennington Seed |
| Grupo Batlle S.A. |
| Advanta Seeds |
| Semillas Fito |
| UPL |
| Tropical Seeds |
| Others |
Value Network & Pricing Analysis
Specialized agronomists and certified seed technicians concentrated in Castile and León's dairy corridor command wage premiums that compress margin spreads between certified lucerne and common-grade alternatives. Labor-cost differentials between Extremadura's irrigated valley operations and marginal rainfall zones in Galicia directly widen pricing-tier spreads across the three-grade certification system.
Pricing Analysis
Three-tier pricing structure across certified, pre-commercial, and common levels stratifies procurement by traceability intensity and germination guarantees. Price differentiation hinges on EU seed marketing framework compliance costs and volume scale through cooperative channels. Pricing pressure stems from water allocation uncertainty in Guadiana basin multiplication fields that elevates risk premiums. Extensive grazing operations in Lugo province exhibit highest price sensitivity; dairy cooperatives in León show lowest sensitivity due to CAP payment eligibility requirements.
Supply Chain Analysis
Workforce availability constraints in French and Dutch breeding centers limit germplasm pipeline throughput for Iberian drought-adapted varieties. Supply concentrates in Denmark and the Netherlands for ryegrass foundation stock, with French multiplication fields dominating lucerne parent lines. Raw material dependencies include captive breeding germplasm, certified field acreage, and phytosanitary treatment inputs. Single-source vulnerability runs through transatlantic hybridization pipelines. Distribution runs through Andalusian cooperative wholesale networks with centralized specification committees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin-expansion pathways through genomic selection cost-down trajectories that compress breeding cycle economics while CAP ecological conditionality redirects procurement toward premium-certified tiers.
For Market Incumbents: Deepen backward integration into field multiplication capacity across Extremadura's Guadiana valley to compress BIS-equivalent inspection timelines and defend against water allocation disruption. Anchor exclusive varietal distribution through Castilian cooperative procurement committees to lock volume concentration. Corteva's transatlantic pipeline and DLF's drought-adapted ryegrass portfolios demonstrate the defensive value of captive breeding infrastructure. For New Entrants and Emerging Players: E-commerce platform penetration presents a white-space route into fragmented Galician smallholder dairy operations resistant to cooperative consolidation. Target Atlantic climate zone beef finishing segments in Catalonia's Pyrenean foothills where ryegrass demand outpaces specialized supply. A direct-to-farm specification transparency play—emphasizing germination rate guarantees and varietal purity documentation—can displace retail channel opacity. For Investors and Strategic Acquirers: Agricultural cooperative federations are the most active acquirer in this space, consolidating procurement authority through centralized seed specification committees. Long-term viability centers on genomic selection infrastructure ownership and CAP tranche negotiation positioning. Watch for inflection in Tagus and Guadiana basin water allocation rulings that would trigger certified seed contract renegotiation waves.| Strategic Initiative | Industry Significance |
|---|---|
| Genomic Selection Infrastructure Investment | Molecular marker-assisted breeding collapses generational intervals for drought-tolerance traits in ryegrass. |
| Cooperative Procurement Committee Partnership | Exclusive distribution agreements with Andalusian centralized buyers lock multi-year volume commitments. |
| Backward Integration into Field Multiplication | In-house Guadiana valley acreage compresses EU seed certification timeline exposure to water rulings. |
| CAP Ecological Conditionality Portfolio Alignment | Legume-dominant mixture development secures direct payment eligibility for dairy cooperative customers. |
| Atlantic Climate Zone Ryegrass Development | Silage-intensive beef finishing demand in northern Spain offers underpenetrated high-digestibility positioning. |
Research Methodology
Multiple input streams—primary interviews with seed breeding directors, cooperative procurement managers, and Ministry of Agriculture regulatory officers; secondary validation through EU variety registry filings, CAP implementation guidance documents, and river basin authority allocation rulings—were reconciled through bottom-up volume triangulation and top-down value reconciliation.
Data-stream reconciliation across the projection horizon applied segmentation dimensions spanning crop type, seed grade tier, application end-use, and distribution channel concentration. CAGRs were derived from trend extrapolation of certified seed uptake rates and cooperative procurement consolidation patterns, with inputs from genomic selection adoption curves and CAP tranche negotiation timelines.
The model assumes a particular technology adoption path; alternative pathways for molecular marker-assisted breeding penetration would alter the outlook. Forecasts embed assumptions around water allocation stability and CAP ecological conditionality implementation sequencing. Material deviation in Tagus basin rulings or CAP incentive structures warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seeds
Tallow Tree Seed Market
Seeds
Flax Crop Market
Seeds
Okra Seed Market
Seeds
India Vegetable Seed Market
Seeds
Hybrid Rice Seeds Market
Seeds
North America Forage Seed Market
Seeds
Europe Grain Seed Market
Seeds
China Rice Seed Market
Seeds
South America Vegetable Seed Market
Seeds
Psyllium Market
Seeds
Uganda Seeds Market
Seeds
Mexico Vegetable Seed Market
Seeds
Lupin Market
Seeds
Psyllium Seed Market
Seeds
Europe Flaxseeds Market
Seeds
North America Grain Seed Market