
 LAMEA Artificial Humus Market | 2026-2036
LAMEA Artificial Humus Market Size, Share, and Industry Trends Forecast 2026-2036
LAMEA Artificial Humus Market Insights
Subscription-based soil monitoring and replenishment programs is broadening the commercial model beyond one-time product sales. Humintech leverages long-term service contracts to secure recurring revenue from large-scale Brazilian soybean operators. Novihum Technologies GmbH anchors its position through specialized granular formulations engineered for tropical acidity conditions. Nature's Force Organics differentiates via direct agronomist support bundled with every bulk delivery.
Artificial humus denotes a manufactured soil amendment designed to replicate the structural and biological functions of natural humus, typically composed of processed lignitic materials, composted biomass, or chemically stabilized organic polymers with specified cation exchange capacity exceeding 50 cmol/kg. Its primary commercial purpose centers on restoring soil organic carbon depleted by intensive monoculture regimes while improving water retention and nutrient buffering in sandy or lateritic substrates. Granular formulations dominate volume shipments across LAMEA due to mechanical compatibility with existing spreader infrastructure and lower dust exposure during handling. Liquid artificial humus represents the fastest-expanding product category, particularly in precision fertigation systems deployed on Chilean vineyard estates and Moroccan greenhouse complexes. Agricultural cooperatives constitute the deepest margin pool among client types, as collective procurement agreements secure multi-year offtake commitments and reduce customer acquisition overhead.
Brazil's Ministry of Agriculture (MAPA) enforces stringent organic input registry requirements under its national fertilizer legislation, compelling foreign suppliers to complete multi-stage efficacy trials before market authorization. South Africa's Fertilizer Association of Southern Africa (FERTASA) maintains voluntary quality protocols that increasingly influence insurer-backed crop protection policies and commercial lending terms for input purchases. The UAE's Ministry of Climate Change and Environment (MOCCAE) has integrated artificial soil amendments into its national food security strategy, creating preferential procurement channels for domestic greenhouse developers. Stakeholders must track how evolving carbon credit methodologies treat manufactured humus relative to composted alternatives, as this classification will determine eligibility for offset-linked financing instruments.
Market Dynamics
Soil organic carbon depletion across Brazil's Cerrado and South Africa's grain belts is forcing agricultural cooperatives toward manufactured humus solutions that bypass multi-year composting cycles. This structural pressure from degraded land economics is compressing adoption timelines and reshaping supplier relationships across the LAMEA region.
Growth Catalysts
- MAPA Organic Input Registry:Brazil's multi-stage efficacy trial mandate is filtering out unverified suppliers and elevating demand for documented artificial humus products with proven cation exchange capacity.
- Degraded Pasture Conversion:Large-scale Brazilian soybean operators are converting former cattle grazing lands into intensive crop production, creating recurring bulk demand for soil restoration amendments.
- Lignitic Material Processing:Advanced oxidation and stabilization technologies are enabling consistent humic acid yields from low-grade coal deposits found across South Africa and Chile.
Market Restraints
- Input Cost Volatility:Energy-intensive drying and granulation processes expose producers to natural gas price swings that compress margin structures on standard-grade formulations.
- Supply Concentration Risk:Premium leonardite deposits suitable for high-CEC artificial humus production cluster in specific mining districts of Mexico and Turkey, creating geographic dependency.
- Technical Limitation:Current polymer stabilization chemistries degrade under sustained ultraviolet exposure above 35 degrees Celsius, limiting shelf life in open-field storage across North African markets.
Strategic Opportunities
- UAE Food Security Procurement:MOCCAE's preferential channels for domestic greenhouse developers create a captured demand pool for liquid artificial humus compatible with drip irrigation infrastructure.
- Carbon Credit Methodology Alignment:Evolving voluntary carbon market protocols for manufactured soil amendments could unlock offset-linked financing instruments for Brazilian restoration projects.
- Precision Fertigation Convergence:Integration of artificial humus with sensor-based nutrient delivery systems is opening vineyard and protected-crop segments in Chile and Morocco.
Industry Challenges
- Agronomic Expertise Scarcity:Field-level calibration of artificial humus application rates requires soil science competencies that remain concentrated in university extension services rather than commercial distribution networks.
- FERTASA Certification Timelines:South Africa's voluntary quality protocol audits extend 14-18 months, delaying market entry for new suppliers targeting insurer-backed crop protection policies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | LAMEA Artificial Humus Market |
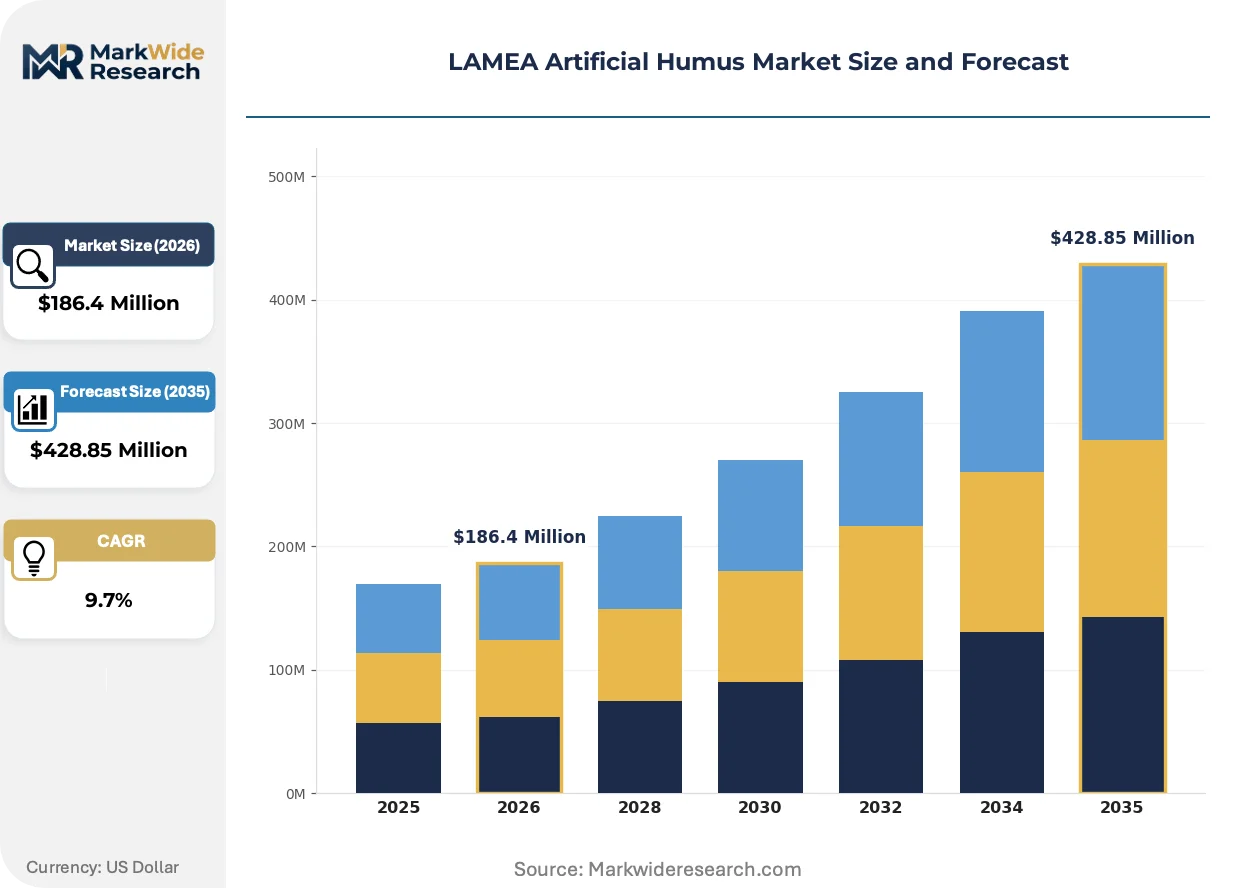
| Market Size in 2026 | $186.4 Million |
| Market Size in 2035 | $428.85 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granular, Liquid, Powder, Pellets Application: Agriculture, Landscaping, Horticulture, Soil Enhancement Distribution Channel: Retail, E-commerce, Wholesale, Direct Sales Client Type: Farmers, Gardeners, Landscaping Companies, Agricultural Cooperatives |
| Companies Covered | Humusolver, The Fertrell Company, Ohio Earth Food, Novihum Technologies GmbH, Humintech, Organic Approach, Nature's Force Organics, Faust Bio-Agricultural Services, Agbest Technology Co.,Ltd., Others |
| Regions Covered | LAMEA: Brazil, Mexico, Argentina, Saudi Arabia, UAE, South Africa, Nigeria, Egypt, Rest of LAMEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
LAMEA Artificial Humus Market Trends and Innovations
Liquid artificial humus formulations are capturing share from established granular products as precision agriculture infrastructure spreads across LAMEA's high-value crop zones. This transition is compressing traditional supply relationships and demanding new technical service capabilities from manufacturers.
Enzymatic liquefaction of lignitic feedstocks is overtaking conventional alkaline extraction methods in commercial production facilities. The enzymatic route delivers higher humic acid bioavailability and lower sodium residue, traits that Chilean vineyard estates and Moroccan greenhouse operators prioritize in fertigation compatibility testing. This technology is overtaking legacy processes among mid-scale processors seeking differentiation in premium segments.
South Africa's Department of Agriculture, Land Reform and Rural Development has tightened organic input certification requirements, compelling growers toward verified artificial humus products with documented cation exchange capacity. The regulatory friction is elevating compliance costs for smaller composting operations while creating structural advantage for manufactured alternatives with standardized analytical certificates. Brazilian cooperatives are responding by demanding batch-specific test documentation that mirrors pharmaceutical-grade traceability.
Collective procurement agreements among agricultural cooperatives are displacing individual farm-level purchasing across Brazil's Mato Grosso and Goiás production zones. These multi-year offtake contracts aggregate volume commitments and reduce customer acquisition overhead for suppliers willing to embed agronomist support into service bundles. The behavioral shift is most visible among soybean operators converting degraded pasture, where soil restoration represents a multi-season investment requiring technical partnership rather than transactional supply.
LAMEA Artificial Humus Market Segmentation
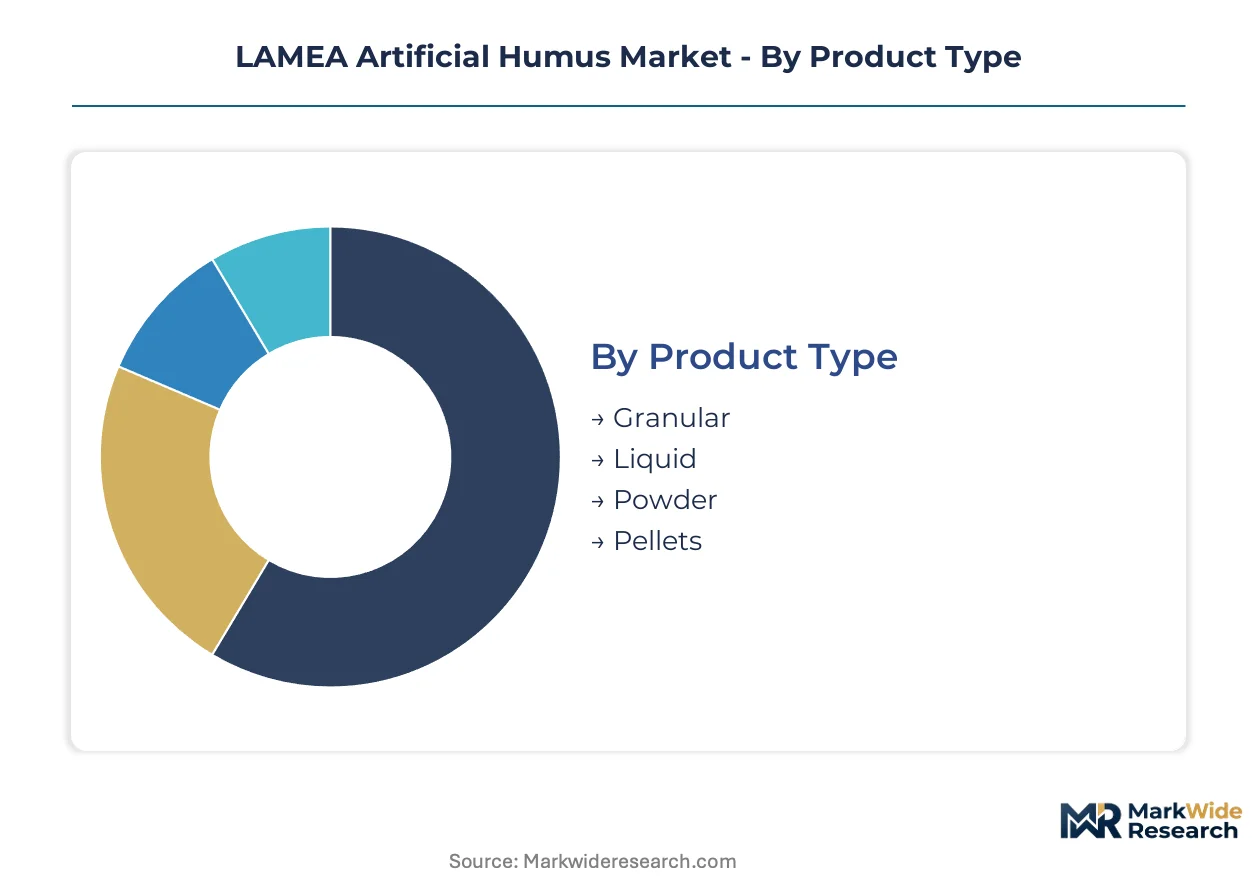
Segmentation in the LAMEA artificial humus market reveals distinct technical and commercial boundaries that determine pricing power and service requirements. Product form factors dictate compatibility with existing farm infrastructure, while client structure shapes contract duration and margin profiles across the region.
Product Type:
Granular formulations integrate directly into mechanical spreader systems without equipment modification, while liquid and powder variants demand specialized handling infrastructure.
- Granular:Composed of stabilized lignitic particles sized 2-4mm for mechanical spreading compatibility. Brazilian soybean operators in Mato Grosso deploy this format for degraded pasture conversion, where dust suppression and storage stability outweigh premium pricing.
- Liquid:Suspended humic acid concentrates engineered for fertigation injection. Chilean vineyard estates and Moroccan greenhouse complexes are standardizing on this format for precision nutrient delivery, though UV degradation above 35°C limits open-field storage.
- Powder:Fine-milled leonardite derivatives requiring sealed transport and dust-controlled handling. South African grain cooperatives favor this grade for on-farm blending with compound fertilizers.
- Pellets:Compressed formulations with slow-release coatings for extended nutrient availability. Landscaping contractors across UAE urban developments specify this grade for reduced application frequency.
Granular leads volumes today; liquid is gaining share fastest.
Application:
Application segments diverge sharply in performance requirements and procurement sophistication, with commercial agriculture demanding documented cation exchange capacity while ornamental segments prioritize visual and handling properties.
- Agriculture:Intensive monoculture restoration requiring specified organic carbon replenishment. Brazil's Cerrado belt drives bulk procurement for soybean and corn systems, with MAPA registry compliance mandatory for market access.
- Horticulture:Protected-crop production in controlled environments. Moroccan greenhouse complexes and Chilean berry operations specify low-sodium liquid formulations for drip irrigation compatibility.
- Landscaping:Urban greening and golf course maintenance across UAE and South African metropolitan zones. Procurement emphasizes dust-free handling and rapid turf establishment.
- Soil Enhancement:Standalone restoration projects on mining-degraded or construction-disturbed sites. South Africa's Department of Agriculture, Land Reform and Rural Development certification requirements filter supplier eligibility.
Agriculture commands the deepest contract values; horticulture shows the steepest expansion trajectory.
Distribution Channel:
Channel structure reflects customer scale and technical service intensity, with direct relationships dominating where application calibration requires agronomist support.
- Direct Sales:Manufacturer-to-cooperative contracts embedding technical service. Brazilian agricultural cooperatives in Goiás aggregate multi-year volume commitments through this channel.
- Wholesale:Distributor networks serving mid-scale farming operations. South Africa's FERTASA-certified wholesalers control access to insurer-backed crop protection policies.
- Retail:Agricultural supply stores and garden centers. Limited penetration due to bulk handling requirements and technical consultation needs.
- E-commerce:Emerging platform for standardized formulations and documented specifications. UAE greenhouse developers pilot procurement through MOCCAE-integrated digital channels.
Direct sales anchor revenue concentration; e-commerce is expanding most quickly.
Client Type:
Client structure determines contract economics, with collective entities capturing volume discounts while individual operators drive premium formulation demand.
- Agricultural Cooperatives:Collective procurement entities aggregating hectare-scale demand. Brazil's Mato Grosso and Goiás cooperatives secure multi-year offtake agreements with embedded agronomist support.
- Farmers:Individual commercial operators, predominantly in degraded pasture conversion. Technical expertise scarcity forces reliance on supplier-provided calibration services.
- Landscaping Companies:Urban development and golf course contractors. UAE-based operators access MOCCAE preferential procurement channels for domestic greenhouse projects.
- Gardeners:Small-scale residential and hobbyist users. Minimal market presence due to product bulk and application complexity.
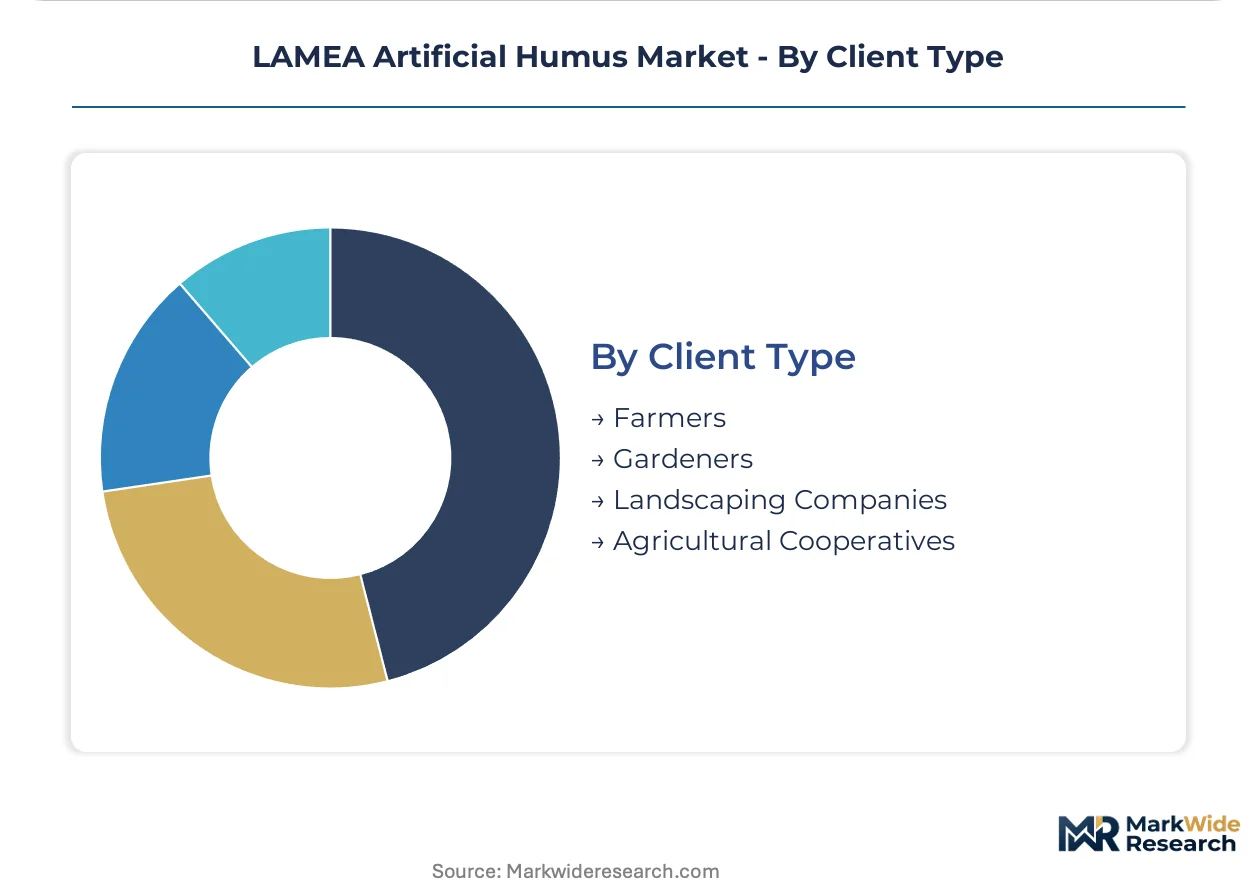
Agricultural cooperatives dominate transaction values; farmers represent the broadest addressable base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil generates volume concentration unmatched elsewhere in LAMEA, while South Africa's regulatory tightening creates premium positioning opportunities for certified suppliers. Mexico's mining-derived feedstock access and Chile's precision agriculture infrastructure round out the regional demand map.
Brazil
Soybean operators in Mato Grosso and Goiás are converting degraded pasture at scale, driving bulk procurement of granular formulations. MAPA's multi-stage efficacy trial mandate filters out unverified suppliers and elevates demand for documented cation exchange capacity. The Cerrado agricultural belt anchors recurring demand from agricultural cooperatives aggregating hectare-scale commitments.
South Africa
Grain belt soil organic carbon depletion is forcing cooperatives toward manufactured humus that bypasses multi-year composting cycles. The Department of Agriculture, Land Reform and Rural Development has tightened organic input certification requirements. FERTASA voluntary quality protocol audits extend 14-18 months, delaying market entry for new suppliers targeting insurer-backed crop protection policies.
Mexico
Leonardite mining districts supply premium feedstock for high-CEC artificial humus production, creating geographic concentration in specific extraction zones. The national fertilizer regulatory framework requires efficacy documentation for commercial distribution. Northern mining regions feed processing facilities serving cross-border demand from US southwestern agricultural operations.
Chile
Vineyard estates in central valley zones are standardizing on liquid formulations for precision fertigation systems. The national agricultural service mandates residue testing for imported soil amendments. Metropolitan Santiago greenhouse complexes pilot enzymatic liquefaction products for drip irrigation compatibility.
United Arab Emirates
MOCCAE has integrated artificial soil amendments into its national food security strategy, creating preferential procurement channels for domestic greenhouse developers. Dubai-based controlled-environment agriculture projects specify liquid formulations compatible with drip infrastructure. Abu Dhabi urban landscaping contractors access subsidized supply lines for turf establishment projects.
LAMEA Artificial Humus Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with formulation expertise commanding premium positioning in certified markets while toll processors capture volume in bulk agriculture. The vendor base clusters around three strategic archetypes: lignitic feedstock processors with captive mining access, enzymatic technology licensors with proprietary extraction methods, and service-integrated distributors bundling agronomist support. Competitive moves concentrate on backward integration into leonardite mining concessions and technology licensing partnerships that accelerate MAPA registry approval timelines.
Within the technology-specialist tier, Novihum Technologies GmbH and Humintech exemplify divergent geographic anchoring strategies, with the former occupying a position calibrated for European regulatory export standards and the latter representing service-contract depth in Brazilian cooperative channels. Nature's Force Organics sits within the agronomist-integrated distribution archetype, bundling technical consultation with bulk delivery logistics. These three entities collectively illustrate how competitive positioning in LAMEA artificial humus markets depends on regulatory navigation capability, feedstock security, and field-level technical service density rather than manufacturing scale alone.
| Leading Market Players |
|---|
| Humusolver |
| The Fertrell Company |
| Ohio Earth Food |
| Novihum Technologies GmbH |
| Humintech |
| Organic Approach |
| Nature's Force Organics |
| Faust Bio-Agricultural Services |
| Agbest Technology Co.,Ltd. |
| Others |
Pricing and Supply Chain Analysis
MAPA's multi-stage efficacy trial mandate gates qualified supply access and premium-tier pricing power for artificial humus manufacturers serving Brazil's agricultural cooperatives. Suppliers lacking documented cation exchange capacity face exclusion from collective procurement agreements while certified entrants capture margin premiums through multi-year service contracts.
Pricing Analysis
Capacity additions in South Africa's lignitic processing corridor are reshaping price floors for standard-grade granular formulations. Three-tier pricing structure across premium MAPA-certified, FERTASA-compliant standard, and uncertified economy levels separates Brazilian cooperative contracts from South African grain-belt offtake and spot-market powder sales. Cost compression in economy tiers intensifies because energy-intensive drying exposes producers to natural gas volatility. Agricultural cooperatives in Mato Grosso exhibit lowest price sensitivity due to embedded agronomist services, while individual pasture-conversion operators drive hardest volume negotiations.
Supply Chain Analysis
Single-source vulnerability sits with Mexico's leonardite mining districts feeding high-CEC artificial humus production. Feedstock draws from Mexican extraction zones, South African low-grade coal deposits, and Chilean lignitic reserves. Supply chain risk centers on geographic concentration of premium leonardite suitable for tropical acidity formulations. Distribution runs through FERTASA-certified South African wholesalers, Brazilian cooperative direct contracts, and MOCCAE-integrated UAE procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where Brazil's MAPA registry milestones and South Africa's certification tightening create structural demand for verified artificial humus products with documented performance metrics.
For Market Incumbents: To counter enzymatic liquefaction technology licensors entering premium segments, Humintech and Novihum Technologies GmbH should deepen backward integration into captive leonardite concessions in Mexico and accelerate MAPA registry approval timelines through dedicated regulatory affairs capacity in Brasília. Certification investment represents the critical defensive lever against commoditization in Brazilian cooperative channels. For New Entrants and Emerging Players: Enter via UAE's MOCCAE preferential procurement channels for liquid formulations serving domestic greenhouse developers, where technical service requirements remain undersupplied relative to Brazilian market saturation. White-space concentration sits with precision fertigation integration for Chilean vineyard estates and Moroccan protected-crop operators. Go-to-market leverage comes through enzymatic technology licensing partnerships that bypass multi-year efficacy trial timelines. For Investors and Strategic Acquirers: Roll-up economics work for mid-scale lignitic processors with FERTASA audit progress because South Africa's 14-18 month certification timelines create acquisition windows before independent completion. Five-to-ten year viability hinges on carbon credit methodology alignment for manufactured soil amendments. The signal to watch is evolving voluntary carbon market protocol classification determining offset-linked financing eligibility for Brazilian restoration projects.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Leonardite Mining | Captive feedstock access insulates margin structures from Mexican deposit concentration risk. |
| MAPA Registry Acceleration Program | Dedicated regulatory capacity in Brasília compresses multi-stage efficacy trial timelines for market authorization. |
| Enzymatic Liquefaction Licensing | Technology partnerships enable differentiation through higher humic acid bioavailability for Chilean vineyard estates. |
| Multi-Year Cooperative Service Contracts | Embedded agronomist support locks in recurring revenue from Brazilian soybean operators in Mato Grosso. |
| Carbon Credit Methodology Alignment | Protocol classification work unlocks offset-linked financing for degraded pasture conversion projects. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary engagement captured agronomists at Brazilian agricultural cooperatives, regulatory affairs leads navigating MAPA and FERTASA protocols, procurement officers at UAE greenhouse developers, and technical directors at Chilean vineyard estates. Secondary validation drew from MAPA fertilizer registry filings, FERTASA certification audit records, MOCCAE food security strategy documents, and South African customs data on lignitic material imports. Bottom-up volume aggregation from cooperative offtake agreements triangulated against top-down market sizing from processing capacity assessments.
Segment-weighting applied differential growth assumptions across product form factors, with liquid formulations assigned accelerated trajectories reflecting precision fertigation infrastructure expansion in Chile and Morocco. Modeled dimensions spanned granular-liquid-powder-pellet product types, agriculture-horticulture-landscaping-soil enhancement applications, and direct-wholesale-retail-e-commerce channels. CAGRs derived from regression analysis of historical procurement volumes against regulatory milestone timing and degraded pasture conversion rates.
Inputs from MAPA registry filings and FERTASA audit records were available through the study window; gaps in private cooperative contract terms introduce uncertainty bands around volume concentration estimates. Forecasts reflect documented assumptions regarding certification timeline progression and carbon credit methodology evolution. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Europe Poultry Feed Market
Agriculture and Agri Products
Kenya Floriculture Market
Agriculture and Agri Products
Frozen Egg Market
Agriculture and Agri Products
Sorghum by-Products Market
Agriculture and Agri Products
Japan Compound Feed Market
Agriculture and Agri Products
Alfalfa Market
Agriculture and Agri Products
Russia Compound Feed Market
Agriculture and Agri Products
Mushroom Cultivation Market
Agriculture and Agri Products
Philippines Feed Industry Market
Agriculture and Agri Products
South America Poultry Feed Market
Agriculture and Agri Products
North America Swine Feed Premix Market
Agriculture and Agri Products
Japan Floriculture Market
Agriculture and Agri Products
Canada Bamboos Market
Agriculture and Agri Products
Centella Asiatica Market
Agriculture and Agri Products
Ethiopia Agriculture Sector Market
Agriculture and Agri Products
Australia Animal Protein Market