
 United Arab Emirates Poultry Meat Market | 2026-2036
United Arab Emirates Poultry Meat Market Size, Share, and Industry Trends Forecast 2026-2036
United Arab Emirates Poultry Meat Market Analytics
Expatriate veterinary and halal processing expertise is collapsing as a bottleneck, forcing producers to recruit from South Asian and North African labor pools. Al Ain Farms for Livestock Production anchors production scale through captive feed milling and hatchery operations. Tanmiah Food Company differentiates via controlled-atmosphere stunning and automated evisceration lines. Al Islami Foods dominates UAE retail freezer space through long-standing hypermarket slotting arrangements.
United Arab Emirates poultry meat encompasses broiler chicken raised under halal-compliant conditions, typically slaughtered by hand or mechanical blade with recitation, chilled to four degrees Celsius within two hours, and distributed as fresh, frozen, or value-added cuts for retail and food service consumption. Whole chicken and chicken breasts lead volume, though organic and pre-cooked processing methods capture widening margin pools as health-positioned consumers trade up. Hotels and restaurants represent the fastest-growing end user segment, while supermarkets and hypermarkets control the bulk of distribution channel throughput.
MOHAP enforces halal integrity and cold-chain compliance through facility audits and product traceability mandates, while Emirates Authority for Standardization and Metrology governs labeling and shelf-life declarations. These frameworks elevate capital requirements for new entrants and favor incumbents with certified in-house slaughter and blast-freezing infrastructure. Stakeholders must monitor feed grain import cost volatility and labor quota policy shifts as determinants of margin sustainability.
Market Dynamics
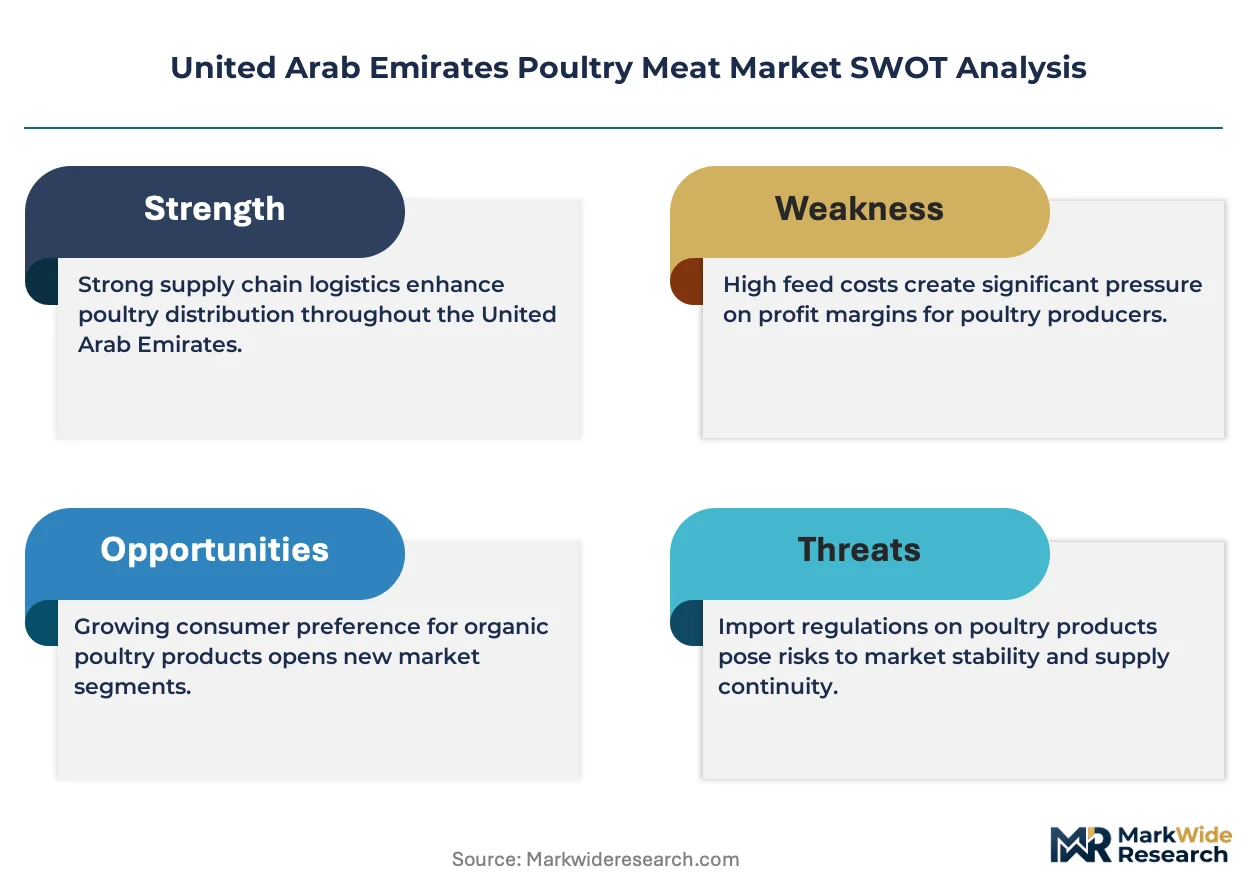
MOHAP's tightened halal certification protocols and cold-chain standards are compressing supplier margins while elevating compliance costs, forcing consolidation among smaller processors unable to fund certified in-house slaughter and blast-freezing infrastructure.
Growth Catalysts
- Tourism-driven hospitality procurement:Dubai's hotel and restaurant clusters are absorbing premium fresh and organic poultry volumes as menu diversification accelerates.
- MOHAP halal integrity mandates:Facility audits and product traceability requirements favor incumbents with certified infrastructure, locking in compliant supplier relationships.
- Controlled-atmosphere stunning:Automated evisceration and mechanical blade slaughter with recitation are reducing labor dependency while preserving halal compliance.
Market Restraints
- Feed grain import cost volatility:UAE producers rely entirely on imported corn and soybean meal, exposing margins to Black Sea and South American supply disruptions.
- Expatriate veterinary expertise collapse:South Asian and North African labor pool recruitment is failing to fill halal processing and flock health management gaps.
- Capital intensity of cold-chain compliance:Blast-freezing infrastructure and continuous temperature monitoring systems require substantial upfront investment.
Strategic Opportunities
- Organic and pre-cooked processing segments:Health-positioned consumers in Dubai's food service corridor are trading up from conventional whole chicken and breast cuts.
- Abu Dhabi hospitality corridor expansion:Underpenetrated five-star and resort properties present volume growth potential for certified premium suppliers.
- Captive feed milling integration:Producers securing upstream control over feed supply can buffer import price shocks and guarantee flock uniformity.
Industry Challenges
- Halal certification timeline compression:MOHAP facility audits and documentation requirements are extending product-to-market cycles for new entrants.
- Labor quota policy volatility:Shifting Ministry of Human Resources and Emiratisation work permit frameworks disrupt processing line staffing predictability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Arab Emirates Poultry Meat Market |
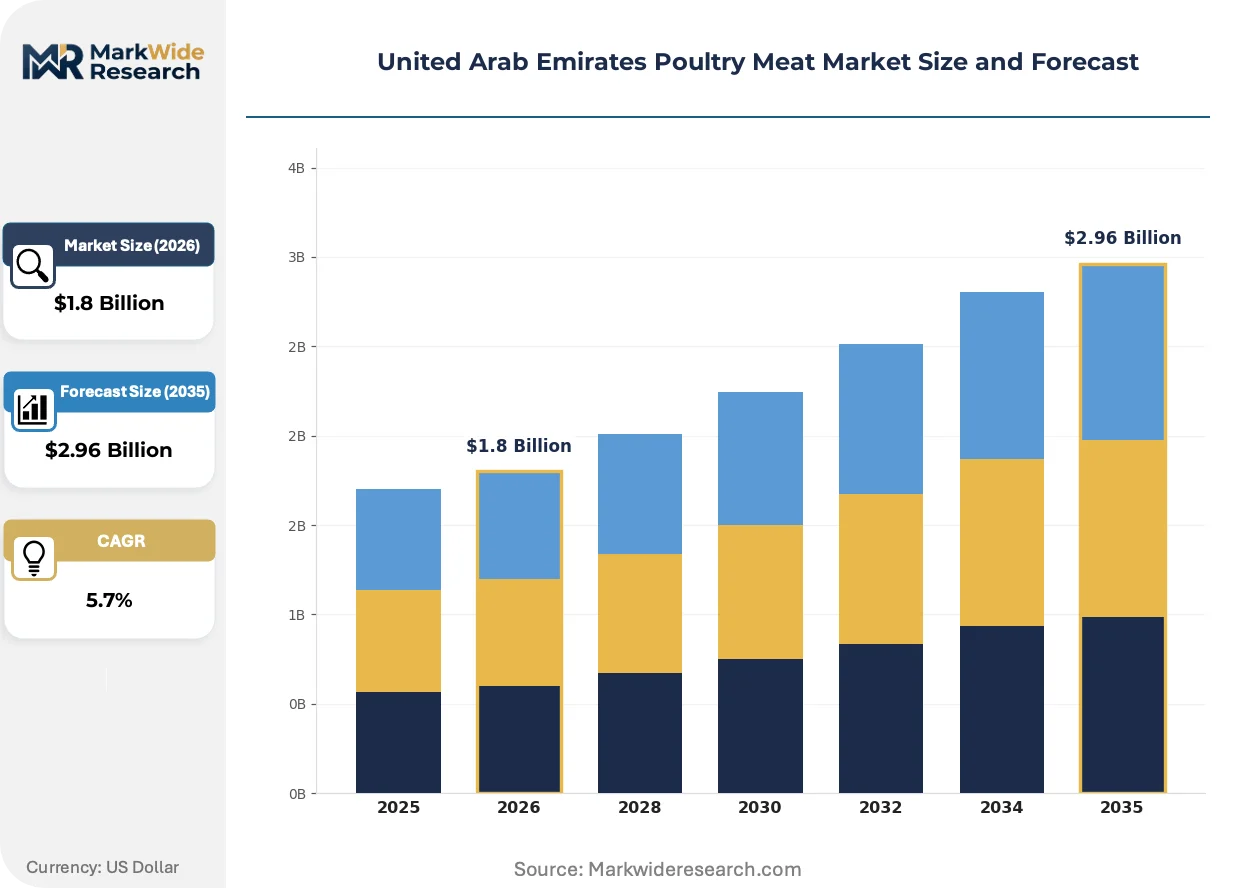
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whole Chicken, Chicken Breasts, Chicken Thighs, Chicken Wings Distribution Channel: Supermarkets, Hypermarkets, Online Retail, Convenience Stores Processing Method: Fresh, Frozen, Pre-Cooked, Organic End User: Retail Consumers, Food Service, Hotels, Restaurants |
| Companies Covered | Al Ain Farms for Livestock Production (AAF), Al Islami Foods, Al Rawdah, Universal Islamic Food Industries, Al Ghurair Foods, Emirates Poultry Farm (Al Bustan), Green Farms Poultry Industries, Tanmiah Food Company, Agthia Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Arab Emirates Poultry Meat Market Evolving Landscape
Processing automation and certification digitization are restructuring competitive advantage, while demand-side preference shifts toward traceable origin claims are fragmenting traditional retail and food service procurement patterns.
Controlled-atmosphere stunning systems with integrated mechanical blade slaughter are replacing manual hand-slaughter operations in large-scale UAE facilities. Hotel and restaurant procurement teams are specifying these systems in supplier qualification questionnaires. The technology is bifurcating the market into automated-compliant and manual-traditional supply tiers with diverging cost structures.
MOHAP's product traceability mandates now require blockchain-enabled batch documentation from hatchery to retail shelf. This regulatory shift is forcing processor investment in ERP-integrated cold-chain monitoring. Fresh and premium segments are absorbing compliance costs fastest, while frozen commodity suppliers face margin compression.
Hypermarket slotting arrangements for long-standing freezer space holders are facing disintermediation pressure from direct-to-hotel procurement platforms. Food service buyers in Dubai's tourism corridor are consolidating volumes through specialized poultry distributors offering certified origin documentation. This channel shift is most visible in five-star hotel clusters where procurement teams prioritize traceability over price.
United Arab Emirates Poultry Meat Market Segmentation
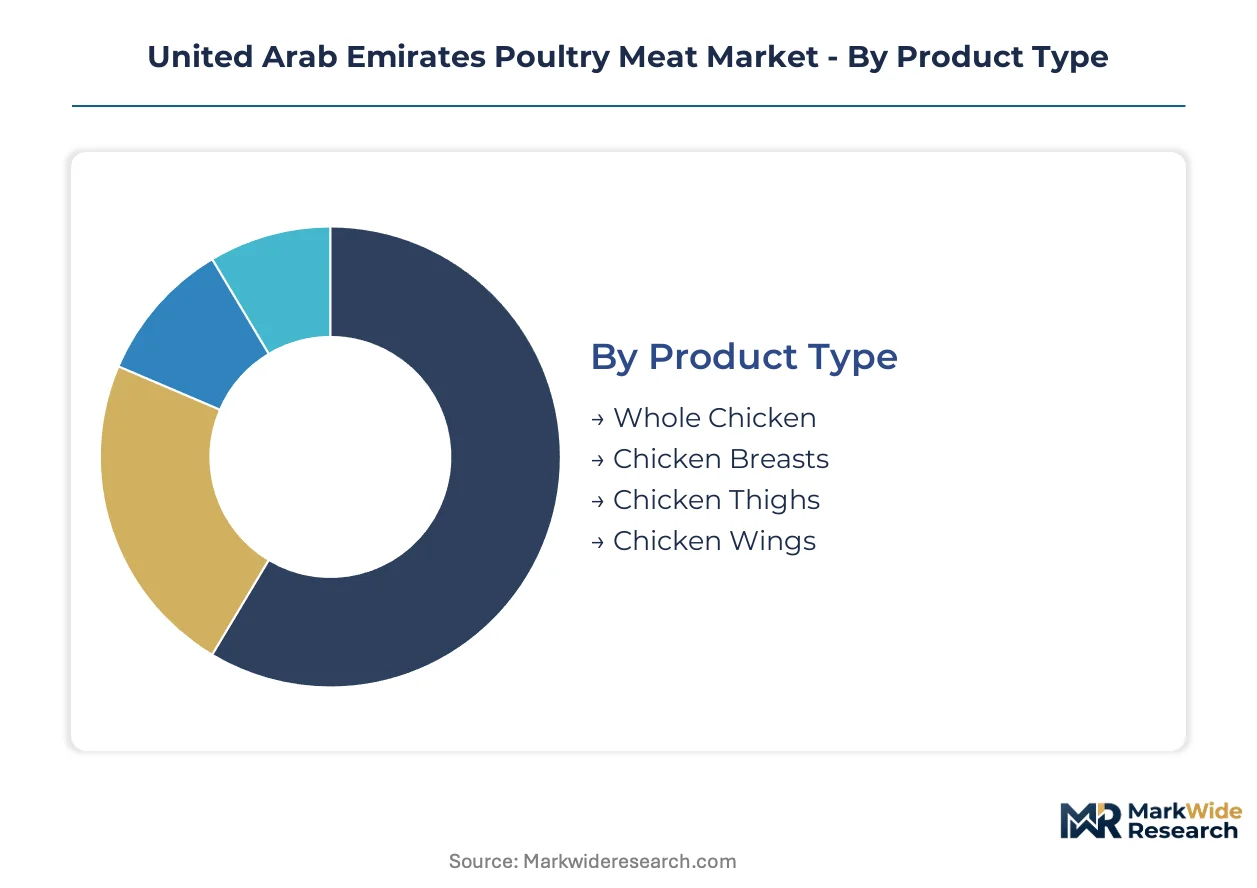
Segmentation in UAE poultry meat tracks how halal compliance requirements, cold-chain infrastructure, and hospitality procurement patterns split demand across product formats and channel tiers. Each category reveals distinct margin structures and regulatory exposure profiles.
Product Type:
Substitution pressure runs strongest against commodity cuts as food service buyers trade toward value-added formats with certified origin documentation.
- Whole Chicken:Standard broiler carcasses processed under MOHAP halal protocols dominate household retail volumes in Dubai's residential corridors. Abu Dhabi hospitality clusters absorb whole bird deliveries for in-house butchery operations where chefs control portion yield and presentation format.
- Chicken Breasts:Boneless skinless cuts command premium positioning across hotel breakfast buffets and airline catering contracts. Dubai International Airport's F&B concessions drive concentrated procurement of individually quick-frozen breast portions with full batch traceability.
- Chicken Thighs:Dark meat segments serve price-sensitive food service accounts and South Asian consumer households in Sharjah and Ajman.
- Chicken Wings:Small-cut portions concentrate in casual dining and delivery-focused restaurant formats.
Whole Chicken retains volume leadership; Chicken Breasts holds the steepest expansion curve.
Distribution Channel:
Channel cost tiers stratify sharply between capital-intensive cold-chain operators and last-mile convenience formats with limited refrigeration capacity.
- Supermarkets:Mid-format grocery chains with dedicated halal meat counters serve residential neighborhoods across Dubai's outer districts. These outlets balance fresh case turnover against frozen backup inventory to manage MOHAP temperature compliance.
- Hypermarkets:Large-format operators control freezer aisle positioning through long-standing slotting arrangements with incumbent suppliers. Al Islami Foods maintains dominant shelf presence in Dubai Mall and Mall of the Emirates locations.
- Online Retail:Delivery platforms with temperature-controlled logistics are capturing hospitality procurement volumes previously routed through traditional distributors.
- Convenience Stores:Small-footprint outlets with limited cold storage concentrate on frozen commodity packs for immediate consumption.
Hypermarkets retain volume leadership; Online Retail is climbing the fastest.
Processing Method:
Application requirements split sharply between food service operators demanding fresh flexibility and retail buyers accepting frozen stability.
- Fresh:Chilled product maintained at four degrees Celsius from slaughter through retail display commands premium positioning in Dubai's five-star hotel procurement. Tanmiah Food Company's controlled-atmosphere stunning facilities supply this segment with reduced labor dependency.
- Frozen:Blast-frozen at minus eighteen degrees Celsius within two hours of slaughter, this format enables inventory buffer for price-volatile import feed environments. Al Ain Farms leverages captive feed milling to stabilize frozen product margins.
- Pre-Cooked:Value-added segments target health-positioned consumers seeking convenience without preparation time.
- Organic:Certified flock management with specified feed regimens captures widening margin pools in expatriate-heavy Dubai districts.
Frozen retains volume leadership; Organic is gaining share fastest.
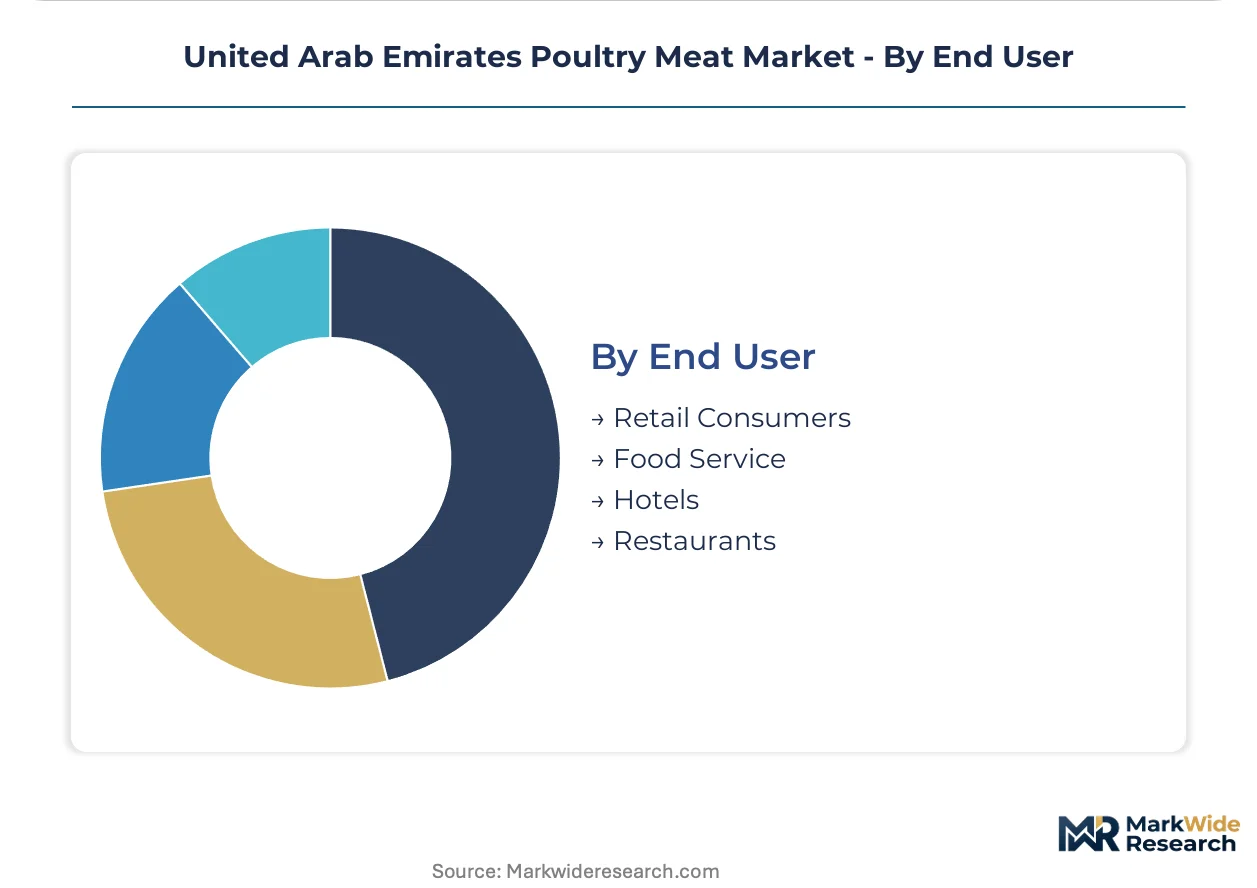
End User:
Customer type determines certification stringency, with hospitality accounts imposing supplier qualification barriers that exclude smaller processors.
- Retail Consumers:Household purchasers across UAE emirates select based on price visibility and halal certification mark recognition. Supermarket meat counters remain the dominant purchase location for family meal preparation.
- Food Service:Institutional caterers and centralized kitchens in Dubai's business district demand consistent portion sizing and delivery reliability. These buyers consolidate volumes through specialized poultry distributors with certified cold-chain documentation.
- Hotels:Five-star properties in Dubai's tourism corridor specify mechanical blade slaughter with recitation and blockchain-enabled batch tracking.
- Restaurants:Independent operators and chain formats balance cost control against menu differentiation requirements.
Retail Consumers retain volume leadership; Hotels holds the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dubai commands premium pricing power over Abu Dhabi hospitality corridors, while Sharjah and Northern Emirates compete on volume throughput. This asymmetry shapes procurement patterns across the federation's seven emirates.
Dubai
Five-star hotel clusters along Sheikh Zayed Road and Downtown Dubai absorb premium fresh poultry volumes with blockchain traceability requirements. MOHAP facility audits enforce halal integrity mandates that exclude uncertified suppliers. Dubai Mall and Mall of the Emirates anchor retail distribution through dominant hypermarket slotting arrangements.
Abu Dhabi
Resort properties on Saadiyat Island and Yas Island drive hospitality procurement expansion with mechanical blade slaughter specifications. The emirate's food safety authority aligns with federal MOHAP standards while adding emirate-level documentation layers. Khalifa Industrial Zone hosts processing facilities serving both local food service and export re-export channels.
Sharjah
South Asian consumer households concentrate demand for price-sensitive dark meat cuts and whole chicken formats. Industrial poultry processing zones near Sharjah International Airport benefit from lower land costs than Dubai counterparts. The emirate's logistics infrastructure supports frozen commodity distribution across northern emirates.
Northern Emirates
Ajman, Umm Al Quwain, Ras Al Khaimah, and Fujairah present underpenetrated retail and food service opportunities with limited local processing capacity. Federal labor quota policies create staffing unpredictability for processors considering facility expansion. These emirates rely heavily on Dubai-based distributors for temperature-controlled last-mile delivery.
United Arab Emirates Poultry Meat Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the UAE poultry meat market. Automated processing facilities with controlled-atmosphere stunning command premium positioning in hospitality procurement, while volume-driven frozen commodity suppliers compete on feed cost management and distribution scale. The market structure bifurcates into integrated producers with captive hatchery and feed milling operations versus specialized processors dependent on third-party supply. Dominant competitive moves include backward integration into upstream feed supply and certification-driven customer lock-in through MOHAP-compliant infrastructure investments.
Within the integrated production tier, Al Ain Farms for Livestock Production and Tanmiah Food Company exemplify scale-driven archetypes with in-house supply chain control. Al Islami Foods occupies a position representing long-standing retail distribution dominance through hypermarket channel relationships. These three entities anchor the competitive landscape across fresh, frozen, and value-added processing segments.
| Leading Market Players |
|---|
| Al Ain Farms for Livestock Production (AAF) |
| Al Islami Foods |
| Al Rawdah |
| Universal Islamic Food Industries |
| Al Ghurair Foods |
| Emirates Poultry Farm (Al Bustan) |
| Green Farms Poultry Industries |
| Tanmiah Food Company |
| Agthia Group |
| Others |
Value Network & Pricing Analysis
Captive feed milling capacity at Al Ain Farms and Tanmiah Food Company anchors price floors across fresh and frozen tiers, compressing margins for processors dependent on spot grain imports while elevating barriers for new entrants lacking upstream integration. Scale economies in blast-freezing infrastructure and MOHAP-certified slaughter facilities concentrate pricing power among incumbents with vertically controlled supply chains.
Pricing Analysis
The customization-premium spread between blockchain-traceable fresh cuts and commodity frozen packs spans three distinct tiers: five-star hotel procurement commands mechanical blade slaughter with recitation certification, mid-tier food service absorbs standard halal-compliant chilled product, and price-sensitive retail channels trade down to frozen whole chicken. Price differentiation hinges on cold-chain documentation rigor and feed origin traceability. Pricing pressure intensifies in frozen commodity segments as Black Sea grain volatility feeds through to import-dependent processors. Retail consumers in Sharjah and Ajman exhibit highest price sensitivity; Dubai hotel procurement teams prioritize certification over cost.
Supply Chain Analysis
Strait of Hormuz transit underwrites feed grain security for UAE producers sourcing corn and soybean meal from Brazil, Argentina, and Black Sea exporters. Raw material dependencies center on imported corn, soybean meal, and veterinary pharmaceuticals for flock health management. Supply chain risk concentrates in single-source vulnerability for halal-certified breeding stock and expatriate veterinary expertise gaps. Distribution runs through temperature-controlled corridors linking Khalifa Industrial Zone processing facilities to Dubai's hotel clusters and hypermarket freezer aisles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent processors must defend against substitution pressure from plant-based protein alternatives and cultured meat ventures targeting UAE's health-positioned consumer segments.
For Market Incumbents: Fortify supplier lock-in through captive hatchery expansion and blockchain-integrated cold-chain investments that MOHAP mandates render non-replicable. Deepen backward integration into feed milling to buffer import price shocks from South American supply disruptions. Secure long-term slotting arrangements with Dubai Mall and Mall of the Emirates hypermarket operators before direct-to-hotel procurement platforms disintermediate traditional retail channels. For New Entrants and Emerging Players: Anchor in Abu Dhabi's underpenetrated five-star resort corridor on Saadiyat Island and Yas Island, where mechanical blade slaughter specifications and traceability requirements have excluded smaller processors. Target organic and pre-cooked value-added segments in Dubai's expatriate-heavy residential districts. Pursue certification-first go-to-market positioning through controlled-atmosphere stunning partnerships with existing facility operators rather than greenfield infrastructure builds. For Investors and Strategic Acquirers: Automated processing specialists with ERP-integrated cold-chain monitoring represent the most defensible acquisition archetype as MOHAP digitization mandates accelerate compliance cost burdens. Long-term viability hinges on feed cost pass-through mechanisms and labor quota policy stability across the analysis window. Monitor Emirates Authority for Standardization and Metrology labeling requirement amendments as inflection indicators for margin compression timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feed Milling | Captive corn and soybean meal supply buffers Black Sea price volatility for Al Ain Farms. |
| Blockchain Cold-Chain Certification | MOHAP traceability mandates force ERP investment that locks in five-star hotel procurement relationships. |
| Controlled-Atmosphere Stunning Deployment | Automated mechanical blade slaughter reduces South Asian labor dependency while preserving halal compliance. |
| Direct-to-Hotel Platform Launch | Bypassing hypermarket slotting arrangements captures margin from Dubai's tourism corridor procurement consolidation. |
| Organic Flock Management Certification | Specified feed regimens command premium positioning in health-conscious Dubai expatriate districts. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with hospitality procurement directors, hypermarket category managers, halal certification auditors, poultry processing plant engineers, and feed grain import specialists. Secondary validation drew from MOHAP facility audit disclosures, Emirates Authority for Standardization and Metrology labeling databases, UAE customs grain import records, and hotel F&B concession contract filings. Bottom-up volume triangulation across processing facility throughput combined with top-down expenditure analysis from tourism sector food service budgets.
Across the projection horizon, the analytical framework modeled segmentation dimensions spanning product format, processing method, distribution channel tier, and end-user certification requirements. CAGRs were derived from trend extrapolation of hospitality procurement volumes and organic segment penetration curves. Forecast inputs incorporated feed grain price scenario modeling and labor quota policy sensitivity testing.
Underlying assumptions cover sustained tourism-driven menu diversification and MOHAP regulatory stability, with deviation risk concentrated in Black Sea supply disruptions and Ministry of Human Resources and Emiratisation work permit framework shifts. Practitioners should keep alternative scenarios live as halal certification digitization timelines and import substitution initiatives evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Alfalfa Hay Market
Agriculture and Agri Products
Africa Rice Market
Agriculture and Agri Products
Brazil Rice Market
Agriculture and Agri Products
North America Hemp Market
Agriculture and Agri Products
North America Compound Feed Market
Agriculture and Agri Products
Clover Leaf Oil Market
Agriculture and Agri Products
Organic Farming Market
Agriculture and Agri Products
United States Floriculture Market
Agriculture and Agri Products
Asia-Pacific Animal Protein Market
Agriculture and Agri Products
Germany Animal Protein Market
Agriculture and Agri Products
Colombia Hemp Market
Agriculture and Agri Products
Fermented Soybean Meal Protein for Animal Feed Market
Agriculture and Agri Products
Primary Feed Materials Market
Agriculture and Agri Products
Kuwait Poultry Meat Market
Agriculture and Agri Products
Ethiopia Agriculture Sector Market
Agriculture and Agri Products
Asia-Pacific Swine Feed Market