
 Bioalcohols Market | 2026-2036
Bioalcohols Market Size, Share, and Industry Trends Forecast 2026-2036
Bioalcohols Market Outlook
Aftermarket service revenue around co-product valorization is narrowing as producers consolidate around captive distillers grains and corn oil recovery. POET LLC leverages its integrated biorefinery network across the US Midwest to capture margin from dried distillers grains with solubles. Archer Daniels Midland Company sustains its position through global origination and multi-feedstock flexibility at scale. Valero Energy Corporation anchors its renewable fuels segment with operational discipline borrowed from conventional refining.
Bioalcohols are oxygenated organic compounds produced through microbial fermentation of biomass feedstocks, with fuel-grade ethanol typically distilled to 99.5% purity and denatured for combustion applications. These molecules serve primarily as gasoline blending components, industrial solvents, and chemical precursors, with energy density and octane enhancement driving their commercial utility. Ethanol dominates volume across fuel applications, while butanol is gaining structural attention for its higher energy content and lower vapor pressure in gasoline blends. The automotive end-user segment concentrates the largest margin pool, whereas pharmaceutical and coatings applications command premium pricing through solvent-grade certification requirements.
The US EPA administers Renewable Fuel Standard volume obligations that mandate minimum biofuel blending, while the European Commission enforces RED III targets that escalate renewable energy share in transport. Brazil's National Petroleum Agency regulates the domestic ethanol blending mandate, currently set at E27, with flex-fuel vehicle penetration reinforcing demand elasticity. Stakeholders must monitor feedstock cost volatility against policy certainty, as corn and sugarcane price swings can compress margins faster than regulatory timelines adjust.
Market Dynamics
Renewable fuel mandates are tightening across major economies, forcing refiners to blend higher bioalcohol volumes while feedstock volatility compresses producer margins faster than regulatory adjustments can offset.
Growth Catalysts
- US EPA Renewable Fuel Standard:Volume obligations mandate minimum biofuel blending thresholds, creating guaranteed offtake for domestic ethanol producers and insulating demand from crude price swings.
- Automotive sector compliance purchasing:Refiners facing renewable fuel obligations are locking in long-term supply contracts with bioalcohol producers to secure blending credits and avoid penalty exposure.
- Brazil flex-fuel vehicle penetration:The National Petroleum Agency's E27 blending mandate combines with a fleet capable of operating on pure ethanol, generating demand elasticity unmatched in other markets.
Market Restraints
- Corn and sugarcane price volatility:Input cost swings can erase producer margins within a single growing season, with feedstock representing 60-70% of production costs for starch and sugar-based ethanol.
- US Midwest production concentration:Distillery capacity clusters in Iowa, Illinois, and Nebraska, exposing supply chains to regional weather shocks and localized logistics bottlenecks.
- Cellulosic ethanol technical limitations:Enzymatic hydrolysis of lignocellulosic feedstocks remains economically uncompetitive at scale despite two decades of pilot investment.
Strategic Opportunities
- EU RED III directive escalation:Renewable energy share targets in transport are tightening through 2030, creating import demand that Brazilian and US producers can capture with certified low-carbon ethanol.
- Butanol-gasoline blending applications:Higher energy density and lower vapor pressure position biobutanol as a premium blending component for specialized fuel formulations and aviation testing.
- Carbon capture integration at biorefineries:Fermentation CO2 streams offer concentrated capture opportunities for producers seeking to monetize emissions reductions through voluntary carbon markets.
Industry Challenges
- Process engineering talent scarcity:Biorefinery operations require hybrid expertise in fermentation microbiology and continuous chemical processing, a skill combination concentrated at a handful of agricultural universities.
- Solvent-grade certification timelines:Pharmaceutical and coatings applications demand multi-year stability testing and traceability documentation that extends customer qualification cycles to 18-24 months.
- Legacy fuel infrastructure compatibility:Existing pipeline networks and storage terminals require material upgrades to handle higher ethanol concentrations, fragmenting distribution economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bioalcohols Market |
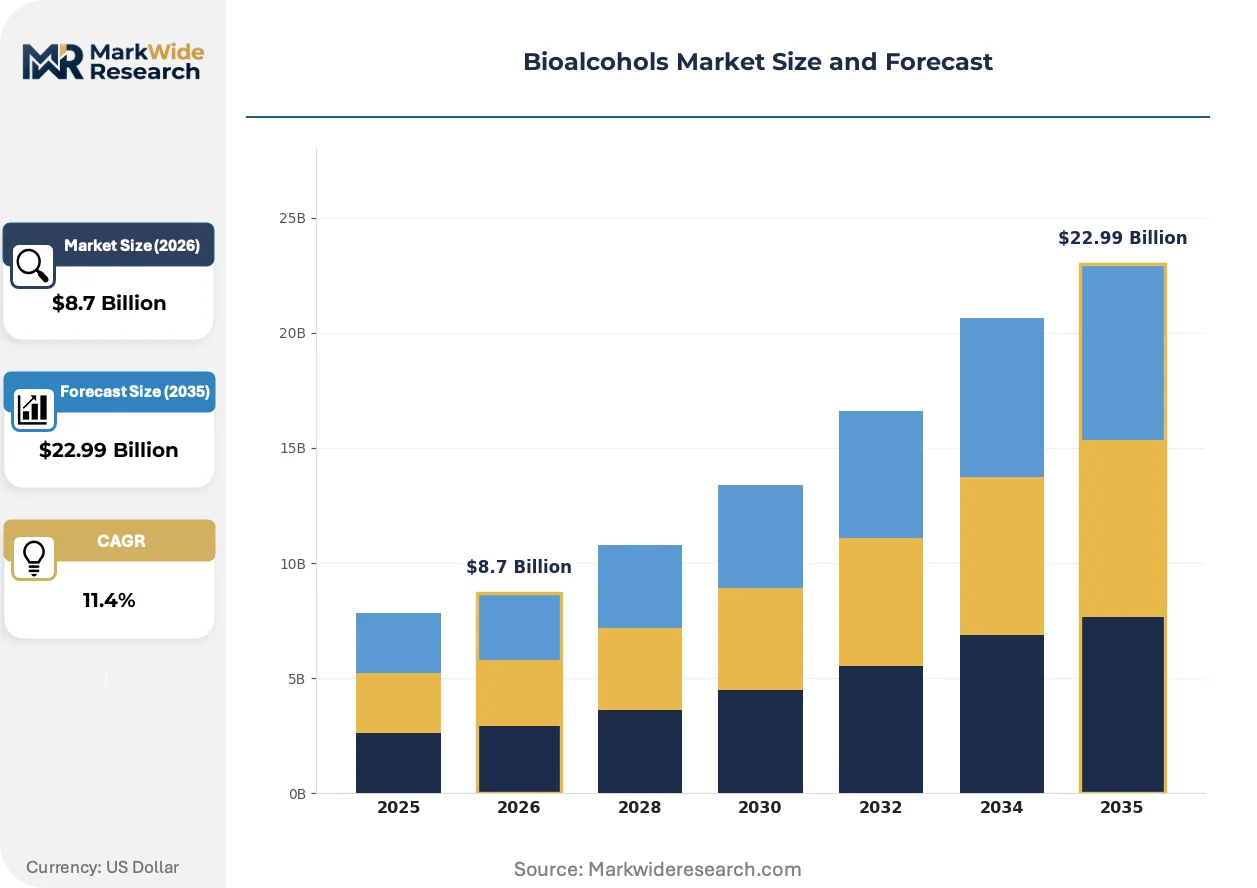
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ethanol, Butanol, Propanol, Methanol Application: Fuel, Solvent, Coatings, Pharmaceutical End User: Automotive, Industrial, Residential, Commercial Distribution Channel: Online, Retail, Direct Sales, Wholesale |
| Companies Covered | POET LLC, Archer Daniels Midland Company, Valero Energy Corporation, Green Plains Inc., CropEnergies, Tereos, Raízen, Flint Hills Resources, The Andersons, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bioalcohols Market Strategic Shifts
Production technology is pivoting toward feedstock flexibility and carbon intensity reduction as policy frameworks reward lifecycle emissions performance over volumetric output alone.
Cellulosic ethanol technology is migrating from demonstration-scale facilities to commercial deployment, with POET-DSM Liberty and Abengoa Hugoton representing the first wave of operational plants processing corn stover and wheat straw. Automotive OEMs and aviation consortia are evaluating these fuels for their 60-90% lifecycle carbon reductions versus gasoline. The structural consequence is a bifurcation between first-generation starch ethanol facing margin pressure and second-generation producers capturing premium pricing through California's Low Carbon Fuel Standard credits.
The European Commission's RED III directive is escalating renewable energy share mandates in transport to 29% by 2030, with sub-targets for advanced biofuels derived from non-food feedstocks. Industrial consequence includes a scramble for waste and residue supply chains, with used cooking oil and animal fats already experiencing price inflation from competing biodiesel and renewable diesel demand. Advanced bioalcohol producers in the EU are responding by securing long-term feedstock contracts with municipal waste processors and agricultural cooperatives.
Refiner procurement patterns are consolidating around vertically integrated biofuel suppliers capable of delivering certified low-carbon intensity scores across multiple regulatory jurisdictions. The spot market for physical ethanol is thinning as compliance buyers prioritize bilateral offtake agreements with producers who control cultivation, processing, and carbon accounting documentation. This concentration is most visible in California, where the Low Carbon Fuel Standard's complex scoring system rewards integrated supply chains with verifiable farming practice data.
Bioalcohols Market Segmentation
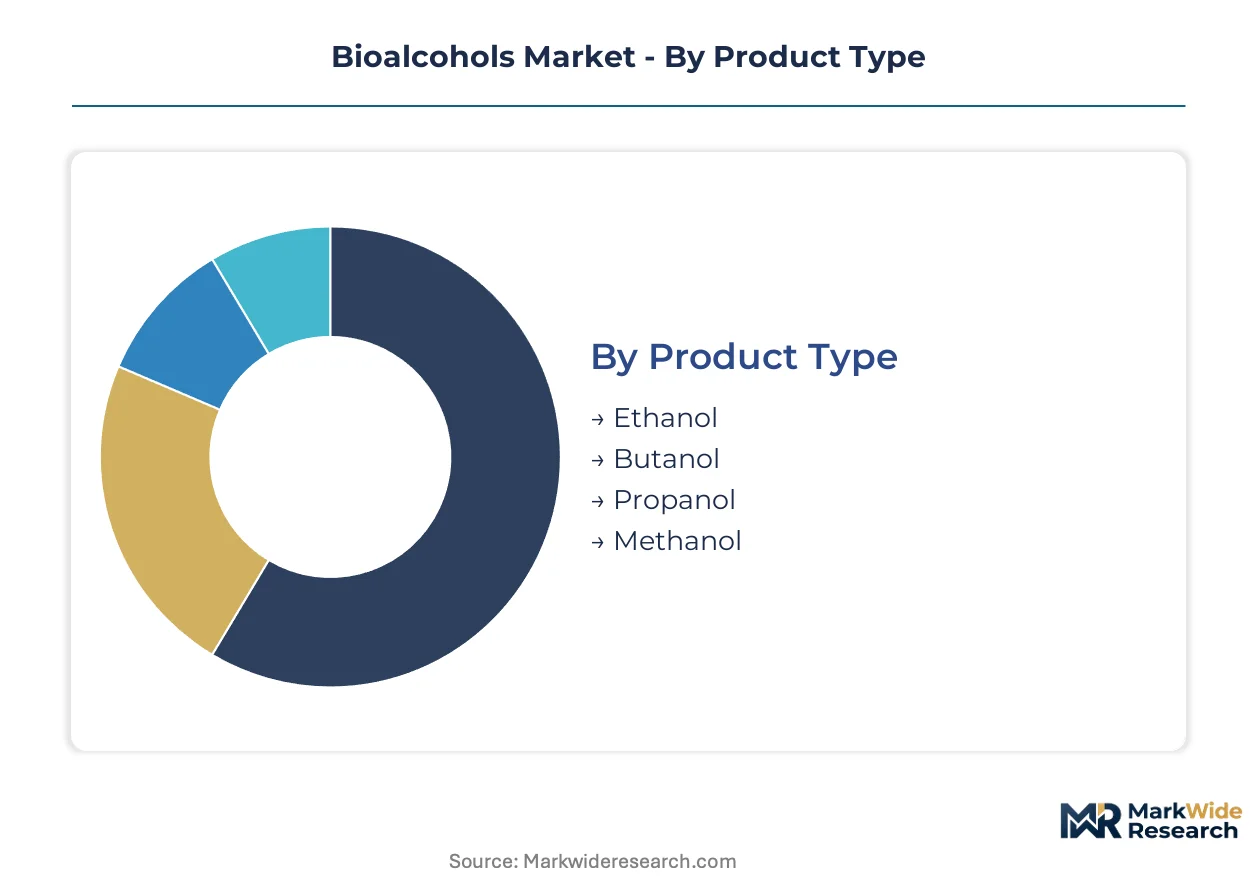
Bioalcohols demand fragments across fuel compliance mandates, industrial solvent specifications, and chemical feedstock requirements. Each segment carries distinct certification barriers, margin profiles, and supply chain configurations that reshape competitive positioning.
Product Type:
Mature fermentation platforms dominate volume, while emerging alcohols capture premium positioning through energy density advantages and specialized blending applications.
- Ethanol:Fuel-grade ethanol distilled to 99.5% purity serves as the primary gasoline oxygenate under US EPA Renewable Fuel Standard mandates. Automotive refiners in Brazil, the United States, and Germany concentrate procurement around this segment as blending obligations tighten.
- Butanol:Biobutanol delivers 25% higher energy density than ethanol with substantially lower vapor pressure, enabling higher-concentration gasoline blends without infrastructure modification. Aviation consortia and specialty fuel formulators are driving qualification testing for this molecule.
- Propanol:Isopropanol variants function as industrial solvents and disinfectant precursors with established pharmaceutical-grade certification pathways.
- Methanol:Biomethanol from syngas fermentation or biomass gasification serves chemical synthesis and emerging marine fuel applications.
Ethanol retains volume leadership; butanol holds the steepest expansion curve.
Application:
Cost tiers separate commodity fuel volumes from certified solvent premiums, with regulatory compliance acting as the primary pricing determinant.
- Fuel:Gasoline blending consumes the majority of bioalcohol volume, driven by renewable fuel mandates in the United States, Brazil, and EU member states. California's Low Carbon Fuel Standard creates additional premium capture for producers with verified farming practice data.
- Solvent:Industrial degreasing and extraction applications require technical-grade certification with less stringent purity thresholds than pharmaceutical segments.
- Coatings:Architectural and automotive paint formulations utilize bioalcohols as volatile organic compound-compliant thinners, with EPA and ECHA regulations pushing substitution of petroleum-derived solvents.
- Pharmaceutical:USP-grade and EP-grade specifications demand multi-year stability testing and batch traceability, extending customer qualification cycles to 18-24 months.
Fuel applications dominate volume throughput; pharmaceutical commands the widest price premium.
End User:
Customer type determines contract structure, with compliance buyers favoring long-term offtake and spot markets thinning for industrial consumers.
- Automotive:Refiners and OEMs purchase through bilateral agreements to secure renewable fuel credits and avoid penalty exposure under EPA and ANP regulations.
- Industrial:Chemical manufacturers and processors source bioalcohols as feedstocks and process solvents, with procurement consolidating around suppliers offering multi-feedstock flexibility.
- Residential:Small-scale heating and cooking applications in Brazil utilize hydrous ethanol through established retail distribution networks.
- Commercial:Institutional cleaning and maintenance operations represent fragmented demand with limited volume concentration.
Automotive concentrates the largest procurement volumes; industrial segments show the most rapid contract restructuring toward integrated suppliers.
Distribution Channel:
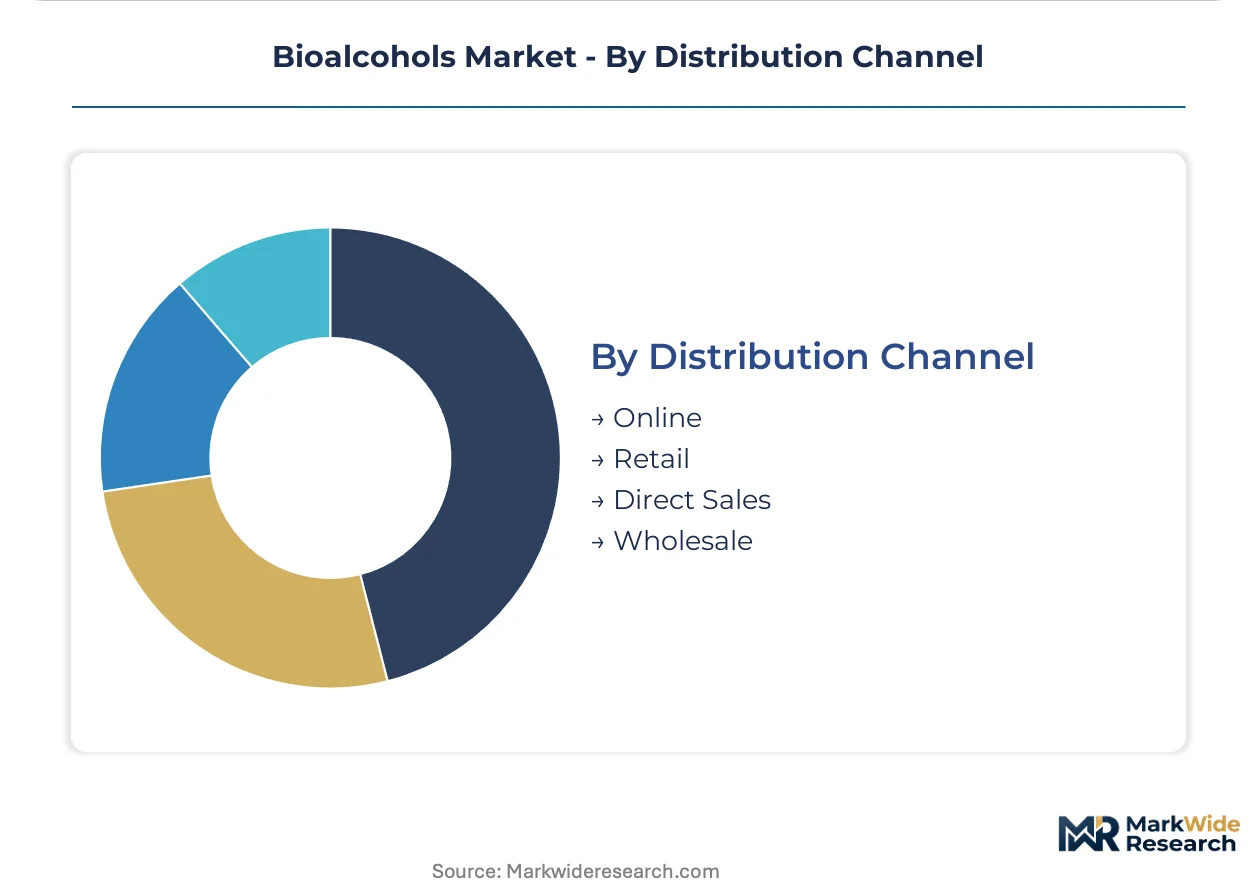
Supply concentration in the US Midwest and Brazilian Center-South shapes logistics economics, favoring direct sales for bulk fuel and wholesale for industrial chemicals.
- Online:Specialty solvent grades and small-volume laboratory chemicals move through digital procurement platforms with certificate of analysis documentation.
- Retail:Hydrous ethanol for flex-fuel vehicles distributes through Brazil's network of fuel stations, with ANP-regulated pricing mechanisms.
- Direct Sales:Refiners and chemical processors negotiate long-term supply agreements with POET, ADM, and Valero for guaranteed renewable fuel credit generation.
- Wholesale:Industrial solvent distributors aggregate demand from coatings and pharmaceutical formulators, managing inventory and certification documentation.
Direct sales capture the fuel-grade majority; wholesale channels are gaining share fastest in specialty solvent segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil exhibits the steepest demand elasticity as flex-fuel vehicle owners switch between hydrous ethanol and gasoline based on price signals, whereas German industrial buyers show inelastic procurement patterns tied to RED III compliance deadlines.
United States
Midwest corn belt concentration drives production economics, with Iowa and Illinois hosting the densest biorefinery clusters. The EPA administers Renewable Fuel Standard volume obligations that mandate minimum blending thresholds, insulating domestic ethanol demand from crude price volatility. POET LLC operates integrated facilities across South Dakota and Nebraska, capturing margin from dried distillers grains with solubles.
Brazil
Center-South sugarcane harvests determine global ethanol pricing benchmarks, with São Paulo state generating over half of national output. The National Petroleum Agency regulates the E27 blending mandate, while flex-fuel vehicle penetration exceeds 80% of new sales. Raízen leverages its Cosan-Shell joint venture structure to coordinate crushing, distillation, and retail distribution.
Germany
Industrial solvent demand from coatings and pharmaceutical formulators concentrates in the Rhine-Ruhr and Bavarian chemical corridors. The European Commission enforces RED III targets that escalate renewable energy share in transport through 2030. CropEnergies operates its Zeitz facility as a multi-feedstock demonstration site for wheat and sugar beet ethanol.
China
Corn stockpile liquidation and cassava import dependence shape production cost structures in the Northeast and Guangxi regions. The National Development and Reform Commission piloted E10 mandates in select provinces before nationwide rollout. State-backed ethanol processors in Jilin and Henan provinces coordinate with Sinopec for blending infrastructure access.
India
Sugarcane surplus diversion and rice straw collection networks determine feedstock availability in Maharashtra and Uttar Pradesh. The central government's Ethanol Blended Petrol program targets 20% blending by 2025, backed by administered pricing for ethanol procurement. Reliance Industries and Indian Oil Corporation are contracting dedicated ethanol supply from distilleries in Bihar and Karnataka.
Bioalcohols Market Competitive Environment
Capability concentration sits with integrated agricultural processors who control origination and fermentation technology; scale advantage sits with energy majors who leverage existing fuel distribution infrastructure. The market structures around three tiers: captive biorefinery operators, independent merchant producers, and petroleum refinery conversions. Dominant competitive moves include backward integration into corn origination and strategic partnerships with automotive OEMs for low-carbon fuel certification.
Among North American integrated processors, POET LLC and Archer Daniels Midland Company exemplify the agricultural-origination archetype, while Valero Energy Corporation anchors the petroleum-refinery conversion tier. These three occupy positions that span the capability-scale spectrum, with the agricultural specialists controlling feedstock cost structures and the energy major leveraging downstream fuel logistics.
| Leading Market Players |
|---|
| POET LLC |
| Archer Daniels Midland Company |
| Valero Energy Corporation |
| Green Plains Inc. |
| CropEnergies |
| Tereos |
| Raízen |
| Flint Hills Resources |
| The Andersons |
| Others |
Value Chain & Pricing Dynamics
The Mississippi River barge corridor anchors bioalcohol logistics economics, with freight differentials between Iowa and Louisiana Gulf terminals directly shaping refinery procurement premiums and producer netbacks across fuel-grade and industrial solvent tiers.
Pricing Analysis
Co-product valorization revenue from dried distillers grains with solubles and corn oil recovery drives lifetime value for integrated biorefinery operators. Three-tier pricing structure across pharmaceutical-grade, technical-grade, and fuel-grade certification levels separates premium solvent markets from commodity fuel blending. Cost compression in fuel-grade ethanol is intensifying because corn price volatility outpaces EPA mandate adjustments. Automotive refiners exhibit the highest price sensitivity due to renewable fuel credit arbitrage, while pharmaceutical formulators show inelastic demand for USP-grade certification.
Supply Chain Analysis
Export-control regimes on advanced fermentation enzymes and cellulosic hydrolysis catalysts limit technology transfer to emerging producers, concentrating proprietary process knowledge among North American and European incumbents. Feedstock supply draws from the United States, Brazil, and India, with corn, sugarcane, and rice straw anchoring regional production economics. Supply chain risk centers on single-source vulnerability for specialty enzyme suppliers controlling cellulosic conversion yields. Distribution runs through captive rail terminals and barge networks for bulk fuel, while industrial solvents move via wholesale chemical distributors managing certification documentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The bioalcohols market functions as a regulatory-moat business where EPA Renewable Fuel Standard entrenchment and EU RED III compliance deadlines create structural switching costs for downstream refiners.
For Market Incumbents: Entrench position through backward integration into corn origination networks across Iowa and Illinois, capturing margin from feedstock cost volatility that threatens merchant producers. Secure long-term offtake agreements with California refiners seeking Low Carbon Fuel Standard credit optimization, while investing in carbon capture retrofit at fermentation facilities to monetize voluntary carbon market premiums.
For New Entrants and Emerging Players: Build out butanol production capacity targeting aviation consortia and specialty fuel formulators, where higher energy density commands premium pricing unavailable to commodity ethanol. Focus initial deployment on EU member states with escalating RED III advanced biofuel sub-targets, leveraging waste and residue feedstock contracts with municipal processors to qualify for preferential regulatory treatment.
For Investors and Strategic Acquirers: Cellulosic ethanol technology holders with demonstrated commercial-scale operations represent the priority acquisition archetype, as policy frameworks increasingly reward lifecycle carbon intensity scores over volumetric output. Monitor California Air Resources Board credit pricing as the inflection indicator for second-generation biofuel margin expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock Origination | Captures margin from corn price volatility that erodes merchant producer economics. |
| Carbon Capture Integration at Biorefineries | Monetizes fermentation CO2 streams through California Low Carbon Fuel Standard credit stacking. |
| Butanol Production Capacity Buildout | Targets aviation consortia seeking higher energy density fuels with lower vapor pressure profiles. |
| Long-term Supply Agreement with Refiners | Locks in renewable fuel credit generation under EPA volume obligation mandates. |
| Advanced Biofuel Certification Investment | Qualifies for EU RED III sub-targets through waste and residue feedstock traceability. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across biorefinery plant managers, downstream refinery procurement leads, agricultural cooperative executives, and EPA regulatory affairs specialists. Secondary validation drew from EIA fuel supply data, EPA Renewable Fuel Standard compliance reports, USDA crop production surveys, and EU RED III implementation guidance. Bottom-up capacity modeling and top-down mandate-driven demand triangulation anchored volume estimates across the analysis window.
Calibration against historical production data and regulatory timeline adjustments shaped the analytical framework across product type, application grade, end-user segment, and regional production hub dimensions. CAGRs were derived from segmented demand modeling and feedstock cost trajectory assumptions. Forecast inputs incorporated EPA volume obligation trajectory, EU renewable energy share escalation, and flex-fuel vehicle fleet penetration curves.
The forecast holds incumbent behavior within observed patterns; aggressive moves by state-backed processors in China and India would shift outcomes through subsidized capacity additions. Material shifts in corn and sugarcane price volatility or accelerated cellulosic technology cost reductions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Digital Shaker Market
Alcoholic Beverages
Alcoholic Beverages Market
Alcoholic Beverages
Pre-Mixed/RTD Alcoholic Drinks Market
Alcoholic Beverages
Tequila Market
Alcoholic Beverages
France Alcohol E-Commerce Market
Alcoholic Beverages
Whiskey Market
Alcoholic Beverages
Craft Wine Market
Alcoholic Beverages
Organic Beer Market
Alcoholic Beverages
Europe Wine Market
Alcoholic Beverages
Premix Bottled Cocktails Market
Alcoholic Beverages
Global Brewery Filtration Market
Alcoholic Beverages
Malt Whiskey Market
Alcoholic Beverages
Sparkling Wine Market
Alcoholic Beverages
Distilled Spirits Market
Alcoholic Beverages
Malaysia Alcohol E-Commerce Market
Alcoholic Beverages
Ethanol Market