
 Sour Flavor Ingredient Market | 2026-2036
Sour Flavor Ingredient Market Size, Share, and Industry Trends Forecast 2026-2036
Sour Flavor Ingredient Market Analytics
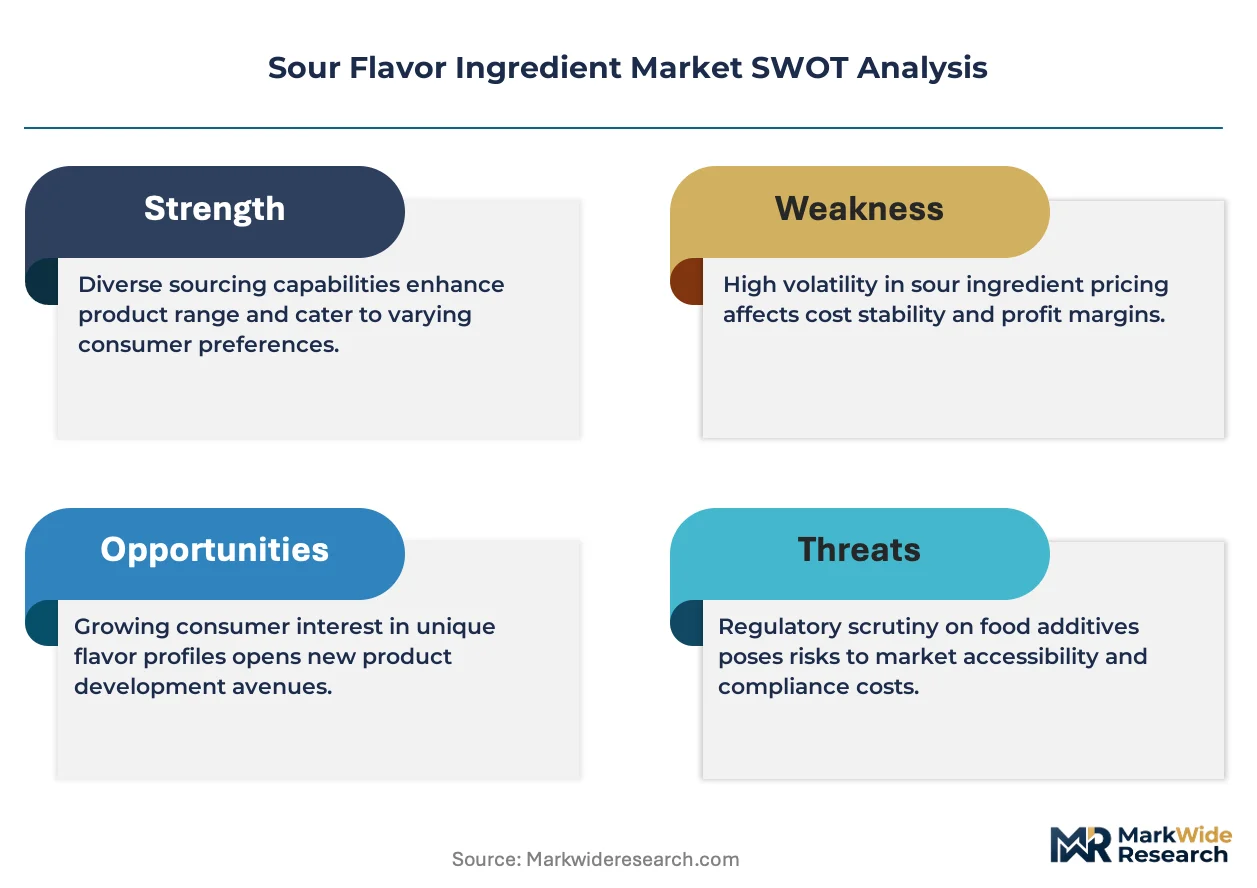
The EU Green Deal is recalibrating sour ingredient procurement across European food manufacturing, pushing formulators toward bio-based acidulants with verified carbon footprints. Kerry leverages its fermentation technology platform to supply citric and malic acid variants aligned with renewable sourcing protocols. McCormick anchors North American supply through its integrated flavor house network, while Oterra specializes in natural color-acid combinations for clean-label applications.
Sour flavor ingredients comprise organic acids—principally citric, malic, tartaric, and lactic—typically produced via microbial fermentation or chemical synthesis, functioning as pH regulators, taste modulators, and preservation enhancers across food and beverage matrices. Citric acid dominates volume flows due to its versatility in beverages and confectionery, though malic acid captures expanding share in sports drinks and sugar-reduced formulations where its smoother tartness profile enables sodium and sugar reduction. The liquid form leads in industrial-scale beverage processing, while powder formats gain traction in bakery and dry-mix applications where storage stability and precise dosing control matter.
FDA GRAS determinations and EPA environmental release standards govern acidulant manufacturing in the United States, while REACH registration requirements and EFSA purity specifications shape European market access and formulation choices. These frameworks elevate compliance costs for synthetic acid producers while creating preferential pathways for fermentation-derived and naturally sourced alternatives. Stakeholders must monitor evolving bio-based certification schemes and carbon border adjustments that will increasingly determine supplier eligibility and contract terms.
Market Dynamics
The EU Green Deal's bio-based chemical mandates are redirecting capital toward fermentation-derived acidulant platforms, compressing synthetic acid margins while elevating renewable feedstock sourcing as a procurement gatekeeper.
Growth Catalysts
- Clean-label beverage reformulation:Craft soda and functional drink portfolios are accelerating natural acidulant adoption as pH regulators replace synthetic alternatives in consumer-facing formulations.
- Fermentation technology maturation:Microbial production platforms now yield citric and malic acid variants with verified carbon footprints, satisfying EFSA purity specifications for European market access.
- German ingredient house clustering:Cologne and Hamburg harbor concentrated technical service capabilities that reduce reformulation cycle times for Central European food manufacturers.
Market Restraints
- Feedstock price volatility:Corn and molasses costs swing with agricultural commodity cycles, squeezing fermentation-derived acid margins when synthetic petrochemical routes hold steady.
- REACH registration burdens:ECHA compliance costs for novel acidulant variants create asymmetric barriers favoring incumbent suppliers with amortized regulatory dossiers.
- Technical performance gaps:Natural acidulants occasionally fail to match synthetic variants in heat stability during high-temperature bakery processing, limiting substitution depth.
Strategic Opportunities
- Carbon border adjustment positioning:EU CBAM implementation rewards suppliers with auditable bio-based supply chains, creating first-mover advantage for fermentation platforms with mass-balance certification.
- Sports drink malic acid expansion:Smoother tartness profiles enable sodium and sugar reduction in performance beverages, opening formulation partnerships with functional drink developers.
- India FSSAI clean-label pathway:India's food safety regulator is tightening additive approval standards, creating entry windows for natural acidulants with established GRAS histories.
Industry Challenges
- Fermentation scale-up talent scarcity:Industrial microbiology and bioprocess engineering expertise concentrates at legacy citric acid producers, constraining new entrant technical staffing.
- Legacy equipment retrofit costs:Powder handling systems designed for synthetic acids require corrosion-resistant modifications to accommodate hygroscopic natural variants.
- Dual certification timelines:Simultaneous FDA GRAS self-affirmation and EFSA novel food consultations extend product launch cycles by months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sour Flavor Ingredient Market |
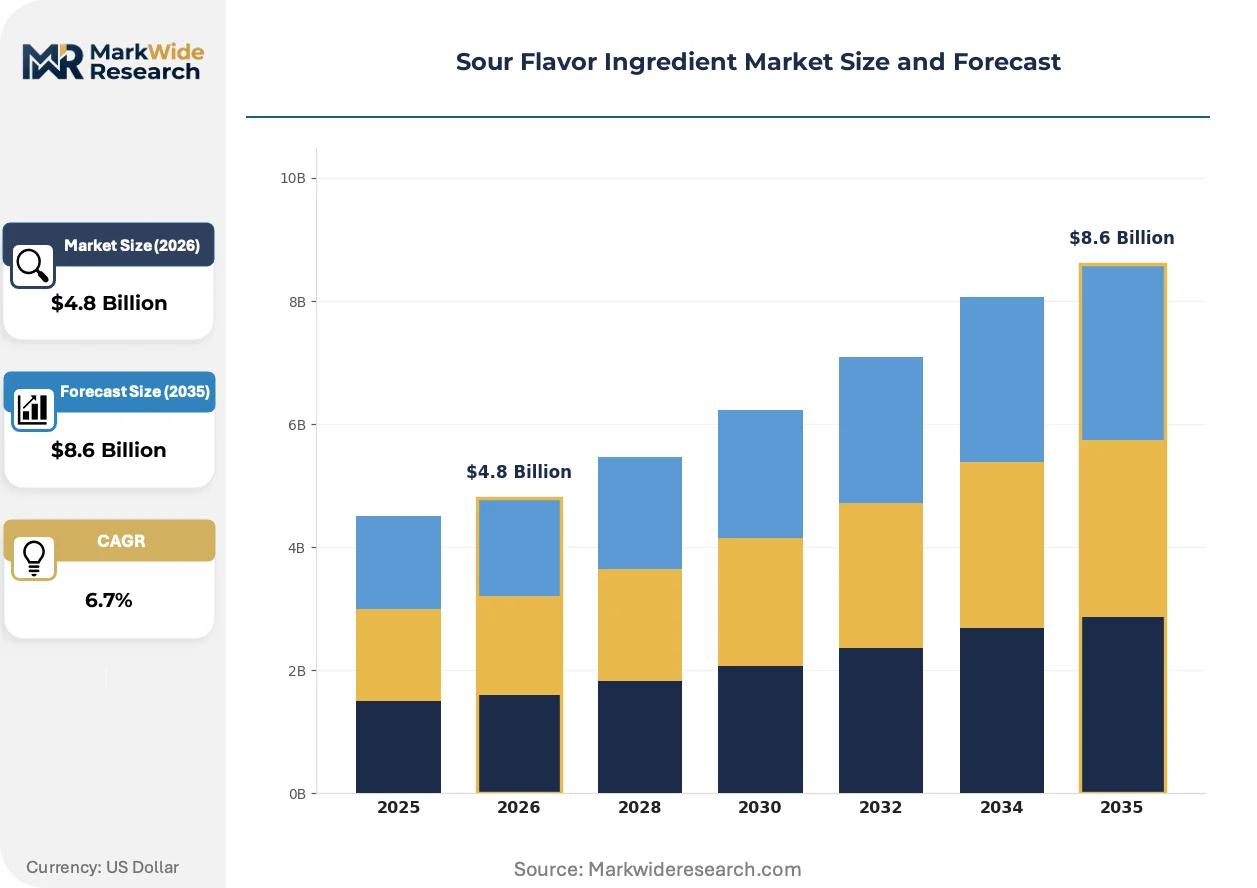
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Citric Acid, Malic Acid, Tartaric Acid, Lactic Acid Application: Beverages, Confectionery, Bakery, Dairy Form: Liquid, Powder, Crystal, Paste End User: Food Industry, Beverage Industry, Pharmaceutical, Cosmetics |
| Companies Covered | Seprify, Bickford Flavors, Kerry, Imbibe, McCormick, Roland Foods, Nestlé, Truff, Oterra, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sour Flavor Ingredient Market Evolving Landscape
Acidulant production is bifurcating between petrochemical synthesis and bio-based fermentation, with digital process control and carbon accounting now embedded in supplier qualification protocols.
Precision fermentation is integrating strain engineering with real-time metabolite monitoring to optimize citric acid titers and reduce batch-to-batch variability. Beverage manufacturers with high-volume, continuous processing lines are adopting these supply streams fastest. The technology is integrating carbon footprint data directly into procurement dashboards, compressing synthetic acid price premiums.
REACH registration requirements are tightening purity specifications for acidulant imports into the European Economic Area. ECHA's updated dossier evaluation criteria now demand extensive ecotoxicity data, elevating compliance costs for smaller synthetic producers. Food manufacturers in Germany and France are responding by consolidating supplier bases around fermentation houses with established registration histories.
Direct supplier relationships are displacing traditional distributor intermediaries in North American acidulant procurement. Large beverage conglomerates now negotiate volume contracts directly with fermentation platforms, bypassing regional chemical distributors. This pattern is most visible in the United States, where IRA bio-based manufacturing incentives accelerate domestic production investments.
Sour Flavor Ingredient Market Segmentation
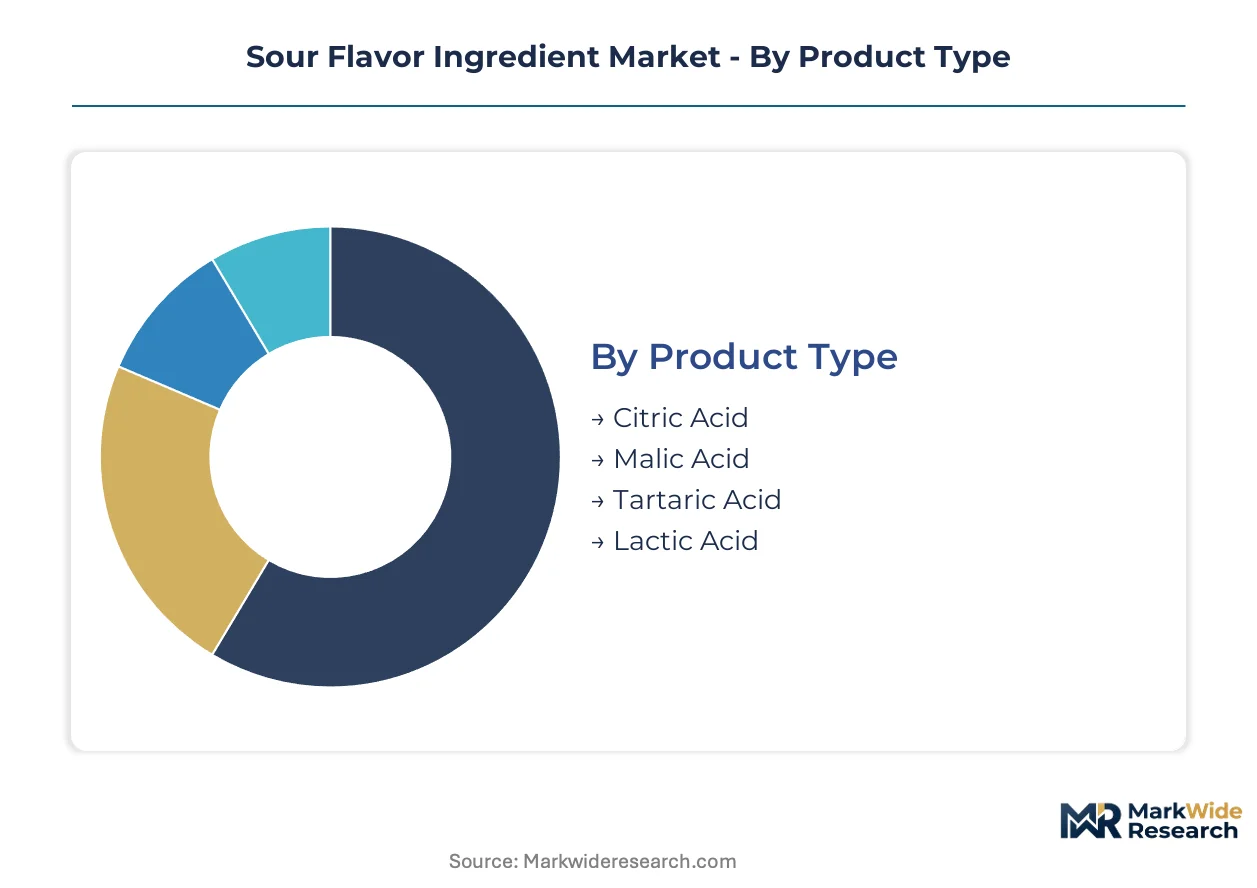
Acidulant procurement strategies diverge sharply across product chemistries and application matrices. Formulators select segments based on heat stability requirements, pH modulation precision, and clean-label compatibility thresholds.
Product Type:
Fermentation infrastructure demands separate capital allocation across each acidulant platform, with citric acid requiring the largest bioreactor footprints and downstream crystallization capacity.
- Citric Acid:Microbial fermentation of Aspergillus niger yields this tricarboxylic acid with broad pH buffering range. Beverage manufacturers in Germany and France concentrate procurement here for sports drink and functional water portfolios, driven by EFSA-compliant purity specifications and established GRAS documentation.
- Malic Acid:This dicarboxylic acid delivers smoother tartness intensity than citric variants, enabling sodium reduction in performance beverages. Sugar-reduced formulation pipelines in the United States are expanding malic acid offtake as Cargill and Tate & Lyle advance fermentation-derived supply.
- Tartaric Acid:Wine industry byproduct extraction dominates European supply, with synthetic petrochemical routes holding residual share for industrial applications.
- Lactic Acid:Bacterial fermentation of carbohydrate feedstocks produces this alpha-hydroxy acid, with dairy acidification and pharmaceutical buffering as primary outlets.
Most installed capacity flows through citric acid. Expansion is steepest in malic acid.
Application:
Processing temperature tolerances and pH stability windows dictate segment selection, with thermal degradation risks highest in bakery and lowest in beverage mixing.
- Beverages:Cold-fill and hot-fill protocols demand rapid acidulant solubility and flavor stability across shelf-life testing. Carbonated soft drink and functional water portfolios in the United States and Germany anchor volume, with clean-label reformulation accelerating natural acidulant substitution.
- Confectionery:Hard candy and gummy matrices require acidulants that survive high-temperature cooking without caramelization or off-flavor development. Sour candy product pipelines in Japan and South Korea concentrate demand here.
- Bakery:Heat stability limitations constrain natural acidulant penetration in oven-exposed applications, with encapsulated variants emerging to protect acid functionality through baking cycles.
- Dairy:Fermented milk and cheese production utilize lactic acid for pH control and texture development, with European dairy cooperatives maintaining captive fermentation capacity.
Beverage applications command the largest volume commitments. Confectionery is climbing the fastest as sour flavor intensity becomes a product differentiation axis.
Form:
Material handling infrastructure and dosing precision requirements separate liquid and solid formats, with powder systems demanding greater capital expenditure for humidity control and dust containment.
- Liquid:Pumpable acidulant solutions integrate directly into continuous beverage processing lines, eliminating dissolution steps and enabling precise flow-controlled dosing. High-volume bottling operations in the United States and Mexico standardize on liquid citric acid for operational efficiency.
- Powder:Free-flowing granules support dry-mix applications where storage stability and weight-based formulation accuracy matter. Bakery premix and confectionery powder blenders in Germany and the Netherlands prefer this format for extended shelf-life requirements.
- Crystal:Purified acid crystals serve pharmaceutical and specialty food applications demanding highest purity grades with minimal moisture content.
- Paste:Viscous acidulant preparations address niche applications in processed fruit and sauce matrices where controlled acid release modifies texture development.
Liquid formats absorb the majority of production volume. Powder is expanding most quickly as clean-label dry-mix portfolios proliferate.
End User:
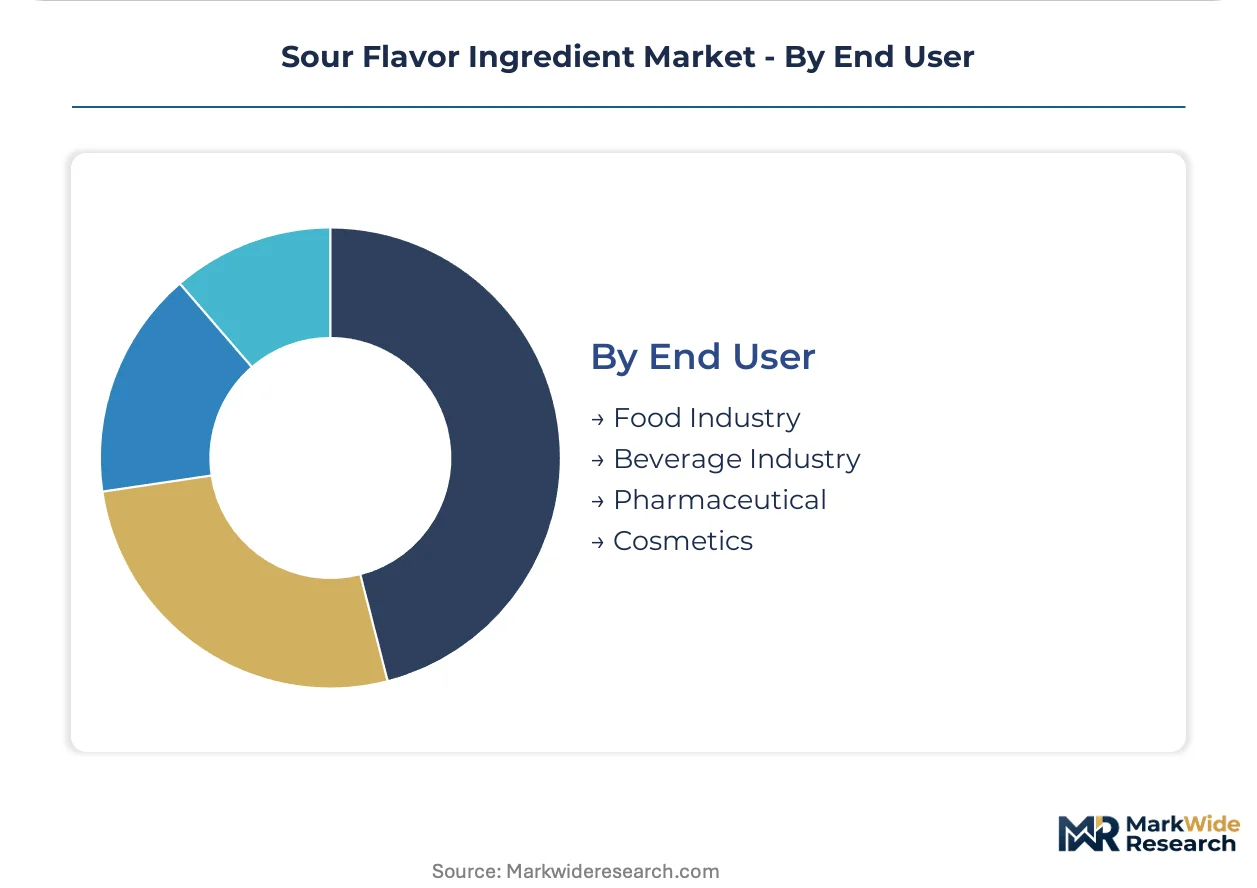
Regulatory compliance burden and technical service intensity vary across end-user categories, with pharmaceutical and cosmetic segments demanding the most extensive documentation and purity certification.
- Food Industry:Processed meat, sauces, and prepared meals utilize acidulants for preservation and flavor modulation. German and French food manufacturers consolidate procurement around fermentation houses with established REACH registration histories.
- Beverage Industry:This category separates from general food processing due to distinct formulation protocols, continuous processing infrastructure, and direct supplier relationship patterns. Major bottlers in the United States negotiate volume contracts directly with acidulant platforms, bypassing distributor intermediaries.
- Pharmaceutical:USP-grade acidulants serve as excipients in tablet formulations and pH buffers in injectable solutions, with FDA compliance documentation requirements elevating supplier qualification barriers.
- Cosmetics:Alpha-hydroxy acid applications in skin care formulations utilize lactic and citric acids for exfoliation and pH adjustment, with EU Cosmetics Regulation compliance shaping European sourcing.
Beverage industry offtake dominates installed capacity utilization. Pharmaceutical is gaining share fastest as excipient reshoring initiatives accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fermentation microbiologists and bioprocess engineers cluster around legacy citric acid production centers, anchoring regional capability in Germany, the United States, China, and India. Talent density shapes where acidulant platforms scale fastest.
Germany
Cologne and Hamburg harbor Europe's densest concentration of ingredient houses serving Central European reformulation needs. EU Green Deal bio-based mandates redirect procurement toward fermentation-derived acidulants with verified carbon footprints. ECHA REACH registration requirements favor incumbent suppliers with amortized regulatory dossiers in these port cities.
United States
IRA bio-based manufacturing incentives accelerate domestic fermentation platform investments for beverage industry offtake. FDA GRAS self-affirmation pathways enable faster product launch cycles than European novel food consultations. Direct supplier relationships displace traditional distributor intermediaries in high-volume bottling corridors.
China
Dual carbon goals reshape acidulant production toward renewable feedstock integration in coastal chemical provinces. SAMR food additive standards tighten alongside GB purity specifications for export-oriented fermentation capacity. Strain engineering capabilities concentrate in state-backed biotechnology clusters.
India
FSSAI clean-label pathway tightening creates entry windows for natural acidulants with established GRAS histories in processed food manufacturing. PLI scheme incentives attract fermentation infrastructure investment for acidulant export platforms. Maharashtra and Gujarat industrial corridors anchor technical service capabilities.
France
Wine industry byproduct extraction sustains tartaric acid supply chains in Bordeaux and Champagne regions. ANSM cosmetic regulation compliance shapes lactic acid sourcing for alpha-hydroxy acid applications. CSRD reporting requirements elevate bio-based certification demands across French food manufacturing.
Sour Flavor Ingredient Market Competitive Landscape
Capital-heavy fermentation platforms compete with asset-light flavor houses for reformulation partnerships. The market structures around three tiers: integrated biotechnology conglomerates with captive fermentation capacity, specialized ingredient houses with technical service depth, and regional distributors with logistics reach. Kerry and McCormick anchor distinct archetypes—biotechnology integration versus flavor house networks—while Oterra occupies a specialist position in natural color-acid combinations. Competitive moves concentrate on fermentation scale-up partnerships and carbon accounting certification to satisfy EU CBAM positioning.
Among biotechnology-integrated suppliers, Kerry exemplifies the fermentation platform archetype with microbial production capabilities spanning citric and malic acid variants. McCormick represents the integrated flavor house model, leveraging North American distribution density for beverage industry volume contracts. Oterra occupies a specialist position at the intersection of natural color and acidulant formulation for clean-label applications. These three anchors illustrate how supplier qualification now embeds carbon footprint data directly into procurement dashboards.
| Leading Market Players |
|---|
| Seprify |
| Bickford Flavors |
| Kerry |
| Imbibe |
| McCormick |
| Roland Foods |
| Nestlé |
| Truff |
| Oterra |
| Others |
Value Network & Pricing Analysis
Corn futures and molasses spot prices on the Chicago Board of Trade cascade directly into fermentation-derived acidulant cost structures, compressing margins for natural variants when synthetic petrochemical routes hold pricing steady. Buyers in Germany and the United States sort into distinct procurement tiers based on carbon certification requirements and volume scale.
Pricing Analysis
Technical service bundling separates premium-tier supplier relationships from commodity spot transactions in this market. Three-tier pricing structure across premium, standard, and economy levels differentiates based on EFSA purity certification and mass-balance carbon accounting. Cost compression in standard-tier fermentation acids is intensifying because REACH registration amortization favors incumbent suppliers with established dossiers. Beverage conglomerates with direct supplier contracts exhibit lowest price sensitivity, while regional bakery premix blenders face acute margin pressure from feedstock volatility.
Supply Chain Analysis
Regional distribution centers in Cologne, Hamburg, and Rotterdam anchor European acidulant logistics through hub-and-spoke patterns serving Central European formulators. Production gravity centers on Germany, the United States, and China, with strain engineering capabilities tethered to legacy fermentation clusters in each geography. Molasses, corn starch, and petrochemical feedstocks constitute the primary input dependencies. Single-source vulnerability concentrates in Aspergillus niger strain banks held by established biotechnology platforms. Distribution runs through direct supplier relationships displacing traditional chemical distributor intermediaries in North American beverage corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The sour flavor ingredient market functions as a stable compounder, with clean-label beverage reformulation driving steady volume expansion across fermentation-derived acidulant platforms.
For Market Incumbents: Lock in carbon border adjustment positioning through mass-balance certification investments before EU CBAM full implementation. Consolidate technical service capabilities around Cologne and Hamburg clusters to compress reformulation cycle times for Central European food manufacturers. Capacity addition in Maharashtra and Gujarat industrial corridors captures PLI scheme incentives while serving FSSAI clean-label pathway demand. For New Entrants and Emerging Players: Enter via malic acid specialization for sports drink sodium-reduction formulations, where smoother tartness profiles command formulation partnership premiums. India's processed food manufacturing presents the most penetrable geography, with FSSAI tightening creating entry windows for natural acidulants with established GRAS histories. Direct technical service relationships with functional drink developers offer the clearest go-to-market angle. For Investors and Strategic Acquirers: Asymmetric upside sits with fermentation platforms possessing integrated strain engineering and real-time metabolite monitoring capabilities. Long-term viability over the 5-10 year horizon rests on bio-based certification depth rather than synthetic route cost advantages. Watch for EU CBAM implementation timelines as the critical inflection signal determining supplier eligibility and contract terms.| Strategic Initiative | Industry Significance |
|---|---|
| Fermentation Capacity Expansion | Builds bio-based acidulant supply to meet EU Green Deal procurement mandates. |
| Backward Integration into Feedstock Supply | Captures corn and molasses cost stability for fermentation platform margins. |
| Carbon Certification Investment | Secures mass-balance documentation for EU CBAM supplier eligibility. |
| Direct Supplier Relationship Development | Bypasses distributor intermediaries for volume contracts with beverage conglomerates. |
| Malic Acid Specialization Partnership | Enables sodium-reduction formulation collaborations with sports drink developers. |
Research Methodology
Bottom-up beverage industry offtake modeling reconciled against top-down fermentation capacity tracking forms the analytical core of this study. Primary interviews with acidulant procurement managers at German and French food manufacturers, technical directors at fermentation platforms, and formulation scientists at functional drink developers combined with secondary validation. Secondary sources include ECHA REACH registration databases, FDA GRAS notification filings, EU customs trade data, and SEC 10-K disclosures from integrated biotechnology conglomerates. Triangulation between demand-side volume commitments and supply-side production capacity yields market size estimates.
Historical trendline analysis of citric and malic acid production volumes informs growth trajectory assumptions across the projection horizon. Segmentation modeling spans acidulant chemistry, application matrix, physical form, and end-user category, with additional dimensioning by carbon certification tier. CAGRs derive from fitted trend analysis adjusted for regulatory inflection points. Forecast inputs incorporate EU CBAM implementation schedules, FSSAI additive approval timelines, and IRA bio-based manufacturing incentive uptake rates.
Inputs from ECHA registration databases and FDA GRAS filings were available through the study window; gaps in real-time fermentation capacity utilization data introduce uncertainty bands around near-term supply estimates. Forecasts reflect documented assumptions regarding regulatory implementation timing and feedstock price stabilization. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
Global Acerola Extracts Market
Flavorings and Food Additives
Beverage Flavoring Agent Market
Flavorings and Food Additives
Food Texturizers Market
Flavorings and Food Additives
Global Flavors Market
Flavorings and Food Additives
Tangerine Essential Oil Market
Flavorings and Food Additives
China Food Flavor and Enhancer Market
Flavorings and Food Additives
Food Flavors & Flavor Enhancers Market
Flavorings and Food Additives
Dairy Flavors Market
Flavorings and Food Additives
Dry Powder Flavors Market
Flavorings and Food Additives
Modified Lecithin Market
Flavorings and Food Additives
D-Limonene Market
Flavorings and Food Additives
US Essential Oil Market
Flavorings and Food Additives
FTNF Flavors Market
Flavorings and Food Additives
Jujube Extracts Market
Flavorings and Food Additives
Asia-Pacific Vanilla Beans and Extract Market
Flavorings and Food Additives
China Food Colorants Market