
 South America Craft Beer Market | 2026-2036
South America Craft Beer Market Size, Share, and Industry Trends Forecast 2026-2036
South America Craft Beer Market Analytics
Brazil is fragmenting as craft breweries multiply across Minas Gerais, São Paulo, and Rio de Janeiro states. Patagonia Brewery anchors its position through vertical integration into barley sourcing and malting operations. Cervejaria Colorado differentiates via experimental hop varieties and localized Brazilian flavor profiles. Cerveceria Kunstmann sustains market presence through German-heritage brewing traditions in southern Chile.
Craft beer denotes small-batch, independently produced fermented beverages brewed with malted grains, hops, yeast, and water at volumes typically below six million barrels annually, emphasizing flavor complexity over mass-market consistency. Its primary commercial purpose serves discerning consumers seeking terroir-specific taste experiences and brewery transparency. Ales occupy the dominant volume position across South American craft portfolios, while IPAs capture the fastest-growing demand among urban millennials and Gen Z drinkers. Distribution through on-trade channels generates premium margin pools, though e-commerce penetration accelerates as specialty retailers build direct-to-consumer logistics.
Brazil's ANVISA mandates nutritional labeling and alcohol content disclosure, elevating compliance costs for microbreweries while rewarding transparent brands with consumer trust. Argentina's national food safety authority enforces brewing facility sanitation standards that limit informal producer market access. Stakeholders must monitor evolving excise tax structures across Andean and Mercosur jurisdictions to anticipate margin compression or competitive advantage shifts.
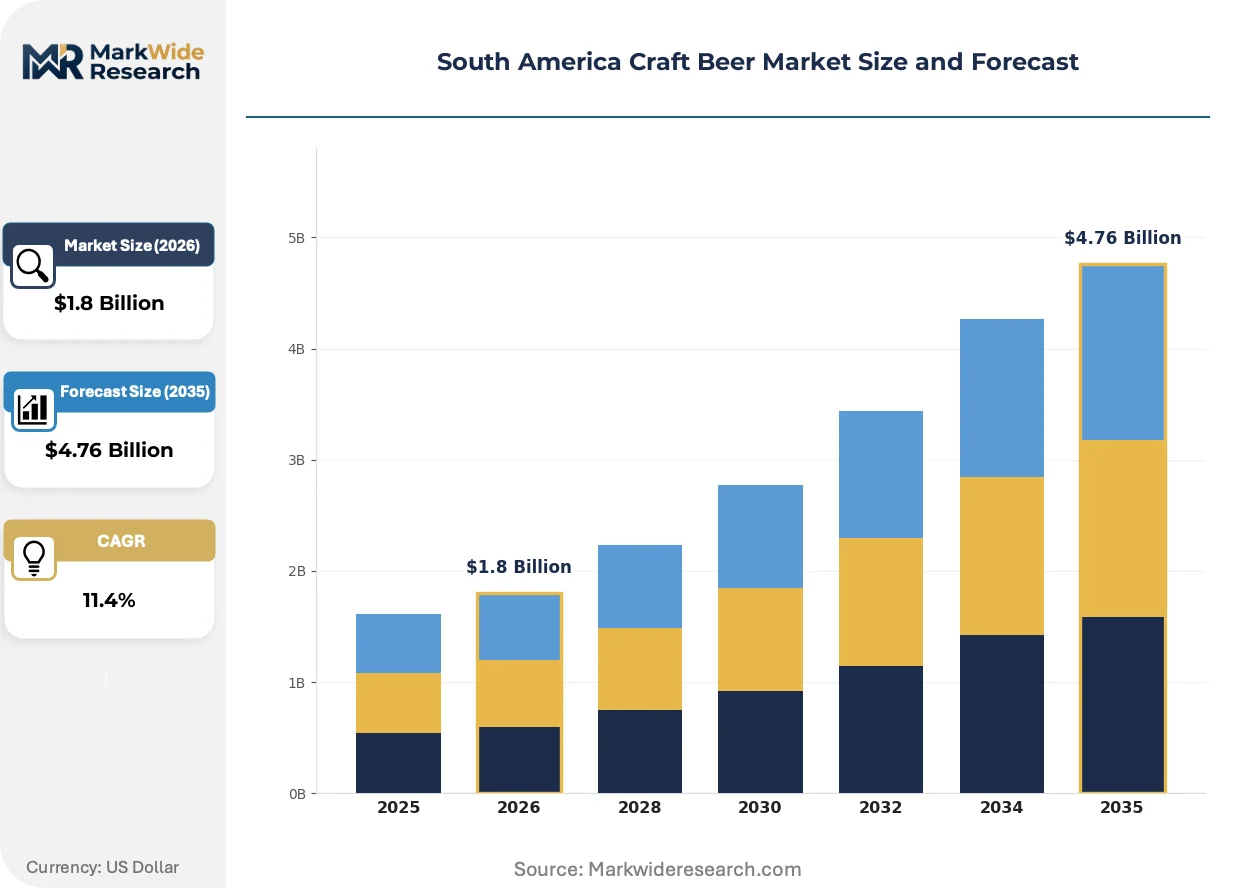
Market Dynamics
Brazil's ANVISA nutritional labeling mandates and excise tax volatility are compressing microbrewery margins while rewarding scaled operators with compliance infrastructure. This regulatory pressure is redrawing competitive boundaries across the Southern Cone.
Growth Catalysts
- ANVISA Transparency Mandates:Brazil's alcohol content disclosure requirements build consumer trust in craft brands that invest in laboratory certification, creating loyalty premiums for compliant producers.
- Barley Malting Localization:Patagonian and Chilean breweries are backward integrating into captive barley cultivation, insulating supply chains from Argentine grain export volatility.
- Urban On-Trade Density:São Paulo's premium venue concentration generates discovery-driven trial among millennials, converting experimental drinkers into repeat purchasers of small-batch ales.
Market Restraints
- Hop Import Dependency:South American craft brewers source 90% of aroma hops from US Pacific Northwest and German Hallertau growers, exposing margins to dollar-euro exchange rate swings and freight cost spikes.
- Mercosur Excise Fragmentation:Divergent alcohol taxation across Brazil, Argentina, Uruguay and Paraguay prevents unified pricing strategies and complicates cross-border distribution economics.
- Glass Bottle Supply Concentration:Brazil's southeastern glass manufacturers dominate packaging supply, limiting negotiating leverage for microbreweries outside São Paulo and Minas Gerais industrial corridors.
Strategic Opportunities
- E-Commerce Direct Channels:Specialty retailers in Buenos Aires and Santiago are building temperature-controlled last-mile logistics, enabling subscription models that bypass traditional three-tier distribution markups.
- Indigenous Ingredient Profiles:Brazilian breweries are experimenting with native fruits and Amazonian botanicals, creating terroir-differentiated products that command export premiums in European craft markets.
- Argentine Barley Export Liberalization:Pending policy shifts at Argentina's agriculture ministry could unlock cheaper malt supply for Chilean and Uruguayan brewers currently dependent on imported grain.
Industry Challenges
- Certified Brewmaster Scarcity:Brazil's technical institutes produce fewer than 200 formally trained craft brewers annually, forcing independent producers to poach talent from industrial lager competitors at wage premiums.
- Refrigerated Distribution Gaps:Cold-chain infrastructure deficiencies in Brazil's northeastern states and Colombian Andean corridors limit shelf-life guarantees for unpasteurized craft products.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Craft Beer Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ales, Lagers, Stouts, IPAs Distribution Channel: On-trade, Off-trade, E-commerce, Specialty Stores Consumer Type: Millennials, Gen Z, Craft Enthusiasts, Casual Drinkers Flavor Profile: Hoppy, Fruity, Dark, Spicy |
| Companies Covered | Bogota Beer Company, Patagonia Brewery, Cerveceria Altamira, Cerveceria Antares, Cervejaria Colorado, Baden Baden, Cervejaria Bodebrown, Cerveceria Kunstmann, Cerveceria Sierra Andina, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Craft Beer Market Evolving Landscape
Digital brewing control systems and indigenous ingredient experimentation are compressing production timelines while fragmenting flavor portfolios across the Southern Cone.
Automated brewhouse management platforms are collapsing the skill barrier for consistent small-batch replication. Mid-sized São Paulo breweries deploy cloud-connected fermentation monitors that adjust temperature and yeast nutrition in real time. This technology is collapsing the quality variance that previously separated craft from industrial production, enabling newer entrants to match established players on batch consistency.
ANVISA's phased implementation of nutritional labeling for alcoholic beverages is forcing reformulation investments across Brazilian craft portfolios. The regulation requires calorie and carbohydrate disclosure by 2026, compelling breweries to adjust recipes or absorb label redesign costs. Minas Gerais producers with existing laboratory partnerships are responding fastest, while smaller Rio de Janeiro operations face compliance timeline compression.
Subscription-based discovery boxes are displacing traditional retail trial for urban millennial drinkers. São Paulo and Buenos Aires consumers now receive curated monthly selections of limited releases, bypassing supermarket shelf competition. This channel shift is most visible in Brazil's southeastern states, where direct-to-consumer revenue now exceeds on-trade growth rates for established craft brands.
South America Craft Beer Market Segmentation
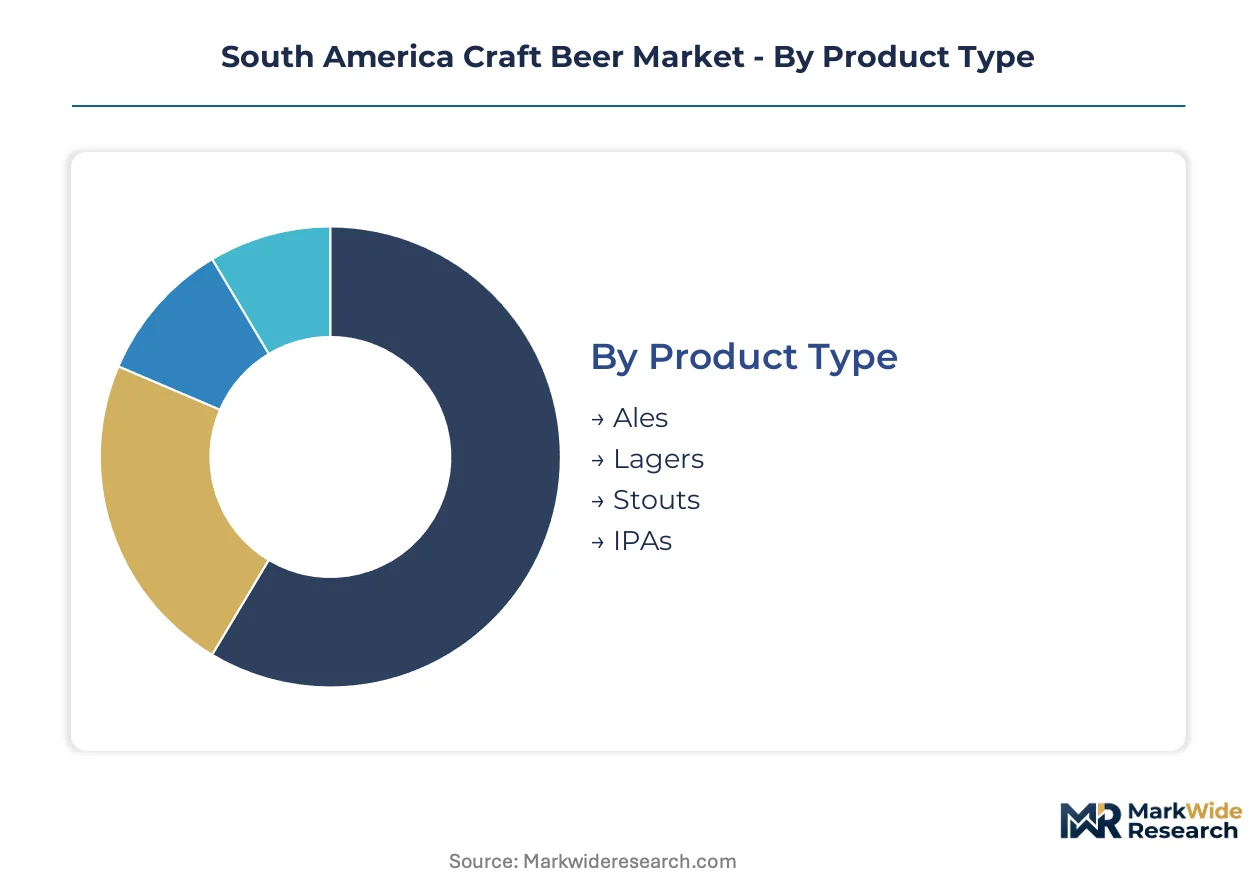
Craft beer segmentation in South America reveals how consumer preference fragmentation and channel evolution create distinct revenue pools. Understanding these divisions enables producers to allocate brewing capacity and marketing spend against the highest-margin opportunities.
Product Type:
The use-case spectrum spans sessionable everyday consumption through experimental limited releases, with each style commanding different production economics and brand positioning.
- Ales:Top-fermented at warmer temperatures yielding fruity ester profiles and softer mouthfeel. Brazilian producers in Minas Gerais and São Paulo states concentrate ale portfolios around accessibility and lower price points, though margin pressure from ANVISA compliance costs is compressing smaller operators.
- IPAs:Hop-forward bitterness ranging from session-strength to imperial ABV levels, with aroma varieties imported from US Pacific Northwest and German Hallertau growers. Urban millennials in São Paulo and Buenos Aires drive IPA demand through on-trade discovery venues, converting experimental trial into subscription-based repeat purchases.
- Lagers:Cold-fermented clarity-focused styles requiring extended conditioning timelines and precise temperature control.
- Stouts:Roasted malt-driven dark beers with coffee and chocolate flavor notes, typically seasonal or limited-release positioning.
The dominant share belongs to Ales, while IPAs are expanding most quickly among younger urban demographics.
Distribution Channel:
Channel cost tiers separate premium-margin direct relationships from volume-driven wholesale arrangements, with cold-chain requirements acting as a selective barrier.
- On-trade:Bars, restaurants, and brewpubs serving draft and packaged products for immediate consumption. São Paulo's premium venue density generates discovery-driven trial, though refrigerated distribution gaps in Brazil's northeastern states limit geographic expansion for unpasteurized offerings.
- E-commerce:Direct-to-consumer platforms and subscription services bypassing traditional three-tier markups. Buenos Aires and Santiago specialty retailers are building temperature-controlled last-mile logistics, enabling recurring revenue models that outpace on-trade growth rates for established craft brands.
- Off-trade:Supermarkets and hypermarkets with ambient shelf placement and lower per-unit margins.
- Specialty Stores:Curated bottle shops with trained staff and refrigerated display cases targeting enthusiast consumers.
On-trade still captures the highest per-liter margins, yet e-commerce is climbing the fastest as logistics infrastructure matures.
Consumer Type:
Customer maturity levels distinguish price-sensitive occasional purchasers from brand-loyal advocates willing to pay discovery premiums.
- Millennials:Urban professionals aged 28-43 with disposable income for premium positioning and experience-seeking consumption patterns. This cohort concentrates in Brazil's southeastern states and Argentina's capital region, where craft brewery clustering supports frequent venue rotation and brand exploration.
- Gen Z:Digital-native drinkers aged 18-27 prioritizing Instagrammable packaging and ethical sourcing transparency. ANVISA nutritional labeling mandates resonate with this group's demand for ingredient disclosure, rewarding compliant Brazilian producers with loyalty premiums.
- Craft Enthusiasts:Deeply knowledgeable repeat purchasers seeking limited releases and brewery-direct relationships.
- Casual Drinkers:Occasional craft purchasers defaulting to familiar styles and accessible price points.
Millennials currently anchor volume, though Gen Z is gaining share fastest through social-media-driven discovery mechanics.
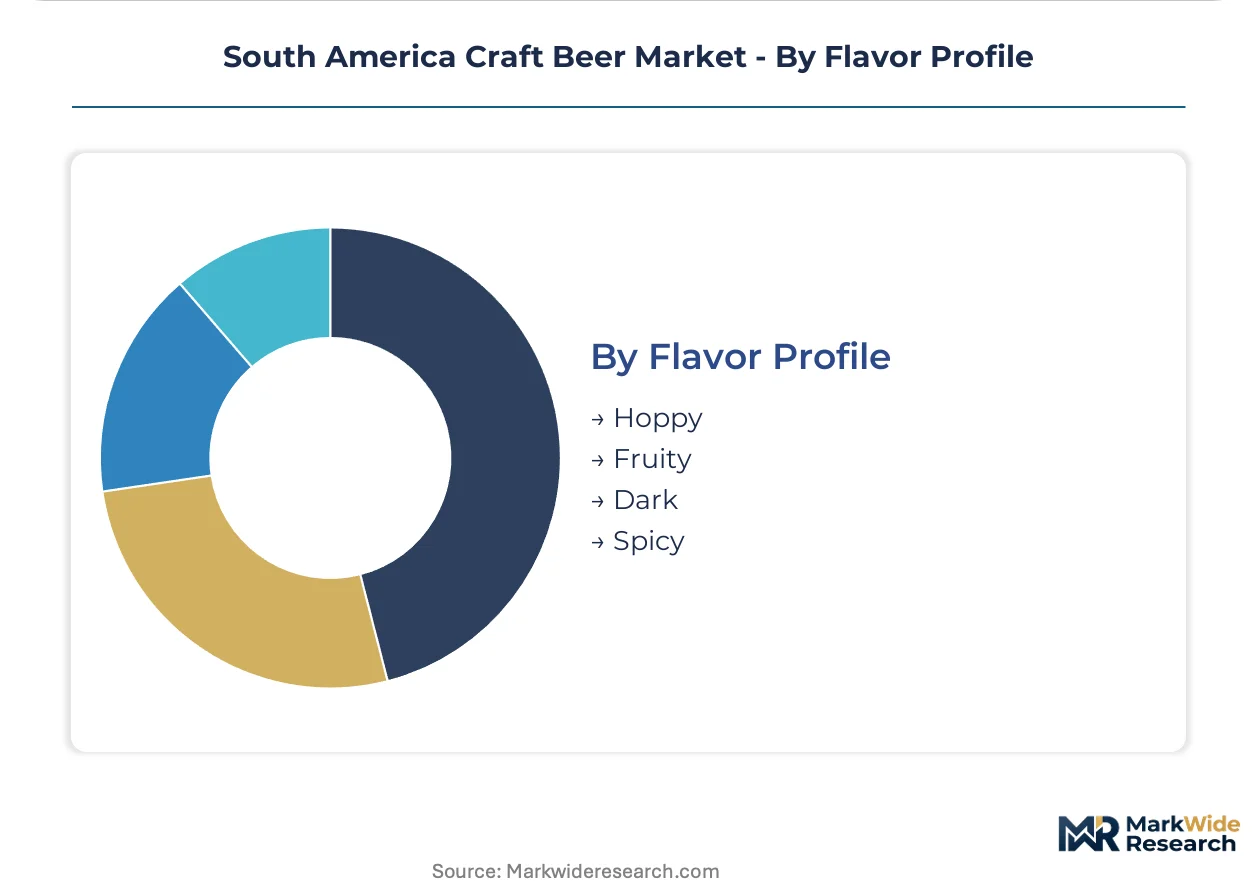
Flavor Profile:
Ingredient differentiation creates pricing power through terroir-specific taste experiences that resist commoditization.
- Hoppy:Bitterness and aroma derived from international and experimental hop varieties. Brazilian brewers face margin exposure from dollar-euro exchange rate volatility on imported inputs, though Patagonian producers are backward integrating into captive barley cultivation to offset supply chain risk.
- Fruity:Native fruit and botanical adjuncts including Amazonian ingredients. Producers experimenting with indigenous flavor profiles command export premiums in European craft markets, creating terroir-differentiated positioning unavailable to mass-market competitors.
- Dark:Roasted malt character with caramel, toffee, or coffee notes, typically winter-seasonal positioning.
- Spicy:Chile, coriander, or indigenous pepper additions for experimental limited releases.
Hoppy profiles retain the largest share, while Fruity formulations are seeing the steepest expansion trajectory as Brazilian producers leverage native ingredient access.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ANVISA's nutritional labeling mandates for alcoholic beverages establish Brazil as the regulatory anchor for South American craft beer compliance standards. Brazil's southeastern states concentrate production capacity and premium on-trade consumption, while Chilean and Argentine markets develop distinct supply chain strategies around barley sourcing and cross-border distribution economics.
Brazil
São Paulo and Rio de Janeiro metropolitan areas generate the highest per-capita craft beer consumption through premium bar and restaurant channels. ANVISA's phased calorie and carbohydrate disclosure requirements compel Minas Gerais breweries to invest in laboratory certification infrastructure by 2026. The southeastern industrial corridor hosts the densest clustering of microbreweries, with cold-chain logistics limitations constraining unpasteurized product distribution to northeastern states.
Argentina
Buenos Aires anchors national demand through discovery-driven on-trade venues serving experimental ales and IPAs to urban millennials. The national food safety authority enforces brewing facility sanitation standards that restrict informal producer market access. Patagonian provinces are developing captive barley cultivation to reduce dependence on imported malt, though agricultural policy uncertainty at the federal level delays investment timelines.
Chile
Santiago's specialty retailers are constructing temperature-controlled last-mile logistics networks enabling subscription-based direct-to-consumer revenue models. German-heritage brewing traditions sustain market presence in southern regions, where Cerveceria Kunstmann maintains production. The central valley's emerging craft clusters face water access regulations under the country's environmental ministry, adding permitting complexity for new entrants.
Colombia
Bogotá's premium venue density is accelerating craft adoption among Gen Z drinkers prioritizing Instagrammable packaging and ethical sourcing transparency. The national food and drug regulator enforces labeling standards that align with Mercosur harmonization efforts, simplifying cross-border export procedures for Brazilian producers. Andean corridor distribution remains constrained by refrigerated infrastructure gaps between major metropolitan centers.
South America Craft Beer Market Competitive Landscape
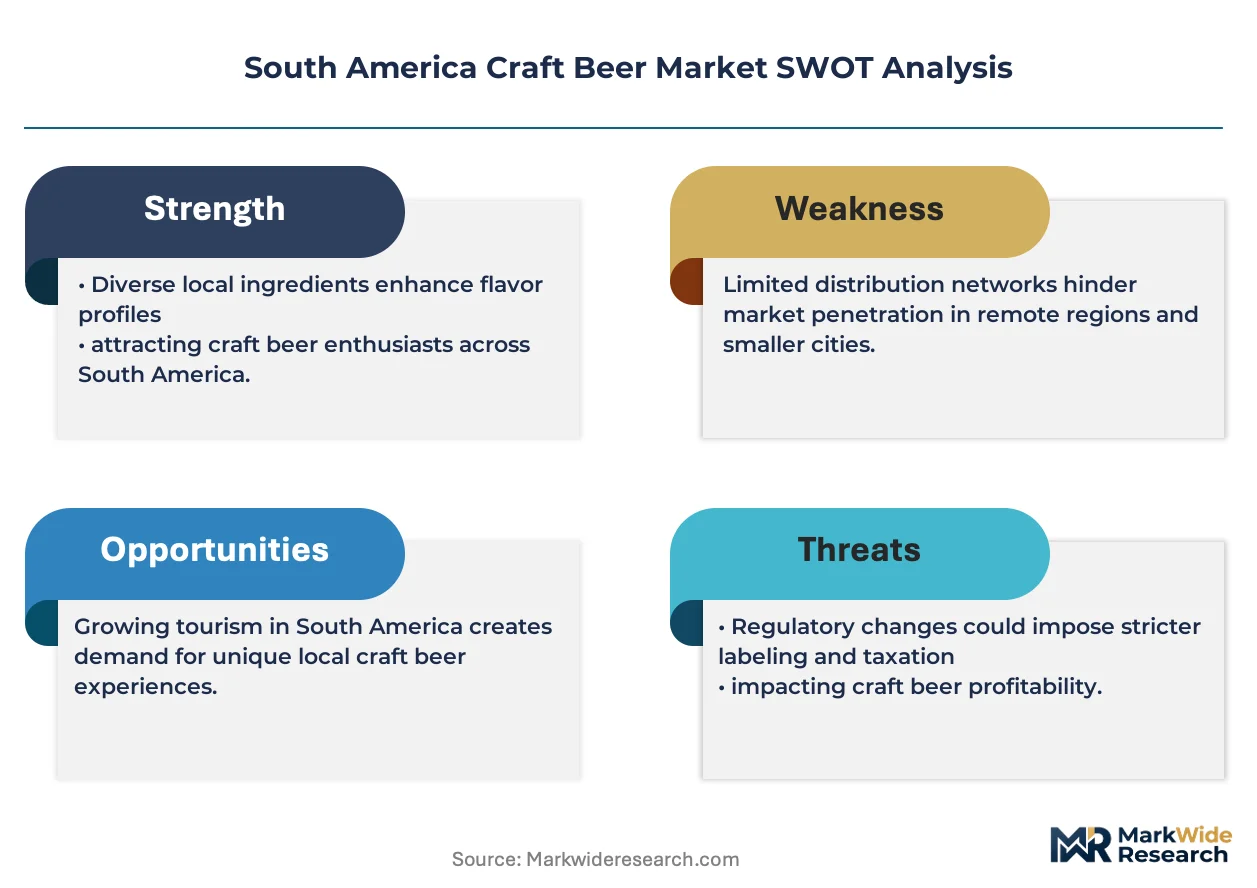
Vertically integrated heritage brewers and experimental microbreweries split the market along supply-chain-control versus flavor-innovation vectors. Brazil's southeastern states host the most fragmented competitive environment, with operator counts multiplying across Minas Gerais and São Paulo. Three archetypes dominate: backward-integrated barley cultivators, indigenous-ingredient experimentalists, and German-heritage traditionalists. Capacity expansion and e-commerce channel development represent the primary competitive moves, as producers bypass traditional three-tier distribution markups.
Among heritage-anchored specialists, Cerveceria Kunstmann occupies a position exemplifying sustained regional presence through traditional brewing methods. Cervejaria Colorado represents the experimental archetype, with portfolio development around localized Brazilian flavor profiles. Patagonia Brewery anchors the vertically integrated tier, with upstream control over barley sourcing and malting operations insulating margin positions from Argentine grain export volatility. These three companies collectively illustrate the strategic segmentation defining competitive positioning across the Southern Cone.
| Leading Market Players |
|---|
| Bogota Beer Company |
| Patagonia Brewery |
| Cerveceria Altamira |
| Cerveceria Antares |
| Cervejaria Colorado |
| Baden Baden |
| Cervejaria Bodebrown |
| Cerveceria Kunstmann |
| Cerveceria Sierra Andina |
| Others |
Value Network & Pricing Analysis
Minas Gerais hosts Brazil's densest craft brewery clustering, where capacity concentration among mid-sized operators creates asymmetric pricing power against dispersed microbreweries struggling with ANVISA compliance costs. São Paulo's premium on-trade venues absorb higher per-liter prices for limited releases, while northeastern states face price premiums driven by refrigerated distribution gaps.
Pricing Analysis
Brazil's southeastern states command 15-20% price premiums over Andean markets due to on-trade density and brand discovery velocity. Three-tier pricing structure across premium limited releases, standard core portfolios, and economy session ales separates craft positioning tiers. Cost compression in economy segments is intensifying because glass bottle supply concentrates among southeastern manufacturers. Casual drinkers in off-trade channels exhibit highest price sensitivity, while craft enthusiasts accept subscription premiums for direct-to-access limited releases.
Supply Chain Analysis
Brazilian and Argentine maltsters hold dominant brewing input capacity, though Chilean producers are backward integrating into captive barley cultivation. Aroma hops draw from US Pacific Northwest and German Hallertau growers, exposing margins to dollar-euro exchange volatility. Single-source vulnerability concentrates in glass packaging, where southeastern Brazilian manufacturers control regional supply. Distribution runs through temperature-sensitive three-tier systems with emerging direct-to-consumer bypass in Buenos Aires and Santiago.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent craft brewers face substitution pressure from hard seltzers and ready-to-drink cocktails capturing Gen Z trial occasions, requiring defensive portfolio moves to retain core drinker relationships.
For Market Incumbents: Harden brand loyalty through subscription-based discovery programs that lock in recurring revenue before trial shifts to substitutes. Invest in laboratory certification infrastructure to capture ANVISA compliance premiums that smaller competitors cannot match. Prioritize backward integration into barley sourcing to insulate margin positions from Argentine grain export volatility. For New Entrants and Emerging Players: Pursue indigenous ingredient differentiation targeting European export markets where terroir-specific Amazonian botanicals command premium positioning. Brazil's northeastern states present the most penetrable geography given refrigerated distribution gaps that favor pasteurized product formats. Launch through e-commerce direct channels to bypass established three-tier markups and build subscriber bases before on-trade expansion. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertically integrated operators with captive malt supply and automated brewhouse platforms enabling consistent small-batch replication. Long-term viability rests on producers combining supply chain control with flavor innovation capabilities. Monitor Argentine barley export liberalization policy signals as inflection indicator for Chilean and Uruguayan brewer cost structures.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Barley Cultivation | Patagonian producers reduce Argentine grain import dependency through captive malting operations. |
| E-Commerce Direct Channel Launch | Buenos Aires specialty retailers bypass traditional distribution markups via temperature-controlled subscription logistics. |
| Indigenous Ingredient Portfolio Expansion | Brazilian brewers leverage Amazonian botanical access for terroir-differentiated European export positioning. |
| Automated Brewhouse Technology Deployment | São Paulo mid-sized operators collapse quality variance through cloud-connected fermentation monitoring systems. |
| Laboratory Certification Infrastructure Investment | Minas Gerais producers capture ANVISA compliance premiums ahead of 2026 nutritional labeling deadlines. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with craft brewery founders, supply chain managers at malt distributors, on-trade venue procurement leads, and ANVISA regulatory affairs specialists; and secondary validation through Brazilian customs records, ANVISA regulatory filings, South American brewing association production surveys, and SEC disclosures from beverage conglomerates with craft portfolios. Bottom-up brewery capacity estimates triangulated against top-down consumption modeling.
Forecast inputs considered malted barley price trajectories, hop import cost structures, excise tax regime stability across Mercosur jurisdictions, and e-commerce logistics penetration curves. Segmentation dimensions modeled include product type, distribution channel, consumer cohort, and flavor profile across the projection horizon. CAGRs derived from volume trajectory analysis incorporating brewery expansion announcements and capital deployment patterns.
The forecast holds incumbent behavior within observed patterns; aggressive capacity additions by industrial lager conglomerates or rapid hard seltzer substitution would shift outcomes beyond projected ranges. Quarterly review of ANVISA enforcement intensity, Argentine agricultural export policy signals, and refrigerated logistics investment flows is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Alcoholic Flavors Market
Alcoholic Beverages
Japan Tequila Market
Alcoholic Beverages
Germany Alcohol E-Commerce Market
Alcoholic Beverages
Vodka Seltzer Market
Alcoholic Beverages
Hard Kombucha Market
Alcoholic Beverages
Microbrewery Supplies Market
Alcoholic Beverages
Tea Beer Market
Alcoholic Beverages
Cooking Wine Market
Alcoholic Beverages
Brewers Spent Grain Market
Alcoholic Beverages
Gluten-Free Beer Market
Alcoholic Beverages
South Africa Tequila Market
Alcoholic Beverages
Canned Alcoholic Beverages Market
Alcoholic Beverages
Frozen Cocktails Market
Alcoholic Beverages
Smart Wine Cellar Market
Alcoholic Beverages
Asia-Pacific Craft Beer Market
Alcoholic Beverages
Bioalcohols Market