
 South America Beer Market | 2026-2036
South America Beer Market Size, Share, and Industry Trends Forecast 2026-2036
South America Beer Market Outlook
On-premise draft and experiential consumption revenue is fragmenting across microbrewery taprooms, festival circuits, and branded pop-up formats. Anheuser-Busch InBev leverages its continental logistics network to sustain volume leadership in mass-market lager. Heineken anchors premium positioning through licensed brewing partnerships and sports sponsorship density. Grupo Petrópolis competes aggressively on price in Brazil's northeast and interior markets.
Beer is a fermented alcoholic beverage produced from malted cereals, hops, water, and yeast, typically achieving alcohol-by-volume concentrations between 3% and 12% depending on style and brewing protocol. The brewing process involves mashing, lautering, boiling with hop addition, fermentation, conditioning, and filtration to achieve microbiological stability and flavor consistency for commercial distribution. Lager dominates South American volume due to climatic preference and production economics, while ale and stout segments capture outsized margin in metropolitan premium channels. Packaging type insights reveal aluminum can formats gaining share against returnable glass as brewery investments in canning lines reduce logistics breakage and extend shelf stability for supermarket and convenience store distribution.
ANVISA governs ingredient disclosure and health warning placement on Brazilian beer labels, while Argentina's national food safety authority enforces maximum contaminant thresholds for mycotoxins in malted barley inputs. Brazil's CADE monitors concentration risks in wholesale distribution, preserving access routes for independent craft producers. Stakeholders must track excise tax restructuring debates in Colombia and Peru, where fiscal pressures threaten to alter retail price architecture and trading-up elasticity.
Market Dynamics
Brazil's ANVISA labeling mandates and excise tax restructuring debates across Colombia and Peru are forcing breweries to reformulate products and redesign packaging architectures ahead of enforcement deadlines.
Growth Catalysts
- Urban Millennial Consumption Clusters:São Paulo and Minas Gerais states concentrate per-capita beer consumption and distribution infrastructure density, creating scalable launch platforms for premium craft variants.
- ANVISA Ingredient Disclosure Framework:Mandatory health warning placement and nutritional transparency requirements are accelerating brewery investment in reformulation capabilities and clean-label product lines.
- Aluminum Canning Line Deployment:Brewery capital allocation toward canning infrastructure reduces logistics breakage rates and extends shelf stability for supermarket and convenience store channels.
Market Restraints
- Malted Barley Input Volatility:Argentina's national food safety authority enforces maximum mycotoxin thresholds that constrain sourcing flexibility and elevate quality-control costs for regional malt suppliers.
- Wholesale Distribution Concentration:Brazil's CADE monitors consolidation risks in distributor networks, preserving access routes for independent craft producers but limiting economies of scale for mid-tier brands.
- Wine and Spirits Substitution:Trading-up elasticity in metropolitan premium channels exposes beer to displacement by wine and craft spirits among higher-income demographic segments.
Strategic Opportunities
- Northeast Brazil Price-Tier Penetration:Interior markets in Brazil's northeast exhibit lower per-capita craft penetration and respond aggressively to price-competitive portfolio positioning.
- Festival Circuit and Pop-Up Channels:Experiential consumption formats including microbrewery taprooms and branded temporary installations capture margin-rich on-premise occasions outside traditional bar and restaurant infrastructure.
- Colombia Excise Tax Restructuring:Pending fiscal policy revisions may create window for premium-tier products to capture trading-up demand before retail price architecture stabilizes.
Industry Challenges
- Master Brewer Talent Scarcity:Craft segment expansion outpaces trained fermentation specialist supply, elevating compensation costs and extending product development timelines for artisanal portfolios.
- Returnable Glass-to-Can Transition Friction:Legacy bottle-return logistics networks require phased decommissioning as breweries redeploy capital toward aluminum packaging lines, straining distributor relationships.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Beer Market |
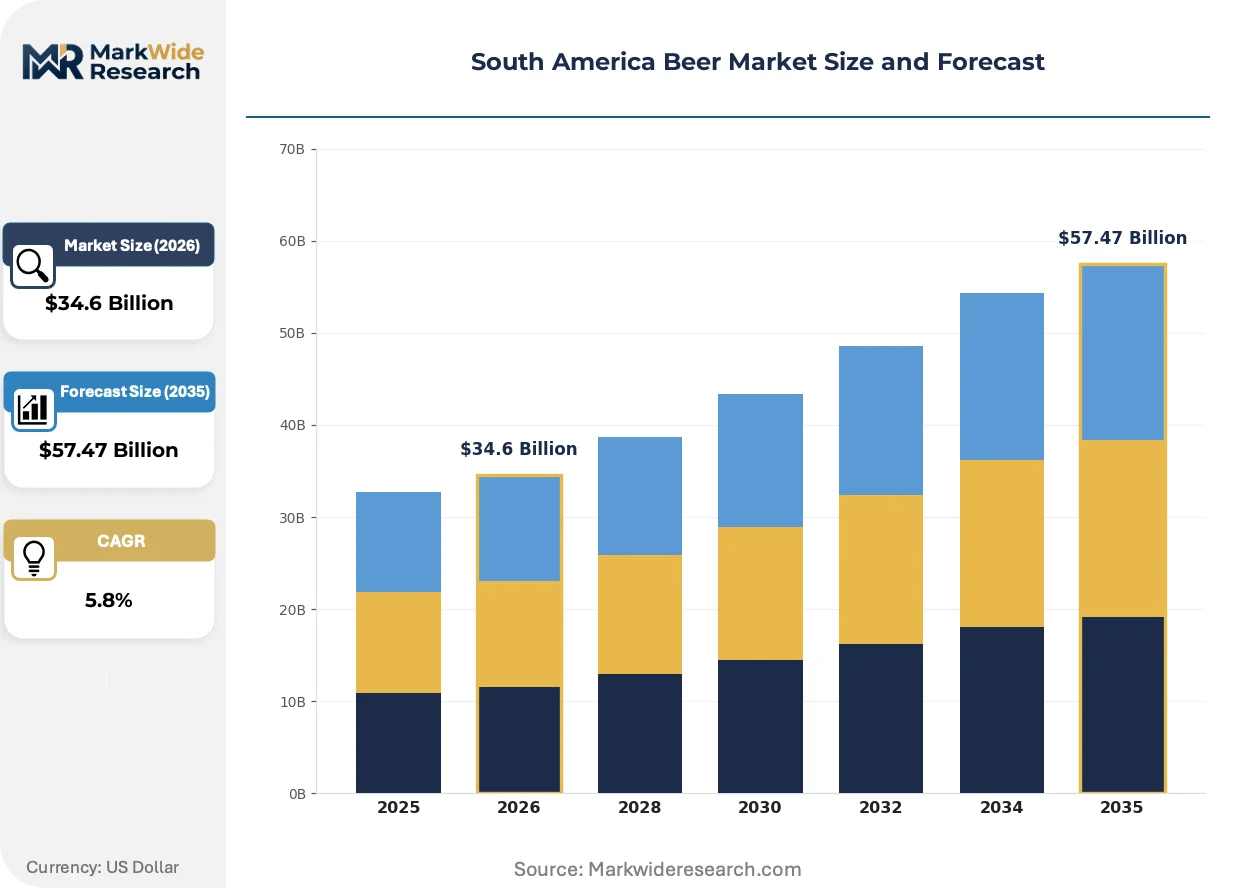
| Market Size in 2026 | $34.6 Billion |
| Market Size in 2035 | $57.47 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lager, Ale, Stout, Porter Packaging Type: Bottle, Can, Keg, Draft Sales Channel: Supermarket, Convenience Store, Bar, Online Customer Type: Retail, Wholesale, Distributor, End User |
| Companies Covered | Bavaria, Carlsberg, Anheuser-Busch InBev, Cervecería y Maltería Quilmes, Molson Coors, Heineken, Grupo Petrópolis, Backus y Johnston, Ambev, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Beer Market Strategic Shifts
Automation in brewing operations and packaging lines is compressing production economics while regulatory transparency mandates and experiential consumption formats are fragmenting traditional channel structures across the continent.
Pasteurization and aseptic filling technology is rendering obsolete thermal processing methods that degrade hop aromatics in premium lager and ale categories. Brazilian craft breweries in São Paulo state are adopting these systems at accelerating cadence. The shift is enabling extended shelf-stable distribution of unpasteurized products without cold-chain dependency, compressing the competitive moat between regional craft operators and national mass-market portfolios.
ANVISA's evolving ingredient disclosure requirements and health warning placement rules are mandating label redesign cycles and reformulation investments across Brazilian production facilities. Industrial consequence includes elevated compliance costs for imported specialty malt and hop inputs that lack standardized nutritional documentation. Premium and super-premium segments face compressed margin structures as they absorb redesign and testing expenditures ahead of enforcement windows.
Direct-to-consumer subscription and brewery membership models are displacing traditional wholesale-dependent distribution for limited-release and seasonal portfolios. São Paulo and Buenos Aires metropolitan craft operators are piloting these channels to capture full retail margin and build proprietary customer data assets. The pattern is most visible among urban millennial and Gen Z cohorts prioritizing access exclusivity over price sensitivity in beverage procurement decisions.
South America Beer Market Segmentation
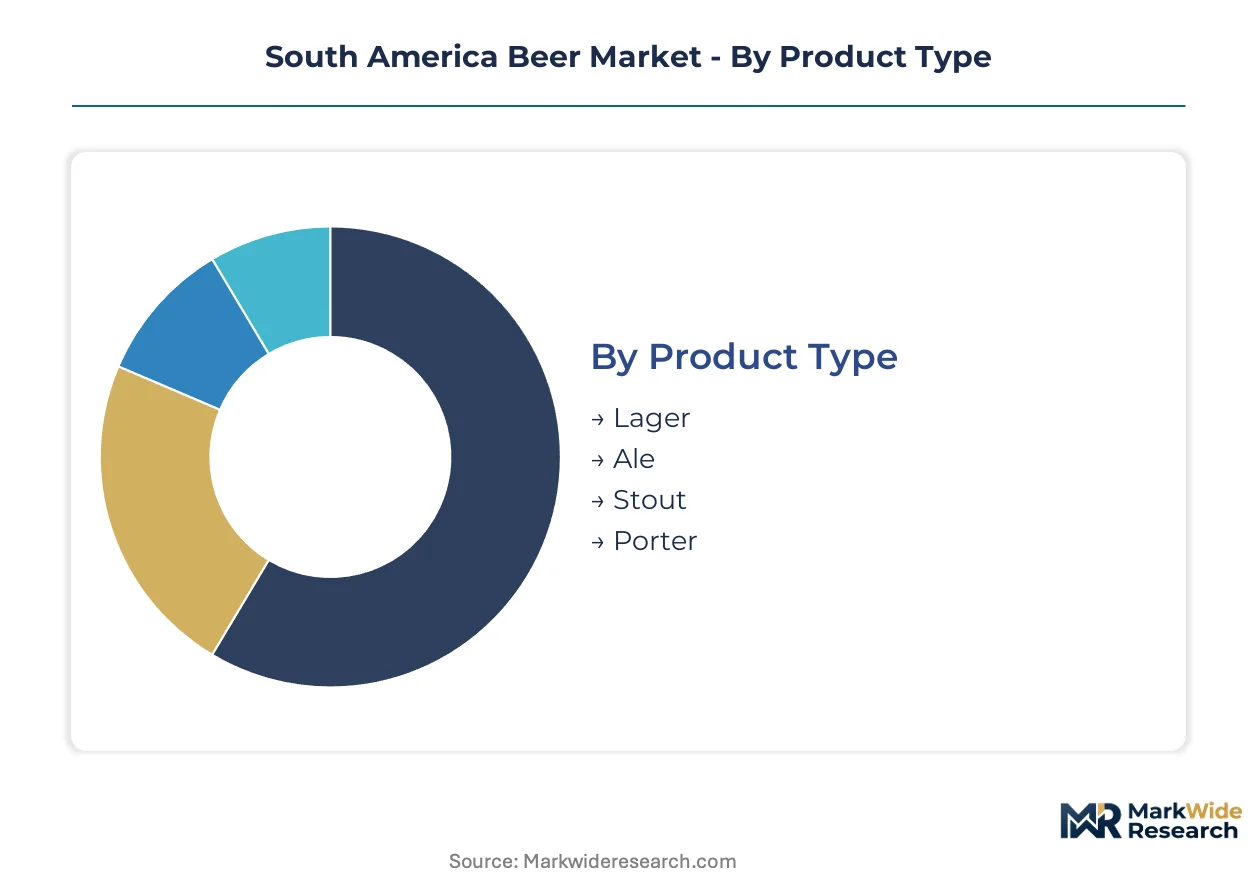
Beer segmentation across South America reflects divergent consumption patterns shaped by climate, urbanization density, and channel infrastructure maturity. Manufacturers calibrate portfolio depth across product, packaging, and sales dimensions to capture margin in premium metropolitan clusters while defending volume in price-sensitive interior markets.
Product Type:
Mature lager formats anchor volume economics while emerging ale and stout variants target premiumization in metropolitan Brazil and Argentina.
- Lager:Bottom-fermented at cooler temperatures producing clean, crisp profiles with alcohol content typically ranging from 4% to 5.5% ABV. São Paulo and Minas Gerais states concentrate lager consumption where established distribution networks and climatic preference sustain mass-market dominance. ANVISA labeling mandates are accelerating reformulation investments across Brazilian lager portfolios to meet disclosure deadlines.
- Ale:Top-fermented at warmer temperatures yielding fruit-forward ester profiles and broader stylistic variation from pale ale through IPA. Demand concentrates in São Paulo's urban millennial clusters and Buenos Aires metropolitan zones where craft taproom density supports trading-up behavior. Pasteurization technology adoption is extending shelf-stable distribution without cold-chain dependency.
- Stout:Dark-roasted malt character with higher gravity profiles typically exceeding 6% ABV, occupying niche premium positioning.
- Porter:Historical English style with moderated roast intensity compared to stout, capturing limited volume in specialty import channels.
Lager handles the majority of throughput; ale is the fastest mover on share.
Packaging Type:
Cost-tier differentiation separates returnable glass infrastructure from aluminum canning line investments reshaping logistics economics.
- Bottle:Returnable glass systems dominate Brazil's interior and northeast markets where deposit-return logistics remain embedded in distributor relationships. Argentina's national food safety authority enforces mycotoxin thresholds that elevate quality-control costs for malt inputs bottled at regional facilities.
- Can:Aluminum formats gain share against glass as brewery capital allocation toward canning lines reduces breakage rates and extends shelf stability for supermarket distribution. São Paulo craft operators are deploying aseptic filling technology to compress production economics versus mass-market portfolios.
- Keg:Stainless steel returnable containers serving on-premise draft consumption at bars and festival circuits.
- Draft:Direct-from-tank dispensing systems concentrated in microbrewery taprooms and experiential pop-up formats capturing margin-rich occasions.
Bottle retains volume leadership in Brazil's northeast; can is expanding most quickly in southeastern supermarket channels.
Sales Channel:
Application-based fragmentation separates routine home consumption from experiential on-premise occasions requiring distinct margin architectures.
- Supermarket:Multi-brand retail environments where aluminum can formats and clean-label positioning drive shelf-space competition. Brazil's CADE monitoring of wholesale distribution concentration preserves access routes for independent craft producers seeking national retail presence.
- Convenience Store:Impulse-oriented locations favoring single-serve can formats with extended shelf stability requirements.
- Bar:On-premise draft and bottle service capturing premium pricing through experiential consumption occasions.
- Online:Direct-to-consumer subscription models piloted by São Paulo and Buenos Aires craft operators to capture full retail margin and build proprietary customer data assets.
Supermarket channels handle the majority of packaged volume; online is gaining share fastest among urban millennial cohorts.
Customer Type:
Supply concentration patterns differentiate volume purchasers with logistics leverage from fragmented end-user demand.
- Retail:Individual consumers purchasing through supermarket, convenience, and online channels with rising preference for craft and artisanal variants.
- Wholesale:Intermediate buyers consolidating volume for redistribution to smaller retail accounts across Brazil's interior markets.
- Distributor:Licensed logistics operators controlling cold-chain infrastructure and route-to-market access, monitored by Brazil's CADE for concentration risks.
- End User:On-premise consumption venues including bars, microbrewery taprooms, and festival circuits where experiential formats command premium pricing.
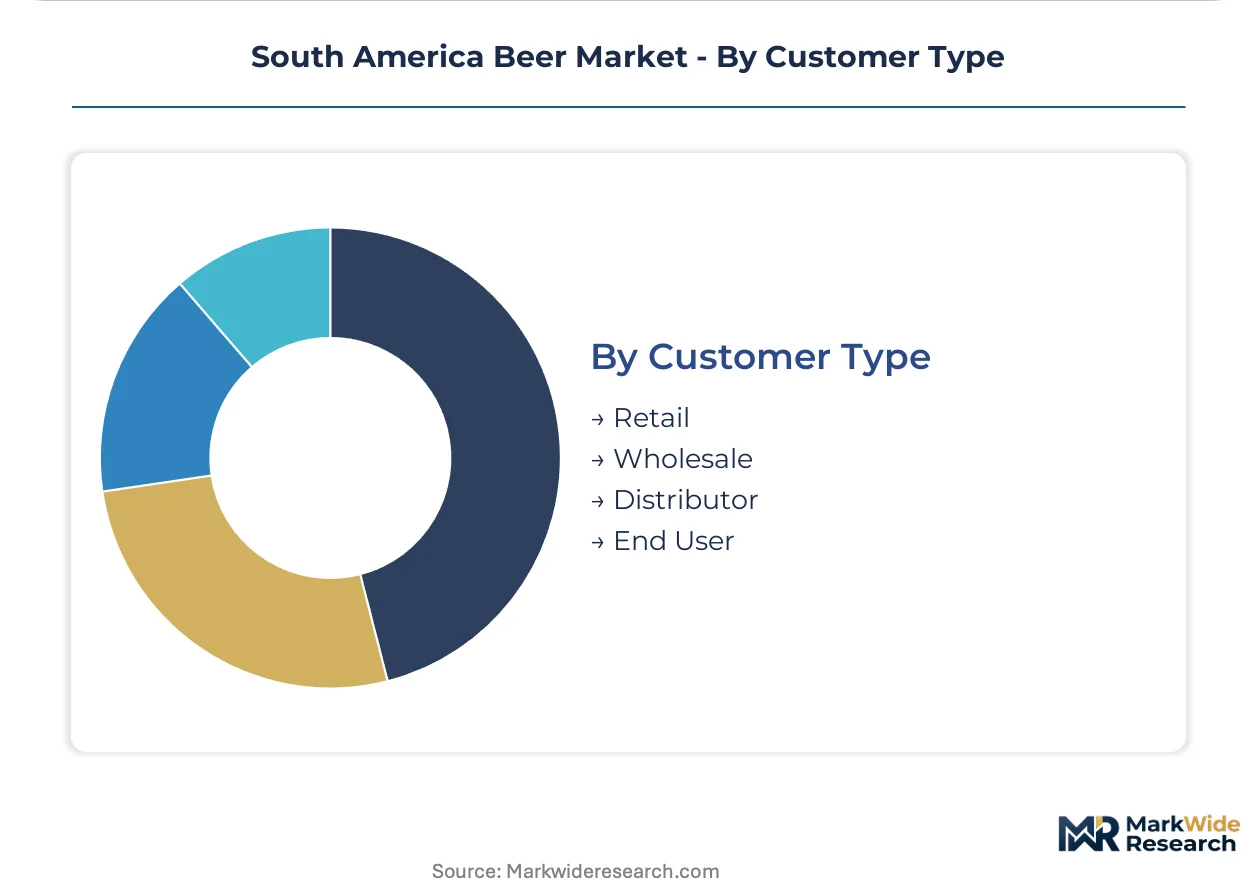
Distributor networks handle the majority of volume throughput; end user direct procurement is climbing the fastest as taproom and subscription models proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's southeastern corridor consumes beer through supermarket and convenience channels with heavy can-format preference, while Argentina's metropolitan centers favor on-premise draft and returnable glass systems. Colombia's Andean markets balance between lager volume and emerging craft penetration. Peru and Chile exhibit distinct taxation-driven pricing architectures that reshape portfolio mix.
Brazil
São Paulo and Minas Gerais states anchor per-capita consumption density with established aluminum canning infrastructure and supermarket channel dominance. ANVISA governs ingredient disclosure mandates and health warning placement requirements that accelerate reformulation investments. Rio de Janeiro and Paraná states concentrate craft brewery taproom expansion where direct-to-consumer subscription models capture urban millennial demand.
Argentina
Buenos Aires metropolitan zone drives premium ale and stout adoption through microbrewery density and festival circuit penetration. The national food safety authority enforces mycotoxin thresholds in malted barley inputs that constrain regional sourcing flexibility. Córdoba and Mendoza provinces support interior distribution networks where returnable glass logistics remain embedded in wholesale relationships.
Colombia
Bogotá and Medellín urban clusters exhibit accelerating craft beer trading-up among Gen Z consumers in experiential pop-up formats. Pending excise tax restructuring debates threaten to alter retail price architecture and premium-tier elasticity. Cali and Barranquilla metropolitan areas concentrate mass-market lager volume through conventional bar and supermarket channels.
Peru
Lima metropolitan demand fragments between traditional on-premise consumption and emerging supermarket can-format preference. Fiscal pressure on alcohol taxation frameworks creates uncertainty in portfolio pricing strategy for imported and domestic premium lines. Arequipa and Trujillo cities anchor regional distribution nodes for interior market penetration.
Chile
Santiago metropolitan concentration supports premiumization trends in craft ale and specialty import channels. National taxation policy shapes competitive positioning between domestic mass-market lager and higher-ABV imported variants. Valparaíso and Concepción urban zones maintain distinct consumption patterns tied to port logistics and regional brewing infrastructure.
South America Beer Market Competitive Environment
Capability concentration sits with craft specialists deploying aseptic filling and direct-to-consumer channels; scale advantage sits with mass-market operators leveraging continental logistics networks and licensed brewing partnerships. The market structures around three tiers: global volume leaders with integrated distribution, regional price competitors with interior market focus, and urban craft operators capturing premium margin through experiential formats. Dominant competitive moves include aluminum canning line deployment to reduce logistics breakage and strategic partnerships with sports sponsorship assets to anchor brand positioning.
Among global-scale brewers, Anheuser-Busch InBev and Heineken occupy positions representing integrated logistics and premium licensing archetypes respectively. Grupo Petrópolis exemplifies regional price-competitive positioning within Brazil's northeast and interior markets. These three entities anchor the competitive structure without exhausting the participant base.
| Leading Market Players |
|---|
| Bavaria |
| Carlsberg |
| Anheuser-Busch InBev |
| Cervecería y Maltería Quilmes |
| Molson Coors |
| Heineken |
| Grupo Petrópolis |
| Backus y Johnston |
| Ambev |
| Others |
Value Chain & Pricing Dynamics
The Santos-Guarulhos logistics corridor carries malted barley and aluminum can inputs from port terminals to São Paulo state brewing facilities, with freight cost volatility compressing margin structures for craft operators while mass-market incumbents absorb shocks through volume leverage. This corridor's cost dynamics concentrate pricing power among distributors controlling cold-chain infrastructure and fragment downstream price differentiation between supermarket can formats and returnable glass bottle tiers.
Pricing Analysis
Long-term offtake contracts dominate malted barley procurement for Brazilian mass-market brewers, while craft operators rely on spot markets for specialty hop inputs and project-based canning line investments. Three-tier pricing structure across premium, standard, and economy levels separates experiential taproom ale from supermarket lager and interior market discount brands. Pricing pressure stems from ANVISA compliance costs elevating label redesign expenditures ahead of enforcement deadlines. Economy-tier consumers in Brazil's northeast exhibit highest price sensitivity; metropolitan craft subscribers in Buenos Aires show lowest sensitivity to per-unit increases.
Supply Chain Analysis
Argentina's mycotoxin inspection regimes and Brazil's ANVISA ingredient documentation requirements function as de facto export controls limiting cross-border specialty malt flows. Supply concentration centers on Argentina for malting barley, Brazil for aluminum can manufacturing, and Germany for advanced brewing equipment. Raw material dependencies include malted cereals, hop extracts, and aseptic filling system components. Single-source vulnerability runs through German pasteurization technology suppliers. Distribution runs through licensed cold-chain operators monitored by Brazil's CADE for concentration risks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Master brewer talent scarcity constrains craft segment expansion across São Paulo and Buenos Aires, extending product development timelines and elevating compensation costs for fermentation specialists with formal training credentials.
For Market Incumbents: Harden logistics networks against distributor consolidation by securing exclusive route-to-market agreements in Minas Gerais and Paraná states before CADE intervention limits acquisition options. Invest in captive canning line capacity to reduce aluminum format cost exposure. Defend mass-market lager positioning through sports sponsorship density that craft operators cannot replicate at equivalent scale. For New Entrants and Emerging Players: Establish a beachhead in Colombia's pending excise tax restructuring window by positioning premium-tier products before retail price architecture stabilizes. Target Peru's Arequipa and Trujillo regional nodes where supermarket can-format penetration lags southeastern Brazil. Deploy direct-to-consumer subscription models in Buenos Aires metropolitan zones to capture full retail margin and build proprietary customer data assets. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors craft operators deploying aseptic filling systems and direct-to-consumer channels over mass-market incumbents with legacy returnable glass infrastructure. Long-term viability across the analysis window hinges on regulatory compliance capabilities and experiential format execution. Target acquisition archetypes include São Paulo craft breweries with pasteurization technology adoption and established subscription bases. The signal to watch is ANVISA enforcement timing accelerating consolidation among undercapitalized reformulation laggards.| Strategic Initiative | Industry Significance |
|---|---|
| Aseptic Filling Technology Deployment | São Paulo craft operators compress production economics versus mass-market portfolios through pasteurization bypass. |
| Direct-to-Consumer Channel Launch | Urban millennial subscription models in Buenos Aires capture full retail margin outside wholesale-dependent distribution. |
| Aluminum Canning Line Investment | Brewery capital redeployment reduces logistics breakage and extends shelf stability for supermarket channels. |
| Licensed Brewing Partnership | Heineken leverages sports sponsorship density to anchor premium positioning against AB InBev volume leadership. |
| Clean-Label Reformulation Program | ANVISA disclosure mandates force accelerated investment in ingredient transparency and nutritional documentation. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of ANVISA regulatory filings, Brazilian customs trade data, and CADE concentration monitoring reports. Master brewers, distributor logistics heads, and supermarket category buyers provided operational perspective on can-format transition economics. Brewery R&D directors and equipment procurement leads supplied input on aseptic filling technology adoption timelines. Secondary validation drew from excise tax policy documents in Colombia and Peru, alongside aluminum industry capacity disclosures. Bottom-up volume modeling triangulated against top-down value projections across product, packaging, and channel segmentation dimensions.
Forecast inputs include malted barley price trajectories, canning line deployment schedules, and regulatory enforcement calendars across the projection horizon. Segmentation dimensions modeled encompass product type hierarchy, packaging format migration curves, and sales channel fragmentation between experiential and routine consumption occasions. CAGRs derive from regression analysis against per-capita consumption density and urbanization rate proxies. Industry-specific forecast inputs incorporate ANVISA compliance cost absorption curves and craft brewery taproom density saturation thresholds.
Stress conditions across excise tax restructuring timelines, mycotoxin threshold enforcement stringency, and aluminum input cost bands were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory adherence rates and technology adoption cadence among mid-tier craft operators. Material shifts in Brazil's CADE distributor concentration rulings or Colombia's fiscal policy implementation would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Global Wine Market
Alcoholic Beverages
Smart Wine Cellar Market
Alcoholic Beverages
Asia-Pacific Alcoholic Beverage Market
Alcoholic Beverages
Bioalcohols Market
Alcoholic Beverages
E Liquid Market
Alcoholic Beverages
Canned Wine Market
Alcoholic Beverages
Beer Mug Market
Alcoholic Beverages
Global Malt Market
Alcoholic Beverages
Global Craft Vodka Market
Alcoholic Beverages
Port Wine Market
Alcoholic Beverages
Wine Aerator Market
Alcoholic Beverages
Alcohol Gummies Market
Alcoholic Beverages
Guerbet Alcohols Market
Alcoholic Beverages
Wine Filtering Machine Market
Alcoholic Beverages
Fruit Brandy Market
Alcoholic Beverages
Whey Based Vodka Market