
 Irish Whiskey Market | 2026-2036
Irish Whiskey Market Size, Share, and Industry Trends Forecast 2026-2036
Irish Whiskey Market Intelligence
Precision barrel management and cask finishing protocols is reconfiguring production economics across the Irish whiskey value chain. Suntory Global Spirits Inc leverages its Japanese parent company's wood science expertise to sustain premium positioning in aged expressions. William Grant & Sons anchors its Irish portfolio through dedicated distilling capacity and heritage brand architecture. Diageo Plc competes via scaled distribution networks that control on-trade and travel retail placement globally.
Irish whiskey denotes a triple-distilled spirit produced from malted and unmalted cereals on the island of Ireland, aged a minimum three years in wooden casks not exceeding 700 liters, yielding a characteristically smooth, fruity profile. Its primary commercial purpose centers on premium beverage consumption across retail, hospitality, and duty-free channels. Blended Irish whiskey occupies the volume core, while single pot still commands concentrated margin pools among connoisseurs. Online retailers represent the fastest-growing retail channel, though specialty stores retain outsized influence on collector-grade releases and limited editions.
The EU Geographical Indication framework and Ireland's national spirits regulator enforce production location, distillation method, and aging requirements that define market access for export-labeled product. The US Alcohol and Tobacco Tax and Trade Bureau governs import classification and labeling standards that shape American consumer perception of authenticity. Stakeholders must monitor evolving trade tariff structures between the European Union and major export destinations, as these directly alter competitive cost positions without warning.
Market Dynamics
Premiumization pressure and maturation cycle economics are tightening capital efficiency requirements across Irish whiskey production, forcing distillers to optimize cask utilization rates while extending aged stock positions.
Growth Catalysts
- EU Geographical Indication framework:Ireland's protected designation enforces provenance standards that block counterfeit competition and secure premium pricing in export markets. The regulation mandates triple distillation and island-origin aging that differentiates authentic product.
- American cocktail culture:Mixology revival in the United States has elevated Irish whiskey's smooth profile as a preferred base spirit for craft cocktails, expanding on-trade volume and brand visibility among younger demographics.
- Ex-Bourbon cask sourcing:Distillers are securing long-term supply agreements with Kentucky cooperages for first-fill American oak, enabling consistent flavor profiles in core blended expressions without competing for scarce sherry cask inventory.
Market Restraints
- Barley price volatility:Climate-driven harvest variability in Ireland and Scotland compresses margin predictability for malt-forward producers dependent on local cereal supply.
- Cooperage concentration:Spanish sherry cask availability remains constrained by bodega consolidation in Jerez, creating bottleneck risk for premium single pot still aging programs.
- Maturation capital lock-up:Three-year minimum aging requirements under EU Spirits Regulation tie working capital in inventory for 36+ months before revenue recognition, disadvantaging new market entrants against established stockholders.
Strategic Opportunities
- China's spirits liberalization:Reduced import tariffs and rising middle-class consumption in tier-one cities create whitespace for super-premium positioning of aged single malts and pot still expressions.
- Direct-to-consumer channels:Distillery-exclusive releases and membership programs bypass traditional three-tier distribution, capturing full margin on limited editions while building proprietary customer data assets.
- Wine cask finishing innovation:Experimentation with ex-Burgundy, ex-Port, and ex-Madeira casks is migrating from niche craft producers to scaled operations, enabling flavor differentiation without extended aging timelines.
Industry Challenges
- Master distiller scarcity:Retirement waves among post-1980s distillery revival veterans create knowledge transfer gaps in traditional pot still operation and cask management protocols.
- Carbon compliance retrofitting:Ireland's national emissions targets and the EU Green Deal mandate energy-intensive kiln and distillation process modifications that disrupt legacy facility configurations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Irish Whiskey Market |
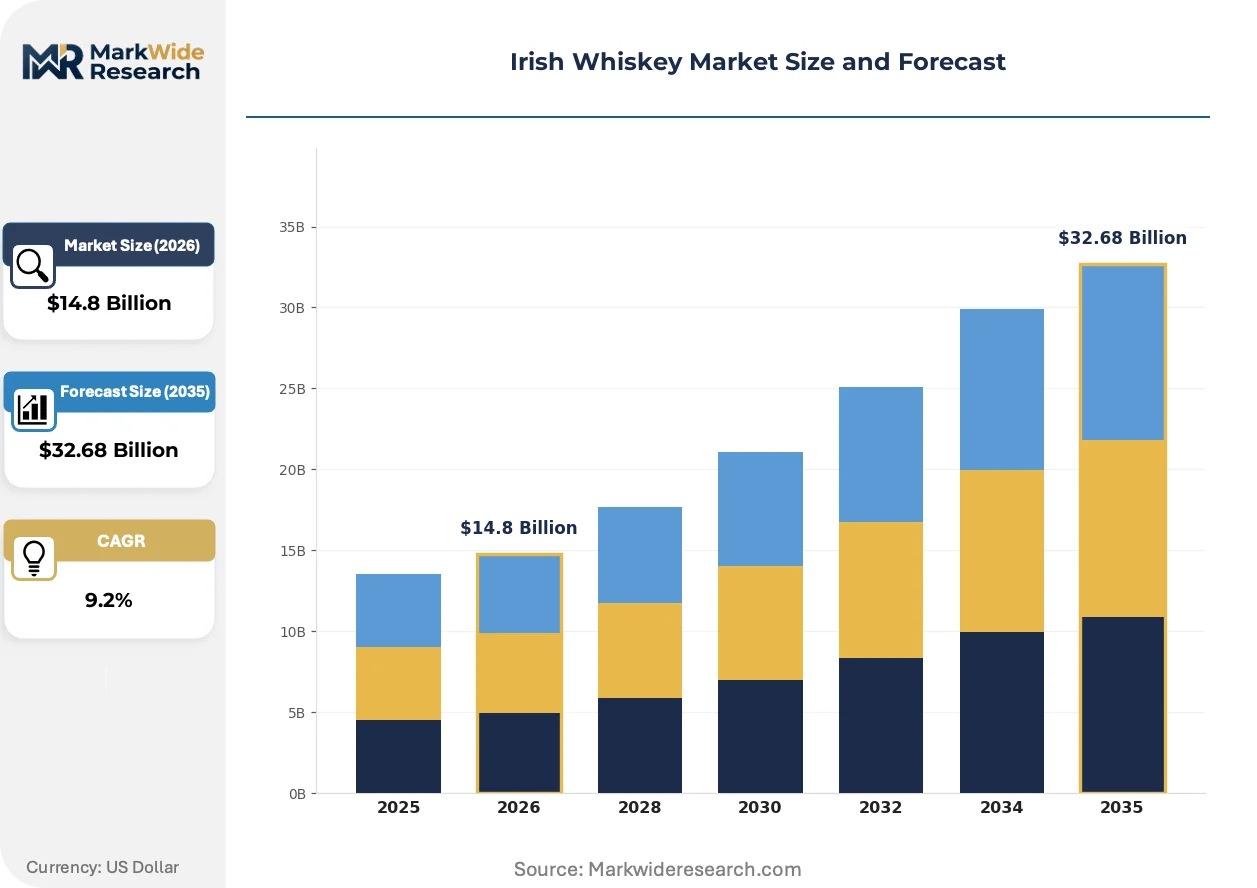
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Malt, Blended, Single Pot Still, Grain, Cask Strength Packaging Type: Bottle, Can, Gift Box, Miniature, Barrel Consumer Type: Connoisseurs, Casual Drinkers, Collectors, Bartenders, Event Planners Retail Channel: Specialty Stores, Online Retailers, Duty-Free Shops, Liquor Stores, Bars |
| Companies Covered | Suntory Global Spirits Inc, William Grant & Sons, Diageo Plc, Beam Suntory, Sazerac Co. Inc., Pernod Ricard SA, Bacardi Limited, Castle Brands, Brown-Forman Corp, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Irish Whiskey Market Strategic Shifts & Innovations
Wood science advancement and digital traceability systems are reconfiguring how Irish whiskey producers manage provenance authentication and maturation optimization across extended aging cycles.
Precision cask monitoring technology is migrating from laboratory settings to commercial distillery operations. Embedded sensor arrays now track temperature, humidity, and evaporation rates in bonded warehouses, enabling data-driven barrel rotation decisions. Mid-sized distilleries in Cork and Dublin are adopting these systems fastest, compressing the traditional apprenticeship model of cask judgment into algorithmic recommendations that reduce angel's share losses.
The EU Green Deal's carbon border adjustment mechanism is reshaping packaging and logistics decisions for export-bound producers. Distillers must now document scope-three emissions across glass sourcing, labeling, and ocean freight to maintain tariff-advantaged access to continental European markets. Bonded warehousing in Rotterdam and Antwerp is expanding as producers seek to minimize carbon-intensive re-export movements from Irish ports.
Collector behavior is fragmenting traditional retail relationships as enthusiasts prioritize provenance documentation over established brand loyalty. Limited-edition releases with blockchain-registered cask histories command price premiums in secondary markets, displacing conventional age-statement hierarchies. This pattern concentrates in the United States and United Kingdom, where auction platforms and verified resale marketplaces have institutionalized whiskey as an alternative asset class.
Irish Whiskey Market Segmentation
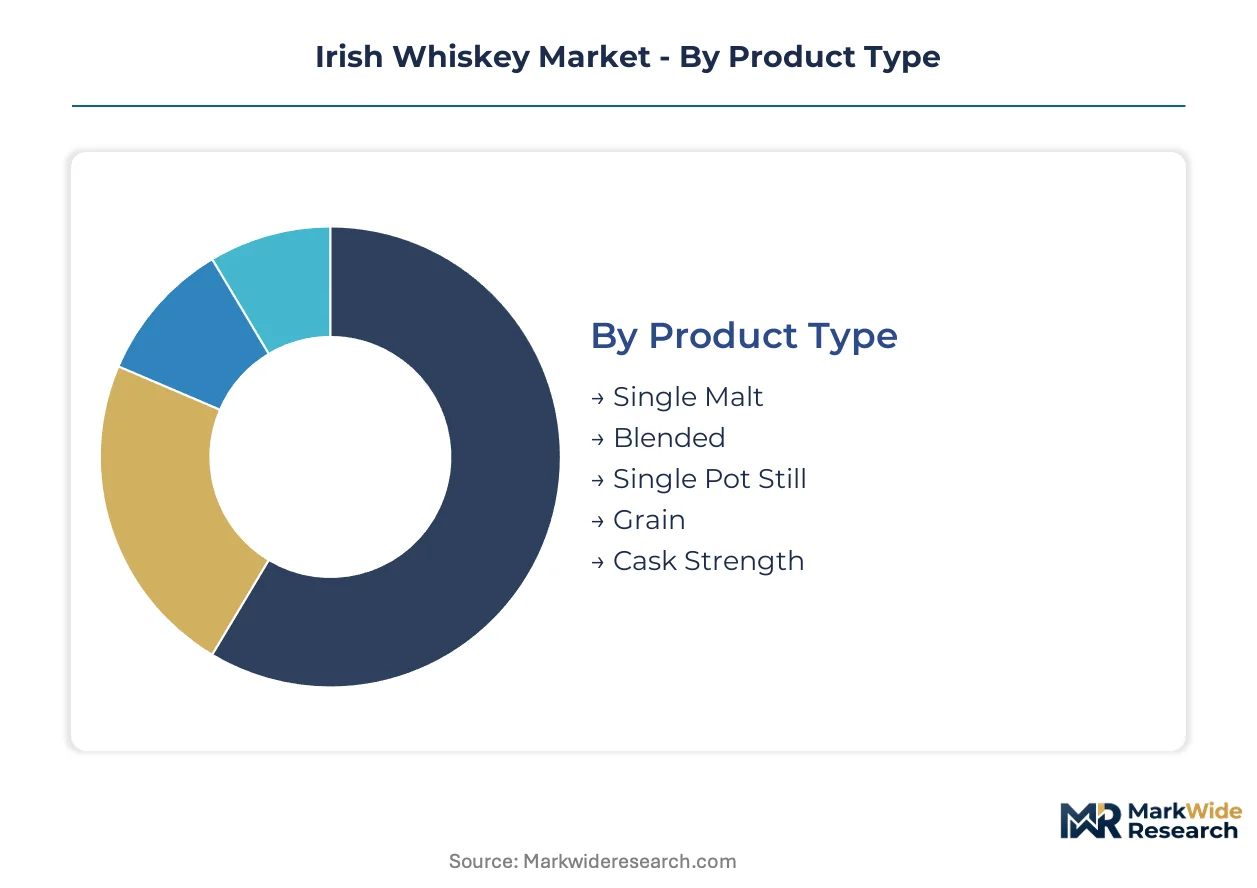
Irish whiskey segmentation reflects divergent production cycles and capital intensity across product categories. Distillers allocate aging inventory and finishing resources based on segment-specific velocity and margin profiles.
Product Type:
Cycle times range from accelerated grain whiskey production to extended single pot still maturation programs tying up capital for decades.
- Single Malt:Produced entirely from malted barley at a single distillery using copper pot stills. United States cocktail bars favor its versatility in highball and sour formats, driving consistent volume through on-trade channels.
- Blended:Combines malt and grain whiskeys from multiple distilleries into accessible flavor profiles. Ireland's domestic hospitality sector and export markets in the United Kingdom absorb the majority of volume, prioritizing consistency over provenance signaling.
- Single Pot Still:Ireland's protected heritage style combining malted and unmalted barley. Connoisseurs in the United States and United Kingdom chase limited releases, creating secondary market premiums for aged stocks.
- Grain:Column-distilled from corn or wheat for lighter body and faster production turnaround. Blenders source this for volume core expressions, compressing time-to-market versus pot still alternatives.
- Cask Strength:Bottled without dilution at original barrel proof. Collectors in American and British auction markets prize these for aging potential and flavor concentration.
Blended anchors the volume base while single pot still gains share at the steepest rate.
Packaging Type:
Cost tiers separate commodity formats from prestige presentation layers that capture gifting occasion premiums.
- Bottle:Standard 700ml and 750ml glass formats dominate retail and hospitality replenishment cycles. Irish distillers source from European glassworks to satisfy EU Green Deal carbon documentation requirements.
- Can:Emerging format for ready-to-serve Irish whiskey cocktails. Younger demographics in the United States trial the category through portable, single-serve packaging.
- Gift Box:Premium presentation packaging with tasting notes and heritage storytelling. Duty-free shops in United States and United Kingdom airports rely on these for traveler gifting occasions.
- Miniature:50ml sampling formats for airline hospitality and hotel minibars. Airlines based in Ireland and the United Kingdom stock these for business class beverage service.
- Barrel:Full cask sales to private buyers and clubs. Wealthy collectors in the United States purchase these for bespoke bottling and cellar ownership status.
Bottle formats command the volume base while barrel sales expand most quickly among ultra-premium buyers.
Consumer Type:
Application intensity varies from daily consumption rituals to episodic collection and event deployment.
- Connoisseurs:Discerning drinkers pursuing provenance, age statements, and craft methodology. Specialty stores in Dublin, Cork, and London cultivate relationships with this segment through allocated releases.
- Casual Drinkers:Occasion-based consumers prioritizing accessibility and mixability. American bars target this group with Irish whiskey highballs and ginger ale serves.
- Collectors:Investors acquiring limited editions for appreciation and portfolio diversification. Verified resale platforms in the United States and United Kingdom institutionalize liquidity for this segment.
- Bartenders:Trade professionals selecting base spirits for cocktail programs. Dublin and New York cocktail bars drive specification influence that shapes brand reputation.
- Event Planners:Corporate and wedding procurement specialists sourcing volume for hospitality occasions. Irish domestic market and United Kingdom event venues represent primary demand concentration.
Casual drinkers anchor the volume base while collectors gain share at the steepest rate.
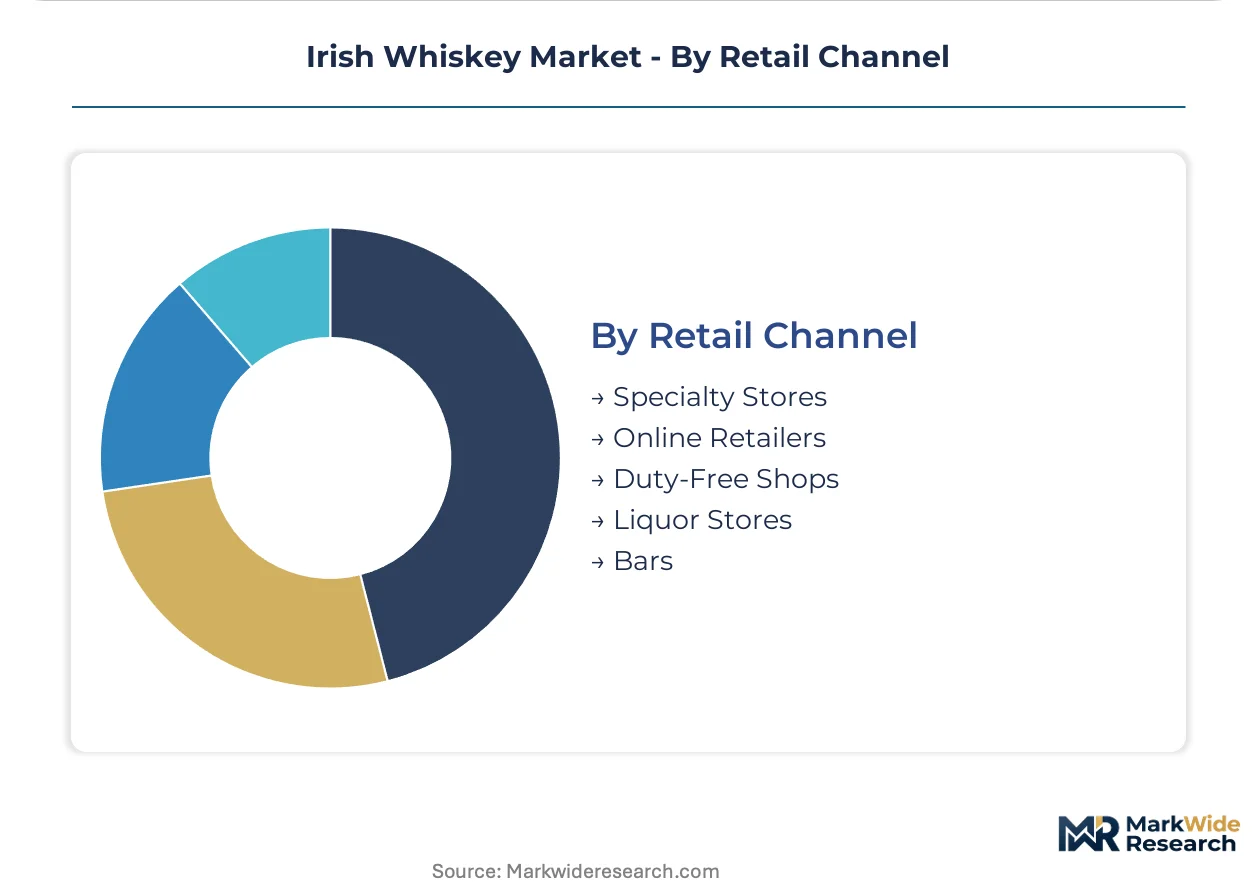
Retail Channel:
Geography and customer type concentrate differently across physical and digital touchpoints.
- Specialty Stores:Independent retailers with curated Irish whiskey selections and staff expertise. Dublin's Celtic Whiskey Shop and London's The Whisky Exchange anchor collector relationships through exclusive allocations.
- Online Retailers:E-commerce platforms with national fulfillment and subscription models. United States consumers in secondary markets access allocated releases without geographic constraint.
- Duty-Free Shops:Airport and border retail with travel-exclusive expressions. Dublin Airport and London Heathrow move significant volume of gift-boxed premium tiers.
- Liquor Stores:Mainstream off-premise retail with broad distribution reach. American control states and licensed retailers in the United Kingdom stock core blended expressions.
- Bars:On-premise consumption venues driving trial and brand education. New York and Chicago cocktail bars elevate Irish whiskey visibility through craft program integration.
Liquor stores anchor the volume base while online retailers gain share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
American collectors and cocktail enthusiasts absorb the largest export volumes, while British connoisseurs drive premium-tier velocity through auction channels and specialty retail. German and French markets exhibit accelerating interest in single pot still expressions, and emerging Asian demand centers on China's tier-one cities.
United States
Mixology-driven consumption in New York and Chicago bars elevates Irish whiskey as a preferred base spirit for craft cocktails. The Alcohol and Tobacco Tax and Trade Bureau governs import classification standards that shape consumer perception of authenticity. Kentucky cooperages supply first-fill ex-Bourbon casks to Irish distillers, cementing transatlantic supply chain interdependence.
United Kingdom
London's The Whisky Exchange and Edinburgh specialty retailers anchor collector relationships through allocated releases and provenance documentation. HM Revenue & Customs administers bonded warehousing regulations that facilitate cask-finishing programs and re-export logistics. Secondary market platforms in London institutionalize whiskey as an alternative asset class among high-net-worth buyers.
Germany
Bavarian and North Rhine-Westphalia hospitality groups specify Irish whiskey for corporate event procurement and premium hotel minibars. The Federal Ministry of Finance enforces EU Spirits Regulation compliance for Geographical Indication-labeled imports. Frankfurt and Munich duty-free channels move significant gift-boxed volumes targeting business traveler gifting occasions.
France
Parisian cocktail bars and Lyon hospitality venues integrate Irish whiskey into aperitif and digestif programs alongside domestic spirits. The National Institute of Origin and Quality collaborates with EU frameworks to recognize protected designation status. Burgundy and Jura wine cask finishing innovations appeal to French palates familiar with terroir-driven beverage differentiation.
China
Shanghai and Beijing tier-one city consumers trial super-premium aged expressions as status-signaling gifts and portfolio diversifiers. The State Administration for Market Regulation oversees import labeling and food safety compliance for spirits distribution. Hainan duty-free zones and bonded warehousing in Guangdong Province reduce tariff exposure for re-export positioning across Asia-Pacific markets.
Irish Whiskey Market Key Industry Players
Channel-controlling players compete with product-specialist players across tiered market positions. The vendor base clusters around three strategic archetypes: diversified spirits conglomerates with scaled distribution networks, family-owned distillers with heritage brand architecture, and Japanese-owned operators leveraging wood science expertise. Dominant competitive moves include securing long-term cooperage supply agreements and expanding direct-to-consumer membership programs that bypass traditional three-tier distribution.
Within the diversified conglomerate tier, Diageo Plc and Pernod Ricard SA exemplify scale-driven positioning through global on-trade and travel retail placement control. William Grant & Sons and Suntory Global Spirits Inc occupy specialist positions, with the former anchoring family-ownership heritage narratives and the latter representing Japanese parent-company wood science integration. Sazerac Co. Inc. sits within the American spirits house archetype, competing through portfolio diversification across brown spirits categories. Beam Suntory and Brown-Forman Corp bridge conglomerate scale with bourbon-category expertise that informs cask sourcing strategies.
| Leading Market Players |
|---|
| Suntory Global Spirits Inc |
| William Grant & Sons |
| Diageo Plc |
| Beam Suntory |
| Sazerac Co. Inc. |
| Pernod Ricard SA |
| Bacardi Limited |
| Castle Brands |
| Brown-Forman Corp |
| Others |
Cost & Logistics Intelligence
Rotterdam-Antwerp bonded warehousing corridors concentrate maturation logistics for EU-bound Irish whiskey, with freight cost differentials between Irish and continental ports feeding directly into tiered pricing structures that separate aged single pot still expressions from standard blended tiers.
Pricing Analysis
Long-term barley supply contracts indexed to Paris Euronext milling wheat futures anchor cost-plus pricing for malt-forward producers. Premium-mid-economy pricing differentiation rests on age-statement certification and cask-provenance documentation, with collector-grade releases commanding substantial premiums over core blended expressions. Cost compression in standard-tier blended whiskey is intensifying because of ex-Bourbon cask competition from American distillers. Casual drinkers in American bars exhibit highest price sensitivity, while connoisseurs in London and Dublin specialty stores demonstrate lowest elasticity for allocated releases.
Supply Chain Analysis
EU Geographical Indication enforcement acts as export-control gatekeeping, restricting market access for non-compliant production. Supply concentration centers on Ireland for distillation, Spain for sherry cask sourcing, and Kentucky for first-fill American oak. Raw material dependencies include Irish malting barley, Jerez cooperage capacity, and Scottish yeast strains. Single-source vulnerability in Spanish sherry bodega consolidation creates bottleneck risk for premium aging programs. Distribution runs through three-tier systems in the United States, bonded wholesale in the United Kingdom, and direct-to-consumer channels for distillery-exclusive releases.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Irish whiskey market approaches a platform-economics inflection as blockchain-registered cask histories and membership programs create proprietary data ecosystems that displace traditional retail intermediation.
For Market Incumbents: Harden cask inventory positions through long-term cooperage agreements with Kentucky and Jerez suppliers before barley price volatility and sherry cask scarcity intensify. Secure bonded warehousing capacity in Rotterdam and Antwerp to minimize carbon-border adjustment exposure under EU Green Deal implementation. Vertical integration into malting operations insulates margin pressure from Euronext-indexed cereal contracts.
For New Entrants and Emerging Players: China's tier-one cities present underpenetration whitespace where reduced import tariffs and rising middle-class consumption create viable super-premium positioning without incumbent stock advantages. Target direct-to-consumer membership programs and distillery-exclusive releases to bypass three-tier distribution capture and build proprietary customer data assets. Emphasize wine cask finishing innovation with ex-Burgundy and ex-Port barrels to differentiate flavor profiles without decade-long aging commitments.
For Investors and Strategic Acquirers: EU Green Deal carbon compliance deadlines reshape the acquisition landscape, favoring targets with existing kiln retrofitting and bonded warehouse carbon documentation systems. Mid-sized distilleries in Cork and Dublin with precision cask monitoring technology and established DTC channels represent optimal acquisition archetypes. Watch for master distiller retirement waves as inflection indicator for knowledge transfer gaps and operational risk.
| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Cooperage Agreement | Secures first-fill American oak from Kentucky and sherry cask pipeline from Jerez bodegas. |
| Direct-to-Consumer Membership Program | Bypasses three-tier distribution to capture full margin on limited editions and build proprietary data assets. |
| Wine Cask Finishing Innovation | Enables flavor differentiation with ex-Burgundy and ex-Port barrels without extended aging timelines. |
| Precision Cask Monitoring Deployment | Reduces angel's share losses through algorithmic barrel rotation recommendations in bonded warehouses. |
| Carbon Compliance Retrofitting | Satisfies EU Green Deal kiln and distillation mandates to maintain tariff-advantaged continental market access. |
Research Approach
Initial hypotheses were tested against primary input from master distillers, cooperage procurement managers, specialty retail buyers, and bonded warehouse operators and refined through secondary validation against EU Spirits Regulation filings, Irish Whiskey Association production statistics, US TTB import classification records, and Euronext agricultural commodity data. Bottom-up volume estimates triangulated with top-down value projections.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation modeled across product type, packaging format, consumer archetype, and retail channel dimensions. CAGRs were derived from trend extrapolation moderated by maturation cycle economics and capital intensity constraints. Forecast inputs incorporated barley harvest variability, sherry cask availability cycles, and tariff structure evolution between the European Union and major export destinations.
Macroeconomic conditions sit as an overlay; deviation in exchange rate volatility, shipping freight indices, or middle-class consumption trajectories in China would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory stability and trade agreement continuity. Material shifts in EU carbon border adjustment implementation or US three-tier distribution reform would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Saffron Beer Market
Alcoholic Beverages
Sparkling Wine Market
Alcoholic Beverages
Grain Alcohol Market
Alcoholic Beverages
Pineapple Beer Market
Alcoholic Beverages
Asia Pacific Beer Market
Alcoholic Beverages
Rhum Agricole Market
Alcoholic Beverages
Herbal Distillates Market
Alcoholic Beverages
Craft Rum Market
Alcoholic Beverages
South America Wine Market
Alcoholic Beverages
Barrel Liner Market
Alcoholic Beverages
Premix Bottled Cocktails Market
Alcoholic Beverages
United States Tequila Market
Alcoholic Beverages
Global Liquor Bottles Market
Alcoholic Beverages
Wine Glass Market
Alcoholic Beverages
Brewers Spent Grain Market
Alcoholic Beverages
Hard Kombucha Market