
 North America Collagen Ingredients Market | 2026-2036
North America Collagen Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
North America Collagen Ingredients Market Analytics
Multi-source procurement strategies is shifting how North American manufacturers secure raw collagen materials. Darling Ingredients Inc. anchors its supply position through vertically integrated rendering and processing assets across the United States. GELITA AG competes by leveraging decades of gelatin expertise to serve food and pharmaceutical formulators with standardized viscosity grades. Rousselot differentiates through marine collagen extraction capabilities that address clean-label preferences in premium cosmetic applications.
Collagen ingredients comprise extracellular matrix proteins—primarily type I, II, and III collagen—extracted through acid or enzymatic hydrolysis of animal connective tissues, with molecular weight distributions determining solubility and bioavailability profiles for targeted end uses. Hydrolyzed collagen dominates volume flows into food and beverage applications where thermal stability and neutral flavor enable beverage fortification, while collagen peptides command premium positioning in nutritional supplements due to documented absorption kinetics. Bovine-sourced material retains cost advantages in mainstream gelatin applications, though marine collagen from Rousselot and others captures accelerating demand in cosmetics where halal certification and perceived purity drive formulation choices.
The FDA oversees New Dietary Ingredient notifications for novel collagen peptides entering supplements, while USDA grading standards govern collagen destined for food applications; Health Canada and PMRA requirements additionally shape cross-border product registration for Canadian market access. The Federal Trade Commission monitors substantiation claims linking collagen to skin elasticity or joint health, pressuring brands toward clinical validation investments. Stakeholders must track evolving FDA guidance on animal-derived ingredient sourcing transparency as consumer litigation risk around labeling intensifies.
Market Dynamics
North American collagen ingredient procurement is reorganizing around supply security as bovine hide availability tightens and marine sourcing gains regulatory traction. FDA New Dietary Ingredient notification requirements now function as a de facto gatekeeper for novel peptide entrants, compressing formulation timelines and favoring established suppliers with dossier libraries.
Growth Catalysts
- Protein fortification mandates:School nutrition programs and institutional foodservice operators across the United States and Canada are expanding collagen inclusion thresholds in meal formulations.
- Joint health positioning:Nutritional supplement brands are leveraging structural claims around cartilage support to capture aging demographic demand in California and Florida retirement corridors.
- Enzymatic hydrolysis advancement:Process intensification is reducing molecular weight variance in peptide outputs, enabling clearer absorption kinetics documentation for FTC substantiation.
Market Restraints
- Bovine input cost volatility:Cattle cycle compression and rendering capacity constraints in the Midwest are squeezing gelatin-grade material margins.
- Marine supply concentration:Wild-caught fish skin and scale sourcing clusters in Atlantic Canada and Alaska, creating single-point vulnerability for clean-label formulators.
- FDA notification friction:Novel collagen peptide structures without 1994 grandfather status face 75-day pre-market review timelines that delay revenue recognition.
Strategic Opportunities
- Mexico manufacturing expansion:Underpenetrated production infrastructure near Baja California offers tariff-advantaged export positioning into US supplement channels.
- Cosmeceutical cross-over:Topical collagen precursor formulations are bridging ingestible and dermal application boundaries in prestige skincare.
- USDA BioPreferred program alignment:Biobased certification pathways for fermentation-derived collagen alternatives are opening federal procurement preferences.
Industry Challenges
- Peptide characterization expertise scarcity:Analytical chemists capable of validating triple-helix disruption profiles and molecular weight distributions command premium compensation in tight labor markets.
- Cross-border Health Canada synchronization:Natural Health Product licensing timelines for Canadian market entry frequently misalign with US launch calendars, fragmenting campaign coordination.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Collagen Ingredients Market |
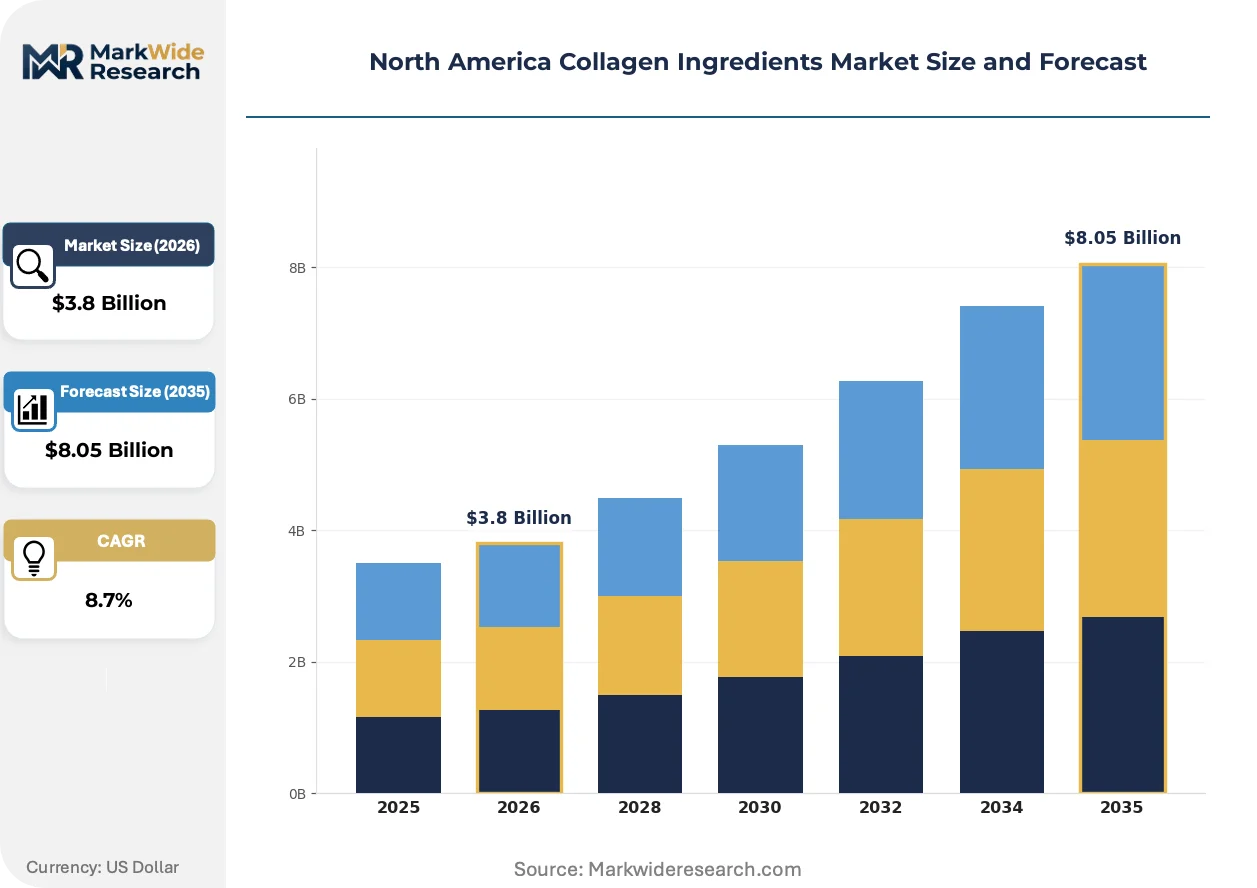
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrolyzed Collagen, Gelatin, Collagen Peptides, Native Collagen Source: Bovine, Porcine, Marine, Poultry Application: Food & Beverage, Cosmetics, Nutritional Supplements, Pharmaceuticals Form: Powder, Liquid, Capsule, Tablet |
| Companies Covered | GELITA AG, Darling Ingredients Inc., Nitta Gelatin NA Inc., Rousselot, Tessenderlo Group, Weishardt, Nippi Collagen NA Inc., Regenity, Collagen Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Collagen Ingredients Market Evolving Landscape
Precision fermentation and cellular agriculture are disrupting traditional animal-derived supply chains while enzymatic specificity advances are collapsing extraction yield variance. These forces are compressing the technical moat between commodity gelatin and premium peptide positioning.
Precision fermentation of recombinant collagen proteins is decentralizing production geography away from rendering facility dependence. Biotech startups and contract manufacturers in Texas and California are commissioning pilot-scale bioreactors to produce type I and III equivalents without animal tissue inputs. This technology is decentralizing supply risk and enabling halal, kosher, and vegan claim simultaneity that animal sourcing cannot match.
The FDA's draft guidance on animal-derived ingredient traceability is tightening documentation requirements for bovine spongiform encephalopathy mitigation. Collagen suppliers must now maintain lot-level geographic provenance records back to slaughter facility. Nutritional supplement brands with direct-to-consumer subscription models face the steepest compliance cost escalation as they lack institutional foodservice audit economies.
Direct sourcing contracts between collagen peptide brands and regenerative ranching operations are displacing commodity spot market purchasing. Supplement formulators in Colorado and Oregon are locking multi-year supply agreements with single-source cattle operations for narrative differentiation. This pattern is most visible in premium positioning channels where origin storytelling commands shelf price premiums over mass-market alternatives.
North America Collagen Ingredients Market Segmentation
Collagen ingredient procurement in North America hinges on precise matching between molecular specifications and end-use performance requirements. Formulators select segments based on thermal stability thresholds, bioavailability documentation, and regulatory pathway complexity rather than commodity pricing alone.
Product Type:
Customization intensity varies sharply across this category, from standardized commodity grades to precision-engineered peptide fractions requiring batch-level certificates of analysis.
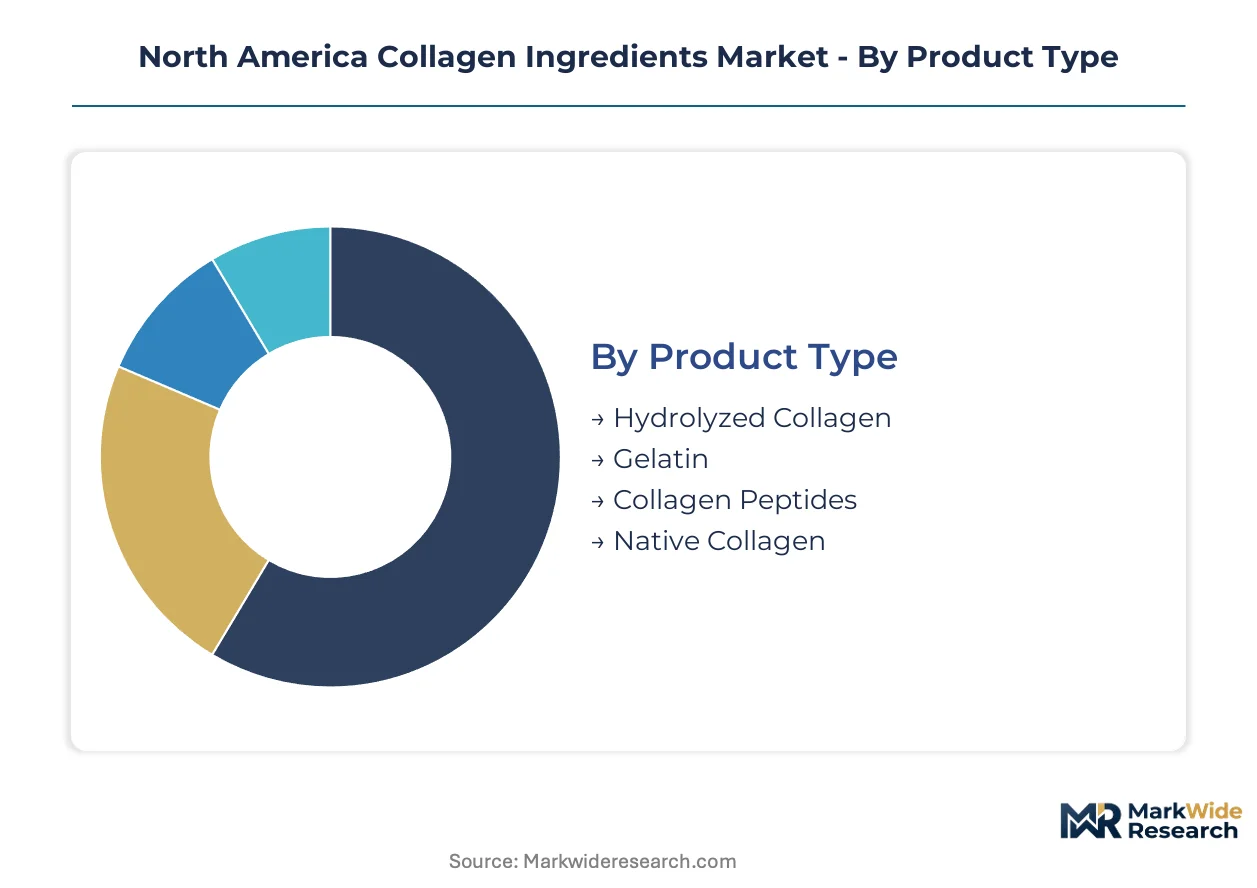
- Hydrolyzed Collagen:Enzymatically cleaved protein fragments with molecular weights typically ranging 2,000-10,000 daltons enable thermal-stable beverage fortification without gelation interference. Demand concentrates in United States foodservice channels where USDA school nutrition programs mandate protein inclusion thresholds.
- Collagen Peptides:Lower molecular weight fractions (below 3,000 daltons) demonstrate documented absorption kinetics through intestinal epithelium, commanding premium positioning in California-based nutritional supplement direct-to-consumer brands. FTC substantiation requirements pressure peptide suppliers toward clinical validation investments.
- Gelatin:Partially hydrolyzed collagen with Bloom strength specifications determines gel-set characteristics for confectionery and pharmaceutical capsule applications.
- Native Collagen:Triple-helix intact proteins serve biomedical scaffolding and wound care matrices where structural integrity outweighs solubility requirements.
Leading the category by volume: Hydrolyzed Collagen. Expanding most quickly: Collagen Peptides.
Source:
Supply security and certification compatibility drive procurement decisions, with halal, kosher, and BSE-traceability requirements filtering viable options.
- Bovine:Hide and bone rendering from United States Midwest cattle operations delivers cost-advantaged gelatin-grade material with established USDA grading protocols. Cattle cycle compression and rendering capacity constraints squeeze margins for commodity purchasers.
- Marine:Wild-caught fish skin and scale extraction from Atlantic Canada and Alaska addresses clean-label preferences in prestige cosmetic formulations. Single-point sourcing vulnerability concentrates risk for formulators dependent on halal-certified marine supply.
- Porcine:Skin-derived material offers intermediate Bloom strength ranges for pharmaceutical capsule manufacturers with established supply relationships.
- Poultry:Underdeveloped extraction infrastructure limits commercial scale, though cartilage-derived type II collagen targets joint health supplement positioning.
Volume leadership: Bovine. Steepest expansion trajectory: Marine.
Application:
End-use channels impose divergent specification burdens, from neutral-flavor beverage integration to dermal penetration claims requiring dermatological substantiation.
- Nutritional Supplements:Powder and capsule formats dominate United States direct-to-consumer subscription channels where joint health and skin elasticity positioning drives repurchase rates. FDA New Dietary Ingredient notification requirements compress formulation timelines for novel peptide entrants.
- Food & Beverage:Thermal-stable hydrolyzed grades enable protein fortification in retorted beverages and nutrition bars without viscosity degradation. Institutional procurement through USDA-administered programs anchors volume demand.
- Cosmetics:Marine-sourced peptides with documented dermal fibroblast stimulation support prestige skincare premium pricing in New York and California retail corridors.
- Pharmaceuticals:USP-grade gelatin for hard and soft capsule shells requires extensive BSE-geographic provenance documentation per FDA guidance.
Dominant by revenue: Nutritional Supplements. Gaining share fastest: Cosmetics.
Form:
Delivery format selection balances manufacturing equipment compatibility, consumer convenience preferences, and stability requirements across temperature and humidity ranges.
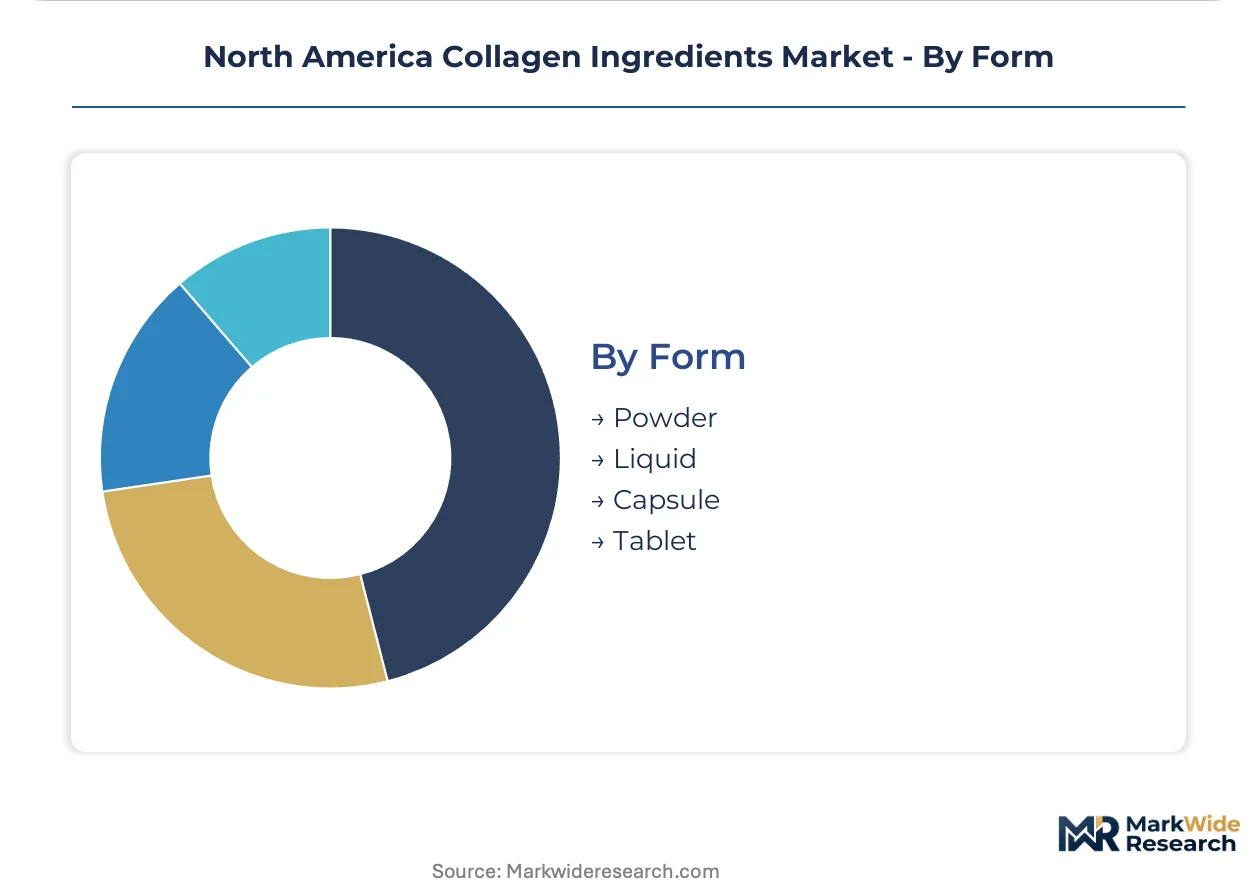
- Powder:Bulk handling efficiency and formulation flexibility favor United States contract manufacturers serving multi-channel brands with shared production lines.
- Liquid:Ready-to-drink positioning in functional beverage channels requires aseptic processing investment and shortened shelf-life management.
- Capsule:Two-piece hard shells and soft gelatin encapsulation dominate pharmaceutical and supplement applications with established USP dissolution standards.
- Tablet:Direct compression and granulation processes accommodate high-volume production with coating options for taste masking and enteric release.
Volume concentration: Powder. Fastest-climbing format: Liquid.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Midwest cattle rendering facilities and Atlantic Canada marine processing plants anchor North American collagen supply geography. Procurement patterns diverge sharply between bovine-dependent gelatin corridors and marine-extraction zones serving clean-label cosmetics.
United States
California functional food startups and New York nutraceutical brands drive peptide demand through direct-to-consumer channels. FDA New Dietary Ingredient notification requirements compress formulation timelines for novel entrants. Midwest rendering clusters in Iowa and Nebraska supply cost-advantaged bovine material to institutional foodservice operators.
Canada
Atlantic Canada wild-caught fish skin extraction serves halal-certified marine collagen demand from prestige cosmetic formulators. Health Canada Natural Health Product licensing timelines frequently misalign with US launch calendars. Quebec gelatin processors leverage established pharmaceutical-grade certification for capsule manufacturers.
Mexico
Baja California underpenetrated production infrastructure offers tariff-advantaged export positioning into US supplement channels. Federal Commission for the Protection against Sanitary Risk (COFEPRIS) registration requirements shape cross-border product entry. Northern border states concentrate contract manufacturing investment for North American brand outsourcing.
North America Collagen Ingredients Market Competitive Landscape
Strategic partnerships dominate the current landscape as peptide suppliers seek fermentation technology access and biotech startups require distribution scale. The vendor base organizes around three archetypes: vertically integrated rendering conglomerates, marine-extraction specialists, and precision fermentation entrants. Tiered positioning separates established dossier libraries from novel peptide challengers facing FDA notification friction. M&A activity and capacity expansion in Mexico represent the dominant competitive moves reshaping supply security.
Among European-headquartered multinationals, GELITA AG and Rousselot occupy positions spanning gelatin expertise and marine collagen extraction capabilities. Darling Ingredients Inc. anchors the North American rendering-integrated tier through captive bovine material supply. These three exemplify the structural divide between commodity-grade volume players and premium peptide positioning specialists.
| Leading Market Players |
|---|
| GELITA AG |
| Darling Ingredients Inc. |
| Nitta Gelatin NA Inc. |
| Rousselot |
| Tessenderlo Group |
| Weishardt |
| Nippi Collagen NA Inc. |
| Regenity |
| Collagen Solutions |
| Others |
Value Network & Pricing Analysis
Bovine hide procurement costs cascade through three pricing tiers as Midwest rendering capacity constraints tighten input availability for gelatin-grade purchasers. Marine collagen extraction from Atlantic Canada and Alaska commands premium positioning in cosmetic applications where halal certification and perceived purity justify elevated price points against commodity bovine alternatives.
Pricing Analysis
Certificate-of-analysis bundling separates peptide suppliers charging premium rates for batch-level molecular weight documentation from unbundled commodity gelatin sellers. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation—USP-grade pharmaceutical gelatin with full BSE-geographic provenance commands top tier, while food-grade hydrolyzed collagen without absorption kinetics data occupies mid-tier positioning. Cost compression in standard-tier bovine material is intensifying because cattle cycle compression and rendering capacity constraints squeeze margins for spot market purchasers. Institutional foodservice operators through USDA-administered programs demonstrate highest price sensitivity due to procurement volume scale and audit economies, while California direct-to-consumer supplement brands show lowest sensitivity given narrative differentiation premiums.
Supply Chain Analysis
Domestic-content mandates under USDA BioPreferred program specifications are reshaping sourcing patterns for fermentation-derived collagen alternatives seeking federal procurement preferences. Supply concentrates in United States Midwest rendering clusters, Atlantic Canada marine processing facilities, and emerging Baja California contract manufacturing zones. Raw material dependencies center on cattle hide and bone rendering outputs, wild-caught fish skin and scale extraction, and recombinant protein fermentation feedstocks. Single-source vulnerability concentrates risk for clean-label formulators dependent on halal-certified marine supply from concentrated Atlantic Canada and Alaska extraction points. Distribution runs through direct sourcing contracts between peptide brands and regenerative ranching operations displacing commodity spot market purchasing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into captive bovine material supply and downstream peptide formulation capabilities is accelerating as suppliers seek margin defense against rendering capacity constraints and FDA notification friction.
For Market Incumbents: Deploy dossier library leverage to compress competitor formulation timelines for novel peptide entrants lacking 1994 grandfather status. Deepen captive supply relationships with single-source cattle operations in Colorado and Oregon for narrative differentiation premiums. Precision fermentation technology access represents the critical defensive lever against biotech startup disruption of traditional animal-derived supply chains. For New Entrants and Emerging Players: Enter via Mexico manufacturing expansion in Baja California underpenetrated production infrastructure offering tariff-advantaged export positioning into US supplement channels. Target cosmeceutical crossover applications bridging ingestible and dermal collagen precursor formulations where topical delivery claims remain underdeveloped. Direct-to-consumer subscription models with origin storytelling provide the most penetrable go-to-market angle against established institutional foodservice incumbents. For Investors and Strategic Acquirers: Distressed-cycle entries favor precision fermentation entrants with halal-kosher-vegan claim simultaneity in Texas and California pilot-scale bioreactor zones. Long-term viability over the projection horizon hinges on technology validation for recombinant collagen proteins achieving cost parity with animal-derived equivalents. Watch FDA draft guidance finalization on animal-derived ingredient traceability as the inflection signal for compliance cost escalation favoring fermentation-derived alternatives.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Decentralizes supply risk from Midwest rendering clusters while enabling simultaneous halal, kosher, and vegan certification claims. |
| Direct Sourcing Contracts | Locks multi-year supply agreements with single-source cattle operations for premium channel narrative differentiation. |
| Mexico Manufacturing Expansion | Positions tariff-advantaged export capacity into US supplement channels from Baja California underpenetrated infrastructure. |
| Clinical Validation Investment | Generates FTC-substantiated absorption kinetics documentation required for premium peptide positioning in California direct-to-consumer brands. |
| Regenerative Ranching Partnerships | Secures lot-level geographic provenance records meeting FDA draft guidance on BSE-mitigation traceability requirements. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs alongside primary interviews with peptide procurement managers at nutraceutical brands, rendering facility operations directors, FDA regulatory affairs consultants, cosmetic formulation chemists, and regenerative ranching supply coordinators. FDA New Dietary Ingredient notification databases, USDA school nutrition program procurement records, Health Canada Natural Health Product licensing filings, and SEC 10-K disclosures from publicly traded rendering conglomerates provided validation layers. Bottom-up volume triangulation across molecular weight grade specifications converged with top-down market sizing through end-use channel expenditure analysis.
Segment-level modeling disaggregated hydrolyzed collagen, collagen peptides, gelatin, and native collagen by molecular weight distribution, thermal stability threshold, and bioavailability documentation requirements. Source-level granularity captured bovine, marine, porcine, and poultry extraction infrastructure capacity by geography. Application-level differentiation tracked nutritional supplements, food and beverage, cosmetics, and pharmaceutical end-use channels with distinct specification burdens. CAGRs derived from logistic adoption curves fitted to historical peptide penetration rates in direct-to-consumer subscription channels, adjusted for FDA notification timeline compression effects on novel entrant revenue recognition.
Forecast precision tightens around the base case; tail outcomes carry wider variance under cattle cycle compression severity, precision fermentation cost parity achievement timing, and FDA traceability guidance finalization stringency. Forecasts reflect assumptions regarding enzymatic hydrolysis yield improvement trajectories and cross-border Health Canada-US synchronization alignment. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Arachidonic Acid Market
Ingredients
Honey Powder Market
Ingredients
Dried Beet Pulp Market
Ingredients
Meat Starter Culture Market
Ingredients
North America Milk Protein Market
Ingredients
Asia-Pacific Soy Protein Market
Ingredients
Global Malt Ingredients Market
Ingredients
North America Bioactive Ingredients Market
Ingredients
Sweet Almond Oil Market
Ingredients
North America Feed Yeast Market
Ingredients
Global Malt and Malt Extracts Market
Ingredients
Vitex Agnus Castus Extract Market
Ingredients
Roll-Dried Starch Market
Ingredients
High Protein Flour Market
Ingredients
Bone and Joint Health Ingredients Market
Ingredients
Global Arabinoxylan Fiber Market