
 Beer Line Cleaning Kit Market | 2026-2036
Beer Line Cleaning Kit Market Size, Share, and Industry Trends Forecast 2026-2036
Beer Line Cleaning Kit Market Outlook
Food-grade certification upgrades is reorganizing procurement priorities across the Beer Line Cleaning Kit Market. Foxx Equipment Company leverages its vertical integration into stainless steel hardware to sustain margin control. Kegco anchors North American distribution through specialized direct-to-brewery channels. Micro Matic USA, Inc. differentiates via proprietary coupling systems that reduce cleaning cycle downtime.
A beer line cleaning kit comprises pumps, brushes, chemical solutions, and fittings engineered to remove organic deposits, biofilm, and mineral scale from draft dispensing systems, typically operating with caustic or acid-based cleaners at temperatures between 80°F and 120°F to restore flow integrity and flavor neutrality. Foam cleaner formulations now capture the fastest expansion within product type segments as operators prioritize low-residue protocols that reduce rinse cycles. Professional users dominate customer type demand, while subscription service delivery modes are gaining traction among multi-location bar groups seeking predictable compliance scheduling.
FDA food code provisions and EPA FIFRA chemical registration requirements govern cleaner composition and labeling across the United States, while the EU REACH framework restricts certain surfactants and preservatives in formulations sold to European hospitality operators. State-level health departments in California and Texas impose additional inspection frequencies that directly influence kit replacement rates. Stakeholders must monitor evolving chemical substance restrictions and assess whether reformulation investments or geographic product segmentation delivers superior returns.
Market Dynamics
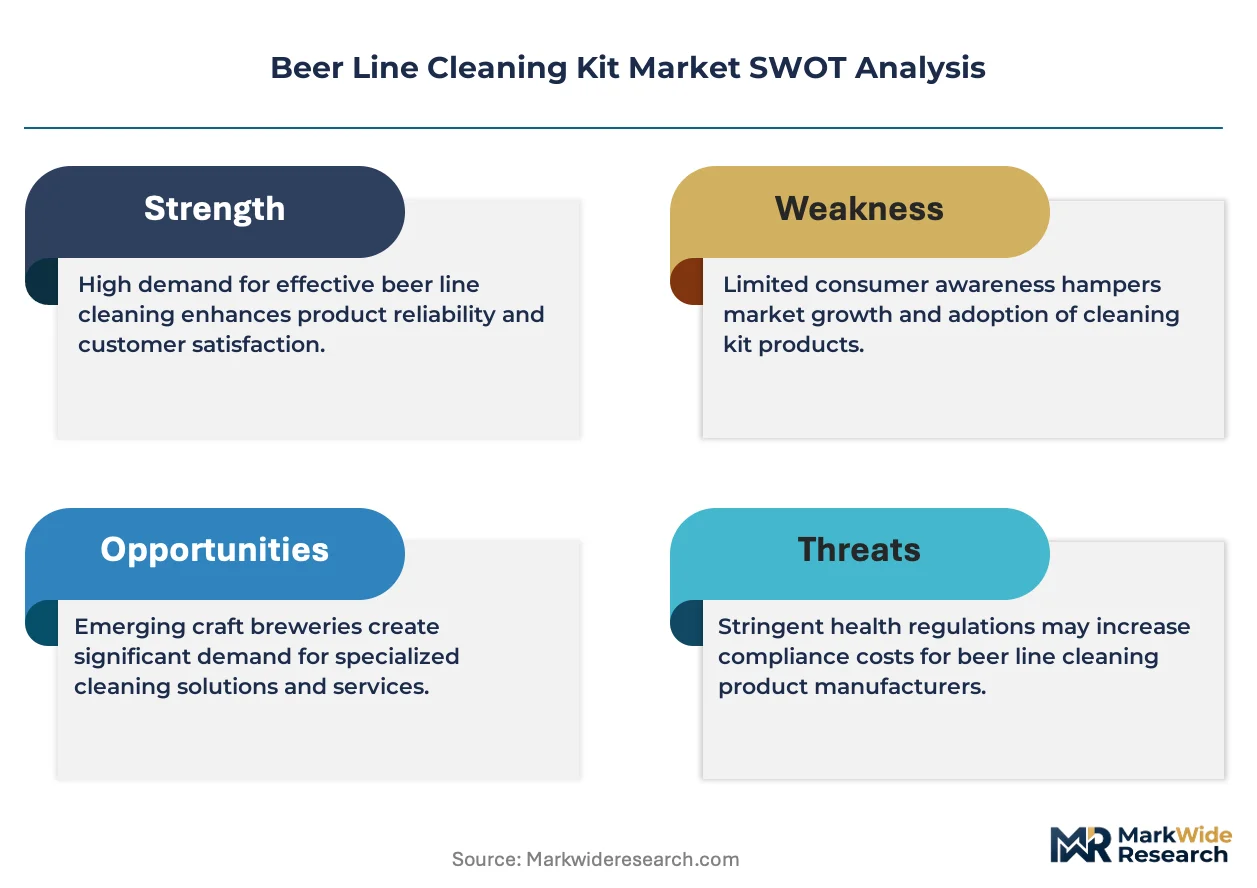
Food-grade certification upgrades is reorganizing procurement priorities across the Beer Line Cleaning Kit Market. Operators now face mandatory compliance deadlines that compress replacement cycles and elevate specification thresholds for chemical formulations and hardware materials.
Growth Catalysts
- REACH framework surfactant restrictions:European hospitality operators must replace legacy cleaners by specified phase-out dates, forcing systematic kit upgrades across Germany, Belgium, and the Netherlands.
- Craft brewery expansion clusters:Pacific Northwest microbreweries are building dedicated draft maintenance programs with weekly cleaning protocols that multiply consumables demand.
- Reinheitsgebot quality culture:Munich and Berlin hospitality clusters sustain rigorous draft standards that mandate frequent line maintenance, creating concentrated replacement demand.
Market Restraints
- Caustic soda price volatility:Input cost swings for sodium hydroxide destabilize chemical solution pricing and squeeze mid-tier kit margins.
- Stainless steel supply concentration:Hardware fabrication depends on concentrated Asian mill supply, exposing lead time risks during trade friction periods.
- EPA FIFRA registration timelines:New chemical formulations face multi-year approval cycles that delay product launches and trap R&D investment.
Strategic Opportunities
- Subscription delivery channels:Multi-location bar groups in Texas and California are adopting scheduled compliance services that lock in recurring revenue streams.
- Foam cleaner technology convergence:Low-residue formulations combined with rapid-connect hardware are reducing rinse cycles and water consumption.
- India FSSAI foodservice expansion:Draft beer penetration in Bangalore and Mumbai hospitality corridors is creating first-mover kit demand as operators build maintenance capabilities.
Industry Challenges
- Certified technician scarcity:Proper line cleaning requires trained personnel familiar with pressure calibration and chemical handling protocols.
- Legacy system integration friction:New quick-connect couplings often require adapter hardware for older draft installations, complicating retrofit sales.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Beer Line Cleaning Kit Market |
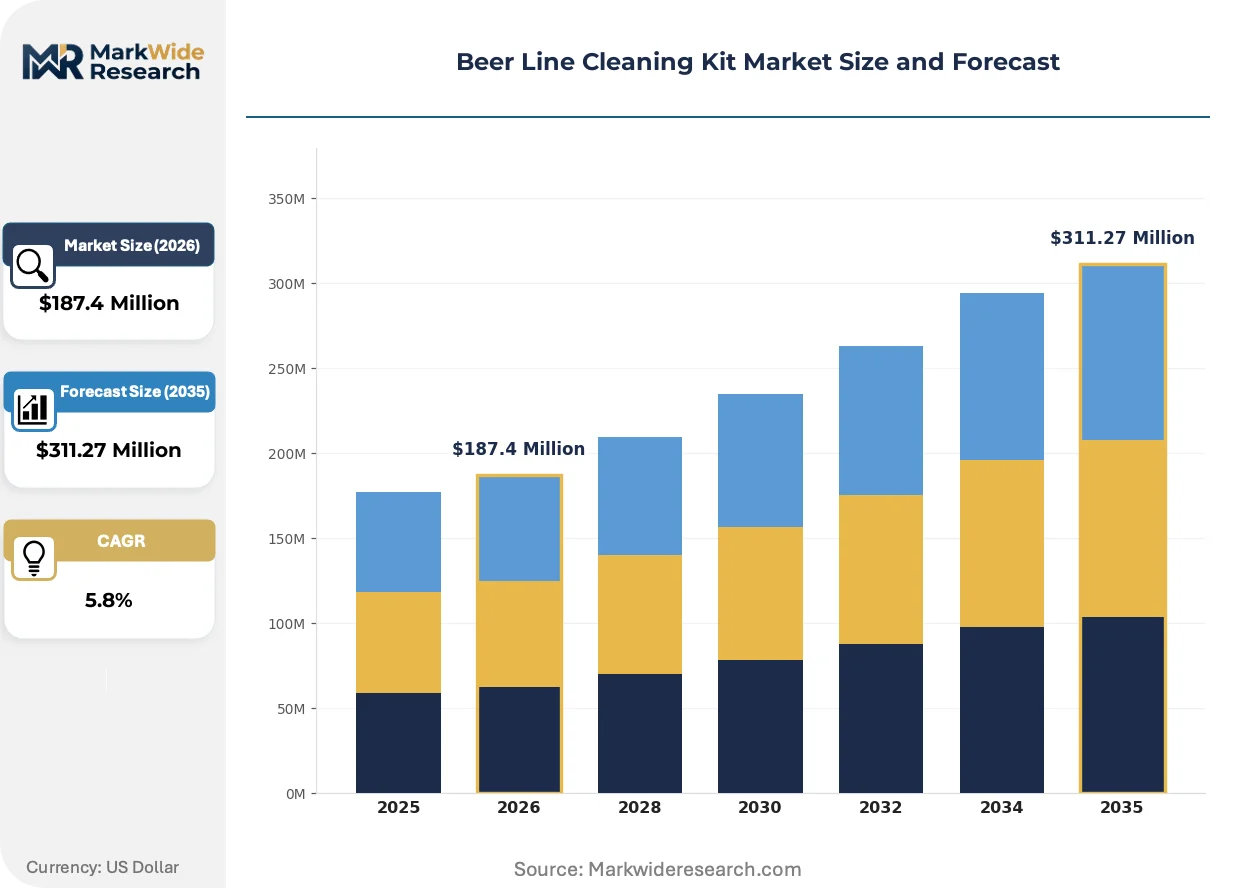
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bulk Cleaner, Foam Cleaner, Tablets, Cleaning Kit Application: Bars, Breweries, Restaurants, Home Brewing Delivery Mode: Direct Supply, Retail Sales, Online Retail, Subscription Service Customer Type: Professional Users, Home Users, Commercial Clients, Industrial Users |
| Companies Covered | Foxx Equipment Company, Beer Tubes, Kegco, UBC Group USA, Perlick Corporation, KegWorks, Rapids Wholesale Equipment, Micro Matic USA, Inc., Krome Dispense Pty Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Beer Line Cleaning Kit Market Strategic Shifts
Active chemistry and hardware interfaces are evolving toward residue-minimizing protocols that reduce operational downtime. Regulatory pressure on chemical composition is accelerating substitution cycles, while procurement centralization among multi-unit operators is reshaping distribution economics.
Foam-based alkaline cleaners is supplanting traditional liquid caustic solutions in high-throughput draft operations. Regional bar chains in California and Texas are adopting these formulations to cut water usage and rinse time. This chemistry shift is compressing the service window between cleaning cycles and enabling same-day operational recovery.
EPA FIFRA registration requirements for antimicrobial claims are tightening label substantiation standards for cleaning solution manufacturers. Formulators must now submit expanded efficacy data, extending product development timelines by twelve to eighteen months. Small-batch chemical suppliers in the Pacific Northwest are responding by narrowing product portfolios to core caustic and acid-based cleaners with established registration pathways.
Centralized procurement by hospitality groups is consolidating vendor relationships and displacing fragmented spot-buying patterns. Multi-location operators in Germany and the United States are negotiating master service agreements that bundle chemical supply with scheduled technical support. This concentration is most visible in Munich's beer hall clusters and Austin's craft bar circuits, where compliance liability has elevated vendor selection criteria above unit pricing.
Beer Line Cleaning Kit Market Segmentation
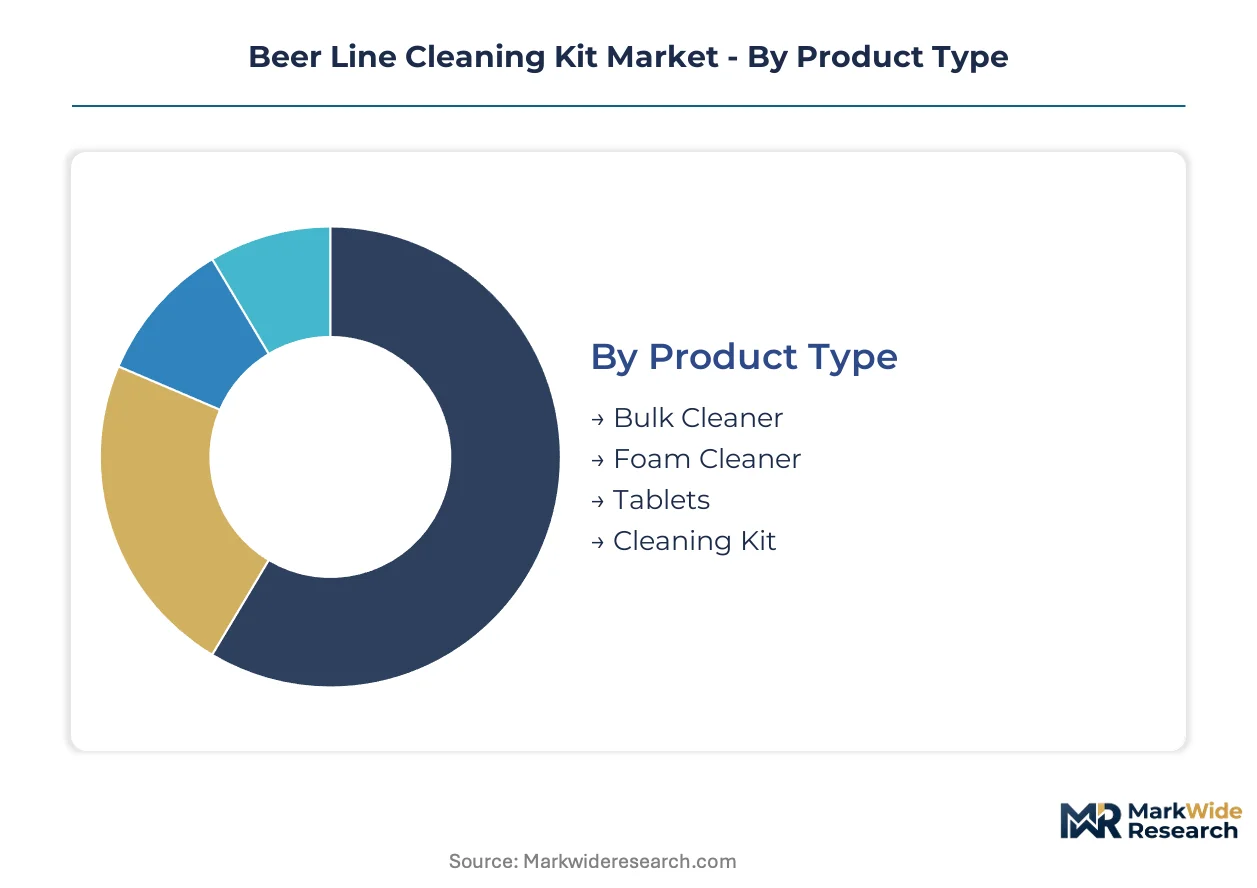
Segmentation in beer line cleaning kits reveals how procurement authority and usage intensity vary across operator types. Product formulation, delivery cadence, and compliance requirements diverge sharply between high-volume hospitality chains and occasional home brewers.
Product Type:
Foam cleaner formulations command the strongest margin expansion as operators prioritize water reduction and cycle compression.
- Foam Cleaner:Low-residue alkaline chemistry expands rapidly across California and Texas bar chains seeking EPA-compliant water conservation. Operators cut rinse cycles by half while maintaining FDA food code sanitation standards.
- Cleaning Kit:Bundled hardware-chemical packages dominate German procurement through Munich and Berlin hospitality clusters adhering to Reinheitsgebot-driven maintenance protocols. Kits integrate pumps, brushes, and calibrated fittings for systematic compliance documentation.
- Bulk Cleaner:Concentrated caustic and acid solutions serve high-throughput breweries in the Pacific Northwest with weekly cleaning mandates.
- Tablets:Pre-measured dissolvable formats reduce handling errors for smaller operators with limited trained technician access.
The dominant share belongs to Cleaning Kit, while Foam Cleaner is closing the gap fastest.
Application:
Volume concentration tracks directly to draft system complexity and regulatory inspection frequency.
- Bars:Multi-tap establishments in Texas and California face state health department inspection schedules that mandate documented weekly cleaning cycles, driving consistent consumables replenishment.
- Breweries:Craft operations in Oregon and Washington build dedicated maintenance programs with in-house technician training, creating captive demand for specialized coupling hardware.
- Restaurants:Foodservice operators with hybrid beverage programs typically outsource line maintenance to third-party service providers.
- Home Brewing:Enthusiast segment purchases sporadically through online retail channels with minimal compliance pressure.
Breweries generate the highest per-site kit consumption, though Bars provide the broadest installed base.
Delivery Mode:
Channel economics shift as multi-location operators consolidate vendor relationships around predictable fulfillment.
- Subscription Service:Scheduled compliance programs lock in recurring revenue from Austin and Dallas bar groups seeking liability protection through documented maintenance records.
- Direct Supply:Brewery-to-manufacturer relationships dominate German procurement, with Munich beer halls negotiating master service agreements bundling chemicals with technical support.
- Online Retail:Home brewers and small operators source tablets and compact kits through specialized e-commerce platforms.
- Retail Sales:Distributor counter sales serve emergency replacement needs for independent bars with spot-buying patterns.
Subscription Service is expanding most quickly, though Direct Supply retains the largest revenue concentration.
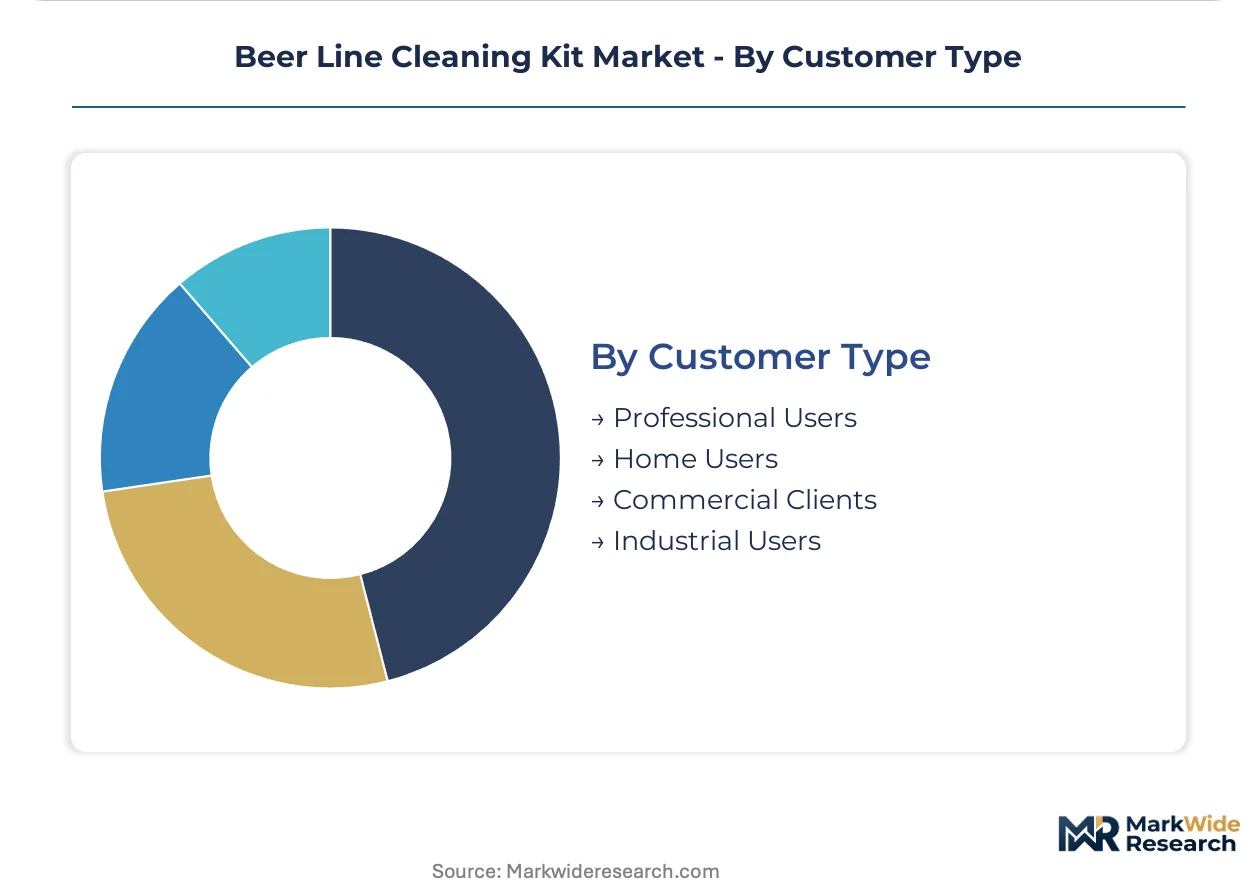
Customer Type:
Specification authority and price sensitivity separate institutional buyers from discretionary purchasers.
- Professional Users:Trained technicians in commercial bars and breweries demand food-grade certified hardware with pressure-calibrated pumps, accepting premium pricing for compliance assurance.
- Commercial Clients:Multi-location hospitality groups centralize procurement through negotiated frameworks, prioritizing vendor reliability over unit cost.
- Industrial Users:Large-scale brewing facilities integrate cleaning systems into automated CIP infrastructure with specialized chemical formulations.
- Home Users:Occasional brewers purchase basic tablet formats with minimal technical support requirements.
Professional Users anchor market value, while Commercial Clients are consolidating purchasing fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in beer line cleaning kits tilt toward net-import dependence in emerging hospitality markets, while established brewing economies sustain trade surpluses in specialized hardware. Germany and the United States anchor outbound shipment volumes through integrated manufacturing bases, whereas India and Brazil absorb inbound flows as draft infrastructure expands.
United States
State health departments in California and Texas enforce inspection frequencies that accelerate kit replacement cycles. EPA FIFRA registration requirements govern antimicrobial cleaner claims, extending product development timelines for domestic formulators. Austin's craft bar circuits and Portland's brewery clusters are consolidating procurement through master service agreements that bundle chemicals with technical support.
Germany
Reinheitsgebot tradition sustains rigorous draft quality standards across Munich and Berlin hospitality clusters, mandating frequent line maintenance. ECHA REACH framework restrictions on surfactants and preservatives force systematic cleaner reformulation by specified phase-out dates. Bavarian beer halls negotiate direct supply relationships with hardware fabricators, bypassing distributor markups for stainless steel pump assemblies.
India
Draft beer penetration in Bangalore and Mumbai hospitality corridors creates first-mover kit demand as operators build maintenance capabilities. FSSAI foodservice expansion guidelines impose sanitation documentation requirements that elevate specification thresholds for imported hardware. Maharashtra and Karnataka microbreweries are sourcing calibrated cleaning pumps through specialized direct-to-brewery channels to meet weekly protocol mandates.
Australia
Independent craft breweries in Victoria and New South Wales are adopting subscription delivery models for compliance scheduling. The country's national food safety regulator enforces draft system inspection standards that mirror FDA food code provisions. Melbourne's bar clusters are consolidating vendor relationships around scheduled foam cleaner replenishment to reduce water consumption.
Brazil
São Paulo and Rio de Janeiro hospitality operators are importing complete kit bundles as domestic chemical formulation capacity remains limited. ANVISA pharmaceutical and sanitation oversight extends to foodservice chemical registration, creating approval bottlenecks for new market entrants. Minas Gerais craft brewing expansion is driving spot demand for portable pump systems until localized supply chains mature.
Beer Line Cleaning Kit Market Competitive Environment
Concentration sits with vertically integrated hardware specialists and regional chemical formulators rather than diversified industrial conglomerates. The vendor base stratifies across three tiers: stainless steel fabricators controlling captive component supply, formulation houses with established EPA or REACH registration pathways, and assembly distributors sourcing white-label hardware. Competitive positioning depends on backward integration into pump machining, surfactant synthesis, or exclusive coupling system patents. M&A activity targets regional distributors with established brewery relationships, while technology licensing agreements accelerate foam cleaner formulation access.
Among North American equipment fabricators, Foxx Equipment Company, Kegco, and Micro Matic USA, Inc. occupy positions reflecting distinct strategic archetypes. Foxx Equipment Company exemplifies the vertically integrated model through in-house stainless steel hardware production. Kegco anchors distribution architecture through specialized direct-to-brewery channels. Micro Matic USA, Inc. represents the technology differentiation path with proprietary coupling systems. These three illustrate how competitive advantage fragments across supply chain control, channel access, and interface engineering rather than consolidating around scale alone.
| Leading Market Players |
|---|
| Foxx Equipment Company |
| Beer Tubes |
| Kegco |
| UBC Group USA |
| Perlick Corporation |
| KegWorks |
| Rapids Wholesale Equipment |
| Micro Matic USA, Inc. |
| Krome Dispense Pty Ltd |
| Others |
Value Chain & Pricing Dynamics
EPA FIFRA registration requirements gate both supply qualification and price differentiation simultaneously, as manufacturers without approved antimicrobial claims cannot access premium positioning while compliant formulators extract certification premiums from liability-conscious hospitality operators.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation hinges on food-grade certification tier and after-sales service bundling. Pricing pressure stems from caustic soda input volatility squeezing mid-tier margins. Home brewers exhibit highest price sensitivity, while multi-location bar groups prioritize compliance assurance over unit cost.
Supply Chain Analysis
Container availability constraints on trans-Pacific trade lanes elevate inbound logistics costs for stainless steel pump assemblies. Hardware fabrication draws from concentrated mill supply in China, South Korea, and Taiwan. Caustic soda and specialized surfactants constitute critical chemical inputs. Single-source vulnerability in Asian stainless steel supply exposes lead time risks. Distribution runs through direct-to-brewery channels and specialized distributor networks serving emergency replacement demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a defensive-moat story anchored in regulatory entrenchment, where EPA FIFRA and REACH compliance timelines create switching costs that lock in incumbent relationships and deter rapid competitive displacement.
For Market Incumbents: Shield market position by deepening backward integration into surfactant synthesis to offset caustic soda volatility, while accelerating foam cleaner R&D to defend against emerging low-residue formulation specialists. Certification investment remains the critical lever against price-based challengers.
For New Entrants and Emerging Players: Lead with subscription service models targeting Texas and California multi-location bar groups, where compliance liability anxiety outstrips brand loyalty. India FSSAI-mandated documentation requirements create the most penetrable white-space for first-mover hardware suppliers.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across foam cleaner formulation capacity as EPA registration timelines extend R&D investment horizons. Acquisition targets should display established registration pathways and captive brewery relationships. Watch REACH surfactant phase-out deadlines as inflection signals for replacement cycle acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Surfactant Synthesis | Captive chemical supply insulates margin from caustic soda volatility and REACH reformulation cycles. |
| Foam Cleaner Technology Licensing | Rapid-access to low-residue formulations compresses product development timelines for regional formulators. |
| Subscription Service Launch | Recurring revenue locks in multi-location bar groups across Austin and Dallas compliance corridors. |
| Direct-to-Brewery Channel Expansion | Bypasses distributor markups in Munich and Portland clusters while capturing maintenance protocol specification authority. |
| India FSSAI Registration Pathway Investment | First-mover positioning in Bangalore and Mumbai hospitality corridors as draft infrastructure matures. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of EPA FIFRA registration databases, ECHA REACH substance restrictions, customs trade flow records, and hospitality operator procurement disclosures. Interviews with brewery maintenance directors, chemical formulation technical leads, distributor channel managers, and state health department inspectors informed demand-side validation. Bottom-up kit shipment analysis triangulates against top-down hospitality sector spend estimates.
Segmentation dimensions modeled span product formulation chemistry, application venue type, delivery mode cadence, and customer specification authority across the analysis window. CAGRs derive from fitted growth curves applied to disclosed replacement cycle frequencies and regulatory compliance deadline impacts. Forecast inputs incorporate REACH surfactant phase-out schedules and state-level inspection frequency mandates.
The analysis sits within stated boundaries; outcomes outside EPA registration timeline assumptions or stainless steel supply stability would require recalibration. Forecasts reflect documented compliance-driven replacement patterns and hospitality sector expansion trajectories. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Premixed Margarita Market
Alcoholic Beverages
Mezcal Market
Alcoholic Beverages
Vodka Seltzer Market
Alcoholic Beverages
Light-Flavor Liquor Market
Alcoholic Beverages
Balsam Bottle Market
Alcoholic Beverages
Saffron Beer Market
Alcoholic Beverages
Stout Market
Alcoholic Beverages
Dark Beer Market
Alcoholic Beverages
Distilled Spirits Market
Alcoholic Beverages
Bayberry Wine Market
Alcoholic Beverages
Beer Keg System Market
Alcoholic Beverages
Gluten Free Alcoholic Drinks Market
Alcoholic Beverages
Global Brewery Filtration Market
Alcoholic Beverages
Organic Beer Market
Alcoholic Beverages
Wine Glass Market
Alcoholic Beverages
Alcoholic Ice Cream Market