
 Oak Barrel Alternatives Market | 2026-2036
Oak Barrel Alternatives Market Size, Share, and Industry Trends Forecast 2026-2036
Oak Barrel Alternatives Market Insights
France is tilting toward expanded oak-alternative manufacturing as native cooperage capacity strains under export pressure. Bouchard Cooperages leverages generational stave-sourcing relationships to sustain premium positioning in Burgundy. Seguin Moreau Napa Cooperage anchors North American demand through California-based production of hybrid barrel systems. Gusmer Enterprises, Inc. competes on scalable infusion and tank-based aging technologies for mid-market wineries.
Oak barrel alternatives encompass engineered vessels and inserts that replicate lignin, vanillin, and tannin extraction from traditional cooperage without full barrel construction, typically using toasted oak staves, chips, spirals, or proprietary diffusion surfaces bonded within stainless steel or neutral containers. These systems target beverage producers seeking controlled extraction rates, reduced angel's share losses, and shorter aging cycles. Wood alternatives dominate current volume as established cooperages extend stave-based product lines, while stainless steel systems with integrated oak elements capture the fastest expansion in commercial-scale whisky and wine operations. Small-scale craft producers concentrate demand in the home-use and boutique winery segments, where batch flexibility outweighs capital intensity.
FDA and TTB oversight in the United States governs aging claims and additive disclosures for spirits, while EFSA and CE marking frameworks in Europe regulate food-contact materials and extraction safety thresholds for wine and spirits applications. REACH compliance shapes material sourcing for synthetic and polymer-based alternatives entering European markets. Producers must monitor evolving oak-origin certification requirements and traceability mandates as regulators tighten supply-chain documentation for aged beverage categories.
Market Dynamics
French cooperage capacity constraints are redirecting Cognac and Bordeaux producers toward stainless steel systems with integrated oak elements, compressing traditional barrel procurement cycles and accelerating alternative technology validation.
Growth Catalysts
- TTB disclosure tightening:FDA and TTB guidelines on spirit aging disclosures are forcing material traceability upgrades across Kentucky and Tennessee distilleries, driving documented demand for engineered stave systems with batch-level extraction data.
- Angel's share mitigation:Stainless steel vessels with bonded oak diffusion surfaces eliminate evaporative losses in high-value whisky maturation, delivering measurable yield retention for commercial-scale bourbon operations.
- Burgundy stave sourcing networks:Generational supplier relationships in French oak forests are being repurposed to supply precision-toasted stave inserts rather than full cooperage, extending premium wood access to tank-based systems.
Market Restraints
- French oak supply concentration:Native cooperage capacity strains under export pressure concentrate premium stave sourcing in limited Allier and Vosges forest zones, creating input bottlenecks for alternative manufacturers.
- REACH compliance costs:ECHA registration requirements for synthetic and polymer-based aging surfaces impose documentation burdens that disadvantage smaller European alternative producers against established wood suppliers.
- Sensory equivalence skepticism:Master distillers and enologists in traditional appellations resist tank-based systems due to perceived micro-oxygenation deficits versus barrel breathing, slowing adoption in protected-origin categories.
Strategic Opportunities
- California hybrid production:North American cooperage operations with California manufacturing bases can capture distressed demand from French supply constraints by scaling domestic stave-toasting and tank-assembly capacity.
- CE marking acceleration:EFSA food-contact material approvals for novel oak-extraction surfaces create regulatory tailwinds for European-engineered diffusion technologies entering spirits applications.
- Craft distillery channel expansion:Small-batch producers in emerging American whiskey regions seek rental and lease-based tank systems, opening subscription-model revenue streams absent in traditional barrel sales.
Industry Challenges
- Cooperage-to-engineering talent migration:Tank system manufacturers compete for scarce process engineers with beverage extraction science expertise, slowing product development cycles against entrenched barrel makers.
- Legacy integration complexity:Stainless steel alternatives require reconfiguration of existing rickhouse infrastructure and humidity-control systems, raising retrofit capital requirements for established distilleries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oak Barrel Alternatives Market |
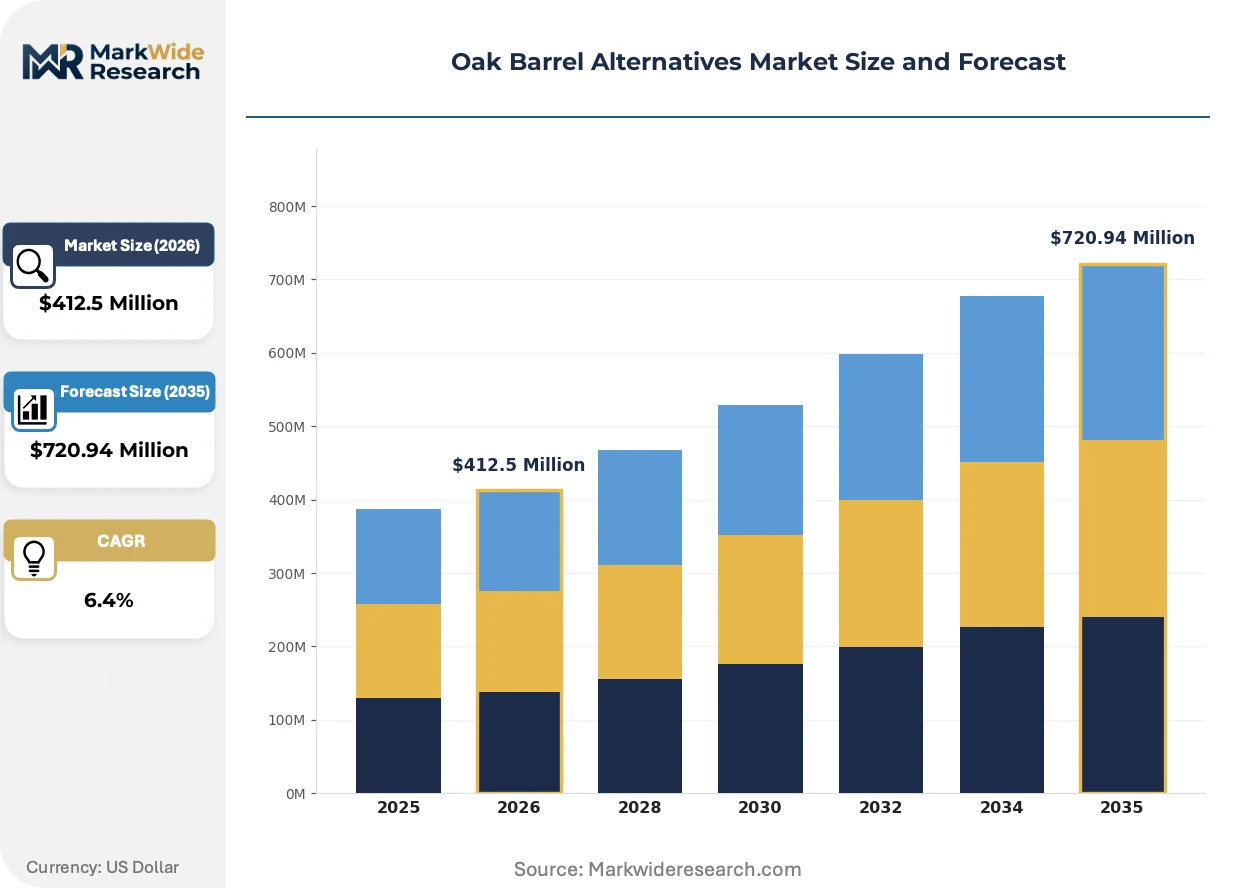
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $720.94 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Stainless Steel, Glass, Synthetic, Wood Alternatives End Use: Wine Making, Whisky Production, Beverage Aging, Culinary Applications Size: Small Scale, Commercial, Industrial, Home Use Application: Aging, Fermentation, Storage, Batch Processing |
| Companies Covered | Suber Oak International, Bouchard Cooperages, Seguin Moreau Napa Cooperage, Gusmer Enterprises, Inc., Innerstave, The Barrel Mill, Protéa France, Canadell SAS, StaVin Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oak Barrel Alternatives Market Trends and Innovations
Controlled extraction technologies are compressing maturation timelines while regulatory documentation requirements reshape supplier qualification protocols across spirits and wine categories.
Precision-toasted oak spirals with programmable rotation mechanisms are rendering obsolete static stave configurations in large-volume tanks. Tennessee and Kentucky bourbon distillers are deploying these systems at commercial scale to compress vanillin and tannin release curves from months to weeks. The technology is rendering obsolete the traditional rickhouse aging model for mid-tier expressions, forcing cooperages to defend premium positioning through origin-certified full-barrel offerings.
REACH substance-of-very-high-concern screening is extending to oak-treatment chemicals and binding agents used in composite stave manufacturing. European alternative producers must now submit full supply-chain dossiers for CE marking renewal, elevating compliance costs for synthetic diffusion surfaces. Wine cooperatives in Bordeaux are responding by demanding Forest Stewardship Council chain-of-custody documentation from all stave suppliers, regardless of barrel or tank destination.
Direct-procurement contracts between distillery technical teams and tank-system engineers are displacing traditional cooperage distributor relationships. Large bourbon producers in Kentucky now specify extraction-rate curves and lignin-release profiles in purchase agreements, transferring specification authority from purchasing to production chemistry functions. This pattern is most visible in American whiskey operations with dedicated innovation labs, where batch-scale experimentation precedes commercial tank deployment.
Oak Barrel Alternatives Market Segmentation
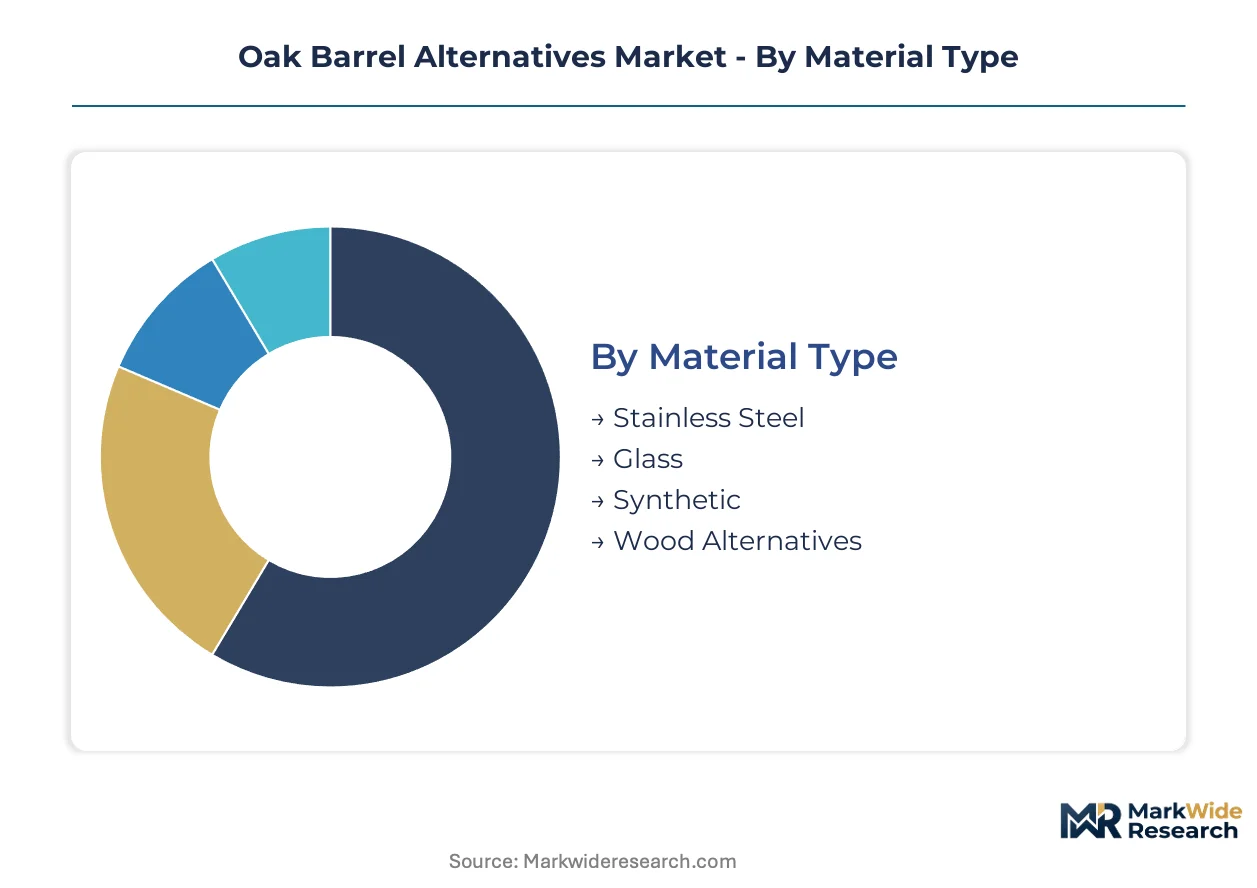
Segmentation in oak barrel alternatives reveals how producers balance extraction precision against capital efficiency. Material composition dictates regulatory pathways, while end-use applications determine oxygenation requirements and batch-scale economics.
Material Type:
The use-case spectrum spans from premium spirit producers seeking micro-oxygenation control to cost-sensitive wineries prioritizing yield retention over traditional barrel aesthetics.
- Stainless Steel:Bonded diffusion surfaces enable programmable extraction curves with zero evaporative loss. Kentucky bourbon distillers deploy these systems at commercial scale to compress vanillin release timelines while satisfying TTB traceability mandates.
- Wood Alternatives:Precision-toasted staves, chips, and spirals replicate lignin and tannin extraction without full cooperage construction. French cooperages in Allier and Vosges redirect generational sourcing relationships toward tank-insert production as native barrel capacity strains.
- Glass:Neutral vessels suit small-batch experimentation and visual monitoring of extraction progression. Home-use and boutique winery segments favor glass for batch flexibility despite limited oxygen permeability.
- Synthetic:Polymer-based diffusion surfaces target cost-sensitive fermentation applications. REACH compliance costs disadvantage smaller European producers against established wood suppliers.
Established volume favors wood alternatives; emerging adoption favors stainless steel.
End Use:
Cost tier stratification separates heritage-protected appellations from commercial-scale operations seeking yield optimization.
- Wine Making:Bordeaux and Burgundy producers balance tradition against supply constraints. Tank-based systems with Forest Stewardship Council-certified staves gain traction in cooperative wineries facing French oak shortages.
- Whisky Production:Tennessee and Kentucky distillers scale stainless steel deployments to mitigate angel's share losses in high-value maturation. Direct procurement contracts now specify extraction-rate curves and lignin-release profiles.
- Beverage Aging:Cross-category applications include brandy, rum, and emerging spirits. CE marking acceleration for novel oak-extraction surfaces creates regulatory tailwinds for European-engineered diffusion technologies.
- Culinary Applications:Barrel-aged condiments and specialty food producers adopt small-scale stave inserts. FDA food-contact material oversight governs extraction safety thresholds.
Heritage-protected categories favor traditional cooperage; commercial-scale operations favor engineered alternatives.
Size:
Customer type fragmentation separates capital-intensive industrial deployments from flexible rental-based craft solutions.
- Commercial:Mid-tier wineries and regional distilleries seek documented extraction data for regulatory compliance. Subscription-model tank rentals are displacing outright barrel purchases.
- Industrial:Large-volume producers specify integrated humidity-control systems and rickhouse reconfiguration protocols. Procurement authority has shifted from purchasing departments to production chemistry functions.
- Small Scale:Craft distilleries in emerging American whiskey regions prioritize batch experimentation over standardization. Lease-based systems reduce capital intensity for innovation-lab workflows.
- Home Use:Enthusiast segments drive demand for compact stave kits and portable aging vessels. E-commerce distribution concentrates in North American and European hobbyist markets.
Industrial scale dominates revenue concentration; small scale climbs fastest on craft channel expansion.
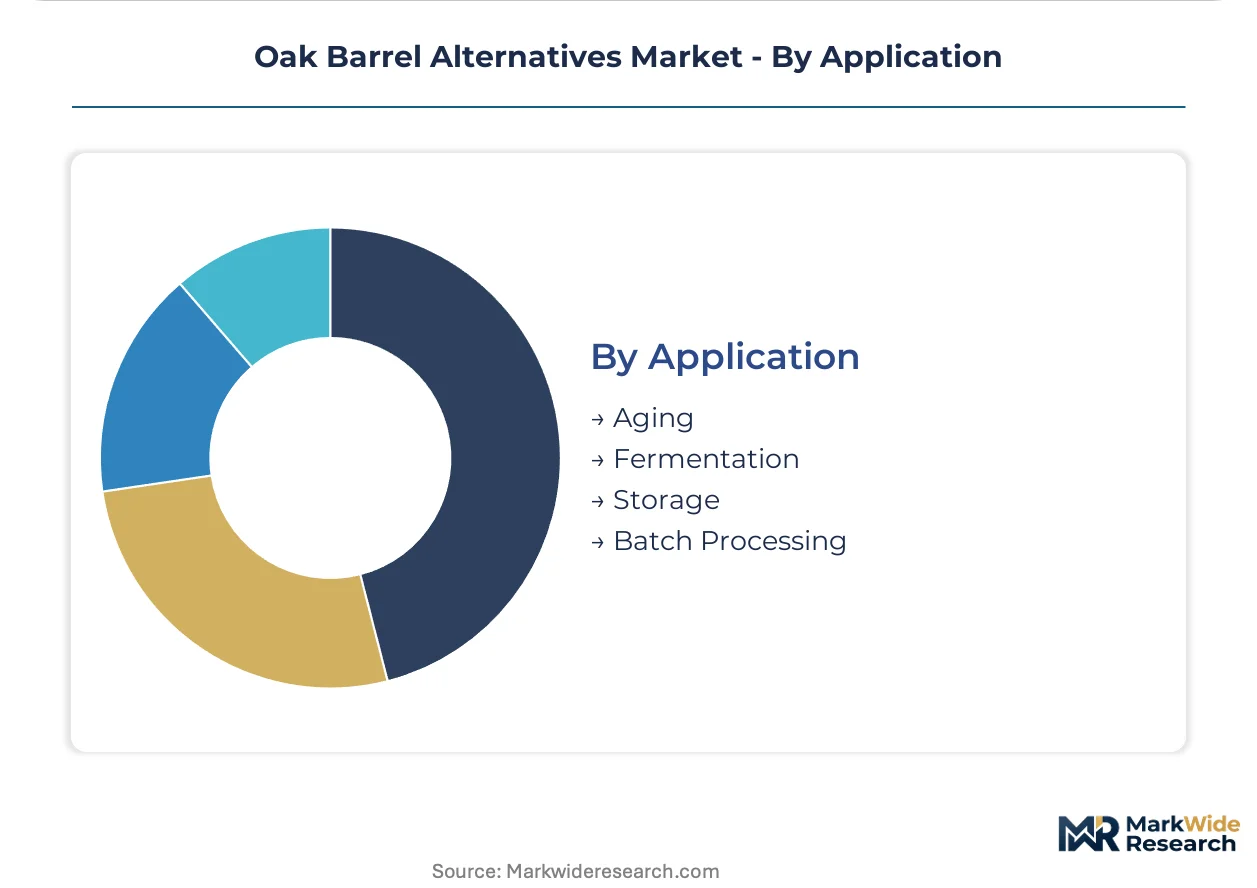
Application:
Maturity differentiation separates validated aging protocols from emerging fermentation and storage functionalities.
- Aging:Controlled extraction technologies compress maturation timelines from months to weeks. Precision-toasted spirals with programmable rotation mechanisms are rendering obsolete static stave configurations.
- Fermentation:Synthetic and hybrid surfaces target primary fermentation with integrated oak influence. EFSA food-contact approvals govern European deployment.
- Storage:Neutral vessels with optional stave inserts provide inventory flexibility. Stainless steel dominates where oxidation control outweighs extraction requirements.
- Batch Processing:Rapid turnaround systems serve contract producers and innovation labs. Extraction-rate programmability enables SKU proliferation without proportional barrel inventory expansion.
Validated aging applications anchor current revenue; fermentation integration represents steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France deploys oak alternatives primarily for Cognac and Bordeaux production under supply constraints, while the United States scales stainless steel systems for bourbon yield optimization—revealing a fundamental geographic split between tradition-preserving and efficiency-maximizing adoption patterns.
United States
Kentucky and Tennessee distilleries drive commercial-scale stainless steel deployments to compress vanillin extraction timelines and eliminate angel's share losses. TTB disclosure tightening on spirit aging claims forces material traceability upgrades across bourbon operations. Technical procurement teams in Louisville and Nashville now specify extraction-rate curves directly with tank-system engineers, bypassing traditional cooperage distributors.
France
Cognac and Bordeaux producers redirect generational stave-sourcing relationships from full cooperage toward tank-insert production as native barrel capacity strains under export pressure. EFSA food-contact material approvals and REACH compliance govern oak-treatment chemical disclosures for alternative systems. Allier and Vosges forest zones concentrate premium stave sourcing for engineered diffusion technologies.
Italy
Tuscan and Piedmont wineries balance DOCG tradition against cooperative-level cost pressures, accelerating adoption of Forest Stewardship Council-certified stave inserts in bulk wine operations. CE marking requirements for novel extraction surfaces create regulatory tailwinds for European-engineered tank systems. Chianti Classico consortium members pilot programmable rotation mechanisms for precision-toasted spirals.
Spain
Rioja and Ribera del Duero bodegas integrate hybrid barrel systems to manage oak inventory volatility amid French supply bottlenecks. ECHA substance-of-very-high-concern screening extends to binding agents in composite stave manufacturing, elevating documentation burdens. Basque Country cooperatives demand chain-of-custody certification from all stave suppliers regardless of final vessel configuration.
Australia
Barossa Valley and McLaren Vale producers adopt small-scale stainless steel systems for batch experimentation and rapid SKU proliferation without proportional barrel inventory expansion. TGA-equivalent state-level food-contact oversight governs extraction safety thresholds for wine applications. Melbourne-based technical teams specify integrated humidity-control protocols for rickhouse retrofits.
Oak Barrel Alternatives Market Competitive Landscape
Capability concentration sits with heritage cooperages possessing generational stave-sourcing networks; scale advantage sits with engineering-led tank-system fabricators offering programmable extraction technologies. The market structures around three archetypes: French forest-zone cooperages repurposing sourcing relationships, North American hybrid manufacturers with California production bases, and infusion-technology specialists serving mid-market wineries. Competitive moves center on direct-procurement contract displacement of traditional distribution channels and capacity expansion in domestic stave-toasting operations.
Among French heritage cooperages, Bouchard Cooperages and Seguin Moreau Napa Cooperage exemplify the capability-concentrated tier leveraging generational supplier relationships. Gusmer Enterprises, Inc. occupies a position within the scale-driven engineering segment focused on tank-based aging technologies. These three anchors illustrate the market's fundamental bifurcation between origin-certified wood sourcing and programmable extraction system fabrication.
| Leading Market Players |
|---|
| Suber Oak International |
| Bouchard Cooperages |
| Seguin Moreau Napa Cooperage |
| Gusmer Enterprises, Inc. |
| Innerstave |
| The Barrel Mill |
| Protéa France |
| Canadell SAS |
| StaVin Inc. |
| Others |
Pricing and Supply Chain Analysis
Allier and Vosges forest zones in France anchor premium stave sourcing for engineered diffusion technologies, concentrating input bargaining power among heritage cooperages and compressing margins for tank-system fabricators dependent on spot-market French oak procurement.
Pricing Analysis
Long-term offtake agreements dominate premium-tier transactions as Kentucky bourbon distillers lock in multi-year extraction-surface contracts to satisfy TTB traceability mandates. Three-tier pricing structure across premium, standard, and economy levels separates Forest Stewardship Council-certified origin staves from generic tank inserts and synthetic diffusion surfaces. Cost compression in mid-market stainless steel systems is intensifying because REACH compliance documentation burdens disadvantage smaller European producers. Craft distillery segments exhibit highest price sensitivity, while industrial-scale bourbon operations prioritize yield retention metrics over unit cost.
Supply Chain Analysis
Upstream feedstock flows from French Allier and Vosges forests, American Appalachian cooperages, and Spanish Galician oak zones into precision-toasting operations. Raw material dependencies center on quarter-sawn white oak staves, food-grade stainless steel sheet, and programmable rotation mechanism components. Single-source vulnerability concentrates in generational French forest-zone supplier relationships that tank-system manufacturers cannot replicate. Distribution runs through direct-procurement contracts between distillery technical teams and tank-system engineers, bypassing traditional cooperage distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in cyclical recovery as French cooperage capacity constraints force Cognac and Bordeaux producers toward alternative systems, creating sustained demand displacement from traditional barrel procurement.
For Market Incumbents: Harden generational stave-sourcing relationships through exclusive forest-zone procurement contracts that block tank-system competitors from premium French oak access. Invest in CE marking acceleration for novel extraction surfaces to defend against REACH-compliant European engineering entrants. Prioritize backward integration into precision-toasting operations in California to capture distressed North American demand.
For New Entrants and Emerging Players: Build out subscription-model tank rental services targeting craft distilleries in emerging American whiskey regions, where capital intensity barriers exclude outright purchase. Focus on small-scale stainless steel systems for batch experimentation workflows. Pursue direct technical sales to distillery innovation labs rather than competing through traditional cooperage distribution channels.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among tank-system fabricators offering lease-based aging solutions with integrated service contracts. Long-term viability favors engineering-led manufacturers with programmable extraction technologies over heritage cooperages facing raw material constraints. Monitor TTB disclosure rulemaking timelines as inflection indicators for documented extraction-data demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Stave-Toasting Operations | California-based precision-toasting capacity captures French supply-constrained demand from distressed Cognac and Bordeaux producers. |
| CE Marking Acceleration for Novel Extraction Surfaces | EFSA food-contact approvals create regulatory tailwinds for European-engineered diffusion technologies entering spirits applications. |
| Direct-Procurement Contract Displacement | Kentucky bourbon technical teams now specify extraction-rate curves directly with tank-system engineers, bypassing cooperage distributors. |
| Subscription-Model Tank Rental Expansion | Craft distilleries in emerging American whiskey regions seek lease-based systems to reduce capital intensity for innovation workflows. |
| Forest Stewardship Council Chain-of-Custody Certification | Bordeaux cooperatives demand documented oak-origin traceability from all stave suppliers regardless of barrel or tank destination. |
Research Methodology
A standing panel of distillery production chemists, cooperage technical directors, tank-system engineers, and TTB regulatory specialists provided ongoing calibration across the research cycle. Primary interviews with Kentucky bourbon innovation lab heads and French Cognac cellar masters combined with secondary validation from FDA guidance documents, EFSA food-contact material approvals, TTB labeling regulations, and Forest Stewardship Council chain-of-custody databases. Bottom-up unit economics from tank-system deployments triangulated against top-down value estimates from cooperage revenue disclosures.
Scenario-bracketing framed low, base, and high cases across the projection horizon without fixed-year anchoring. Segmentation dimensions modeled include material type, end-use application, operational scale tier, and geographic regulatory cluster. CAGRs derived from fitted growth curves applied to validated base-year estimates. Industry-specific forecast inputs incorporated angel's share mitigation valuations and REACH compliance cost trajectories for synthetic diffusion surfaces.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by California-based hybrid manufacturers or accelerated TTB disclosure mandates would shift outcomes beyond modeled ranges. Cross-checking against distillery capital expenditure disclosures and cooperage order backlogs is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Nitro Cocktails Market
Alcoholic Beverages
N-Hexyl Alcohol Market
Alcoholic Beverages
Beer Pasteurization Equipment Market
Alcoholic Beverages
Wine Production Machinery Market
Alcoholic Beverages
Global Brewery Filtration Market
Alcoholic Beverages
CBD Wine Market
Alcoholic Beverages
Alcoholic Drinks Market
Alcoholic Beverages
Europe Craft Beer Market
Alcoholic Beverages
Organic Beer Market
Alcoholic Beverages
Mexico Tequila Market
Alcoholic Beverages
Gluten-Free Beer Market
Alcoholic Beverages
Pressurized Wine Filter System Market
Alcoholic Beverages
Asia-Pacific Craft Beer Market
Alcoholic Beverages
Craft Spirits Market
Alcoholic Beverages
Mexico Alcohol E-Commerce Market
Alcoholic Beverages
Port Wine Market