
 Liquid Caramel Color Market | 2026-2036
Liquid Caramel Color Market Size, Share, and Industry Trends Forecast 2026-2036
Liquid Caramel Color Market Insights
Consolidation among multinational beverage manufacturers is recalibrating procurement volumes and supplier qualification criteria across the liquid caramel color value chain. Sethness Caramel Products Company leverages its century-long specialization in burnt sugar chemistry to sustain premium positioning with North American cola and beer producers. Sensient Technologies Corporation anchors global supply security through vertically integrated extraction and blending operations across multiple continents. DDW The Color House differentiates via customized emulsion stability solutions for acidified beverage systems where competitive suppliers struggle with shelf-life performance.
Liquid caramel color comprises heat-treated carbohydrates—typically glucose, fructose, or sucrose—reacted with catalysts under controlled temperature and pressure to produce water-soluble brown pigments with specific tinctorial power ranging from 0.10 to 0.60 absorbance units. These colorants serve primarily to impart consistent visual appeal in beverages, confectionery, and savory applications where consumer acceptance hinges on predictable hue intensity and stability under thermal processing. Natural caramel color variants command widening specification premiums as beverage manufacturers reformulate away from synthetic alternatives, while Caramel Color IV dominates high-volume cola production due to its superior acid stability and negative charge characteristics that prevent flocculation in phosphoric acid environments. The bakery application segment exhibits concentrated margin pools tied to heat-stable Class III pigments that withstand oven temperatures without Maillard browning deviation.
EFSA maintains active re-evaluation protocols for 4-MEI and 2-MEI contaminants in caramel color classes, directly constraining manufacturing process parameters and maximum permissible concentrations in EU-bound shipments. The FDA's GRAS designation for caramel color under 21 CFR 73.85 permits broader formulation flexibility in US markets, though California Proposition 65 warning requirements for 4-MEI exposure create state-level compliance fragmentation. India's FSSAI enforces mandatory INS 150 labeling and maximum usage levels across processed food categories, shaping local production investments and import substitution dynamics. Stakeholders must monitor evolving contaminant thresholds across jurisdictions while aligning R&D spending with natural-class process innovations that preempt regulatory tightening.
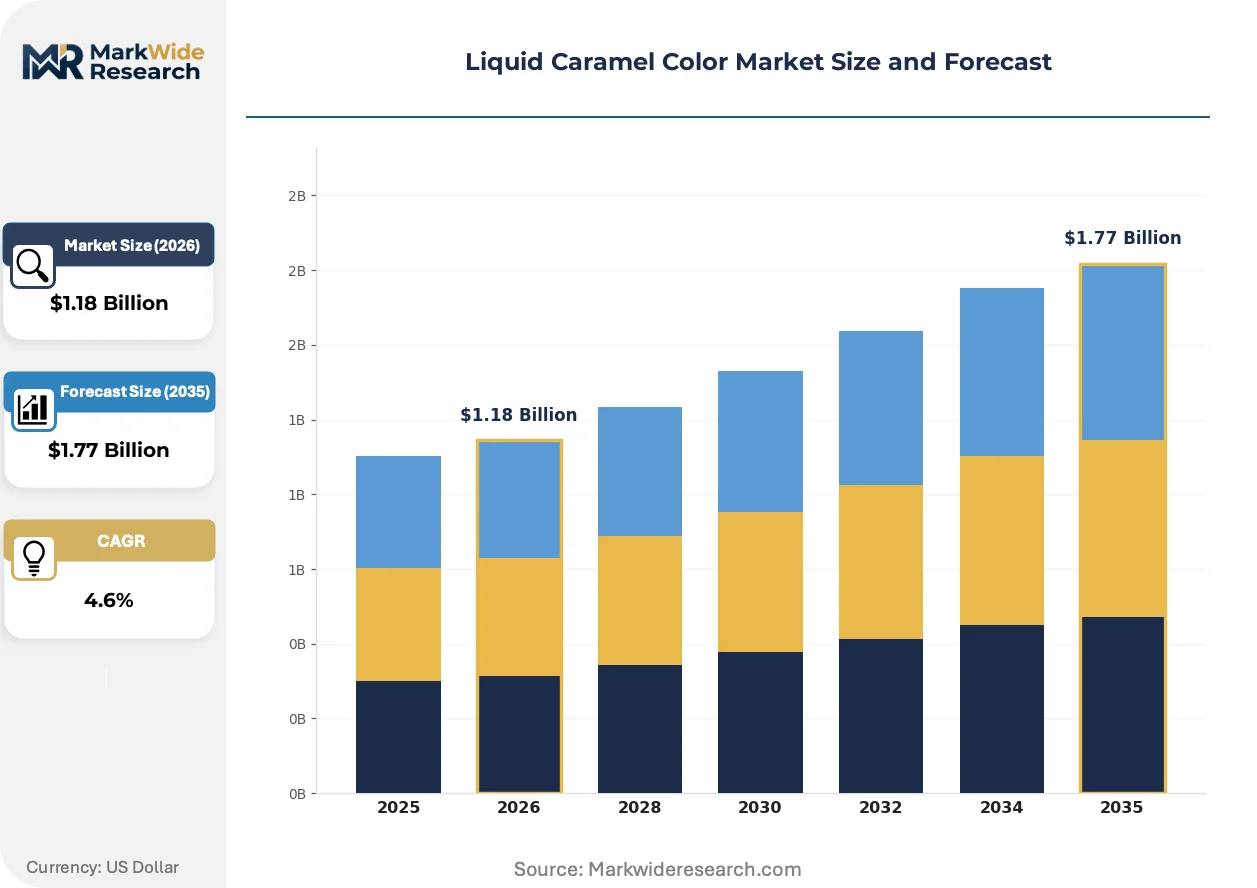
Market Dynamics
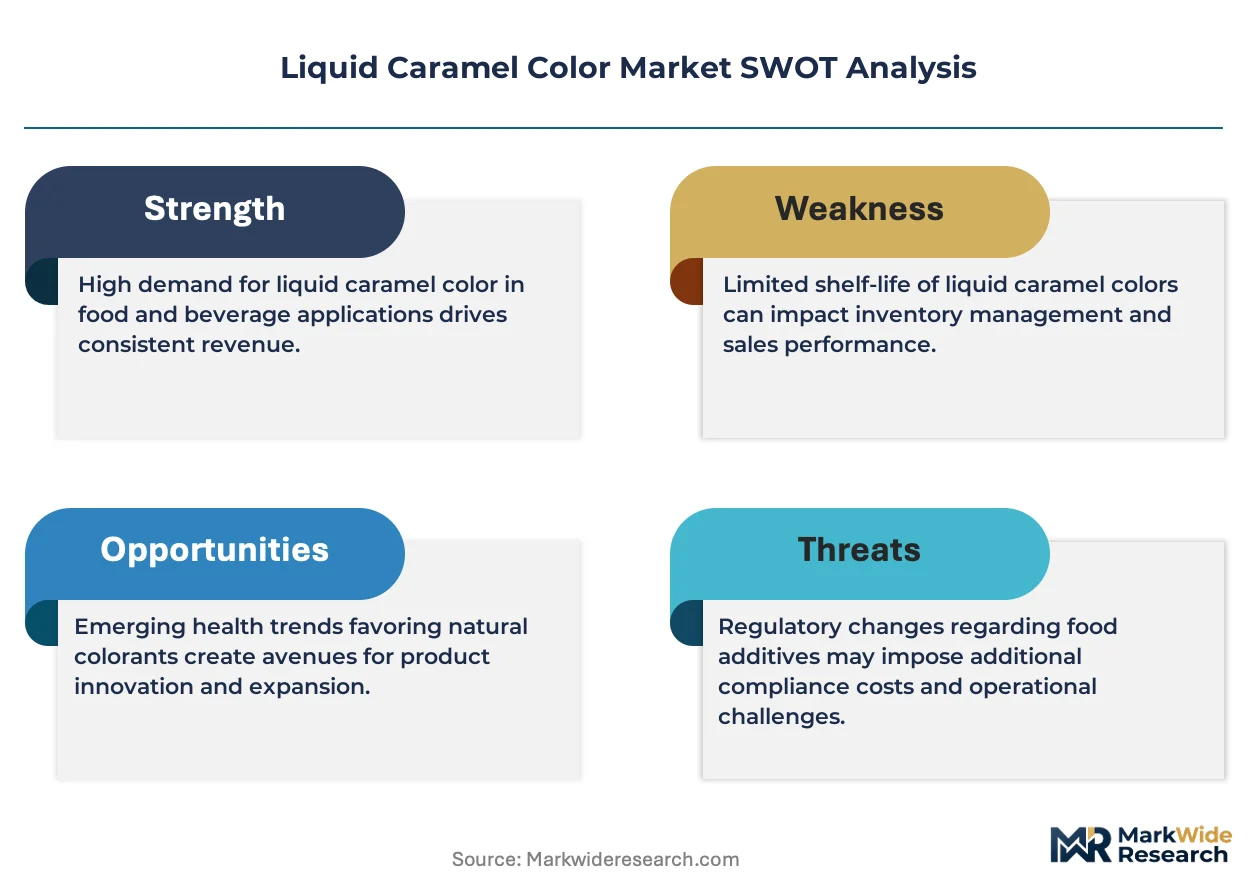
EFSA's tightening purity protocols for 4-MEI and 2-MEI contaminants are forcing manufacturers to reengineer thermal process parameters and catalyst selection, compressing legacy process margins while advantaging capital-rich operators capable of continuous purification upgrades.
Growth Catalysts
- Clean-label beverage reformulation:North American cola producers are substituting synthetic dyes with Class I natural caramel variants to meet retailer clean-label mandates and consumer ingredient transparency expectations.
- FSSAI labeling enforcement:India's mandatory INS 150 disclosure rules and maximum usage levels are accelerating domestic production investments and import substitution across processed food categories.
- Acid-stable Caramel Color IV:Negative charge characteristics that prevent flocculation in phosphoric acid environments sustain irreplaceable demand from high-volume carbonated soft drink manufacturers.
Market Restraints
- Input cost volatility:Glucose and sucrose feedstock prices swing with Brazilian sugar harvest cycles and corn ethanol diversion pressures in the US Midwest.
- Supply concentration risk:Three integrated manufacturers control the majority of high-tinctorial-power Class IV production capacity, creating single-source vulnerability for multinational beverage procurement teams.
- Technical limitation:Natural Class I variants lack the acid stability and shelf-life performance of sulfite-ammonia Class IV pigments, constraining clean-label migration in long-dated beverage SKUs.
Strategic Opportunities
- India processed food expansion:Surging urban consumption of packaged snacks and ready-to-drink beverages creates underpenetrated demand for heat-stable Class III bakery and confectionery pigments.
- California Proposition 65 compliance services:Warning label requirements for 4-MEI exposure create paid advisory and certified-low-contaminant product premiums for suppliers with validated analytical capabilities.
- Membrane filtration convergence:Cross-flow ceramic systems combined with enzymatic catalyst recovery are enabling closed-loop manufacturing with reduced wastewater discharge and catalyst consumption.
Industry Challenges
- Maillard chemistry expertise scarcity:Fewer than two dozen technical specialists worldwide possess deep knowledge of controlled carbohydrate pyrolysis kinetics, constraining R&D velocity and process troubleshooting.
- Multi-jurisdiction certification timelines:Simultaneous EFSA re-evaluation, FDA GRAS maintenance, and FSSAI registration create overlapping compliance burdens with divergent analytical method requirements.
- Legacy equipment retrofit costs:Continuous thermal processors require seven-figure capital outlays to install real-time contaminant monitoring and automated catalyst dosing systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Liquid Caramel Color Market |
| Market Size in 2026 | $1.18 Billion |
| Market Size in 2035 | $1.77 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural, Caramel Color II, Caramel Color IV, Caramel Color I Application: Beverages, Confectionery, Bakery, Sauces End User: Food Industry, Beverage Manufacturers, Cosmetics, Pharmaceuticals Formulation Type: Liquid, Powder, Paste, Granules |
| Companies Covered | Sethness Caramel Products Company, Sensient Technologies Corporation, DDW The Color House, Cargill Incorporated, Ingredion Incorporated, Aarkay Food Products Ltd, Nigay, Roquette Freres, Givaudan, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Liquid Caramel Color Market Trends and Innovations
Digital process control and predictive analytics are displacing manual temperature monitoring in caramel color manufacturing, compressing batch-to-batch variation while enabling real-time contaminant detection that preempts regulatory rejection.
Continuous thermal processing with inline spectrophotometric feedback is automating tinctorial power adjustment during carbohydrate pyrolysis. Beverage manufacturers in Germany and the Netherlands are adopting these systems at pilot scale. The technology is automating quality assurance labor and reducing off-spec batches that previously required reprocessing or disposal.
REACH authorization requirements for ammonium compounds used in Class III and IV production are tightening supply chain documentation and substitution assessment obligations for EU-bound shipments. Manufacturers must now maintain substance volume tracking and exposure scenario records across downstream formulations. Acidified beverage systems face the steepest compliance burden due to higher Caramel Color IV incorporation rates.
Direct procurement relationships between beverage manufacturers and caramel color specialists are displacing traditional distributor intermediaries in North America and Western Europe. Large cola and beer producers now negotiate multi-year supply agreements with technical service attachments. This pattern concentrates most visibly in the US Midwest and Bavaria, where brewing clusters demand customized emulsion stability specifications and rapid formulation support.
Liquid Caramel Color Market Segmentation
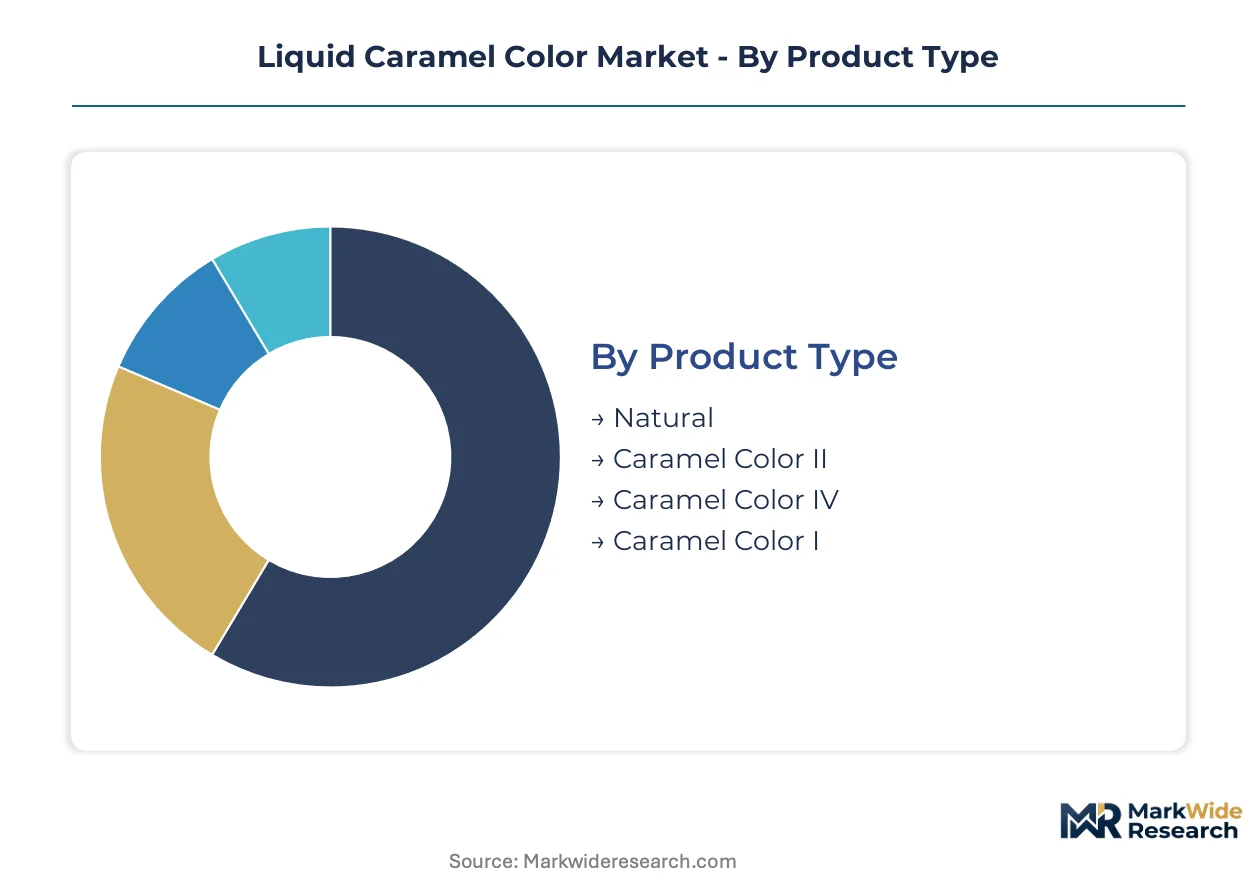
Liquid caramel color specifications diverge sharply across beverage, bakery, and pharmaceutical applications, with thermal stability, acid tolerance, and regulatory classification dictating procurement decisions. Manufacturers configure production lines around these technical boundaries rather than pursuing universal formulations.
Product Type:
Heat-treatment chemistry and catalyst selection define the four product classes, with sulfite-ammonia variants dominating high-volume cola production while natural alternatives command specification premiums.
- Natural:Produced via controlled carbohydrate pyrolysis without ammonium or sulfite catalysts, yielding positive-charge pigments with limited acid stability. North American clean-label beverage reformulation is concentrating procurement here, though shelf-life constraints restrict deployment in long-dated carbonated SKUs.
- Caramel Color IV:Sulfite-ammonia process generates negatively charged colloidal particles with superior phosphoric acid tolerance. This variant sustains irreplaceable demand from multinational cola producers operating in EFSA and FDA jurisdictions where flocculation resistance determines formulation acceptance.
- Caramel Color II:Caustic sulfite process creates intermediate tinctorial power suitable for neutral pH confectionery applications. European chocolate and candy manufacturers specify this grade for consistent hue intensity without ammonia-derived contaminants.
- Caramel Color I:Plain heat-treated carbohydrates without catalysts produce the lightest color intensity. Specialty sauce manufacturers in India leverage this class for subtle browning where aggressive Maillard notes would distort flavor profiles.
Mature deployment sits with Caramel Color IV. Newer deployment is concentrated in Natural variants.
Application:
End-use thermal environments and pH conditions segment demand across four distinct processing categories.
- Beverages:Carbonated soft drinks, alcoholic beverages, and ready-to-drink formulations require acid-stable pigments with predictable tinctorial power across shelf-life durations. FSSAI-mandated INS 150 labeling in India is accelerating specification verification here.
- Bakery:Oven temperatures exceeding 180°C demand heat-stable Class III pigments that resist Maillard browning deviation. Margin pools concentrate in this segment due to technical barriers and customized emulsion requirements.
- Confectionery:Chocolate coatings and hard candy applications prioritize consistent hue under rapid temperature cycling.
- Sauces:Acidified tomato and soy-based formulations require charge-stabilized pigments that prevent precipitation during thermal processing.
Volume leadership belongs to Beverages. Margin expansion is climbing the fastest in Bakery.
End User:
Procurement scale and technical service requirements separate four distinct customer categories with diverging qualification protocols.
- Food Industry:Processed snack and packaged meal producers specify heat-stable pigments for retort and microwave applications. India's urban consumption surge is driving domestic production investments to serve this category.
- Beverage Manufacturers:Multinational cola and beer producers negotiate multi-year supply agreements with attached technical service requirements. Direct procurement relationships are displacing distributor intermediaries in Germany and the US Midwest brewing clusters.
- Cosmetics:Hair dye and skincare formulations require low-contaminant grades with validated 4-MEI and 2-MEI thresholds.
- Pharmaceuticals:Tablet coating and liquid formulation applications demand pharmaceutical-grade certification with batch-level traceability.
Procurement consolidation is most advanced with Beverage Manufacturers. Penetration gaps persist in Pharmaceuticals.
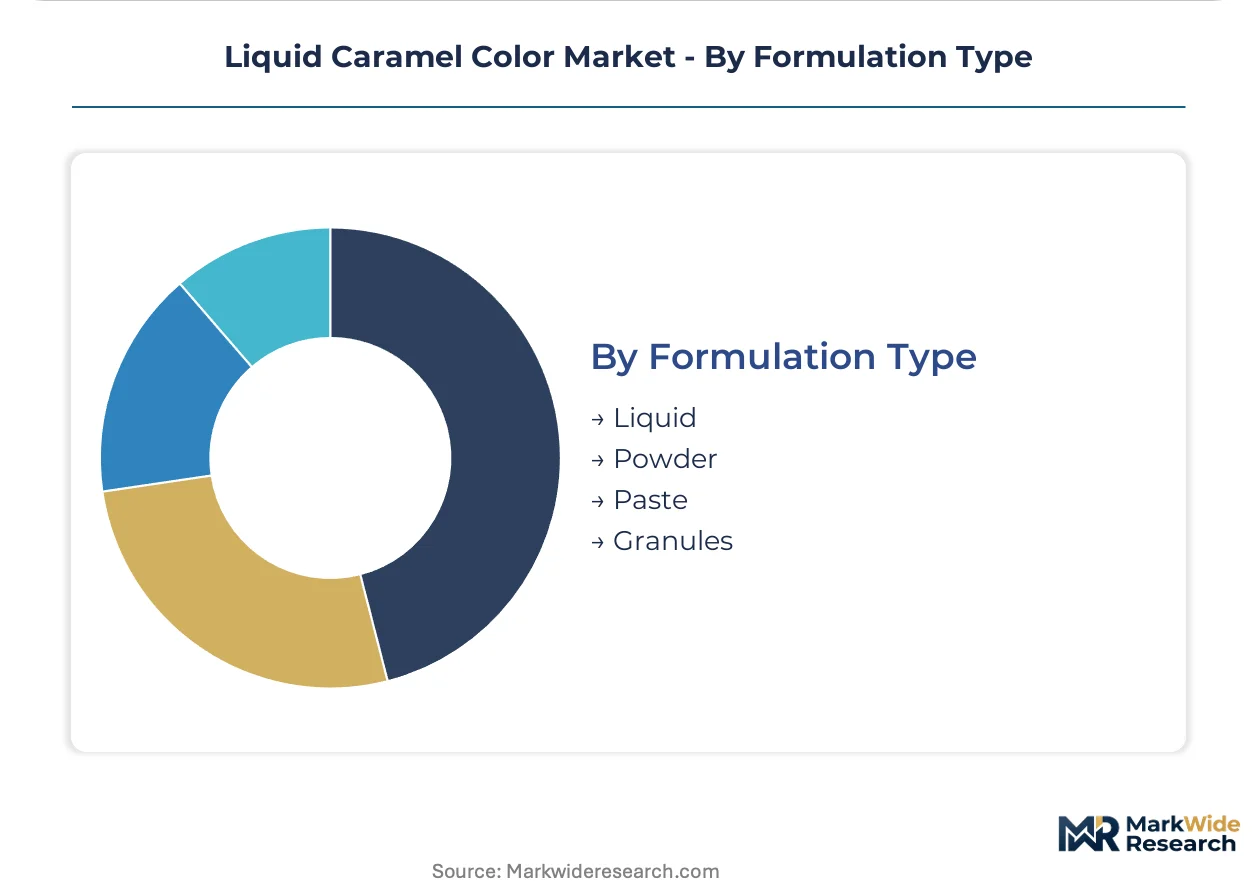
Formulation Type:
Physical state determines handling infrastructure, dissolution kinetics, and transportation economics across the value chain.
- Liquid:Ready-to-use aqueous solutions dominate high-volume beverage production where automated dosing systems require pumpable consistency. EFSA purity protocols are forcing continuous purification upgrades in European liquid production lines.
- Powder:Spray-dried variants reduce shipping costs for intercontinental supply chains serving confectionery and bakery compound manufacturers.
- Paste:High-solids formulations suit small-batch sauce producers with limited liquid storage capacity.
- Granules:Free-flowing dry forms enable precise metering in automated pharmaceutical tablet coating operations.
Capacity concentration favors Liquid. Infrastructure-light deployment is expanding most quickly in Powder.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India concentrates the fastest demand acceleration for liquid caramel color, with FSSAI-mandated INS 150 labeling and surging processed food consumption driving domestic production investments. Germany and the United States anchor high-volume procurement from multinational beverage manufacturers. Brazil and Japan complete the demand map with distinct regulatory and application profiles.
India
Urban consumption of packaged snacks and ready-to-drink beverages is accelerating specification verification for heat-stable pigments. FSSAI enforces mandatory INS 150 disclosure rules and maximum usage levels across processed food categories. Maharashtra and Gujarat host expanding domestic production facilities as import substitution dynamics reshape supply chains.
Germany
Brewing clusters in Bavaria demand customized emulsion stability specifications for acidified beer systems. EFSA maintains active re-evaluation protocols for 4-MEI and 2-MEI contaminants, constraining manufacturing process parameters for EU-bound shipments. Direct procurement relationships between beverage manufacturers and caramel color specialists are displacing traditional distributor intermediaries.
United States
North American cola producers are substituting synthetic dyes with Class I natural caramel variants to meet retailer clean-label mandates. California Proposition 65 warning requirements for 4-MEI exposure create state-level compliance fragmentation alongside FDA's GRAS designation under 21 CFR 73.85. The US Midwest brewing corridor negotiates multi-year supply agreements with attached technical service requirements.
Brazil
Carbonated soft drink manufacturers require acid-stable Caramel Color IV with negative charge characteristics for phosphoric acid environments. ANVISA regulates food additive purity specifications for domestic and imported colorants. São Paulo anchors procurement volumes for multinational beverage production facilities serving Latin American markets.
Japan
Confectionery and sauce applications prioritize consistent hue under rapid temperature cycling and subtle browning requirements. METI oversees food additive standards alignment with international Codex frameworks. The Kanto region around Tokyo concentrates formulation R&D for premium bakery and savory applications.
Liquid Caramel Color Market Competitive Landscape
North American producers anchor one tier; European specialists hold process chemistry advantages in high-purity segments. The vendor base concentrates around three integrated manufacturers controlling majority Class IV production capacity, with mid-tier regional formulators serving localized bakery and sauce applications. Two strategic archetypes dominate: century-established burnt sugar chemistry specialists and vertically integrated extraction-blending operators. Competitive moves center on continuous purification upgrades for EFSA compliance and direct procurement relationship cultivation with multinational beverage procurement teams.
Within the heritage specialist tier, Sethness Caramel Products Company represents century-long process chemistry accumulation, while Sensient Technologies Corporation exemplifies vertically integrated extraction and blending operations across multiple continents. DDW The Color House occupies a position emphasizing customized emulsion stability solutions for acidified beverage systems. These three anchors illustrate the competitive spectrum from specialized process knowledge to global supply security architectures.
| Leading Market Players |
|---|
| Sethness Caramel Products Company |
| Sensient Technologies Corporation |
| DDW The Color House |
| Cargill Incorporated |
| Ingredion Incorporated |
| Aarkay Food Products Ltd |
| Nigay |
| Roquette Freres |
| Givaudan |
| Others |
Pricing and Supply Chain Analysis
Natural-versus-synthetic grade bifurcation in liquid caramel color separates procurement into two pricing regimes with divergent supply chain architectures. Premium natural Class I variants command specification premiums through dedicated pyrolysis lines and catalyst-free process controls, while commodity Caramel Color IV flows through high-volume continuous processors optimized for multinational beverage offtake. This divergence concentrates margin capture with heritage specialists possessing closed-loop purification systems, while price-sensitive bakery and sauce manufacturers source through distributor intermediaries lacking technical service attachments.
Pricing Analysis
Volume leadership in Caramel Color IV generates thin margins offset by multi-year contract security, whereas natural Class I variants capture expanded spreads from clean-label reformulation mandates. Price differentiation rests on EFSA contaminant certification tiers and attached technical service bundling for acidified beverage stability. Cost compression in standard-grade liquid formulations is intensifying because Brazilian sugar harvest volatility feeds directly into glucose feedstock indices. Small-batch sauce producers in India exhibit highest price sensitivity, while multinational cola procurement teams prioritize supply security over unit cost.
Supply Chain Analysis
Intercontinental freight economics favor powder and liquid bulk shipments from production clusters in the United States, Germany, and India over regional micro-production. Manufacturing draws from glucose and sucrose feedstocks anchored in Brazilian sugar cycles and US Midwest corn ethanol diversion pressures. Single-source vulnerability concentrates in high-tinctorial-power Class IV capacity controlled by three integrated manufacturers. Distribution runs through direct procurement relationships with multinational beverage manufacturers displacing traditional distributor channels in North America and Western Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a vertical-integration race where upstream control over purification technology and downstream captive relationships with beverage procurement teams determine competitive survival. Players are pursuing backward integration into membrane filtration and enzymatic catalyst recovery to compress cost structures and preempt regulatory rejection.
For Market Incumbents: To counter EFSA tightening on 4-MEI and 2-MEI thresholds, deploy continuous purification upgrades with real-time spectrophotometric feedback and deepen direct procurement relationships with Bavarian and Midwest brewing clusters through attached technical service contracts. Prioritize certification maintenance across simultaneous FDA GRAS and FSSAI registration timelines to lock out mid-tier regional formulators lacking compliance bandwidth. For New Entrants and Emerging Players: FSSAI-mandated INS 150 labeling in India opens a window for domestic production facilities serving Maharashtra and Gujarat processed food corridors with heat-stable Class III pigments for bakery applications. Target pharmaceutical-grade certification gaps where batch-level traceability requirements exclude commodity suppliers. Pursue membrane filtration technology licensing from European equipment vendors to bypass legacy thermal processor capital barriers. For Investors and Strategic Acquirers: Re-rating potential sits with heritage specialists possessing century-long Maillard chemistry expertise given clean-label reformulation tailwinds and regulatory compliance moats. Long-term viability centers on acquisition targets with validated low-contaminant analytical capabilities and established direct relationships with multinational beverage procurement teams. Monitor EFSA re-evaluation timeline acceleration as the inflection signal for consolidation urgency.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Purification Upgrade | Real-time contaminant detection preempts EFSA rejection and secures EU-bound shipment eligibility. |
| Backward Integration into Membrane Filtration | Ceramic cross-flow systems reduce catalyst consumption and wastewater discharge liabilities. |
| Direct Procurement Relationship Cultivation | Multi-year supply agreements with technical service attachments displace distributor intermediaries. |
| Pharmaceutical-Grade Certification Investment | Batch-level traceability unlocks tablet coating and liquid formulation premium segments. |
| India Domestic Production Facility Buildout | FSSAI labeling enforcement and urban consumption surges reshape import substitution dynamics. |
Research Methodology
Document review covered EFSA re-evaluation protocols, FSSAI regulatory circulars, and FDA GRAS designation records, complemented by interviews with caramel color plant managers, procurement leads at multinational beverage manufacturers, distribution channel partners, and technical R&D directors specializing in Maillard chemistry. Secondary validation drew from customs and trade data, SEC filings of publicly traded ingredient suppliers, and industry association reports from European and North American food additive consortia. Bottom-up volume modeling and top-down value triangulation reconciled production capacity disclosures with downstream formulation demand estimates.
Historical shipment patterns were cross-referenced against panel input from procurement executives to anchor growth assumptions across the projection horizon. Segmentation modeling incorporated product class chemistry, application thermal environment, end-user procurement scale, and formulation physical state. CAGRs were derived from slope analysis of normalized volume trends adjusted for regulatory inflection points and feedstock price elasticity. Forecast inputs included Brazilian sugar harvest projections, corn ethanol diversion pressures, and EFSA re-evaluation timeline scenarios.
The model assumes a particular technology adoption path for continuous thermal processing with inline spectrophotometric feedback; alternative pathways for batch manual control would alter the outlook through higher contaminant rejection rates and compressed legacy margins. Forecasts reflect documented assumptions on regulatory timeline adherence and feedstock price stability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Global Fatty Acids Market
Food Additives and Ingredients
Food Texturing Agents Market
Food Additives and Ingredients
South Africa Anti Caking Agents Market
Food Additives and Ingredients
China Food Additives Market
Food Additives and Ingredients
Egg Wash Substitute Market
Food Additives and Ingredients
Oxidized Starch Market
Food Additives and Ingredients
Asia-Pacific Fermented Ingredient Market
Food Additives and Ingredients
Global Food Texturants Market
Food Additives and Ingredients
Polyglycerol Esters of Fatty Acids Market
Food Additives and Ingredients
India Food Colorants Market
Food Additives and Ingredients
Food Grade Calcium Hydroxide Market
Food Additives and Ingredients
Europe Food Acidulants Market
Food Additives and Ingredients
Lycopene Food Colors Market
Food Additives and Ingredients
Lactose Monohydrate Market
Food Additives and Ingredients
Germany Anticaking Market
Food Additives and Ingredients
North America Microencapsulation Market