
 Beer Filter System Market | 2026-2036
Beer Filter System Market Size, Share, and Industry Trends Forecast 2026-2036
Beer Filter System Market Outlook
A widening capital-intensity divergence between membrane specialists and legacy mechanical suppliers is unwinding competitive parity in beer filtration. Pall Corporation leverages its hollow-fiber membrane portfolio to capture premium craft brewery contracts in North America. Alfa Laval anchors its position through integrated separation systems that span wort cooling through final polish filtration. GEA Group competes on engineering scale, sustaining large-order dominance among multinational beverage conglomerates.
Beer filter systems encompass enclosed vessels, membrane arrays, and cartridge housings engineered to remove yeast, proteins, and colloidal haze from fermented wort and finished beer, typically operating at temperatures between 0°C and 10°C with pore ratings from 0.45 to 10 microns depending on clarification stage. Their primary purpose is stabilizing shelf life and visual clarity while preserving flavor-active compounds sensitive to oxidation or thermal damage. Membrane filtration technology leads value generation as breweries replace diatomaceous earth with cross-flow systems that slash waste disposal costs. Automated installation types attract capital fastest among mid-size breweries seeking labor efficiency without dedicated cellar staff. Mechanical filters retain volume dominance in emerging markets where low capital thresholds and simple maintenance protocols outweigh efficiency gains.
The EPA enforces effluent limits on diatomaceous earth disposal from traditional filtration, pushing US breweries toward regenerable membrane alternatives. REACH restricts chemical sanitizers used in European filter cleaning protocols, elevating demand for steam-sterilizable polymeric membranes from suppliers like Sartorius AG. ISO 22000 and HACCP frameworks govern food-contact surfaces across export-oriented brewing operations, creating compliance barriers for uncertified equipment entrants. Stakeholders must weigh water-recovery specifications against total cost of ownership when specifying filtration architecture for new brewhouse capacity.
Market Dynamics
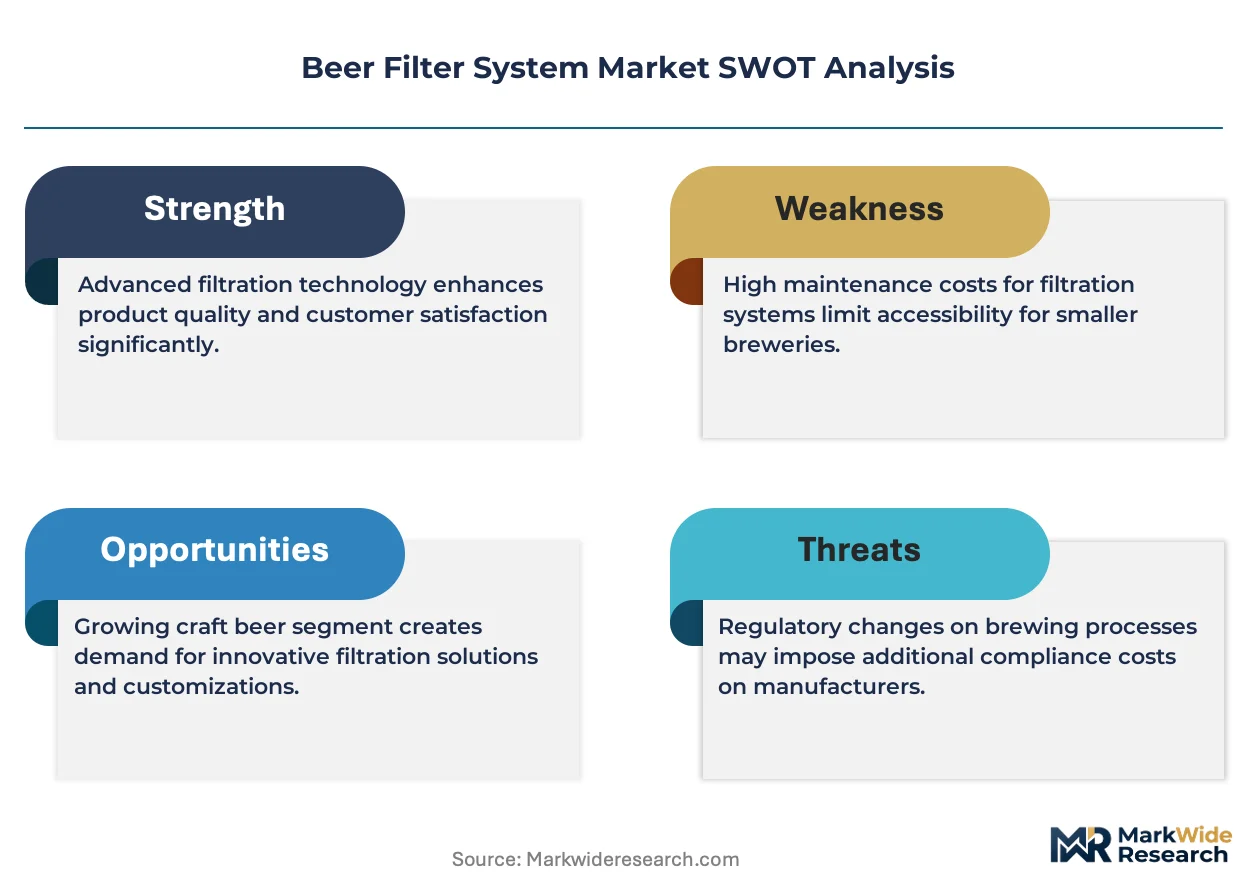
Membrane filtration technology is compressing capital recovery timelines for craft breweries while EU Green Deal water-efficiency mandates force legacy diatomaceous earth operators into costly retrofits or replacement cycles.
Growth Catalysts
- REACH chemical restrictions:Steam-sterilizable polymeric membranes from European suppliers satisfy sanitizer-reduction mandates while eliminating chemical discharge liabilities for export-oriented brewhouses.
- Craft brewery quality benchmarks:North American and European craft producers deploy cross-flow systems to achieve haze stability in unfiltered beer styles without flavor oxidation.
- Cross-flow membrane arrays:These systems slash waste disposal costs by 60-80% versus diatomaceous earth, regenerating filter media through automated back-pulse cycles rather than single-use consumption.
Market Restraints
- Membrane module cost volatility:Specialized hollow-fiber polyethersulfone and ceramic substrates concentrate supply among three dominant polymer suppliers, exposing brewhouse capex budgets to raw material price swings.
- Technical limitation in high-solids wort:Membrane fouling rates accelerate dramatically above 5% solids concentration, forcing hybrid mechanical-membrane architectures that duplicate capital footprint.
- EPA effluent enforcement friction:Diatomaceous earth disposal restrictions trigger compliance costs that disadvantage small regional breweries lacking on-site waste-treatment infrastructure.
Strategic Opportunities
- India microbrewery licensing liberalization:State-level excise reforms in Karnataka and Maharashtra enable membrane system deployment in a market where mechanical filtration currently dominates due to low capital thresholds.
- Water-recovery specification convergence:EU Green Deal water-intensity targets create demand for closed-loop filtration architectures that reclaim 85-90% of process water for CIP reuse.
- Automated installation channel innovation:Skid-mounted membrane systems with remote monitoring capability penetrate mid-size brewery segments previously served by manual mechanical filters.
Industry Challenges
- Cross-functional talent scarcity:Membrane system operation requires simultaneous competence in fluid mechanics, polymer chemistry, and PLC programming—skill bundles rarely found in traditional cellar staff.
- ISO 22000 certification timeline compression:Export-oriented breweries face 12-18 month validation cycles for food-contact surface compliance, delaying revenue recognition on new filtration lines.
- Legacy system integration complexity:Retrofitting membrane arrays into 1990s-era brewhouses with fixed pipe routing and limited headroom demands custom engineering that erodes modular cost advantages.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Beer Filter System Market |
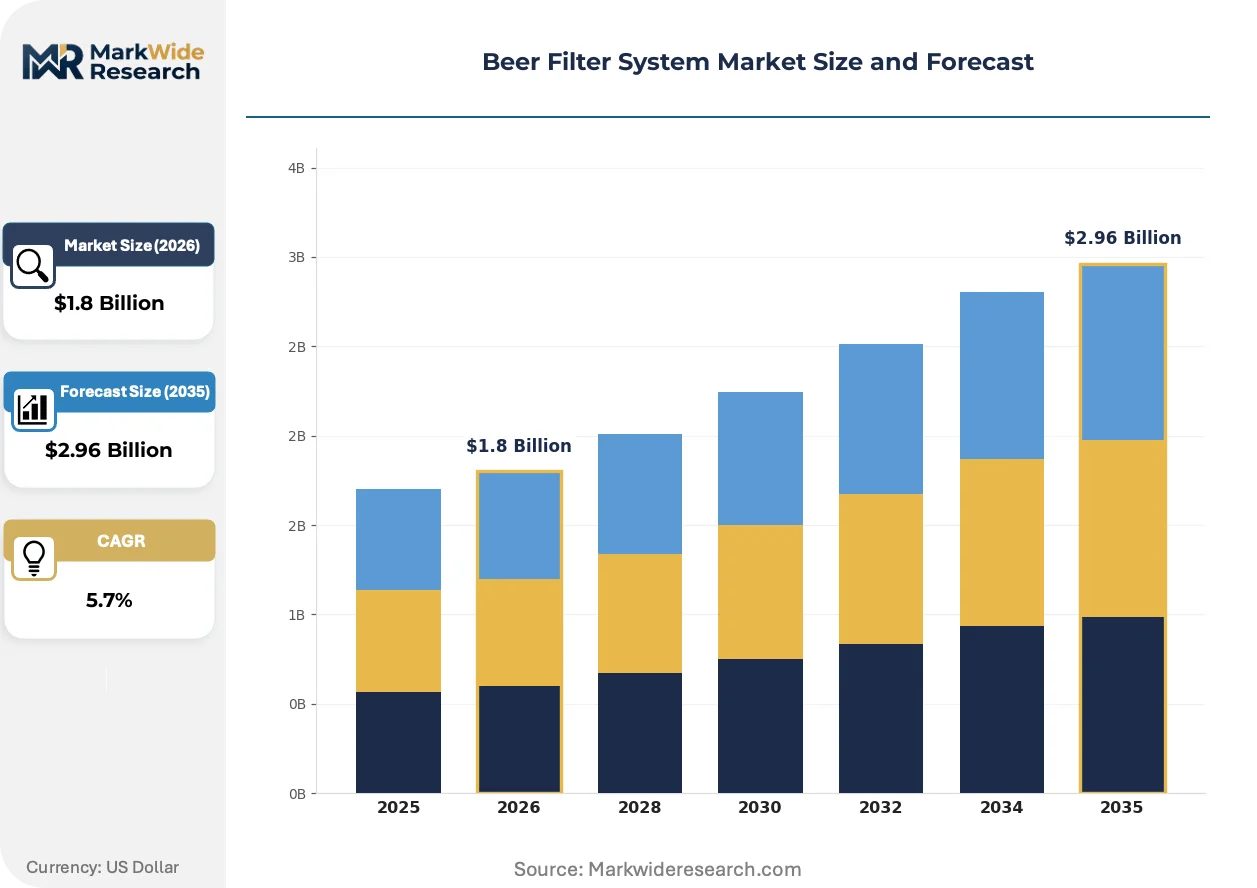
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mechanical Filters, Membrane Filters, Cartridge Filters, Plate Filters Technology: Microfiltration, Ultrafiltration, Nanofiltration, Vacuum Filtration End User: Brewery, Beverage Manufacturer, Home Brewer, Research Laboratory Installation Type: Inline Systems, Batch Systems, Portable Systems, Automated Systems |
| Companies Covered | Pall Corporation, Alfa Laval, Pentair, Sartorius AG, GEA Group, Andritz AG, Krones AG, Bucher Unipektin AG, SPX FLOW, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Beer Filter System Market Strategic Shifts
Active transformation in beer filtration centers on three vectors: ceramic and polymeric membranes displacing legacy media, regulatory pressure reshaping equipment specifications, and brewery procurement models favoring operational expenditure over capital deployment.
Ceramic membrane arrays with 0.1-0.2 micron nominal ratings are displacing diatomaceous earth filtration in premium craft brewery installations. Mid-size North American brewhouses with 50,000-200,000 hectoliter annual output are adopting these systems fastest, driven by waste disposal cost elimination and labor automation. This displacement is compressing the installed base of mechanical filter presses by 8-12% annually in quality-focused segments.
REACH Annex XVII restrictions on quaternary ammonium sanitizers are forcing European filter manufacturers toward steam-sterilizable membrane materials. Industrial consequence includes elevated R&D allocation to polyphenylsulfone and PVDF formulations rated for 140°C saturated steam cycles. German and Czech brewhouses, bound by Reinheitsgebot purity traditions and modern chemical discharge limits, are the most affected and are specifying membrane systems with integrated SIP (steam-in-place) capability.
Brewery procurement departments are unbundling after-sales service from equipment capital contracts, negotiating separate multi-year membrane replacement and technical support agreements. Equipment distributors in North America and Western Europe are responding by launching subscription-based filter performance contracts with guaranteed flux rates and scheduled module replacement. This behavioral shift is most visible among venture-backed craft brewery chains seeking to preserve balance-sheet flexibility for taproom expansion.
Beer Filter System Market Segmentation
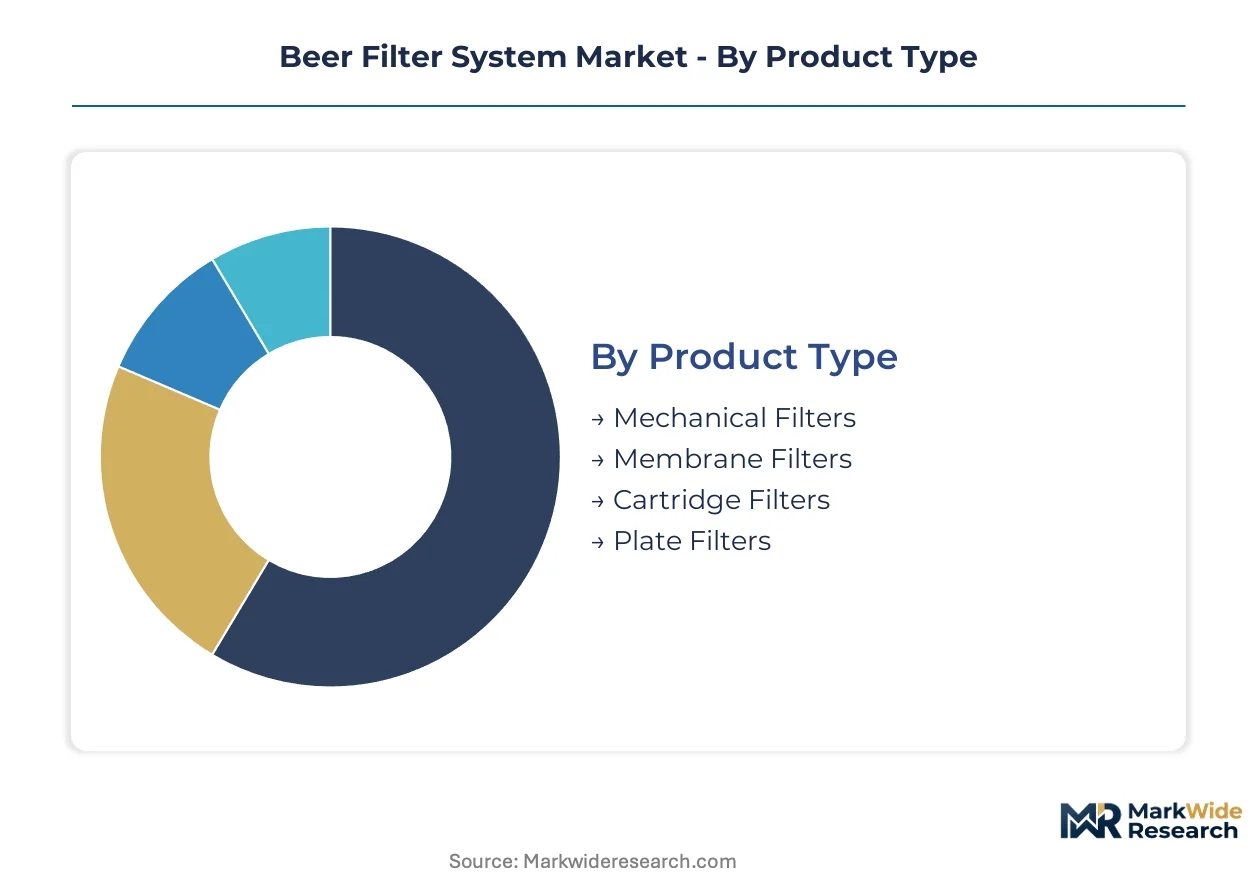
Beer filtration architectures diverge sharply across brewery scale and regulatory environment, with membrane technology commanding premium positioning while mechanical systems retain volume dominance in cost-sensitive markets. Channel economics dictate whether systems sell through direct engineering contracts, distributor networks, or subscription-based service models.
Product Type:
Mechanical filters move through legacy distributor channels serving emerging markets, while membrane arrays flow through direct OEM relationships with multinational brewhouses and craft brewery chains.
- Mechanical Filters:Diatomaceous earth and perlite-based pressure vessels with plate-and-frame or candle configurations dominate installed capacity across Latin American and African brewing operations. Demand concentrates in Brazil and Mexico, where low capital thresholds and established maintenance protocols outweigh efficiency penalties.
- Membrane Filters:Cross-flow hollow-fiber and ceramic arrays with automated back-pulse regeneration eliminate single-use media consumption. German and Czech craft breweries specify these systems fastest, driven by EU Green Deal water-recovery mandates and REACH chemical discharge restrictions.
- Cartridge Filters:Pleated polypropylene and cellulose depth filters provide final polish filtration in multi-stage architectures. Beverage conglomerates deploy these as terminal guards downstream of primary membrane clarification.
- Plate Filters:Traditional filter presses with cellulose sheets persist in small-scale European farmhouse breweries preserving Reinheitsgebot-compatible processes without synthetic materials.
Mechanical filters dominate installed base. Membrane filters are where expansion concentrates.
Technology:
Cost tier stratification separates premium ceramic membranes from commodity polymeric alternatives, with vacuum filtration anchoring the economy segment.
- Microfiltration:0.1-0.45 micron rated membranes remove yeast and bacteria while preserving protein haze in unfiltered beer styles. North American craft breweries with 50,000-200,000 hectoliter output adopt ceramic microfiltration fastest to achieve haze stability without flavor oxidation.
- Ultrafiltration:0.01-0.1 micron cut-offs separate colloidal proteins and polyphenols for extended shelf-life stability. Large-scale German export breweries deploy these systems to satisfy destination-market clarity specifications.
- Nanofiltration:Molecular weight cut-offs below 1000 Da enable alcohol adjustment and dealcoholized beer production. Specialty beverage manufacturers in Switzerland and Belgium leverage this for low-ABV product lines.
- Vacuum Filtration:Reduced-pressure mechanical systems with cellulose pads serve home brewing and pilot-scale research applications where throughput requirements remain modest.
Microfiltration commands revenue share. Ultrafiltration is climbing the fastest on water-efficiency compliance.
End User:
Volume concentration follows brewery consolidation patterns, with research laboratories representing a specialized channel requiring distinct validation documentation.
- Brewery:Commercial brewhouses from craft microbreweries to multinational conglomerates constitute the core demand channel, with procurement shifting toward operational expenditure models.
- Beverage Manufacturer:Cider, kombucha, and functional drink producers repurpose beer filtration architectures for analogous clarification challenges.
- Home Brewer:Small-scale cartridge and plate filter kits distribute through specialty retail and direct-to-consumer channels.
- Research Laboratory:Pilot-scale membrane skids with data logging capability serve university brewing programs and yeast genetics facilities.
Breweries dominate installed base. Beverage manufacturers are gaining share fastest on category diversification.
Installation Type:
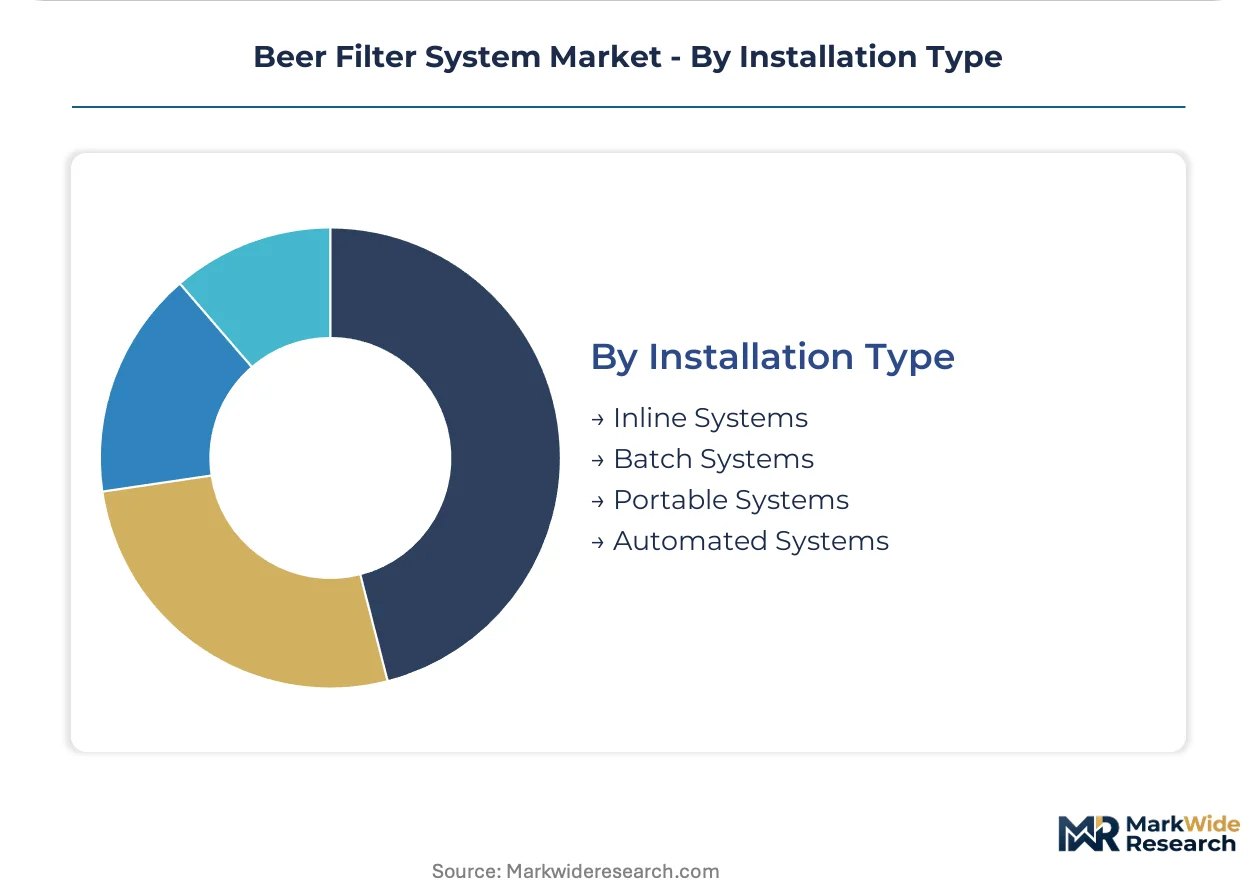
Customer type dictates automation intensity, with mid-size breweries driving fastest uptake of remote-monitored systems.
- Inline Systems:Continuous-flow membrane arrays integrated between fermentation and packaging lines maximize throughput for high-volume operations.
- Batch Systems:Discontinuous filtration cycles with manual transfer steps persist in traditional European cellar operations.
- Portable Systems:Skid-mounted units with quick-connect fittings serve contract brewing facilities and seasonal capacity expansion.
- Automated Systems:PLC-controlled membrane skids with remote monitoring and predictive maintenance algorithms penetrate venture-backed craft brewery chains seeking labor efficiency without dedicated cellar staff.
Batch systems dominate legacy installed base. Automated systems are where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German brewhouses deploy membrane arrays for Reinheitsgebot-compliant haze stability, while Brazilian operators favor mechanical filters on capital constraints. This consumption-mix differential separates regulatory-driven technology adoption from price-sensitive volume markets.
United States
EPA effluent enforcement on diatomaceous earth disposal accelerates membrane retrofits across craft brewery clusters. The agency's Clean Water Act discharge limits pressure mid-size brewhouses toward regenerable cross-flow systems. Colorado's Front Range brewing corridor sees fastest automated filtration uptake as venture-backed chains expand packaging capacity.
Germany
EU Green Deal water-intensity targets intersect with Reinheitsgebot traditions to elevate ceramic membrane specifications. REACH Annex XVII chemical restrictions eliminate quaternary ammonium sanitizers, forcing steam-sterilizable polymer adoption. Bavarian craft breweries around Munich specify integrated SIP-capable systems for export-oriented pilsner production.
Brazil
Mechanical filtration retains dominance as low capital thresholds outweigh efficiency penalties for regional brewhouses. ANVISA food-contact surface regulations govern import certification for European membrane suppliers. São Paulo state's consolidated brewing sector concentrates large-order mechanical filter demand among multinational beverage conglomerates.
India
State-level excise reforms in Karnataka and Maharashtra enable microbrewery licensing expansion previously blocked by regulatory friction. FSSAI food safety standards create compliance barriers for uncertified equipment imports. Bangalore's emerging craft brewing cluster drives initial membrane system trials as licensing liberalization attracts private equity.
China
MIIT industrial upgrading guidelines encourage water-efficient filtration architectures in state-owned brewhouse consolidation. National dual carbon goals pressure large-scale operators toward closed-loop membrane systems reclaiming process water. Shandong Province's brewing base sees hybrid mechanical-membrane retrofits as provincial environmental bureaus tighten discharge permits.
Beer Filter System Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with hollow-fiber membrane developers competing against legacy separation equipment fabricators. The upper tier commands premium positioning through multi-stage system integration spanning wort cooling through final polish. Mid-tier specialists anchor regional market access through distributor relationships and aftermarket service networks. Competitive moves concentrate on portfolio diversification into adjacent beverage clarification and strategic partnerships for ceramic substrate supply security.
Within the integrated systems tier, Pall Corporation and Alfa Laval occupy positions exemplifying membrane specialization versus engineered separation platforms. GEA Group represents the engineering-scale archetype sustaining large-order dominance. Sartorius AG anchors the steam-sterilizable polymer membrane segment serving REACH-constrained European brewhouses. These three company patterns illustrate how technology focus, system breadth, and manufacturing scale segment competitive positioning across regulatory and brewery-scale vectors.
| Leading Market Players |
|---|
| Pall Corporation |
| Alfa Laval |
| Pentair |
| Sartorius AG |
| GEA Group |
| Andritz AG |
| Krones AG |
| Bucher Unipektin AG |
| SPX FLOW |
| Others |
Value Chain & Pricing Dynamics
Ninety-day ceramic membrane module lead times concentrate procurement power among German and Japanese polymer suppliers, compressing margin flexibility for mid-tier system integrators while amplifying pricing leverage at the hollow-fiber substrate tier. This inventory-to-pricing dynamic shapes how breweries structure capital deployment across membrane and mechanical alternatives.
Pricing Analysis
Long-term membrane replacement contracts dominate brewery procurement, with pricing stratifying across ceramic premium tiers, polymeric standard configurations, and refurbished economy modules. REACH-compliant steam-sterilizable membranes command certification premiums over commodity alternatives. Cost compression in standard polymeric tiers intensifies as Chinese substrate entrants expand capacity. Regional craft breweries exhibit highest price sensitivity, while multinational beverage conglomerates absorb premium positioning for integrated system packages.
Supply Chain Analysis
Strategic stockpiling of polyethersulfone resins characterizes European membrane fabricator behavior, contrasting with just-in-time ceramic substrate procurement among North American system assemblers. Hollow-fiber polymer supply concentrates in Germany, Japan, and the United States. Ceramic membrane production draws from alumina and zirconia feedstocks anchored in Chinese and Australian mining operations. Single-source vulnerability persists at the specialized polyphenylsulfone formulation tier. Distribution runs through direct OEM relationships for large brewhouses and distributor networks for mid-size craft installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as craft brewery procurement unbundles equipment capital from aftermarket service, creating niche entry points for membrane specialists and automated system integrators outside legacy mechanical supply chains.
For Market Incumbents: Consolidate aftermarket service contracts into multi-year performance guarantees with scheduled module replacement, defending against subscription-based entrants. Backward integration into ceramic substrate production secures supply continuity amid polymer price volatility. Capture venture-backed craft brewery chains through remote-monitored automated skids before regional distributors establish relationships. For New Entrants and Emerging Players: Differentiate on steam-sterilizable membrane formulations targeting REACH-constrained German and Czech export breweries. Target India's Karnataka and Maharashtra microbrewery clusters with skid-mounted portable systems as state licensing liberalization accelerates. Pursue channel partnerships with European brewing engineering consultants rather than direct distributor competition. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance play because EU Green Deal water-intensity mandates and EPA effluent enforcement structurally displace diatomaceous earth filtration regardless of brewery scale cyclicality. Acquisition focus centers on hollow-fiber membrane specialists with integrated SIP capability and established ISO 22000 certification pathways. Signal to monitor: state-level excise liberalization in India and Brazil creating addressable market expansion beyond saturated North American craft segments.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ceramic Substrates | Secures polyphenylsulfone supply continuity against REACH-driven formulation shifts. |
| Subscription-Based Performance Contracts | Captures venture-backed craft brewery chains seeking balance-sheet flexibility for taproom expansion. |
| Steam-in-Place Capability Integration | Satisfies German Reinheitsgebot traditions intersecting with REACH chemical discharge restrictions. |
| Remote Monitoring Platform Deployment | Penetrates mid-size brewery segments lacking dedicated cellar staff for membrane system operation. |
| India Microbrewery Channel Partnership | Positions for Karnataka and Maharashtra licensing liberalization creating first-mover membrane adoption. |
Study Parameters
The analysis maps mechanical filtration, membrane arrays, cartridge systems, and automated installation architectures, each validated through brewhouse engineering directors, membrane system operators, distributor technical sales leads, and regulatory compliance officers at export-oriented breweries. Primary interview insights triangulate against customs filtration equipment import records, EPA Clean Water Act enforcement disclosures, EU ECHA REACH restriction updates, and brewery capital expenditure filings. Bottom-up brewery-scale demand modeling cross-references top-down equipment manufacturer revenue segmentation.
Consistency checks validate volume and value outputs against membrane module shipment data, water-recovery specification trends in EU Green Deal implementation reports, and diatomaceous earth disposal cost trajectories across US craft brewery clusters. Segmentation dimensions span product type, technology tier, end-user scale, and installation automation intensity. CAGRs derive from brewery capacity expansion pipelines, regulatory compliance timelines, and membrane displacement curves in quality-focused market segments. Forecast inputs incorporate REACH chemical restriction phase-in schedules and state-level excise reform progressions.
The analysis sits within stated boundaries; outcomes outside sustained regulatory enforcement intensity or ceramic substrate supply stability would require recalibration. Forecasts reflect assumptions regarding EU water-intensity target adherence and EPA effluent limit continuity. Revision becomes warranted when membrane fouling rate improvements in high-solids applications cross commercial viability thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
South Africa Beverages Market
Alcoholic Beverages
Chocolate Liqueur Market
Alcoholic Beverages
Liqueurs Market
Alcoholic Beverages
American Oak Barrels Market
Alcoholic Beverages
Global Craft Vodka Market
Alcoholic Beverages
Smart Wine Cellar Market
Alcoholic Beverages
Wine Filtering Machine Market
Alcoholic Beverages
Lager Market
Alcoholic Beverages
Brewing Enzymes Market
Alcoholic Beverages
Barrel Liner Market
Alcoholic Beverages
Alcoholic Ready-To-Drink (Rtds)/High Strength Premixes Market
Alcoholic Beverages
Middle East and Africa Alcoholic Beverage Market
Alcoholic Beverages
Beer Cans Market
Alcoholic Beverages
Beer Bottle Market
Alcoholic Beverages
Saffron Beer Market
Alcoholic Beverages
Wine Box Market