
 Herbal Distillates Market | 2026-2036
Herbal Distillates Market Size, Share, and Industry Trends Forecast 2026-2036
Herbal Distillates Market Analytics
Modular dosing formats and unbundled ingredient kits are realigning how cosmetic formulators source botanical inputs. Givaudan leverages captive distillation capacity in Grasse to secure consistent lavender and rosemary outputs. Synthite Industries anchors its position through backward integration into cardamom and turmeric estates in southern India. Symrise competes via precision-controlled vacuum distillation systems that preserve heat-sensitive terpene profiles.
Herbal distillates comprise aqueous and volatile fractions recovered through steam distillation, hydrodistillation, or solvent extraction of aromatic plant material, yielding essential oils, hydrosols, and concentrated extracts with defined organoleptic and phytochemical specifications. These inputs serve as functional actives, natural preservatives, and flavor carriers across formulated consumer products. Essential oils currently dominate value capture due to concentrated potency and premium positioning in therapeutic applications, while hydrosols represent the fastest-expanding category as water-based personal care formulations displace alcohol-heavy alternatives. Within end-user verticals, cosmetics and wellness applications concentrate margin pools where clean-label positioning commands formulation premiums.
EMA guidelines on herbal medicinal products, REACH substance registration requirements, and EU Green Deal sustainable sourcing mandates collectively elevate compliance costs while favoring traceable supply chains. The EU AI Act introduces emerging documentation obligations for automated quality-control systems used in distillation monitoring. Stakeholders must weigh organic certification investments against conventional volume plays as regulatory stringency diverges across destination markets.
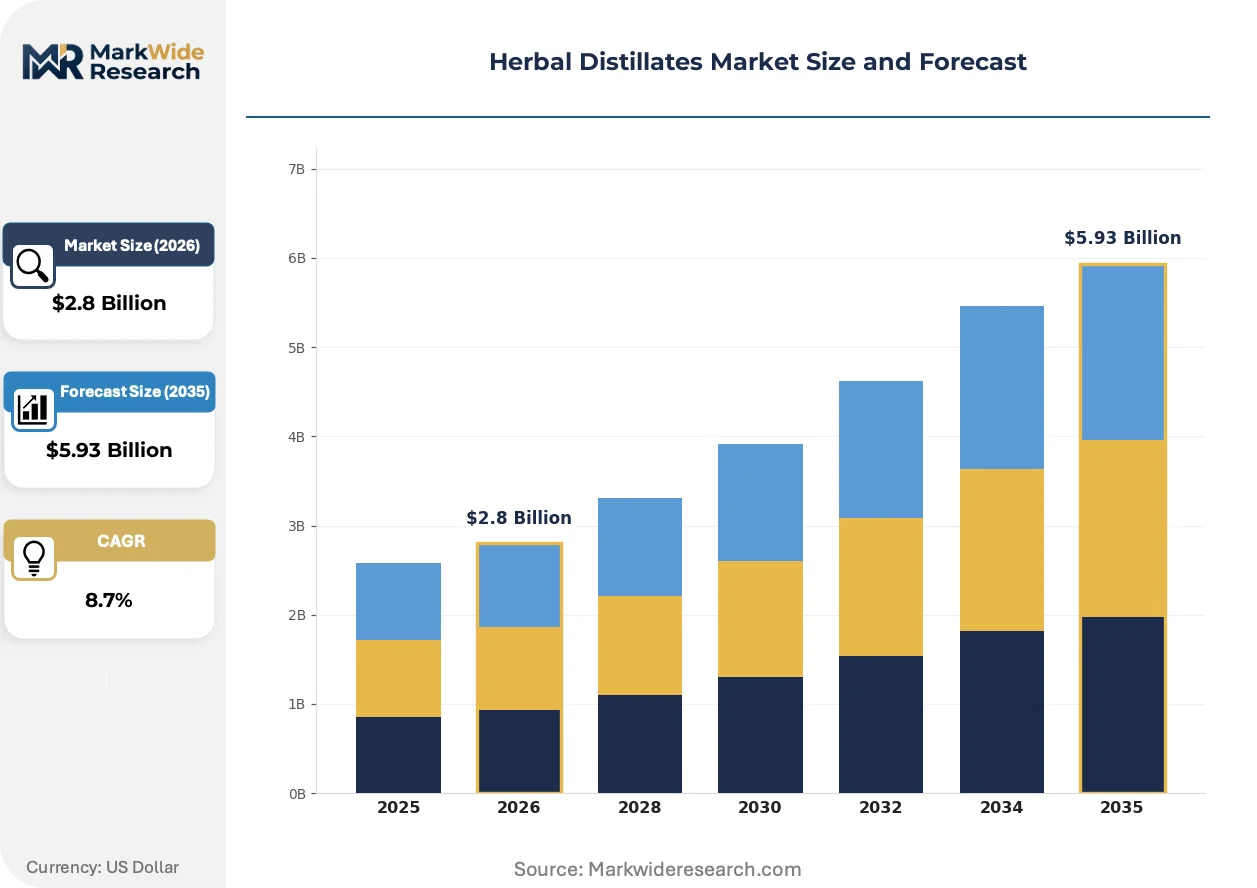
Market Dynamics
REACH solvent restrictions and EU Green Deal sustainable sourcing mandates are compressing conventional extraction margins while redirecting investment toward traceable, certified supply chains across European aromatherapy and personal care supply bases.
Growth Catalysts
- Clean-label cosmetics demand:Formulators in France's personal care sector now specify organic-certified hydrosols for alcohol-free facial toners, displacing synthetic alternatives in premium skincare lines.
- REACH compliance investments:Registration requirements for extraction solvents have consolidated supplier bases toward integrated distillers with captive laboratory testing capabilities.
- Aromatherapy cluster expansion:Germany's Black Forest region anchors concentrated demand for therapeutic-grade essential oils, drawing specialized distillation capacity from adjacent supply zones.
Market Restraints
- Feedstock price volatility:Cardamom and turmeric root costs fluctuate with monsoon patterns across southern India's Kerala belt, compressing margins for non-integrated processors.
- Organic certification timelines:EMA herbal medicinal product guidelines impose multi-year field-to-shelf documentation requirements that freeze out rapid market entry.
- Solvent substitution limits:Supercritical CO2 extraction remains capital-intensive for terpene-sensitive botanicals, trapping mid-scale operators in conventional steam distillation.
Strategic Opportunities
- EU AI Act documentation:Automated quality-control systems for distillation monitoring create first-mover advantages for distillers investing in sensor-integrated production lines before mandatory compliance dates.
- Hydrosol beverage applications:Functional water brands in North American markets are piloting botanical distillate fractions as natural flavor carriers in zero-proof spirits.
- Backward integration models:Control over cardamom and turmeric estates in Kerala enables guaranteed organic throughput for export-certified production.
Industry Challenges
- Terpenoid chemist scarcity:Formulation expertise in heat-sensitive compound preservation remains concentrated among Grasse-trained specialists, limiting replication of precision vacuum distillation elsewhere.
- Legacy equipment retrofit costs:Conventional alembic stills require extensive modification to meet ECHA emission thresholds for volatile organic compound capture.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Herbal Distillates Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Essential Oils, Hydrosols, Herbal Extracts, Floral Waters End User: Cosmetics, Food & Beverage, Pharmaceuticals, Wellness Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales Application: Aromatherapy, Flavoring, Medicinal Uses, Personal Care |
| Companies Covered | Givaudan, Synthite Industries, Döhler, Kalsec Inc., Vidya Herbs, International Flavors & Fragrances, Symrise, Kerry Group, Treatt, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Herbal Distillates Market Evolving Landscape
Extraction technology is fragmenting into configurable unit operations while regulatory documentation obligations expand beyond substance safety into algorithmic process control. These shifts are compressing traditional batch distillation economics and elevating traceability infrastructure as a competitive differentiator.
Vacuum distillation technology is modularizing around precision-controlled temperature zones that preserve heat-sensitive sesquiterpenes in rosemary and lavender processing. Mid-scale cosmetic formulators in France and Germany are adopting skid-mounted units at twice the rate of conventional still replacement. This equipment trajectory is compressing minimum efficient scale thresholds and enabling distributed production closer to botanical sourcing clusters.
REACH substance registration requirements now extend to automated distillation monitoring systems under emerging EU AI Act documentation obligations. Distillers must maintain algorithmic audit trails for quality-control decisions previously logged manually. Germany's Black Forest aromatherapy processors face the steepest compliance burden given their concentration of therapeutic-grade certification requirements.
Ingredient sourcing is consolidating around unbundled procurement of certified organic fractions rather than commodity essential oil purchases. Personal care brands in France now specify hydrosol terpene profiles by lot rather than accepting standard grades. This specification intensity is most visible in facial toner formulations where alcohol displacement has elevated water-based botanical inputs to primary active status.
Herbal Distillates Market Segmentation
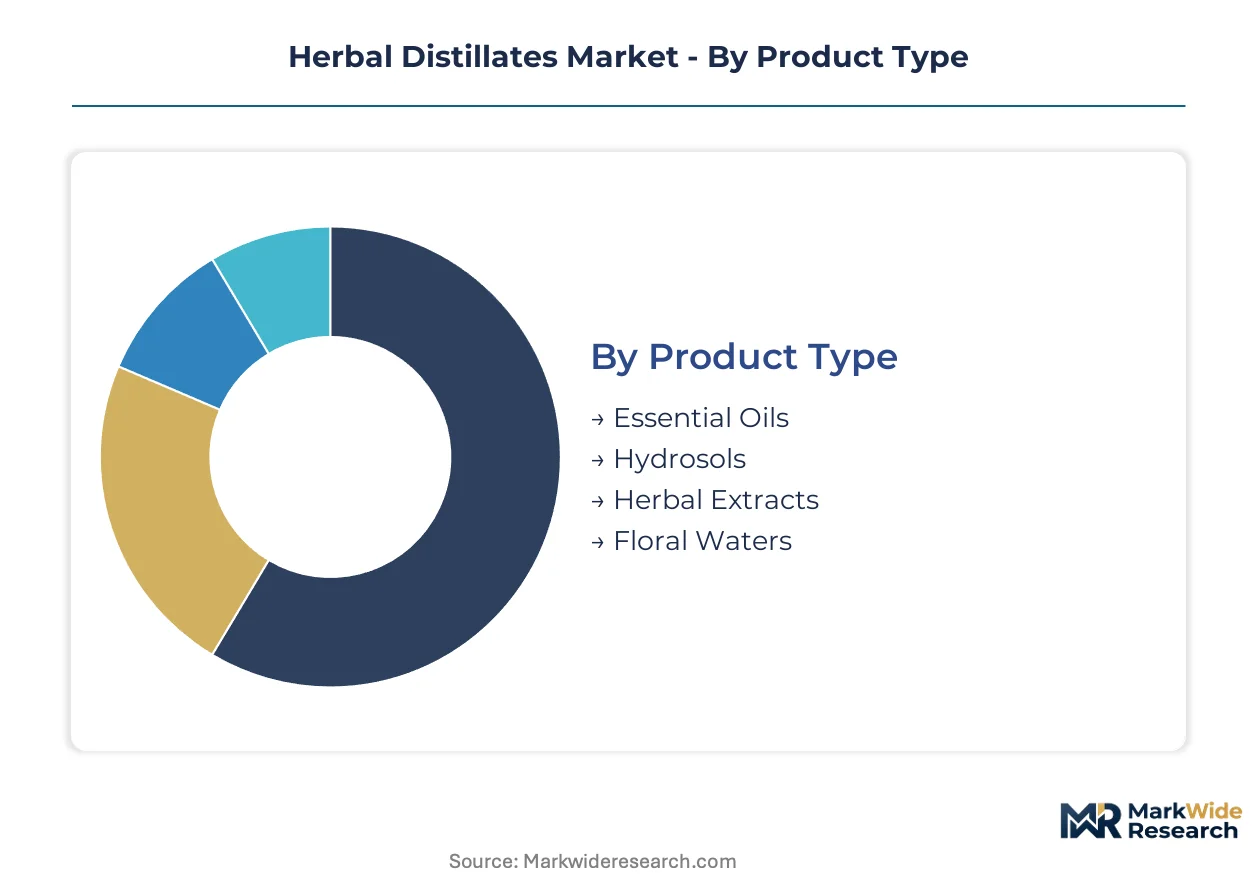
Herbal distillates fragment across multiple axes that determine specification intensity, regulatory burden, and margin capture. Product chemistry dictates extraction method and stability requirements. End-user verticals impose divergent purity standards from therapeutic-grade certification to food-safe thresholds. Distribution channel selection shapes lot traceability investments and packaging formats.
Product Type:
Buyers differentiate by concentration potency, volatility profile, and shelf-stability requirements when selecting among aqueous and lipid fractions.
- Essential Oils:Concentrated lipophilic fractions containing terpenes, phenylpropanoids, and sesquiterpenes recovered through steam distillation or expression. Therapeutic-grade demand in Germany's Black Forest aromatherapy cluster commands premium positioning for lavender and rosemary variants with defined chemotype specifications.
- Hydrosols:Aqueous co-products retaining trace volatile compounds and water-soluble plant acids, increasingly specified by French personal care formulators for alcohol-free facial toners requiring gentle pH profiles and clean-label positioning.
- Herbal Extracts:Concentrated preparations standardized for marker compounds through solvent or supercritical extraction, serving pharmaceutical and nutraceutical applications with documented phytochemical consistency.
- Floral Waters:Dilute aromatic preparations traditionally used in Middle Eastern and South Asian cosmetic rituals, now penetrating Western markets through premium positioning in natural fragrance layering systems.
Essential oils lead volumes today; hydrosols are gaining share fastest.
End User:
Vertical selection determines regulatory pathway, documentation burden, and permissible extraction solvent categories.
- Cosmetics:Formulators prioritize REACH-compliant, organic-certified inputs for EU market access, with hydrosol specifications tightening around terpene profile consistency and microbial load thresholds.
- Food & Beverage:Natural flavor carriers face EFSA and national food safety evaluations, with extraction solvent residues strictly controlled and organic certification increasingly mandatory for premium positioning.
- Pharmaceuticals:EMA herbal medicinal product guidelines impose multi-year field-to-shelf documentation, favoring integrated suppliers with captive cultivation and laboratory testing capabilities.
- Wellness:Aromatherapy and complementary health applications concentrate demand in Germany and France, where therapeutic-grade certification commands formulation premiums and repeat purchase loyalty.
Cosmetics captures the largest revenue pool; pharmaceuticals imposes the steepest compliance barriers.
Distribution Channel:
Channel choice reflects order scale, documentation requirements, and buyer technical sophistication.
- Online Retail:Direct-to-consumer and small-batch formulator procurement, requiring lot-specific certificates of analysis and cold-chain logistics for heat-sensitive terpene preservation.
- Supermarkets:Mass-market personal care and food-grade products with standardized specifications, favoring high-volume, lower-margin essential oil and floral water categories.
- Specialty Stores:Aromatherapy boutiques and natural health retailers in France and Germany, where staff expertise enables premium positioning and education-dependent hydrosol adoption.
- Direct Sales:Contract relationships between integrated distillers and major cosmetic houses, ensuring captive supply with customized specification development and joint regulatory filing support.
Direct sales dominates value capture; online retail shows the steepest expansion trajectory.
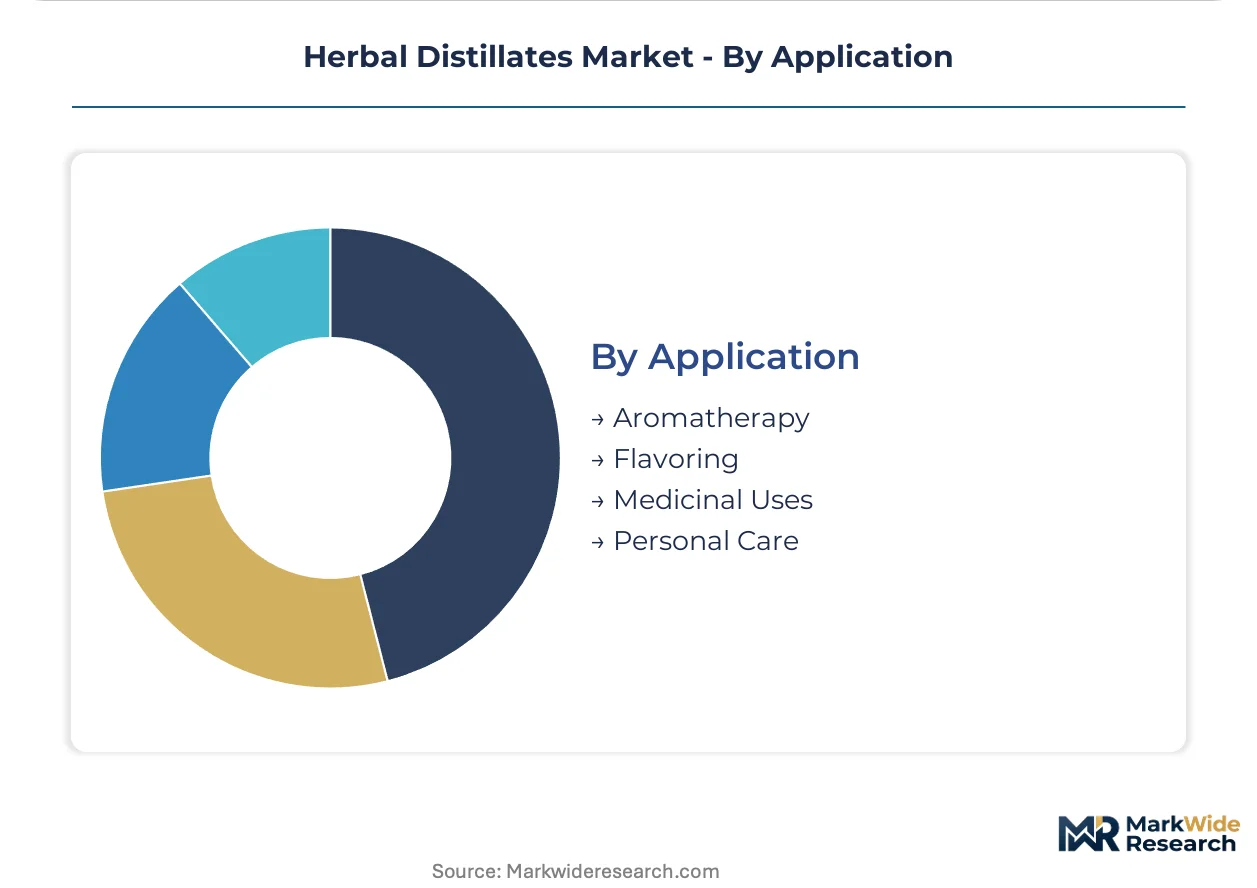
Application:
Functional use determines extraction precision requirements, dosage concentration, and stability testing protocols.
- Aromatherapy:Therapeutic-grade essential oils with defined chemotype ratios for inhalation and topical use, concentrated in Germany's wellness cluster with stringent quality-control documentation.
- Flavoring:Food-grade distillates for beverage and confectionery applications, where natural positioning displaces synthetic alternatives and organic certification commands price premiums.
- Medicinal Uses:EMA-registered herbal preparations with demonstrated efficacy and safety profiles, requiring pharmaceutical-grade manufacturing and batch release testing.
- Personal Care:Skin and hair formulations leveraging hydrosol gentleness and essential oil bioactivity, with French formulators leading alcohol-free toner innovation.
Personal care leads application volumes; medicinal uses faces the longest commercialization timelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Steam distillation traditions trace to Grasse in southern France, where commercial essential oil extraction scaled during the 16th century. Modern aromatherapy demand now concentrates in German wellness clusters and Indian spice belts.
France
Personal care formulators in Grasse and the wider Provence-Alpes-Côte d'Azur region specify organic-certified hydrosols for alcohol-free facial toners. ANSM cosmetic safety guidelines enforce microbial load thresholds and traceability documentation. Grasse maintains captive distillation capacity for lavender and rosemary processing.
Germany
Therapeutic-grade essential oil demand concentrates in the Black Forest aromatherapy cluster, where wellness boutiques command premium positioning. REACH substance registration requirements for extraction solvents favor integrated distillers with in-house laboratory testing. Bavarian processors invest in automated quality-control systems to meet emerging EU AI Act documentation obligations.
India
Cardamom and turmeric root supply chains anchor the Kerala spice belt, where monsoon patterns drive feedstock price volatility. FSSAI and CDSCO impose multi-year field-to-shelf documentation for herbal medicinal products. Synthite Industries exemplifies backward integration into southern Indian estates for guaranteed organic throughput.
United States
Functional water brands pilot botanical distillate fractions as natural flavor carriers in zero-proof spirits. FDA food additive regulations and state-level cannabis-derived ingredient rules create compliance fragmentation. California formulators lead hydrosol adoption in clean-label personal care lines.
China
Traditional medicine applications sustain demand for concentrated herbal extracts standardized to marker compounds. NMPA herbal product registration and GB standards for solvent residues elevate manufacturing compliance costs. Sichuan-Chongqing processors expand supercritical CO2 capacity for heat-sensitive terpene preservation.
Herbal Distillates Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification-grade and traceability dimensions. The vendor base organizes into three tiers: integrated cultivator-distillers with captive estate supply, specialized flavor houses with modular extraction technology, and regional commodity processors serving bulk pharmaceutical and food-grade contracts. Consolidation pressure intensifies as REACH compliance costs and organic certification timelines freeze out rapid market entry. Dominant competitive moves include backward integration into botanical estates and precision-controlled vacuum distillation capacity expansion.
Within the integrated cultivator-distiller tier, Givaudan and Synthite Industries exemplify contrasting geographic anchors. Givaudan represents European Grasse-based heritage positioning with captive lavender and rosemary distillation infrastructure. Synthite Industries occupies a parallel position in southern India through upstream control over cardamom and turmeric estates. Symrise sits within the specialized technology tier, distinguished by precision vacuum distillation systems that preserve heat-sensitive terpene profiles.
| Leading Market Players |
|---|
| Givaudan |
| Synthite Industries |
| Döhler |
| Kalsec Inc. |
| Vidya Herbs |
| International Flavors & Fragrances |
| Symrise |
| Kerry Group |
| Treatt |
| Others |
Value Network & Pricing Analysis
Monsoon-driven cardamom and turmeric root costs in Kerala trace directly through three-tier pricing structures separating organic-certified therapeutic grades from conventional bulk pharmaceutical tiers and commodity food-grade volumes. REACH solvent compliance investments and EU AI Act documentation mandates compress margins at the standard tier while premium hydrosol specifications in French personal care sustain markup capture.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates organic-certified therapeutic grades with full traceability documentation from REACH-compliant conventional volumes and commodity food-grade spot purchases. Price differentiation hinges on certification grade and captive estate integration, with organic throughput commanding sustained premiums. Cost compression in the standard tier intensifies because ECHA emission retrofit requirements and laboratory testing investments outpace volume scaling. Small-batch cosmetic formulators in France exhibit lowest price sensitivity; bulk pharmaceutical contractors in India face acute margin pressure from feedstock volatility.
Supply Chain Analysis
EU Green Deal local-content mandates and sustainable sourcing rules are reshaping procurement toward traceable European and Indian estate networks. Supply concentrates in France's Grasse distillation cluster, Germany's Black Forest processing belt, and Kerala's spice-growing regions. Raw material flows draw from lavender and rosemary cultivars in Provence, cardamom and turmeric root in southern India, and imported botanicals for supercritical CO2 extraction. Single-source vulnerability runs through monsoon-dependent Kerala feedstocks. Distribution runs through direct sales contracts with integrated cosmetic houses and specialty aromatherapy retailers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in herbal distillates rests on hydrosol category premiumization displacing alcohol-based formulations and automation investments compressing per-unit compliance costs.
For Market Incumbents: Lock in captive distillation capacity through estate acquisition in Kerala and Grasse-adjacent zones before organic certification timelines freeze out rapid land conversion. Defend against modular vacuum distillation entrants by embedding sensor-integrated quality-control systems ahead of EU AI Act mandatory compliance dates. Prioritize laboratory testing capability expansion to consolidate REACH-registered supplier bases. For New Entrants and Emerging Players: Specialty retailers in Germany's Black Forest wellness cluster offer the most penetrable channel for therapeutic-grade hydrosol introduction with education-dependent purchase decisions. Target North American functional water brands piloting zero-proof botanical flavor carriers as white-space demand with lower certification barriers than pharmaceutical pathways. Pursue skid-mounted vacuum distillation equipment partnerships to bypass Grasse-trained terpenoid chemist scarcity. For Investors and Strategic Acquirers: Consolidation pressure builds where REACH compliance costs and multi-year organic certification timelines strand mid-scale conventional processors without captive estate supply. Five-to-ten-year viability favors integrated cultivator-distillers with backward control over cardamom, turmeric, or lavender throughput and in-house laboratory infrastructure. Watch for EU AI Act documentation deadline acceleration as inflection signal for automated quality-control system adoption rates.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Estate Supply | Captive organic throughput insulates margin compression from Kerala monsoon volatility and feedstock spot markets. |
| Precision Vacuum Distillation Capacity Expansion | Modular temperature-zone control preserves heat-sensitive sesquiterpenes for premium cosmetic specifications. |
| Automated Quality-Control System Deployment | Sensor-integrated production lines satisfy emerging EU AI Act algorithmic audit trail obligations. |
| Hydrosol Beverage Application Development | Natural flavor carrier positioning in North American zero-proof spirits opens category extension beyond personal care. |
| Direct Sales Contract Structuring | Joint regulatory filing support with major cosmetic houses locks in specification-customized volume commitments. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with distillation plant managers, cosmetic formulator procurement leads, specialty retailer category buyers, and regulatory affairs directors at integrated flavor houses with secondary validation. Customs and trade data, ECHA substance registration databases, ANSM cosmetic safety filings, and FSSAI herbal product documentation anchored supply-side assessment. Bottom-up capacity and throughput estimates triangulated against top-down category spending analysis.
Segment-weighting approaches distributed value and volume projections across essential oil, hydrosol, herbal extract, and floral water categories by extraction method, end-user vertical, and geographic regulatory cluster. CAGRs were derived from fitted growth curves applied to baseline consumption patterns and elasticity-adjusted price trajectories across the analysis window. Forecast inputs incorporated organic certification adoption rates, REACH compliance cost pass-through assumptions, and hydrosol specification intensity in French personal care formulation.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU AI Act implementation timing, monsoon pattern shifts affecting Kerala feedstock yields, and substitution acceleration toward synthetic alternatives under sustained cost compression. Forecasts reflect documented assumptions about regulatory trajectory and category demand elasticity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
N-Hexyl Alcohol Market
Alcoholic Beverages
Craft Wine Market
Alcoholic Beverages
Spain Alcohol E-Commerce Market
Alcoholic Beverages
F-Style Jugs Market
Alcoholic Beverages
North America Tequila Market
Alcoholic Beverages
South Africa Beverages Market
Alcoholic Beverages
Fruit Wine Market
Alcoholic Beverages
Automated Brewing System Market
Alcoholic Beverages
Turkey Tequila Market
Alcoholic Beverages
South Korea Tequila Market
Alcoholic Beverages
India Tequila Market
Alcoholic Beverages
Alcohol Gummies Market
Alcoholic Beverages
E Liquid Market
Alcoholic Beverages
Global Malted Barley Market
Alcoholic Beverages
Europe Craft Beer Market
Alcoholic Beverages
Home Brewing Systems Market